
 Australia and New Zealand Diabetes Devices Market | 2026-2036
Australia and New Zealand Diabetes Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Diabetes Devices Market Outlook
Multi-source procurement of glucose sensors is hardening across Australian hospital networks as buyers diversify supplier relationships to mitigate disruption risk. Dexcom leverages its wearable sensor ecosystem to sustain premium positioning in continuous monitoring. Abbott anchors the self-monitoring blood glucose segment through broad pharmacy distribution. Medtronic competes in integrated pump-CGM systems with closed-loop algorithm development.
Diabetes devices comprise electrochemical biosensors, precision insulin delivery mechanisms, and data-integrated wearable platforms engineered to maintain glycemic control within clinically specified ranges. Continuous glucose monitors operate via subcutaneous enzymatic sensors measuring interstitial glucose every one to five minutes, transmitting data to receivers or smartphones for real-time therapeutic adjustment. Blood glucose meters retain the largest installed base among product types though continuous glucose monitors capture the fastest growth trajectory as reimbursement broadens. Smart technology integration across wearable devices and mobile apps is reshaping how end users in home care and diabetes clinics manage daily insulin dosing decisions.
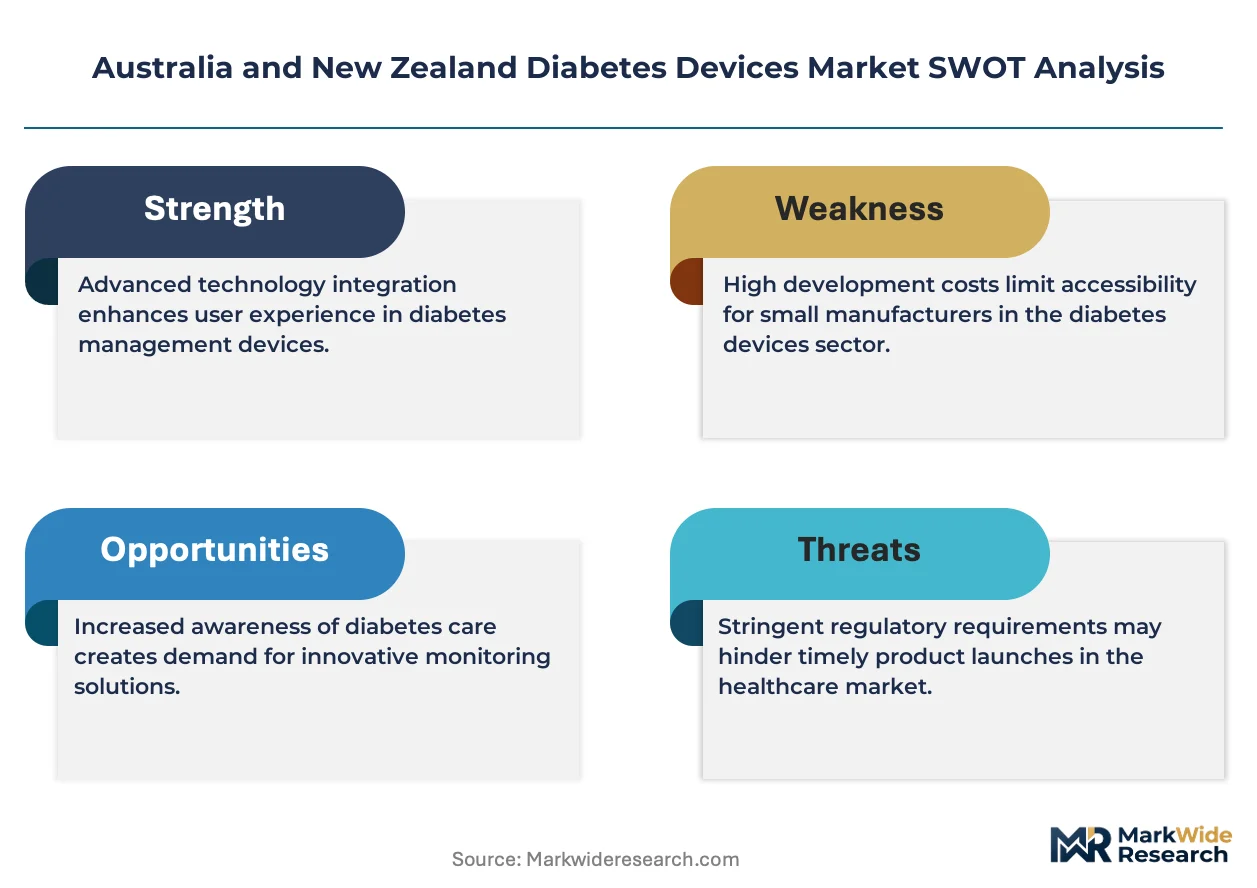
TGA governs pre-market approval and post-market vigilance for diabetes devices in Australia while Medsafe performs equivalent functions in New Zealand, with both agencies aligning toward harmonized standards under the Australia New Zealand Therapeutic Products Administration framework. Compliance with ISO 15197 accuracy standards for blood glucose meters and IEC 62304 software lifecycle requirements for connected devices shapes product development timelines and market access pathways. Stakeholders must monitor reimbursement policy shifts between Australia's National Diabetes Services Scheme and New Zealand's Pharmaceutical Management Agency as these funding mechanisms determine patient access to advanced insulin pump and continuous monitoring technologies.
Market Dynamics
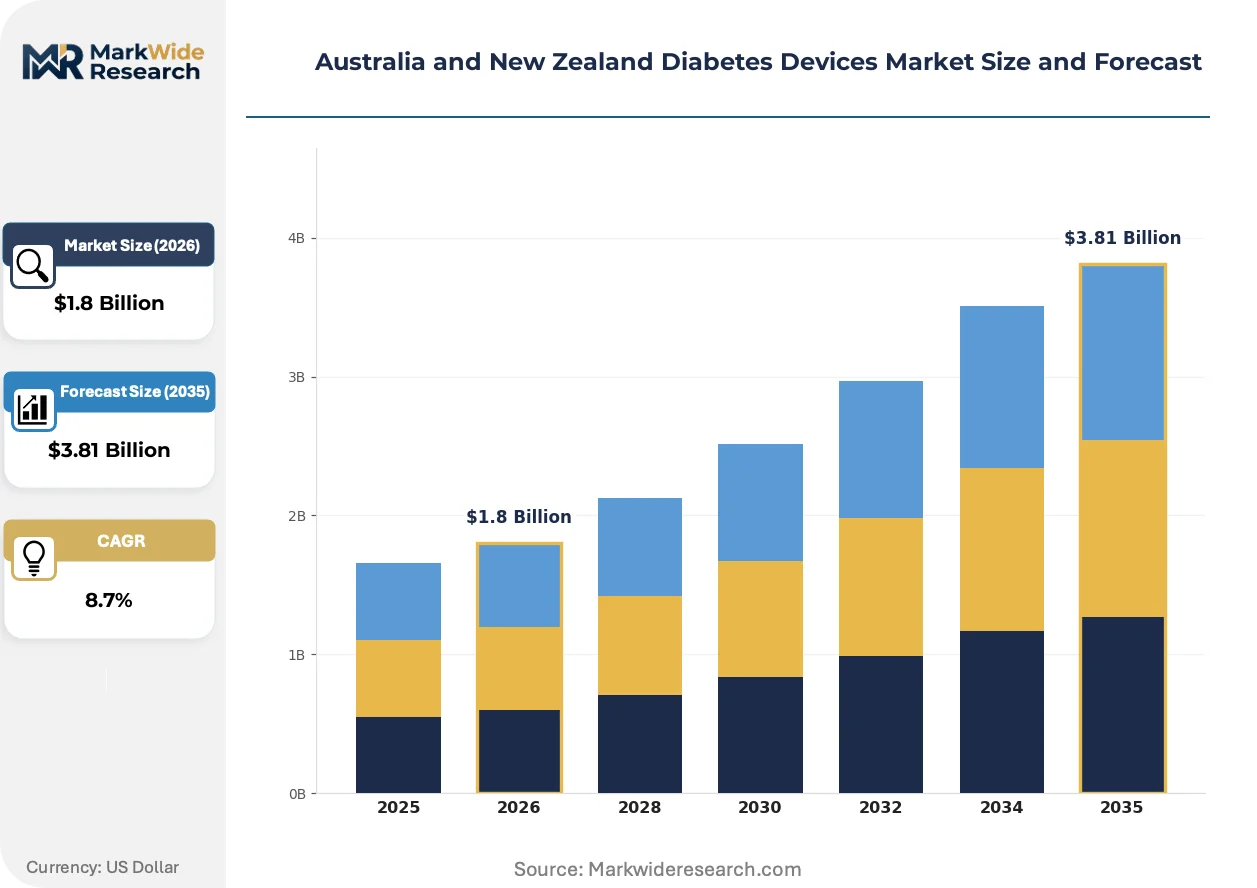
Reimbursement expansion under Australia's National Diabetes Services Scheme is accelerating continuous glucose monitor penetration beyond metropolitan diabetes clinics into regional home care settings, compressing traditional blood glucose meter volumes while elevating software-integrated device standards across both markets.
Growth Catalysts
- ANZTPA Harmonization:The Australia New Zealand Therapeutic Products Administration framework streamlines dual-market registration pathways, reducing time-to-market for wearable sensor platforms seeking simultaneous TGA and Medsafe approvals.
- Metropolitan Clinic Demand:Australia's state-funded diabetes clinics in Sydney and Melbourne are mandating real-time glucose data integration into electronic health records, driving institutional procurement of connected monitoring ecosystems.
- Enzymatic Sensor Advances:Extended-wear subcutaneous sensors measuring interstitial glucose every one to five minutes are eliminating calibration requirements, improving patient adherence in New Zealand's dispersed rural populations.
Market Restraints
- Platinum Electrode Costs:Electrochemical biosensor production depends on platinum-group metal electrodes, exposing manufacturers to commodity price volatility that compresses margins on disposable sensor strips.
- Single-Source Pump Component Risk:Precision insulin delivery mechanisms rely on concentrated micro-pump motor supply from German and Swiss specialty component houses, creating vulnerability to export licensing delays.
- ISO 15197 Accuracy Burden:Blood glucose meter manufacturers face extended validation timelines to demonstrate 95% of results within 15% of laboratory reference values, slowing product refresh cycles.
Strategic Opportunities
- Queensland and Western Australia Expansion:Underpenetrated regional markets beyond Australia's eastern seaboard present whitespace for home care distribution partnerships with rural pharmacy networks.
- Closed-Loop Algorithm Convergence:Integration of continuous glucose monitors with predictive insulin dosing software creates premium positioning for automated glycemic control systems in pediatric endocrinology practices.
- Pharmaceutical Management Agency Reimbursement:New Zealand's pending expansion of CGM subsidy eligibility to Type 2 insulin-dependent patients will unlock volume growth in Auckland and Christchurch hospital networks.
Industry Challenges
- IEC 62304 Software Validation:Connected devices require documented software lifecycle processes for mobile app integration, extending development timelines by 12-18 months for smartphone-linked monitoring platforms.
- Biocompatibility Certification Complexity:Subcutaneous sensor adhesives must demonstrate ISO 10993 cytotoxicity and sensitization compliance across diverse skin types, complicating multi-ethnic market rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Diabetes Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Insulin Pumps, Continuous Glucose Monitors, Smart Pens End User: Hospitals, Home Care, Diabetes Clinics, Pharmacies Technology: Smart Technology, Wearable Devices, Mobile Apps, Cloud-Based Solutions Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Ketoacidosis |
| Companies Covered | Novo Nordisk, Dexcom, Abbott, Sanofi, Medtronic, Roche Diabetes Care, Insulet, Ypsomed, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Diabetes Devices Market Strategic Shifts
Wearable platform integration is compressing device replacement cycles while elevating data interoperability requirements. Software-defined functionality now differentiates hardware offerings across both markets.
Closed-loop automated insulin delivery is consolidating discrete pump and monitor categories into unified glycemic management systems. Pediatric endocrinology departments in Melbourne and Sydney are prioritizing these platforms for adolescent Type 1 patients. The technology is consolidating vendor relationships around single-ecosystem procurement contracts that exclude standalone device suppliers.
TGA's post-market vigilance requirements for software-as-medical-device are tightening adverse event reporting timelines for connected glucose monitors. Manufacturers must now submit periodic safety update reports within 30 days of signal detection. Blood glucose meter incumbents with limited software capabilities face compliance cost escalation that favors platform-native competitors.
Hospital pharmacy buyers in New South Wales and Victoria are consolidating sensor procurement through multi-year framework agreements with performance-based adherence metrics. Traditional distributor relationships are yielding to direct manufacturer contracts with embedded clinical educator support. This shift is most visible in Australia's public hospital networks where volume aggregation justifies dedicated account management resources.
Australia and New Zealand Diabetes Devices Market Segmentation
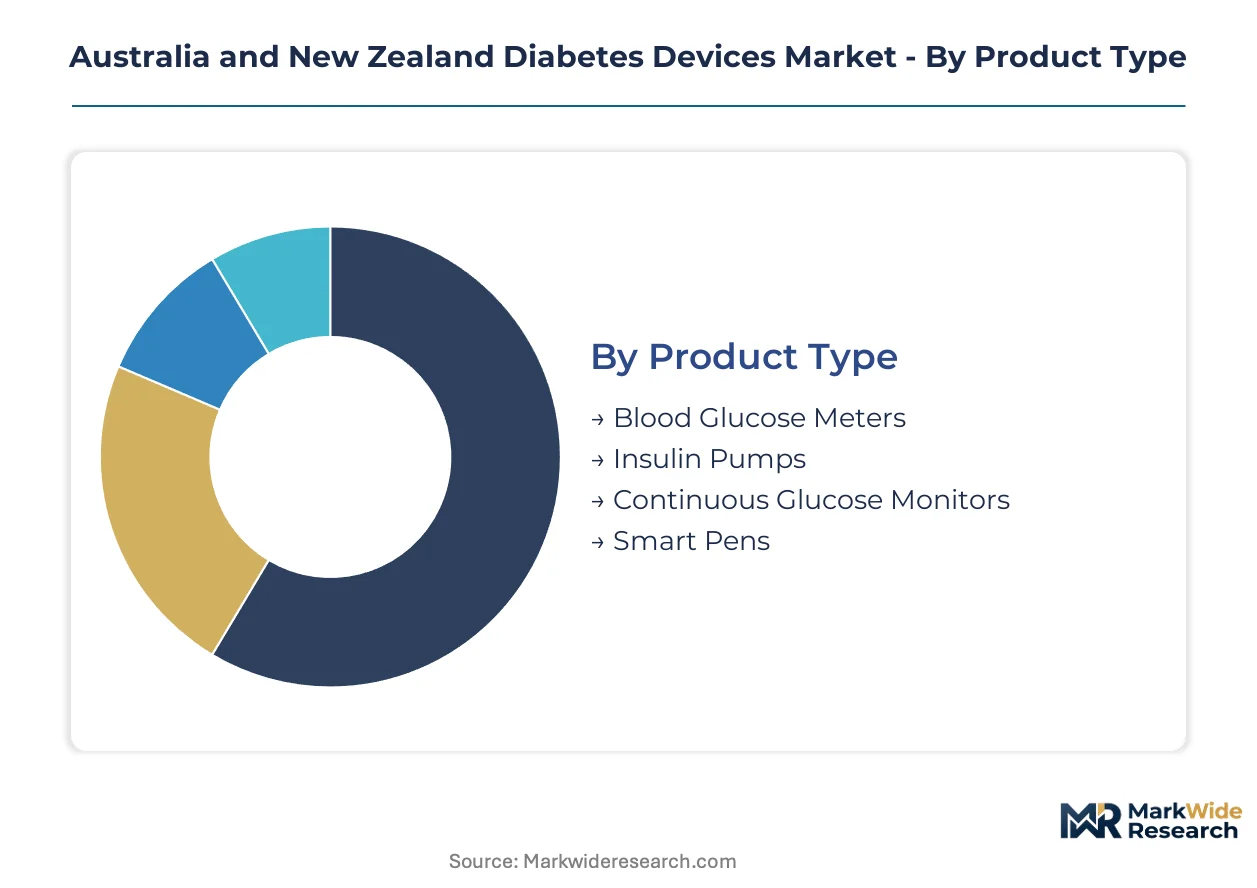
Device segmentation in Australia and New Zealand reveals divergent capital requirements across hardware categories. Software-integrated platforms demand sustained R&D investment while consumable strips rely on manufacturing scale economies.
Product Type:
Continuous glucose monitors and insulin pumps require the heaviest upfront capital deployment for enzymatic sensor fabrication and precision micro-pump assembly.
- Blood Glucose Meters:Electrochemical biosensors using platinum-group electrodes measure capillary glucose via disposable test strips. Australia's National Diabetes Services Scheme subsidizes these units heavily, though volumes are compressing as continuous monitoring expands.
- Insulin Pumps:Precision delivery mechanisms with programmable basal-bolus algorithms integrate with continuous glucose data for predictive dosing. Melbourne and Sydney pediatric endocrinology departments are consolidating procurement around closed-loop systems.
- Continuous Glucose Monitors:Subcutaneous sensors transmitting interstitial glucose readings every one to five minutes to smartphones or receivers.
- Smart Pens:Bluetooth-enabled insulin delivery devices capturing dose timing and amount for mobile app integration.
Most installed capacity flows through blood glucose meters. Expansion is steepest in continuous glucose monitors.
End User:
Institutional procurement patterns split between concentrated hospital networks and dispersed home care delivery models.
- Hospitals:Acute care settings in Auckland and Christchurch manage diabetic ketoacidosis with integrated monitoring systems. New Zealand's hospital networks are tightening multi-source procurement requirements for sensor supplies.
- Home Care:Self-managed glycemic control dominates device utilization across Australia's regional Queensland and Western Australia expanses. TGA's post-market vigilance requirements now extend to home-use adverse event reporting.
- Diabetes Clinics:State-funded metropolitan facilities in Sydney and Melbourne mandate real-time glucose data integration into electronic health records.
- Pharmacies:Community distribution points anchor blood glucose meter and test strip access, particularly in rural pharmacy networks.
Home care settings absorb the greatest device volume. Diabetes clinics are expanding fastest as institutional procurement consolidates.
Technology:
Software development timelines now exceed hardware production cycles across all technology tiers.
- Smart Technology:Algorithm-driven insulin dosing recommendations based on predictive glucose trajectory modeling. IEC 62304 software lifecycle compliance extends development timelines by 12-18 months for these platforms.
- Wearable Devices:Extended-wear subcutaneous sensors eliminating calibration requirements through factory-calibrated enzymatic technology. Biocompatibility certification across diverse skin types complicates rollout.
- Mobile Apps:Smartphone platforms receiving continuous glucose data and delivering dosing alerts.
- Cloud-Based Solutions:Remote data aggregation enabling clinician oversight of patient glucose patterns.
Wearable devices carry the largest installed base. Cloud-based solutions are climbing the fastest as telehealth integration accelerates.
Application:
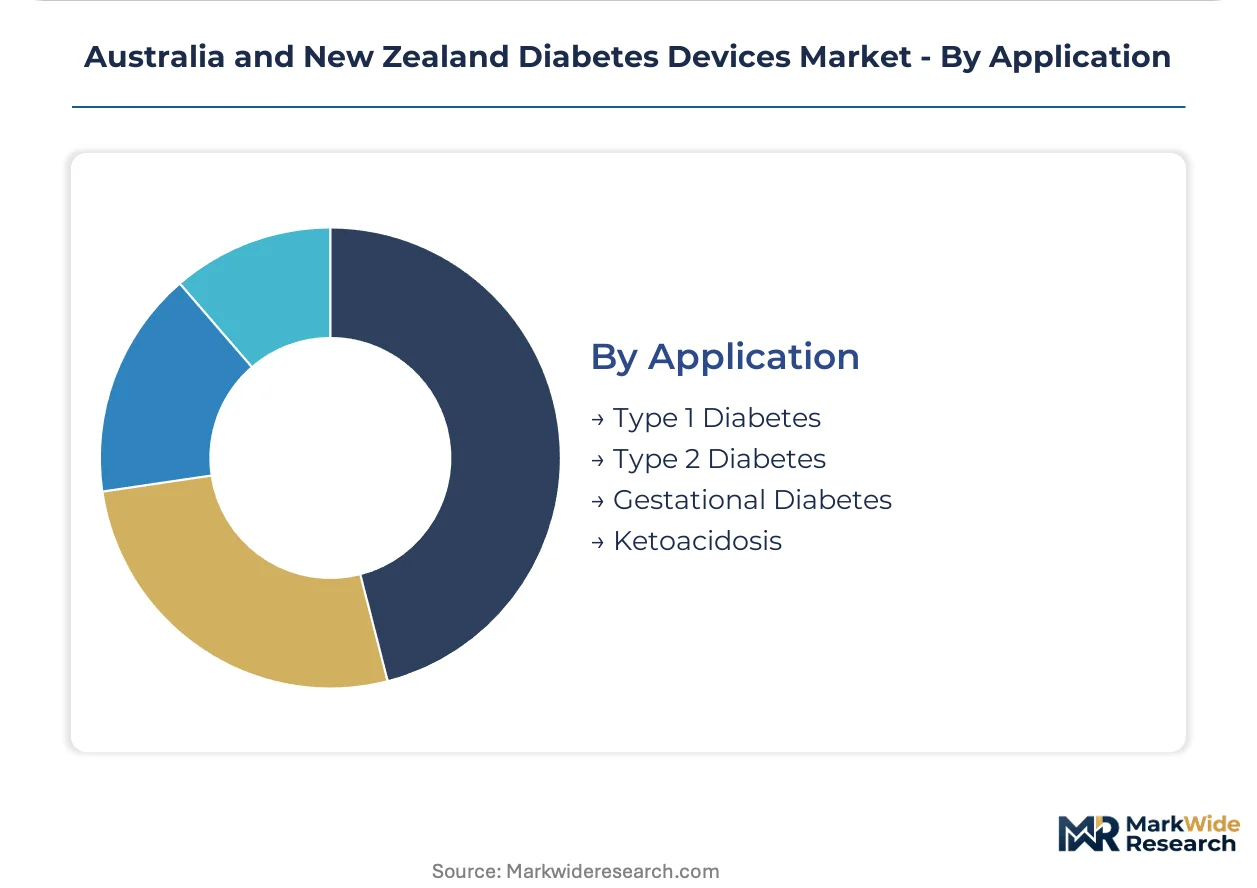
Disease severity and insulin dependency determine device sophistication requirements and reimbursement eligibility.
- Type 1 Diabetes:Absolute insulin deficiency requiring continuous monitoring and pump delivery. Australia's NDSS and New Zealand's Pharmaceutical Management Agency prioritize subsidy access for this population.
- Type 2 Diabetes:Progressive insulin resistance with variable pharmacological management. Pending CGM subsidy expansion to insulin-dependent Type 2 patients will unlock volume growth in Auckland hospital networks.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring temporary monitoring intervention.
- Ketoacidosis:Acute metabolic emergency managed in hospital settings with intensive monitoring protocols.
Type 2 diabetes generates the largest patient population. Type 1 diabetes shows the steepest expansion trajectory as closed-loop automation penetrates pediatric practices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney and Melbourne anchor device procurement across Australia's southeastern diabetes corridor, while Auckland and Christchurch hospital networks concentrate New Zealand's institutional demand.
New South Wales
State-funded diabetes clinics in Sydney mandate real-time glucose data integration into electronic health records, driving connected monitoring ecosystem procurement. TGA's post-market vigilance requirements extend to home-use adverse event reporting across Greater Sydney and regional hubs. The Sydney Children's Hospital Network is consolidating closed-loop system contracts for pediatric Type 1 patients.
Victoria
Melbourne's Royal Children's Hospital and Monash Medical Centre prioritize automated glycemic control systems for adolescent endocrinology departments. Australia's National Diabetes Services Scheme reimbursement expansion is compressing traditional blood glucose meter volumes in metropolitan Melbourne while elevating software-integrated standards. The Melbourne biomedical precinct clusters sensor algorithm development alongside clinical validation trials.
Queensland
Underpenetrated regional markets beyond Brisbane present whitespace for home care distribution partnerships with rural pharmacy networks. Extended-wear subcutaneous sensors are improving patient adherence in dispersed populations across the Sunshine Coast and Gold Coast hinterlands. The Queensland Children's Hospital in Brisbane is piloting predictive insulin dosing software integration.
Western Australia
Perth's tertiary hospitals manage diabetic ketoacidosis presentations with intensive monitoring protocols, while remote Aboriginal communities drive demand for durable, calibration-free wearable sensors. The WA Country Health Service is expanding telehealth-integrated glucose monitoring to reduce travel burdens for regional patients. Fiona Stanley Hospital in Perth anchors the state's closed-loop therapy evaluation program.
New Zealand
Auckland and Christchurch hospital networks are tightening multi-source procurement requirements for sensor supplies to mitigate disruption risk. Medsafe's alignment with TGA under the Australia New Zealand Therapeutic Products Administration framework is streamlining dual-market registration pathways for wearable platforms. Pharmac's pending expansion of continuous glucose monitor subsidy eligibility to Type 2 insulin-dependent patients will unlock volume growth across Auckland's metropolitan clinics.
Australia and New Zealand Diabetes Devices Market Competitive Environment
Global majors compete with regional champions across integrated pump-sensor ecosystems and standalone monitoring categories. Market structure tilts toward consolidated vendor relationships around single-ecosystem procurement contracts, particularly in pediatric endocrinology departments. Three archetypes dominate: platform-native specialists with closed-loop algorithm capabilities, diversified medtech conglomerates with broad diabetes portfolios, and pharmacy-distributed consumable leaders. Competitive moves center on strategic partnerships with hospital networks and backward integration into enzymatic sensor fabrication.
Within the platform-native tier, Dexcom and Insulet exemplify wearable sensor ecosystem positioning, while Abbott occupies a position among pharmacy-distributed consumable anchors. Medtronic sits within the diversified medtech conglomerate archetype with integrated pump-CGM system offerings. Novo Nordisk represents the pharmaceutical-origin entrant bridging drug delivery with device integration. These three archetypes—platform-native specialists, consumable distributors, and diversified conglomerates—capture distinct procurement channels across Australia's NDSS-subsidized access points and New Zealand's hospital network tenders.
| Leading Market Players |
|---|
| Novo Nordisk |
| Dexcom |
| Abbott |
| Sanofi |
| Medtronic |
| Roche Diabetes Care |
| Insulet |
| Ypsomed |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Performance-tier bifurcation between factory-calibrated continuous glucose monitors and commodity blood glucose meters manifests in divergent margin structures and supply chain configurations across Australian and New Zealand procurement channels. Premium-tier closed-loop systems command subscription-based pricing anchored to enzymatic sensor fabrication costs, while standard consumables compete on platinum-group electrode sourcing efficiency and distributor volume rebates.
Pricing Analysis
Input-cost pass-through from platinum-group metals and precision micro-pump motors compresses margins on disposable sensor strips while elevating pricing power for integrated pump-CGM ecosystems. Three-tier pricing structure across premium, standard, and economy levels reflects calibration-free sensor technology, software algorithm sophistication, and bundled clinical educator support. Pricing pressure stems from Australia's National Diabetes Services Scheme reimbursement compression on traditional blood glucose meters. Hospital procurement committees exhibit lowest price sensitivity; rural pharmacy networks show highest.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss specialty component houses supplying precision micro-pump motors for insulin delivery mechanisms. Manufacturing concentration spans Ireland and Malaysia for enzymatic sensor fabrication, with final assembly anchored in Singapore and Costa Rica. Platinum-group metal electrodes and biocompatible adhesive polymers constitute critical raw material dependencies. Commodity price volatility in precious metals creates margin exposure. Distribution runs through hospital pharmacy consolidators in New South Wales and Victoria, direct manufacturer contracts for diabetes clinics, and wholesale pharmacy networks for home care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in software-integrated platforms where algorithm development costs amortize across expanding CGM reimbursement eligibility, while platinum-input exposure in consumable strips pressures legacy meter manufacturers toward premium-tier migration.
For Market Incumbents: Anticipate procurement consolidation in Melbourne and Sydney pediatric endocrinology departments by securing sole-source closed-loop contracts before multi-hospital framework agreements harden. Backward integration into enzymatic sensor fabrication reduces platinum-group metal cost exposure. Prioritize IEC 62304 software lifecycle certification investment to defend against platform-native competitors with native mobile app capabilities. For New Entrants and Emerging Players: Rural Aboriginal communities in Western Australia present an underserved buyer archetype requiring calibration-free wearable sensors with telehealth integration. Queensland's dispersed regional populations outside Brisbane offer whitespace for home care distribution partnerships with independent pharmacy networks. Entry through pharmaceutical management agency reimbursement strategy alignment unlocks New Zealand hospital network access. For Investors and Strategic Acquirers: Consolidation pressure builds where software-defined functionality differentiates hardware offerings and standalone device suppliers face compliance cost escalation. Five-to-ten year viability favors platform-native specialists with closed-loop algorithm capabilities over blood glucose meter incumbents with limited software stacks. Monitor TGA post-market vigilance enforcement intensity as inflection signal for regulatory compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Algorithm Development | Predictive insulin dosing software captures premium positioning in Melbourne pediatric practices. |
| ANZTPA Harmonization Compliance | Dual-market registration streamlining reduces time-to-market for wearable sensor platforms. |
| Hospital System Partnership | Direct contracts with New South Wales pharmacy buyers displace traditional distributor relationships. |
| Software Companion Development | Mobile app integration extends device replacement cycles and elevates data interoperability requirements. |
| Reimbursement Strategy Alignment | Pharmac CGM subsidy expansion to Type 2 insulin-dependent patients unlocks Auckland volume growth. |
Study Parameters
Multiple input streams — hospital procurement database analysis, clinician interviews, and regulatory filing review — were reconciled across primary fieldwork with diabetes device category managers, biomedical engineers at tertiary hospitals, GPO contracts administrators, and pharmacy procurement leads, supplemented by secondary validation against TGA adverse event reports, Medsafe device safety updates, NDSS reimbursement schedules, and ISO 15197 accuracy standard documentation. Bottom-up demand modeling across enzymatic sensor fabrication capacity and top-down market sizing from reimbursement-expansion trajectories were triangulated.
Data-stream reconciliation anchored volume and value outputs to patient population segmentation by diabetes type, insulin dependency status, and care setting, with technology-tier splits across wearable, mobile-integrated, and standalone device categories. CAGRs were derived from reimbursement policy elasticity modeling and closed-loop adoption curve analysis across pediatric endocrinology practices. Enzymatic sensor wear-duration improvements and platinum-group metal price volatility indices informed input-cost assumptions.
Underlying measurement precision varies by segment; continuous glucose monitor forecasts carry tighter precision than blood glucose meter projections given reimbursement policy visibility. Forecasts reflect documented assumptions regarding NDSS expansion timing and Pharmac subsidy eligibility revisions. Sensor adhesive biocompatibility certification delays and micro-pump motor export licensing disruptions constitute specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
US Contact Lenses Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Low Vision Aids Market
Medical Devices
Asia-Pacific Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Patient Lift Slings Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Electroencephalogram (EEG) Caps Market
Medical Devices
Biologic Injectors Market
Medical Devices
Zygomatic and Pterygoid Implants Market