
 Asia-Pacific Vagus Nerve Stimulation Market | 2026-2036
Asia-Pacific Vagus Nerve Stimulation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Vagus Nerve Stimulation Market Outlook
Epilepsy treatment centers are bifurcating from traditional psychiatric clinics as the dominant buyer archetype across the Asia-Pacific Vagus Nerve Stimulation landscape. LivaNova PLC anchors its regional position through deep specialization in implantable pulse generator technology. Medtronic Plc leverages its established cardiac rhythm management infrastructure to cross-sell neuromodulation systems into hospital networks. ElectroCore Inc differentiates via non-invasive transcutaneous platforms that bypass surgical eligibility constraints.
Vagus nerve stimulation delivers electrical impulses to the left cervical vagus nerve through implantable or external devices, typically operating at frequencies between 20-30 Hz with pulse widths of 250-500 microseconds to modulate aberrant neural signaling. Implantable devices command the dominant value share due to chronic therapy requirements and replacement cycles, while external devices represent the fastest-expanding segment as clinicians prioritize reversible, non-surgical interventions for treatment-resistant depression. The technology dimension splits sharply between transcutaneous systems gaining traction in outpatient settings and invasive platforms retaining primacy in hospital surgical departments.
Japan's PMDA and Australia's TGA enforce divergent reimbursement and safety surveillance standards that fragment product registration timelines across the region. India's CDSCO has issued draft guidance on neurostimulator classification that will reshape market access for imported devices. South Korea's MFDS maintains stringent electromagnetic compatibility testing protocols that favor manufacturers with established quality management systems. Stakeholders must monitor evolving reimbursement decisions by Japan's Ministry of Health, Labour and Welfare, as these determinations will signal whether non-invasive vagus nerve stimulation achieves parity coverage with implantable alternatives.
Market Dynamics
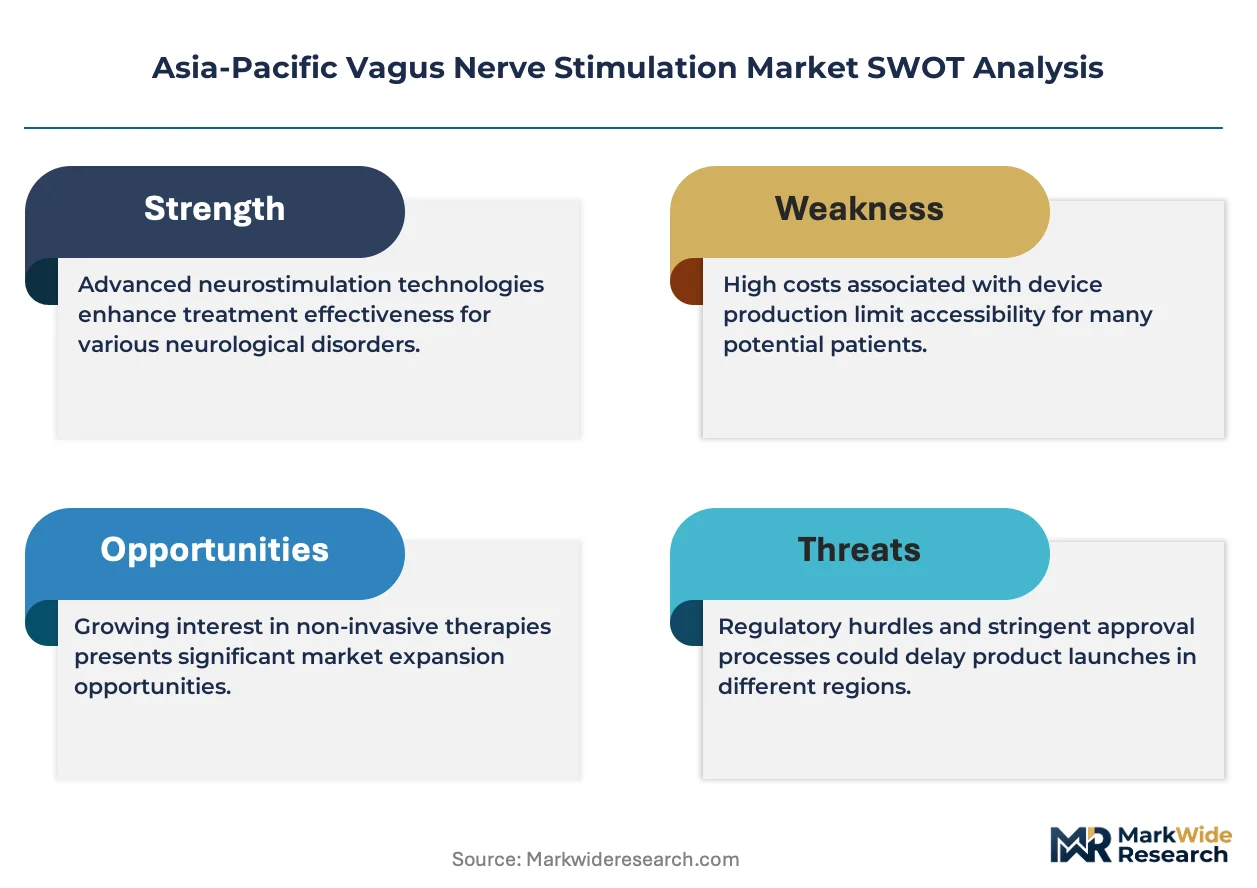
The Asia-Pacific vagus nerve stimulation market is bifurcating around surgical eligibility, with transcutaneous platforms eroding the historical monopoly of implantable systems in outpatient neurology.
Growth Catalysts
- MFDS Streamlined Pathways:South Korea's medical device regulator has compressed review timelines for neurostimulators, accelerating hospital procurement cycles in Seoul's tertiary networks.
- Epilepsy Center Expansion:Australia's major metropolitan hospitals are establishing dedicated neuromodulation units, creating concentrated demand clusters in Melbourne and Sydney.
- Transcutaneous Technology Maturation:Non-invasive vagus nerve stimulation devices now deliver therapeutic efficacy thresholds previously requiring surgical implantation.
Market Restraints
- PMDA Reimbursement Lag:Japan's Ministry of Health, Labour and Welfare maintains differential coverage that disadvantages external devices against implantable alternatives.
- Electromagnetic Compatibility Costs:South Korean testing protocols impose capital-intensive validation requirements that filter smaller manufacturers from market entry.
- Neurosurgical Capacity Constraints:Implantable device growth depends on specialized surgeon availability concentrated in Tier-1 cities across the region.
Strategic Opportunities
- India's CDSCO Draft Guidance:Pending neurostimulator classification rules will clarify import pathways for multinational manufacturers.
- Treatment-Resistant Depression Protocols:Psychiatric institutions in Japan and Australia are piloting vagus nerve stimulation as first-line intervention before pharmaceutical escalation.
- Telemedicine Integration:Remote device programming and patient monitoring platforms are opening rural patient access beyond metropolitan hospital catchments.
Industry Challenges
- Biomedical Engineer Scarcity:Device programming and troubleshooting require specialized training unavailable in most Asia-Pacific biomedical technology curricula.
- Multijurisdictional Registration Burden:Divergent electromagnetic standards between Japan's PMDA, Australia's TGA, and South Korea's MFDS force redundant certification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Vagus Nerve Stimulation Market |
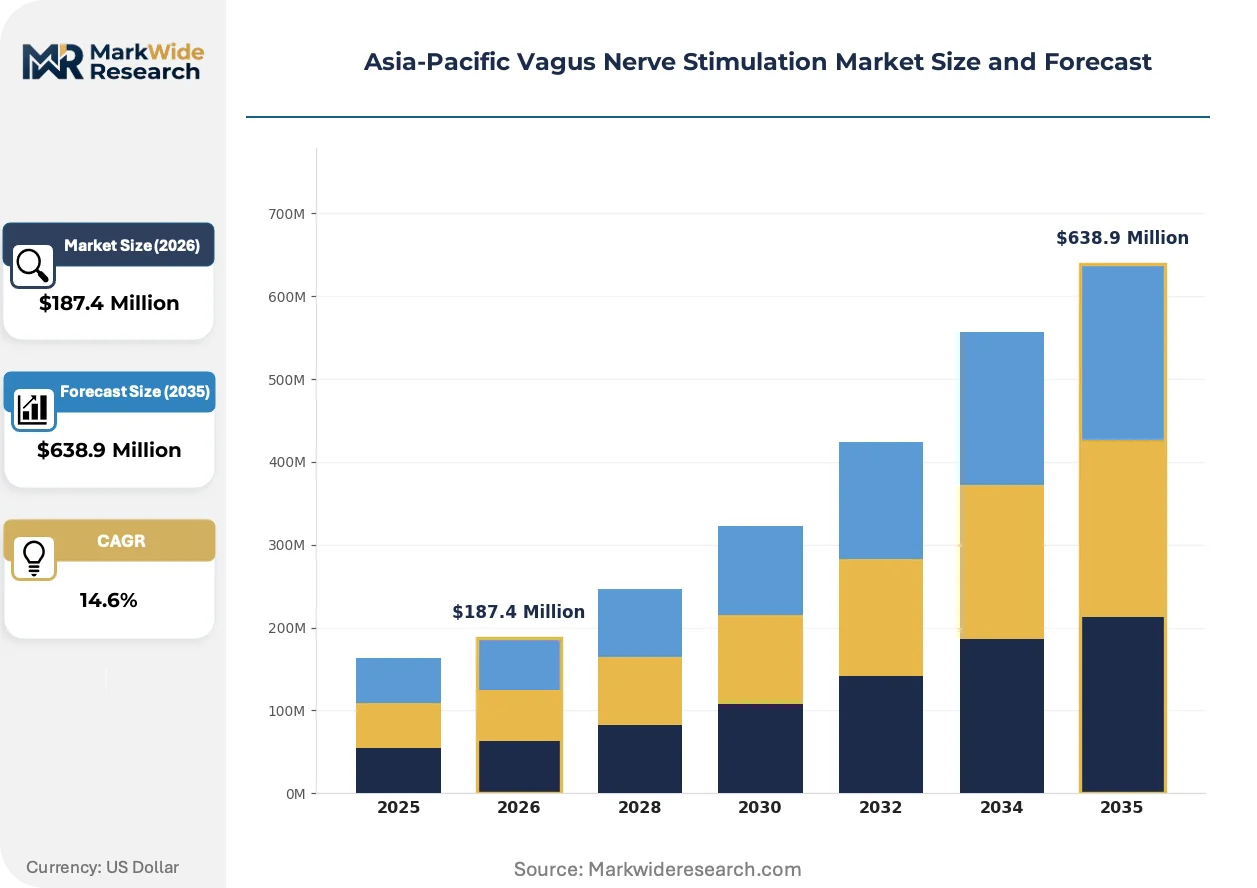
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, External Devices, Accessories, Neurostimulators End User: Hospitals, Clinics, Homecare, Outpatient Facilities Indication: Epilepsy, Depression, Migraine, Heart Failure Technology: Transcutaneous, Invasive, Wireless, Battery-operated |
| Companies Covered | LivaNova PLC, ElectroCore Inc, MicroTransponder Inc, Parasym Ltd, tVNS Technologies GmbH, Soterix Medical Inc, Cerebral, Medtronic Plc, Boston Scientific Corp, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Vagus Nerve Stimulation Market Strategic Shifts
Digital health integration and non-invasive platform advancement are compressing the traditional surgical implantation pathway while expanding addressable patient populations beyond historical eligibility criteria.
Miniaturized pulse generator architectures are decomposing the historical trade-off between device longevity and surgical invasiveness. Seoul-based hospital networks are adopting these platforms for pediatric epilepsy cases previously excluded from implantation protocols. This miniaturization is decomposing the market into discrete service lines segmented by patient age and comorbidity profile rather than unified surgical departments.
PMDA's revised medical device regulations have established a priority review track for neurostimulators with demonstrated equivalence to predicate devices. Japanese manufacturers are leveraging this pathway to compress registration timelines from thirty-six to eighteen months. Implantable pulse generators with closed-loop sensing capabilities receive preferential treatment under these guidelines.
Hospital procurement committees are consolidating vendor relationships around full-service neuromodulation partnerships rather than discrete device transactions. Australia's public hospital networks are negotiating multi-year service agreements bundling devices, programming support, and replacement guarantees. This consolidation is most visible in Victoria's centralized health procurement framework.
Asia-Pacific Vagus Nerve Stimulation Market Segmentation
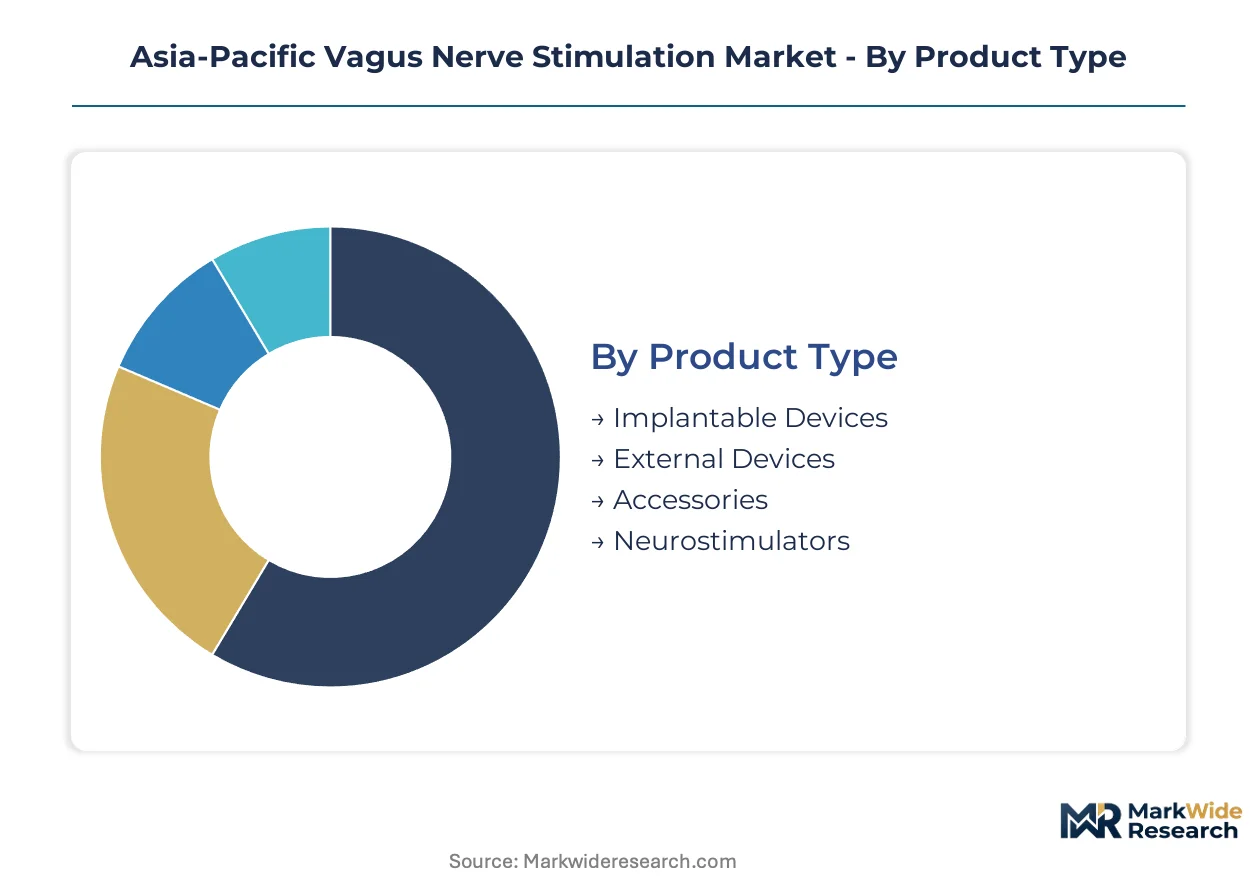
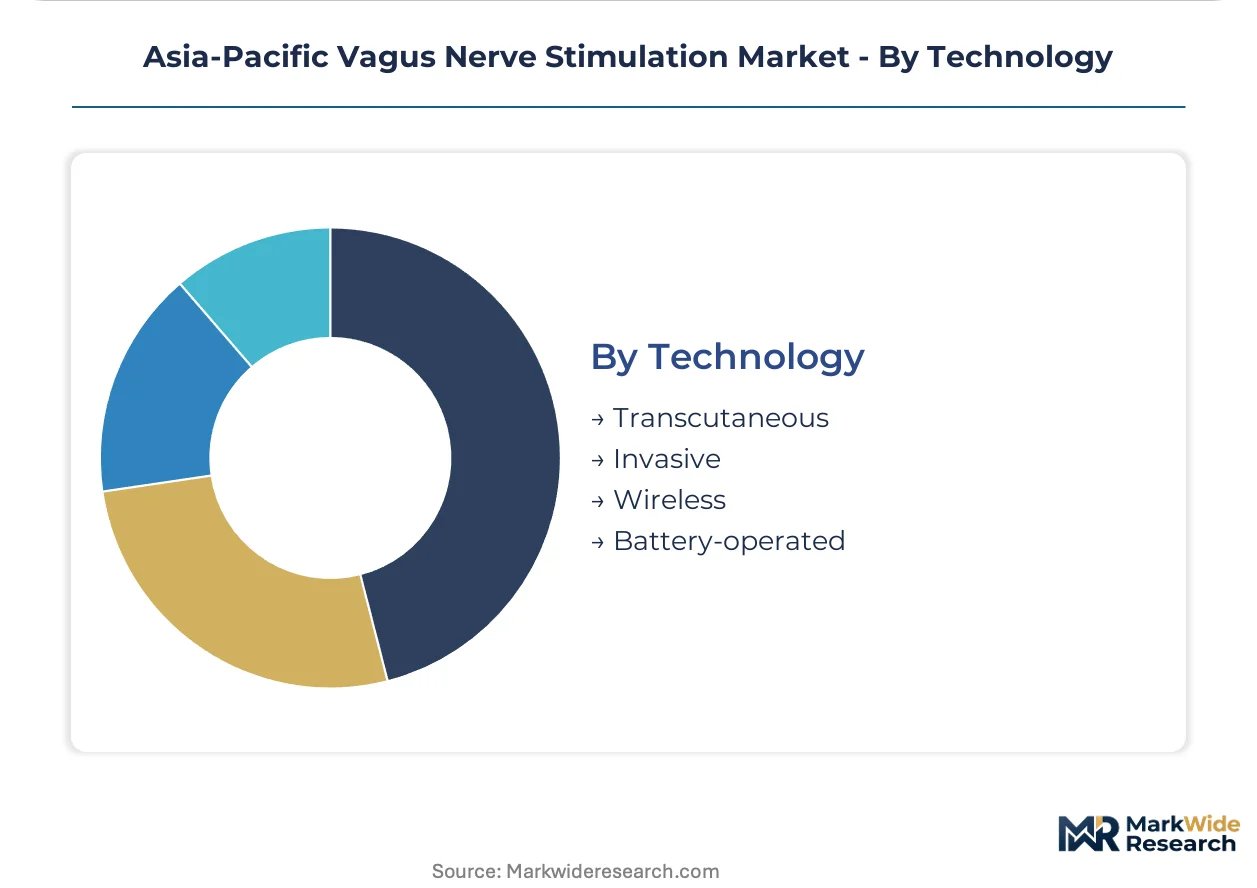
Vagus nerve stimulation markets fragment along surgical eligibility, care setting economics, and regulatory risk tolerance. Segment boundaries determine reimbursement pathways, procurement cycles, and manufacturer margin structures across the Asia-Pacific region.
Product Type:
Margin pools concentrate in devices requiring chronic replacement cycles and specialized surgical support infrastructure.
- Implantable Devices:These systems deliver electrical impulses through surgically embedded pulse generators connected to the cervical vagus nerve. Australia's epilepsy treatment centers in Melbourne and Sydney drive concentrated demand as these institutions expand dedicated neuromodulation units and establish recurring revenue streams from battery replacement procedures.
- External Devices:Transcutaneous platforms apply stimulation through surface electrodes without surgical intervention. Seoul-based hospital networks are building dedicated vagus nerve stimulation service lines around these platforms to capture outpatient psychiatric cases previously excluded from implantable protocols due to surgical risk profiles.
- Accessories:Lead extensions, programming wands, and patient controllers support device ecosystem functionality. South Korea's MFDS electromagnetic compatibility testing protocols favor established manufacturers with integrated accessory portfolios.
- Neurostimulators:The core pulse generation units vary in battery chemistry and programmable parameter ranges. Japan's PMDA priority review track accelerates approval for closed-loop sensing variants.
The dominant share belongs to Implantable Devices, while External Devices is closing the gap fastest.
End User:
Procurement authority and reimbursement rates diverge sharply between institutional settings and decentralized care models.
- Hospitals:Tertiary medical centers in Australia and South Korea capture complex surgical implantations and device programming. Victoria's centralized health procurement framework bundles multi-year service agreements covering devices, support, and replacement guarantees.
- Clinics:Specialized neurology and psychiatric clinics manage patient screening and longitudinal device monitoring. Japan's differential reimbursement coverage disadvantages external device prescriptions in clinic settings relative to hospital-based implantations.
- Homecare:External device adoption enables patient-managed therapy outside institutional settings. Australia's TGA safety surveillance standards require robust remote monitoring infrastructure for homecare deployment.
- Outpatient Facilities:Ambulatory surgical centers and day-procedure units handle low-risk implantations and device replacements. Seoul's tertiary networks are piloting same-day transcutaneous protocols in dedicated outpatient neuromodulation suites.
Hospitals retain the largest volume concentration, though Outpatient Facilities are expanding capacity most rapidly.
Indication:
Addressable patient populations and evidence requirements create divergent commercialization timelines across therapeutic areas.
- Epilepsy:Treatment-resistant epilepsy represents the original approved indication with the deepest clinical evidence base. Australia's expanding epilepsy treatment centers anchor regional demand as these institutions prioritize neuromodulation before pharmaceutical escalation.
- Depression:Treatment-resistant depression protocols are gaining traction in psychiatric institutions across Japan and Australia. Non-invasive platforms are eroding the historical surgical requirement for this indication in outpatient neurology settings.
- Migraine:Chronic migraine applications leverage existing vagus nerve stimulation infrastructure with modified parameter protocols. South Korean hospital networks are building specialized headache clinic service lines around transcutaneous platforms.
- Heart Failure:Cardiovascular autonomic modulation represents an emerging application with distinct regulatory pathways. Japan's PMDA evaluates these devices under cardiac rhythm management rather than neurological device frameworks.
Epilepsy commands the established revenue base, while Depression is gaining regulatory momentum fastest.
Technology:
Engineering architecture determines surgical risk, patient eligibility, and competitive differentiation in procurement decisions.
- Transcutaneous:Surface electrode systems deliver stimulation through the skin without invasive procedures. Australia's psychiatric institutions are piloting these platforms as first-line intervention before pharmaceutical escalation, expanding addressable populations beyond historical surgical candidates.
- Invasive:Implantable lead and generator systems require surgical placement with chronic therapy delivery. Japan's revised medical device regulations compress registration timelines for predicate-equivalent invasive platforms.
- Wireless:Radiofrequency or inductive coupling enables leadless energy transfer and remote parameter adjustment. South Korea's stringent electromagnetic compatibility testing protocols filter smaller manufacturers from wireless platform market entry.
- Battery-operated:Self-contained power systems dominate implantable architectures with defined replacement cycles. Australia's public hospital networks negotiate replacement guarantees as bundled service agreement components.
Invasive platforms retain primacy in surgical departments, though Transcutaneous systems are penetrating outpatient settings most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for implantable pulse generators clusters in Japan and South Korea, where established cardiac rhythm management infrastructure supports neuromodulation device assembly. Australia's public procurement frameworks and India's emerging regulatory clarity are redistributing commercial activity across the region.
Japan
Tokyo's tertiary hospital networks drive demand for closed-loop sensing implantable devices. PMDA's priority review track compresses registration timelines for predicate-equivalent neurostimulators from thirty-six to eighteen months. Osaka-based manufacturers leverage revised medical device regulations to accelerate hospital procurement cycles in the Kansai region.
South Korea
Seoul Capital Area hospital networks are building dedicated vagus nerve stimulation service lines for outpatient psychiatric protocols. MFDS electromagnetic compatibility testing protocols filter smaller manufacturers from market entry. Busan-Ulsan's biomedical engineering clusters supply specialized programming support to tertiary neuromodulation units.
Australia
Melbourne and Sydney epilepsy treatment centers anchor regional demand through expanding neuromodulation programs. TGA safety surveillance standards require robust remote monitoring infrastructure for homecare device deployment. Victoria's centralized health procurement framework bundles multi-year service agreements covering devices and replacement guarantees.
India
Delhi-NCR and Maharashtra hospital systems await CDSCO draft guidance on neurostimulator classification to clarify import pathways. The national pharmaceutical regulator's pending rules will reshape market access for multinational manufacturers. Karnataka's medical device manufacturing zones are positioning for contract assembly partnerships.
China
Shanghai and Beijing hospital networks pilot vagus nerve stimulation for treatment-resistant depression before pharmaceutical escalation. NMPA evaluates neurostimulators under neurological device frameworks distinct from cardiac rhythm management pathways. Yangtze River Delta medical technology clusters are developing localized pulse generator assembly capabilities.
Asia-Pacific Vagus Nerve Stimulation Market Competitive Environment
Concentration sits with diversified medical technology conglomerates and specialized neuromodulation developers. The market structure reflects a tiered configuration where implantable device expertise anchors premium positioning while transcutaneous platforms erode surgical-eligibility barriers. Two strategic archetypes dominate: cardiac rhythm management cross-sellers leveraging existing hospital relationships, and pure-play neuromodulation specialists with deep pulse generator engineering. Competitive moves center on regulatory pathway optimization and service agreement bundling rather than price-based displacement.
Among diversified technology conglomerates, Medtronic Plc and Boston Scientific Corp occupy positions built on cardiac rhythm management infrastructure that extends into neuromodulation cross-selling. Within the specialized neuromodulation tier, LivaNova PLC exemplifies deep implantable pulse generator expertise, while ElectroCore Inc represents the transcutaneous platform vector bypassing surgical requirements. These three anchors illustrate how competitive positioning diverges between invasive and non-invasive technology architectures across Asia-Pacific procurement frameworks.
| Leading Market Players |
|---|
| LivaNova PLC |
| ElectroCore Inc |
| MicroTransponder Inc |
| Parasym Ltd |
| tVNS Technologies GmbH |
| Soterix Medical Inc |
| Cerebral |
| Medtronic Plc |
| Boston Scientific Corp |
| Others |
Value Chain & Pricing Dynamics
Miniaturized pulse generator architectures replacing conventional battery housings are redistributing manufacturing gravity toward South Korea and Japan while compressing premium-tier pricing spreads across the Asia-Pacific region. This substitution simultaneously erodes the cost advantage of legacy implantable platforms and rewards manufacturers with captive semiconductor fabrication partnerships.
Pricing Analysis
Volume-discount tiering structures in Australia's public hospital networks bundle multi-year service agreements covering devices, programming support, and replacement guarantees. Three-tier pricing structure across premium closed-loop systems, standard programmable generators, and economy fixed-parameter units reflects certification grade differentiation under MFDS and PMDA pathways. Pricing pressure stems from Seoul-based hospital networks consolidating vendor relationships around full-service neuromodulation partnerships. Biomedical engineering scarcity in Tier-2 cities renders these institutions most price-sensitive, whereas Tokyo's tertiary centers prioritize sensing capabilities over unit economics.
Supply Chain Analysis
Inventory lead times for implantable pulse generators stretch longest for closed-loop variants requiring specialized ASIC fabrication, compressing for standard programmable units with commodity battery chemistries. Manufacturing clusters concentrate in Japan, South Korea, and China's Yangtze River Delta, drawing from lithium primary cells, biocompatible titanium housings, and platinum-iridium electrode materials. Single-source vulnerability sits with Japanese foundries supplying neuromodulation-specific integrated circuits. Distribution runs through hospital procurement committees consolidating around multi-year vendor partnerships rather than spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: PMDA's eighteen-month priority review track and MFDS electromagnetic compatibility protocols create certification barriers that filter smaller competitors and protect incumbent positioning.
For Market Incumbents: Fortify service agreement bundling in Australia's Victoria centralized procurement framework to lock out transcutaneous platform competitors. Deepen backward integration into pulse generator ASIC design to secure supply continuity against Japanese foundry capacity constraints. The emerging threat of non-invasive platforms eroding surgical-eligibility criteria demands preemptive capture of outpatient facility relationships.
For New Entrants and Emerging Players: Remote device programming and patient monitoring capabilities represent a service-layer gap where incumbents under-serve rural patient populations beyond metropolitan hospital catchments. Target Australia's homecare deployment protocols, where TGA safety surveillance standards require robust infrastructure that established players have underinvested in. A telemedicine-integrated go-to-market angle bypasses the neurosurgical capacity constraints blocking implantable device penetration.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors transcutaneous platform specialists with demonstrated equivalence to invasive efficacy thresholds. Long-term viability over the coming decade hinges on reimbursement parity achievement in Japan's Ministry of Health, Labour and Welfare determinations. The signal to watch is CDSCO's final neurostimulator classification rules, which will clarify whether multinational manufacturers can access India's hospital procurement channels without local assembly partnerships.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Priority Review Track Utilization | Compresses registration timelines from thirty-six to eighteen months for predicate-equivalent neurostimulators. |
| Hospital System Partnership Expansion | Seoul-based networks are building dedicated vagus nerve stimulation service lines around outpatient psychiatric protocols. |
| Telemedicine Integration Development | Remote programming platforms open rural patient access beyond metropolitan hospital catchments in Australia. |
| Closed-Loop Sensing Capability Investment | Tokyo's tertiary centers prioritize these variants, creating premium-tier positioning under revised PMDA guidelines. |
| Reimbursement Strategy Execution | Japan's Ministry of Health, Labour and Welfare determinations will signal non-invasive platform coverage parity. |
Study Parameters
A spread of perspectives from hospital purchasing committee members, biomedical engineering directors, regulatory affairs specialists at PMDA and MFDS, and neuromodulation program clinicians converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against hospital procurement databases, GPO contracts, CMS Medicare data analogs, and neurostimulator registration filings. Bottom-up demand modeling across implantable and external device segments triangulated against top-down market sizing from manufacturer revenue disclosures and replacement cycle assumptions.
Segmentation dimensions modeled span product type, end user setting, therapeutic indication, and technology architecture across the analysis window. CAGRs derive from logistic growth curve fitting anchored to epidemiological prevalence data for treatment-resistant epilepsy and depression, adjusted for reimbursement expansion scenarios. Industry-specific forecast inputs include neurosurgical capacity constraints in Tier-1 cities and electromagnetic compatibility testing protocol evolution under South Korea's MFDS.
Forecasts assume regulatory continuity in Japan's PMDA priority review track, Australia's TGA safety surveillance standards, and South Korea's MFDS electromagnetic compatibility regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact Lens Lubricant Market
Medical Devices
India Medical Devices Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Elbow Fixators Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Printed Electronics in Healthcare Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
Handheld Red Light Therapy Device Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Europe Aligner Sheet Market
Medical Devices
Cytology Brush Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Devices Market
Medical Devices
India Hemostats Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market