
 Asia-Pacific Biosurgery Market | 2026-2036
Asia-Pacific Biosurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Biosurgery Market Analytics
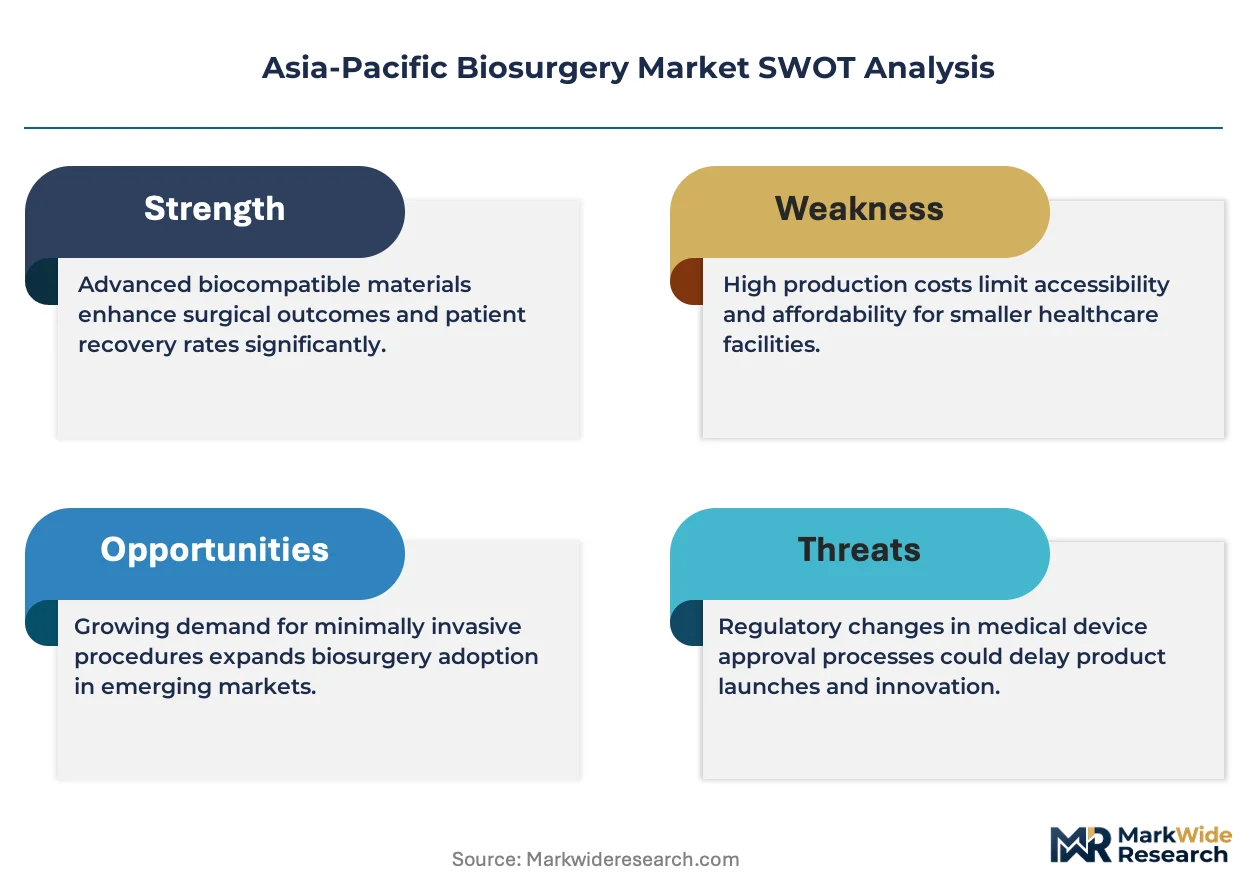
Specialized surgical training capacity is redrawing competitive boundaries across the Asia-Pacific Biosurgery Market. Johnson & Johnson leverages its hemostat portfolio to anchor premium positioning in Japan's university hospital systems. Medtronic sustains R&D intensity in advanced biomaterials for cardiac sealant applications. Baxter International dominates plasma-derived surgical sealant supply through backward integration into protein fractionation.
Asia-Pacific biosurgery encompasses implantable and topical products derived from biological or synthetic polymers that achieve hemostasis, tissue sealing, or adhesion prevention during operative procedures; these materials typically incorporate collagen, gelatin, polysaccharide, or fibrin-based matrices engineered to activate coagulation cascades or form mechanical barriers. The primary commercial purpose centers on reducing operative blood loss, eliminating suture line leaks, and preventing post-surgical adhesions in open and minimally invasive settings. Hemostat demand leads product type revenue generation due to universal application across surgical disciplines, while sealants capture expanding share in cardiovascular and spinal fusion procedures where suture reinforcement proves critical. Hospitals remain the dominant end user channel, though ambulatory surgical centers represent the fastest-growing site of care as regional health systems push same-day joint and cardiac interventions.
Japan's PMDA enforces stringent biocompatibility and viral inactivation standards for fibrin sealants, elevating compliance costs for multinational entrants while protecting domestic manufacturers with established quality systems. Australia's TGA aligns with EU MDR equivalence pathways, streamlining approval for CE-marked biosurgery products but requiring local clinical evidence for novel regenerative formulations. China's NMPA accelerates review timelines for innovative medical devices under priority review channels, reshaping launch sequencing for tissue-engineered hemostats. Stakeholders must monitor evolving national reimbursement lists and biologics pricing negotiations that determine commercial viability independent of regulatory clearance.
Market Dynamics
India's PLI scheme for medical devices is redrawing manufacturing geography across the Asia-Pacific Biosurgery Market, pulling production capacity eastward while Japan's PMDA maintains the region's most demanding biocompatibility standards.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework accelerates domestic hemostat manufacturing capacity, reducing import dependence for tertiary hospital networks.
- Cardiovascular sealant applications:Cardiac surgery departments in China's eastern province hospital networks are expanding fibrin-based product utilization for suture line reinforcement.
- Same-day intervention protocols:Ambulatory surgical centers across Australia and South Korea are adopting topical biosurgery products for outpatient joint and cardiac procedures.
Market Restraints
- Fibrinogen raw material concentration:Plasma-derived protein fractionation capacity concentrates among a limited set of specialized suppliers, creating input cost volatility for sealant manufacturers.
- PMDA viral inactivation requirements:Japan's biocompatibility standards impose extended validation timelines that elevate compliance expenditure for novel biomaterial entrants.
- Synthetic polymer substitution:Polyethylene glycol-based synthetic sealants are capturing select applications where immunogenicity concerns limit biological product adoption.
Strategic Opportunities
- Vietnam's hospital modernization:Underpenetrated provincial health networks in Vietnam present first-mover positioning for collagen-based hemostat suppliers establishing distribution partnerships.
- Priority review channels:China's NMPA accelerated review pathway for innovative medical devices compresses launch sequencing for tissue-engineered formulations.
- Minimally invasive convergence:Laparoscopic delivery systems combined with flowable hemostats are opening spinal fusion applications previously restricted to open procedures.
Industry Challenges
- Specialized surgical training scarcity:Advanced sealant application techniques require hands-on credentialing programs that tertiary hospital systems struggle to scale across regional networks.
- Dual certification complexity:Manufacturers targeting both Japan's PMDA and Australia's TGA must maintain parallel quality systems despite divergent viral inactivation evidence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Biosurgery Market |
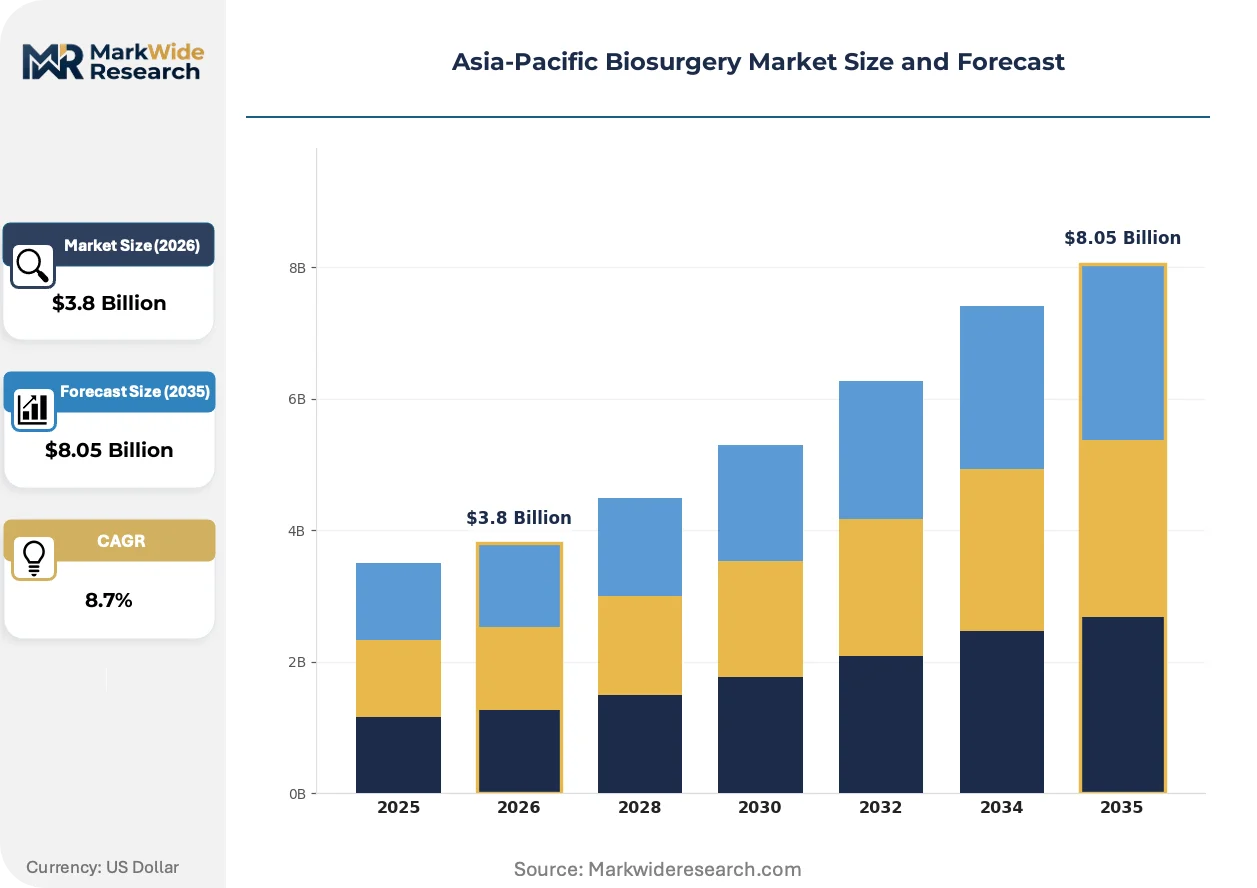
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Staplers, Sealants, Hemostats Application: Surgery, Wound Care, Orthopedics, Cardiology End User: Hospitals, Clinics, Ambulatory Surgical Centers, Trauma Centers Technology: Advanced Biomaterials, Biotechnology, Regenerative Medicine, Tissue Engineering |
| Companies Covered | Johnson & Johnson, Medtronic, Stryker, B. Braun, Integra LifeSciences, Baxter International, Boston Scientific, Zimmer Biomet, BD, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Biosurgery Market Evolving Landscape
Biomaterial engineering is compressing product form factors while regulatory convergence and procurement centralization are redrawing commercial access patterns across the Asia-Pacific Biosurgery Market.
Flowable hemostat formulations incorporating oxidized regenerated cellulose are miniaturizing delivery systems for arthroscopic and endoscopic channels. Orthopedic surgery departments in South Korea's university hospital systems are adopting these formulations at accelerated pace for outpatient rotator cuff repairs. The technology is miniaturizing access requirements, enabling same-day discharge protocols that were previously restricted to inpatient settings.
China's NMPA priority review channel for innovative medical devices is compressing approval timelines for novel regenerative formulations. The policy shift permits domestic manufacturers to reach commercial scale faster than multinationals relying on traditional review pathways. Tissue-engineered hemostats with active biologic components are capturing disproportionate benefit from this regulatory tailwind.
Hospital procurement consortia in Australia's eastern states are consolidating biosurgery purchasing through centralized tender frameworks. Single-source agreements for hemostat and sealant categories are displacing multi-vendor arrangements that previously dominated supply contracts. The concentration is most visible in Queensland's public hospital network, where standardized product formularies now govern 80 percent of biosurgery expenditure.
Asia-Pacific Biosurgery Market Segmentation
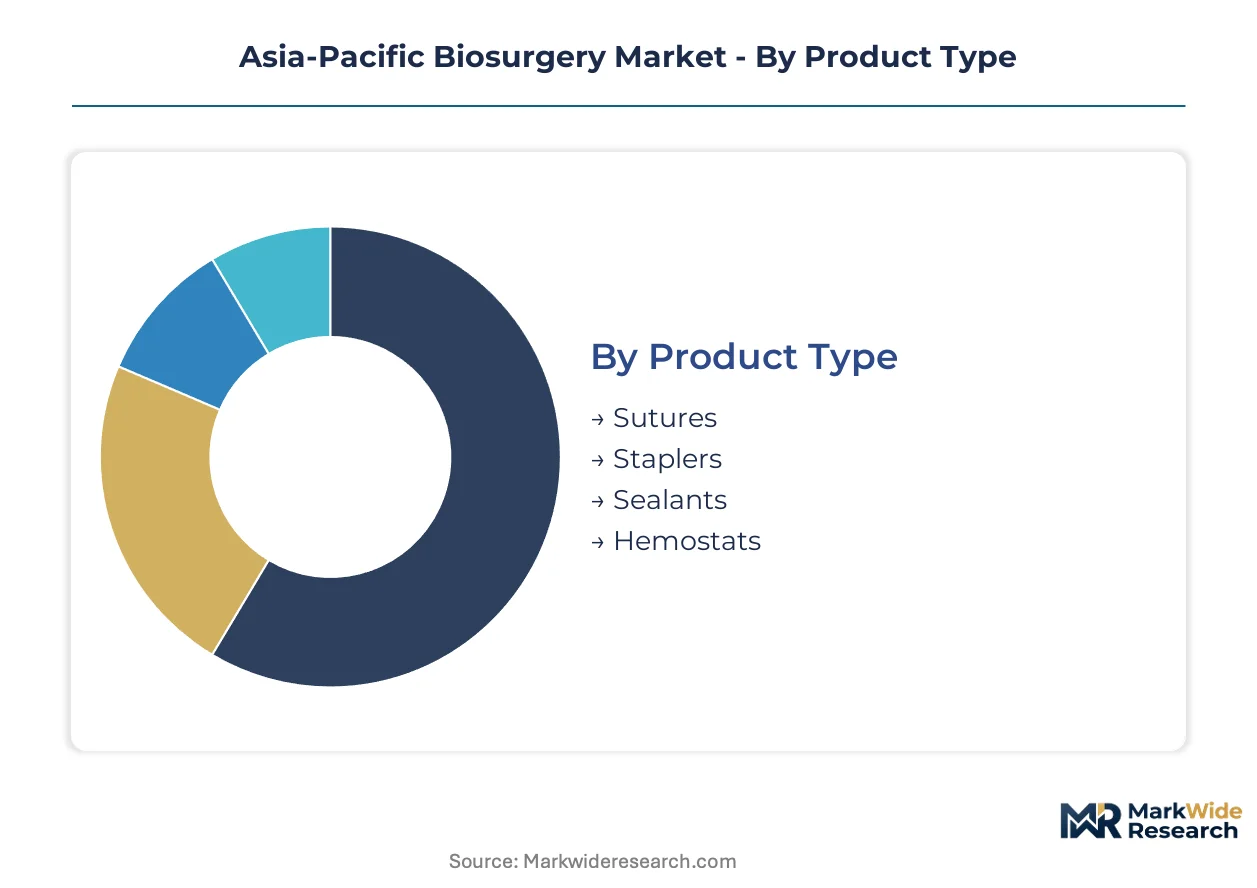
Segmentation in the Asia-Pacific Biosurgery Market reveals distinct substitution dynamics across product categories. Synthetic polymer alternatives and mechanical closure methods compete directly with biological products in price-sensitive procurement environments.
Product Type:
Synthetic polymer substitutes exert concentrated pressure on biological sealants and hemostats, while mechanical closure devices face limited functional displacement.
- Hemostats:These products incorporate collagen, gelatin, or oxidized regenerated cellulose matrices engineered to activate coagulation cascades at surgical sites. China's eastern province hospital networks are expanding hemostat utilization for orthopedic and cardiac procedures where blood loss reduction proves critical. India's PLI scheme accelerates domestic manufacturing capacity for these products.
- Sealants:Fibrin-based and synthetic polymer formulations create mechanical barriers for suture line reinforcement. Cardiac surgery departments in Japan's university hospital systems drive premium demand for plasma-derived sealants despite PMDA viral inactivation compliance costs. Baxter International's backward integration into protein fractionation secures raw material supply.
- Sutures:Mechanical closure devices retain universal application across surgical disciplines with established reimbursement pathways.
- Staplers:Surgical stapling systems serve high-volume abdominal and thoracic procedures where speed outweighs biological product costs.
Hemostats retain volume leadership; sealants hold the steepest expansion curve.
Application:
Cost tier differentiation separates high-complexity inpatient procedures from outpatient interventions where product economics tighten.
- Surgery:General surgical applications encompass open and minimally invasive procedures requiring hemostasis and tissue sealing across multiple specialties.
- Orthopedics:Spinal fusion and joint replacement procedures utilize flowable hemostat formulations for bone bleeding control. South Korea's university hospital systems adopt miniaturized delivery systems for arthroscopic channels.
- Cardiology:Cardiovascular sealant applications demand suture line reinforcement in cardiac surgery. China's eastern province hospital networks expand fibrin-based product utilization for these procedures.
- Wound Care:Topical biosurgery products serve chronic and acute wound management with lower technical complexity than operative applications.
Surgery anchors volume concentration; cardiology displays the most rapid uptake acceleration.
End User:
Procurement centralization varies sharply between consolidated hospital networks and fragmented outpatient settings.
- Hospitals:Tertiary hospital systems dominate biosurgery expenditure through standardized product formularies and volume contracting. Australia's Queensland public hospital network consolidates purchasing through centralized tender frameworks.
- Ambulatory Surgical Centers:Same-day intervention protocols drive topical product adoption for outpatient joint and cardiac procedures. Australia's eastern states and South Korea lead this site-of-care shift.
- Clinics:Primary care and specialty clinics utilize lower-complexity hemostasis products for minor surgical interventions.
- Trauma Centers:Emergency surgical facilities require rapid-acting hemostats for acute bleeding control in critical care settings.
Hospitals maintain procurement dominance; ambulatory surgical centers are climbing the fastest.
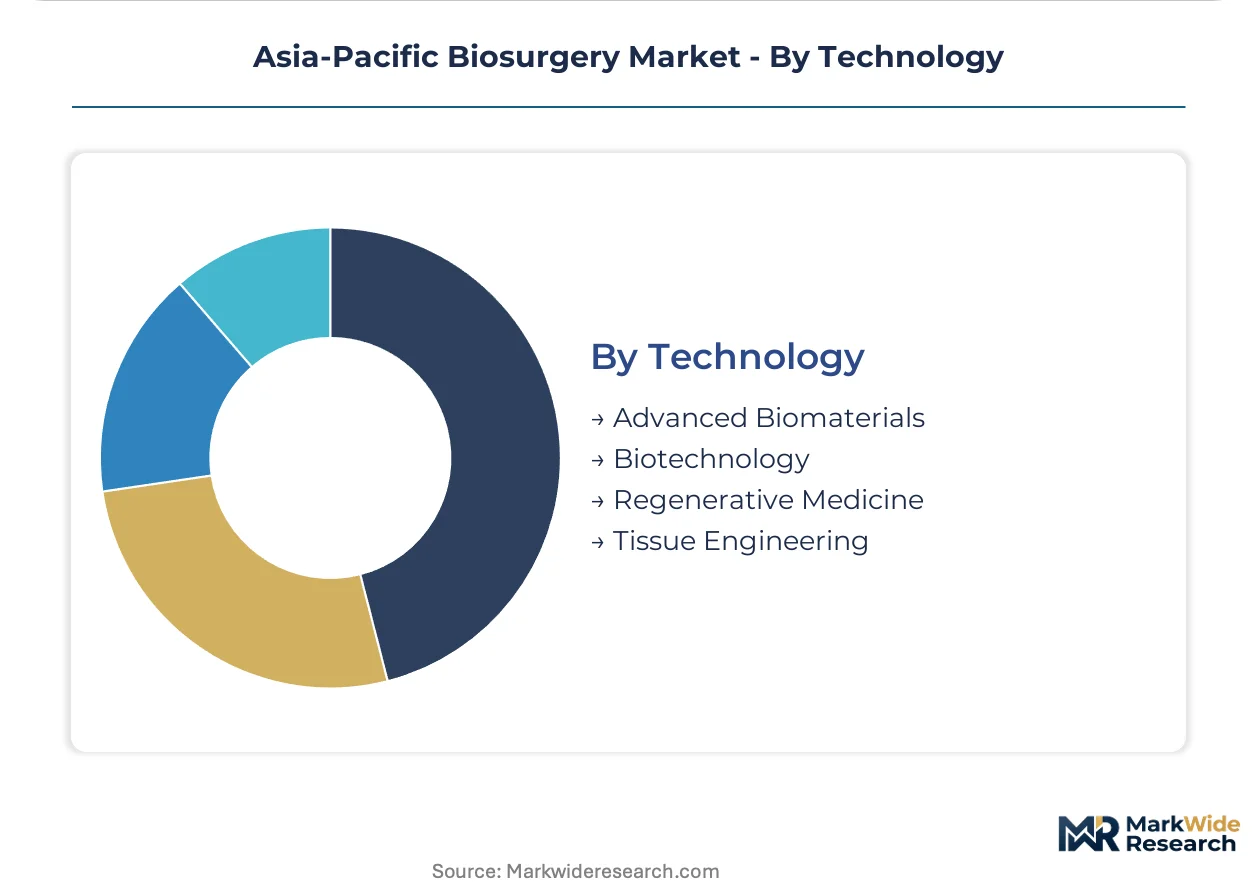
Technology:
Regulatory maturity separates established biomaterial platforms from emerging regenerative approaches facing extended validation timelines.
- Advanced Biomaterials:Engineered collagen, gelatin, and polysaccharide matrices constitute the commercial core of hemostat and sealant products with established PMDA and TGA clearance pathways.
- Tissue Engineering:Active biologic components and tissue-engineered hemostats capture disproportionate benefit from China's NMPA priority review channel for innovative medical devices.
- Biotechnology:Recombinant protein production and enzymatic processing technologies support scalable manufacturing of biological active ingredients.
- Regenerative Medicine:Cell-based and growth factor-enhanced formulations face extended clinical evidence requirements in Japan's stringent regulatory environment.
Advanced biomaterials command current revenue concentration; tissue engineering displays the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PMDA's biocompatibility standards anchor Japan's premium positioning while NMPA's priority review channels accelerate China's domestic manufacturer scale-up. India's PLI scheme and Australia's TGA equivalence pathways complete the regulatory mosaic shaping commercial access across the region.
China
Eastern province hospital networks drive fibrin-based sealant demand for cardiovascular suture line reinforcement. NMPA's priority review channel compresses approval timelines for tissue-engineered hemostats with active biologic components. Shanghai and Beijing medical device clusters host domestic manufacturers capturing disproportionate regulatory tailwind.
Japan
University hospital systems sustain premium demand for plasma-derived surgical sealants despite elevated compliance costs. PMDA enforces the region's most stringent viral inactivation and biocompatibility validation standards. Tokyo and Osaka metropolitan medical centers concentrate procurement volume through standardized product formularies.
India
Tertiary hospital networks are expanding biosurgery product utilization as domestic manufacturing capacity accelerates. The PLI scheme for medical devices pulls production eastward, reducing import dependence for hemostat categories. Maharashtra and Gujarat industrial corridors anchor new manufacturing investments targeting hospital procurement centralization.
Australia
Ambulatory surgical centers across eastern states adopt topical biosurgery products for same-day joint and cardiac interventions. TGA aligns with EU MDR equivalence pathways, streamlining approval for CE-marked products while requiring local clinical evidence for novel regenerative formulations. Queensland's public hospital network consolidates purchasing through centralized tender frameworks governing the majority of biosurgery expenditure.
South Korea
University hospital systems accelerate adoption of miniaturized flowable hemostat formulations for arthroscopic channels. MFDS maintains regulatory standards supporting orthopedic surgery department expansion. Seoul metropolitan medical clusters lead outpatient rotator cuff repair protocols enabling same-day discharge previously restricted to inpatient settings.
Asia-Pacific Biosurgery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Biosurgery Market. The vendor base concentrates around diversified medical technology conglomerates with established hospital system relationships and specialized biomaterial manufacturers with captive protein fractionation capabilities. Three archetypes dominate: premium-tier multinationals with backward-integrated plasma supply, mid-scale regional specialists leveraging PLI incentives, and emerging domestic players capturing NMPA priority review benefits. Competitive moves center on strategic partnerships with hospital procurement consortia and portfolio diversification into flowable delivery systems for minimally invasive channels.
Among diversified medical technology conglomerates, Johnson & Johnson and Medtronic occupy positions exemplifying premium-tier positioning through established university hospital system relationships. Baxter International anchors the plasma-derived supply archetype through in-house protein fractionation capabilities. These three entities represent distinct competitive vectors: technology-intensive R&D positioning, cardiac sealant specialization, and raw material supply security respectively.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Stryker |
| B. Braun |
| Integra LifeSciences |
| Baxter International |
| Boston Scientific |
| Zimmer Biomet |
| BD |
| Others |
Value Network & Pricing Analysis
Plasma fractionation scale economies in Japan and the United States anchor global fibrinogen supply, concentrating raw material pricing power among three specialized suppliers while elevating cost floors for sealant manufacturers lacking backward integration into protein processing. This concentration propagates through hospital procurement networks, where tertiary systems absorb premium pricing for viral-inactivated products while price-sensitive provincial networks in Vietnam and Indonesia gravitate toward synthetic polymer alternatives.
Pricing Analysis
Japan commands a 40-60% premium over India's domestic hemostat pricing due to PMDA viral inactivation compliance costs and university hospital procurement standards. Three-tier pricing structure across premium, standard, and economy levels separates plasma-derived sealants from recombinant formulations and synthetic polyethylene glycol products. Cost compression in India's standard tier is intensifying because PLI scheme incentives attract domestic manufacturers competing on volume scale. Provincial hospital networks in Vietnam and Indonesia exhibit highest price sensitivity; Tokyo and Osaka metropolitan medical centers show least.
Supply Chain Analysis
Container availability constraints on Asia-Pacific trade lanes elevate inbound logistics costs for European and North American plasma-derived inputs, compressing margins for manufacturers without regional fractionation assets. Fibrinogen supply concentrates in Japan, the United States, and Germany; hemostat matrix production clusters in China, India, and South Korea. Raw material dependencies span cryoprecipitate, oxidized regenerated cellulose, and collagen peptides. Single-source vulnerability in plasma fractionation capacity creates structural risk. Distribution runs through hospital procurement consortia and specialized surgical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's NMPA priority review channel for innovative medical devices compresses commercialization timelines, creating a regulatory inflection that rewards domestic manufacturers with active biologic formulations while challenging multinational incumbents dependent on traditional pathways.
For Market Incumbents: Fortify university hospital system relationships in Japan through expanded surgical training credentialing programs that lock in premium sealant utilization. Deepen backward integration into protein fractionation to offset fibrinogen raw material volatility. Counter emerging domestic Chinese manufacturers by accelerating CE marking for tissue-engineered formulations targeting Australia's TGA equivalence pathway. For New Entrants and Emerging Players: Differentiate on laparoscopic delivery system miniaturization for South Korean and Australian ambulatory surgical center networks. Target Vietnam's underpenetrated provincial health infrastructure with economy-tier collagen hemostats distributed through local surgical device partnerships. Prioritize China's NMPA priority review channel for tissue-engineered hemostats with active biologic components. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized biomaterial manufacturers with captive plasma fractionation capabilities over diversified medical technology conglomerates dependent on external fibrinogen supply. Five-to-ten year viability hinges on regulatory navigation capacity across PMDA, NMPA, and TGA frameworks. Watch for consolidation signals when hospital procurement consortia shift from multi-vendor to single-source agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Fractionation | Captive fibrinogen supply secures raw material cost stability for sealant manufacturers against plasma market volatility. |
| NMPA Priority Review Channel Submission | Accelerated approval timelines compress commercialization sequencing for tissue-engineered hemostats in China. |
| Hospital System Partnership | Standardized product formularies in Queensland's public network lock in volume contracting for hemostat suppliers. |
| Surgical Training Credentialing Program | Hands-on certification programs in Japan's university hospitals create switching costs for premium sealant users. |
| Minimally Invasive Delivery System Development | Miniaturized flowable hemostat applicators enable arthroscopic procedures in South Korea's outpatient settings. |
Research Methodology
A spread of perspectives from cardiac surgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions shaping demand forecasts. Primary interviews combined with secondary validation against PMDA submission databases, NMPA approval records, hospital procurement tender documents, and TGA equivalence pathway guidance. Bottom-up product-level volume builds triangulated against top-down macro healthcare expenditure projections across the analysis window.
Segmentation dimensions modeled span product type, application specialty, end-user facility tier, and technology platform maturity across the projection horizon. CAGRs derived from historical procedure volume growth, product penetration curves, and pricing trajectory analysis. Forecast inputs incorporated PLI scheme capacity buildout timelines, NMPA review velocity trends, and ambulatory surgical center expansion rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory priority review momentum, stable plasma fractionation supply, or continued hospital procurement centralization would require recalibration. Forecasts reflect documented assumptions regarding reimbursement list inclusion and biologics pricing negotiation outcomes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Gracey Curette Market
Medical Devices
Japan Artificial Organs and Bionic Implants Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Global Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Next Generation Nebulizers Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Global Electrotherapy System Market
Medical Devices
Sphincterotomes Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Hearing Aids Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market