
 Global EV Charger Market | 2026-2036
Global EV Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Global EV Charger Market Analysis
The gap between premium 350kW DC hardware and commodity Level 2 residential units is realigning procurement patterns across fleet and consumer channels. ABB leverages its power electronics heritage to anchor European highway corridor deployments. Tesla sustains proprietary connector dominance in North American destination charging while navigating open-standard transition risks. BYD controls integrated battery-to-charger supply chains that underpin its cost position in Asian fleet tenders.
An EV charger converts grid electricity into direct-current power matched to battery chemistry, with DC fast chargers requiring liquid-cooled cable assemblies rated above 500 amperes to prevent thermal derating during sustained 350kW sessions. AC chargers retain cost advantages for overnight residential and workplace installations where dwell times exceed eight hours. DC chargers capture the fastest growth trajectory as commercial fleets and highway operators prioritize throughput over unit economics. Wireless inductive systems occupy niche premium positioning in automated guided vehicle and luxury residential applications where connector wear represents a liability.
The EU Green Deal and F-Gas Regulation shape thermal management refrigerant choices in European charger manufacturing, while China's GB/T standards and dual carbon goals mandate domestic interoperability protocols that condition market access. The US NHTSA and FAA coordinate on electric fleet safety standards that influence charger enclosure and cable specifications for commercial vehicle depots. Stakeholders must monitor which connector standard—CCS, NACS, or GB/T—achieves regulatory preference in target geographies before committing manufacturing capacity.
Market Dynamics
Fleet electrification timelines are compressing procurement cycles for high-amperage DC hardware, forcing charger manufacturers to align liquid-cooled cable production with automotive OEM platform launches rather than aftermarket demand curves.
Growth Catalysts
- EU Green Deal mandates:Germany's ICE phase-out law and France's national low-carbon transport framework are mandating highway corridor DC fast-charger density minimums that pull forward infrastructure investment.
- Coastal manufacturing clusters:China's state grid partnerships in Guangdong and Jiangsu provinces are bundling charger deployment with industrial zone electrification, creating captive demand for integrated battery-to-charger systems.
- Fleet depot electrification:North American logistics operators are consolidating charging procurement around overnight DC fast-charging to maximize vehicle utilization rates and minimize dwell-time penalties.
Market Restraints
- Copper and silicon carbide cost volatility:Power semiconductor substrates and high-conductivity cable assemblies face raw material price swings that compress hardware margins on fixed-price municipal tenders.
- Connector standard fragmentation:The unresolved competition between CCS, NACS, and GB/T physical interfaces forces manufacturers to maintain redundant tooling lines and inventory buffers.
- Grid interconnection queues:Distribution network upgrade timelines in dense urban corridors delay commercial commissioning by 12-18 months beyond hardware delivery schedules.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives for power electronics and thermal management subsystems are attracting charger assembly investments ahead of passenger EV volume ramp.
- Wireless inductive integration:Automated guided vehicle fleets in warehouse and port automation are adopting contactless charging pads that eliminate connector wear in high-cycle environments.
- V2G bidirectional protocols:IEEE 2030.5 and ISO 15118-20 standardization is enabling fleet operators to monetize battery capacity as grid storage, transforming chargers into revenue-generating assets.
Industry Challenges
- High-voltage safety certification timelines:UL 2594 and IEC 61851-23 testing protocols for 1000V DC systems require 8-14 month validation cycles that lag product development schedules.
- Thermal engineering talent scarcity:Liquid-cooled cable and refrigerant-based enclosure design expertise concentrates among automotive HVAC specialists, creating hiring bottlenecks for charger OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global EV Charger Market |
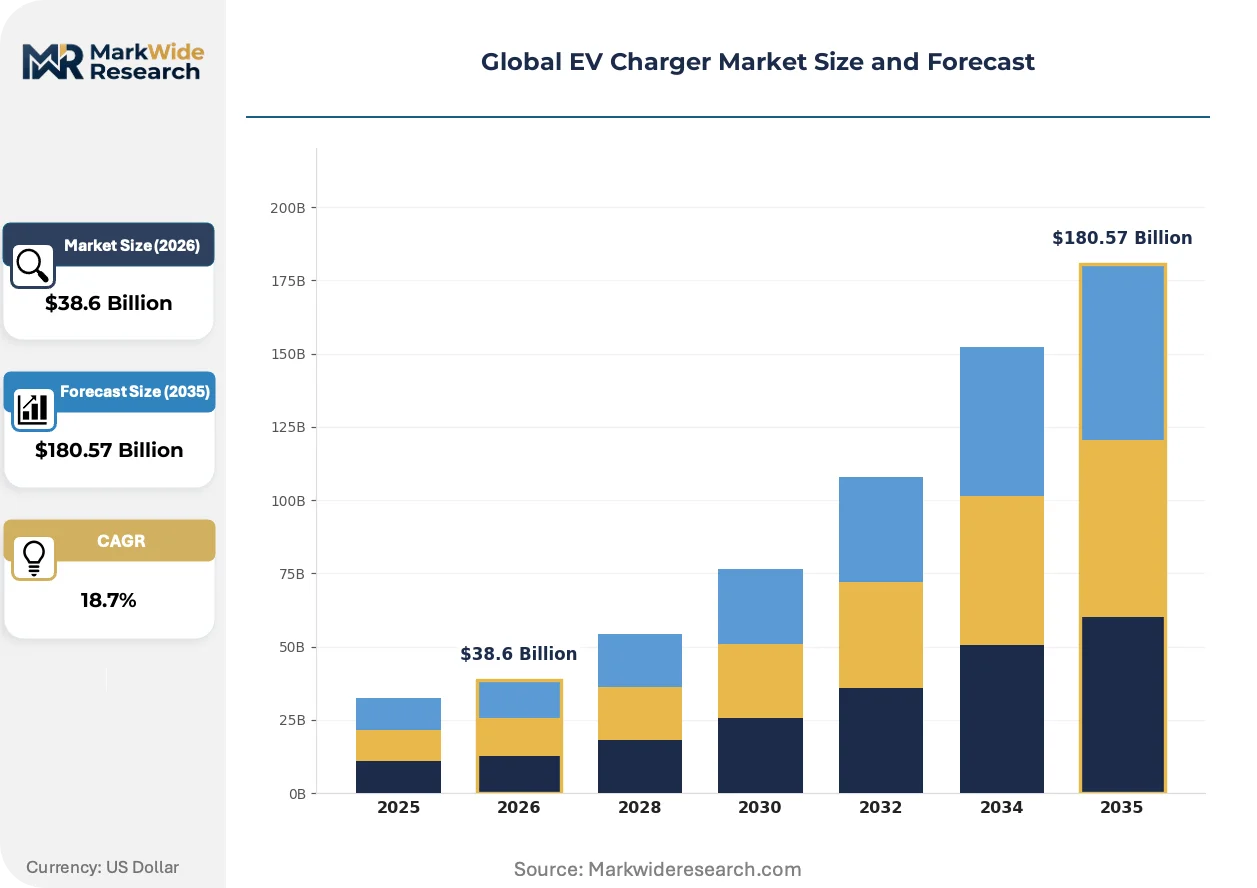
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $180.57 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Chargers, Wireless Chargers, Bidirectional Chargers Technology: Plug-in, Inductive Charging, Conductive Charging, Battery Swapping Application: Public Charging Stations, Workplace Charging, Fleet Charging, Destination Charging End User: Electric Utilities, Commercial Fleets, Municipalities, Individual Consumers |
| Companies Covered | ChargePoint, ABB, Tesla, EVBox, Eaton, BYD, Delta Electronics, Wallbox, TELD New Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global EV Charger Market Emerging Trajectories
Silicon carbide power electronics and dynamic load management software are converging to reshape charger architecture, enabling higher power density without proportional increases in footprint or cooling infrastructure.
Silicon carbide MOSFETs are replacing legacy IGBT modules in DC fast-charger power conversion stages, cutting switching losses by half and enabling 350kW output from compact skid-mounted enclosures. Highway corridor operators in Germany and the Netherlands are specifying SiC-based hardware for new tender rounds to minimize transformer footprint at constrained service plazas. This semiconductor transition is integrating thermal management and power electronics design into unified engineering disciplines that incumbent industrial players must acquire or partner to access.
The EU F-Gas Regulation is banning refrigerants with global warming potential above 150 in new charger production from 2027, forcing manufacturers to redesign liquid-cooled cable and enclosure cooling loops around CO2 or hydrofluoroolefin alternatives. European charger assembly lines are retooling coolant circuit architectures and pressure-testing protocols to accommodate lower-density refrigerants with different thermal transfer coefficients. This environmental compliance burden falls heaviest on high-power highway chargers where sustained 350kW sessions demand active thermal management rather than passive convection.
Buyers are consolidating procurement around performance-based service contracts that bundle hardware, installation, maintenance, and energy management into single-vendor relationships with uptime guarantees. Fleet operators in California and Texas are displacing transactional equipment purchases with 10-year availability agreements that transfer operational risk to charger providers. This contractual evolution is most advanced in commercial vehicle depot electrification, where downtime penalties exceed hardware amortization costs and operators lack in-house electrical maintenance capabilities.
Global EV Charger Market Segmentation
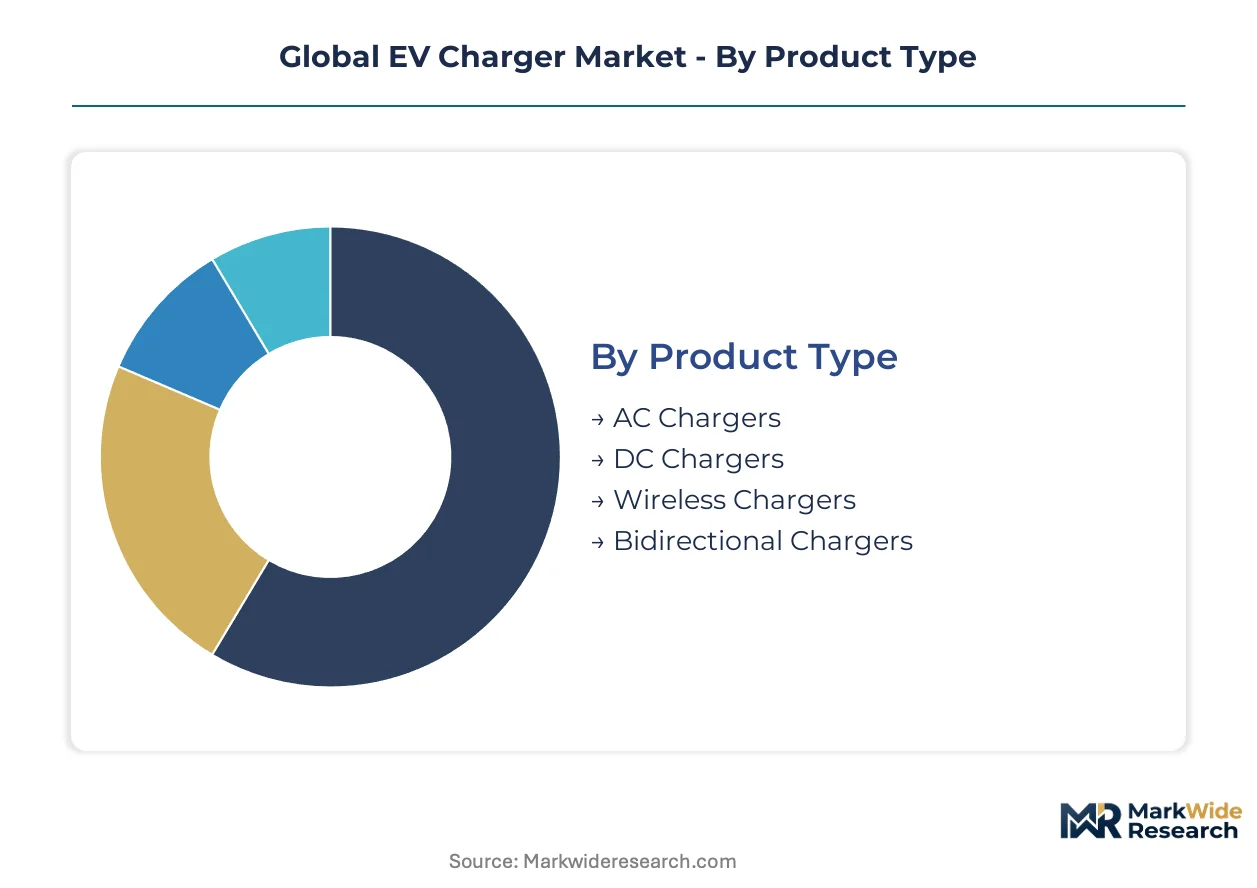
Charger procurement patterns diverge sharply across power levels, installation contexts, and ownership models. Fleet operators prioritize DC hardware with service contracts, while residential buyers favor AC units with minimal installation complexity. Understanding these segment boundaries clarifies where margin pools concentrate and which technical specifications command pricing power.
Product Type:
The customization-vs-standardization spectrum runs from commodity AC hardware with universal connectors to liquid-cooled DC systems requiring site-specific thermal engineering.
- AC Chargers:These units convert alternating current from residential or commercial panels to vehicle-compatible DC through onboard inverters, typically delivering 7-22kW. Demand concentrates in German and Dutch suburban housing developments where overnight dwell times exceed ten hours and grid upgrades remain minimal. Standardization around IEC 61851-1 keeps hardware costs low but compresses margins for assembly-only manufacturers.
- DC Chargers:Off-board power conversion enables 50-350kW direct current delivery, requiring silicon carbide MOSFETs and actively cooled cable assemblies. Fleet depots in California and Texas are consolidating procurement around these units to minimize vehicle downtime during shift changes. Site preparation costs often exceed hardware prices, favoring vendors with integrated electrical contracting capabilities.
- Wireless Chargers:Inductive pads using resonant magnetic coupling transfer power across air gaps up to 25cm, eliminating connector wear in automated warehouse environments.
- Bidirectional Chargers:V2G-capable hardware enables battery discharge back to grid or building loads, attracting municipal utility pilots in Japan and Denmark.
Most installed capacity flows through AC Chargers. Expansion is steepest in DC Chargers.
Technology:
Cost tier separation distinguishes mature conductive methods from capital-intensive alternatives still seeking volume scale.
- Plug-in:Physical connector interfaces—CCS, NACS, GB/T—dominate volume, with cable and handle assemblies representing 15-20% of total hardware cost. China's state grid partnerships in Guangdong province mandate GB/T compatibility, while German highway tenders now require CCS2 with liquid-cooled cables for 350kW capability. Connector fragmentation forces manufacturers to maintain redundant tooling lines.
- Inductive Charging:Magnetic resonance systems eliminate physical contact, commanding 3-4x hardware premiums that limit adoption to luxury residential and automated guided vehicle fleets where connector reliability failures carry high downtime costs.
- Conductive Charging:Pantograph and overhead catenary systems serve electric bus depots in France and the Netherlands with megawatt-level power transfer.
- Battery Swapping:Automated exchange stations replace depleted packs with charged units in under five minutes, deployed by NIO in Chinese urban corridors where apartment dwellers lack home charging access.
Plug-in infrastructure retains the largest footprint. Battery Swapping is gaining share fastest where residential parking constraints persist.
Application:
Customer type and volume concentration reshape how charger specifications translate to contract structures and service obligations.
- Public Charging Stations:Highway corridor and urban fast-charging hubs prioritize throughput and uptime guarantees, with German autobahn operators specifying 99% availability penalties in tender documents. These installations require redundant power modules and remote diagnostic capabilities that add 30-40% to base hardware costs.
- Workplace Charging:Employer-sited AC and mid-power DC units serve daytime dwell patterns, with California's Title 24 building code mandating EV-ready parking ratios that pull forward installation timelines ahead of vehicle fleet turnover.
- Fleet Charging:Depot-based DC fast-charging for logistics and transit operators emphasizes vehicle utilization rates over energy margins, with 10-year availability contracts displacing transactional equipment sales in North American markets.
- Destination Charging:Hotels, retail centers, and entertainment venues deploy slower AC units to extend customer dwell times, with hardware often subsidized by property marketing budgets rather than direct user fees.
Public Charging Stations absorb the majority of capital deployment. Fleet Charging shows the steepest contract value growth as operators outsource operational risk.
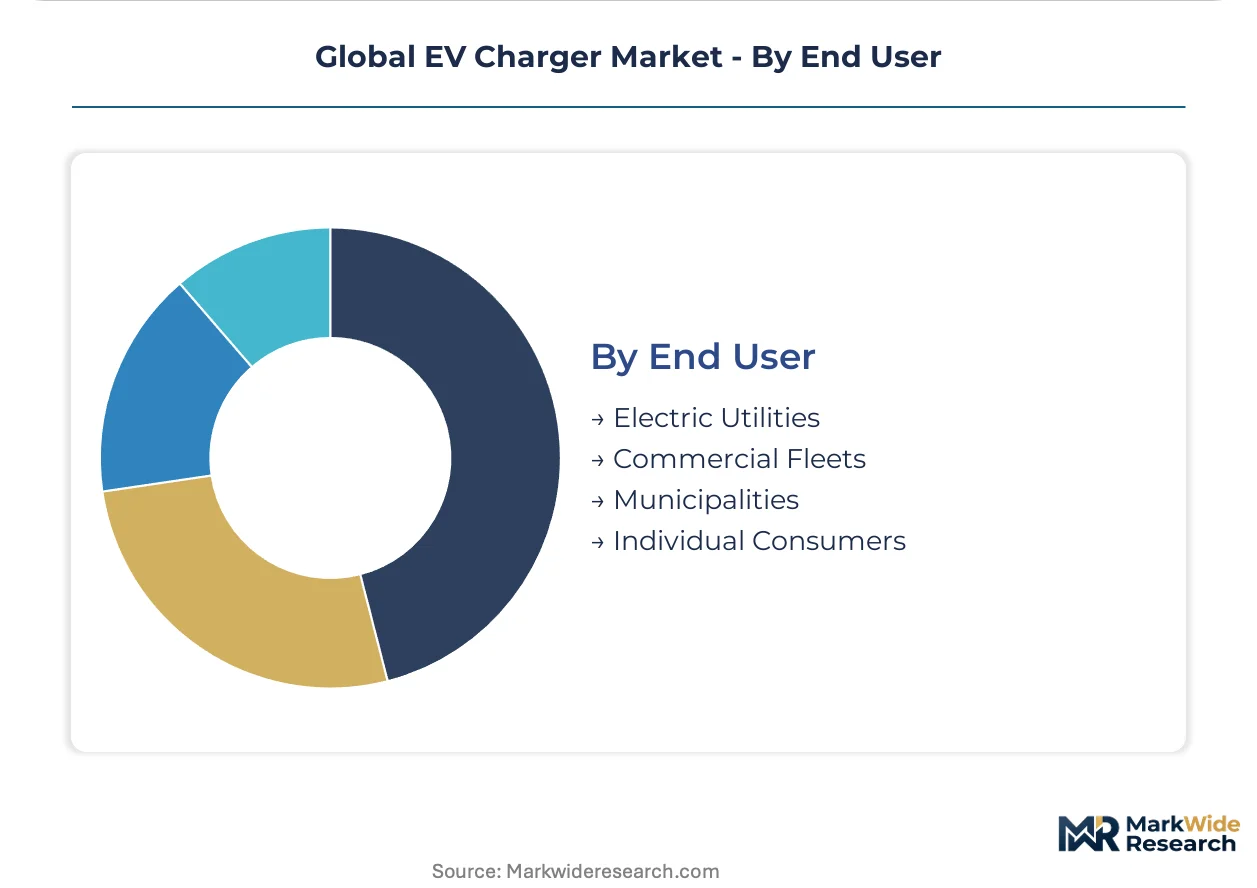
End User:
Margin structure and procurement authority vary substantially across entities with differing balance sheet capacity and regulatory obligations.
- Electric Utilities:Grid operators in France and Germany are directly procuring highway corridor hardware to manage distribution network loading, bundling charger deployment with transformer upgrades and demand response software. These entities negotiate multi-year framework agreements that lock in pricing but require extensive safety certification documentation.
- Commercial Fleets:Logistics operators and ride-hail platforms in Texas and California are consolidating charging procurement under chief sustainability officers with direct C-suite authority, favoring single-vendor relationships with uptime guarantees over lowest-bidder hardware selection.
- Municipalities:City governments face compressed procurement cycles tied to federal infrastructure grant deadlines, with interconnection queue delays often extending project timelines beyond political reporting horizons.
- Individual Consumers:Residential buyers prioritize installation simplicity and smartphone integration, with retail channel pricing transparency limited by electrical contractor markups on turnkey packages.
Commercial Fleets command the largest contract values per deployment. Electric Utilities are scaling fastest where regulatory mandates align grid investment with transport electrification targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's coastal manufacturing corridors deploy chargers at triple the per-capita density of German autobahn networks, yet both markets face parallel grid interconnection bottlenecks that extend commissioning timelines by 12-18 months.
United States
Fleet operators in California and Texas are consolidating depot-based procurement around 350kW DC hardware with 10-year uptime guarantees. The NHTSA coordinates with FAA on commercial vehicle safety standards that shape charger enclosure specifications for logistics hubs. Dallas-Fort Worth and Los Angeles Basin corridors concentrate installation activity where federal infrastructure grants intersect with state zero-emission mandates.
Germany
Highway corridor operators specify 99% availability penalties in tender documents for autobahn fast-charging plazas. The KBA enforces type approval protocols for 1000V DC systems that add 8-14 months to product validation cycles. Bavaria and North Rhine-Westphalia host the densest charging infrastructure networks, with Munich-Stuttgart and Cologne-Frankfurt axes receiving priority transformer upgrades.
China
State Grid partnerships in Guangdong and Jiangsu provinces bundle charger deployment with industrial zone electrification, creating captive demand for integrated battery-to-charger systems. The MIIT mandates GB/T compatibility standards that condition market access for foreign hardware vendors. Pearl River Delta manufacturing clusters dominate domestic production capacity, with Shenzhen and Dongguan anchoring liquid-cooled cable assembly supply chains.
India
The PLI scheme for auto components attracts power electronics and thermal management subsystem investments ahead of passenger EV volume ramp. BIS certification requirements for high-voltage DC equipment create compliance barriers for unvalidated foreign suppliers. Maharashtra and Gujarat industrial corridors concentrate assembly investments where state-level electric mobility policies align with central manufacturing incentives.
Netherlands
Urban fast-charging hub density exceeds European averages due to compressed ICE phase-out timelines and apartment-dwelling demographics lacking residential parking. The EU F-Gas Regulation bans refrigerants with global warming potential above 150 from 2027, forcing coolant circuit redesigns for Dutch-assembled highway chargers. Randstad metropolitan clusters prioritize 350kW corridor hardware to service cross-border freight flows into Germany and Belgium.
Global EV Charger Market Vendor Landscape
Top-tier vendors anchor highway corridor and fleet depot procurement with integrated service contracts, while mid-tier assembly specialists compete on price for standardized AC residential units. The vendor base separates into three functional tiers: power electronics heritage players with silicon carbide MOSFET capabilities, electrical infrastructure conglomerates with installation and maintenance networks, and pure-play software-integrated hardware specialists. Consolidation pressure concentrates on capacity expansion for liquid-cooled cable production and strategic partnerships to secure thermal engineering talent.
Within the power electronics heritage tier, ABB and Delta Electronics occupy positions defined by transformer integration capabilities and semiconductor sourcing relationships. Among integrated automotive-to-charger specialists, BYD exemplifies captive battery supply chain control that underpins cost positioning in Asian fleet tenders. Tesla sits within the proprietary ecosystem vector, navigating open-standard transition risks while sustaining destination charging network dominance in North American markets.
| Leading Market Players |
|---|
| ChargePoint |
| ABB |
| Tesla |
| EVBox |
| Eaton |
| BYD |
| Delta Electronics |
| Wallbox |
| TELD New Energy |
| Others |
Supply Flow & Price Mechanics
Copper futures volatility on the London Metal Exchange cascades through EV charger manufacturing, compressing margins on fixed-price municipal tenders while pushing fleet operators toward performance-based service contracts that transfer raw material risk.
Pricing Analysis
Capacity additions in China's Guangdong and Jiangsu provinces are reshaping price floors for silicon carbide MOSFETs and liquid-cooled cable assemblies. Three-tier pricing structure across premium, standard, and economy levels separates highway corridor operators demanding 99% uptime guarantees from residential AC buyers prioritizing installation simplicity. Cost compression in standard-tier DC hardware is intensifying because state grid partnerships in China bundle charger deployment with industrial zone electrification. Fleet operators in California and Texas show least price sensitivity, accepting 10-year availability premiums, while municipal procurement teams in Europe face strict budget caps that amplify bidding competition.
Supply Chain Analysis
Single-source vulnerability sits with Malaysian and Vietnamese cable assembly plants that feed liquid-cooled connector production for 350kW DC systems. Silicon carbide substrates draw from Japanese and American wafer foundries, while copper conductors and refrigerant-grade aluminum enclosures rest on Chinese smelter output. Tariff exposure on power electronics imports into the European Union threatens margin stability for assembly specialists without bonded warehouse arrangements. Distribution runs through electrical infrastructure conglomerates with installation networks rather than direct OEM-to-fleet relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV charger market compounds steadily as fleet electrification timelines compress procurement cycles for high-amperage DC hardware, embedding recurring service revenue into vendor cash flows.
For Market Incumbents: Lock in thermal engineering talent through acquisition of automotive HVAC specialists, defending against hiring bottlenecks that delay liquid-cooled cable development. Secure captive silicon carbide sourcing relationships before semiconductor substrate allocations tighten, and anchor European highway corridor deployments with integrated transformer capabilities that replicate ABB's positioning.
For New Entrants and Emerging Players: Begin with India's PLI scheme for power electronics subsystems, where domestic manufacturing incentives attract assembly investments ahead of passenger EV volume ramp. Target warehouse automation fleets for wireless inductive pads, exploiting 3-4x hardware premiums in high-cycle environments where connector wear carries downtime costs. Pursue V2G bidirectional certification early to capture utility pilot revenue in Japan and Denmark.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier assembly specialists possessing UL 2594 and IEC 61851-23 pre-certification for 1000V DC systems, given 8-14 month validation cycles that lag product development schedules. Five-to-ten-year viability hinges on backward integration into liquid-cooled cable production. Watch for GB/T standard adoption outside China as the inflection signal for connector standard consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Electronics Transition | German autobahn operators specify SiC-based hardware to minimize transformer footprint at constrained service plazas. |
| Liquid-Cooled Cable Capacity Expansion | Pearl River Delta manufacturing clusters anchor supply chains for 500-ampere assemblies preventing thermal derating. |
| V2G Bidirectional Protocol Certification | IEEE 2030.5 standardization enables fleet operators to monetize battery capacity as grid storage assets. |
| F-Gas Compliant Thermal Management | EU regulation bans high-GWP refrigerants from 2027, forcing coolant circuit redesigns for highway chargers. |
| Performance-Based Service Contract Bundling | California logistics operators displace transactional purchases with 10-year availability agreements transferring operational risk. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining discussions with charger OEM procurement directors, fleet sustainability officers, electrical infrastructure EPC contractors, and utility grid planning engineers with secondary validation. SEC filings from power electronics specialists, IEA electric vehicle outlooks, FERC interconnection queue data, and national regulator type-approval databases anchored demand-side estimates. Bottom-up installation forecasts triangulated against top-down infrastructure investment targets across the analysis window.
Historical reference periods anchored projections across the modeling period, with segmentation by power level tier, installation context, connector standard, and regional regulatory cluster. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, incorporating silicon carbide adoption curves, copper price sensitivity, and grid interconnection timeline assumptions as industry-specific inputs.
Several conditions sit outside the modeled scope, including breakthrough wireless charging efficiency gains, abrupt connector standard mandates by major automotive OEMs, and distribution network upgrade accelerations by national regulators. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Asia-Pacific Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Bi Directional Electric Vehicle Charger Market
Electric Vehicle Charging
Portable EV Charger Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
Airport Electric Vehicle Charging Station Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
HVAC Electronically Commutated Motor (ECM) Market
Electric Vehicle Charging
Bidirectional Charging Units Market
Electric Vehicle Charging
Asia-Pacific Electric Vehicle Charging Cable Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Asia Pacific Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market