
 United States Electric Vehicle Charging Systems and Equipment Market | 2026-2036
United States Electric Vehicle Charging Systems and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States Electric Vehicle Charging Systems and Equipment Market Analytics
Market Context
Multi-source procurement for charging hardware is pivoting toward vertically integrated domestic suppliers. Tesla anchors the high-speed DC segment through its proprietary Supercharger network and NACS licensing strategy. ChargePoint Inc. competes across Level 2 and DC fast product lines with broad channel partnerships. Blink Charging Co. specializes in turnkey deployment models for commercial property owners and municipal clients.
Technical Definition and Segment Structure
United States Electric Vehicle Charging Systems and Equipment encompasses conductive and inductive power transfer infrastructure rated from 1.4 kW residential Level 1 through 350 kW DC fast systems, incorporating power conversion electronics, cable assemblies, and network management software to replenish battery electric vehicle storage. DC Fast Chargers command the steepest capital outlays and tightest supply chains due to high-voltage silicon carbide component requirements. Residential Users represent the volume base, though Commercial Fleets generate superior utilization rates and faster payback periods for network operators.
Regulatory Framework and Outlook
NHTSA and FERC shape interoperability mandates and grid interconnection standards that determine product certification timelines and site approval complexity. The National Electric Vehicle Infrastructure program administered by the Federal Highway Administration dictates connector compatibility and domestic content thresholds for federally funded installations. Stakeholders must monitor state-level public utility commission rulings on demand charge restructuring and time-of-use rate designs that directly alter charger economics.
Market Dynamics
The National Electric Vehicle Infrastructure program is compressing deployment timelines while forcing domestic content compliance, creating a bifurcation between federally funded corridor projects and privately financed urban networks.
Growth Catalysts
- National Electric Vehicle Infrastructure program:Federal funding mandates standardized connector protocols and Buy America sourcing requirements, accelerating procurement cycles for interstate corridor installations.
- Fleet electrification mandates:Logistics operators at California's Inland Empire and Texas logistics hubs are pre-ordering DC fast systems to secure queue positions with constrained domestic manufacturers.
- Silicon carbide power electronics:Wide-bandgap semiconductor adoption is reducing converter losses and enabling 350 kW output from smaller footprints, cutting site preparation costs for constrained urban locations.
Market Restraints
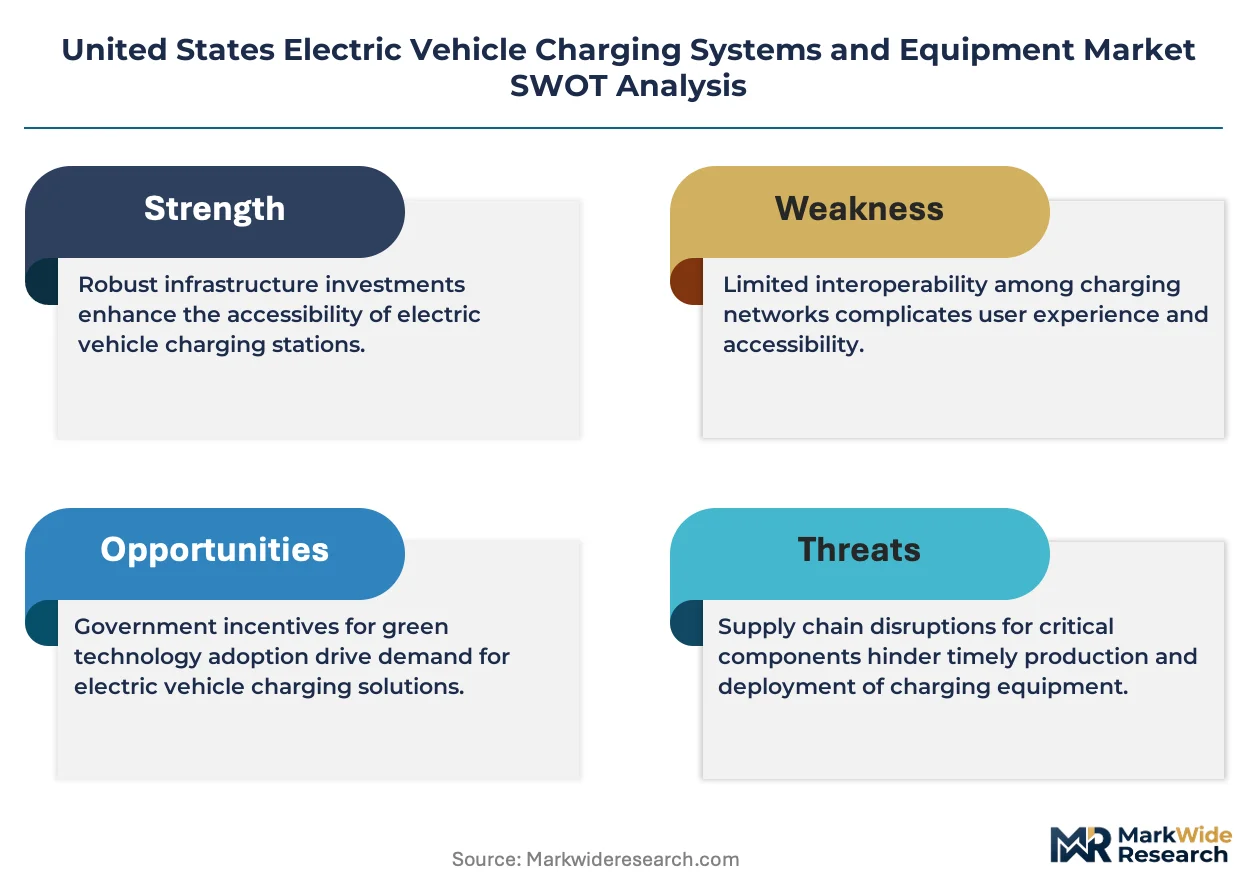
- Transformer and switchgear lead times:Utility-scale electrical equipment from domestic suppliers now stretches 18-24 months, delaying commercial site energization regardless of charger availability.
- High-voltage silicon carbide wafer concentration:Substrate supply chains cluster with limited North American fabrication capacity, constraining DC fast charger production ramps.
- Interconnection queue complexity:FERC jurisdictional overlaps with state public utility commissions create procedural deadlocks for multi-megawatt charging depots requiring distribution system upgrades.
Strategic Opportunities
- Texas Triangle corridor saturation:Interstate nodes connecting Dallas, Houston, and San Antonio remain underdeployed relative to California, offering first-mover positioning for 350 kW hub networks.
- Managed charging software integration:Convergence of vehicle-to-grid protocols with utility demand response programs enables revenue stacking beyond per-kWh margins.
- Multi-family residential retrofit:California's Title 24 building code amendments will mandate EV-ready parking for new construction, opening retrofit demand in existing rental housing stock.
Industry Challenges
- High-voltage electrical technician scarcity:Qualified installers for 480V three-phase DC fast systems remain concentrated in coastal metropolitan areas, extending deployment timelines for interior states.
- NACS certification backlog:Third-party laboratory testing capacity for connector interoperability validation has not scaled with licensing demand, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Electric Vehicle Charging Systems and Equipment Market |
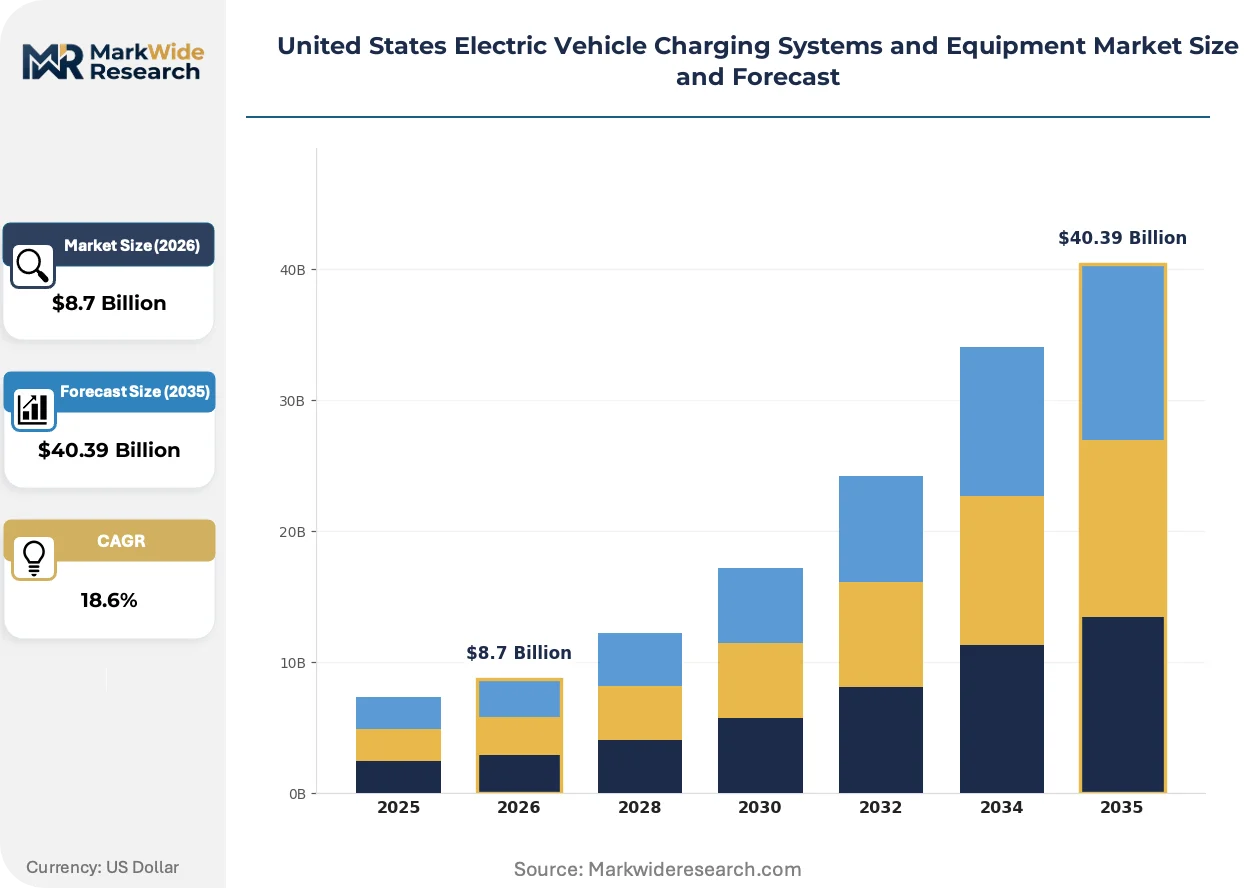
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Chargers, Level 2 Chargers, DC Fast Chargers, Wireless Chargers End User: Residential Users, Commercial Fleets, Public Charging Stations, Automotive OEMs Installation Type: On-Premise, Off-Premise, Integrated Solutions, Standalone Units Connectivity: Wired, Wireless, Smart Charging, Universal Charging |
| Companies Covered | ChargePoint Inc., Blink Charging Co., Tesla Inc., ABB Group, EVBox Group, Leviton Manufacturing Co. Inc., SemaConnect Inc., EVgo, Webasto SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Electric Vehicle Charging Systems and Equipment Market Evolving Landscape
Hardware commoditization is pushing competitive differentiation toward software-defined power management and dynamic load balancing architectures that optimize grid interaction.
Silicon carbide MOSFETs in 350 kW DC fast chargers are electrifying the high-power segment by slashing thermal management requirements and enabling liquid-cooled cable assemblies. Fleet operators at logistics depots are specifying these systems for their reduced footprint and faster vehicle turnaround. The technology is electrifying site economics by cutting electrical infrastructure costs per stall by roughly one-third compared to silicon IGBT predecessors.
The Federal Highway Administration's domestic content thresholds under NEVI are forcing supply chain reconfiguration toward North American transformer and enclosure fabrication. Manufacturers must now certify steel sourcing and final assembly locations to maintain funding eligibility. This regulatory pressure falls heaviest on mid-tier suppliers lacking captive metalworking capacity, pushing consolidation toward vertically integrated domestic producers.
Commercial property owners are unbundling hardware ownership from network management, preferring charging-as-a-service contracts that transfer capital risk to operators. Retail and hospitality landlords in Texas metropolitan corridors are leading this shift, trading upfront equipment costs for revenue-sharing arrangements. This procurement evolution is most visible in Dallas-Fort Worth, where REITs have standardized on third-party operator models for new construction.
United States Electric Vehicle Charging Systems and Equipment Market Segmentation
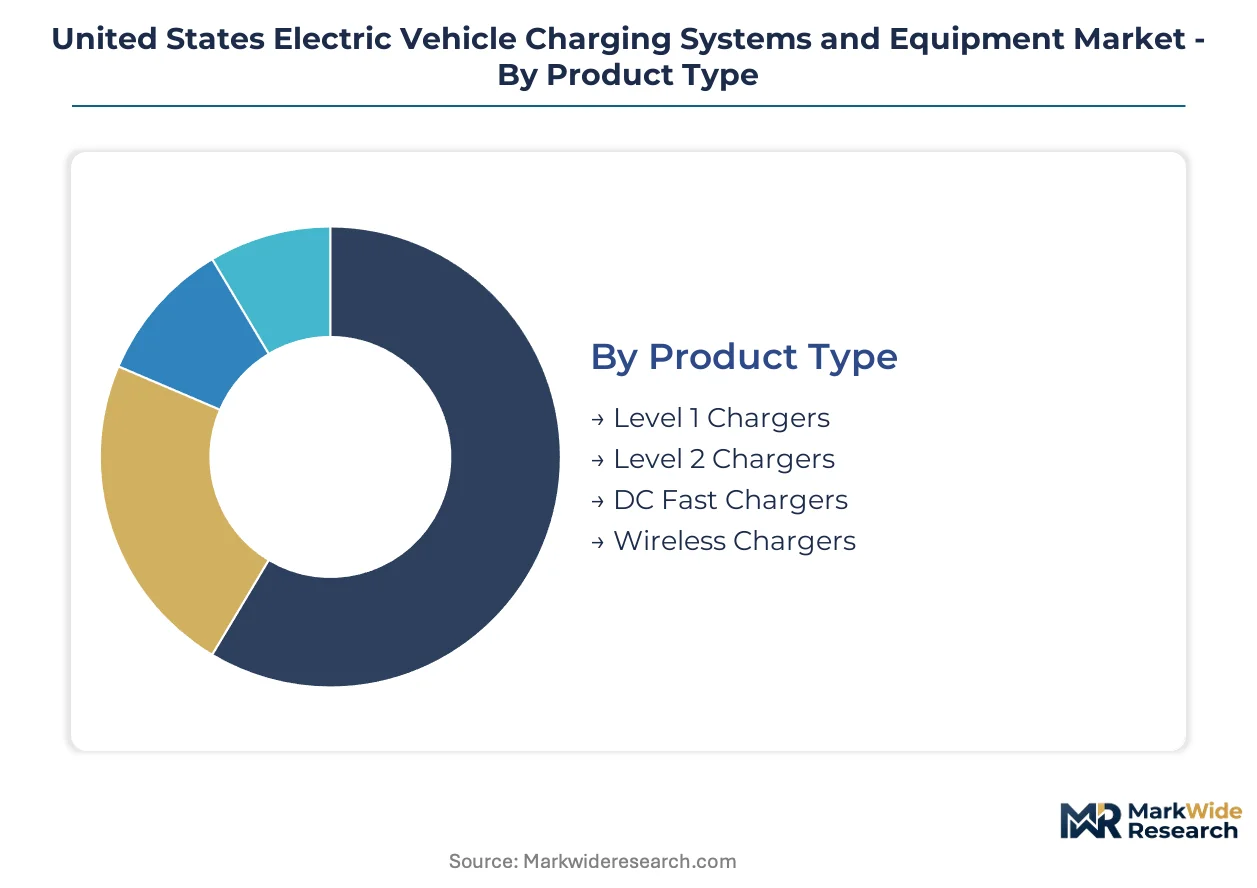
Segmentation in the United States Electric Vehicle Charging Systems and Equipment Market reveals divergent hardware economics across power tiers and installation contexts. Procurement patterns split sharply between federal corridor mandates and private fleet deployments, with each segment demanding distinct certification pathways and supply chain configurations.
Product Type:
Volume concentrates in lower-power residential systems, while premium economics favor high-output DC infrastructure with advanced semiconductor architectures.
- Level 1 Chargers:These 1.4 kW residential units plug into standard 120V outlets without requiring electrical upgrades. Demand clusters in older housing stock across Midwest states where panel capacity constraints block Level 2 retrofits. NHTSA safety certification remains the primary regulatory gateway.
- Level 2 Chargers:Operating at 240V and 3.3-19.2 kW output, these systems dominate multi-family construction compliance under California's Title 24 amendments. Texas metropolitan developers are pre-wiring parking structures to capture this mandated demand stream.
- DC Fast Chargers:High-voltage silicon carbide converters enable 50-350 kW output for commercial fleet turnaround. NEVI funding eligibility requires Buy America compliance, compressing supplier margins.
- Wireless Chargers:Inductive power transfer systems remain pre-commercial with SAE J2954 certification pending widespread adoption.
Today's leader: Level 2 Chargers. Tomorrow's challenger: DC Fast Chargers.
End User:
Customer type determines utilization intensity, with commercial operators extracting 3-5x more throughput per installed kilowatt than residential counterparts.
- Residential Users:Single-family homeowners purchase Level 1 and Level 2 hardware through retail channels and electrical contractor referrals. California and Texas account for disproportionate volume due to vehicle registration concentration and utility rebate programs.
- Commercial Fleets:Logistics operators at California's Inland Empire and Texas Triangle hubs are pre-ordering DC fast systems to secure manufacturing queue positions. FERC interconnection timelines represent the binding constraint on depot energization.
- Public Charging Stations:Retail landlords and municipal authorities deploy mixed-power networks with revenue-sharing operator contracts. Dallas-Fort Worth REITs have standardized on third-party ownership models.
- Automotive OEMs:Vehicle manufacturers bundle charging hardware with new sales or operate captive networks for brand differentiation.
Commercial Fleets deliver the steepest expansion trajectory as electrification mandates harden. Residential Users provide the volume foundation.
Installation Type:
Capital structure preferences are shifting from ownership toward service contracts, reshaping procurement relationships between property stakeholders and network operators.
- On-Premise:Hardware installed at fleet depots, workplaces, and residential garages where the property owner controls site access. Texas logistics hubs favor this model for security and utilization control.
- Off-Premise:Public corridor and retail location deployments where third-party operators manage customer acquisition and payment processing.
- Integrated Solutions:Turnkey packages combining hardware, software, and maintenance contracts. Municipal clients in California prefer this procurement structure to transfer operational risk.
- Standalone Units:Single-charger installations without networked management, declining as smart charging capabilities become standard.
Integrated Solutions are gaining share fastest among risk-averse institutional buyers. Standalone Units face obsolescence pressure.
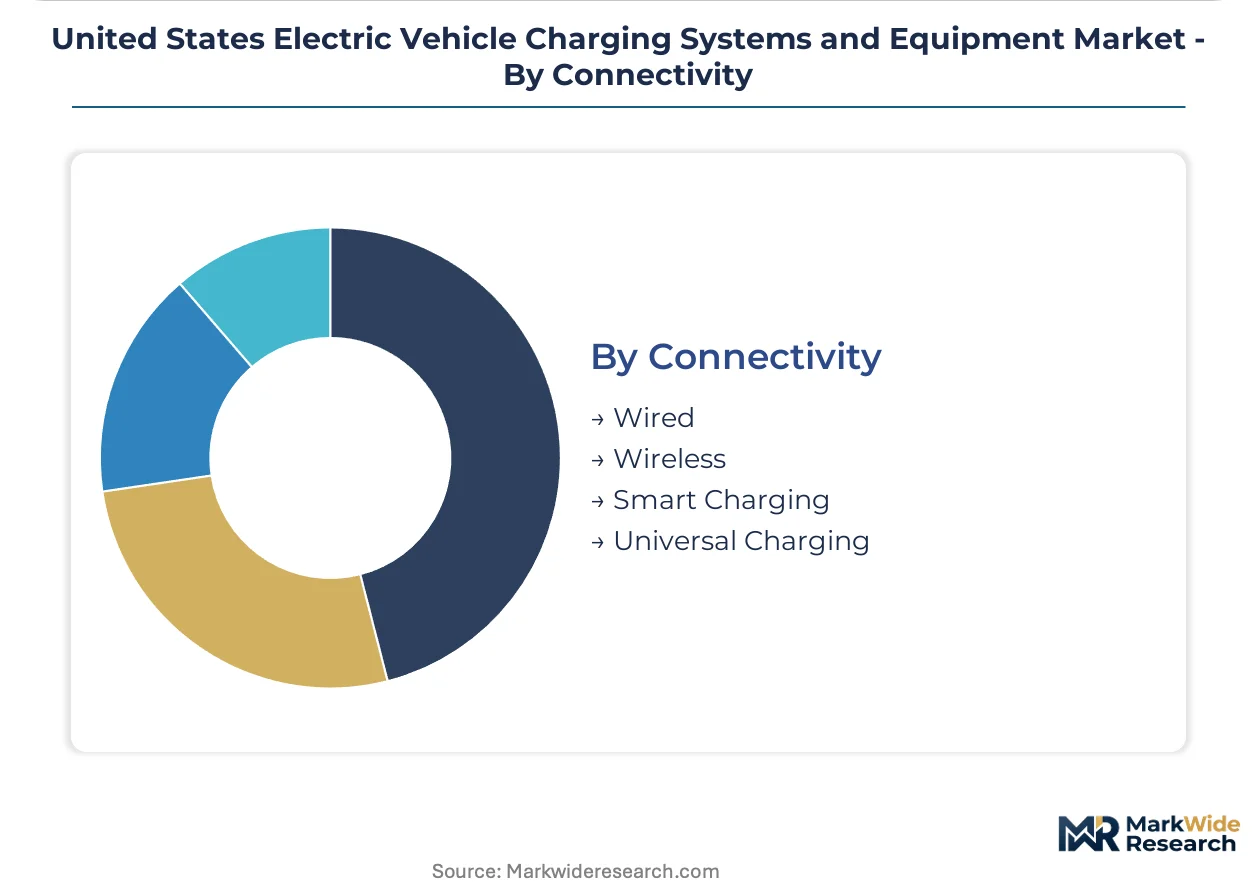
Connectivity:
Network intelligence is becoming a baseline requirement rather than a premium feature, with interoperability mandates accelerating standardization.
- Wired:Physical Ethernet or powerline communication links for reliable data transmission in high-interference environments. Industrial fleet depots specify wired backhaul for cybersecurity compliance.
- Wireless:Cellular and Wi-Fi connectivity enabling remote diagnostics and dynamic pricing updates. NEVI-funded corridor installations require this capability for federal reporting.
- Smart Charging:Load-balancing algorithms that modulate output based on grid conditions and utility rate signals. FERC demand response programs in Texas and California create revenue stacking opportunities.
- Universal Charging:Multi-protocol compatibility supporting both CCS and NACS connectors without adapter requirements.
Smart Charging represents the current procurement priority. Universal Charging is emerging as the interoperability baseline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's metropolitan corridors concentrate the highest charger deployment density, with federal NEVI funding and state building codes accelerating installation timelines across the United States.
California
Fleet electrification mandates and Title 24 building code amendments drive procurement of Level 2 and DC fast systems. The California Energy Commission administers rebate programs for multi-family residential retrofits. The Inland Empire logistics hub hosts pre-ordered DC fast deployments for commercial operators securing manufacturing queue positions.
Texas
Interstate corridor nodes connecting Dallas, Houston, and San Antonio attract NEVI-funded 350 kW hub networks. The Public Utility Commission of Texas structures demand response programs enabling revenue stacking for smart charging operators. Dallas-Fort Worth REITs standardize on third-party charging-as-a-service contracts for new retail construction.
New York Metro
Multi-family housing stock and municipal fleet electrification create dual demand streams for Level 2 infrastructure. The New York State Public Service Commission oversees interconnection standards for grid-tied depot charging. Brooklyn and Queens warehouse districts see early commercial fleet pre-positioning ahead of congestion pricing implementation.
Pacific Northwest
Utility-led transportation electrification programs in Oregon and Washington subsidize residential and workplace installations. State public utility commissions mandate transportation electrification plans with binding deployment targets. Seattle and Portland metropolitan areas cluster pilot programs for managed charging integration with hydroelectric grid resources.
Southeast
Automotive manufacturing corridors in Georgia and South Carolina attract DC fast infrastructure to support OEM assembly plant electrification. State economic development authorities coordinate with FHWA on NEVI corridor planning along I-95 and I-85. Atlanta logistics hubs emerge as secondary fleet electrification nodes outside California and Texas concentrations.
United States Electric Vehicle Charging Systems and Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-defined power management and charging-as-a-service models. The market structure bifurcates between vertically integrated domestic suppliers capturing NEVI-funded corridor projects and specialized operators serving commercial property owners. Three archetypes dominate: captive network operators with proprietary connector standards, turnkey deployment specialists, and hardware-agnostic software platforms. Competitive moves center on domestic content certification for federal funding eligibility and strategic partnerships with REITs and fleet operators.
Among domestic network operators, ChargePoint Inc., Blink Charging Co., and Tesla Inc. exemplify distinct strategic positions. ChargePoint Inc. anchors the broad-channel partnership archetype across Level 2 and DC fast product lines. Blink Charging Co. occupies the turnkey deployment specialist tier for commercial property and municipal clients. Tesla Inc. represents the captive network model through proprietary Supercharger infrastructure and connector licensing strategy.
| Leading Market Players |
|---|
| ChargePoint Inc. |
| Blink Charging Co. |
| Tesla Inc. |
| ABB Group |
| EVBox Group |
| Leviton Manufacturing Co. Inc. |
| SemaConnect Inc. |
| EVgo |
| Webasto SE |
| Others |
Value Network & Pricing Analysis
Federal Buy America sourcing thresholds under NEVI gate both qualified domestic supply and premium-tier pricing access for federally funded corridor deployments. Manufacturers lacking captive North American metalworking capacity face margin compression or exclusion from the largest procurement stream.
Pricing Analysis
Input-cost pass-through from silicon carbide wafer scarcity and transformer lead-time extension is intensifying price pressure on DC fast charger tiers. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide-enabled 350 kW systems from silicon IGBT predecessors and entry-level fleet hardware. Price differentiation centers on NACS certification status and domestic content compliance grade. Fleet operators show lowest price sensitivity due to mandate-driven procurement timelines, while municipal clients under fixed capital budgets gravitate toward economy-tier integrated solutions.
Supply Chain Analysis
NEVI certification and UL 2594 qualification requirements gate supplier participation, compressing the qualified vendor base toward vertically integrated domestic producers. High-voltage silicon carbide substrates draw from Japan, Germany, and limited US fabrication capacity. Power conversion electronics, cable assemblies, and network management software rest on semiconductor supply chains concentrated in East Asia. Single-source vulnerability in wide-bandgap substrate supply creates bottleneck risk for 350 kW production ramps. Distribution runs through direct OEM sales for fleet depots and electrical contractor channels for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Electric Vehicle Charging Systems and Equipment Market functions as a stable compounder anchored by federal infrastructure mandates that lock in decade-long deployment visibility regardless of near-term vehicle sales volatility.
For Market Incumbents: Extend domestic content certification coverage to capture NEVI-funded corridor awards before qualification windows narrow. Secure captive transformer and enclosure fabrication capacity to defend margin position against supply-chain margin squeeze. Deepen software-defined power management R&D to differentiate as hardware commoditization accelerates.
For New Entrants and Emerging Players: Electrical contractor networks represent the most accessible channel for penetrating the fragmented multi-family residential retrofit segment. Target California Title 24 compliance-driven demand in existing rental housing stock outside coastal metropolitan cores. Pursue charging-as-a-service operator partnerships with Texas REITs seeking to transfer capital risk for new retail construction.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier hardware suppliers lacking NEVI qualification but holding captive metalworking capacity suitable for rapid certification. Long-term viability favors vertically integrated domestic producers with software platforms capable of revenue stacking through FERC demand response programs. Watch NACS certification backlog resolution as the signal for product launch velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Certification | NEVI funding eligibility requires certified steel sourcing and final assembly location verification. |
| Silicon Carbide Supply Agreement | Long-term substrate contracts with Japanese or German wafer producers secure 350 kW production capacity. |
| Managed Charging Software Platform | FERC demand response program integration enables revenue stacking beyond per-kWh transaction margins. |
| Electrical Contractor Channel Partnership | Multi-family residential retrofits in California and Texas flow through qualified installer networks. |
| Charging-as-a-Service Operator Model | Texas REITs standardize on third-party ownership contracts transferring capital risk from property owners. |
Research Methodology
Coverage spans California, Texas, New York Metro, Pacific Northwest, and Southeast states, with primary inputs from each regional cluster. The analysis combines structured interviews with fleet electrification managers, electrical contractor owners, public utility commission staff, REIT asset managers, and charging network operations executives. Secondary validation draws from FHWA NEVI program filings, FERC interconnection queue data, state public utility commission rulings, and utility transportation electrification plan submissions. Bottom-up installation forecasts triangulate against top-down federal funding allocation trajectories.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. Segmentation dimensions include charger power tier, end-user archetype, installation context, and connectivity protocol. CAGR derivation incorporates fleet electrification mandate timelines, building code amendment schedules, and utility rate restructuring proceedings. Industry-specific inputs include silicon carbide adoption curves and NACS certification throughput estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to transformer manufacturing capacity expansion and wide-bandgap semiconductor supply diversification. Forecasts reflect assumptions regarding NEVI funding continuity and state-level zero-emission vehicle mandate durability. Deviation in FERC interconnection reform timing or NHTSA connector standard rulings would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Oman EV Charging Station Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market
Electric Vehicle Charging
Japan Electric Vehicles (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Wireless Electric Vehicle Charger Market
Electric Vehicle Charging
Belgium Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Battery Rental and Swapping Market
Electric Vehicle Charging
Metals in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Electric Vehicle Home Charger Market
Electric Vehicle Charging
EV Charging Cables Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market