
 EV Smart Charge Controller Market | 2026-2036
EV Smart Charge Controller Market Size, Share, and Industry Trends Forecast 2026-2036
EV Smart Charge Controller Market Insights
Fleet management is hardening as the dominant demand vertical for EV smart charge controllers, displacing earlier residential-centric deployment patterns. Siemens leverages its grid automation heritage to anchor utility-scale charging integration projects across European markets. Schneider Electric sustains competitive positioning through deep specialization in building-energy management convergence with EV infrastructure. ABB competes aggressively in high-power DC fast-charging controller segments where thermal management and power conversion density determine performance benchmarks.
An EV smart charge controller is an embedded power electronics system that manages bidirectional energy flow between electric vehicles and grid infrastructure, typically operating at voltage ranges from 120V AC residential levels to 1000V DC commercial configurations while executing real-time communication protocols for load balancing and demand response. Its primary commercial purpose is to optimize charging economics, extend battery longevity, and enable grid services revenue through intelligent power scheduling algorithms. AC charger controllers occupy the mature volume tier where cost compression and installer familiarity sustain margin pressure, while bidirectional charger controllers represent the fastest-expanding segment as vehicle-to-home and vehicle-to-grid applications gain regulatory traction across multiple jurisdictions. Wi-Fi-enabled controllers lead residential installations due to consumer device ecosystem familiarity, though PLC technology dominates public charging deployments where mesh network reliability and cybersecurity hardening requirements override consumer convenience preferences.
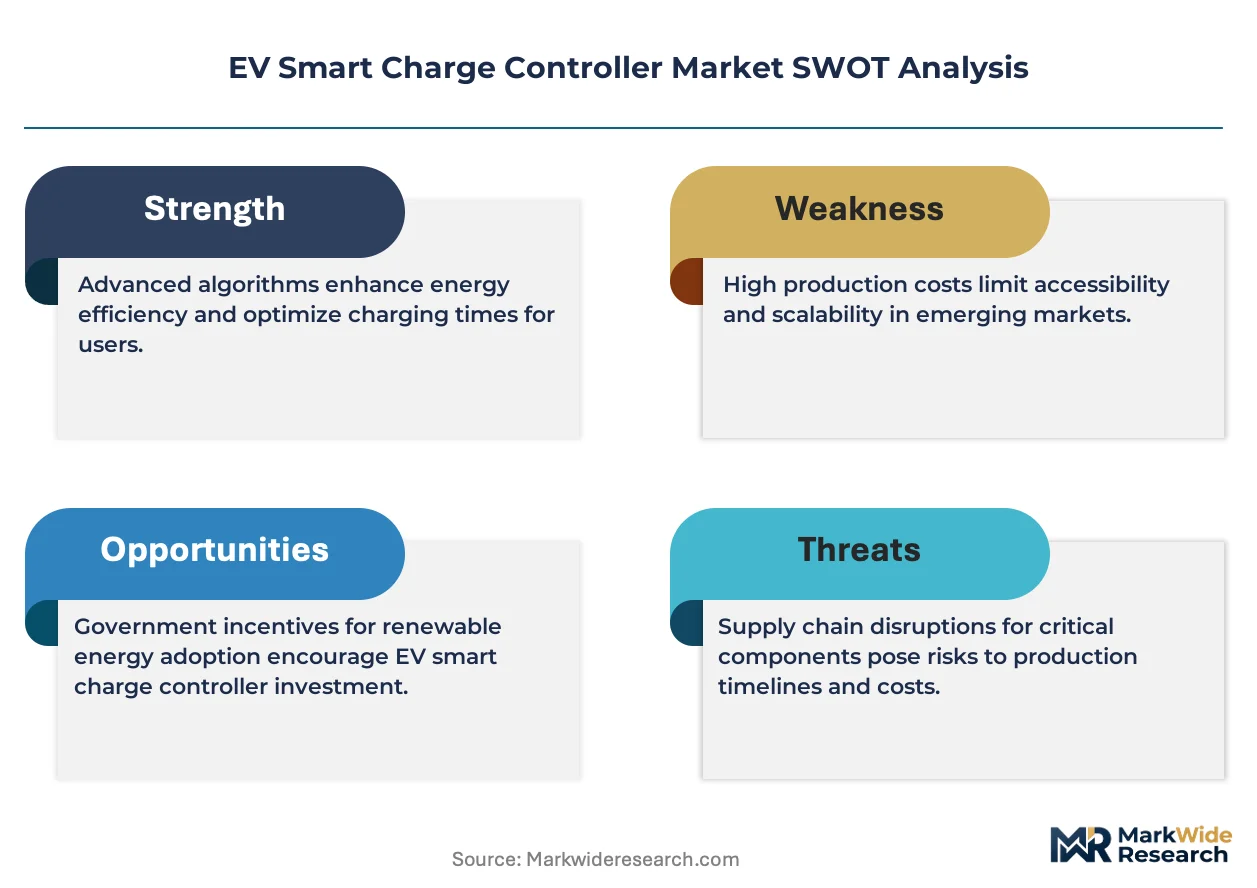
The US Department of Energy's FERC Order 2222 enables aggregated distributed energy resources including EV chargers to participate in wholesale markets, directly expanding revenue model viability for smart controller vendors. California's Title 24 and the EU's Energy Performance of Buildings Directive collectively mandate EV-ready electrical capacity in new construction, embedding controller demand into building code compliance cycles rather than discretionary consumer purchases. China's GB/T standards and dual carbon policy framework accelerate domestic controller specification requirements through state-owned utility procurement mandates. Stakeholders must monitor interoperability protocol fragmentation between ISO 15118, CHAdeMO, and regional Chinese standards as this technical divergence threatens to partition addressable market segments and strand controller development investments.
Market Dynamics
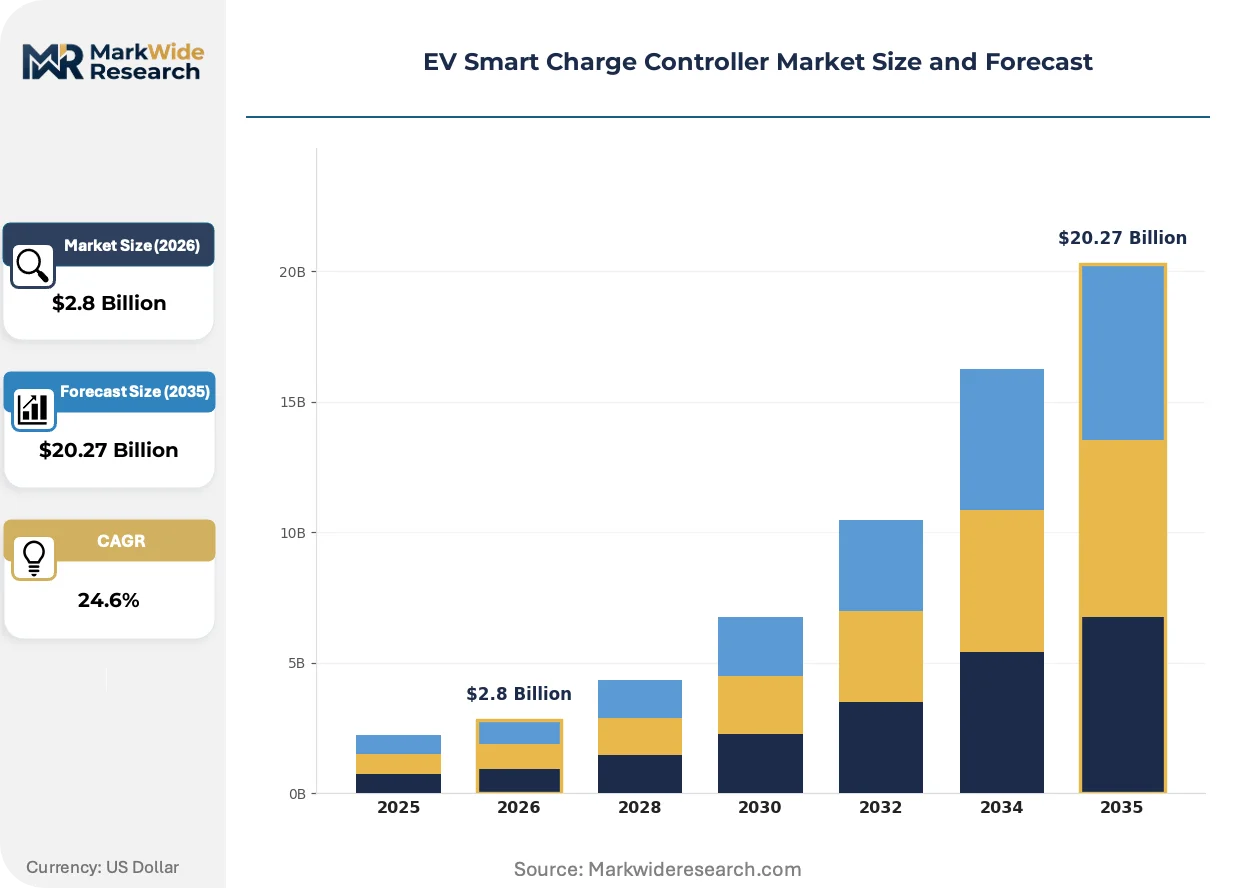
Fleet electrification mandates and building code integration are compressing controller deployment timelines from discretionary consumer purchases to compliance-driven infrastructure embedding. Bidirectional power electronics capabilities now determine competitive tiering as vehicle-to-grid revenue models gain regulatory validation.
Growth Catalysts
- California's Title 24 mandate:New construction EV-ready requirements lock controller demand into building permit cycles, eliminating consumer adoption friction for residential and commercial installations.
- FERC Order 2222 aggregation rules:Distributed energy resource participation in wholesale markets creates recurring revenue streams for controller-enabled grid services beyond hardware sales.
- China's eastern manufacturing corridor:State-backed charging network expansion and domestic EV production concentration generate synchronized procurement demand for high-volume controller specifications.
Market Restraints
- Silicon carbide semiconductor supply concentration:Power electronics substrate availability bottlenecks constrain controller manufacturing scale-up for 800V+ architectures.
- Protocol fragmentation:ISO 15118, CHAdeMO, and GB/T technical divergence forces redundant controller SKUs and stranded development investment across regional markets.
- Utility interconnection delays:Distribution system upgrade backlogs extend bidirectional charger commissioning timelines and compress project IRRs for fleet operators.
Strategic Opportunities
- India's PLI scheme for auto component manufacturing:Localized controller production incentives align with emerging EV assembly capacity in Tamil Nadu and Gujarat industrial corridors.
- Vehicle-to-home emergency power:Residential backup applications create premium controller tiers beyond standard charging functions in disaster-prone US and Japanese markets.
- Building-energy management convergence:Schneider Electric's integration playbook demonstrates HVAC-EV load orchestration as a new specification battleground for commercial controllers.
Industry Challenges
- Cybersecurity certification complexity:IEC 62443 and NIST framework compliance timelines extend product release cycles for PLC-enabled public charging controllers.
- Power electronics thermal engineering talent scarcity:High-frequency magnetics and wide-bandgap semiconductor design skills concentrate at specialized engineering firms and academic programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Smart Charge Controller Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $20.27 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Chargers, Bidirectional Chargers, Portable Chargers Technology: Wi-Fi, Zigbee, Ethernet, PLC Application: Residential, Commercial, Fleet Management, Public Charging End User: Individuals, Businesses, Government, Utilities |
| Companies Covered | Phoenix Contact, Schneider Electric, Siemens, ABB, Flex Charge, Bender, Vector, innolectric, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Smart Charge Controller Market Trends and Innovations
Silicon carbide power semiconductors and embedded AI load forecasting are redefining controller performance benchmarks. Regulatory mandates are accelerating bidirectional capability as a standard feature rather than premium option.
Silicon carbide MOSFETs replace silicon IGBTs in high-power DC fast-charging controllers, enabling higher switching frequencies and reduced thermal management overhead. Fleet operators in Germany and California specify SiC-based architectures for 350kW+ charging hubs where power density determines site footprint economics. Wide-bandgap semiconductor adoption is overtaking legacy silicon in premium controller tiers and compressing cost parity timelines for mid-market segments.
The EU's Energy Performance of Buildings Directive mandates EV-ready electrical capacity in all new residential and non-residential construction by 2025. This regulatory embedding shifts controller procurement from aftermarket installation to original equipment specification by electrical contractors and building developers. European controller vendors are restructuring sales organizations around construction channel partnerships rather than consumer direct distribution.
Fleet procurement teams now specify outcome-based charging availability contracts rather than capital equipment purchases, transferring controller performance risk to vendors or charge point operators. This model disrupts traditional hardware sales cycles in North American logistics and last-mile delivery verticals. California's drayage truck electrification mandates are accelerating this shift as port operators prioritize uptime guarantees over asset ownership.
EV Smart Charge Controller Market Segmentation
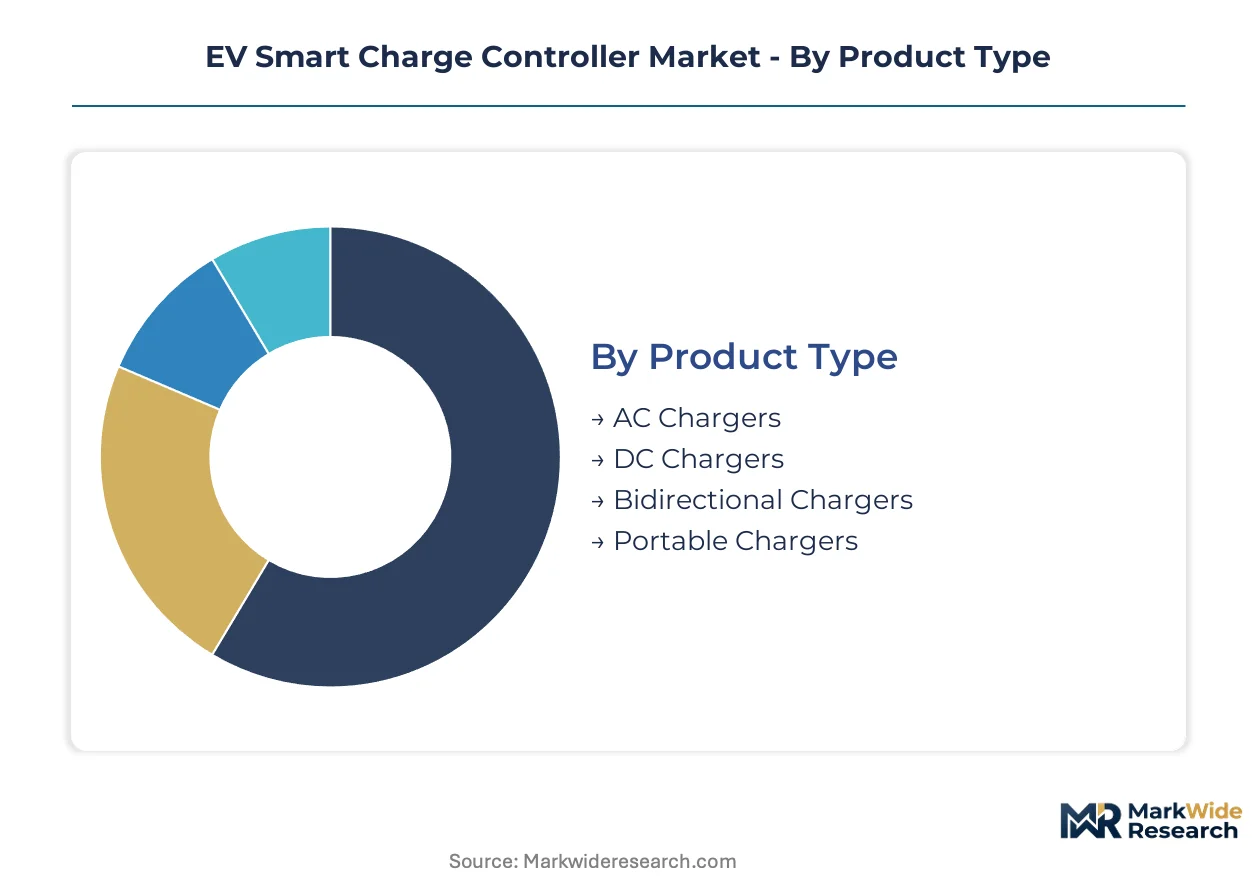
Controller segmentation reveals divergent capital requirements and margin structures across power electronics architectures. Procurement patterns cluster around voltage specifications, communication protocols, and grid-interconnection complexity rather than surface-level application labels.
Product Type:
Capital intensity escalates with power conversion density and bidirectional switching capability, separating commodity AC hardware from premium DC and V2G-enabled systems.
- AC Chargers:Silicon IGBT-based power stages handle single-phase 120V to three-phase 480V conversion with passive cooling architectures. Residential retrofits and workplace Level 2 installations in Germany and California concentrate volume demand where installer familiarity and code compliance drive specification decisions.
- DC Chargers:Active rectification and DC-DC conversion stages operate at 200V to 1000V with forced liquid cooling requirements. Fleet depots along China's eastern manufacturing corridor and US interstate highway corridors absorb high-power hardware where site power upgrades and transformer capacity determine deployment feasibility.
- Bidirectional Chargers:Dual-active-bridge topologies enable grid-synchronized power export with IEC 61851 compliance overhead. Vehicle-to-home backup applications in disaster-prone Japanese prefectures and FERC Order 2222-enabled wholesale markets in Texas and California create premium tier demand.
- Portable Chargers:Integrated cable and control electronics prioritize weight reduction and plug compatibility over thermal performance. Emergency roadside assistance providers and apartment dwellers without dedicated parking represent the addressable base.
AC hardware absorbs the bulk of installed capacity; bidirectional systems are expanding most quickly as regulatory frameworks validate grid services revenue.
Technology:
Communication protocol selection trades consumer convenience against cybersecurity hardening and mesh reliability in high-density deployments.
- Wi-Fi:IP-based stacks leverage residential router infrastructure with TLS encryption for over-the-air firmware updates. Single-family home installations in North American suburbs dominate demand where smartphone app integration drives purchasing decisions.
- PLC:Power-line carrier modulation traverses existing electrical infrastructure without additional cabling. Public charging networks across EU member states and China's state-backed highway corridors specify PLC for cybersecurity isolation and deterministic latency.
- Zigbee:Mesh networking at 2.4GHz supports demand response aggregation with sub-100mW standby power. Utility-managed residential programs in South Korea and select US municipal markets pilot load curtailment schemes.
- Ethernet:Hardwired CAT5/6 connectivity eliminates wireless attack surfaces for critical infrastructure sites. Data center campus charging and airport ground support equipment installations require physical segmentation.
Wi-Fi commands residential volume; PLC is climbing the fastest in commercial and public infrastructure procurement.
Application:
Site electrical capacity and utilization patterns determine controller specification more than nominal power ratings alone.
- Fleet Management:Centralized depots with 20+ vehicle capacity require load orchestration algorithms and transformer upgrade coordination. Last-mile logistics operators in California's San Pedro Bay port complex and German Rhine-Ruhr industrial belt prioritize uptime guarantees over capital expenditure.
- Residential:Single-point installations at 7kW to 19kW face panel capacity constraints and permit timeline variability. New construction in jurisdictions with Title 24 or EPBD mandates embeds controller specification into electrical contractor procurement.
- Commercial:Workplace and retail destinations balance employee dwell time against customer turnover rates. Mixed-use developments in Singapore and Dubai integrate charging with building energy management systems.
- Public Charging:High-turnover sites demand 150kW+ capability with payment processing and dynamic pricing integration. Highway corridor networks in China's eastern provinces and US Interstate 5 corridor compete on availability metrics.
Fleet management captures the steepest expansion trajectory; residential remains the volume anchor due to building code embedding.
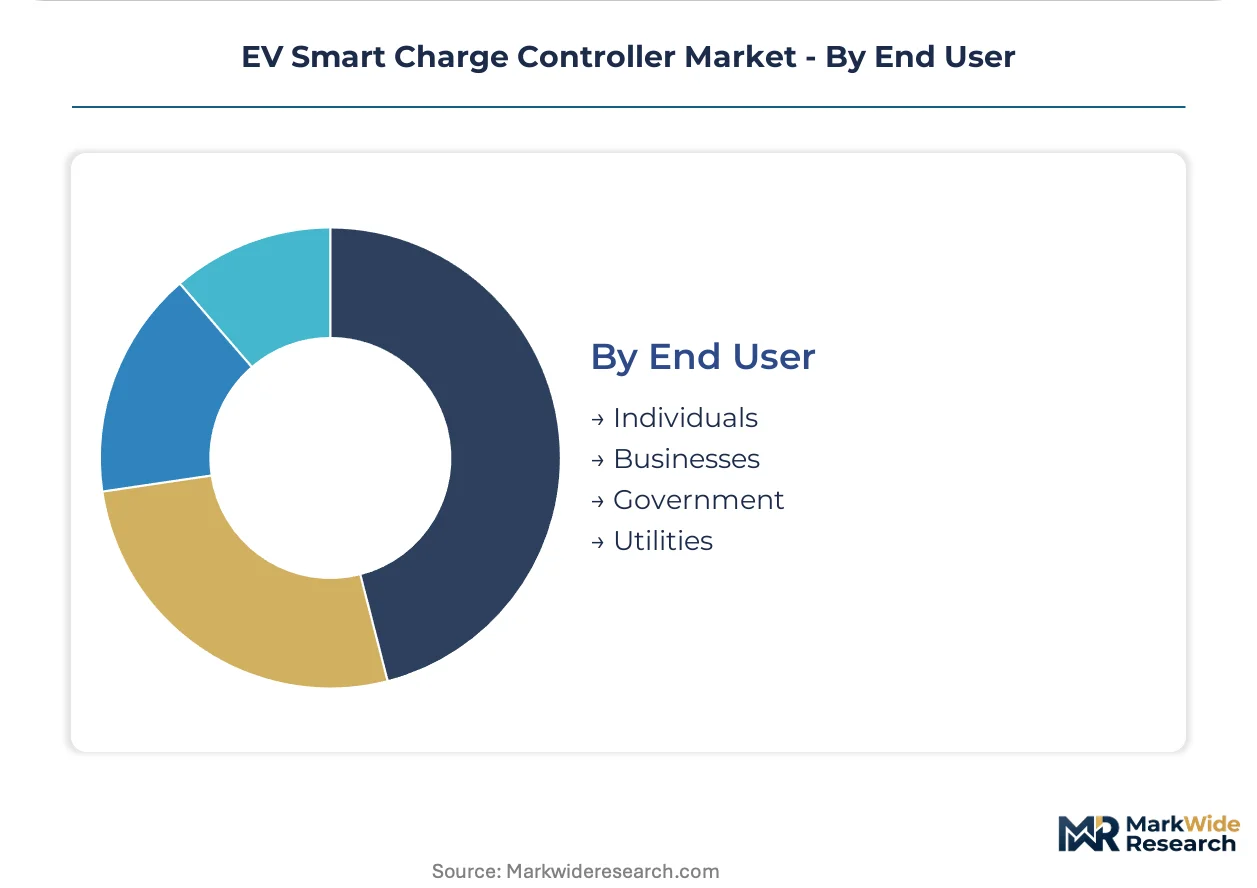
End User:
Purchasing authority and financing structures segment the market across consumer discretion, enterprise procurement, and regulated utility mandates.
- Utilities:State-owned grid operators in China and investor-owned utilities in California deploy controllers as distributed energy resource aggregation nodes. Procurement emphasizes interoperability certification and decade-scale service life.
- Businesses:Corporate sustainability targets and fleet electrification mandates drive capital allocation. Logistics operators and ride-hail platforms specify outcome-based availability contracts rather than hardware ownership.
- Government:Municipal transit authorities and federal facility managers face procurement regulations favoring domestic content and Buy America compliance. School bus electrification programs across US states create concentrated demand spikes.
- Individuals:Discretionary purchases respond to vehicle acquisition timing and homeownership status. Tax credit eligibility and electricity rate structures influence technology tier selection.
Utility procurement anchors long-term volume commitments; business segment demand is gaining share fastest as fleet mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates controller manufacturing capacity while the United States and Germany anchor deployment demand through fleet electrification mandates and building code integration. Production clusters align with domestic EV assembly volumes and state-backed charging procurement programs.
United States
California's Title 24 mandate embeds controller specification into new construction permit cycles, eliminating consumer adoption friction for residential installations. FERC Order 2222 enables aggregated EV charger participation in wholesale electricity markets, expanding revenue model viability for smart controller vendors. The San Pedro Bay port complex drives concentrated fleet depot demand as drayage truck electrification deadlines tighten.
Germany
The EU Energy Performance of Buildings Directive mandates EV-ready electrical capacity in all new construction by 2025, shifting procurement from aftermarket to electrical contractor specification. The Rhine-Ruhr industrial belt concentrates fleet management deployments where logistics operators prioritize charging availability guarantees. Grid automation integration projects leverage existing utility infrastructure partnerships.
China
GB/T standards and dual carbon policy frameworks accelerate domestic controller specification through state-owned utility procurement mandates. The eastern manufacturing corridor synchronizes charging network expansion with domestic EV production volumes. State-backed highway corridor networks compete on availability metrics and high-power hardware deployment.
Japan
Vehicle-to-home backup applications create premium controller demand in disaster-prone prefectures where grid resilience commands regulatory priority. METI programs incentivize bidirectional charging infrastructure as standard residential equipment. The Kanto region concentrates early deployment clusters around Tokyo metropolitan resilience planning.
India
The PLI scheme for auto component manufacturing incentivizes localized controller production aligned with emerging EV assembly capacity. Tamil Nadu and Gujarat industrial corridors attract component manufacturing investments through production-linked incentives. State electricity regulators draft distributed energy resource frameworks that anticipate EV load aggregation participation.
EV Smart Charge Controller Market Competitive Landscape
Top-tier vendors anchor utility-scale and fleet integration projects, while mid-tier specialists concentrate on building-energy convergence and thermal engineering differentiation. The competitive structure stratifies across power electronics heritage, software integration depth, and construction channel access. Strategic archetypes include grid automation incumbents leveraging utility relationships, building-energy specialists pursuing HVAC-EV orchestration, and power semiconductor firms capturing wide-bandgap transition premiums. Dominant competitive moves encompass construction channel partnership restructuring and bidirectional capability standardization across product portfolios.
Among European industrial incumbents, Phoenix Contact, Schneider Electric, and Siemens occupy positions defined by electrical infrastructure heritage and construction specification influence. These firms exemplify archetypes spanning component-level connectivity, building-energy management convergence, and grid automation integration respectively. Their competitive positioning reflects decades of electrical contractor relationships and standards body participation rather than hardware specification alone.
| Leading Market Players |
|---|
| Phoenix Contact |
| Schneider Electric |
| Siemens |
| ABB |
| Flex Charge |
| Bender |
| Vector |
| innolectric |
| Delta Electronics |
| Others |
Pricing and Supply Chain Analysis
Bidirectional capability certification tiers bifurcate controller economics between commodity AC hardware and premium V2G-enabled systems, compressing margins at the standard tier while concentrating supply chain leverage with silicon carbide substrate vendors serving 800V+ architectures. California's Title 24 compliance deadlines and China's state procurement mandates synchronize demand timing, amplifying price volatility during quarterly utility purchasing windows.
Pricing Analysis
Lead-time-driven pricing premiums apply to SiC-based DC fast-charging controllers with sub-12-week delivery commitments, while spot inventory of silicon IGBT-based AC units trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade (UL vs CE vs GB/T) and thermal management complexity. Cost compression in residential AC controllers is intensifying because installer familiarity sustains commodity competition. Fleet operators exhibit lowest price sensitivity due to uptime guarantee requirements, while individual homeowners drive aggressive quote comparison.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from China's state-backed charging networks, while electrical contractor distribution serves California and Germany's construction-embedded procurement. Manufacturing concentrates in China, Germany, and Taiwan, with silicon carbide wafers drawing from Wolfspeed's US facilities and Showa Denko's Japanese substrates. Controller assembly rests on magnetics from TDK-EPCOS, gate drivers from Infineon, and thermal interface materials from Henkel. Single-source vulnerability in 6-inch SiC substrate supply threatens 350kW+ controller output. Distribution runs through utility procurement consortia and construction channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream captive supply of wide-bandgap semiconductors and downstream construction channel control determine margin capture. Players pursuing backward integration into SiC substrate supply or electrical contractor specification influence will dominate tier-1 positioning.
For Market Incumbents: Lock in construction channel partnerships before California's Title 24 and the EU Energy Performance of Buildings Directive fully embed controller specification into electrical contractor procurement cycles. Defensive moves require captive supply agreements with silicon carbide substrate vendors and ISO 15118-20 certification investment to neutralize protocol fragmentation threats. Siemens and Schneider Electric's existing utility relationships provide template defense against emerging building-energy convergence specialists. For New Entrants and Emerging Players: Launch via outcome-based charging availability contracts targeting California drayage fleet operators and German Rhine-Ruhr logistics depots where uptime guarantees override hardware ownership preferences. White-space targets include India's Tamil Nadu industrial corridor under PLI scheme incentives and Japanese V2H residential backup applications in disaster-prone prefectures. Go-to-market angle should emphasize thermal engineering specialization for 800V+ architectures where talent scarcity constrains incumbent response speed. For Investors and Strategic Acquirers: Re-rating potential sits with bidirectional-capable controller specialists given FERC Order 2222 aggregation rule expansion and METI residential V2H standardization. Long-term viability favors firms with decade-scale utility service life commitments and construction channel specification lock-in. Acquisition target archetype: mid-tier European firms with IEC 61851 compliance depth and HVAC-EV orchestration software. Signal to watch: utility interconnection queue clearance rates in Texas and California as bidirectional commissioning bottleneck indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive access to Wolfspeed and Coherent output secures 800V+ controller manufacturing capacity against allocation constraints. |
| Construction Channel Partnership Restructuring | Electrical contractor specification lock-in captures Title 24 and EPBD-mandated new construction procurement before competitor entry. |
| Bidirectional Capability Standardization | Dual-active-bridge topology deployment across product portfolios enables FERC Order 2222 grid services revenue capture. |
| ISO 15118-20 Certification Investment | Plug and Charge interoperability neutralizes protocol fragmentation risk across North American and European deployment. |
| Vehicle-to-Home Software Platform Launch | Residential backup orchestration creates premium tier pricing power in Japanese and Texas markets with resilience priorities. |
Research Methodology
Document review covered SEC 10-K filings from power electronics vendors, FERC Order 2222 implementation dockets, and California Title 24 compliance guidance, complemented by interviews with utility distributed resource planners, fleet electrification procurement leads, electrical contractor specification managers, and silicon carbide substrate supply directors. Secondary validation drew from IEA EV outlook data, China GB/T standards documentation, and EU Energy Performance of Buildings Directive transposition reports. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Historical deployment trajectories across the analysis window were cross-referenced against expert panel input on utility procurement timing and fleet mandate compliance deadlines. Segmentation modeling incorporated power electronics architecture, communication protocol, grid-interconnection complexity, and regional regulatory framework dimensions. CAGRs were derived from infrastructure investment run-rates and EV production volume correlations. Industry-specific inputs included silicon carbide substrate allocation forecasts and electrical contractor channel capacity surveys.
Utility interconnection delay escalation, silicon carbide supply concentration disruption, and protocol standardization deadlock are the dominant revision risks to deployment assumptions. Forecasts reflect documented base-case assumptions regarding mandate enforcement timing and substrate capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Vehicle Fast and Rapid Charger Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
Solar Charging Station Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
Electric Vehicle Safe Charging Inlet Market
Electric Vehicle Charging
Home EV Chargers Market
Electric Vehicle Charging
United States Electric Vehicle Charging Systems and Equipment Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Electric Vehicle Showroom Charger Market
Electric Vehicle Charging
Electric Vehicle Charging Facilities Market
Electric Vehicle Charging
India Battery Swapping for Electric Two-Wheelers Market
Electric Vehicle Charging
EV Charging Software Market
Electric Vehicle Charging
EV Charging Kiosk Market
Electric Vehicle Charging
Electric Vehicle Charging Management Software Market