
 Pantograph Charger Market | 2026-2036
Pantograph Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Pantograph Charger Market Analysis
Multi-source procurement for high-voltage contact systems is realigning supply relationships across the pantograph charger value chain. ABB leverages its traction electrification heritage to anchor European depot installations. Siemens competes through integrated rail-to-road charging architectures. Schunk Group specializes in precision carbon contact strip manufacturing that sustains performance under high-current duty cycles.
A pantograph charger is an overhead current collection device that uses an articulated mechanical arm with carbon or copper-alloy contact strips to draw electrical power from an energized conductor rail or catenary wire, typically operating at voltages between 600V and 800V DC for heavy-duty vehicle applications. Static charger deployments dominate current infrastructure spending as transit agencies prioritize depot-based overnight replenishment, while smart chargers represent the fastest-expanding technology segment due to grid-integrated load management and predictive maintenance capabilities. Mobile charger adoption remains concentrated in logistics corridors where route flexibility outweighs infrastructure density requirements.
The EU Green Deal and F-Gas Regulation are mandating emissions reductions that accelerate municipal procurement of electrified bus fleets, while CE marking and MDR compliance frameworks govern electrical safety and mechanical reliability standards for overhead charging equipment. Germany's KBA enforces type-approval protocols that shape product certification pathways for manufacturers seeking market access. Stakeholders must monitor evolving interoperability standards between automatic contact charging and emerging inductive systems as technology pathways diverge across procurement jurisdictions.
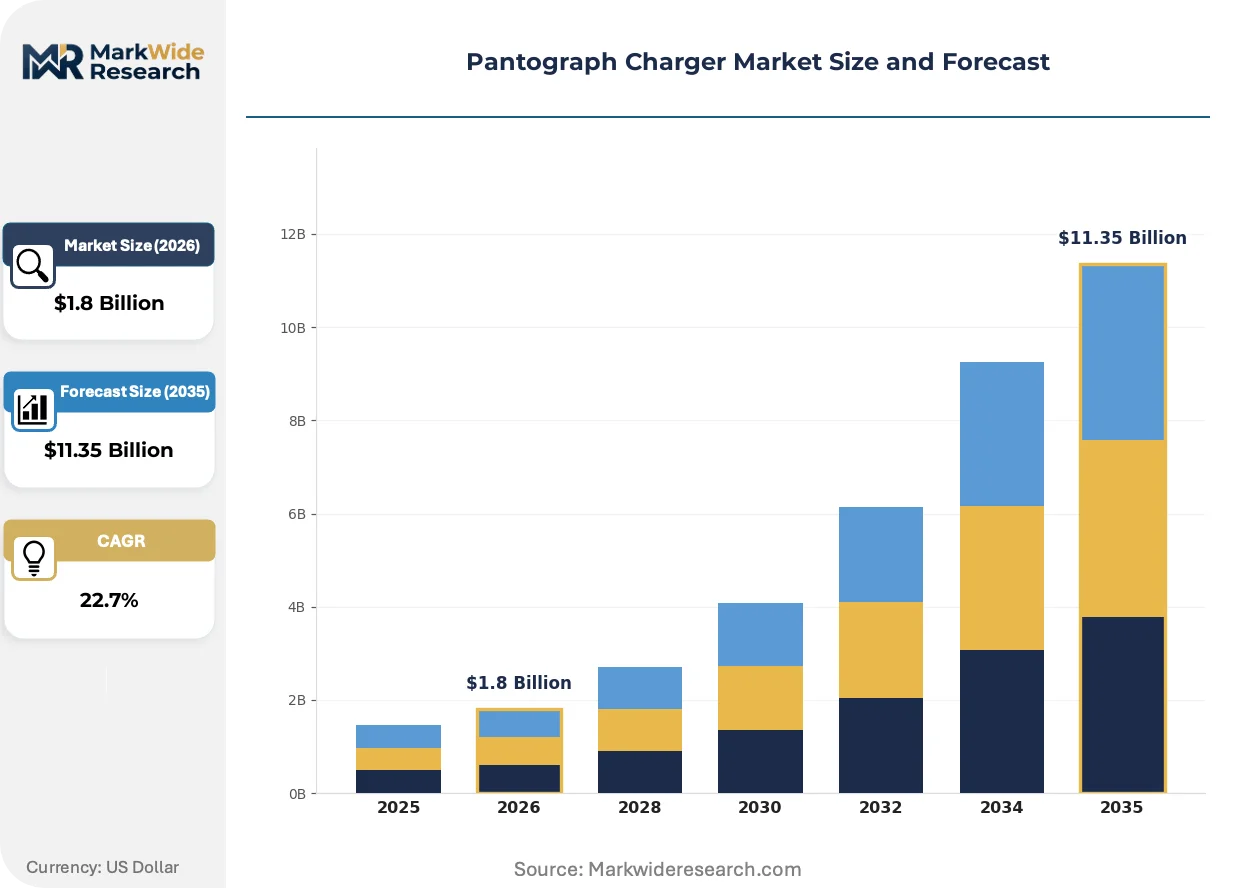
Market Dynamics
Depot-based overnight charging infrastructure is consolidating procurement power among municipal transit agencies across Northern Europe, compressing vendor margins while accelerating standardization of high-voltage contact systems.
Growth Catalysts
- EU Green Deal fleet mandates:Binding emissions targets for public transport operators in Germany and the Netherlands are accelerating electrification tenders and expanding addressable demand for overhead charging hardware.
- Catenary network legacy:Existing overhead wire infrastructure in French and German urban corridors reduces deployment friction and capital barriers for pantograph charger retrofits versus greenfield alternatives.
- Carbon contact strip advances:Improved graphite-copper composite formulations are extending maintenance intervals and lowering total cost of ownership for high-frequency depot operations.
Market Restraints
- Copper price volatility:Contact strip and conductor rail manufacturing face input cost pressure from commodity fluctuations, squeezing margin stability for component suppliers.
- Regional supply concentration:Precision mechanical fabrication for articulated arm assemblies clusters in Southern Germany, creating geographic vulnerability to localized disruption.
- Inductive charging substitution:Wireless power transfer systems under development for autonomous vehicle applications threaten long-term relevance of mechanical contact methods.
Strategic Opportunities
- Polish and Romanian municipal expansion:EU cohesion fund allocations for sustainable urban mobility are opening procurement windows in underpenetrated Eastern European transit markets.
- Rail-to-road convergence:Integration of traction electrification expertise from railway applications with bus depot architectures creates cross-sector technology transfer potential.
- CE marking pathway harmonization:Streamlined conformity assessment procedures under MDR and Low Voltage Directive revisions are reducing time-to-market for new equipment entrants.
Industry Challenges
- High-voltage technician scarcity:Qualified electrical specialists for 800V DC installation and maintenance are in short supply across German and French contracting markets.
- KBA type-approval timelines:Extended certification cycles for novel contact system designs delay revenue recognition and compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pantograph Charger Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Chargers, Mobile Chargers, Fast Chargers, Smart Chargers End User: Public Transport, Commercial Fleets, Private Vehicles, Logistics Technology: Contact Charging, Inductive Charging, Automatic Charging, Manual Charging Installation Type: On-Street, Depots, Parking Lots, Integrated |
| Companies Covered | ABB, Siemens, Schunk Group, Wabtec Corporation, Hangzhou Aoneng Power Supply Equipment Co., Ltd., ChargePoint, Alstom, Schneider Electric, Kempower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pantograph Charger Market Emerging Trajectories
Smart grid integration and predictive diagnostics are redefining value capture in pantograph charging infrastructure, shifting vendor competition from hardware specifications to software-enabled service models.
Silicon carbide power electronics are rewriting thermal and efficiency parameters for charging station inverters. Transit operators in the Netherlands are piloting these systems for depot installations. The technology is compressing footprint requirements and enabling higher power density in constrained urban sites.
F-Gas Regulation phase-down schedules are accelerating refrigerant transition timelines for thermal management systems in charging equipment. Manufacturers must redesign cooling architectures to accommodate lower-GWP alternatives. German component suppliers are absorbing the steepest compliance costs due to earlier enforcement dates.
Lifecycle service contracting is displacing transactional equipment sales in municipal procurement. French and Dutch transport authorities now bundle installation, maintenance, and energy management under single-vendor agreements. This consolidation favors integrated suppliers with software capabilities over pure hardware manufacturers.
Pantograph Charger Market Segmentation
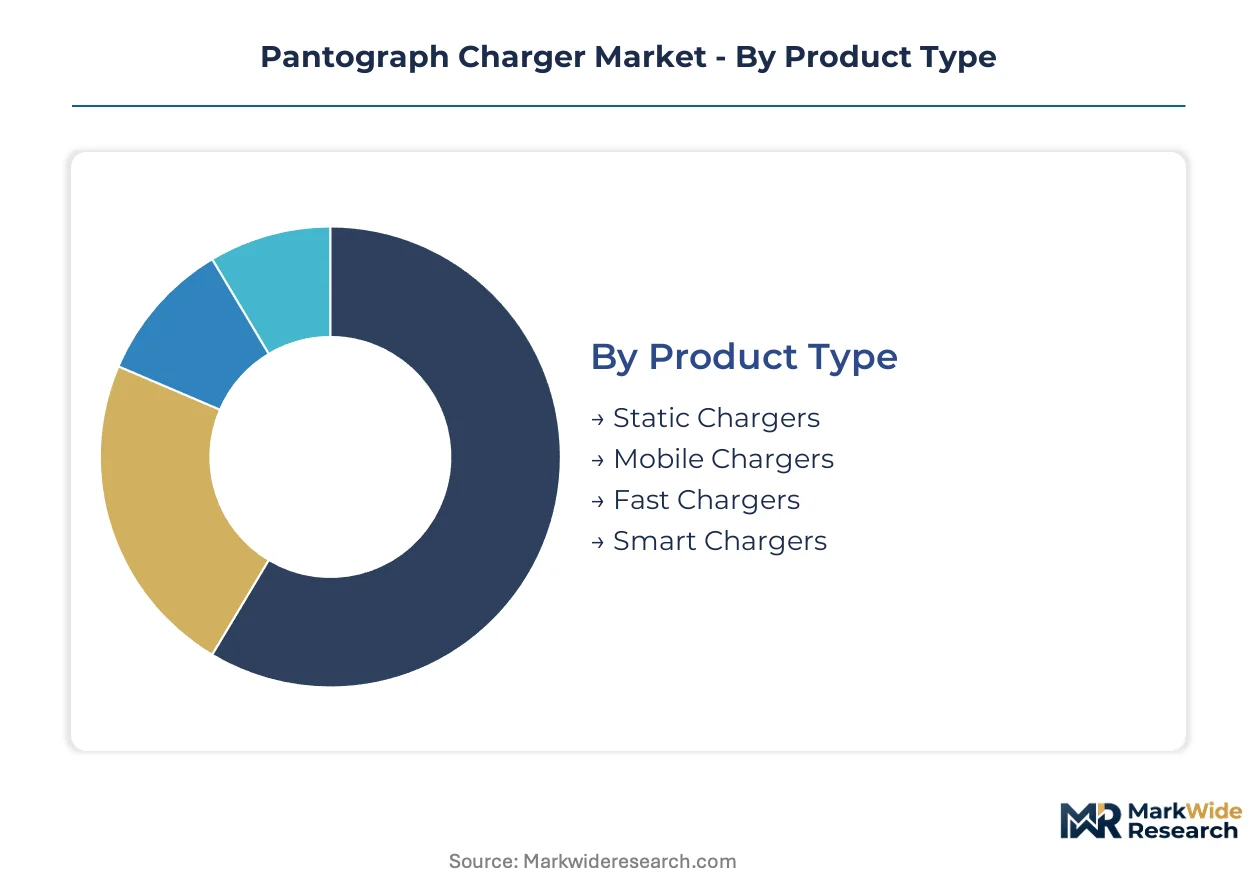
Pantograph charger procurement patterns diverge sharply across product architectures and deployment contexts. Transit agencies prioritize depot-based static systems for fleet standardization, while logistics operators demand mobile configurations for route flexibility. Technology selection increasingly hinges on grid integration capabilities rather than contact mechanism alone.
Product Type:
Upgrade cycles for pantograph charging infrastructure concentrate on systems with embedded intelligence and higher power throughput, reflecting municipal demands for operational visibility and faster turnaround times.
- Static Chargers:Fixed-position overhead systems with articulated pantograph arms mounted on dedicated infrastructure. German and Dutch municipal bus operators dominate procurement for overnight depot replenishment, driven by EU Green Deal fleet electrification mandates and established catenary network legacies in Northern European urban corridors.
- Smart Chargers:Grid-integrated systems with predictive load management, remote diagnostics, and dynamic power allocation. French transport authorities are bundling these into lifecycle service contracts that displace transactional hardware sales, with silicon carbide power electronics compressing footprint requirements in constrained Paris and Lyon depot sites.
- Mobile Chargers:Deployable units for temporary or corridor-based charging along logistics routes.
- Fast Chargers:High-power systems designed for rapid opportunity charging during service intervals.
Static chargers sit at the top of the volume ranking, with smart chargers climbing the fastest.
End User:
Customer archetypes segment cleanly between public procurement regimes with extended tender cycles and commercial operators prioritizing asset utilization rates.
- Public Transport:Municipal bus and tram operators with standardized fleet compositions and centralized depot infrastructure. Procurement concentrates in Germany, France, and the Netherlands where KBA type-approval protocols and EU Green Deal binding targets shape equipment specifications, with carbon contact strip maintenance intervals representing a critical total-cost-of-ownership calculation.
- Logistics:Freight operators and last-mile delivery fleets requiring route-flexible charging solutions. Demand clusters along Rhine-Alpine and North Sea-Baltic corridors where mobile pantograph configurations supplement fixed infrastructure, driven by F-Gas Regulation compliance timelines for thermal management systems and scarcity of qualified 800V DC technicians.
- Commercial Fleets:Corporate and rental vehicle operators with mixed-duty cycle requirements.
- Private Vehicles:Individual owner-operators with intermittent high-power charging needs.
Public transport commands the dominant revenue share, though logistics applications are expanding most quickly.
Technology:
Contact mechanism selection reflects a tension between proven mechanical reliability and emerging wireless alternatives, with automation levels determining labor cost structures.
- Contact Charging:Direct mechanical interface between pantograph carbon strips and energized conductor rails or catenary wires, operating at 600V-800V DC. This remains the default specification for German and French municipal tenders due to KBA certification pathways and established maintenance protocols, with graphite-copper composite formulations extending service intervals under high-frequency depot duty cycles.
- Automatic Charging:Self-aligning pantograph systems that eliminate manual positioning. Dutch transit operators are piloting these for driverless bus deployments, with CE marking and MDR compliance frameworks governing electrical safety certification under streamlined conformity assessment procedures.
- Inductive Charging:Wireless power transfer via magnetic resonance for autonomous vehicle applications.
- Manual Charging:Operator-positioned pantograph arms requiring physical intervention.
Contact charging retains volume leadership, while automatic systems are gaining share fastest.
Installation Type:
Physical deployment context determines capital intensity, grid connection complexity, and regulatory permitting pathways.
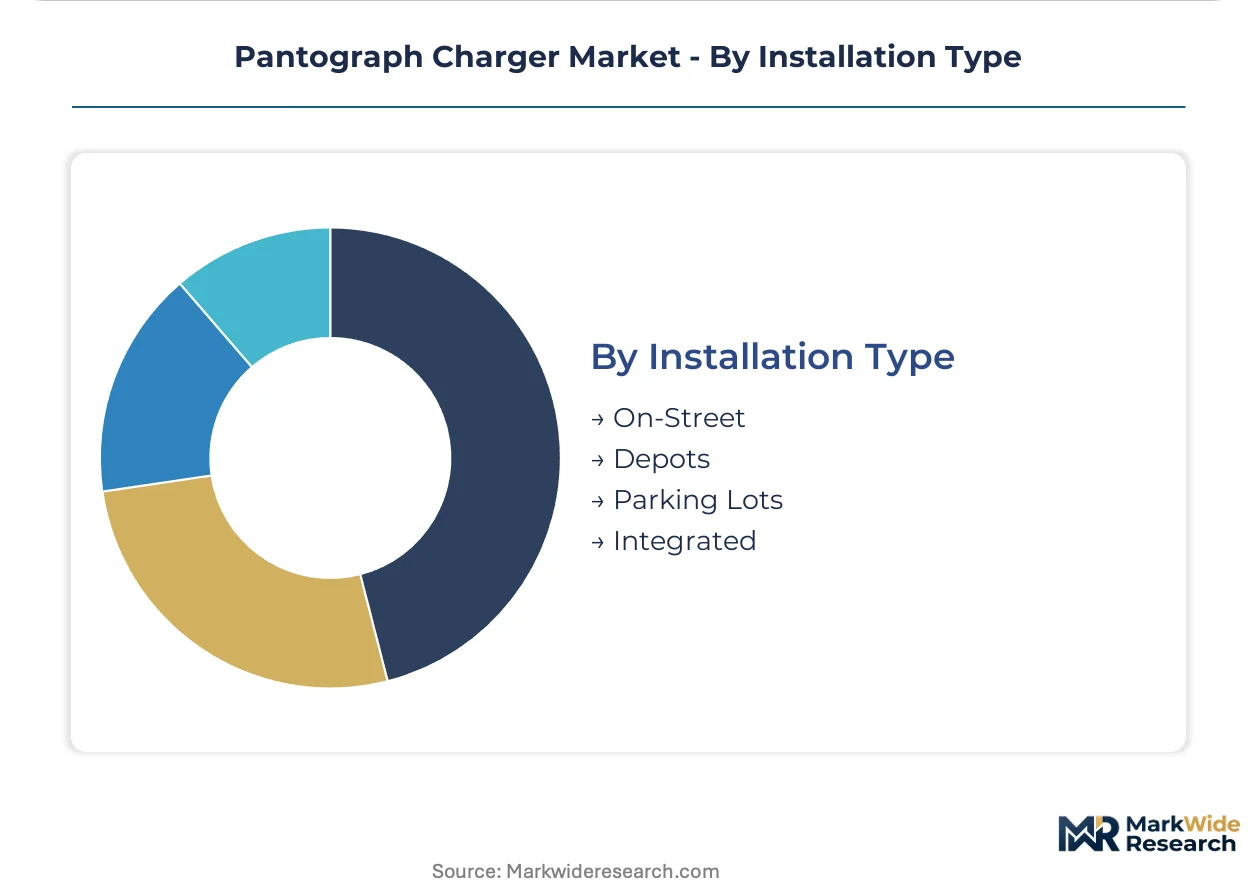
- Depots:Dedicated fleet facilities with overnight charging infrastructure and centralized maintenance. Northern European urban corridors with existing overhead catenary networks—particularly in German cities like Hamburg and Berlin—exhibit lowest deployment friction for these installations, with lifecycle service contracting now bundling installation, energy management, and predictive maintenance under single-vendor agreements.
- On-Street:Curb-side installations integrated with urban infrastructure. French cities are prioritizing these for bus rapid transit corridors, constrained by high-voltage technician scarcity across contracting markets and extended KBA type-approval timelines for novel contact system designs.
- Parking Lots:Shared-use facilities serving multiple vehicle classes.
- Integrated:Pantograph systems embedded within existing transport infrastructure such as bus stops or rail platforms.
Depot installations dominate current infrastructure spending, with integrated configurations showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan corridor anchors European pantograph charger deployment, with German municipal operators accounting for the densest concentration of depot-based infrastructure investment.
Germany
Municipal bus fleets in Hamburg and Berlin drive procurement volumes for overnight depot systems. KBA type-approval protocols govern certification timelines for novel contact strip designs. The Baden-Württemberg industrial cluster hosts precision mechanical fabrication for articulated arm assemblies.
France
Paris and Lyon transit authorities bundle lifecycle service contracts covering installation through predictive maintenance. EU Green Deal binding targets accelerate electrification tenders for Île-de-France bus operators. The Auvergne-Rhône-Alpes region pilots silicon carbide inverters for constrained urban depot sites.
Netherlands
Randstad corridor operators deploy automatic pantograph systems for driverless bus trials. CE marking and MDR compliance frameworks streamline electrical safety certification for grid-integrated chargers. Eindhoven serves as a testbed for smart load management algorithms.
Poland
Warsaw and Krakow municipal agencies access EU cohesion fund allocations for sustainable urban mobility. F-Gas Regulation phase-down schedules force thermal management redesigns for charging equipment cooling. The Silesian urban agglomeration develops maintenance technician training programs.
Romania
Bucharest transport operators evaluate pantograph retrofits against greenfield inductive alternatives. National procurement regulations align with EU Green Deal fleet mandate timelines. The Cluj-Napoca metropolitan area experiments with mobile charger configurations for peripheral route coverage.
Pantograph Charger Market Vendor Landscape
Global majors compete with regional champions across electrification technology heritage and rail-to-road adaptation capabilities. The vendor base organizes around three tiers: integrated industrial conglomerates with traction power expertise, precision component specialists, and emerging Asian fabricators. Strategic moves concentrate on lifecycle service contracting and silicon carbide power electronics integration.
Within the integrated systems tier, ABB and Siemens exemplify archetypes leveraging railway electrification legacies for depot infrastructure. Schunk Group occupies a position among precision contact component specialists. Hangzhou Aoneng Power Supply Equipment Co., Ltd. represents Chinese-scale manufacturing entry into European procurement channels.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schunk Group |
| Wabtec Corporation |
| Hangzhou Aoneng Power Supply Equipment Co., Ltd. |
| ChargePoint |
| Alstom |
| Schneider Electric |
| Kempower |
| Others |
Supply Flow & Price Mechanics
Municipal lifecycle service contracting across French and Dutch transport authorities is compressing hardware margins while elevating software-enabled service premiums, forcing suppliers to restructure cost bases around predictive maintenance capabilities rather than equipment markups.
Pricing Analysis
Copper and graphite input costs pass through directly to contact strip and conductor rail pricing, with German component suppliers absorbing the steepest margin compression due to earlier F-Gas Regulation enforcement dates for thermal management redesigns. Three-tier pricing structure across premium smart-grid-integrated, standard static depot, and economy mobile configurations separates vendors with silicon carbide inverters from legacy hardware manufacturers. Pricing pressure stems from procurement consolidation among Northern European municipal agencies bundling installation through maintenance under single-vendor agreements. Logistics operators along Rhine-Alpine corridors exhibit highest price sensitivity due to route-flexibility requirements, while public transport agencies prioritize total-cost-of-ownwership over upfront capital expenditure.
Supply Chain Analysis
Refurbishment flows for carbon contact strips and articulated arm assemblies are developing in Baden-Württemberg and Silesian industrial clusters, extending component lifecycles and creating secondary supply streams for maintenance-intensive depot operations. Precision mechanical fabrication concentrates in Germany, Poland, and China, with graphite-copper composite formulations drawing from established carbon processing capabilities in Southern Germany and emerging Eastern European suppliers. Single-source vulnerability persists for high-voltage silicon carbide power electronics tethered to specialized semiconductor foundries. Distribution runs through rail-electrification channel partners with existing municipal transit relationships, supplemented by direct procurement for large-scale depot installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in pantograph charging infrastructure rests on silicon carbide power electronics cost curves and premium-tier service bundling, with software-enabled predictive maintenance displacing transactional hardware sales.
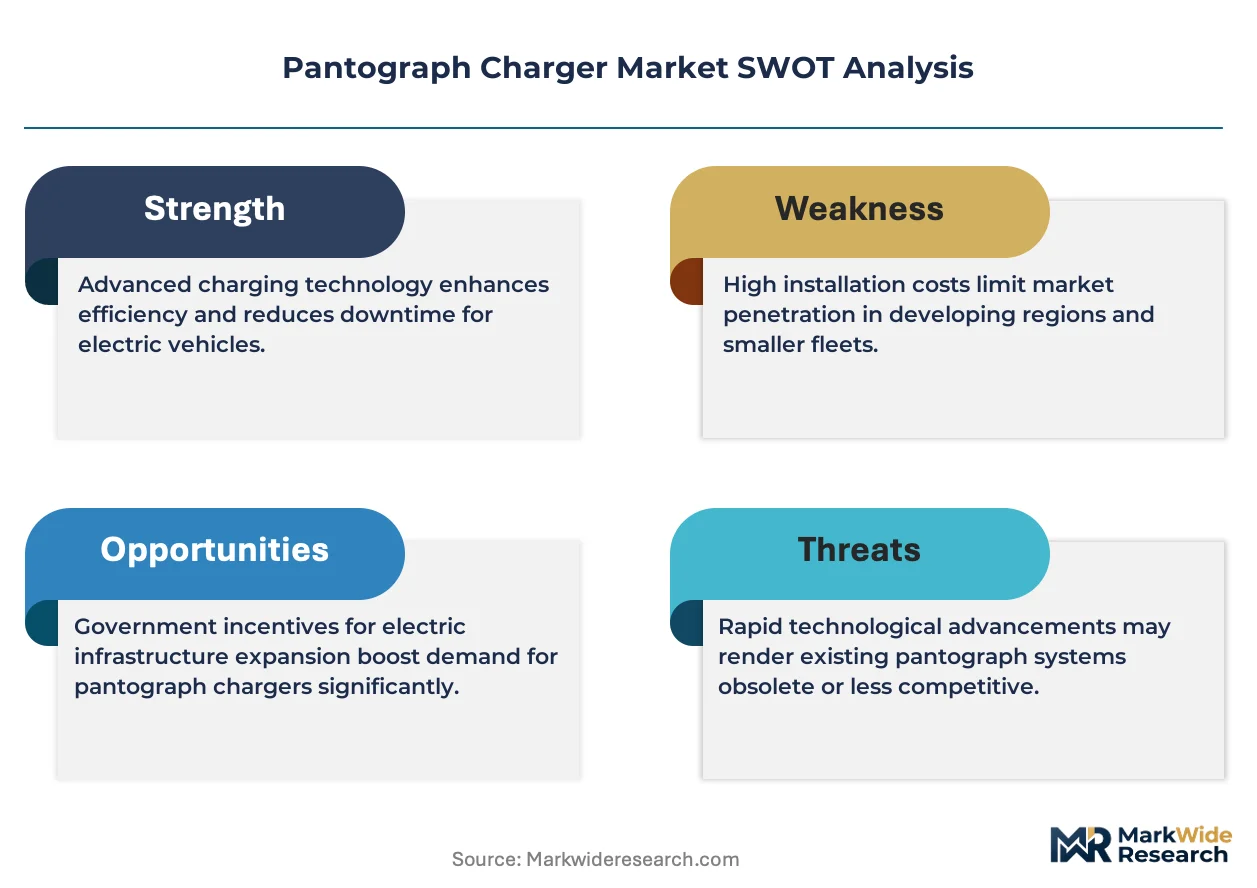
For Market Incumbents: Anticipate inductive charging substitution threats by accelerating automatic pantograph deployment for driverless bus trials, while deepening backward integration into carbon contact strip manufacturing to defend margin position against commodity volatility. KBA type-approval timeline compression represents the critical certification lever for revenue recognition acceleration. For New Entrants and Emerging Players: EU cohesion fund allocations in Poland and Romania open a window for depot infrastructure penetration in underelectrified Eastern European municipal markets, with Warsaw and Krakow procurement cycles offering lower competitive density than saturated German corridors. Target rail-to-road technology transfer partnerships as the primary go-to-market mechanism for credibility establishment. For Investors and Strategic Acquirers: Asymmetric upside sits with precision contact component specialists possessing captive graphite-copper composite formulation capabilities, given lifecycle service contracting trends elevating aftermarket revenue streams. Five-to-ten year viability hinges on smart grid integration software stacks. Monitor KBA and CE marking pathway harmonization progress as regulatory inflection signals for equipment entrant viability.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Compresses depot footprint requirements in constrained Paris and Lyon urban sites. |
| Lifecycle Service Contracting | Bundles predictive maintenance with energy management under single-vendor French and Dutch agreements. |
| Rail-to-Road Technology Transfer | Leverages ABB and Siemens traction electrification heritage for bus depot architecture adaptation. |
| Eastern European Geographic Expansion | Captures EU cohesion fund flows for Warsaw and Krakow sustainable urban mobility procurement. |
| Carbon Contact Strip Formulation R&D | Extends maintenance intervals under high-frequency German depot duty cycles. |
Methodological Framework
Multiple input streams — technical discussions with pantograph system engineers and depot infrastructure planners, procurement officer interviews at French and Dutch transport authorities, and regulatory affairs consultations on KBA and CE marking pathways — were reconciled against secondary validation from EU Green Deal implementation reports, F-Gas Regulation compliance databases, and municipal electrification tender documents. Bottom-up installation volume estimates across German, French, and Polish urban corridors were triangulated with top-down market sizing from rail-electrification equipment trade flows.
Data-stream reconciliation informed analytical frameworks spanning product architecture, end-user procurement regime, contact mechanism automation level, and physical deployment context across the projection horizon. CAGRs were derived from segment-level adoption curves weighted by EU fleet mandate compliance timelines and catenary network legacy density. Forecast inputs incorporated silicon carbide inverter penetration rates and lifecycle service contract bundling trends specific to Northern European municipal transit.
Revisions become necessary when EU Green Deal fleet mandate enforcement accelerates or delays, inductive charging technology achieves cost parity for autonomous applications, or copper-graphite composite supply disruptions materialize. Forecasts reflect assumptions on KBA type-approval timeline stability and qualified 800V DC technician availability. Practitioners should monitor CE marking pathway harmonization progress and F-Gas Regulation phase-down schedule adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Germany Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
France Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
APAC Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Integrated EV Chargers Market
Electric Vehicle Charging
Electric Two Wheeler Charging Station Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
EV Charging Point Market
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
EV Charging System Test and Certification Equipment Market