

Bi Directional Electric Vehicle Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Bi Directional Electric Vehicle Charger Market Insights
Software-defined energy management subscriptions is broadening what charger vendors actually monetize beyond hardware sales. Tesla leverages its proprietary ecosystem to control the full vehicle-to-home orchestration stack. Siemens anchors European utility partnerships with grid-code-certified bidirectional platforms. Wallbox competes through modular residential systems that extend into fleet-aggregation services.
A bi-directional electric vehicle charger converts direct current from a vehicle's battery into alternating current compatible with building loads or grid infrastructure, typically operating at power levels from 7 kW residential units to 350 kW commercial systems with IEEE 1547 interconnection compliance. Its primary purpose enables vehicle-to-grid discharge, vehicle-to-home backup power, and demand-charge reduction for commercial facilities. Wall-mounted chargers dominate residential attachment as homeowners prioritize fixed-installation reliability, while DC fast chargers capture the steepest growth trajectory in fleet operations where turnaround speed determines asset utilization. Combined Charging System technology leads interoperability investment among European and North American OEMs, though CHAdeMO retains entrenched positions in Japanese municipal deployments.
The US Federal Energy Regulatory Commission and state public utility commissions shape market access through interconnection standards and rate-design approvals for vehicle-grid integration services. Europe's F-Gas Regulation and CE marking requirements constrain coolant selections in high-power thermal management systems, directly affecting product development cycles. California's Air Resources Board and Germany's Bundesnetzagentur both mandate cybersecurity certification for grid-connected assets, creating compliance thresholds that filter vendor participation. Stakeholders must track which jurisdictions move first on standardized revenue streams for distributed energy resources to avoid stranded hardware investments.
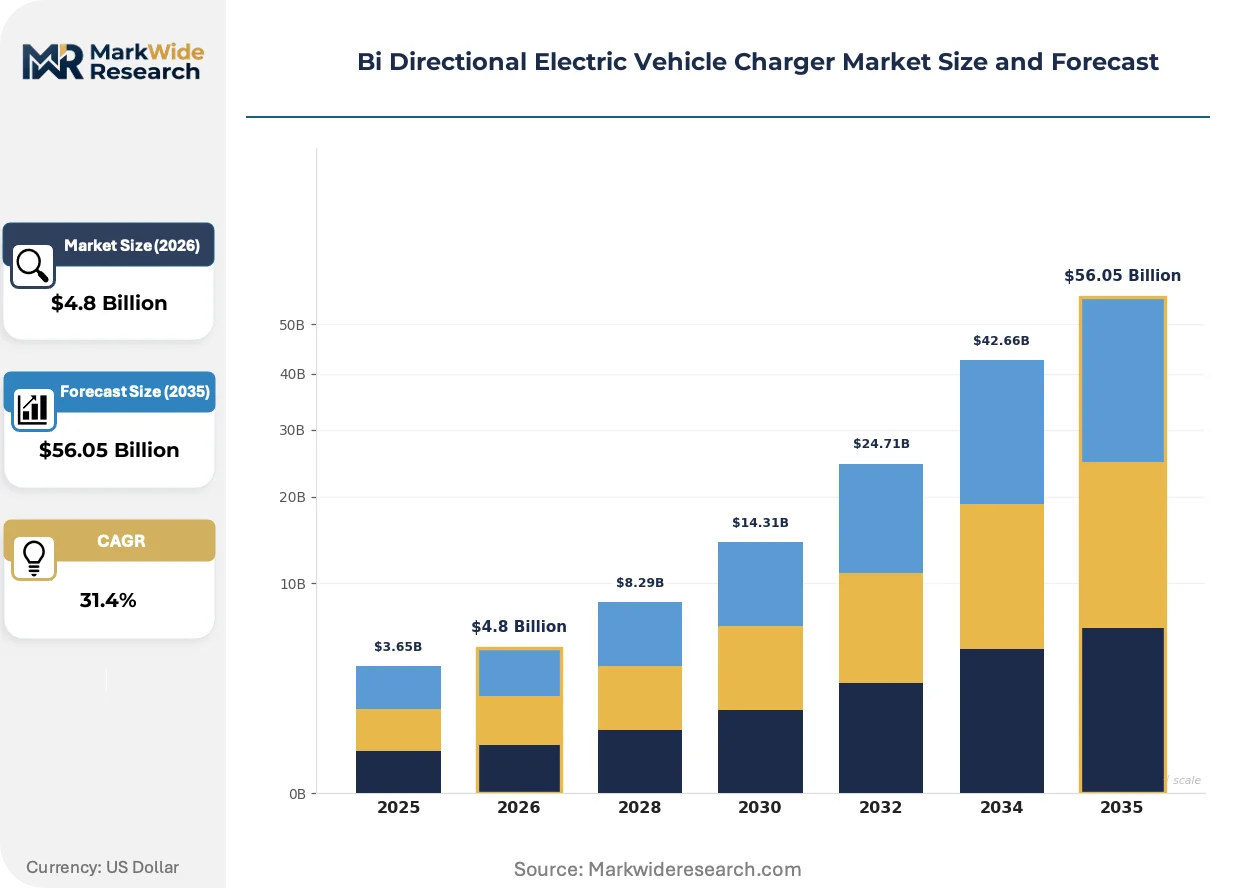
Market Dynamics
Utility-backed demand response programs are forcing fleet operators to treat bidirectional chargers as revenue-generating grid assets rather than passive infrastructure, compressing procurement cycles and reshaping vendor qualification criteria around IEEE 1547 certification and cybersecurity attestations.
Growth Catalysts
- California SB 100 Mandates:Vehicle-grid integration requirements are accelerating hardware deployments across municipal and commercial fleets, creating standardized procurement templates that reduce vendor qualification friction.
- Silicon Carbide Power Electronics:Wide-bandgap semiconductors are reducing thermal losses in 350 kW commercial systems, enabling faster turnaround times for fleet operators managing high-utilization assets.
- Aggregated Behind-the-Meter Storage:Fleet depots are monetizing pooled battery capacity through frequency regulation services, transforming charging infrastructure into grid-stabilizing revenue centers.
Market Restraints
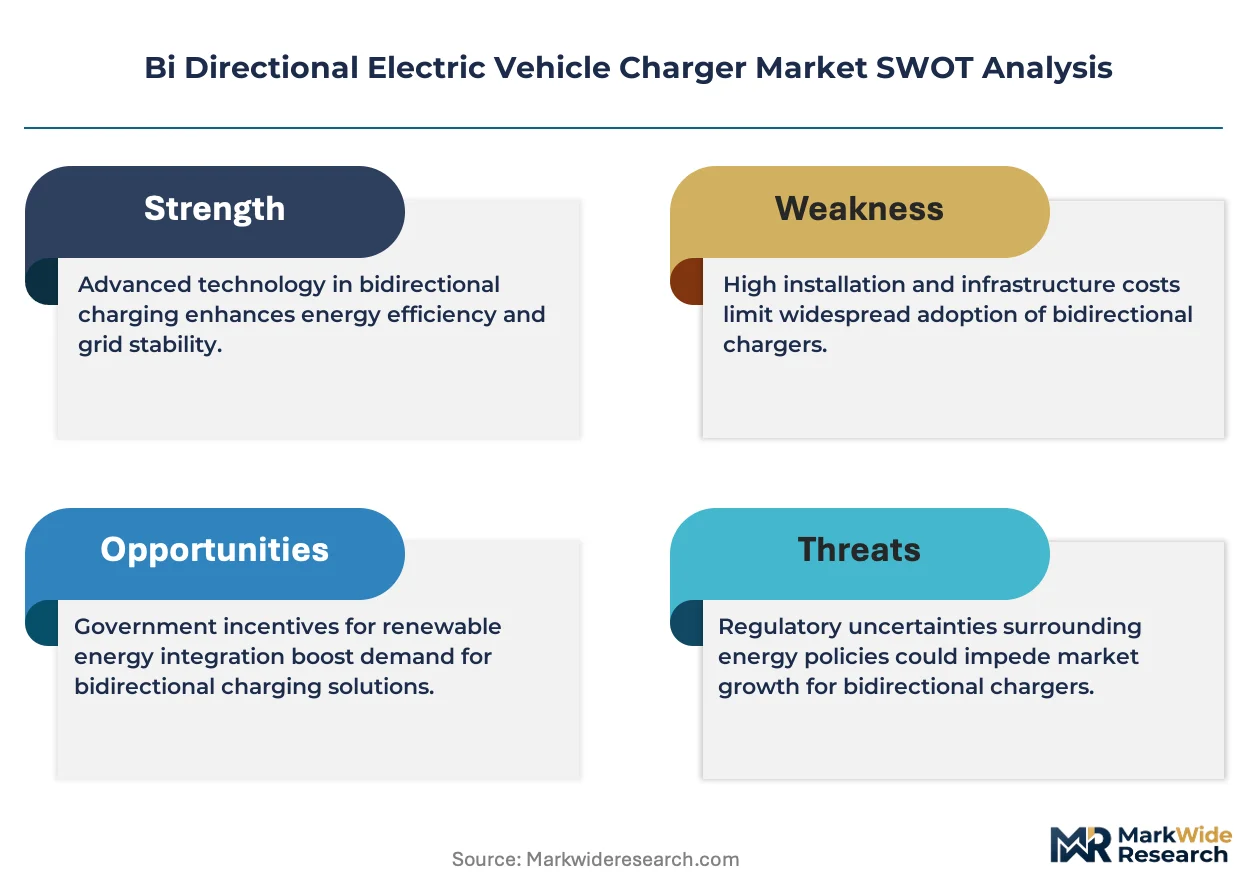
- Copper and Rare Earth Magnet Volatility:Power electronics and motor components face input cost pressure from concentrated mining jurisdictions, squeezing margins on high-power thermal management systems.
- CHAdeMO Entrenchment in Japan:Municipal procurement standards anchored to legacy connector protocols create interoperability friction for CCS-equipped vehicles entering fleet rotations.
- F-Gas Thermal Management Constraints:Europe's refrigerant phase-down regulations are extending product development cycles for liquid-cooled 350 kW systems, delaying commercialization timelines.
Strategic Opportunities
- Vehicle-to-Home Residential Bundling:Homeowners in Germany and South Korea are combining solar-plus-storage installations with bidirectional chargers, creating integrated energy management ecosystems.
- Software-Defined Energy Subscriptions:Recurring revenue models for grid orchestration and demand-charge optimization are displacing pure hardware sales in commercial segments.
- US Inflation Reduction Act Credits:Section 30C infrastructure incentives are expanding addressable market size for residential and fleet installations, lowering effective customer acquisition costs.
Industry Challenges
- IEC 61850 and IEEE 2030.5 Certification Timelines:Multi-jurisdiction protocol compliance is extending product validation cycles, delaying revenue recognition for hardware vendors.
- Grid Interconnection Queue Congestion:Utility engineering review backlogs for behind-the-meter distributed energy resources are stretching deployment schedules for commercial fleet depots.
- Cross-Standard Patent Licensing:Intellectual property fragmentation across CCS and CHAdeMO patent pools is inflating royalty stacks and complicating product architecture decisions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bi Directional Electric Vehicle Charger Market Trends and Innovations
Silicon carbide power modules and solid-state thermal management are compressing charger form factors while grid-edge software platforms are unbundling hardware from energy services, creating new monetization architectures.
Silicon carbide MOSFETs are replacing silicon IGBTs in high-frequency power conversion stages, cutting switching losses by half in 350 kW commercial systems. Fleet operators in North America are specifying SiC-based units for new depot construction, prioritizing reduced cooling overhead and higher power density. This semiconductor transition is electrifying the competitive landscape, compressing incumbent advantages in thermal engineering and enabling new entrants to leapfrog legacy platform investments.
The US Inflation Reduction Act's Section 30C tax credits are restructuring capital deployment patterns across fleet and residential segments, with bonus credits for domestic content sourcing. Equipment vendors are reconfiguring supply chains to capture full incentive value, shifting assembly operations to qualified domestic facilities. Commercial fleet procurement teams are front-loading 2024-2025 deployments to lock in credit certainty before program sunset provisions trigger.
Aggregators are unbundling charger hardware from energy management services, selling grid-responsive discharge capacity as a standalone subscription. Fleet managers are adopting this model to avoid capital ownership while capturing demand response revenue streams. This service-layer separation is most visible in California and Germany, where utility tariff structures reward dispatchable behind-the-meter resources with capacity payments and frequency regulation premiums.
Bi Directional Electric Vehicle Charger Market Segmentation
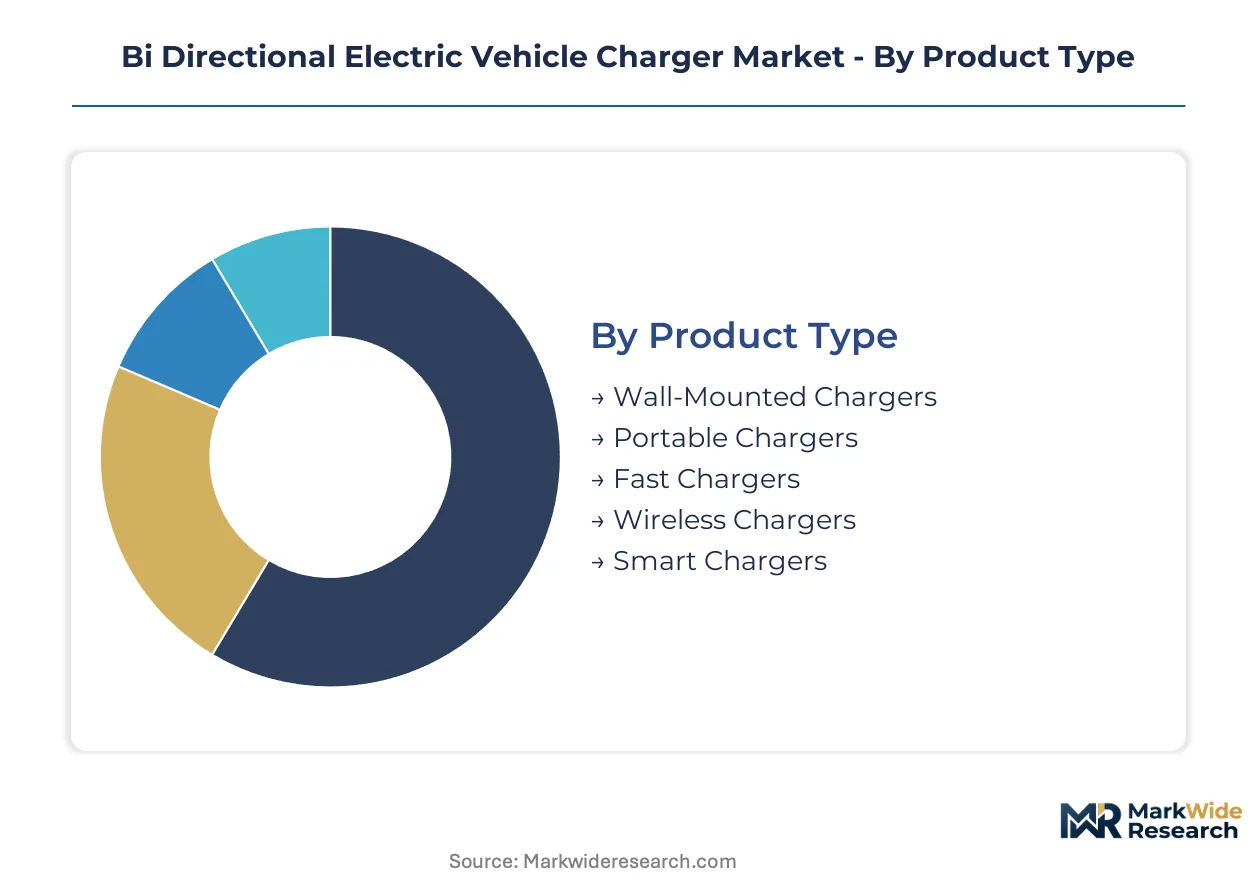
Segmentation in bidirectional charging reveals how hardware specifications, grid interconnection protocols, and ownership models create distinct procurement pathways. Fleet operators prioritize DC fast charging with vehicle-to-grid revenue stacking, while residential buyers favor fixed-installation wall units with vehicle-to-home backup capability.
Product Type:
Volume deployment concentrates in entry-level fixed-installation units, while premium pricing attaches to high-power modular systems with liquid cooling and multi-protocol interoperability.
- Wall-Mounted Chargers:Fixed-installation units dominate residential attachment where homeowners prioritize reliability and weather-sealed enclosures. Demand concentrates in Germany and California, driven by solar-plus-storage bundling incentives and vehicle-to-home backup mandates from utilities like Pacific Gas & Electric.
- Fast Chargers:High-power DC systems operating at 150-350 kW enable fleet turnaround under 30 minutes with bidirectional discharge capability. North American fleet operators are specifying these for depot construction, prioritizing IEEE 1547 certification for frequency regulation revenue participation.
- Portable Chargers:Mobile units with detachable cables serve multi-vehicle households and temporary installations.
- Wireless Chargers:Inductive pad systems eliminate connector wear but face efficiency penalties and interoperability constraints.
- Smart Chargers:Grid-responsive units with embedded energy management software command subscription revenue streams.
Mature deployment sits with wall-mounted residential systems. Newer deployment is concentrated in fast chargers for fleet electrification.
Technology:
Connector protocol selection determines vehicle compatibility, grid interconnection standards, and patent licensing obligations across procurement decisions.
- Combined Charging System:The European and North American OEM consortium standard supports AC and DC charging through a single inlet with power levels to 350 kW. Volkswagen, BMW, and Ford fleet vehicles in the US and Germany ship CCS-native, creating procurement lock-in for commercial operators managing mixed-brand fleets.
- DC Chargers:Direct-current systems bypass onboard converters for faster energy transfer and heavier discharge cycles. Fleet depots in South Korea are deploying DC bidirectional infrastructure under Korea Electric Power Corporation demand response programs, prioritizing silicon carbide power electronics for thermal efficiency.
- AC Chargers:Lower-power units leveraging vehicle onboard inverters dominate residential price-sensitive segments.
- CHAdeMO:The Japanese standard retains municipal procurement preference in Tokyo and Osaka, creating friction for CCS-equipped imports.
- Tesla Supercharger:Proprietary connector with expanding non-Tesla access through network licensing agreements.
Protocol standardization is accelerating around Combined Charging System. CHAdeMO maintains entrenched positions in Japanese municipal infrastructure.
Application:
Site-specific duty cycles and revenue stacking opportunities create divergent hardware specifications across deployment contexts.
- Fleet Operations:High-utilization depots with scheduled charging windows and vehicle-to-grid aggregation contracts. California municipal fleets under SB 100 mandates are procuring bidirectional hardware with cybersecurity certification from the California Air Resources Board, treating chargers as grid assets with capacity payment revenue.
- Residential Use:Single-family installations with solar integration and backup power priorities. German homeowners combine bidirectional chargers with battery storage under Bundesnetzagentur grid codes, creating integrated energy management ecosystems with vehicle-to-home discharge during peak pricing periods.
- Commercial Facilities:Workplace and retail installations with demand-charge reduction objectives.
- Public Parking:Curbside and garage infrastructure with high connector turnover and vandalism exposure.
- Carsharing Stations:Shared-vehicle hubs with utilization-maximizing fast-charge requirements.
Revenue stacking complexity peaks in fleet operations. Simpler payback calculations drive residential adoption.
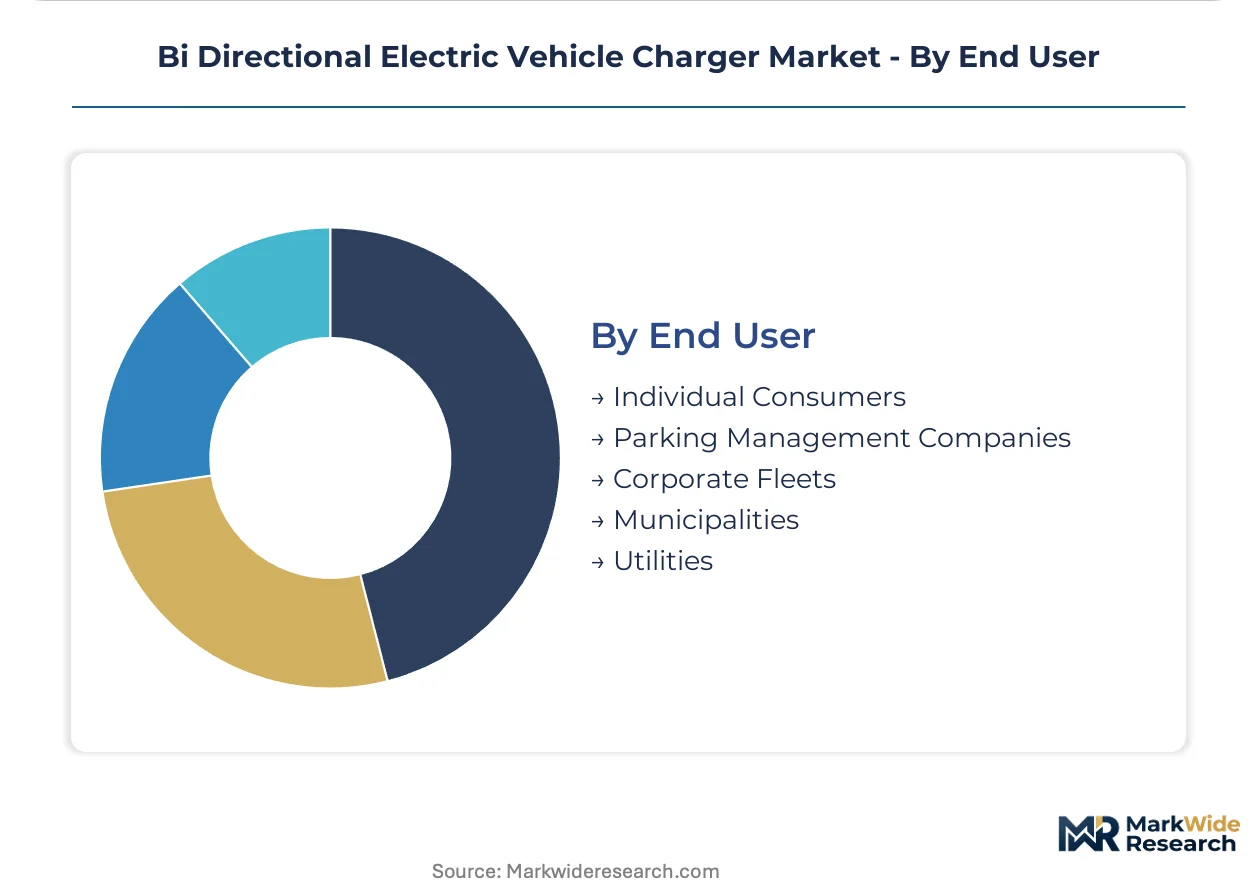
End User:
Procurement sophistication varies from individual price sensitivity to institutional vendor qualification and long-term service contracting.
- Utilities:Grid operators procuring distributed energy resources for virtual power plant aggregation. Duke Energy and Southern California Edison are qualifying bidirectional charger vendors through cybersecurity and interoperability testing, deploying hardware as behind-the-meter storage with frequency regulation dispatch contracts.
- Corporate Fleets:Commercial operators with total-cost-of-ownership modeling and sustainability mandates. Amazon and Walmart logistics divisions in the US are specifying DC fast chargers with vehicle-to-grid capability, capturing Inflation Reduction Act Section 30C credits and demand response revenue.
- Individual Consumers:Residential buyers prioritizing upfront cost and installation simplicity.
- Parking Management Companies:Commercial real estate operators with tenant amenity and revenue share objectives.
- Municipalities:Government procurement with domestic content and prevailing wage requirements.
Institutional procurement sophistication is highest among utilities. Individual consumers remain price-elastic and feature-sensitive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley anchors global bidirectional charger development, hosting Tesla's vehicle-to-home orchestration stack and Fermata Energy's grid aggregation software. Fleet operators in the San Francisco Bay Area are deploying vehicle-to-grid hardware under Pacific Gas & Electric demand response programs, compressing procurement cycles for IEEE 1547-certified systems.
United States
Fleet electrification mandates from Amazon and Walmart logistics divisions are accelerating DC fast charger procurement with vehicle-to-grid capability. The Inflation Reduction Act's Section 30C tax credits are restructuring capital deployment patterns, with bonus credits for domestic content sourcing shifting assembly operations to qualified facilities. California's SB 100 vehicle-grid integration requirements are creating standardized procurement templates across municipal and commercial fleets in Los Angeles and San Diego.
Germany
Homeowners in Bavaria and Baden-Württemberg are combining solar-plus-storage installations with bidirectional chargers under Bundesnetzagentur grid codes. The F-Gas Regulation constrains coolant selections in high-power thermal management systems, directly affecting product development cycles for liquid-cooled 350 kW systems. Siemens anchors European utility partnerships from its Munich base with grid-code-certified bidirectional platforms.
Japan
Tokyo and Osaka municipal procurement standards remain anchored to CHAdeMO legacy connector protocols, creating interoperability friction for CCS-equipped vehicles entering fleet rotations. METI pilots in Kansai are testing vehicle-to-grid aggregation models with Korea Electric Power Corporation counterparts. The densest cluster of standards development activity sits in Nagoya's automotive corridor.
South Korea
Seoul Capital Area fleet depots are deploying DC bidirectional infrastructure under Korea Electric Power Corporation demand response programs. Silicon carbide power electronics are prioritized for thermal efficiency in high-utilization assets. Daegu-Gyeongbuk hosts concentrated manufacturing of wide-bandgap semiconductor components for 350 kW commercial systems.
Bi Directional Electric Vehicle Charger Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the bidirectional charger value chain. The market structure fragments between integrated automotive OEMs controlling full vehicle-to-home stacks, industrial conglomerates anchoring utility partnerships, and modular specialists extending into fleet-aggregation services. Three archetypes dominate: ecosystem-locked platform owners, grid-code-certified infrastructure vendors, and software-defined energy aggregators. Competitive moves concentrate on strategic partnerships for utility qualification and geographic licensing of proprietary connector networks.
Within the ecosystem-locked tier, Tesla exemplifies vertical control over vehicle-to-home orchestration, while Siemens occupies a position as the European utility partnership anchor. Among modular specialists, Wallbox represents the residential-to-fleet extension archetype. These three names illustrate how vendor qualification criteria now center on IEEE 1547 certification, cybersecurity attestations from regulators like California's Air Resources Board, and interoperability testing through utility programs at Duke Energy and Southern California Edison.
| Leading Market Players |
|---|
| Delta Electronics |
| Enphase Energy |
| Tesla |
| Wallbox |
| Indra Renewable Technologies |
| ABB |
| Autel Energy |
| Fermata Energy |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
California's SB 100 vehicle-grid integration mandates gate both qualified supply and premium-tier pricing access, restricting vendor participation to IEEE 1547-certified and cybersecurity-attested hardware while compressing procurement cycles for compliant systems.
Pricing Analysis
Throughput-based pricing anchors commercial fleet contracts, where vehicle-to-grid revenue stacking potential determines willingness-to-pay. Pricing stratifies across premium certified tiers, standard utility-qualified units, and economy residential installations, with differentiation driven by cybersecurity certification level and silicon carbide power electronics integration. Cost compression in economy residential tiers intensifies because of copper and rare earth magnet volatility. Individual consumers exhibit highest price sensitivity, while utility procurement teams prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
IEEE 1547 and IEC 61850 certification requirements filter component sourcing to qualified semiconductor foundries and thermal management specialists. Manufacturing concentrates in Germany, South Korea, and the United States, with silicon carbide substrates and liquid cooling systems as critical inputs. Single-source vulnerability in wide-bandgap semiconductor supply creates structural risk for 350 kW commercial system production. Distribution runs through utility qualification programs and OEM fleet procurement channels rather than open market resale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide power module capacity constraints prop pricing power for qualified vendors, creating supply-constrained market dynamics that favor early certification investments and long-term offtake agreements.
For Market Incumbents: Hedge against silicon carbide supply concentration by securing multi-source semiconductor agreements and captive thermal engineering capacity. Incumbent vendors must accelerate IEEE 2030.5 protocol compliance to defend against modular specialists unbundling hardware from energy services. Vertical integration into wide-bandgap semiconductor assembly offers margin protection against foundry pricing power. For New Entrants and Emerging Players: Utility engineering review backlogs represent the most penetrable white-space, with grid interconnection queue congestion creating demand for expedited certification services. New entrants should target municipal fleet procurement in California under SB 100 mandates, where standardized templates reduce vendor qualification friction. A software-defined energy subscription model enables asset-light entry without capital-intensive manufacturing. For Investors and Strategic Acquirers: California Air Resources Board cybersecurity certification batch approvals are the leading indicator that vendor consolidation will accelerate. Long-term viability favors grid-code-certified platform owners with utility partnership density over pure hardware manufacturers. Investors should monitor FERC demand response tariff standardization as the inflection signal for distributed energy resource monetization scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | California Air Resources Board attestation unlocks utility procurement eligibility and premium pricing tiers. |
| Silicon Carbide Supply Agreement | Long-term offtake from Daegu-Gyeongbuk foundries secures thermal efficiency advantages in 350 kW systems. |
| Utility Partnership Program | Duke Energy and Southern California Edison qualification creates recurring revenue through grid aggregation contracts. |
| Software-Defined Energy Platform | Fermata Energy-style unbundling transforms hardware vendors into subscription-based grid service providers. |
| Domestic Content Assembly Shift | US Inflation Reduction Act Section 30C bonus credit capture requires qualified facility reconfiguration. |
Research Methodology
Independent corroboration across fleet procurement officers, utility planning engineers, and semiconductor supply specialists underwrites the qualitative findings, with secondary validation from FERC interconnection filings, EIA distributed resource databases, and California Air Resources Board certification registries. Bottom-up unit economics modeling triangulates against top-down infrastructure investment tracking.
Rate-of-change decomposition across the projection horizon segments volume by power tier, connector protocol, and grid interconnection standard, with CAGRs derived from installed base replacement cycles and fleet electrification mandates. Silicon carbide adoption curves and utility demand response program expansion serve as primary forecast inputs alongside Inflation Reduction Act credit utilization patterns.
Caveats apply where IEEE 2030.5 protocol finalization delays or F-Gas Regulation thermal management constraints could materially shift the outlook. A model refresh is warranted upon material change in federal vehicle-grid integration tariff standardization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.