
 India Electric Vehicle Charging Station Market | 2026-2036
India Electric Vehicle Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
India Electric Vehicle Charging Station Market Foresight
Skilled electrical technician shortages across tier-two and tier-three cities is unwinding deployment timelines for charging networks. Tata Power leverages its integrated generation-to-retail footprint to secure prime real estate for highway corridor installations. Servotech Power Systems specializes in domestic manufacturing of power electronics, reducing import dependency for rectifier modules. Magenta ChargeGrid competes through dense urban siting in Mumbai and Pune, where parking scarcity elevates location value.
An electric vehicle charging station is an electromechanical system that converts grid electricity into direct current or conditioned alternating current at specified voltage and amperage levels to replenish onboard battery storage. These installations incorporate power conditioning units, connector protocols, and network communication modules to enable safe, metered energy transfer for passenger and commercial electric vehicles. Fast charging deployments dominate capital allocation due to higher throughput revenue per socket, while battery swapping is gaining structural traction among commercial fleets where asset utilization rates justify standardized pack exchange. AC charging maintains volume leadership in residential installations where dwell times accommodate slower replenishment cycles.
The Ministry of Power, Bureau of Indian Standards, and Central Electricity Authority collectively shape market access through technical standards for connector compatibility, grid interconnection codes, and tariff notification frameworks. State-level nodal agencies in Gujarat, Tamil Nadu, and Telangana layer additional siting approvals and capital subsidy disbursal conditions that fragment execution timelines. Stakeholders must monitor evolving standards for vehicle-to-grid integration and dynamic tariff structures as these will determine which hardware configurations retain long-term asset viability.
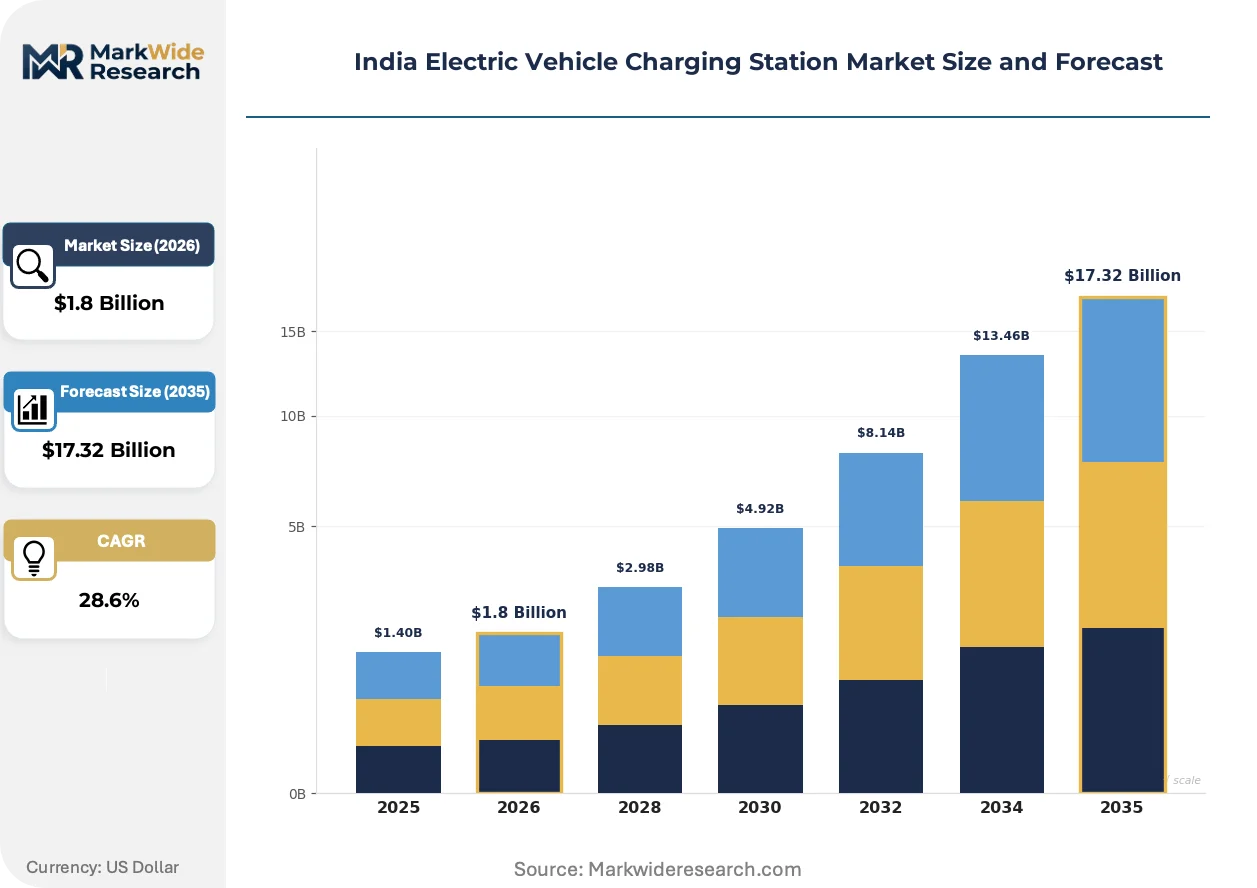
Market Dynamics
The Bureau of Indian Standards and Ministry of Power interoperability mandates are compressing hardware refresh cycles, forcing operators to pre-position capital for multi-standard connector configurations before revenue certainty materializes.
Growth Catalysts
- FAME-II subsidy extension:The Ministry of Heavy Industries incentive scheme for public charging infrastructure reduces payback periods for highway corridor installations.
- Commercial fleet electrification:E-commerce logistics operators and state transport undertakings are mandating EV procurement, creating guaranteed offtake for depot charging hubs.
- CEA grid interconnection codes:Standardized technical requirements for distribution network access are reducing utility negotiation timelines for new station approvals.
Market Restraints
- Power electronics import dependency:Rectifier modules and IGBT components concentrate in Chinese and Taiwanese supply chains, exposing margins to currency and tariff volatility.
- Real estate acquisition costs:Prime urban locations in Mumbai and Delhi NCR command rental premiums that consume 35-45% of station operating expenditure.
- Distribution transformer capacity:Rural and semi-urban substations lack headroom for 100+ kW fast charging loads, requiring upstream grid reinforcement.
Strategic Opportunities
- Tier-two city penetration:Nagpur, Indore, and Kochi exhibit EV registration growth without proportional charging infrastructure, creating first-mover location advantages.
- Battery swapping standardization:BIS draft protocols for commercial two-wheeler and three-wheeler pack interoperability enable asset-light network expansion.
- Vehicle-to-grid integration:Central Electricity Authority pilot programs for bi-directional charging create new revenue streams from grid ancillary services.
Industry Challenges
- Certified electrical technician scarcity:State-level electrical licensing requirements and limited vocational training throughput delay commissioning schedules in non-metro markets.
- Multi-agency approval fragmentation:Urban development authorities, fire departments, and distribution utilities operate non-harmonized inspection protocols that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electric Vehicle Charging Station Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Charging Station Type: Fast Charging, Slow Charging, Ultra-Fast Charging, Level 2 Charging Charging Mode: AC Charging, DC Charging, Wireless Charging, Battery Swapping End User: Private Owners, Commercial Fleets, Public Transport, Ride-Sharing Services Installation Site: Residential, Commercial, Highway, Urban Locations |
| Companies Covered | CHARGE+ZONE, EVRE, Servotech Power Systems, Volttic, Celectric Mobility, Tata Power, Magenta ChargeGrid, AAR Power Solution, Okaya Power Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electric Vehicle Charging Station Market Shifts & Advancements
Hardware architecture and service delivery models are diverging between premium fast-charging corridors and low-cost urban saturation strategies, with regulatory pressure on interoperability acting as the forcing function.
Charging hardware is bifurcating between liquid-cooled 350+ kW systems for highway commercial fleets and air-cooled 25-50 kW units for residential and workplace deployments. Fleet operators in the Delhi-Mumbai industrial corridor are specifying liquid-cooled configurations to minimize dwell time, while housing societies prioritize compact AC wallboxes that avoid distribution network upgrades. This split is compressing vendor R&D budgets across incompatible thermal management approaches.
BIS connector standardization mandates are phasing out proprietary charging protocols by 2027. The Bureau of Indian Standards adoption of CCS2 and Type 2 AC specifications forces incumbent operators to retrofit or retire early-deployed CHAdeMO infrastructure. Maharashtra and Karnataka state nodal agencies are accelerating compliance deadlines, compelling hardware replacement cycles ahead of asset depreciation schedules.
Fleet procurement contracts now specify charging-as-a-service rather than capital expenditure ownership. Logistics operators in Bengaluru and Hyderabad are outsourcing depot infrastructure to third-party operators who retain asset risk and optimize utilization across multiple fleet customers. This unbundling concentrates operational expertise with specialized providers while freeing fleet capital for vehicle acquisition.
India Electric Vehicle Charging Station Market Segmentation
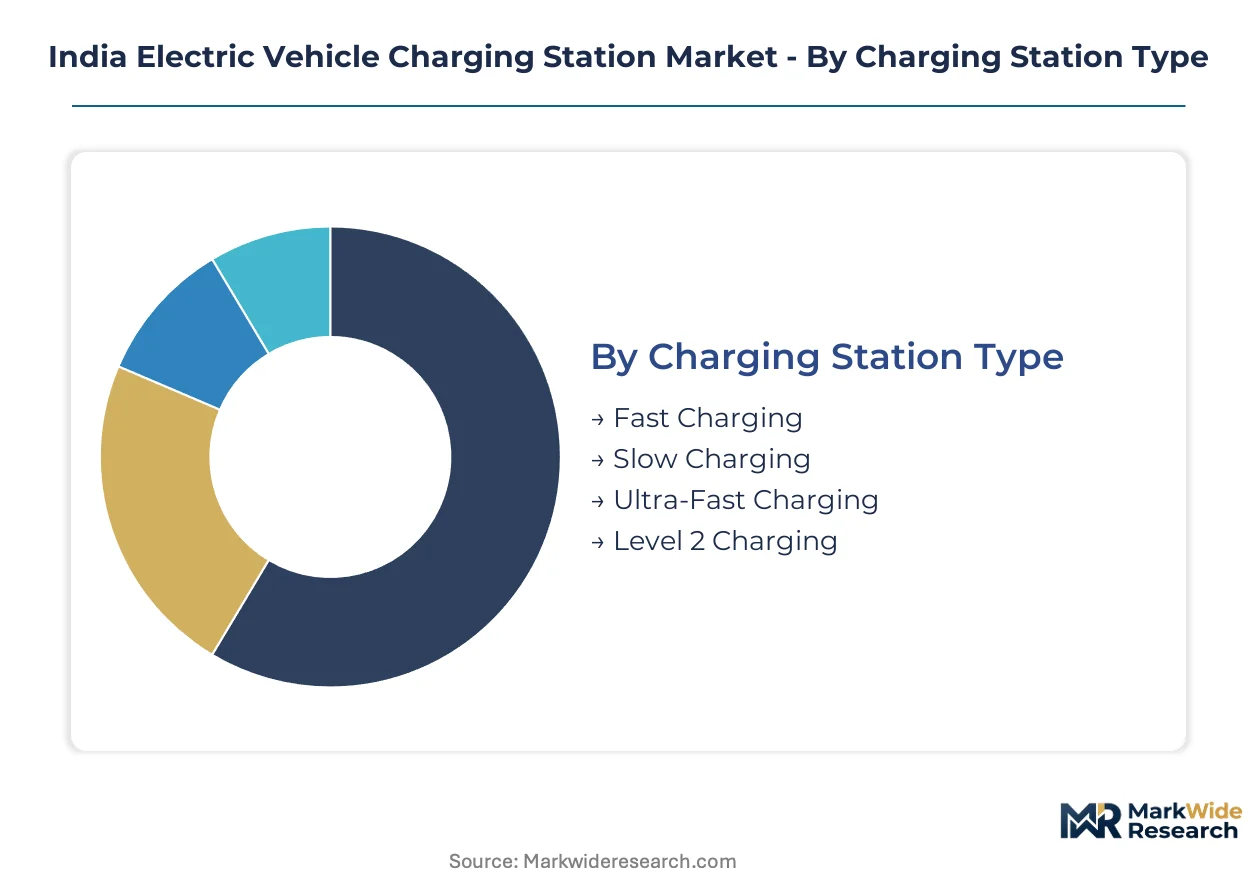
Charging station segmentation in India reveals how capital allocation splits between throughput-maximizing highway infrastructure and low-cost urban saturation. Hardware specifications and installation economics vary dramatically across these divides, forcing operators to choose between asset intensity and location coverage.
Charging Station Type:
Margin pools concentrate in ultra-fast and fast charging segments where higher capital deployment commands premium pricing per kWh delivered.
- Fast Charging:50-150 kW DC systems dominate highway corridor deployments along the Delhi-Mumbai and Chennai-Bengaluru expressways. Fleet operators at logistics hubs in Gurugram and Pune specify these configurations to minimize vehicle downtime during shift changes.
- Ultra-Fast Charging:350+ kW liquid-cooled installations serve long-haul commercial fleets where 15-minute replenishment cycles justify equipment costs three times standard fast charging units. Deployment concentrates at transport nagar clusters and industrial beltway junctions.
- Slow Charging:3-7 kW AC wallbox units for overnight residential replenishment in apartment complexes and individual housing societies.
- Level 2 Charging:11-22 kW AC systems for workplace parking installations where dwell times extend 6-8 hours.
The dominant share belongs to fast charging, while ultra-fast charging is closing the gap fastest as commercial fleet electrification accelerates.
Charging Mode:
Volume leadership sits with AC charging due to lower hardware costs and simpler grid interconnection requirements.
- AC Charging:Alternating current systems from 3 kW to 22 kW constitute the bulk of residential and workplace installations. Housing societies in Mumbai and Delhi NCR favor these units to avoid distribution transformer upgrades.
- DC Charging:Direct current fast charging at 50 kW and above captures the majority of public infrastructure capital. State transport undertakings in Maharashtra and Karnataka mandate DC configurations for depot charging hubs.
- Battery Swapping:Standardized pack exchange systems for two-wheeler and three-wheeler commercial fleets in Bengaluru and Hyderabad eliminate charging downtime entirely.
- Wireless Charging:Inductive pad systems for premium residential applications and automated guided vehicle fleets in controlled environments.
DC charging commands the largest installed base, though battery swapping is expanding most quickly in last-mile delivery segments.
End User:
Revenue stability varies sharply between guaranteed offtake from fleet contracts and discretionary usage from private owners.
- Commercial Fleets:E-commerce logistics operators and courier services with centralized depot charging requirements. Amazon, Flipkart, and Delhivery electrification mandates create contracted demand visibility for charging network operators.
- Public Transport:State transport corporation bus electrification programs in Delhi, Mumbai, and Bengaluru with dedicated depot infrastructure.
- Private Owners:Individual EV purchasers relying on residential charging with occasional public network usage.
- Ride-Sharing Services:Ola, Uber, and BluSmart driver-partners requiring rapid turnaround charging at urban hubs.
Commercial fleets anchor current revenue, while public transport is scaling fastest under state government procurement programs.
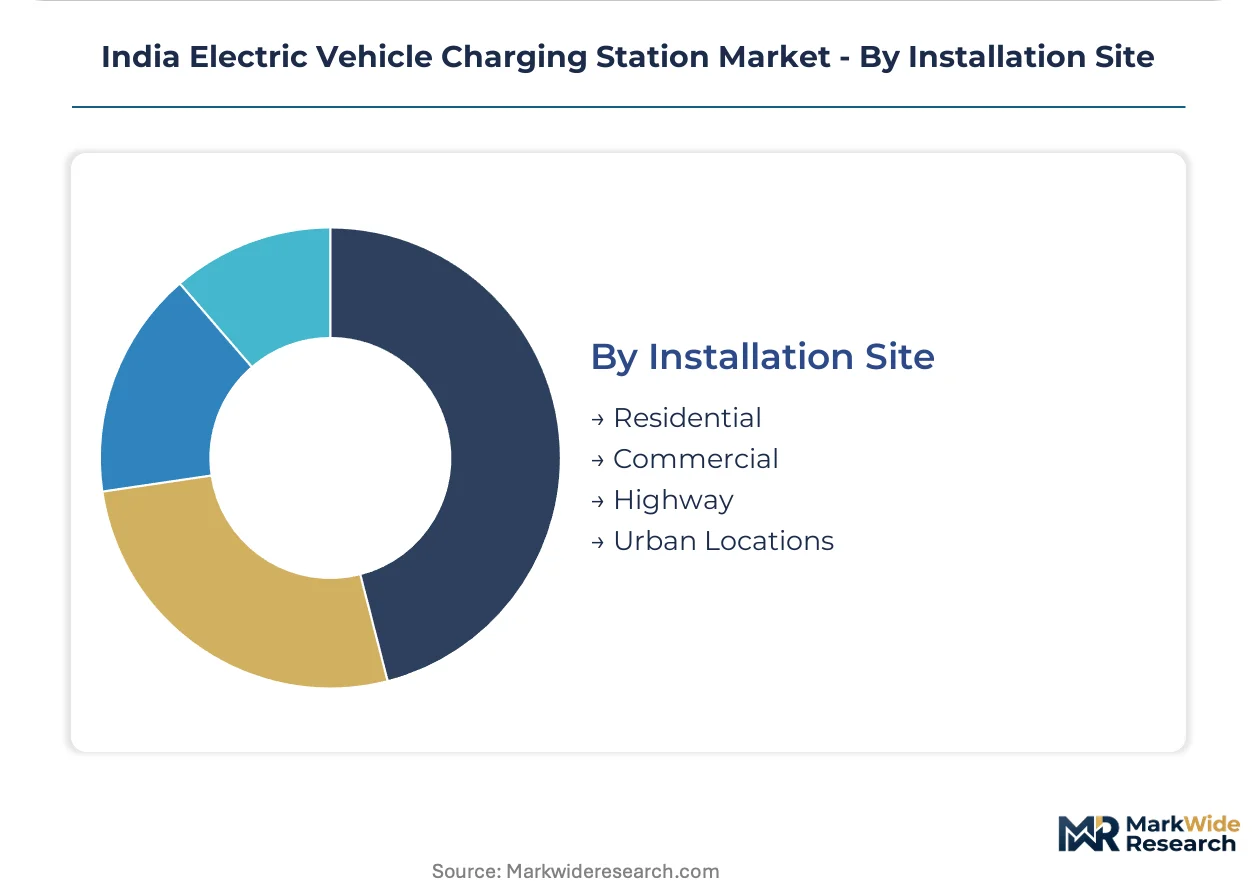
Installation Site:
Real estate economics drive divergent deployment strategies between premium highway locations and saturated urban pockets.
- Highway:Corridor installations along National Highways 48, 44, and 19 require land acquisition from state highway authorities and petroleum marketing company lease partnerships.
- Urban Locations:Dense siting in Mumbai, Pune, and Delhi NCR where parking scarcity elevates location value and utilization rates.
- Residential:Individual housing societies and apartment complex installations with load-sanctioned electrical connections.
- Commercial:Shopping malls, office complexes, and hospitality venues offering charging as an amenity service.
Urban locations hold the largest deployment share, while highway installations are gaining share fastest as intercity EV adoption rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Central Electricity Authority and Bureau of Indian Standards anchor deployment frameworks across India's most electrified states. State-level nodal agencies layer siting approvals and subsidy conditions that fragment execution timelines. Metropolitan corridors concentrate capital allocation while tier-two cities exhibit infrastructure gaps.
Maharashtra
Mumbai and Pune anchor the nation's densest charging network deployment. The state nodal agency accelerates BIS compliance deadlines for CCS2 retrofitting. Transport nagar clusters in Thane and Nashik host ultra-fast corridor installations serving long-haul commercial fleets.
Karnataka
Bengaluru's e-commerce logistics density drives depot charging hub construction. State transport undertaking mandates for bus electrification create guaranteed offtake at peripheral depots. Electronics manufacturing corridors in Hosur and Mysuru attract power electronics suppliers reducing import dependency.
Delhi-NCR
The Delhi Electric Vehicle Policy mandates public charging infrastructure ratios per vehicle registration. Gurugram's corporate park density supports workplace Level 2 installations. Noida and Faridabad industrial belts concentrate battery swapping pilots for last-mile delivery fleets.
Gujarat
Surat and Ahmedabad textile logistics operators specify charging-as-a-service contracts. Gujarat Energy Development Agency capital subsidies compress payback periods for highway corridor developers. Mundra port vicinity attracts equipment fabricators serving export markets.
Telangana
Hyderabad's pharmaceutical and IT corridor employee bases generate residential charging demand. State EV policy incentives target charging infrastructure in HITEC City and Gachibowli commercial districts. ORR industrial clusters host pilot vehicle-to-grid programs under CEA technical supervision.
India Electric Vehicle Charging Station Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the India Electric Vehicle Charging Station Market. Integrated utilities leverage generation-to-retail footprints for prime real estate access while domestic power electronics specialists reduce import exposure. Three archetypes dominate: utility-affiliated operators with captive grid relationships, indigenous component manufacturers, and pure-play charging network specialists. Competitive moves concentrate on strategic land leasing partnerships and hardware standardization pre-positioning ahead of BIS mandate deadlines.
Among utility-affiliated operators, Tata Power occupies a position exemplifying integrated infrastructure control. Servotech Power Systems and Magenta ChargeGrid represent contrasting archetypes: the former anchors domestic manufacturing capability in power electronics, while the latter exemplifies dense urban saturation strategies in parking-scarce metropolitan markets. These three players collectively illustrate how capital intensity, manufacturing depth, and location strategy segment competitive positioning.
| Leading Market Players |
|---|
| CHARGE+ZONE |
| EVRE |
| Servotech Power Systems |
| Volttic |
| Celectric Mobility |
| Tata Power |
| Magenta ChargeGrid |
| AAR Power Solution |
| Okaya Power Group |
| Others |
Supply & Pricing Matrix
Charging-as-a-service contracts with multi-year offtake guarantees from e-commerce logistics operators lock in both power electronics supply access and per-kWh pricing visibility across the Delhi-Mumbai industrial corridor. These structures insulate operators from spot volatility in rectifier module procurement while compressing margins for asset-light entrants lacking contracted demand.
Pricing Analysis
Mumbai and Delhi NCR command 40-60% per-kWh premiums over tier-two city installations due to real estate scarcity and higher grid demand charges. The dominant pricing structure stratifies across premium, standard, and economy tiers differentiated by charging speed and location convenience. Cost compression in the economy tier intensifies because state transport undertakings negotiate volume-based tariffs for depot charging hubs. Fleet operators exhibit lowest price sensitivity due to guaranteed offtake contracts, while private owners at public stations demonstrate highest sensitivity to per-session pricing.
Supply Chain Analysis
Taiwan Strait shipping lanes for IGBT modules and semiconductor components expose Indian charging hardware manufacturers to 6-8 week lead time volatility during peak demand cycles. Power electronics sourcing draws from China, Taiwan, and South Korea for rectifier modules, cooling systems, and controller chipsets. Tariff exposure on Chinese electrical components feeds into hardware cost structures. Distribution runs through domestic system integrators who assemble imported subcomponents at facilities in Noida and Pune before final site commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified electrical technician throughput constraints across tier-two and tier-three markets create a binding bottleneck that determines which operators can execute on contracted deployment timelines.
For Market Incumbents: Consolidate technician training pipelines through partnerships with Industrial Training Institutes in Maharashtra and Karnataka to preempt commissioning delays. Secure backward integration into power electronics assembly to reduce exposure to Chinese tariff volatility. Pre-position CCS2-compliant hardware ahead of BIS mandate deadlines to capture stranded CHAdeMO retrofit demand from smaller competitors lacking capital reserves. For New Entrants and Emerging Players: Anchor in battery swapping infrastructure for commercial two-wheeler and three-wheeler fleets in Bengaluru and Hyderabad where BIS standardization creates first-mover protocol advantages. Target underpenetrated tier-two cities including Nagpur, Indore, and Kochi where EV registration growth outpaces charging infrastructure deployment by 3:1 ratios. Pursue land-banking partnerships with petroleum marketing companies at highway corridor locations before prime sites saturate. For Investors and Strategic Acquirers: Domestic power electronics specialists with captive rectifier module manufacturing represent the highest-conviction acquisition archetype given import substitution tailwinds. Long-term viability hinges on operators' ability to monetize vehicle-to-grid ancillary services as CEA pilot programs scale. Monitor BIS compliance deadline acceleration in Maharashtra and Karnataka as inflection indicators for hardware replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| CCS2 Hardware Pre-Positioning | BIS mandate deadlines in Maharashtra and Karnataka compress retrofit windows for early movers. |
| Technician Training Pipeline Expansion | ITI partnerships in tier-two cities unlock execution capacity that competitors cannot replicate. |
| Battery Swapping Protocol Standardization | BIS draft specifications for commercial two-wheeler packs enable asset-light network scaling. |
| Vehicle-to-Grid Pilot Participation | CEA bi-directional charging programs create new revenue streams from grid ancillary services. |
| Petroleum Marketing Company Land Leasing | Highway corridor site control secures intercity EV adoption capture before location saturation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and state nodal agency procurement records to establish baseline market sizing. Primary interviews with charging network operators, power electronics manufacturers, distribution utility planning officers, and commercial fleet procurement managers informed operational assumptions. Secondary validation drew from CEA grid interconnection codes, BIS technical standards, FAME-II subsidy disbursement data, and state EV policy documents. Bottom-up station deployment counts triangulate against top-down infrastructure investment flows.
Segmentation dimensions modeled span charging station type, charging mode, end user category, and installation site geography across the projection horizon. Analytical framework incorporates hardware cost curves, real estate rental indices, and grid interconnection timelines to derive deployment trajectories. CAGRs emerge from compounded annual installation rates adjusted for regulatory milestone impacts. Forecast inputs include commercial fleet electrification mandates from e-commerce operators and state transport undertaking procurement schedules.
Material uncertainties — BIS standardization timeline revisions, FAME-II subsidy extensions, and distribution transformer capacity upgrades — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory coherence across central and state agencies. Practitioners should keep alternative scenarios live as CEA vehicle-to-grid commercialization pathways and BIS connector mandate enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Europe Electric Vehicle Chargers Market
Electric Vehicle Charging
Germany EV Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
Wireless Charging Market
Electric Vehicle Charging
Norway Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
AC Electric Vehicle Charging Station Market
Electric Vehicle Charging
EV Charge Management Software Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Connector Market
Electric Vehicle Charging
South Korea Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Heavy-Duty Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Bidirectional EV Charger and V2X Grid Integration Test Systems Market
Electric Vehicle Charging
EV Charging Infrastructure Market
Electric Vehicle Charging
EV Charging Networks Market
Electric Vehicle Charging
Electric Vehicle Charging Station Raw Materials Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market