
 Portable EV Charger Market | 2026-2036
Portable EV Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Portable EV Charger Market Analytics
Silicon carbide is expanding its footprint in portable EV charger power electronics, displacing traditional silicon IGBTs in high-frequency inverter stages and cutting thermal management costs by enabling smaller heat sinks and lighter enclosures. Blink Charging Co. leverages its established North American charging network to anchor fleet partnerships for mobile deployment units. FreeWire Technologies, Inc. specializes in battery-integrated charger architecture that eliminates grid-upgrade dependencies at commercial sites. Shenzhen SETEC Power Co., Ltd. dominates manufacturing scale for AC-DC conversion modules, sustaining cost advantages across Level 2 and DC fast product lines.
A portable EV charger is a self-contained or transportable power conversion system designed to deliver controlled electrical energy to electric vehicle battery packs, typically incorporating power ratings from 1.4 kW (Level 1, 120V AC input) through 19.2 kW (Level 2, 240V AC) and up to 350 kW for DC fast variants with direct current output bypassing onboard rectifiers. Its primary commercial purpose is to extend charging accessibility beyond fixed infrastructure, serving fleet depots, roadside assistance providers, and residential users lacking permanent installation capacity. Level 2 Charger units command the largest revenue pool today due to their balance of deployment cost and charging speed for commercial fleets, while DC Fast Charger configurations represent the fastest-growing product type as battery-electric trucks and delivery vans enter service with larger pack capacities requiring rapid turnaround. Smart Charging technology sits at the margin center, enabling load scheduling, demand-response integration, and software-based tariff optimization that differentiates premium hardware from commodity plug-and-play alternatives.
The US Department of Transportation's National Electric Vehicle Infrastructure program and the EPA's vehicle emissions standards jointly shape product certification requirements and procurement incentives for portable charging equipment deployed along federal highway corridors. In Europe, the EU Green Deal transport targets and CE marking under the Low Voltage Directive establish harmonized safety and efficiency benchmarks that manufacturers must satisfy for market access across member states. China's MIIT dual carbon goals and GB standards for conductive charging interfaces create a separate compliance pathway that influences design choices for exporters targeting domestic fleet operators. Stakeholders must monitor how evolving grid interconnection rules in multiple jurisdictions treat mobile battery-integrated chargers versus fixed infrastructure, as this classification determines eligibility for utility rebates and network access tariffs that directly alter unit economics.
Market Dynamics
Fleet electrification timelines are compressing procurement cycles for mobile charging infrastructure, forcing manufacturers to prioritize battery-integrated architectures that bypass utility interconnection delays and enable rapid deployment at logistics depots lacking permanent grid capacity.
Growth Catalysts
- EU Green Deal transport mandates:Binding vehicle emissions standards under the EU Green Deal are compelling commercial fleet operators to acquire portable charging assets as bridge infrastructure during depot electrification.
- Silicon carbide power electronics:SiC MOSFET adoption in high-frequency inverter stages is cutting thermal management costs and enabling lighter, more efficient charger enclosures for roadside assistance applications.
- Last-mile logistics electrification:Dense urban delivery networks in Germany are generating concentrated demand for on-demand EV power solutions that fixed infrastructure cannot match.
Market Restraints
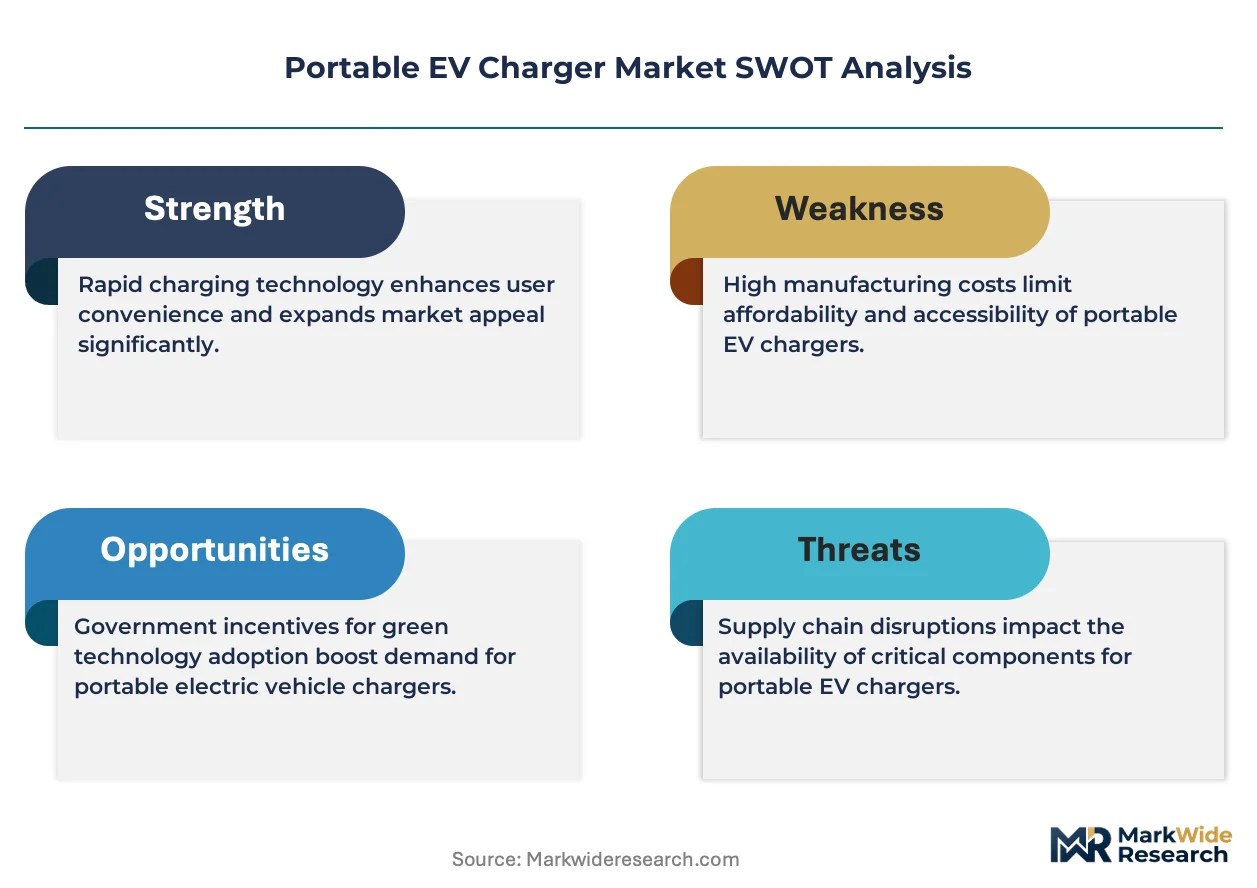
- AC-DC conversion module supply concentration:Manufacturing scale advantages for Chinese module suppliers create import dependency and tariff exposure for North American and European charger assemblers.
- Grid interconnection classification ambiguity:Utility rebate eligibility rules that treat mobile battery-integrated chargers differently from fixed infrastructure are distorting unit economics across multiple jurisdictions.
- Copper and rare-earth magnet cost volatility:Input price swings for power magnetics and thermal conductors are compressing margin buffers in mid-tier product lines.
Strategic Opportunities
- CE marking harmonization:The Low Voltage Directive's unified safety benchmarks are lowering cross-border compliance costs for manufacturers targeting pan-European fleet contracts.
- Rural corridor deployment:Federal highway corridor programs in the United States are creating procurement channels for mobile units serving intercity electric truck routes lacking permanent fast-charging coverage.
- Smart charging software convergence:Integration of load scheduling algorithms with demand-response platforms is opening premium pricing tiers for fleet management contracts.
Industry Challenges
- Power electronics engineering talent scarcity:Shortages of SiC inverter design specialists and thermal simulation engineers are extending product development cycles for high-frequency architectures.
- Multi-jurisdiction certification timelines:Divergent testing requirements between EPA vehicle emissions-adjacent equipment standards, CE marking procedures, and China's GB interface standards are fragmenting product variant strategies.
- Legacy fleet management system integration:API incompatibility between proprietary charger networks and incumbent telematics platforms is forcing costly middleware development for enterprise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable EV Charger Market |
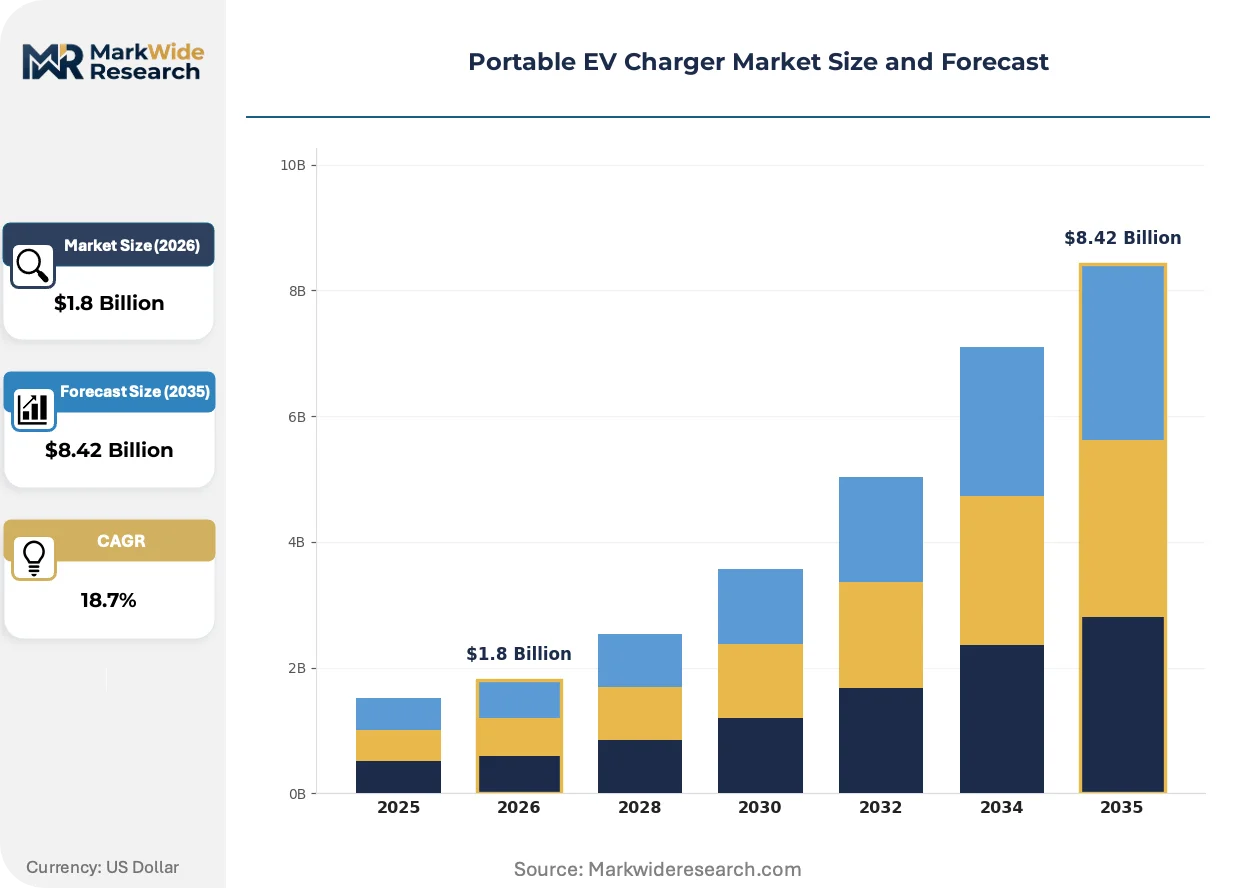
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Charger, Level 2 Charger, DC Fast Charger, Mobile Charger Technology: Wireless Charging, Smart Charging, Plug-and-Play, Solar Powered End User: Residential Users, Fleet Operators, Commercial Users, Government Agencies Installation: Wall-Mounted, Portable, Stationary, Integrated Solutions |
| Companies Covered | Blink Charging Co., FreeWire Technologies, Inc., ZipCharge Limited, Shenzhen SETEC Power Co., Ltd., SparkCharge, Guangzhou Electway Technology Co., Ltd, Evteq Mobility Private Limited, JTM Power Limited, Heliox Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable EV Charger Market Evolving Landscape
Power semiconductor material transitions and software-defined charging architectures are restructuring competitive differentiation, shifting value capture from hardware specifications toward energy management intelligence and grid-interaction capabilities.
Silicon carbide MOSFETs are replacing silicon IGBTs in high-frequency inverter stages of portable DC fast chargers. Fleet operators with battery-electric truck deployments are adopting SiC-based units to reduce thermal footprint and enable air-cooled designs that eliminate liquid cooling maintenance. This transition is decentralizing charging infrastructure deployment authority from utility-controlled interconnection queues to fleet operators who can relocate battery-integrated assets based on route optimization needs.
The EPA's vehicle emissions standards and NHTSA fuel economy regulations are tightening in parallel, creating overlapping compliance obligations for commercial vehicle manufacturers. These dual pressures are accelerating OEM partnerships with portable charger providers to ensure charging availability during customer fleet transitions. Heavy-duty electric truck segments face the most acute infrastructure gaps and are driving specification requirements for 350 kW mobile units.
Leasing and subscription models for mobile charging assets are displacing outright purchase arrangements among mid-size fleet operators. Third-party logistics providers and regional delivery cooperatives are adopting usage-based contracts that bundle hardware, software, and maintenance. This shift is most pronounced in Germany, where automaker-backed charging networks are white-labeling portable units to logistics customers seeking operational flexibility without capital commitment.
Portable EV Charger Market Segmentation
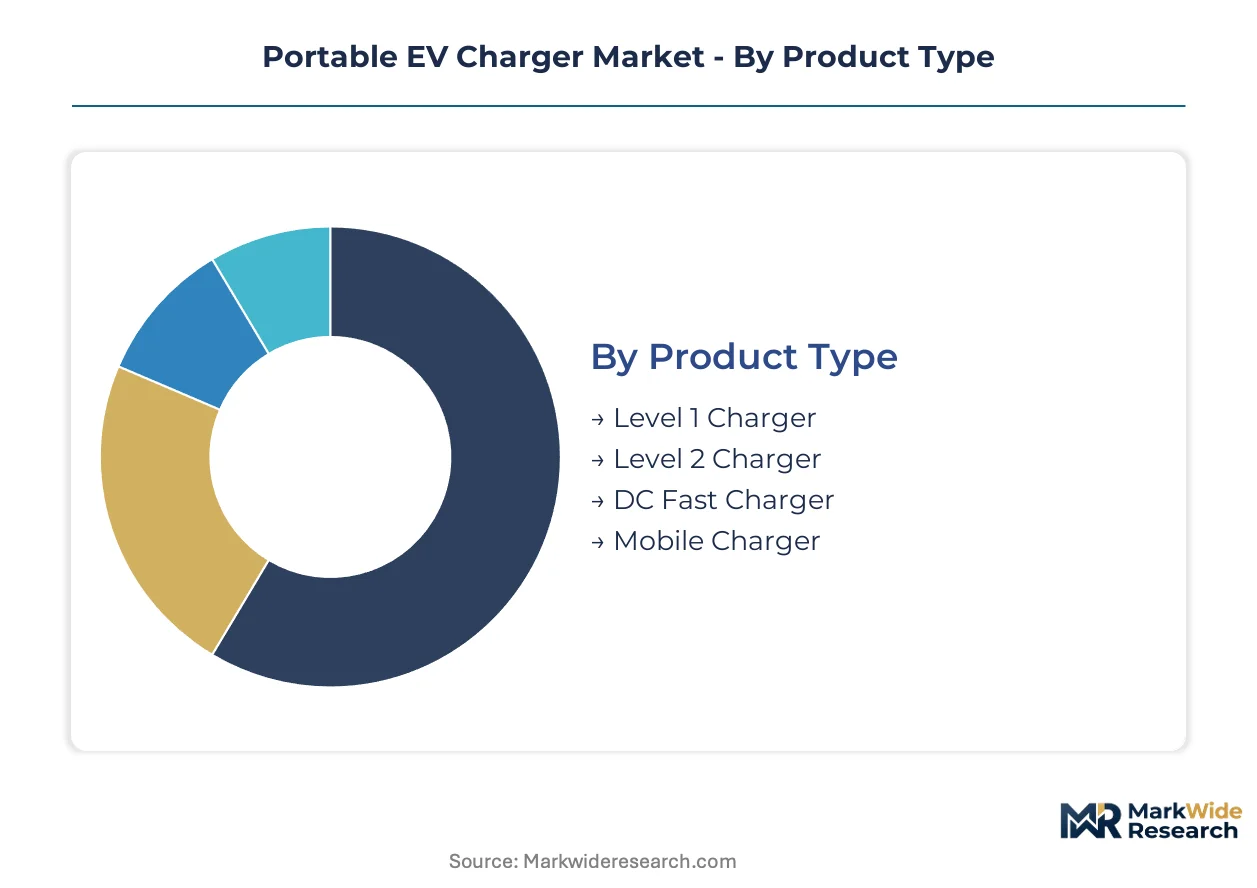
Segmentation in portable EV chargers reveals how procurement authority splits between fleet operators seeking deployment flexibility and residential users prioritizing cost containment. Technology choices cascade from these divergent requirements, with power electronics specifications and software integration depth varying sharply across buyer categories.
Product Type:
Power output ratings dominate fleet procurement decisions, determining whether units serve overnight depot charging or rapid roadside turnaround.
- Level 1 Charger:Operates at 1.4 kW from 120V AC residential circuits, delivering 3-5 miles of range per hour. Residential users in Germany and France lacking panel capacity drive residual demand for these entry-level units.
- Level 2 Charger:Delivers 3.3-19.2 kW via 240V AC input, balancing acquisition cost against charging speed for commercial fleet depots. Logistics operators across the United States concentrate procurement here for medium-duty electric van fleets.
- DC Fast Charger:Bypasses onboard rectifiers to feed 50-350 kW direct current, slashing heavy-duty truck turnaround times. Battery-electric truck deployments along US federal highway corridors are accelerating specification requirements for mobile 350 kW units.
- Mobile Charger:Battery-integrated architectures eliminate grid interconnection delays, enabling rapid relocation between logistics sites. Roadside assistance providers and third-party logistics operators in dense urban European markets favor these for route-optimization flexibility.
Level 2 Charger leads on scale; DC Fast Charger leads on momentum.
Technology:
Software capabilities now differentiate premium hardware from commodity alternatives, with load management intelligence commanding pricing power in fleet contracts.
- Wireless Charging:Inductive power transfer eliminates connector wear but sacrifices efficiency, limiting deployment to premium residential and controlled fleet environments. Automaker-backed pilot programs in Germany are testing standardized ground pad integration for automated logistics vehicles.
- Smart Charging:Load scheduling algorithms and demand-response integration enable tariff optimization and grid stabilization services. Fleet management platforms in California and Texas are mandating API compatibility for utility rebate eligibility.
- Plug-and-Play:Dumb hardware without network connectivity dominates price-sensitive residential procurement. These units face margin compression as silicon carbide power electronics raise performance floors across all tiers.
- Solar Powered:DC-coupled photovoltaic integration appeals to off-grid and remote deployment scenarios. Rural corridor programs in Australia and select US mountain states are evaluating these for intercity electric truck routes lacking grid infrastructure.
Smart Charging commands premium pricing; Solar Powered expands most quickly in niche applications.
End User:
Procurement scale and technical sophistication diverge sharply between individual consumers and enterprise fleet operators.
- Residential Users:Individual consumers prioritize acquisition cost and plug compatibility over advanced features. Single-family homeowners in the United States lacking garage electrical upgrades drive steady Level 1 and entry Level 2 volume.
- Fleet Operators:Logistics companies and delivery services demand battery-integrated mobility, software-defined load management, and rapid deployment without utility interconnection queues. German last-mile electrification timelines are compressing procurement cycles for these buyers.
- Commercial Users:Retail properties, workplaces, and multi-unit dwellings seek charging amenities without permanent infrastructure commitment. Property managers in France and the Netherlands favor portable units for tenant flexibility.
- Government Agencies:Municipal and federal procurement channels prioritize domestic content compliance and NEVI program certification for highway corridor deployment. US Department of Transportation specifications are shaping product development roadmaps for this segment.
Fleet Operators lead on scale; Government Agencies lead on momentum through federal procurement mandates.
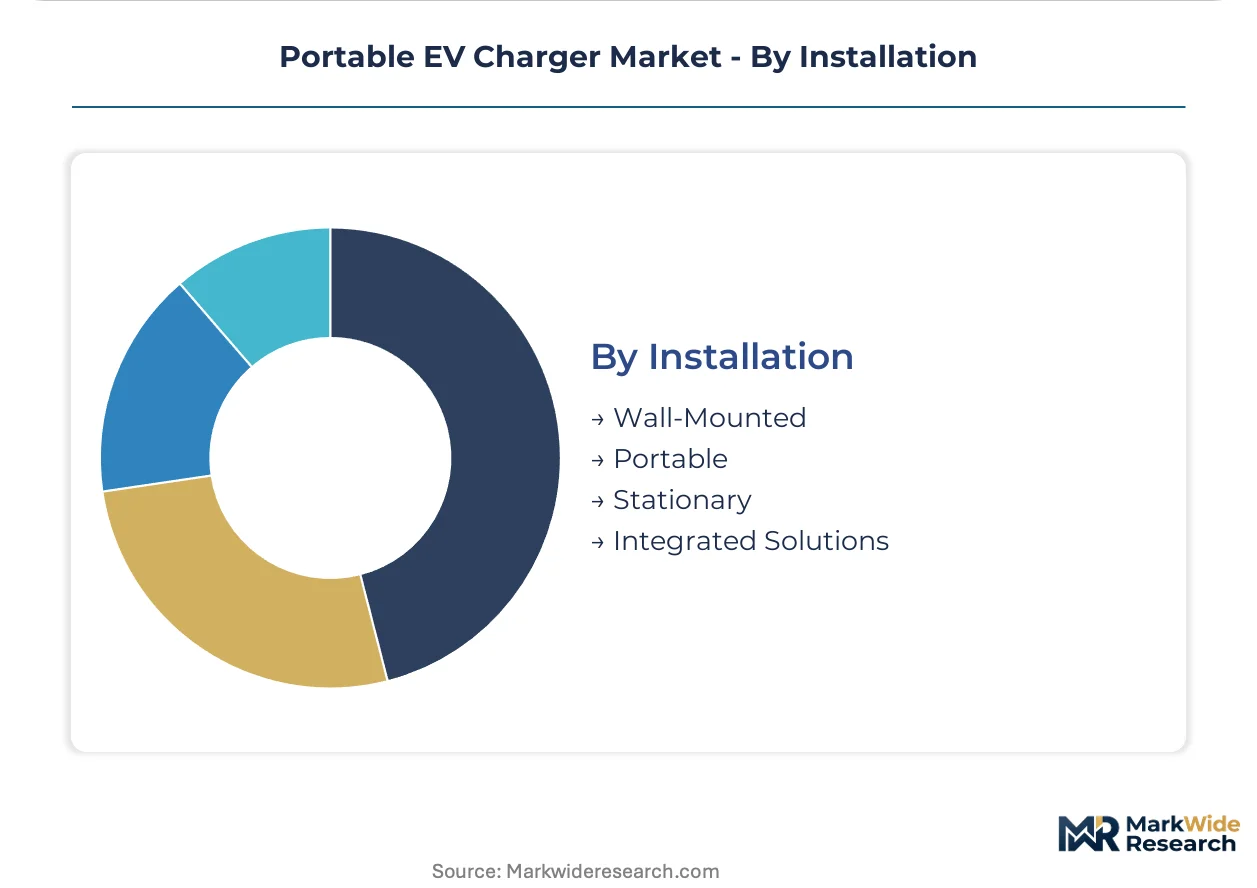
Installation:
Physical mounting configuration determines relocation frequency and grid dependency, directly impacting total cost of ownership calculations.
- Wall-Mounted:Fixed bracket installation suits semi-permanent depot assignments with predictable vehicle routing. Fleet operators in established logistics hubs favor these for cost efficiency over fully mobile alternatives.
- Portable:Self-contained units with integrated cabling and storage enable rapid repositioning between sites. Roadside assistance providers and temporary event power services in Germany and the United Kingdom concentrate demand here.
- Stationary:Permanent foundation-mounted systems approximate fixed infrastructure functionality. These capture minimal share in portable-specific procurement but serve bridge infrastructure roles during depot construction delays.
- Integrated Solutions:Battery-integrated chargers with solar coupling or generator backup address complete off-grid requirements. Remote mining operations and disaster response agencies in Australia and Canada are evaluating these for critical fleet resilience.
Portable leads on scale; Integrated Solutions lead on momentum in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's dense automaker-backed charging networks and last-mile logistics clusters anchor portable EV charger deployment intensity. Fleet operators across multiple jurisdictions are accelerating procurement as electrification timelines compress and depot grid capacity lags vehicle rollout schedules.
United States
Federal highway corridor programs and heavy-duty electric truck deployments drive concentrated demand for mobile DC fast charging units. The US Department of Transportation's National Electric Vehicle Infrastructure program shapes product certification requirements and procurement incentives for equipment deployed along interstate routes. Texas and California logistics hubs are generating the densest fleet operator procurement activity for battery-integrated architectures.
Germany
EU Green Deal transport decarbonization mandates and binding vehicle emissions standards compel commercial fleet electrification on compressed timelines. CE marking under the Low Voltage Directive establishes harmonized safety benchmarks that manufacturers must satisfy for cross-border market access. The Rhine-Ruhr and Stuttgart metropolitan logistics corridors are seeing acute demand concentration for on-demand EV power solutions that bypass fixed infrastructure gaps.
China
Domestic fleet electrification scale and export manufacturing concentration for AC-DC conversion modules shape dual market dynamics. MIIT dual carbon goals and GB standards for conductive charging interfaces create compliance pathways that influence design choices for domestic and export-oriented producers. The Yangtze River Delta manufacturing cluster sustains cost advantages across Level 2 and DC fast product lines.
United Kingdom
Roadside assistance provider demand and temporary event power services favor rapid-relocation portable units over permanent installations. Post-Brexit regulatory alignment with EU safety benchmarks under retained CE marking procedures maintains market access continuity for continental suppliers. The Midlands logistics corridor and Greater London last-mile delivery networks are compressing procurement cycles for mobile charging assets.
France
Commercial property managers and multi-unit dwelling operators seek charging amenities without permanent infrastructure commitment. The country's national transport decarbonization framework tightens vehicle emissions standards for urban delivery fleets. The Île-de-France logistics basin and Lyon-Grenoble industrial corridor are generating procurement concentration for tenant-flexible portable deployment models.
Portable EV Charger Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to bypass utility interconnection delays and accelerate fleet deployment timelines. The vendor base organizes into three tiers: established charging network operators with fleet anchoring capabilities, battery-integrated architecture specialists, and manufacturing-scale component suppliers. Competitive moves concentrate on M&A to secure software integration capabilities and geographic expansion to capture federal procurement mandates.
Within the network-operator tier, Blink Charging Co. and FreeWire Technologies, Inc. exemplify divergent strategic positioning—one leveraging existing infrastructure relationships, the other pioneering battery-integrated architectures that eliminate grid-upgrade dependencies. Shenzhen SETEC Power Co., Ltd. occupies a manufacturing-scale position, sustaining cost advantages across conversion module supply. These three entities represent the archetypal competitive vectors: fleet partnership anchoring, technical architecture differentiation, and component-scale manufacturing efficiency.
| Leading Market Players |
|---|
| Blink Charging Co. |
| FreeWire Technologies, Inc. |
| ZipCharge Limited |
| Shenzhen SETEC Power Co., Ltd. |
| SparkCharge |
| Guangzhou Electway Technology Co., Ltd |
| Evteq Mobility Private Limited |
| JTM Power Limited |
| Heliox Energy |
| Others |
Value Network & Pricing Analysis
Fleet operator procurement concentration in Germany and the United States anchors contract-based long-term offtake pricing for battery-integrated portable chargers, with subscription bundling of hardware and software services displacing per-unit transactional models among mid-size logistics providers.
Pricing Analysis
Copper and rare-earth magnet cost volatility feeds directly into power magnetics pricing, compressing margin buffers in mid-tier Level 2 product lines. Three-tier pricing structure across premium, standard, and economy levels separates SiC-enabled smart charging units with API integration from basic plug-and-play alternatives. Cost compression in standard-tier AC-DC modules is intensifying because Chinese manufacturing scale advantages create import dependency exposure. Residential users in France and the United States show highest price sensitivity, while German fleet operators prioritize deployment speed over acquisition cost.
Supply Chain Analysis
Direct-to-fleet channels handle hyperscale buyer demand for mobile DC fast units, bypassing traditional distributor markups. Manufacturing concentrates in China for AC-DC conversion modules, Germany for power electronics engineering, and the United States for final assembly serving federal procurement mandates. Silicon carbide wafers, copper busbars, and rare-earth permanent magnets constitute critical input dependencies. Single-source vulnerability in Chinese module supply creates tariff exposure for North American and European charger assemblers. Distribution runs through automaker-backed charging networks in Germany and certified NEVI program vendors in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EU Green Deal transport mandates and US NEVI program certification timelines creates geographic-arbitrage opportunities for manufacturers with dual-compliance capabilities, exploiting faster approval pathways in one jurisdiction to fund penetration in the other.
For Market Incumbents: Hedge against SiC inverter design talent scarcity by acquiring thermal simulation engineering teams in Germany and establishing captive training pipelines with technical universities. Battery-integrated architecture specialists like FreeWire Technologies threaten established network operators by eliminating utility interconnection queues entirely. Priority levers include backward integration into power module assembly and CE marking pre-certification stockpiling for pan-European fleet contracts. For New Entrants and Emerging Players: Launch via white-label partnerships with third-party logistics cooperatives seeking operational flexibility without capital commitment, the most penetrable white-space in Germany's last-mile electrification timeline. Rural US federal highway corridors lacking permanent fast-charging coverage offer secondary entry points. Solar-powered integrated solutions for remote mining and disaster response agencies in Australia and Canada represent a defensible niche with limited incumbent attention. For Investors and Strategic Acquirers: Charging network operators with established fleet anchoring relationships are the most active acquirer in this space, seeking software integration capabilities to differentiate from commodity hardware. Long-term viability hinges on convergence between vehicle electrification timelines and grid interconnection rule clarity. Acquisition target archetype: battery-integrated architecture specialists with utility-scale deployment track records. Monitor EPA vehicle emissions standard tightening velocity as inflection indicator for heavy-duty electric truck charging demand.| Strategic Initiative | Industry Significance |
|---|---|
| SiC Power Electronics Transition | Silicon carbide MOSFET adoption cuts thermal management costs and enables air-cooled portable DC fast charger designs. |
| Battery-Integrated Architecture Scale-Up | FreeWire Technologies' mobile units eliminate grid-upgrade dependencies at commercial logistics depots lacking permanent capacity. |
| Smart Charging Software Convergence | Load scheduling algorithms with demand-response integration open premium pricing tiers for California and Texas fleet contracts. |
| CE Marking Harmonization Investment | Low Voltage Directive unified safety benchmarks lower cross-border compliance costs for pan-European manufacturer market access. |
| Federal Highway Corridor Partnership | NEVI program certification creates procurement channels for mobile units serving US interstate electric truck routes. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, charging network procurement leads, power electronics engineering heads, and utility interconnection planners with secondary validation from SEC filings of listed charging equipment manufacturers, US Department of Transportation NEVI program disclosures, EU Green Deal transport implementation reports, and MIIT dual carbon goal progress assessments. Bottom-up unit shipment modeling by product type and top-down market sizing by end-use segment were cross-referenced for convergence.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeled across power output ratings, charging technology tiers, end-user procurement authority, and installation mobility configuration. CAGRs were derived from fitted growth curves incorporating fleet electrification timeline compression, silicon carbide cost reduction trajectories, and grid interconnection queue duration estimates as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper and rare-earth price volatility scenarios or abrupt grid interconnection rule reclassifications. Outputs reflect documented assumptions regarding EU vehicle emissions standard enforcement velocity and US federal procurement mandate expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Charging As a Service Market
Electric Vehicle Charging
Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Supply Equipment (EVSE) Market
Electric Vehicle Charging
India Electric Vehicle Charging Station Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Electric Vehicle Charging Pile Cables Market
Electric Vehicle Charging
Public EV Charging Pile Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station and Pile Operation and Management Market
Electric Vehicle Charging
Denmark Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Smart Charge Controller Market
Electric Vehicle Charging
E-Bike Charging Station Market
Electric Vehicle Charging
EV Charging Facilities Market
Electric Vehicle Charging
Airport Charging Stations Market
Electric Vehicle Charging
Second Life Electric Vehicle Battery Market
Electric Vehicle Charging
EV Charge Controller Market
Electric Vehicle Charging
Electric Vehicle Charging Plugs Market