
 Asia Pacific Electric Vehicle Charging Equipment Market | 2026-2036
Asia Pacific Electric Vehicle Charging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Electric Vehicle Charging Equipment Market Insights
High-power silicon carbide (SiC) module integration is rewriting how DC fast charging hardware achieves thermal efficiency and power density. Delta Electronics leverages its semiconductor foundry partnerships to control upstream component costs. BYD anchors its position through captive battery and power electronics manufacturing. ABB competes on grid-integration software that manages bi-directional energy flows between chargers and utility networks.
Electric vehicle charging equipment comprises power conversion systems, cable assemblies, and communication modules engineered to deliver controlled electrical energy from grid infrastructure to onboard vehicle batteries, typically operating across voltage ranges from 120V AC residential levels to 800V+ DC fast-charging architectures. The primary commercial purpose centers on reducing charge duration while protecting battery cell chemistry through precise thermal management and handshake protocols. DC Fast Chargers dominate capital deployment in highway corridor and fleet depot applications where throughput economics justify premium hardware costs. Wireless Chargers occupy a nascent but structurally distinct margin pool focused on luxury residential and automated parking integrations. Residential installations remain the highest-volume segment though per-unit economics trail commercial and public station deployments.
China's MIIT enforces GB/T charging standards that shape connector geometry and communication protocols for all hardware sold domestically, while India's BIS certification requirements for electrical safety create compliance barriers for imported equipment. Japan's METI subsidizes CHAdeMO-compatible ultra-fast charging nodes along expressway corridors, directing infrastructure investment toward specific technical specifications. Stakeholders must monitor how interoperability mandates evolve across these three regulatory regimes to determine hardware platform standardization bets.
Market Dynamics
High-power charging hardware economics are restructuring around silicon carbide semiconductor costs and grid-interconnection approval timelines, with procurement decisions increasingly driven by total cost of ownership calculations spanning equipment lifespan and demand charge optimization rather than upfront capital expenditure alone.
Growth Catalysts
- Fleet depot electrification mandates:Commercial vehicle operators across India and China face binding zero-emission deadlines under state-level clean air regulations, forcing capital deployment into DC fast charging infrastructure at scale.
- MIIT GB/T standard harmonization:China's unified connector and communication protocols eliminate interoperability friction, reducing hardware platform fragmentation and accelerating supplier production ramp rates.
- Silicon carbide module cost curves:Power semiconductor foundries in Taiwan and South Korea are expanding 6-inch and 8-inch SiC wafer capacity, compressing bill-of-material costs for 350kW+ charging systems.
Market Restraints
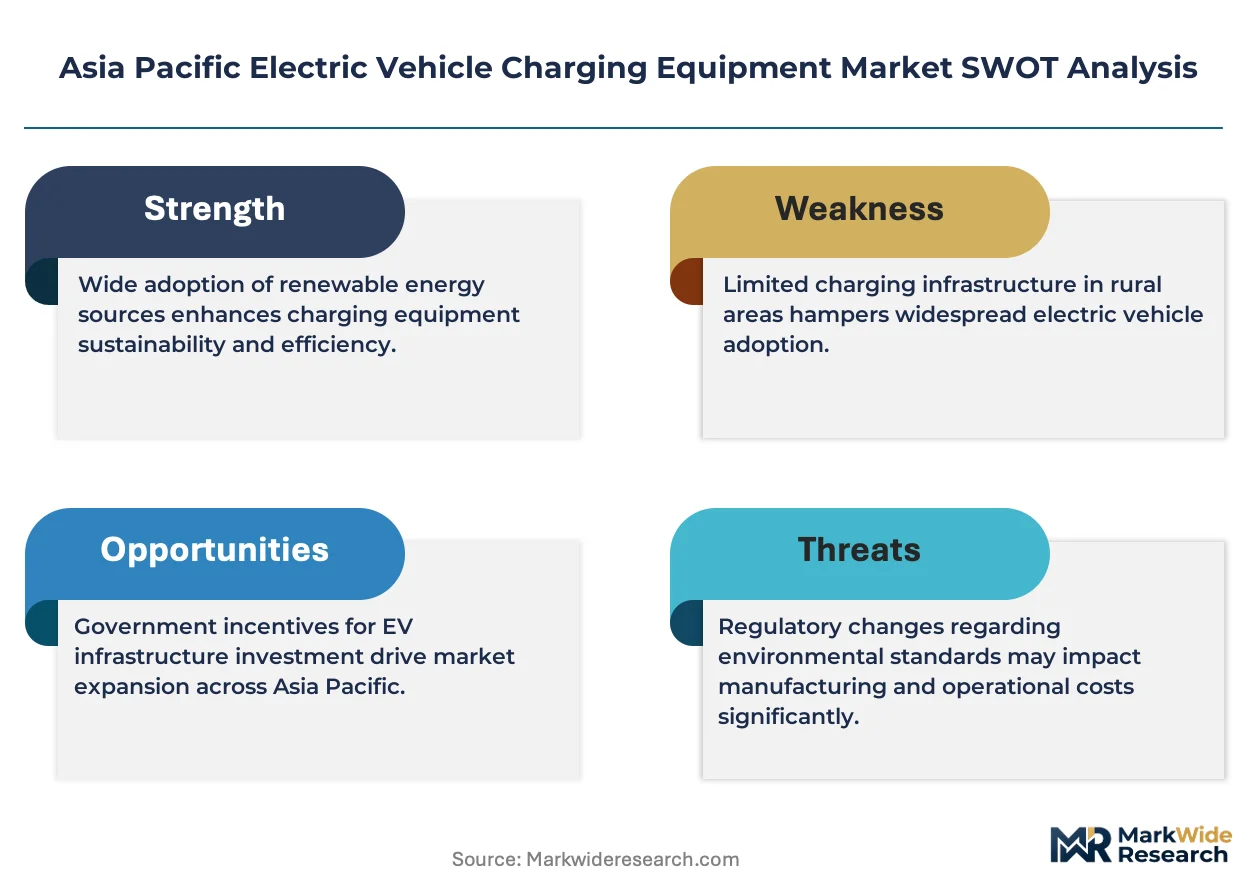
- Grid connection queue congestion:Distribution network upgrade approvals from state electricity boards in India and provincial grid companies in China extend project commissioning timelines by 12-24 months.
- Copper and rare earth price volatility:Cable assemblies and permanent magnet components in power conversion systems face input cost instability from concentrate supply concentration in Chile and China.
- CHAdeMO-CCS protocol bifurcation:Japan's METI expressway subsidies lock infrastructure investment into CHAdeMO specifications, fragmenting hardware platform standardization across Northeast Asia.
Strategic Opportunities
- Indonesia archipelago deployment gap:The national electric vehicle roadmap targets 31,000 public charging points by 2030, with current installed base below 2,000 units creating first-mover terrain.
- V2G bi-directional integration:Aggregated fleet battery capacity offers frequency regulation services to national grid operators, unlocking ancillary revenue streams beyond energy sales.
- Wireless inductive systems for automated parking:Luxury residential developments in Singapore and South Korea are specifying pad-based charging for autonomous valet applications.
Industry Challenges
- Power electronics engineering talent scarcity:Design of 800V+ thermal management systems requires specialized expertise concentrated among semiconductor and automotive Tier-1 suppliers.
- BIS electrical safety certification timelines:India's mandatory testing protocols for imported charging equipment create 4-6 month approval delays that compress supplier margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Electric Vehicle Charging Equipment Market |
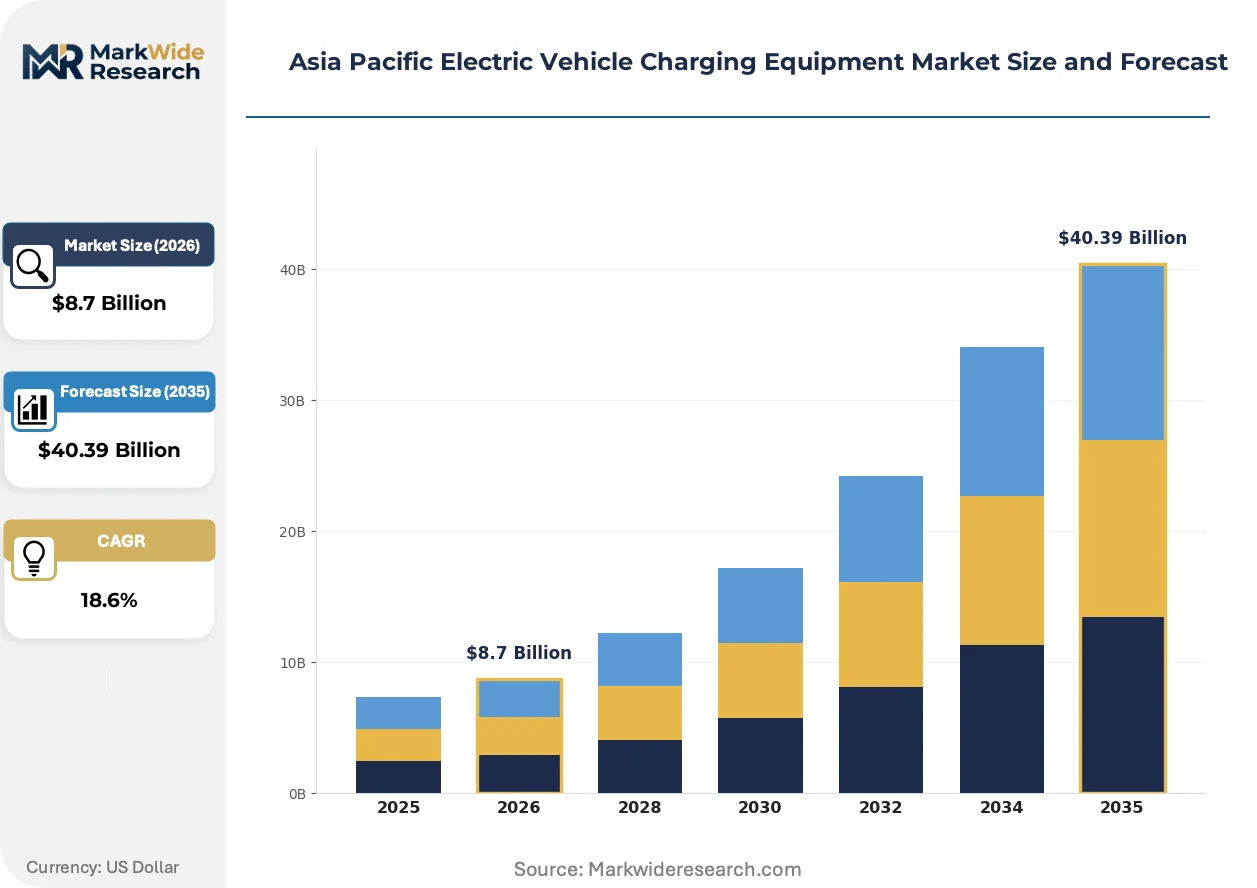
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $40.39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Chargers, DC Fast Chargers, Wireless Chargers, Standalone Units Technology: Level 1, Level 2, DC Fast Charging, Ultra-Fast Charging End User: Residential, Commercial, Public Charging Stations, Fleet Operators Installation: On-Street, Off-Street, Home Installation, Workplace Charging |
| Companies Covered | Delta Electronics, BYD, ABB, Schneider Electric, Siemens, ChargePoint, Tata Power, Star Charge, TGOOD Global, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Electric Vehicle Charging Equipment Market Trends and Innovations
Hardware architecture decisions are converging around thermal performance thresholds and grid-code compliance requirements, with supplier R&D roadmaps prioritizing semiconductor efficiency gains and software-defined power management over mechanical reliability improvements alone.
Silicon carbide MOSFETs are replacing insulated-gate bipolar transistors as the primary switching technology in DC fast charging power modules, delivering higher switching frequencies and reduced thermal losses. Tier-1 charging system integrators in South Korea and Taiwan are qualifying SiC-based designs for 350kW and 480kW output classes. The technology is migrating from premium highway corridor applications toward fleet depot hardware where duty cycles and utilization rates justify the component cost premium.
India's BIS certification framework for electrical safety and electromagnetic compatibility is tightening import requirements for charging equipment without domestic testing infrastructure. Foreign suppliers must establish local certification partnerships or face extended market entry timelines. Maharashtra and Gujarat industrial corridor deployments are experiencing procurement delays as hardware platforms undergo revised compliance validation.
Fleet operators are consolidating charging infrastructure procurement under long-term service agreements that bundle hardware, installation, maintenance, and energy management into per-kilometer or per-charge-event pricing. This unbundles capital expenditure from operational decision-making. The shift is most visible among logistics and ride-hailing platforms in China's Pearl River Delta and India's National Capital Region.
Asia Pacific Electric Vehicle Charging Equipment Market Segmentation
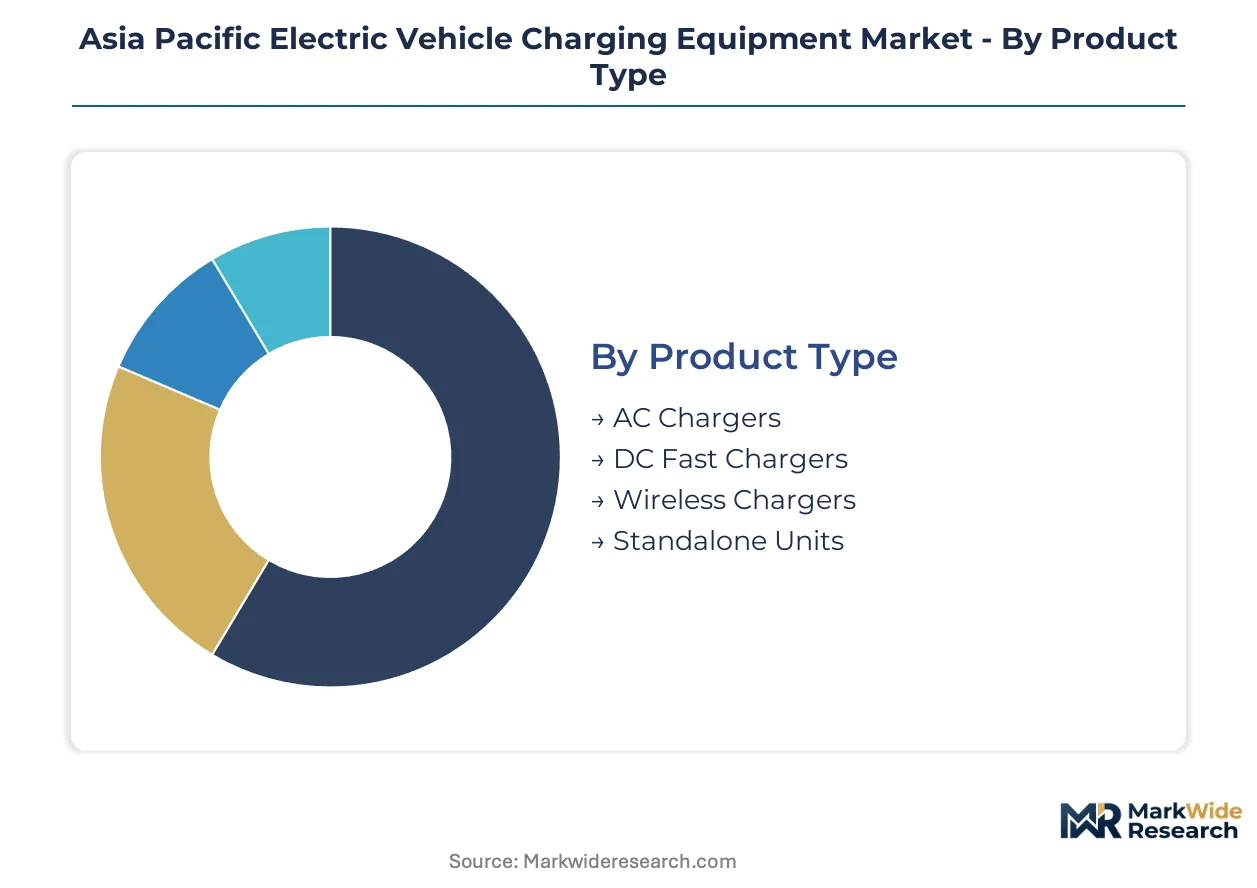
Segmentation in Asia Pacific electric vehicle charging equipment reveals how hardware specifications, power delivery architectures, and deployment contexts shape procurement economics. Supplier product roadmaps must reconcile divergent thermal performance requirements across residential, commercial, and fleet applications while navigating fragmented certification regimes.
Product Type:
Mature AC charging hardware dominates residential volume, while emerging DC and wireless architectures are capturing premium deployment channels.
- AC Chargers:These units convert grid alternating current to vehicle-compatible power through onboard rectification, typically delivering 3-22kW. Demand concentrates in China's tier-two residential compounds and India's apartment complexes where grid capacity constraints limit power draw. Hardware margins compress under standardized GB/T and BIS certification requirements.
- DC Fast Chargers:Off-board power conversion enables direct current delivery at 50kW to 480kW, bypassing vehicle onboard charger limitations. Fleet depots across Maharashtra-Gujarat industrial corridors and Pearl River Delta logistics hubs drive procurement volumes under long-term service agreements that bundle hardware with energy management software.
- Wireless Chargers:Inductive pad systems transfer power through magnetic resonance without physical connectors. Singapore luxury residential developments and South Korean automated parking structures specify these for autonomous valet integration.
- Standalone Units:Self-contained charging posts with integrated payment terminals and network connectivity serve remote highway corridors and island archipelagos where grid-tied infrastructure remains uneconomical.
AC Chargers retain volume leadership; DC Fast Chargers hold the steepest expansion curve.
Technology:
Cost tiers stratify sharply between entry-level residential hardware and premium fleet infrastructure requiring silicon carbide power electronics.
- Level 1:Standard 120V AC residential connections deliver 1-2kW through conventional household outlets. Rural Indian households and Japanese single-family residences deploy these as interim solutions pending grid upgrades.
- Level 2:240V AC systems achieve 7-22kW through dedicated circuit installation. China's MIIT subsidizes these for workplace parking structures in tier-one cities under dual carbon goal implementation timelines.
- DC Fast Charging:50-150kW direct current systems serve highway corridor waypoints and urban fast-charging plazas. Taiwan semiconductor foundries supply silicon carbide modules that enable higher switching frequencies and reduced thermal losses.
- Ultra-Fast Charging:350kW+ architectures utilize liquid-cooled cable assemblies and advanced power electronics to deliver 200km range in under 15 minutes. South Korean charging network operators deploy these along expressway corridors to support premium electric vehicle platforms.
Level 2 retains volume leadership; Ultra-Fast Charging holds the steepest expansion curve.
End User:
Customer type determines procurement structure, with fleet operators consolidating under long-term service agreements while residential buyers favor capital purchase models.
- Residential:Individual vehicle owners install charging hardware in private parking spaces or dedicated residential parking structures. India's BIS certification delays compress supplier margins for imported equipment targeting this price-sensitive segment.
- Commercial:Retail property owners, shopping malls, and hospitality operators deploy charging as amenity infrastructure. Thailand and Vietnam commercial real estate developers specify these to attract tenant businesses with fleet electrification commitments.
- Public Charging Stations:Government-procured highway corridor and urban plaza infrastructure serves sporadic user demand. Japan's METI subsidizes CHAdeMO-compatible nodes along expressway networks, directing investment toward specific technical specifications.
- Fleet Operators:Logistics platforms, ride-hailing services, and municipal bus operators consolidate charging procurement under per-kilometer pricing contracts. Binding zero-emission deadlines under state-level clean air regulations in India and China force capital deployment at scale.
Residential retains volume leadership; Fleet Operators holds the steepest expansion curve.
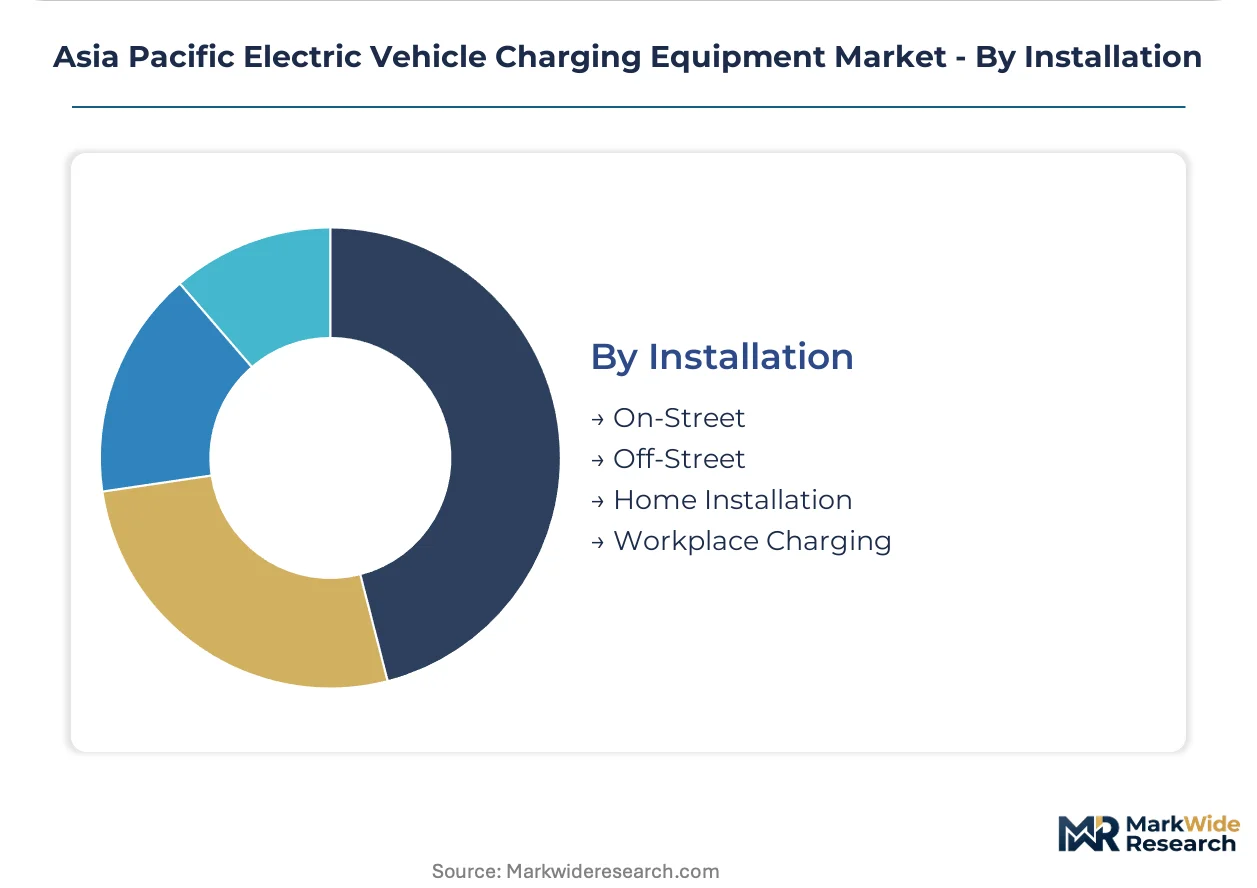
Installation:
Geography of deployment shapes hardware specifications, with on-street installations requiring vandal-resistant enclosures and home installations prioritizing compact form factors.
- On-Street:Curb-side charging posts serve urban residents without dedicated parking. Australian and New Zealand municipalities specify these for dense inner-city neighborhoods with limited off-street capacity.
- Off-Street:Dedicated parking structure and surface lot installations accommodate higher power levels and multiple simultaneous connections. Indonesia's archipelago deployment gap creates first-mover terrain for off-street infrastructure in Jakarta and Surabaya commercial zones.
- Home Installation:Wall-mounted or pedestal units in private garages and carports prioritize ease of installation and minimal electrical upgrade requirements. Philippine residential developments in Metro Manila specify these for middle-class townhouse communities.
- Workplace Charging:Employer-subsidized installations in commercial office parks support commuter vehicle charging during business hours. Malaysia's industrial corridor employers deploy these to attract talent in Iskandar Malaysia and Penang manufacturing zones.
Home Installation retains volume leadership; Workplace Charging holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese charging equipment manufacturers supply highway corridor and fleet depot infrastructure across Southeast Asia, with India emerging as the primary import destination for high-power DC systems amid domestic production scale-up.
China
Fleet depot electrification and highway corridor densification drive hardware procurement volumes. MIIT enforces GB/T charging standards that unify connector geometry and communication protocols, eliminating interoperability friction. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou produce silicon carbide power modules for 350kW+ systems.
India
State-level clean air regulations impose binding zero-emission deadlines on commercial vehicle operators. BIS certification requirements for electrical safety create 4-6 month approval delays for imported equipment. Maharashtra-Gujarat industrial corridors concentrate fleet depot deployments under long-term service agreements.
Japan
Expressway corridor electrification supports premium electric vehicle platform adoption. METI subsidizes CHAdeMO-compatible ultra-fast charging nodes, directing infrastructure investment toward specific technical specifications. Kanto region operators deploy these along Tokyo-Osaka highway corridors.
South Korea
Semiconductor foundries expand 6-inch and 8-inch silicon carbide wafer capacity, compressing bill-of-material costs for power electronics. National charging network operators deploy 350kW+ systems along expressway corridors. Seoul Capital Area hosts R&D facilities qualifying SiC-based designs for next-generation hardware.
Indonesia
The national electric vehicle roadmap targets 31,000 public charging points by 2030 against a current installed base below 2,000 units. Archipelago geography favors standalone units with integrated payment terminals for island deployments. Jakarta and Surabaya commercial zones attract first-mover infrastructure investment.
Asia Pacific Electric Vehicle Charging Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated power electronics manufacturers with captive semiconductor sourcing, grid-software specialists with utility network integration capabilities, and regional system integrators with local certification expertise. Competitive positioning depends on backward integration into silicon carbide module supply and forward integration into energy management software. M&A activity concentrates on semiconductor foundry partnerships and charging network operator acquisitions.
Within the integrated power electronics tier, Delta Electronics and BYD exemplify archetypes of upstream control over component costs. ABB occupies a position among grid-software specialists with bi-directional energy flow management capabilities. These three entities represent distinct competitive vectors: semiconductor foundry partnerships, captive battery and power electronics manufacturing, and utility-scale grid integration software.
| Leading Market Players |
|---|
| Delta Electronics |
| BYD |
| ABB |
| Schneider Electric |
| Siemens |
| ChargePoint |
| Tata Power |
| Star Charge |
| TGOOD Global |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Taiwan's 8-inch silicon carbide wafer foundries is compressing component availability for 350kW+ charging systems, forcing hardware suppliers to pre-commit volumes and accept pricing premiums that cascade through DC fast charger bill-of-materials. This utilization squeeze simultaneously tightens supplier bargaining power and accelerates buyer consolidation around long-term service agreements that internalize cost volatility.
Pricing Analysis
Next-generation silicon carbide-based DC fast chargers command 40-60% premiums over prior-generation IGBT systems, while entry-level AC residential hardware faces commoditization. Three-tier pricing structure across premium liquid-cooled 480kW highway systems, standard 150kW fleet depot units, and economy 7kW residential chargers reflects thermal performance differentiation and certification grade. Pricing pressure stems from BIS certification delays in India that extend supplier working capital cycles and compress margins. Fleet operators exhibit lowest price sensitivity due to throughput economics, while residential buyers in tier-two Chinese cities demand aggressive unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for power module procurement, with supply-chain finance facilities emerging as a competitive differentiator among Tier-1 integrators. Manufacturing concentrates in China for GB/T-certified power conversion systems, Taiwan for silicon carbide semiconductors, and South Korea for high-frequency magnetics. Cable assemblies draw from Chilean copper concentrate and Chinese rare earth processing. Single-source vulnerability in 6-inch SiC wafer supply creates exposure to foundry allocation decisions. Distribution runs through charging network operators and EPC contractors rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific electric vehicle charging equipment market is recovering from a capital deployment lull as fleet electrification mandates trigger infrastructure refresh cycles. This cyclical upswing is anchored in binding zero-emission deadlines under state-level clean air regulations across India and China.
For Market Incumbents: Pre-empt margin erosion in AC residential hardware by accelerating backward integration into silicon carbide module supply through Taiwan foundry partnerships. Defend position in fleet depot procurement by bundling energy management software with hardware to create switching costs against emerging grid-software specialists. The priority lever rests on qualifying liquid-cooled 480kW systems before competitors achieve BIS certification for Indian industrial corridor deployments. For New Entrants and Emerging Players: Establish a beachhead in Indonesia's archipelago deployment gap where standalone units with integrated payment terminals face limited incumbent presence. Target Maharashtra-Gujarat industrial corridors through local certification partnerships that compress BIS approval timelines versus direct import routes. The most penetrable segment is workplace charging in Malaysia's Iskandar Malaysia zone, where employer-subsidized installations lack established supplier relationships. For Investors and Strategic Acquirers: Capital is best deployed toward semiconductor foundry partnerships and charging network operator acquisitions that combine upstream component access with downstream utilization visibility. Over the projection horizon, vertically integrated power electronics manufacturers with captive SiC sourcing represent superior viability versus pure-play hardware assemblers. The signal to watch is MIIT GB/T standard harmonization progress that would accelerate production ramp rates and reward early capacity positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Taiwanese 8-inch wafer access secures component supply for 350kW+ systems ahead of allocation constraints. |
| Long-Term Service Agreement Expansion | Fleet operator bundling of hardware, installation, and energy management creates recurring revenue and switching costs. |
| BIS Certification Infrastructure Investment | Domestic Indian testing capability compresses 4-6 month approval delays and unlocks Maharashtra-Gujarat procurement. |
| Bi-Directional Grid Integration Software | V2G frequency regulation services to national grid operators unlock ancillary revenue beyond energy sales. |
| Indonesia First-Mover Deployment | Standalone unit installation in Jakarta and Surabaya captures 31,000-point national roadmap target against sub-2,000 current base. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT regulatory filings, BIS certification databases, Taiwan semiconductor foundry capacity disclosures, and India state electricity board procurement records. Primary interviews engaged charging network operators, fleet depot procurement managers, power electronics design engineers, and EPC contractors across China, India, South Korea, and Indonesia. Bottom-up unit economics modeling triangulated against top-down infrastructure investment forecasts from national electric vehicle roadmaps.
Forecast inputs span charging power class, end-user procurement structure, installation geography, and semiconductor technology generation across the analysis window. Segmentation dimensions include product type, technology tier, end-user category, and installation context. CAGRs were derived from infrastructure deployment timelines under regulatory mandate scenarios and fleet electrification commitment tracking. Key inputs include silicon carbide module cost curves, grid interconnection queue durations, and certification timeline compression potential.
Stress conditions across SiC wafer supply allocation, copper concentrate price bands, and grid approval timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fleet operator capital commitment durability. Macroeconomic contraction, protocol standardization reversal, or foundry capacity expansion delays would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Electric Bus Charging Infrastructure Market
Electric Vehicle Charging
Stationary Electric Vehicle Charging Gun Market
Electric Vehicle Charging
Western Europe Electric Vehicle (EV) Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Global Electric Vehicle (EV) Charging Service Market
Electric Vehicle Charging
EV DC Fast Charger Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Electric Vehicle Public Charging Pile Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Netherlands Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Automotive EV Charging Adapters Market
Electric Vehicle Charging
North America EV Charging Stations Market
Electric Vehicle Charging
Electric Vehicle Charger Operations and Maintenance Services Market