
 Viscosity Reducing Agents Market | 2026-2036
Viscosity Reducing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Viscosity Reducing Agents Market Outlook
Gulf Coast additive producers is rebalancing supply chains after capacity rationalization in Texas and Louisiana. BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply of polymeric viscosity modifiers for oilfield service firms. Baker Hughes Company anchors its position through technology leadership in synthetic compound formulations for high-temperature reservoir conditions. Halliburton competes by extending its direct sales channel to bypass distributor markups in North American shale plays.
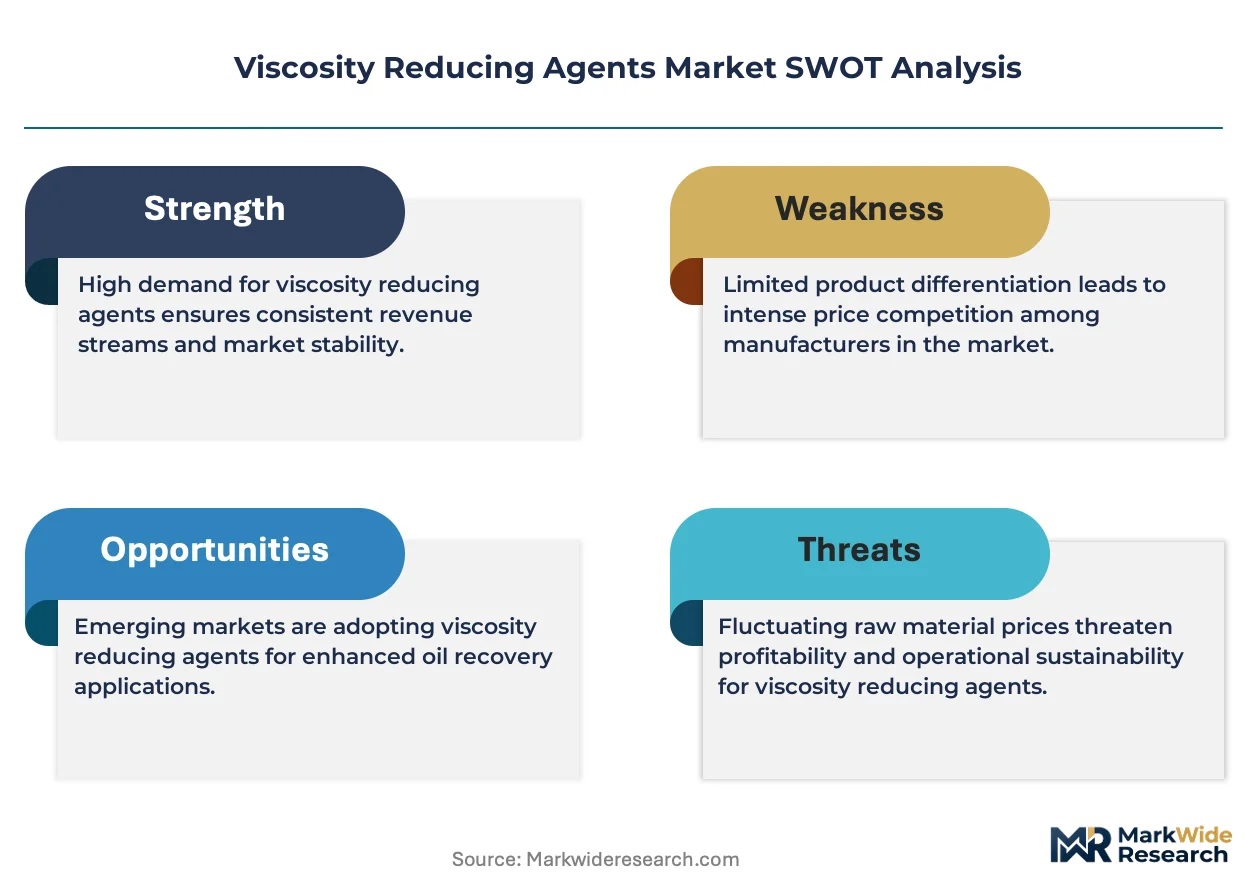
Viscosity reducing agents are chemical additives that lower fluid resistance to flow, typically functioning at dosage rates between 100–10,000 ppm depending on base fluid composition and target rheology. These compounds operate by disrupting intermolecular associations within crude oil, drilling muds, or process fluids to improve pumpability, reduce energy consumption, and enable pipeline transport of heavy hydrocarbons. Polymeric additives occupy the largest share of product value owing to their tunable molecular weight architectures and proven performance in paraffinic crude systems. Surfactant-based formulations represent the fastest-expanding category as operators seek lower-dose alternatives compatible with tight reservoir chemistries. Natural polymers command premium positioning in food and personal care applications where clean-label certification restricts synthetic compound use.
EPA regulations under the Toxic Substances Control Act constrain new chemical introductions, while REACH registration requirements in Europe mandate full toxicological dossiers for surfactant chemistries above one-tonne annual volumes. FDA food additive regulations and FSSC 22000 certification standards govern natural polymer incorporation into food-grade viscosity systems. Stakeholders must monitor evolving state-level chemical disclosure rules in Texas and California alongside emerging biobased content thresholds in EU procurement directives.
Market Dynamics
Permian Basin operators are driving reformulation toward lower-dose surfactant chemistries as pipeline transport economics tighten and water-cut ratios climb in maturing shale wells.
Growth Catalysts
- REACH Registration Thresholds:ECHA's one-tonne annual volume trigger for full toxicological dossiers is accelerating bio-based polymeric alternatives in European oilfield services.
- Enhanced Oil Recovery Expansion:Thermal and chemical EOR projects in heavy oil formations require viscosity reducers at 5,000–10,000 ppm dosage rates to maintain pumpability.
- Gulf Coast Refining Corridor:Concentrated demand from Texas and Louisiana refiners processing Venezuelan and Canadian heavy crudes sustains bulk additive offtake.
Market Restraints
- Alpha-Olefin Feedstock Volatility:Surfactant precursor costs fluctuate with ethylene pricing, compressing margin visibility for synthetic formulation producers.
- Ludwigshafen Supply Concentration:European additive supply depends heavily on integrated petrochemical complexes in Germany, creating single-point vulnerability.
- High-Temperature Performance Ceiling:Polymeric additives degrade above 150°C in deep reservoir conditions, limiting deployment in geothermal and ultra-deepwater fields.
Strategic Opportunities
- India Heavy Oil Reserves:Underdeveloped Barmer-Sanchore and Cambay Basin fields present greenfield demand for paraffinic crude viscosity modifiers.
- EU Green Deal Biobased Mandates:Procurement directives specifying renewable content thresholds create preferential market access for natural polymer suppliers.
- Direct-to-Operator Digital Channels:Bypassing distributor networks through integrated e-procurement platforms reduces customer acquisition costs in North American shale plays.
Industry Challenges
- Rheology Modeling Expertise Gap:Reservoir-specific fluid characterization requires computational chemists scarce in mid-sized oilfield service firms.
- FDA Food Additive Certification Timelines:Natural polymer suppliers targeting personal care adjacencies face 18–24 month GRAS determination delays.
- Legacy SCADA Integration Friction:Real-time dosage optimization systems struggle to interface with decades-old refinery distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscosity Reducing Agents Market |
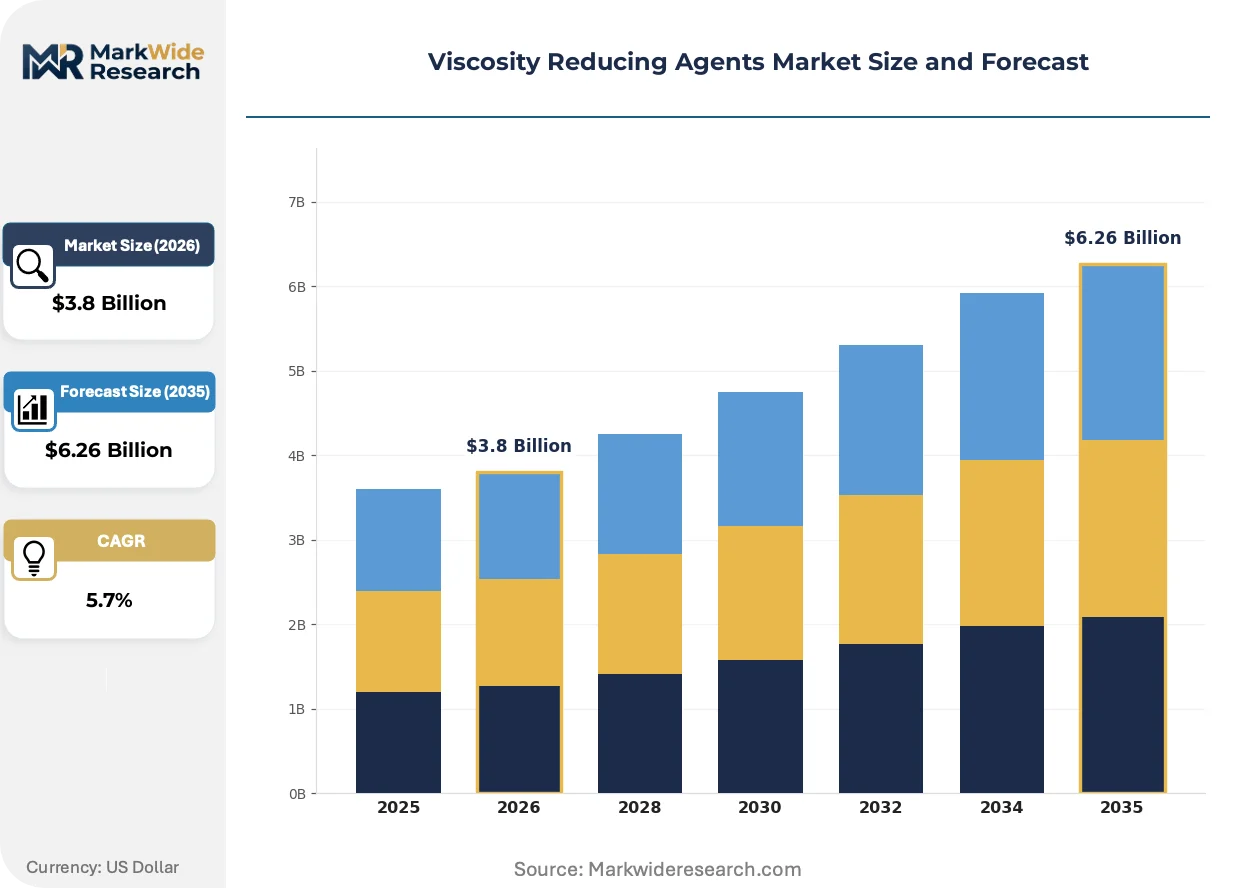
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Additives, Surfactants, Synthetic Compounds, Natural Polymers Application: Oil Recovery, Food Products, Paints, Personal Care End User: Oil & Gas, Food & Beverage, Automotive, Pharmaceuticals Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | The Lubrizol Corporation, BYK-CHEMIE GMBH, Ecolab, Innospec, ARKEMA Group, BASF SE, Baker Hughes Company, LiquidPower Specialty Products Inc., Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscosity Reducing Agents Market Strategic Shifts
Surfactant-based low-dose formulations are compressing traditional polymeric additive economics while digital dosage control systems enable precision injection at the wellhead.
Microemulsion surfactant systems is decentralizing additive deployment from centralized blending facilities to wellpad-scale injection skids. Operators in the Permian Basin are adopting portable units at 40% of new drilling sites. This technology is decentralizing supply chain power toward regional service companies and away from bulk chemical distributors.
EPA Toxic Substances Control Act pre-manufacture notification requirements are extending review timelines for novel surfactant chemistries to 90–180 days. Formulators are retreating to existing chemical inventories rather than innovating new molecular architectures. Small and mid-sized additive producers lacking regulatory affairs departments are most affected, with several abandoning new product pipelines.
Specification-driven procurement now dominates capital project awards, with operators mandating certified performance guarantees rather than accepting traditional volume-based supply agreements. Distributor markups face compression as Halliburton and Baker Hughes build direct sales organizations. This pattern concentrates in Texas and North Dakota shale formations where operator consolidation has reduced buyer fragmentation.
Viscosity Reducing Agents Market Segmentation
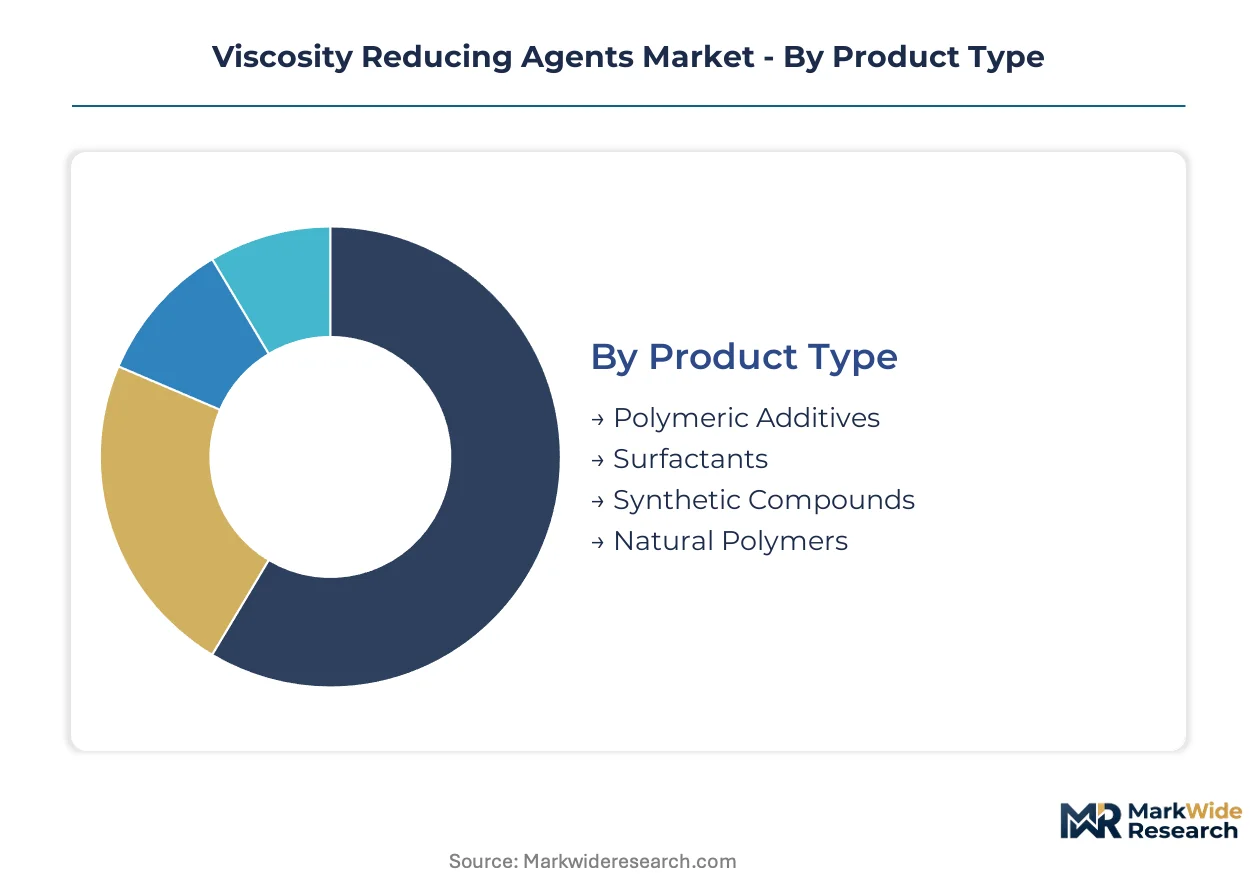
Segmentation in viscosity reducing agents reveals divergent specification requirements across oilfield chemistry and consumer-facing applications. Product architecture, dosage precision, and regulatory compliance thresholds vary substantially by end-use, creating distinct competitive arenas with limited technology transfer between them.
Product Type:
Polymeric architectures dominate commercial value through tunable molecular weight engineering and thermal stability optimization.
- Polymeric Additives:Long-chain synthetic polymers with molecular weights ranging from 10,000 to 2,000,000 Daltons disrupt paraffin crystal formation in heavy crude systems. Demand concentrates in Permian Basin thermal EOR operations where operators require 5,000–10,000 ppm dosage rates to maintain pumpability in maturing shale wells with climbing water-cut ratios.
- Surfactants:Microemulsion systems and alkyl polyglucosides function at 100–1,000 ppm concentrations through interfacial tension reduction rather than bulk viscosity modification. Newer deployment is concentrated in tight reservoir chemistries across the Gulf Coast refining corridor where lower-dose economics improve pipeline transport margins.
- Synthetic Compounds:Alpha-olefin derivatives and ester-based formulations engineered for 150°C+ reservoir conditions.
- Natural Polymers:Xanthan gum, guar derivatives, and cellulosic extracts carrying FSSC 22000 certification for clean-label applications.
Mature deployment sits with polymeric additives. Newer deployment is concentrated in surfactant systems.
Application:
Volume concentration tracks hydrocarbon processing intensity, with consumer applications commanding premium positioning through certification requirements.
- Oil Recovery:Enhanced oil recovery operations in heavy oil formations and paraffinic crude systems require continuous viscosity modification to sustain production economics. Demand clusters in thermal and chemical EOR projects across the Permian Basin and Canadian oil sands where declining reservoir pressures necessitate artificial lift optimization.
- Food Products:Natural polymer incorporation into sauces, dressings, and dairy systems governed by FDA 21 CFR 172 and GRAS self-determination pathways. Clean-label certification requirements restrict synthetic compound use, creating preferential positioning for xanthan and guar-based systems in premium product tiers.
- Paints:Rheology modification in waterborne and solvent-based coating systems for application viscosity control and sag resistance.
- Personal Care:Sensorial texture engineering in lotions, creams, and hair care formulations requiring dermatological safety testing.
Established consumption patterns characterize oil recovery. Food products and personal care are expanding most quickly through clean-label substitution trends.
End User:
Procurement sophistication varies dramatically between capital-intensive hydrocarbon operators and formulation-driven consumer goods manufacturers.
- Oil & Gas:Integrated operators and oilfield service firms purchasing bulk additives through specification-driven procurement with certified performance guarantees. Direct sales channels dominate as Halliburton and Baker Hughes bypass distributor markups in North American shale plays.
- Food & Beverage:CPG manufacturers and contract manufacturers requiring FSSC 22000 certification and lot-level traceability for natural polymer sourcing. FDA food additive regulations and 18–24 month GRAS determination timelines constrain supplier switching.
- Automotive:Lubricant formulators and coating applicators seeking viscosity index improvers and paint rheology modifiers.
- Pharmaceuticals:Excipient suppliers and drug manufacturers governed by USP-NF monographs and ICH Q3D elemental impurity guidelines.
Procurement maturity is highest in oil and gas. Pharmaceutical qualification represents the steepest expansion trajectory as excipient outsourcing accelerates.
Distribution Channel:
Channel economics reflect order scale, technical service requirements, and geographic concentration of demand.
- Direct Sales:Technical field support and formulation optimization services bundled with bulk chemical supply. Oilfield service firms anchor this channel through integrated e-procurement platforms reducing customer acquisition costs in Texas and North Dakota shale formations.
- Distributors:Regional chemical distributors maintaining inventory positions for mid-sized refiners and blenders. Markups face compression as operator consolidation reduces buyer fragmentation and rewards volume concentration.
- Online Retail:E-commerce platforms serving small-batch personal care formulators and research laboratories.
- Wholesalers:Aggregated procurement for food and beverage manufacturers with standardized specification requirements.
Channel power is concentrating in direct sales. Online retail is gaining share fastest among independent formulators and specialty chemical buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene feedstock availability along the US Gulf Coast anchors viscosity reducing agent production capacity. Alpha-olefin derivatives from Texas and Louisiana petrochemical complexes supply surfactant precursors to North American oilfield service firms. Regional demand concentrates in heavy crude processing corridors and shale extraction zones.
United States
Permian Basin thermal EOR operations drive polymeric additive consumption at 5,000–10,000 ppm dosage rates. EPA Toxic Substances Control Act pre-manufacture notifications extend novel surfactant review timelines to 90–180 days. Houston-Gulf Coast refining clusters process Venezuelan and Canadian heavy crudes requiring continuous viscosity modification.
Germany
REACH registration thresholds above one-tonne annual volumes accelerate bio-based polymeric alternatives in oilfield services. ECHA toxicological dossier requirements constrain surfactant chemistry introductions. BASF SE's Ludwigshafen integrated complex sustains captive supply of viscosity modifiers for European operators.
China
Shale gas development in Sichuan Basin creates emerging demand for drilling fluid rheology control. MIIT industrial standards govern chemical additive environmental discharge limits. Yangtze River Delta petrochemical hubs manufacture alpha-olefin feedstocks for domestic surfactant production.
Saudi Arabia
Heavy oil reserves in the Eastern Province require viscosity reducers for thermal EOR pumpability. Saudi Aramco procurement specifications mandate certified performance guarantees rather than volume-based supply agreements. Jubail industrial city hosts specialty chemical production serving regional oilfield service demand.
India
Barmer-Sanchore and Cambay Basin heavy oil fields present greenfield demand for paraffinic crude viscosity modifiers. FSSAI food additive regulations govern natural polymer incorporation into processed food systems. Gujarat chemical manufacturing clusters supply guar derivatives for domestic oil recovery and food applications.
Viscosity Reducing Agents Market Competitive Environment
Global majors compete with regional champions across formulation technology and direct sales channel access. Market structure tilts toward consolidation among integrated oilfield service firms while specialty chemical suppliers fragment across application-specific niches. Three archetypes dominate: petrochemical conglomerates with backward integration into feedstocks, oilfield service firms with captive additive supply, and independent specialty formulators. Competitive moves concentrate on bypassing distributor networks and securing certified performance contracts with consolidated operators.
Among Germany-based chemical conglomerates, BASF SE anchors the integrated petrochemical archetype through its Ludwigshafen complex. Oilfield service specialists include Baker Hughes Company and Halliburton, which occupy positions emphasizing direct operator relationships and technology leadership in high-temperature formulations. These three exemplify distinct competitive vectors: feedstock security, field service integration, and specification-driven procurement influence.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| BYK-CHEMIE GMBH |
| Ecolab |
| Innospec |
| ARKEMA Group |
| BASF SE |
| Baker Hughes Company |
| LiquidPower Specialty Products Inc. |
| Halliburton |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal biobased content mandates gate qualified supply and premium-tier pricing access, as REACH-registered polymeric alternatives command 15-25% markups over conventional synthetic formulations while excluding uncertified competitors from European oilfield procurement channels.
Pricing Analysis
Warranty-backed performance guarantees separate bundled from unbundled supply arrangements, with Halliburton and Baker Hughes embedding field technical support and dosage optimization into long-term offtake contracts at premium rates. Three-tier pricing structure across REACH-certified premium, standard synthetic, and economy unregistered tiers reflects differentiation by regulatory compliance grade and volume scale. Cost compression in economy-tier surfactants is intensifying because alpha-olefin feedstock volatility erodes margin visibility. Mid-sized independent formulators exhibit highest price sensitivity, while integrated oilfield service firms prioritize certified performance over unit economics.
Supply Chain Analysis
Specialized chemical engineers and computational rheologists concentrate in Texas Gulf Coast and German Rhine-Ruhr manufacturing geographies, constraining capacity expansion for complex polymeric additive production. Supply draws from alpha-olefin precursors manufactured in Texas and Louisiana petrochemical corridors, guar derivatives processed in Gujarat, India, and xanthan gum fermentation capacity concentrated in China. Single-source vulnerability around BASF SE's Ludwigshafen complex exposes European additive supply to geopolitical disruption. Distribution runs through direct sales channels anchored by oilfield service firms, with regional distributors serving fragmented mid-sized refiner demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EPA pre-manufacture notification timelines and REACH dossier requirements force capital-constrained formulators to abandon new product pipelines.
For Market Incumbents: Anchor position through captive supply of high-temperature synthetic compounds and backward integration into alpha-olefin feedstocks. Secure direct e-procurement platform relationships with Permian Basin operators to lock out distributor-dependent competitors. Invest in ECHA registration completion ahead of one-tonne volume thresholds to exclude unregistered rivals from European tenders. For New Entrants and Emerging Players: Regional service companies with portable microemulsion injection skids represent the most penetrable channel partner type for wellpad-scale deployment bypassing centralized blending facilities. Target India's Barmer-Sanchore heavy oil fields where greenfield demand for paraffinic crude modifiers lacks established supplier relationships. Lead with digital dosage optimization systems compatible with legacy SCADA architectures as the primary go-to-market angle. For Investors and Strategic Acquirers: Halliburton or Baker Hughes announcing direct sales channel expansion into North Dakota shale formations is the leading indicator that distributor markups are entering terminal compression, signaling acquisition timing for undervalued regional formulators. Five-to-ten year viability favors specialists with REACH-registered bio-based portfolios and certified food-grade polymer capabilities. Watch for EU procurement directives specifying renewable content thresholds as the inflection signal for natural polymer supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Feedstocks | Texas and Louisiana petrochemical complexes secure margin control against ethylene price volatility. |
| REACH Registration Completion | ECHA toxicological dossiers unlock European oilfield service procurement above one-tonne annual volumes. |
| Direct E-Procurement Platform Launch | Integrated digital channels bypass distributor markups in Texas and North Dakota shale plays. |
| Portable Microemulsion Skid Deployment | Wellpad-scale injection decentralizes supply chain power toward regional service companies. |
| FSSC 22000 Certification Investment | Food safety certification enables natural polymer premium positioning in clean-label consumer applications. |
Study Parameters
Independent corroboration across oilfield service procurement directors, refinery operations managers, and specialty chemical R&D leads underwrites the qualitative findings, validated against ECHA registration databases, EPA pre-manufacture notifications, SEC 10-K chemical segment disclosures, and customs trade data for alpha-olefin derivatives. Bottom-up volume modeling from individual facility consumption patterns triangulates with top-down market sizing from petrochemical feedstock flow analysis.
Comparable-period anchoring to historical dosage rate trends and EOR project deployment cycles shapes the projection framework across the analysis window. Segmentation dimensions span product architecture, application intensity, end-user procurement sophistication, and channel economics. CAGRs derive from weighted scenario modeling incorporating thermal EOR expansion rates, regulatory compliance cost trajectories, and surfactant substitution elasticities in tight reservoir conditions.
Caveats apply where alpha-olefin feedstock cost spikes, unanticipated REACH enforcement acceleration, or breakthrough geothermal drilling technologies could materially shift the outlook. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Lauroyl Methyl Glucamide Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Europe Citric Acid Market
Additives
Plasticizer Concrete Admixtures Market
Additives
Biofuel Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Marine Fuel Additives Market
Additives
Inorganic Rheology Modifiers Market
Additives
Dipotassium Guanylate Market
Additives
Ammonium Phosphatide Market
Additives
Antimicrobial Ingredients Market
Additives
Low-Carbon Concrete Shrinkage-Reduction Additives Market
Additives
Wax Additives Market
Additives
Global Matting Agents Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Maltitol Based on Corn Starch Market