
 Allura Red AC Market | 2026-2036
Allura Red AC Market Size, Share, and Industry Trends Forecast 2026-2036
Allura Red AC Market Outlook
Buyer concentration among food manufacturers is expanding as multinational beverage and confectionery houses consolidate supplier rosters toward fewer certified partners. Sensient Technologies Corporation leverages its integrated color platform to sustain long-term contracts with regulated food brands. Vidhi Specialty Food Ingredients Limited anchors its position through specialized manufacturing of Halal and Kosher-certified dye grades for export markets. Dynemic Products Limited competes on geographic dominance within India's domestic food processing corridor.
Allura Red AC is a synthetic azo dye, chemically designated as FD&C Red 40, characterized by a maximum absorption wavelength near 504 nm and manufactured through diazotization and coupling reactions of aromatic amines. The compound serves primarily as a water-soluble colorant in acidic food matrices where heat stability and hue consistency are required. Powder formulations occupy the largest volume share due to handling efficiency in industrial batching operations, while liquid variants represent the fastest-growing format as beverage processors automate dosing systems. Certification stratification creates distinct margin pools, with FDA-approved and Halal-certified grades commanding premium positioning over standard industrial grades.
The FDA maintains strict batch certification requirements for Allura Red AC under 21 CFR 74.340, while the EU's EFSA evaluates reauthorization of azo dyes through periodic safety assessments that directly impact import eligibility. India's FSSAI enforces maximum permissible limits for synthetic colors in processed foods, creating compliance barriers for non-certified imports. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and certification investment priorities.
Market Dynamics
Clean-label pressures are compressing procurement timelines as beverage manufacturers accelerate supplier consolidation toward certified colorant partners, forcing reformulation cycles that favor compliance-ready synthetic dye grades over uncertified alternatives.
Growth Catalysts
- FSSAI enforcement expansion:India's tightening maximum permissible limits for synthetic colors in processed foods are redirecting domestic processors toward certified Allura Red AC suppliers with documented batch traceability.
- Beverage automation:Liquid dosing systems in carbonated and still drink production lines are accelerating format migration from powder to liquid colorant variants, tightening supplier specifications.
- Export certification premiums:Halal and Kosher-certified dye grades are capturing expanded share in Middle Eastern and North African food export corridors as import gatekeeping intensifies.
Market Restraints
- Aromatic amine feedstock volatility:Naphthalene derivative pricing swings are compressing margin stability for diazotization-dependent manufacturers without backward integration into petrochemical precursors.
- FDA batch certification bottlenecks:Certification queue delays under 21 CFR 74.340 are extending lead times for US-bound shipments, favoring pre-certified inventory holders.
- Natural colorant substitution:Anthocyanin and carmine alternatives are displacing synthetic azo dyes in premium confectionery segments where cost tolerance permits hue trade-offs.
Strategic Opportunities
- Southeast Asian processing expansion:Vietnam and Indonesia's nascent food manufacturing clusters present underpenetrated demand for FDA-certified colorants serving export-oriented contract manufacturers.
- EU reauthorization tailwinds:EFSA's pending azo dye safety assessments may create temporary supply windows for compliant non-EU producers if domestic European capacity faces suspension.
- Pharmaceutical excipient crossover:Tablet coating applications for Allura Red AC in generic drug manufacturing represent an adjacent demand vertical with distinct certification pathways.
Industry Challenges
- Analytical chemistry talent scarcity:Batch certification laboratories face recruitment gaps for chromatography specialists capable of executing FDA-mandated purity assays under compressed turnaround requirements.
- Legacy equipment retrofit costs:Powder-to-liquid format shifts demand capital outlays for sealed transfer systems and automated dosing infrastructure that mid-tier processors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Allura Red AC Market |
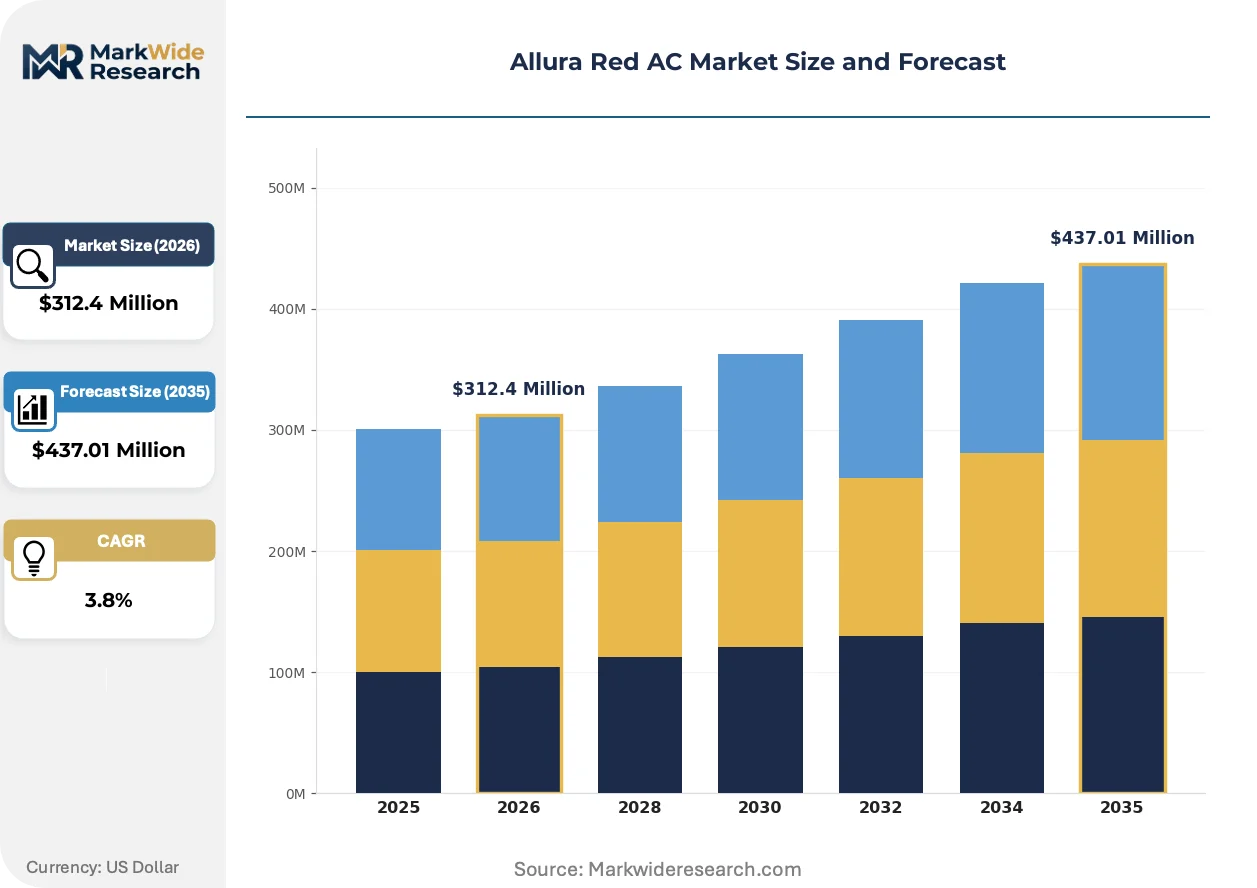
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $437.01 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Paste Application: Beverages, Dairy Products, Confectionery, Bakery End User: Food Manufacturers, Beverage Industry, Retailers, Foodservice Certification: FDA Approved, ISO Certified, Halal, Kosher |
| Companies Covered | Archer Daniels Midland Company, Vidhi Specialty Food Ingredients Limited, Sensient Colors LLC, Vinayak Ingredients (India) Pvt. Ltd., Dynemic Products Limited, Sensient Technologies Corporation, Symrise AG, DIC Corporation, Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Allura Red AC Market Strategic Shifts
Microencapsulation technologies are reshaping heat stability performance standards across acidic food matrices, enabling synthetic dye deployment in previously excluded thermal processing environments while compressing the technical advantage window of natural alternatives.
Encapsulated Allura Red AC variants with modified starch or gum arabic shells are electrifying retention performance in UHT-treated beverages and extruded snacks. Major dairy and savory processors in Mexico and Thailand are piloting these grades at commercial scale. The technology is compressing reformulation cycle frequency by extending hue consistency through aggressive heat treatment regimes previously hostile to unprotected azo dyes.
REACH authorization timelines for aromatic amine derivatives are compressing European supply security for azo dye manufacturers dependent on imported intermediates. Industrial users are stockpiling certified inventory ahead of potential substance restriction proposals. The confectionery segment across Germany and Poland is accelerating dual-sourcing strategies to preempt supply interruption scenarios.
Specification-driven procurement is consolidating buyer decision authority within centralized technical teams rather than decentralized plant purchasing functions. Long-term contracting with certified suppliers is displacing spot market transactions for volume beverage accounts. This pattern is most visible in India's organized retail supply chain, where private-label beverage manufacturers enforce supplier qualification protocols that exclude uncertified dye sources.
Allura Red AC Market Segmentation
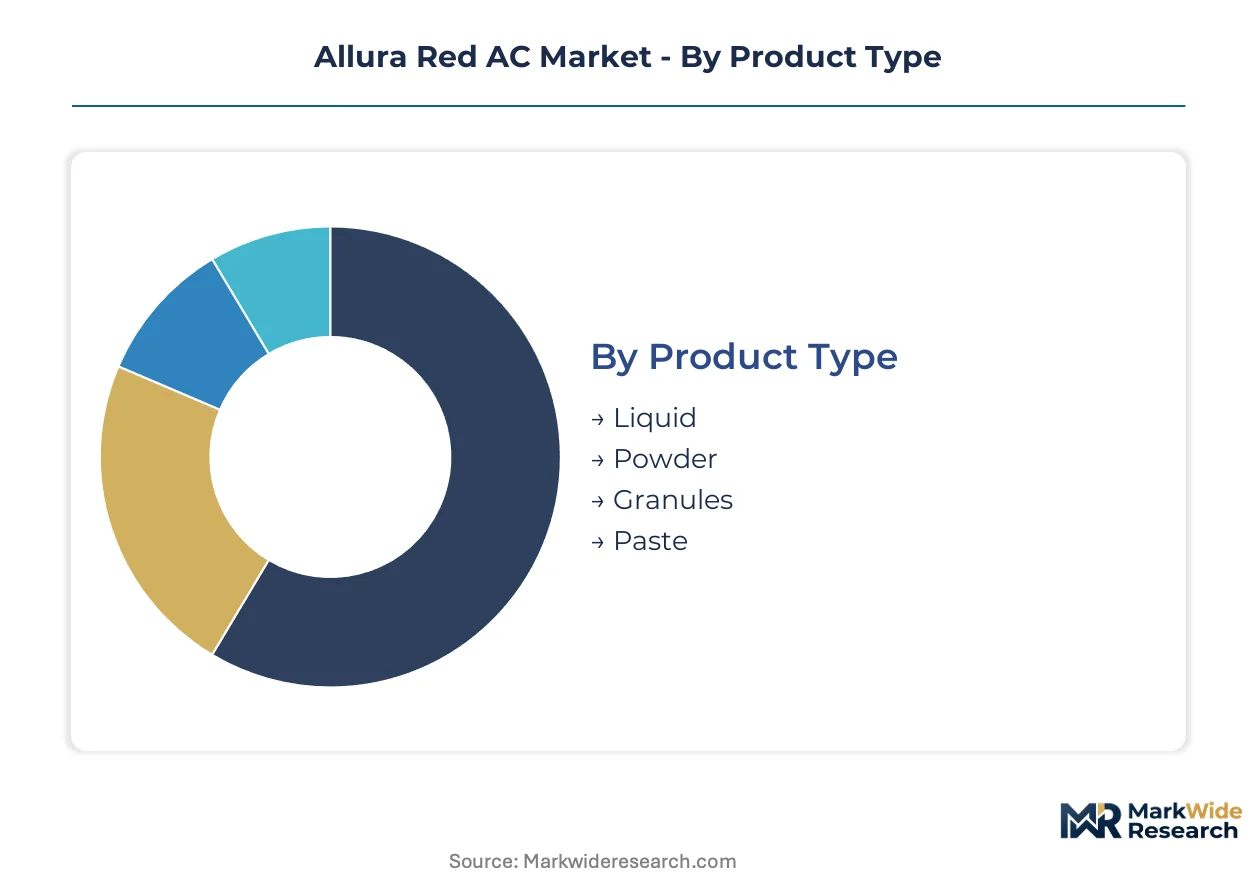
Procurement specifications for Allura Red AC are hardening as beverage automation and export certification requirements reshape supplier qualification protocols. Format preferences and compliance tiers now determine contract eligibility more than unit economics alone.
Product Type:
Equipment replacement cycles in beverage processing are accelerating format migration, with liquid dosing infrastructure displacing legacy powder-handling systems.
- Liquid:Pre-dissolved aqueous solutions enable precision metering through automated injection skids in carbonated drink lines. Demand clusters in Thailand and Mexico where contract beverage manufacturers serve export markets under FDA scrutiny.
- Powder:Spray-dried crystalline formulations retain dominance in industrial batching for confectionery and bakery applications requiring dry-blending compatibility. India's domestic food processing corridor sustains volume concentration here.
- Granules:Free-flowing agglomerated particles reduce dust exposure during manual handling operations in smaller-scale foodservice environments.
- Paste:High-viscosity suspensions serve niche applications in marzipan and fondant production where moisture control is critical.
Volume placements concentrate in Powder; the faster expansion belongs to Liquid.
Application:
Reformulation mandates across customer tiers are segmenting demand by thermal processing tolerance and pH stability requirements.
- Beverages:Carbonated soft drinks, sports drinks, and flavored waters require hue consistency under acidic conditions and pasteurization. India's organized retail supply chain and Thai export-oriented bottlers drive procurement.
- Confectionery:Hard candies, gummies, and compressed tablets demand heat-stable colorants surviving elevated temperatures during cooking and depositing. Germany and Poland show accelerated dual-sourcing behavior ahead of REACH uncertainty.
- Dairy Products:Flavored milk and yogurt applications need compatibility with protein matrices and refrigerated distribution.
- Bakery:Frostings, fillings, and decorative coatings prioritize light-fastness over thermal extremes.
Procurement scale tilts toward Beverages; Confectionery shows the steepest certification premium capture.
End User:
Centralized technical purchasing is consolidating decision authority away from plant-level buyers toward qualified supplier rosters.
- Food Manufacturers:Integrated processors of multiple categories negotiate multi-year colorant contracts with batch traceability guarantees. India's expanding domestic capacity anchors this segment.
- Beverage Industry:Dedicated drink producers specify liquid formats with automated dosing compatibility and FDA certification documentation for export eligibility.
- Retailers:Private-label program managers enforce supplier qualification protocols excluding uncertified dye sources.
- Foodservice:Distributors to commercial kitchens and bakeries purchase smaller pack sizes with less stringent certification requirements.
Contract value aggregates with Food Manufacturers; Beverage Industry climbs the fastest on automation-driven specification tightening.
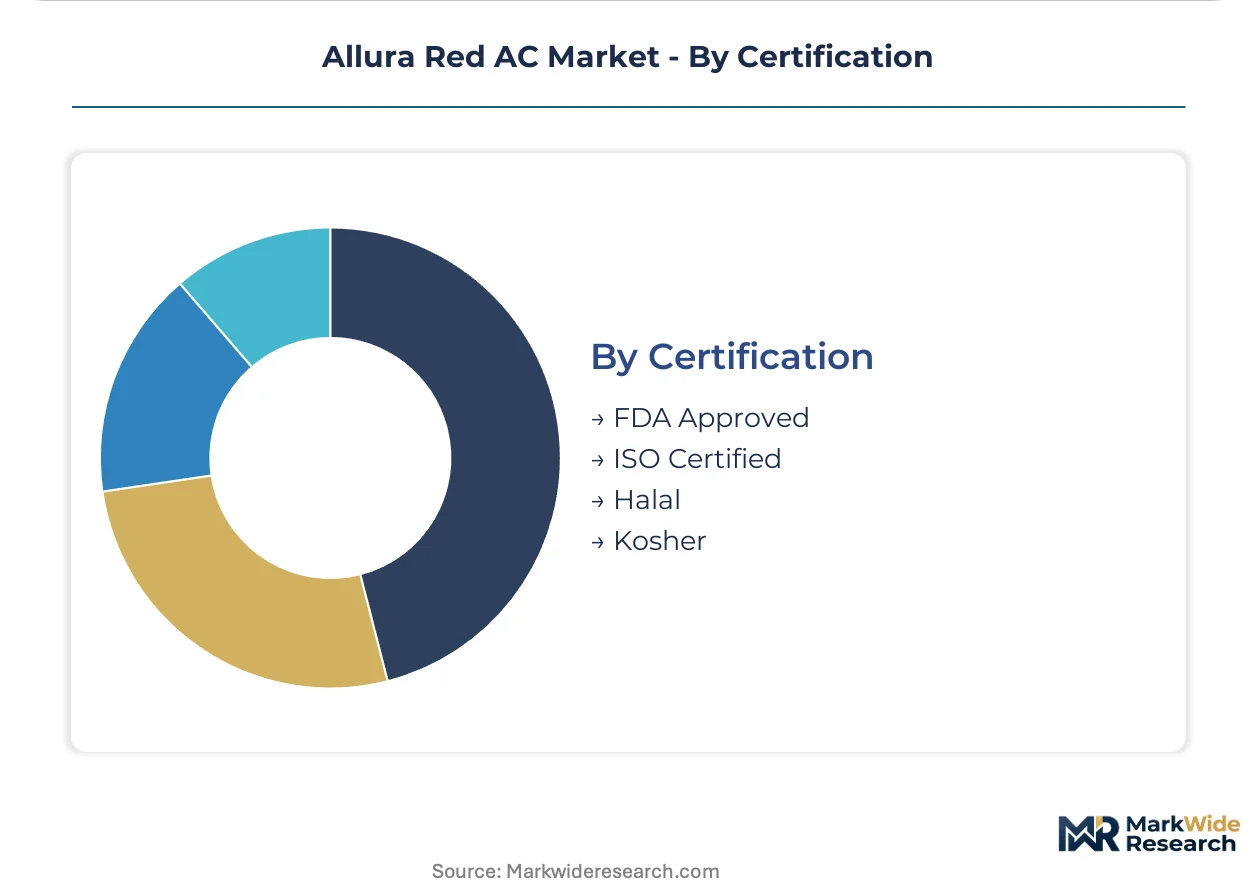
Certification:
Regulatory divergence between import jurisdictions is stratifying margin pools by compliance investment level.
- FDA Approved:Batch-certified grades under 21 CFR 74.340 command premium positioning for US-bound shipments, with certification queue delays extending lead times and favoring pre-certified inventory holders.
- Halal:Sharia-compliant manufacturing protocols unlock Middle Eastern and North African export corridors where import gatekeeping intensifies.
- Kosher:Rabbinical supervision requirements serve Orthodox Jewish consumer segments and parallel export channels.
- ISO Certified:Quality management system verification provides baseline assurance for industrial buyers without religious or jurisdiction-specific mandates.
Revenue concentration sits with FDA Approved; Halal certification gains share fastest on export corridor expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement volume for Allura Red AC as domestic food processing capacity and export-oriented production scale in parallel. The United States and Germany anchor certification-premium demand through strict regulatory gatekeeping. Thailand and Mexico emerge as automation-driven growth corridors for liquid format adoption.
India
FSSAI enforcement of maximum permissible limits for synthetic colors redirects domestic processors toward certified suppliers with documented batch traceability. The regulator's tightening compliance framework excludes uncertified imports from organized retail supply chains. Maharashtra and Gujarat host expanding manufacturing clusters where private-label beverage producers enforce supplier qualification protocols.
United States
FDA batch certification requirements under 21 CFR 74.340 extend lead times for US-bound shipments, favoring pre-certified inventory holders. The certification queue bottlenecks create procurement advantages for established suppliers with dedicated compliance infrastructure. Texas and California beverage bottlers drive liquid format specification tightening through automated dosing system investments.
Germany
REACH authorization timelines for aromatic amine derivatives compress European supply security, accelerating dual-sourcing strategies among confectionery processors. EFSA's periodic azo dye safety assessments create regulatory uncertainty that favors compliant non-EU producers. The industrial corridor across North Rhine-Westphalia and Bavaria shows intensified stockpiling behavior ahead of potential substance restrictions.
Thailand
Export-oriented contract beverage manufacturers serving FDA-scrutinized markets concentrate demand for certified liquid colorants with automated dosing compatibility. The country's national food regulator enforces alignment with international import standards for processed food exports. Bangkok and surrounding provinces anchor carbonated drink production lines where precision metering infrastructure displaces legacy powder-handling systems.
Mexico
Major dairy and savory processors pilot microencapsulated Allura Red AC variants at commercial scale for UHT-treated beverage applications. The national health regulator maintains import parity requirements that favor certified colorant grades for cross-border supply chains. Central Mexico's food manufacturing belt shows accelerated adoption of heat-stable encapsulated formats for aggressive thermal processing regimes.
Allura Red AC Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue certification-specialized positioning and microencapsulation technology licensing. The supplier base stratifies across integrated color platforms, regional manufacturing specialists, and excipient-crossover players. Three archetypes dominate: multinational platform operators with batch certification infrastructure, geography-anchored specialists serving Halal and Kosher export corridors, and diversified ingredient houses leveraging adjacent pharmaceutical coating expertise. Competitive moves concentrate on backward integration into aromatic amine precursors and long-term contracting with centralized technical purchasing teams.
Within the certification-specialist tier, Vidhi Specialty Food Ingredients Limited and Dynemic Products Limited exemplify regional manufacturing depth anchored in India's domestic processing corridor. Sensient Technologies Corporation represents the integrated platform archetype with sustained positioning in regulated food brand supply chains. These three entities illustrate the competitive spectrum from geographic concentration to multi-jurisdictional compliance infrastructure.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Vidhi Specialty Food Ingredients Limited |
| Sensient Colors LLC |
| Vinayak Ingredients (India) Pvt. Ltd. |
| Dynemic Products Limited |
| Sensient Technologies Corporation |
| Symrise AG |
| DIC Corporation |
| Chr. Hansen Holding A/S |
| Others |
Value Chain & Pricing Dynamics
Beverage automation specifications are forcing powder-to-liquid format conversions that compress supplier margins and concentrate pricing power among pre-certified inventory holders. India's FSSAI enforcement redirects procurement toward documented batch traceability, elevating certification premiums over standard industrial grades.
Pricing Analysis
Volume placements concentrate in powder grades where India's domestic food processing corridor sustains commodity-scale transactions; margins concentrate in liquid variants and encapsulated formats where beverage automation and heat-stability specifications command technical premiums. Three-tier pricing structure separates FDA-certified from Halal-certified from standard industrial grades, with certification queue delays under 21 CFR 74.340 extending lead times and favoring established compliance infrastructure. Cost compression in standard powder grades stems from naphthalene derivative feedstock volatility, while beverage processors show least price sensitivity for automated dosing-compatible liquid solutions.
Supply Chain Analysis
Reverse-logistics flows for batch-certified colorants remain minimal given food-grade contamination protocols, though pharmaceutical excipient crossover applications are piloting returnable container systems for generic drug coating operations. Manufacturing concentrates in India, China, and Germany, with aromatic amine precursors drawing from petrochemical complexes in the US Gulf Coast and Northeast Asia. Single-source vulnerability runs through diazotization intermediate suppliers without backward integration into naphthalene derivatives. Distribution runs through qualified supplier rosters serving centralized technical purchasing teams at multinational beverage and confectionery houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation technology is displacing unprotected azo dye deployment in thermal processing environments, compressing the technical advantage window of natural alternatives and reshaping supplier capability requirements.
For Market Incumbents: Hedge against natural colorant substitution in premium confectionery by deepening microencapsulation R&D partnerships with modified starch and gum arabic shell suppliers. Secure long-term offtake agreements with aromatic amine precursor producers to defend margin position against naphthalene derivative volatility. Prioritize backward integration into petrochemical feedstocks where feasible. For New Entrants and Emerging Players: Enter via Southeast Asian contract manufacturing corridors in Vietnam and Indonesia, where FDA-certified colorant demand from export-oriented processors outpaces domestic supply capacity. Target pharmaceutical excipient crossover applications for tablet coating, where distinct certification pathways and lower incumbent concentration create white-space opportunity. Pursue licensing arrangements for microencapsulation technology rather than greenfield R&D investment. For Investors and Strategic Acquirers: The window for entry favors certification-specialist manufacturers with Halal and Kosher infrastructure serving Middle Eastern and North African export corridors. Long-term viability hinges on regulatory compliance scalability across multiple jurisdictions rather than single-market dominance. Monitor EFSA azo dye reauthorization timelines as inflection indicator for European supply disruption scenarios that would advantage compliant non-EU producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Amine Precursors | Captive supply of naphthalene derivatives insulates margin stability from petrochemical pricing volatility. |
| Microencapsulation Technology Licensing | Modified starch and gum arabic shell partnerships enable UHT beverage and extruded snack market entry. |
| Halal and Kosher Certification Expansion | Sharia-compliant and rabbinical supervision protocols unlock Middle Eastern and North African import corridors. |
| Long-term Supply Agreements with Beverage Multinationals | Centralized technical purchasing consolidation favors qualified supplier rosters with batch traceability guarantees. |
| Pharmaceutical Excipient Crossover Development | Tablet coating applications for generic drug manufacturing diversify revenue beyond food-grade colorant dependence. |
Study Parameters
Regulatory filings, customs trade databases, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with plant managers at synthetic dye manufacturing facilities, procurement leads at downstream beverage and confectionery OEMs, distribution channel partners specializing in food ingredients, and technical R&D directors overseeing colorant formulation. Bottom-up volume modeling triangulated against top-down market sizing derived from FSSAI enforcement records, FDA batch certification queues, and EFSA safety assessment timelines.
Historical trendline analysis established baseline growth patterns across powder, liquid, granule, and paste format segments, with projection modeling incorporating certification tier stratification, application-specific thermal stability requirements, and end-user automation adoption curves. CAGRs were derived from segmented demand elasticity analysis rather than simple extrapolation. Forecast inputs included aromatic amine feedstock pricing indices, beverage processing equipment replacement cycles, and pharmaceutical excipient regulatory pathway timelines.
Revisions become necessary when REACH authorization timelines for aromatic amine derivatives accelerate, when FDA batch certification bottlenecks extend beyond current queue patterns, or when EFSA azo dye safety assessments trigger reformulation mandates. Practitioners should monitor regulatory divergence between jurisdictions, microencapsulation technology licensing activity, and centralized purchasing consolidation patterns for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Liquid Silage Additive Market
Additives
Viscosity Reducing Agents Market
Additives
China Citric Acid Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Isopropyl Acetate Market
Additives
South America Concrete Admixtures Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Foundry Additives Market
Additives
Sodium Caprylate Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Global Rheology Modifiers Market
Additives
Adjustive Agents Market
Additives
Global Pour Point Depressant Market
Additives
Plastic Fillers Market
Additives
Anti-Settling Agents Market
Additives
Global Isosorbide Market