
 South America Sodium Reduction Agents Market | 2026-2036
South America Sodium Reduction Agents Market Size, Share, and Industry Trends Forecast 2026-2036
South America Sodium Reduction Agents Market Analytics
Advanced microencapsulation of potassium chloride is reshaping how sodium reduction agents deliver taste stability in high-moisture processed foods. Cargill Inc. leverages its regional grain processing infrastructure to secure backward integration into potassium salt sourcing. Kerry Group PLC anchors its position through specialized flavor masking systems that compete with standard mineral salt offerings.
Sodium reduction agents comprise mineral salts, yeast extracts, and amino acid-based formulations engineered to replicate sodium chloride's osmotic and flavor functions in food matrices. Potassium chloride dominates volume due to its ionic similarity to sodium, though bitter aftertaste challenges require companion technologies. Natural extracts represent the fastest-growing structural segment as clean-label mandates from Brazilian and Argentine processors shift procurement away from synthetic mineral blends. The application split tilts heavily toward processed foods, where sauces and snacks absorb reformulation investment driven by retail channel pressure.
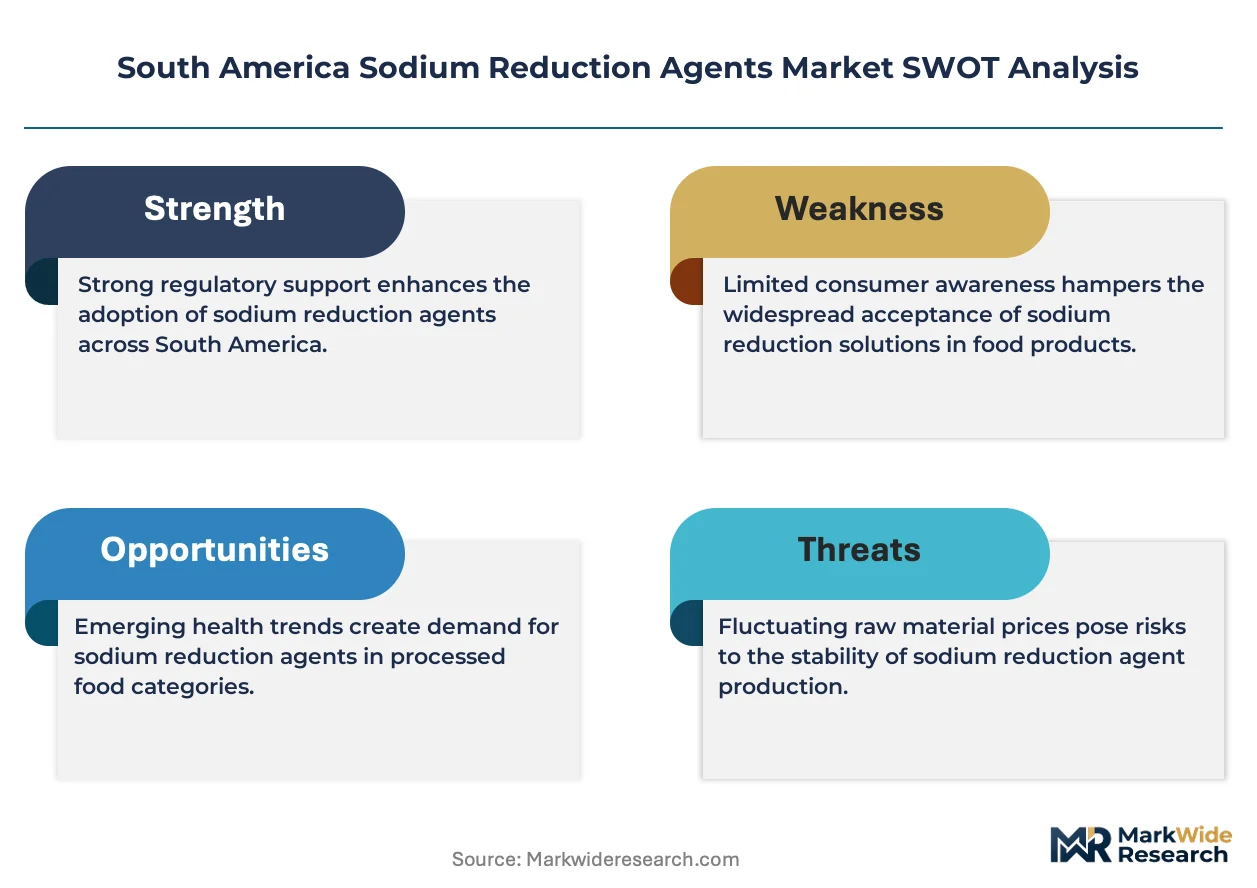
ANVISA's updated nutritional labeling rules and Argentina's national sodium reduction program create compliance-driven demand across the Mercosur trade zone. Brazil's Ministry of Health front-of-package warning seals force reformulation timelines that outpace voluntary industry commitments. Stakeholders must monitor regulatory divergence between national health agencies and sub-national municipal procurement standards that increasingly restrict sodium in institutional foodservice contracts.
Market Dynamics
ANVISA's front-of-package warning seal mandates are compressing reformulation timelines for Brazilian processed food manufacturers, forcing immediate procurement of flavor-masked potassium chloride blends.
Growth Catalysts
- ANVISA Warning Seal Mandates:Brazil's Ministry of Health labeling rules accelerate sodium reduction agent adoption across sauce and snack manufacturing corridors.
- Potassium Chloride Microencapsulation:Advanced coating technologies now eliminate bitter aftertaste in high-moisture food matrices without companion additives.
- Mercosur Regulatory Alignment:Argentina's national sodium reduction program creates cross-border procurement standardization for regional food exporters.
Market Restraints
- Potassium Salt Supply Concentration:Chilean and Argentine brine operations control upstream mineral feedstock, exposing formulators to Andean supply disruptions.
- Flavor Masking Cost Premium:Yeast extract and amino acid companion technologies add 15-30% formulation cost versus standard mineral salts.
- Clean-Label Certification Friction:Brazilian organic certifiers maintain inconsistent standards for processed mineral-derived ingredients versus natural extracts.
Strategic Opportunities
- Colombian Institutional Foodservice:Municipal school procurement contracts in Bogotá and Medellín increasingly specify sodium limits, opening public sector demand.
- Yeast Extract-Natural Extract Convergence:Hybrid formulations combining fermented umami compounds with botanical extracts address clean-label and performance requirements simultaneously.
- E-commerce Direct Procurement:Mid-size Brazilian bakeries and meat processors now source sodium reduction agents through B2B platforms, bypassing traditional distributor markups.
Industry Challenges
- Food Technologist Talent Scarcity:Brazilian universities produce insufficient formulation specialists trained in salt replacer integration and sensory optimization.
- Legacy Equipment Retrofit Requirements:Minas Gerais meat processing facilities require capital-intensive line modifications to handle hygroscopic potassium chloride blends.
- ANVISA Compliance Timeline Compression:Six-month reformulation windows strain R&D cycles for small and mid-size sauce manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Sodium Reduction Agents Market |
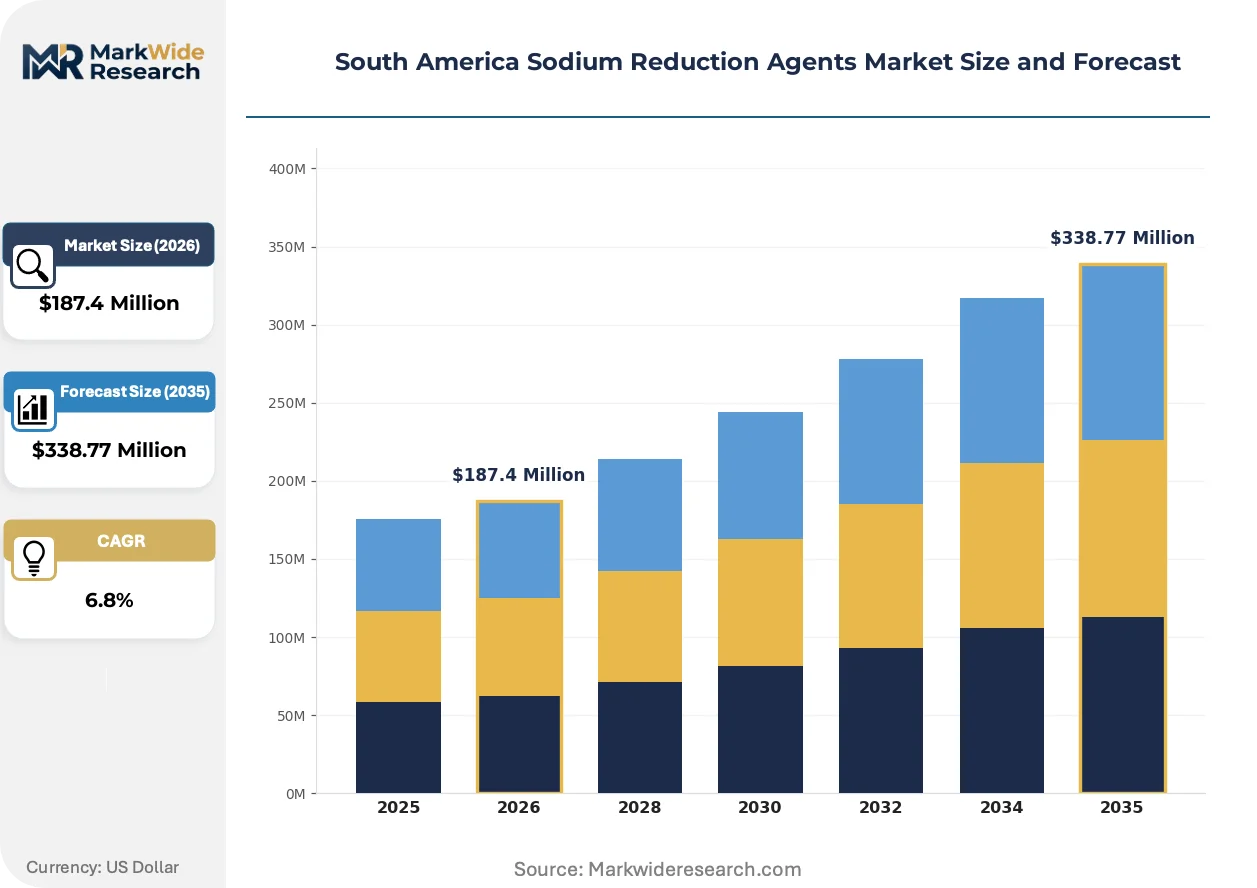
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Chloride, Calcium Salt, Magnesium Salt, Natural Extracts Application: Processed Foods, Sauces, Snacks, Dairy Products End User: Food & Beverage Manufacturers, Restaurants, Retailers, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Cargill Inc., Tate & Lyle PLC, Givaudan SA, Kerry Group PLC, Corbion NV, Sensient Technologies Corporation, Archer Daniels Midland Company, DSM NV, Innophos Holdings, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Sodium Reduction Agents Market Evolving Landscape
Microencapsulation chemistry and fermentation-derived umami systems are displacing conventional mineral salt blends across South American processed food manufacturing.
Multi-layer lipid encapsulation of potassium chloride is rendering obsolete traditional single-coat formulations in Brazilian high-moisture sauce applications. São Paulo-based condiment manufacturers now specify spray-dried lipid matrices that withstand retort processing without bitter ion release. This structural shift compresses demand for standalone flavor masking additives.
ANVISA's updated nutritional labeling resolution forces explicit sodium disclosure on processed food packaging, compelling reformulation across Brazil's southeastern industrial corridor. Argentine food exporters to Brazil must now synchronize formulations with Mercosur-wide standards. Sauce and ready-meal segments absorb the highest compliance investment.
Direct technical service relationships between ingredient suppliers and mid-size meat processors are displacing traditional distributor-led sales models in Brazil. Curitiba and Porto Alegre sausage manufacturers now demand on-site formulation support during product redevelopment. This behavioral shift concentrates procurement influence with technical-capable suppliers.
South America Sodium Reduction Agents Market Segmentation
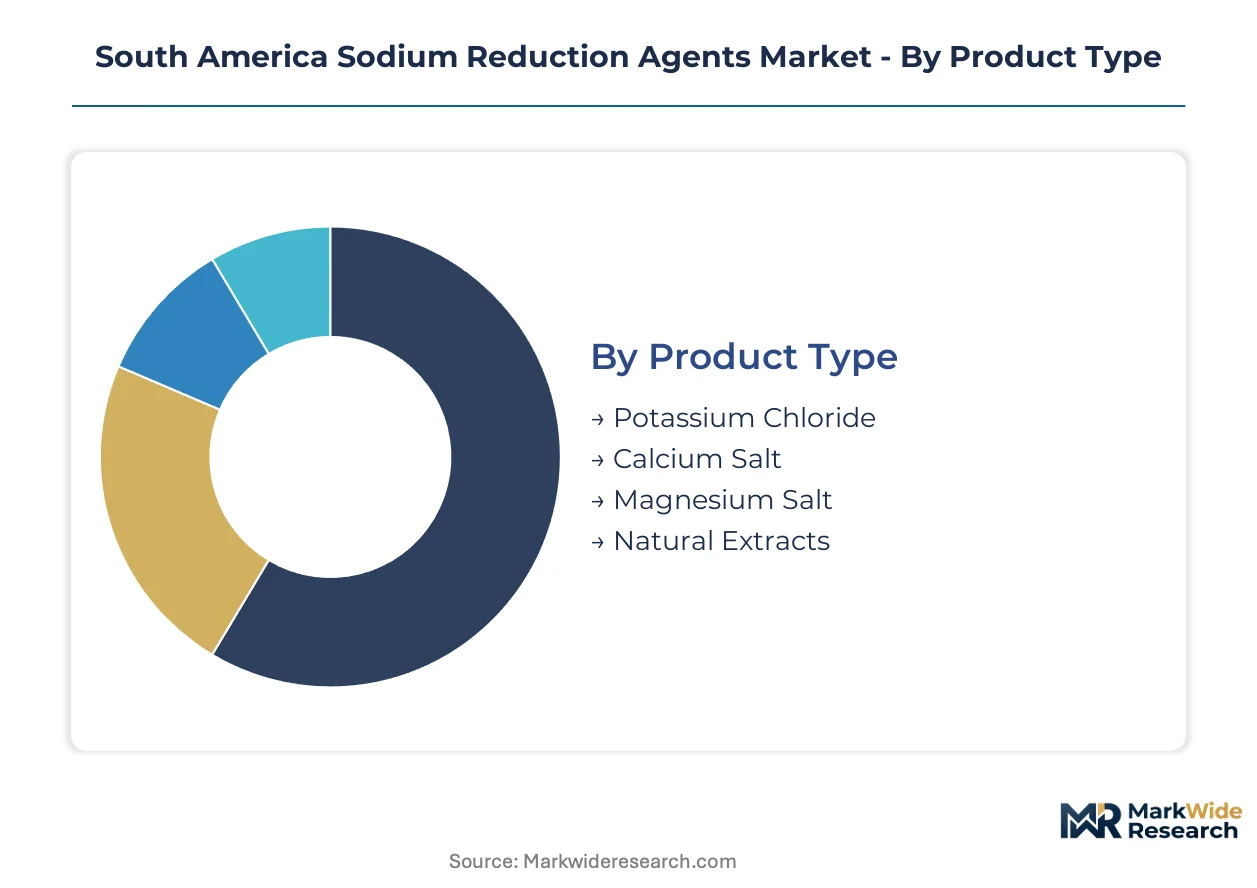
Sodium reduction agents serve distinct functional roles across South American food manufacturing, with formulation requirements varying sharply by moisture content, thermal processing intensity, and clean-label positioning. Procurement patterns diverge significantly between multinational processed food corporations and mid-size regional meat processors.
Product Type:
Technical service intensity concentrates around bitter-masking formulations, where supplier field support determines adoption success in high-volume sauce operations.
- Potassium Chloride:Ionic sodium replacement dominates volume through chloride-based osmotic functionality. São Paulo sauce manufacturers specify microencapsulated grades for retort-stable applications where ANVISA compliance deadlines compress reformulation windows.
- Natural Extracts:Botanical and fermentation-derived sodium replacers leverage clean-label positioning in Argentine organic exports. Brazilian organic certifiers maintain inconsistent standards, creating procurement friction for processors seeking dual-market access.
- Calcium Salt:Secondary mineral replacement with texture-modifying properties in low-moisture snack matrices.
- Magnesium Salt:Niche hydration-control functionality in cured meat applications across Minas Gerais processing corridors.
Potassium chloride holds the largest share; momentum sits with natural extracts.
Application:
Reformulation investment intensity tracks directly with front-of-package warning seal exposure in Brazilian retail channels.
- Processed Foods:Ready-meal and convenience food segments absorb the highest compliance-driven R&D expenditure. ANVISA's six-month reformulation timelines strain small and mid-size manufacturers in Brazil's southeastern industrial corridor.
- Sauces:High-moisture matrices demand advanced encapsulation to prevent bitter ion release during thermal processing. Spray-dried lipid matrices from São Paulo suppliers now displace traditional single-coat formulations.
- Snacks:Dry-seasoning applications favor potassium chloride blends with lower technical service requirements.
- Dairy Products:Fermented dairy matrices in Argentine export operations require specialized flavor masking systems.
Processed foods command the greatest reformulation spend; sauces are climbing the fastest on encapsulation innovation.
End User:
Procurement scale and technical capability split sharply between industrial formulators and foodservice operators.
- Food & Beverage Manufacturers:Multinational and regional processors drive specification standards through direct technical service relationships. Curitiba and Porto Alegre sausage manufacturers now demand on-site formulation support during product redevelopment.
- Restaurants:Chain operators in Bogotá and Medellín face municipal sodium limits in institutional procurement contracts.
- Retailers:Private-label reformulation pressure transmits through supplier quality agreements.
- Households:Direct consumer sales remain minimal outside specialty health retail channels.
Food and beverage manufacturers dominate procurement volume; restaurants are gaining share fastest on institutional contract specifications.
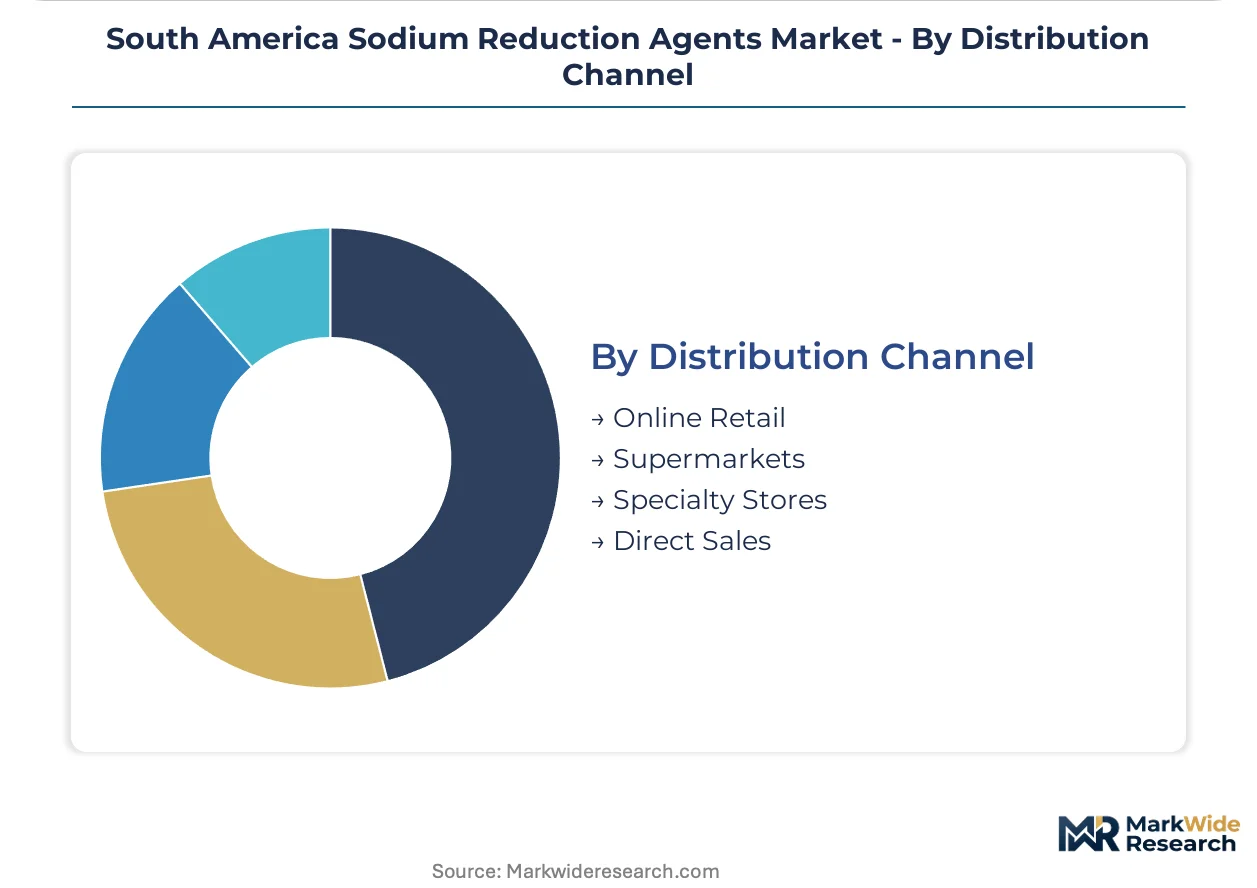
Distribution Channel:
Channel selection reflects customer scale and technical support requirements across the Mercosur trade zone.
- Direct Sales:Technical-capable suppliers anchor relationships through on-site formulation support for mid-size meat processors. This model concentrates influence with suppliers possessing sensory optimization capabilities.
- Online Retail:B2B platforms enable mid-size Brazilian bakeries and meat processors to bypass traditional distributor markups. E-commerce direct procurement is expanding most quickly in São Paulo state's independent processing sector.
- Supermarkets:Limited to small-scale household and artisanal processor purchases.
- Specialty Stores:Natural extracts and clean-label formulations for organic-certified operations.
Direct sales maintain the largest channel position; online retail shows the steepest expansion trajectory on platform-enabled procurement disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented food manufacturers across South America face divergent sodium compliance requirements between Mercosur members and external markets. Cross-border formulation standardization is accelerating as Brazilian ANVISA rules become the de facto regional benchmark for processed food exporters.
Brazil
Southeastern industrial corridors in São Paulo and Minas Gerais absorb the highest reformulation investment as ANVISA's front-of-package warning seals compress compliance timelines to six months. The Ministry of Health mandates explicit sodium disclosure on processed food packaging. Curitiba and Porto Alegre sausage manufacturers now demand direct technical service relationships with ingredient suppliers during product redevelopment cycles.
Argentina
National sodium reduction program requirements synchronize export formulations with Brazilian Mercosur standards for cross-border food trade. The country's national food safety regulator enforces alignment with regional labeling protocols. Buenos Aires and Córdoba organic food processors face procurement friction as Brazilian certifiers maintain inconsistent standards for mineral-derived versus natural extract ingredients.
Chile
Upstream potassium salt brine operations in northern mining regions control critical mineral feedstock for regional formulators. The country's national health agency supports sodium reduction through voluntary industry commitments rather than mandatory seals. Santiago-based condiment manufacturers source advanced microencapsulated potassium chloride from Brazilian suppliers to meet export specifications.
Colombia
Municipal procurement contracts in Bogotá and Medellín institutional foodservice sectors increasingly specify hard sodium limits for school feeding programs. The national health ministry's guidelines create compliance-driven demand independent of Mercosur regulatory frameworks. Medellín-based bakery chains are expanding direct B2B platform procurement of sodium reduction agents to bypass traditional distributor channels.
Peru
Lima's processed food manufacturing base serves as a secondary demand node for potassium chloride blends targeting export markets rather than domestic regulatory compliance. The country's national food safety authority maintains less stringent sodium labeling requirements than Brazilian or Argentine counterparts. Arequipa snack manufacturers prioritize cost-competitive mineral salt formulations over advanced encapsulation technologies for domestic product lines.
South America Sodium Reduction Agents Market Competitive Landscape
On the supply side, the industry is consolidating around technical-capable suppliers capable of delivering on-site formulation support and sensory optimization services. Mid-size regional processors now bypass traditional distributors to establish direct procurement relationships with ingredient specialists. Two strategic archetypes dominate: multinational agricultural conglomerates with backward integration into mineral salt sourcing, and specialized flavor technology firms with proprietary masking systems. Competitive moves concentrate on capacity expansion in microencapsulation facilities and strategic partnerships with regional meat processing clusters.
Within the multinational agricultural tier, Cargill Inc. and Archer Daniels Midland Company represent integrated supply chain positioning with captive access to upstream potassium feedstock. Kerry Group PLC and Givaudan SA exemplify the flavor technology specialist archetype, anchoring competitive positions through sensory optimization capabilities rather than mineral sourcing control. These groupings illustrate how supplier selection criteria now prioritize technical service depth over commodity pricing in reformulation-intensive market segments.
| Leading Market Players |
|---|
| Cargill Inc. |
| Tate & Lyle PLC |
| Givaudan SA |
| Kerry Group PLC |
| Corbion NV |
| Sensient Technologies Corporation |
| Archer Daniels Midland Company |
| DSM NV |
| Innophos Holdings |
| Others |
Value Network & Pricing Analysis
Chilean and Argentine brine operations controlling upstream potassium feedstock concentrate margin capture with regional formulators downstream. São Paulo sauce manufacturers absorb cost premiums for microencapsulated grades as ANVISA compliance deadlines compress procurement leverage.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for standard mineral salt grades. Price differentiation separates ANVISA-certified microencapsulated formulations from commodity potassium chloride on technical service bundling and certification tier. Cost compression in standard mineral blends is intensifying as mid-size Brazilian processors migrate to B2B platform procurement. Small and mid-size sauce manufacturers exhibit highest price sensitivity; multinational food corporations prioritize performance stability over unit cost.
Supply Chain Analysis
Potassium chloride feedstock draws from Chilean northern mining regions and Argentine brine operations, with secondary sourcing from Brazilian domestic processors. Upstream dependencies rest on mineral extraction equipment, lipid encapsulation chemistries, and spray-drying infrastructure. Single-source vulnerability concentrates in Andean brine supply corridors exposed to geological disruption and export licensing variability. Distribution runs through direct technical service relationships for large processors, with B2B platforms disintermediating traditional distributors for mid-size buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against yeast extract and amino acid formulations displacing mineral salts in clean-label positioning. Incumbents must navigate divergent certification standards between Brazilian and Argentine organic regulators that fragment procurement specifications.
For Market Incumbents: Insulate market position through captive backward integration into Chilean brine assets or Argentine salt flat concessions. Prioritize microencapsulation capacity expansion in São Paulo state's southeastern industrial corridor to compress reformulation service delivery timelines. Defend against natural extract substitutes by embedding sensory optimization capabilities that commodity mineral suppliers cannot replicate.
For New Entrants and Emerging Players: Establish a beachhead in Colombian institutional foodservice procurement, where Bogotá and Medellín municipal sodium limits create compliance-driven demand absent entrenched supplier relationships. Target mid-size Brazilian bakeries and meat processors through B2B platform direct sales, bypassing distributor markups that inflate incumbent pricing. Lead with hybrid yeast extract-botanical formulations that satisfy simultaneous clean-label and performance requirements.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flavor technology specialists possessing proprietary masking systems but lacking mineral sourcing integration. Long-term viability hinges on technical service density rather than commodity scale, favoring platforms with embedded formulation support capabilities. Monitor ANVISA enforcement variance across Brazil's sub-national municipal procurement standards as an inflection signal for compliance-driven demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Capacity Expansion | São Paulo facilities enable retort-stable potassium chloride delivery for ANVISA-compliant sauce reformulation. |
| Backward Integration into Brine Assets | Chilean and Argentine salt flat control secures upstream feedstock against Andean supply disruption. |
| Hybrid Formulation Development | Yeast extract-botanical convergence addresses Brazilian-Argentine certification divergence for dual-market access. |
| B2B Platform Direct Procurement | Disintermediation of traditional distributors captures margin compression in mid-size processor segments. |
| Technical Service Relationship Anchoring | On-site sensory optimization at Curitiba and Porto Alegre meat processors locks in specification influence. |
Research Methodology
A standing panel of food technology directors, ANVISA regulatory affairs specialists, procurement leads at multinational processed food corporations, and sensory scientists provided ongoing calibration across primary fieldwork. Secondary validation drew from ANVISA regulatory filings, Brazilian Ministry of Health labeling resolutions, Mercosur trade documentation, and customs import records for potassium salt feedstock. Bottom-up demand modeling from individual processor reformulation timelines was triangulated against top-down market sizing from regional ingredient distributor channel checks.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation dimensions spanning product type, application moisture content, clean-label positioning, and end-user technical capability tier. CAGRs were derived from elasticity-adjusted adoption curves calibrated to ANVISA compliance deadline impacts. Forecast inputs incorporated municipal procurement specification trajectories in Colombian institutional foodservice and microencapsulation technology diffusion rates among São Paulo condiment manufacturers.
Stress conditions across Andean supply disruption severity, ANVISA enforcement acceleration, and natural extract substitution velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory timeline adherence and technology cost curves. Cross-checking against Brazilian food industry association reformulation expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Micronized Powder Market
Additives
Isobutyl Acetate Market
Additives
Battery Additives Market
Additives
Global Caprylhydroxamic Acid Market
Additives
North America Phosphate Esters Market
Additives
Anti-Creasing Agent Market
Additives
Spain Anti Caking Market
Additives
Global Chelated Trace Minerals Market
Additives
Trioctyldodecyl Citrate Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Calcium Diglutamate Market
Additives
Driveline Additives Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
United Kingdom Feed Additives Market
Additives
Defoaming Coating Additives Market
Additives
Automotive Additives Market