
 Global Pine-Derived Chemicals Market | 2026-2036
Global Pine-Derived Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pine-Derived Chemicals Market Foresight
The pine-derived chemicals industry is restructuring around a widening split between high-purity specialty grades and standardized commodity outputs. Kraton Corporation leverages captive distillation capacity to secure consistent rosin derivative supply across North American adhesive markets. Eastman Chemical Company anchors its position through backward integration into crude tall oil refining, while Ingevity Corporation specializes in performance resins for pavement and industrial binders.
Pine-derived chemicals comprise secondary metabolites extracted from softwood biomass, primarily encompassing terpenes, resin acids, and fatty acids with boiling points spanning 150–350°C, serving as renewable feedstocks for adhesives, coatings, and surfactant synthesis. Turpentine fractions lead volume throughput due to established naval stores infrastructure, though tall oil derivatives command superior margins through integration into alkyd resins and lubricant esters. Rosin-based segments compete aggressively in printing ink formulations where Chinese and Brazilian producers dominate cost structures.
EPA biomass-based diesel quotas under the Renewable Fuel Standard, REACH registration requirements for turpentine monomers in Europe, and China's GB standards for pine oil purity collectively shape product specifications and cross-border trade flows. FDA oversight of rosin derivatives in food-contact adhesives adds compliance layers for packaging sector suppliers. Stakeholders must monitor regulatory divergence between bio-based content mandates and chemical hazard classifications to align capacity investments with shifting certification requirements.
Market Dynamics
Adhesive manufacturers' procurement of bio-based feedstocks is compressing supply windows for crude tall oil and gum rosin, forcing chemical processors to secure multi-year offtake agreements with pulp mill operators before capacity expansions finalize.
Growth Catalysts
- REACH Registration Mandates:European ECHA requirements for turpentine monomer purity are filtering out low-grade suppliers and consolidating order flow toward certified refiners.
- US EPA Renewable Fuel Standard:Biomass-based diesel quotas are pulling tall oil fatty acids into fuel ester production, tightening availability for traditional chemical applications.
- China's GB Standards:National pine oil purity specifications are accelerating domestic distillation upgrades and redirecting export-grade volumes toward internal alkyd resin consumption.
Market Restraints
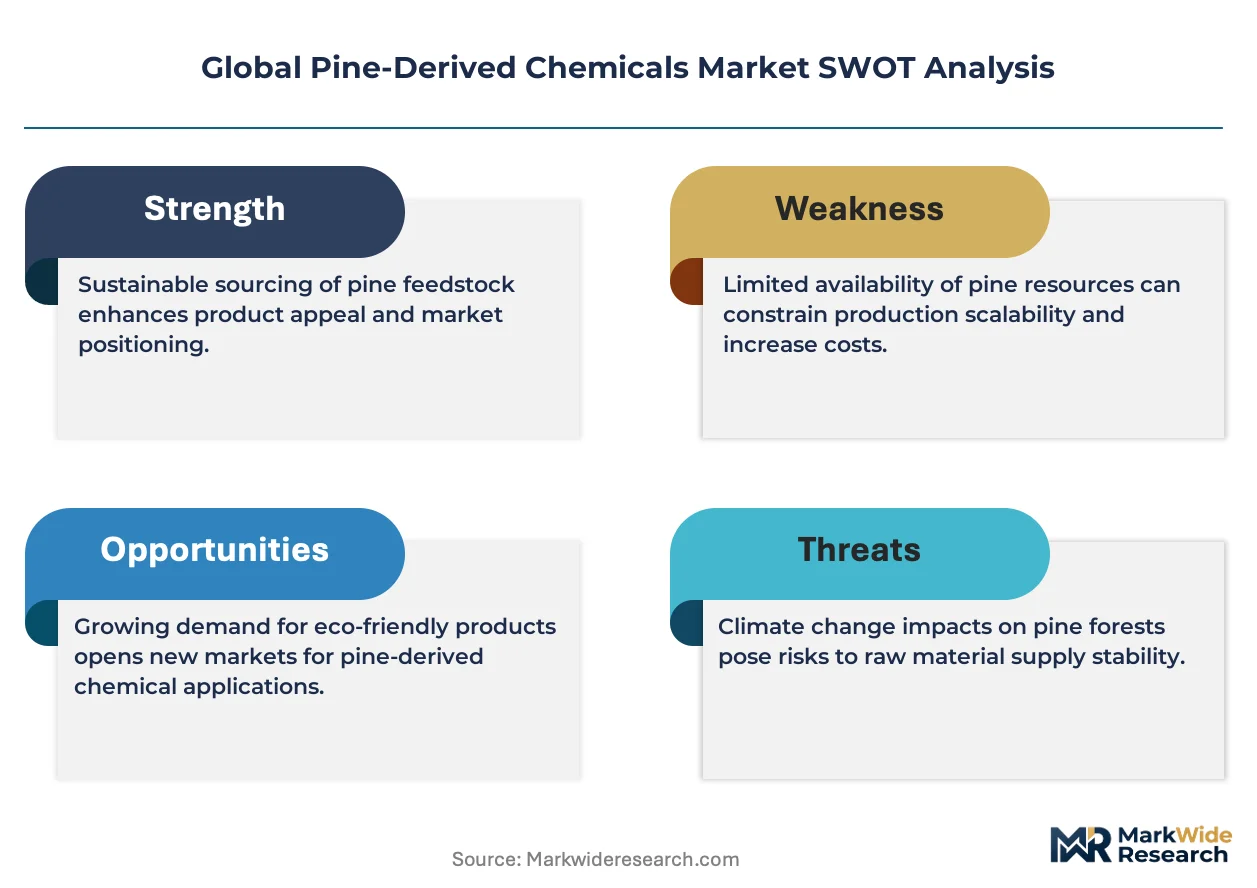
- Crude Tall Oil Supply Concentration:Scandinavian and US South pulp mill operators control 70% of global CTO extraction, creating bottleneck risk during maintenance cycles.
- Petroleum-Derived Substitute Pricing:Synthetic hydrocarbon resins from polyolefin feedstocks undercut rosin derivatives during crude oil price collapses.
- Seasonal Gum Rosin Collection:Brazilian and Indonesian tapping labor shortages constrain H1 resin acid availability regardless of downstream demand.
Strategic Opportunities
- India's BIS Certification Gap:Domestic pine chemical production remains below technical specification thresholds, creating import substitution potential for EU-compliant suppliers.
- Food-Contact Adhesive Tailwinds:FDA 21 CFR 175.105 compliance for rosin esters is opening packaging sector contracts previously held by petroleum-based hot melts.
- Metathesis Chemistry Convergence:Cross-coupling of terpene fractions with catalytic upgrading platforms is unlocking novel fragrance and pharmaceutical intermediate pathways.
Industry Challenges
- Distillation Skilled Operator Shortage:Fractionation facilities require ASME-certified technicians with naval stores experience, a workforce cohort nearing retirement density.
- REACH-EPA Divergence:Dual registration timelines for turpentine derivatives create 18-24 month product launch delays for multinational formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pine-Derived Chemicals Market |
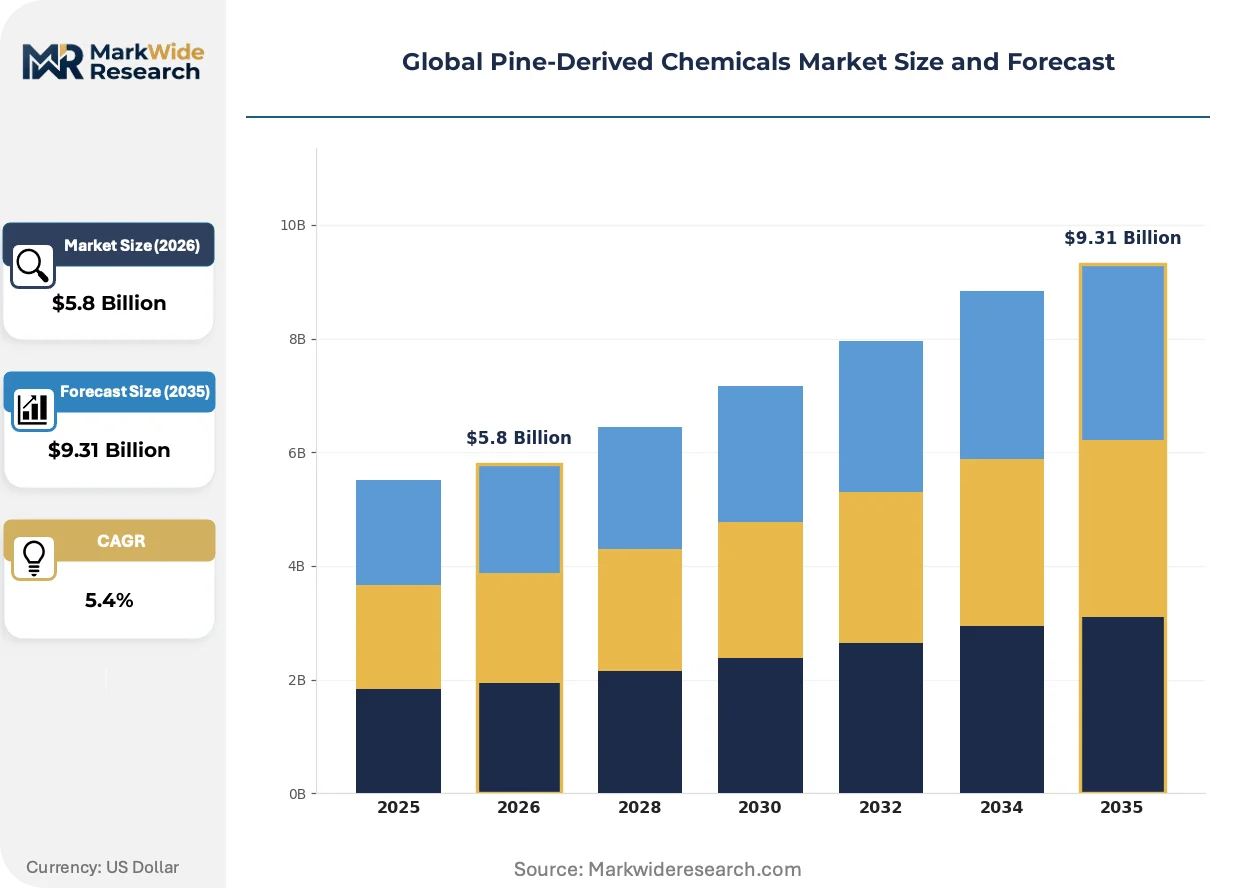
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.31 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
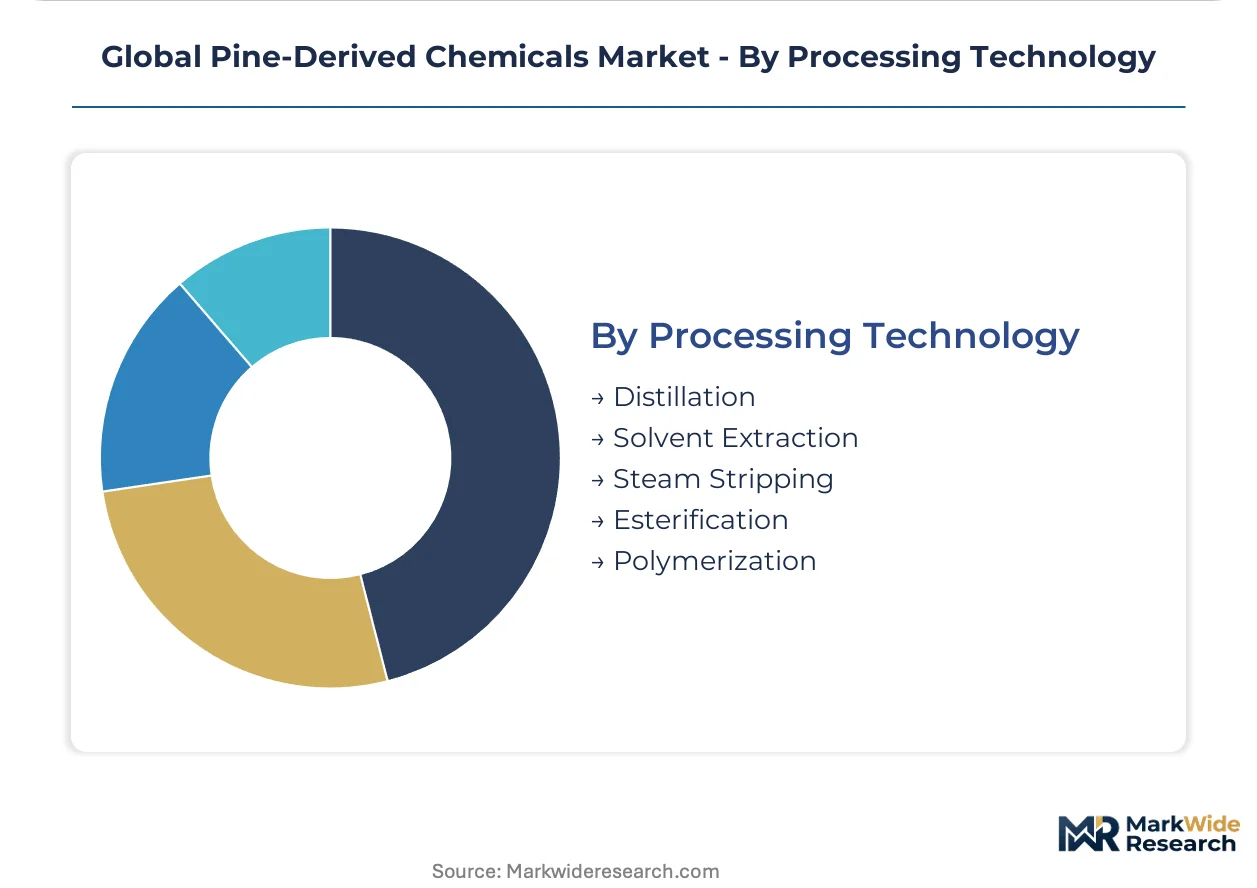
| Segmentation | Product Type: Turpentine, Rosin, Tall Oil, Pine Oil, Pine Resin Application: Adhesives, Paints & Coatings, Printing Inks, Detergents, Pharmaceuticals End User Industry: Packaging Manufacturers, Personal Care, Pulp & Paper, Chemical Processing, Textile Manufacturers Processing Technology: Distillation, Solvent Extraction, Steam Stripping, Esterification, Polymerization |
| Companies Covered | Kraton Corporation, Eastman Chemical Company, Ingevity Corporation, Harima Chemicals Group, Arakawa Chemical Industries, DRT, Florachem, Forforeverest Resources Ltd, Forchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pine-Derived Chemicals Market Shifts & Advancements
Continuous processing technology is displacing batch distillation across naval stores refining, while metathesis catalysis and supercritical extraction methods are opening molecular valorization pathways previously uneconomical at scale.
Supercritical CO2 extraction of pine bark and needles is electrifying terpene recovery yields beyond conventional steam distillation limits. Fragrance compounders in Grasse and Geneva are retrofitting extraction trains to handle pressurized solvent loops. The technology is electrifying margin structures for perfumery-grade isolates previously dominated by synthetic equivalents.
EU F-Gas Regulation phase-down schedules are restricting fluorinated blowing agents in polyurethane foams, redirecting formulators toward pine-derived surfactant alternatives. Foam producers in Germany and Poland are reformulating rigid insulation systems with tall oil-based polyols. Construction sector specification sheets are being rewritten to highlight bio-based carbon content thresholds.
Long-term offtake contracting is displacing spot market purchasing among North American adhesive compounders. Procurement departments at tape and label manufacturers are locking 36-month supply agreements with rosin derivative refiners. The shift is most visible in Wisconsin and Ohio packaging corridors where just-in-time inventory models are being abandoned for supply security.
Global Pine-Derived Chemicals Market Segmentation
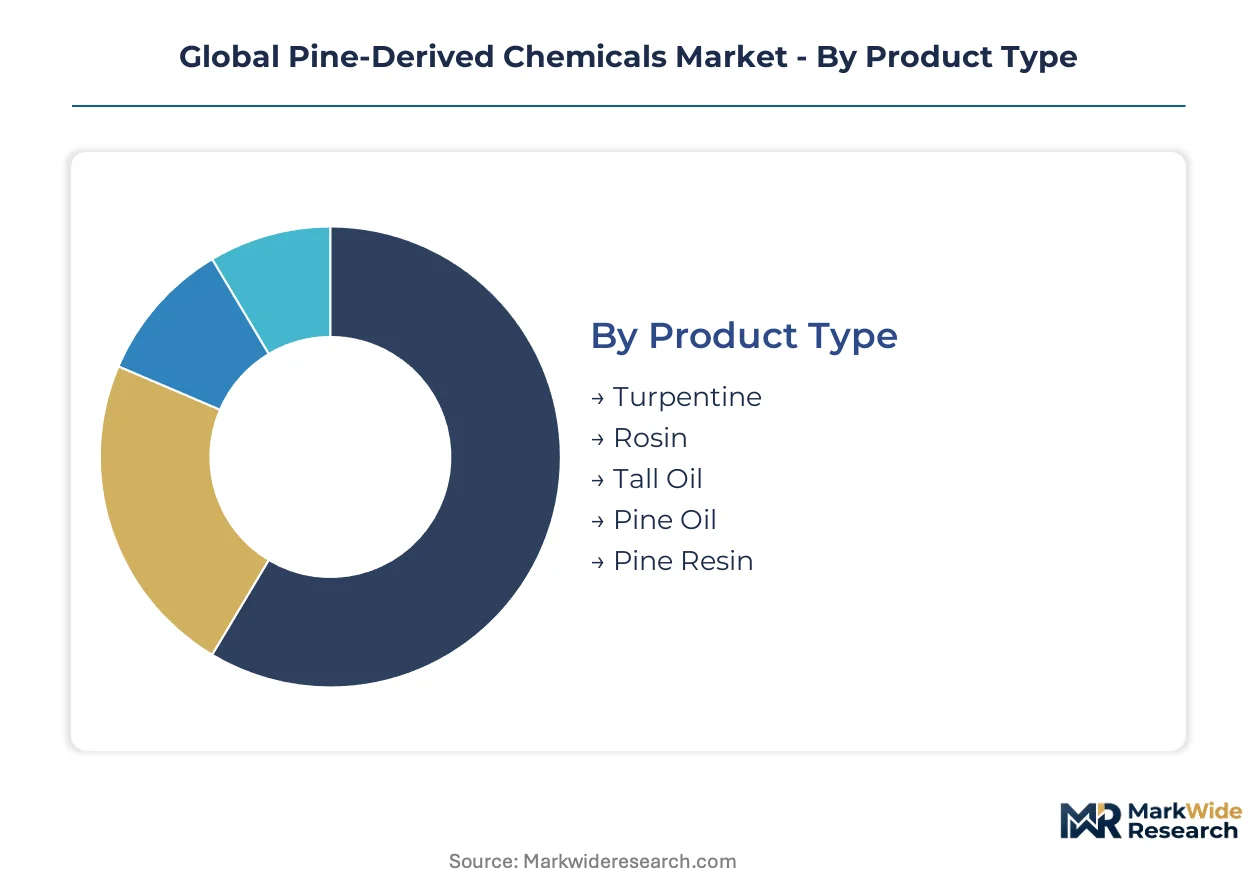
Pine-derived chemical procurement hinges on purity thresholds that diverge sharply between fuel ester markets and pharmaceutical-grade applications. Distillation capability and regulatory certification now outweigh price as primary supplier selection criteria across all major buying centers.
Product Type:
Buyers prioritize carbon chain length and resin acid concentration when matching feedstock to downstream reactivity requirements.
- Turpentine:A volatile terpene fraction extracted through steam distillation of pine oleoresin, yielding alpha-pinene and beta-pinene isomers with boiling points between 155-170°C. Naval stores infrastructure in the United States and Brazil channels volumes into fragrance synthesis and synthetic camphor production, though EPA biomass-based diesel quotas are diverting increasing quantities toward fuel ester applications.
- Tall Oil:A byproduct of kraft pulping containing fatty acids, resin acids, and unsaponifiables in varying proportions depending on wood species and digestion conditions. Scandinavian pulp mill operators in Finland and Sweden dominate extraction capacity, with Chinese alkyd resin manufacturers now absorbing export volumes previously destined for European lubricant ester producers.
- Rosin:Solid resin acids obtained from gum tapping or tall oil fractionation, classified by color grade from WW (water-white) to D (dark). Brazilian and Indonesian tapping labor constraints create seasonal availability gaps regardless of adhesive sector demand cycles.
- Pine Oil:A terpene alcohol mixture containing terpineol and borneol, valued for disinfectant and fragrance applications. Chinese GB standards for purity are accelerating domestic distillation upgrades and reducing export-grade availability.
- Pine Resin:Raw oleoresin collected from living trees, requiring immediate processing to prevent oxidation and viscosity degradation. Gum rosin collectors in Guangxi and Fujian provinces supply regional adhesive compounders with minimal international trade exposure.
Volume sits with tall oil derivatives; growth tilts toward turpentine fractions diverted into renewable fuel pathways.
Application:
End-use specifications divide markets between commodity-scale consumption and specialized performance requirements.
- Adhesives:Hot-melt and pressure-sensitive formulations consume disproportionate rosin ester volumes, with FDA 21 CFR 175.105 compliance opening food-contact packaging contracts previously held by petroleum-based alternatives. Wisconsin and Ohio tape manufacturers are locking multi-year supply agreements to secure against CTO availability constraints.
- Paints & Coatings:Alkyd resins and drying oil modifiers rely on tall oil fatty acid integration, with German and Polish construction sector specification sheets now highlighting bio-based carbon content thresholds.
- Printing Inks:Rosin-derived resins provide pigment wetting and vehicle compatibility, though Chinese and Brazilian producers dominate cost structures in publication gravure applications.
- Detergents:Tall oil fatty acids serve as surfactant precursors, with EU F-Gas Regulation phase-down schedules redirecting polyurethane foam formulators toward pine-derived polyol alternatives.
- Pharmaceuticals:Terpene isolates from supercritical CO2 extraction command premium pricing for active pharmaceutical intermediate synthesis, with Grasse and Geneva fragrance compounders retrofitting extraction trains for pressurized solvent loops.
Adhesives anchor current volume; pharmaceutical-grade terpene isolation offers the steepest expansion trajectory.
End User Industry:
Customer scale and technical capability determine whether procurement favors spot markets or integrated supply arrangements.
- Packaging Manufacturers:Tape, label, and corrugated board producers drive rosin ester consumption, with just-in-time inventory models giving way to 36-month supply security contracts across North American converting corridors.
- Pulp & Paper:Integrated kraft mills represent the primary tall oil extraction source, creating captive supply advantages for operators with in-house fractionation capacity.
- Chemical Processing:Specialty resin and surfactant refiners compete for limited CTO availability, with Kraton Corporation leveraging captive distillation to secure consistent derivative supply.
- Personal Care:Fragrance and cosmetic formulators specify perfumery-grade terpene isolates, absorbing supercritical extraction premiums unavailable to industrial buyers.
- Textile Manufacturers:Sizing agents and softening compound applications consume lower-purity tall oil derivatives, with Indian BIS certification gaps creating import substitution opportunities for EU-compliant suppliers.
Packaging procurement dominates transaction frequency; chemical processing integration captures margin concentration.
Processing Technology:
Capital intensity and operator skill requirements stratify competitive positions between batch and continuous operations.
- Distillation:Atmospheric and vacuum fractionation separates terpenes, resin acids, and fatty acids by boiling point, with ASME-certified technician shortages constraining facility expansion regardless of capital availability.
- Solvent Extraction:Hexane or ethanol-based recovery improves yield from pine bark and needles, though REACH registration requirements for solvent residues complicate EU market access.
- Steam Stripping:Conventional naval stores processing for turpentine recovery faces yield limitations that supercritical CO2 methods are now displacing in high-value applications.
- Esterification:Rosin acid modification with polyols produces adhesive-compatible resins, with glycerol and pentaerythritol esters commanding distinct specification tiers.
- Polymerization:Diels-Alder and metathesis chemistry platforms unlock novel molecular architectures, with cross-coupling of terpene fractions opening fragrance and pharmaceutical intermediate pathways previously uneconomical at scale.
Continuous distillation holds installed capacity; metathesis catalysis platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US South naval stores corridor stretching from Georgia to Louisiana channels the majority of North American turpentine and rosin derivative throughput, with Jacksonville and Savannah ports handling bulk export consolidation for European adhesive manufacturers.
United States
Pulp mill operators across the Southeast and Pacific Northwest dominate crude tall oil extraction, supplying Kraton Corporation's captive distillation network. EPA Renewable Fuel Standard biomass-based diesel quotas are diverting tall oil fatty acids toward fuel ester production, tightening availability for traditional chemical applications. The Wisconsin-Ohio packaging corridor is locking multi-year rosin ester supply agreements to secure against CTO constraints.
China
Guangxi and Fujian province gum rosin collectors supply regional adhesive compounders, while Yangtze River Delta alkyd resin manufacturers absorb export-grade tall oil volumes previously destined for Europe. GB standards for pine oil purity are accelerating domestic distillation upgrades and redirecting export-grade availability toward internal consumption. Shanghai and Ningbo chemical clusters are expanding fractionation capacity to meet construction sector bio-based carbon specifications.
Germany
Rhine-Ruhr industrial chemical processors formulate tall oil-based polyols for rigid polyurethane insulation systems, responding to EU F-Gas Regulation phase-down schedules restricting fluorinated blowing agents. ECHA REACH registration requirements for turpentine monomer purity are filtering order flow toward certified refiners. Cologne-Düsseldorf formulation laboratories are rewriting construction specification sheets to highlight bio-based content thresholds.
Brazil
Paraná and São Paulo state tapping operations face seasonal labor shortages that constrain H1 resin acid availability regardless of downstream demand cycles. Naval stores infrastructure channels gum rosin volumes into international printing ink markets where Brazilian producers dominate cost structures. Santos port consolidation facilities are expanding storage capacity to buffer against harvest timing volatility.
Finland
Scandinavian pulp mill operators in the Lakeland region control substantial global CTO extraction capacity, creating bottleneck risk during maintenance cycles. Tall oil fractionation yields supply European lubricant ester producers and increasingly Chinese alkyd resin manufacturers. Kotka and Hamina port terminals are upgrading dedicated chemical handling infrastructure to manage shifting export destination patterns.
Global Pine-Derived Chemicals Market Competitive Landscape
Capital-heavy producers compete with asset-light specialty compounders across distinct margin tiers. Integrated pulp-to-derivative operators command supply security advantages through captive tall oil access, while independent refiners rely on multi-year offtake contracting to secure feedstock windows. Three archetypes dominate: backward-integrated chemical majors with naval stores infrastructure, mid-cap performance resin specialists, and regional gum rosin processors with tapping network control. Competitive moves center on distillation capacity expansion and strategic partnerships with pulp mill operators.
Among North American integrated operators, Kraton Corporation and Eastman Chemical Company exemplify the captive supply archetype through in-house crude tall oil refining positions. Ingevity Corporation occupies a performance resin specialization tier focused on pavement and industrial binder applications. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Kraton Corporation |
| Eastman Chemical Company |
| Ingevity Corporation |
| Harima Chemicals Group |
| Arakawa Chemical Industries |
| DRT |
| Florachem |
| Forforeverest Resources Ltd |
| Forchem |
| Others |
Supply & Pricing Matrix
ASME-certified distillation technicians concentrated across the US Southeast and Scandinavia command wage premiums that widen spreads between pharmaceutical-grade and fuel-tier tall oil fatty acid pricing. Labor scarcity at fractionation facilities feeds directly into contract structures, with multi-year offtake agreements now carrying escalation clauses tied to operator certification costs rather than raw material indices alone.
Pricing Analysis
Yield-based pricing anchors tall oil derivative contracts, with refiners capturing value proportional to fatty acid recovery rates achieved during vacuum fractionation. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and fuel-tier certifications separates buyers by purity threshold and regulatory registration burden. Cost compression in standard-grade segments is intensifying because Brazilian and Indonesian gum rosin supply volatility forces adhesive compounders to pay premiums for supply security. Packaging manufacturers in the Wisconsin-Ohio corridor demonstrate highest price sensitivity, while fragrance compounders in Grasse absorb supercritical extraction premiums without volume elasticity.
Supply Chain Analysis
Direct-to-adhesive-compounder channels handle North American demand through Jacksonville and Savannah port consolidation, bypassing distributor markups for qualified buyers. Supply concentrates in Finland, Sweden, and the US Southeast, where integrated pulp mill operators control crude tall oil extraction. Feedstock supply draws from softwood kraft pulping operations, gum rosin tapping networks, and naval stores distillation infrastructure. Single-source vulnerability runs through Scandinavian CTO extraction during maintenance cycles. Distribution runs through Rotterdam and Shanghai chemical terminals for Asian alkyd resin manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance barriers, with REACH-EPA divergence forcing subscale refiners to exit rather than absorb dual registration costs.
For Market Incumbents: Extend captive distillation capacity through backward integration into pulp mill offtake agreements before Chinese alkyd resin manufacturers lock Asian tall oil supply. Secure ASME-certified operator pipelines through technical training partnerships with regional community colleges to defend against workforce retirement density. Prioritize FDA 21 CFR 175.105 certification investment to capture food-contact packaging contracts from petroleum-based hot melt suppliers. For New Entrants and Emerging Players: Digital procurement platforms for spot tall oil fatty acid trading offer entry points without fractionation asset ownership. India's BIS certification gap presents the most penetrable geography, with domestic pine chemical production below technical thresholds for textile sizing applications. Target EU-compliant import substitution through toll distillation arrangements with established refiners lacking Indian market presence. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap performance resin specialists given EU F-Gas Regulation phase-down schedules redirecting polyurethane foam formulators toward pine-derived polyol alternatives. Long-term viability favors operators with integrated pulp-to-derivative positions and naval stores infrastructure rather than standalone gum rosin processors exposed to Brazilian labor volatility. Watch Chinese GB standard enforcement as the signal for domestic distillation upgrade capex cycles and export-grade availability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crude Tall Oil Supply | Kraton Corporation's captive distillation network secures consistent rosin derivative availability across North American adhesive markets. |
| Long-term Supply Agreement Lock-in | Wisconsin and Ohio tape manufacturers are abandoning just-in-time inventory for 36-month contracts against CTO constraints. |
| Supercritical CO2 Extraction Capacity Addition | Grasse and Geneva fragrance compounders retrofit extraction trains to capture perfumery-grade terpene isolate premiums. |
| REACH-EPA Dual Registration Investment | Certified refiners filter order flow as ECHA purity requirements eliminate low-grade turpentine monomer suppliers. |
| Joint Venture with Pulp Mill Operator | Eastman Chemical Company anchors market position through upstream control over crude tall oil refining infrastructure. |
Research Methodology
Independent corroboration across customs trade databases, SEC 10-K filings from listed chemical processors, and Cefic industry reports underwrites the qualitative findings. Primary interviews with plant managers at Scandinavian pulp mills, procurement leads at North American adhesive compounders, distribution channel partners in Rotterdam and Shanghai, and technical R&D directors at performance resin specialists combined with secondary validation from tall oil trade flow data and EPA Renewable Fuel Standard compliance disclosures. Bottom-up capacity modeling and top-down end-use demand estimation triangulate volume outputs.
Rate-of-change decomposition separates volume growth into fuel ester diversion, alkyd resin demand expansion, and fragrance isolate premiumization across the analysis window. Segmentation dimensions include purity grade tier, end-use industry, processing technology, and regional production hub. CAGRs derive from installed capacity utilization trends and offtake contract tenor analysis. Forecast inputs incorporate pulp and paper capacity expansion schedules and naval stores infrastructure retirement timelines.
The model holds under stable regulatory divergence between REACH and EPA timelines; deviation in harmonized global bio-based content mandates or synchronized tall oil fuel ester quota expansion would shift derivative availability assumptions. Periodic stress-testing of base assumptions against Chinese GB standard enforcement pace and Brazilian tapping labor availability is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Europe Mineral Turpentine Market
Extracts
Frankincense Oil Market
Extracts
Irish Moss Market
Extracts
India Retail Mineral Turpentine Oil Market
Extracts
Myrrh Powder Market
Extracts
Bromelain Market
Extracts
Potassium Hydrogen Tartrate Market
Extracts
Organic Extracts Market
Extracts
Agmatine Market
Extracts
Ovalbumin Powder Market
Extracts
Gum Turpentine Oil Market
Extracts
Botanical CO2 Extracts Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Black Fungus Extract Market
Extracts
Pearl Extract Market
Extracts
Pectinase Market