
 Anti-Foaming Agent Market | 2026-2036
Anti-Foaming Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Foaming Agent Market Analysis
Specialty chemical buyers in wastewater treatment are collapsing their vendor lists toward suppliers with validated silicone chemistries. Dow Inc. leverages its Midland, Michigan manufacturing complex to sustain North American supply security for emulsion-grade defoamers. Evonik Industries AG anchors European demand through its specialty surfactant portfolio tailored to pulp and paper mills. Wacker Chemie AG dominates high-purity silicone defoamer production from its Burghausen facility.
Anti-foaming agents are surface-active formulations, typically silicone oils or hydrophobic particles dispersed in carrier fluids, engineered to rupture foam lamellae by reducing local surface tension below the threshold for bubble stability. Their primary purpose is preventing process inefficiencies, product defects, and overflow hazards in continuous manufacturing operations. Silicone-based products occupy the largest share of value given their performance across extreme pH and temperature ranges, while fatty acid esters represent the fastest-growing chemistry as food-grade regulations tighten. Liquid formulations lead volume, though powder and granule forms are gaining share in remote mining and construction applications where water-based logistics prove costly.
EPA effluent guidelines under the Clean Water Act shape wastewater treatment defoamer specifications, while FDA food-contact substance notifications govern silicone migration limits in food and beverage processing. ECHA REACH restrictions on persistent organic pollutants are forcing reformulation of certain mineral oil-based products across EU member states. Stakeholders must monitor regulatory divergence between US and European permissible chemistries when designing unified product platforms.
Market Dynamics
Formulation chemistry is pivoting under dual pressure from ECHA REACH restrictions on persistent organic pollutants and food-grade silicone migration limits enforced by FDA food-contact substance notifications. Suppliers must maintain parallel product platforms to serve divergent regulatory regimes.
Growth Catalysts
- Clean-label food processing mandates:North American and European food and beverage manufacturers are expanding silicone-based defoamer procurement as consumer transparency requirements tighten formulation disclosure standards.
- EPA effluent guideline enforcement:The Clean Water Act is driving municipal and industrial wastewater treatment facilities to upgrade foam control systems, accelerating replacement cycles for legacy mineral oil chemistries.
- Bio-based polyether innovation:European Union REACH compliance deadlines are redirecting R&D investment toward renewable feedstock derivatives that maintain performance across extreme pH ranges.
Market Restraints
- Silicone feedstock concentration:High-purity silicone defoamer production depends on concentrated precursor supply from German and Chinese chemical corridors, creating geographic vulnerability.
- Fatty acid ester performance ceiling:Food-grade alternatives face thermal stability limitations above 120°C that restrict deployment in high-temperature pulp processing applications.
- Mineral oil reformulation costs:ECHA restrictions on persistent organic pollutants are forcing costly redevelopment of established industrial formulations without guaranteed performance parity.
Strategic Opportunities
- Remote mining and construction logistics:Powder and granule defoamer formats are capturing share in Australian and Canadian extraction operations where water-based distribution infrastructure remains underdeveloped.
- EU Green Deal chemistry incentives:Bio-based formulation pathways qualify for preferential financing under European sustainable chemistry transition programs.
- Pulp and paper mill service integration:Specialty chemical suppliers are embedding defoamer dosing systems within continuous process control platforms to capture recurring revenue streams.
Industry Challenges
- Cross-regulatory formulation complexity:Product development teams must engineer simultaneous compliance with FDA silicone migration limits, EPA effluent guidelines, and ECHA REACH substance restrictions.
- Application engineering talent scarcity:Foam control specification requires expertise spanning surface chemistry, process engineering, and regulatory interpretation that outpaces current training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Foaming Agent Market |
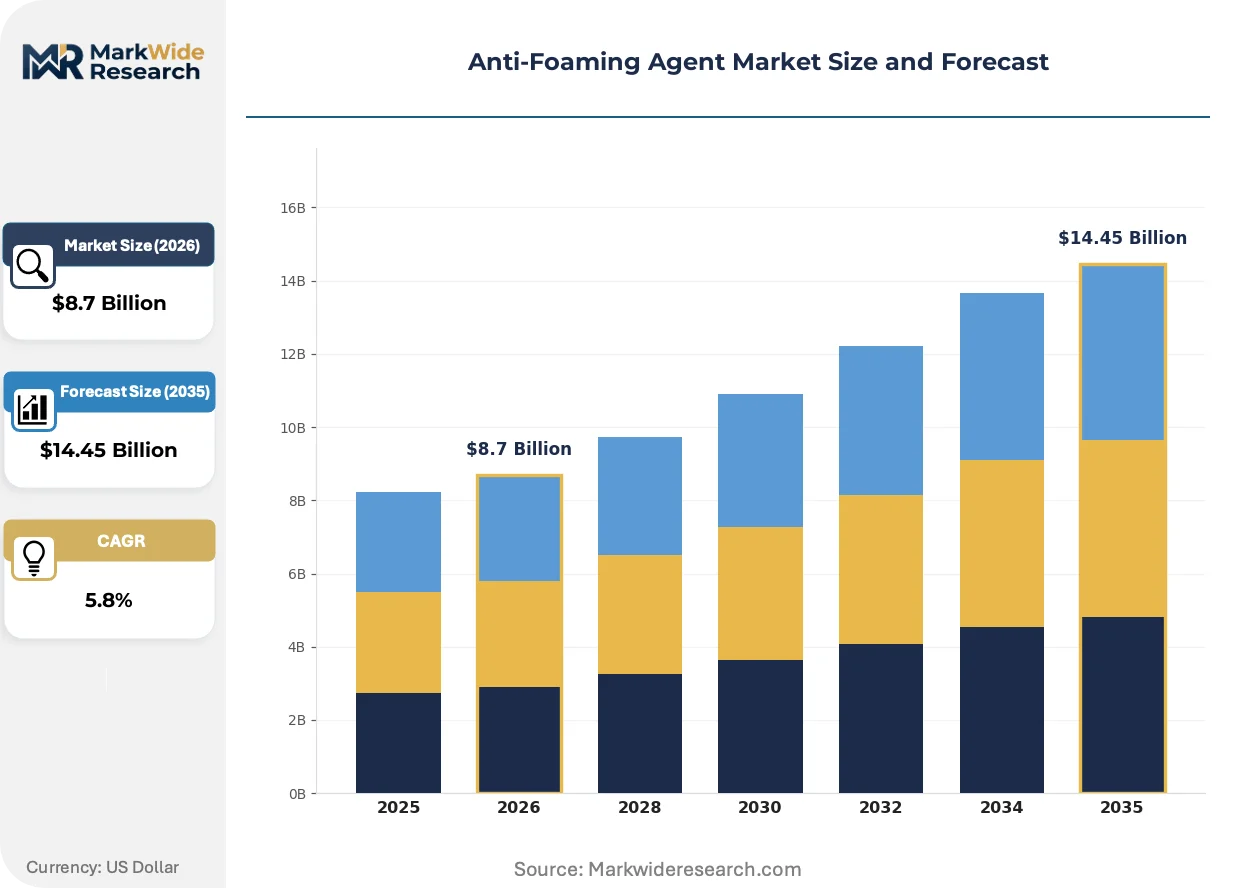
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Alcohol Ethoxylates, Fatty Acid Esters, Hydrophobic Silica End User: Food & Beverage, Paints & Coatings, Pulp & Paper, Personal Care Application: Emulsions, Adhesives, Liquid Detergents, Wastewater Treatment Form: Liquid, Powder, Granules, Concentrate |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, Wacker Chemie AG, Ashland Global Holdings Inc., Clariant AG, Shin-Etsu Chemical Co., Ltd., Ecolab Inc., Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Foaming Agent Market Emerging Trajectories
Active ingredient delivery mechanisms and regulatory chemistry pathways are diverging across major jurisdictions, forcing suppliers to maintain multiple formulation generations in parallel rather than unified global platforms.
Silicone-polyether hybrid chemistries are displacing single-class defoamers in demanding industrial applications. These formulations combine the thermal stability of silicone backbones with the environmental compatibility of polyether segments. Pulp and paper mills in Scandinavia and the US Pacific Northwest are adopting hybrids at accelerated rates to preempt regulatory phase-outs. This displacement is compressing margins on legacy mineral oil products while rewarding suppliers with integrated silicone-polyether synthesis capabilities.
REACH authorization requirements for persistent organic pollutants are fragmenting the European product landscape. Industrial users must now document substance volume tracking and substitution planning for defoamer chemistries previously treated as commodity inputs. Mineral oil-based formulations face the steepest compliance burden, driving rapid qualification of bio-polyether alternatives in German chemical processing clusters around Ludwigshafen.
Specification authority is migrating from procurement departments to process engineering teams with direct operational accountability. Food and beverage processors are collapsing vendor lists toward suppliers offering validated application support rather than lowest-unit-cost sourcing. This shift concentrates contract value with integrated chemical-service providers and disadvantages pure-manufacturing competitors, particularly visible in North American dairy processing and brewing operations.
Anti-Foaming Agent Market Segmentation
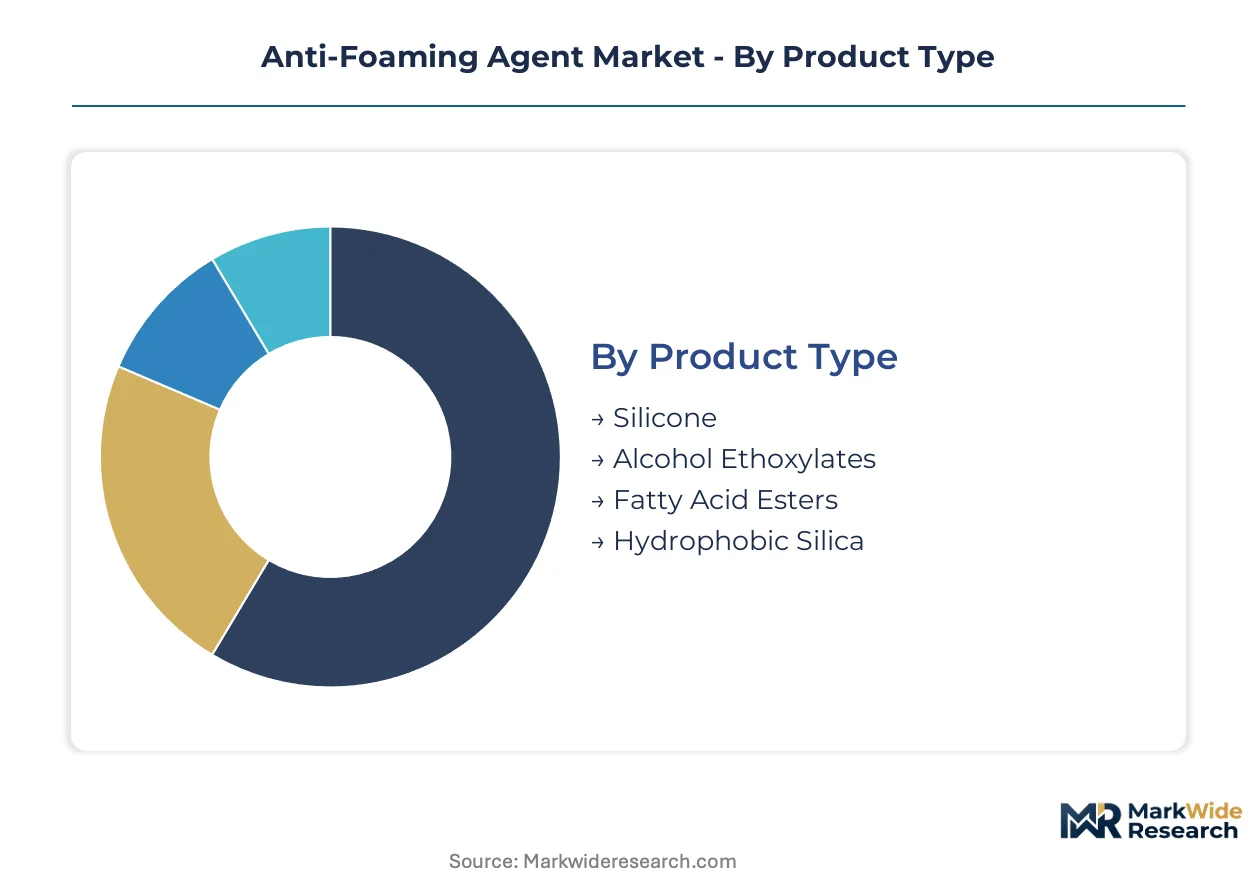
Anti-foaming agent procurement channels diverge sharply by formulation chemistry and physical state. Liquid emulsions flow through integrated chemical distributors, while solid formats reach remote industrial sites via specialized logistics networks.
Product Type:
Channel economics favor silicone fluids through bulk tanker distribution, whereas bio-based alternatives move through specialty chemical distributors with technical service capabilities.
- Silicone:Polydimethylsiloxane-based fluids dominate high-temperature industrial processes. Pulp mills in Germany's chemical corridor specify these for continuous digester operations where thermal stability exceeds 150°C.
- Fatty Acid Esters:Food-grade formulations derived from vegetable oils are displacing mineral oil products under tightening FDA and EFSA migration limits. Clean-label dairy processors in Wisconsin and Bavaria are accelerating procurement.
- Alcohol Ethoxylates:Surfactant hybrids serve mid-range temperature applications in textile finishing.
- Hydrophobic Silica:Powdered silica compounds target powder detergent manufacturers seeking defoaming without liquid carrier logistics.
Silicone dominates installed base. Fatty acid esters are where expansion concentrates.
End User:
Customer concentration varies by regulatory exposure — food-contact applications demand validated supply chains, while industrial users prioritize unit economics.
- Pulp & Paper:Kraft pulping and paper machine wet-end operations require continuous foam suppression. Scandinavian mills are retrofitting defoamer dosing systems to preempt ECHA substance restrictions.
- Food & Beverage:Fermentation and processing lines use food-grade silicones under FDA 21 CFR compliance. Breweries in Colorado and craft distilleries in Kentucky are consolidating vendor lists toward suppliers with validated silicone chemistries.
- Paints & Coatings:Waterborne formulations need defoamers that prevent microfoam without surface defects.
- Personal Care:Cosmetic emulsions require low-residue silicones for skin-contact applications.
Pulp and paper commands the largest volume footprint. Food and beverage is climbing the fastest.
Application:
Specification complexity escalates from simple batch processes to continuous systems with real-time foam monitoring.
- Wastewater Treatment:Municipal and industrial aeration basins require defoamers compatible with biological nutrient removal. EPA effluent guideline enforcement is accelerating replacement of legacy mineral oil products.
- Emulsions:Polymer emulsion manufacturing demands defoamers that prevent viscosity drift during storage.
- Liquid Detergents:High-foaming surfactant bases need controlled defoaming for packaging efficiency.
- Adhesives:Water-based adhesive production requires defoamers that survive shear mixing without reactivation.
Wastewater treatment absorbs the highest absolute volume. Emulsion applications are gaining share fastest.
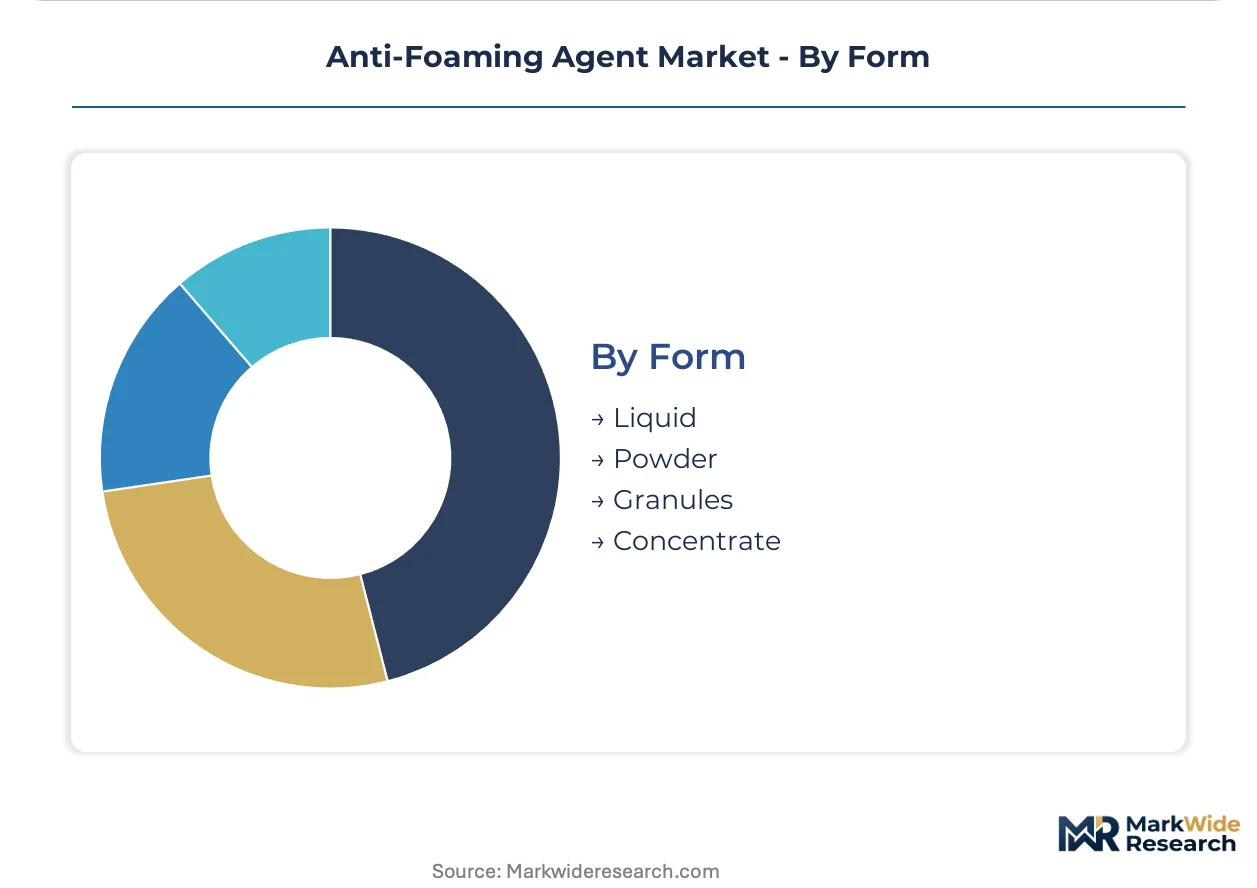
Form:
Physical state determines logistics infrastructure requirements and dosing system compatibility.
- Liquid:Emulsion and neat oil formats serve continuous manufacturing through automated dosing skids. Dow's Midland complex supplies North American tanker volumes.
- Powder:Spray-dried formulations eliminate water freight for remote mining operations in Western Australia's Pilbara region.
- Granules:Dust-free granules suit construction chemical blending where precise metering matters.
- Concentrate:High-actives products reduce freight costs for distant pulp mills with on-site dilution capability.
Liquid holds the dominant share. Powder formats are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicone defoamer production clusters around German and Chinese chemical corridors, creating geographic vulnerability for buyers dependent on concentrated precursor supply. Formulation chemistry diverges sharply between jurisdictions as ECHA REACH restrictions and FDA migration limits force parallel product platforms.
United States
Wastewater treatment facilities under EPA Clean Water Act enforcement are accelerating replacement cycles for legacy mineral oil chemistries. FDA 21 CFR compliance mandates shape food-grade silicone specifications for dairy processors in Wisconsin and brewing operations in Colorado. Dow's Midland, Michigan manufacturing complex anchors North American supply security for emulsion-grade defoamers distributed via bulk tanker networks.
Germany
ECHA REACH authorization requirements for persistent organic pollutants are fragmenting the European product landscape and driving rapid qualification of bio-polyether alternatives. The EU Green Deal chemistry incentives redirect R&D investment toward renewable feedstock derivatives. Industrial chemical clusters around Ludwigshafen and Leverkusen concentrate demand for continuous digester operations in pulp mills requiring thermal stability above 150°C.
China
Dual carbon goals and MEE environmental enforcement are reshaping industrial chemical production standards for foam control applications. GB standards compliance requirements intensify for silicone-based formulations serving domestic manufacturing. Yangtze River Delta chemical processing hubs are expanding capacity for emulsion-grade defoamers targeting textile finishing and waterborne coatings production.
Japan
METI industrial policy incentives support specialty surfactant innovation for high-performance defoamer applications. JIS standards govern silicone purity specifications for electronics and personal care manufacturing. Kanto region chemical processors are adopting silicone-polyether hybrid chemistries to preempt regulatory phase-outs in pulp and paper mill operations.
Australia
Remote mining operations in Western Australia's Pilbara region are driving adoption of powder and granule defoamer formats where water-based distribution infrastructure remains underdeveloped. TGA regulatory frameworks influence food-grade formulation imports for domestic processing. Spray-dried formulations eliminate water freight costs for extraction operations with limited liquid logistics access.
Anti-Foaming Agent Market Vendor Landscape
Concentration sits with integrated chemical conglomerates possessing captive silicone synthesis capabilities and validated regulatory compliance portfolios. The vendor base separates into three tiers: multinational diversified suppliers with global formulation platforms, regional specialists with application engineering depth, and commodity producers competing on unit economics. Strategic moves center on backward integration into silicone precursor production and geographic expansion through technical service partnerships rather than pure manufacturing scale.
Within the integrated chemical conglomerate tier, BASF SE and Dow Inc. exemplify archetypes with diversified specialty chemical portfolios spanning multiple regulatory jurisdictions. Evonik Industries AG occupies a position emphasizing specialty surfactant expertise tailored to pulp and paper mill process integration. Wacker Chemie AG anchors the high-purity silicone defoamer segment through its Burghausen facility concentration. These four entities collectively represent the competitive core where formulation chemistry, regulatory navigation, and application engineering capabilities converge.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| Wacker Chemie AG |
| Ashland Global Holdings Inc. |
| Clariant AG |
| Shin-Etsu Chemical Co., Ltd. |
| Ecolab Inc. |
| Air Products and Chemicals, Inc. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day silicone precursor lead times concentrate pricing power with German and Chinese chemical corridor producers, compressing margins for formulation houses lacking backward integration into methylchlorosilane supply. Food-grade certification tiers amplify this dynamic, as FDA-validated silicone defoamers command substantial premia over industrial-grade alternatives.
Pricing Analysis
ECHA REACH authorization requirements dictate the pricing tier structure across the European product landscape, separating validated bio-polyether formulations from legacy mineral oil products facing substitution mandates. Pricing stratifies across food-contact certified, industrial high-temperature, and economy mineral oil tiers, with FDA 21 CFR compliance and thermal stability above 150°C as the primary differentiation drivers. Cost compression in mineral oil formulations is intensifying because ECHA persistent organic pollutant restrictions force costly reformulation without guaranteed performance parity. Municipal wastewater treatment facilities exhibit highest price sensitivity due to budget constraints, while pulp mills running continuous digesters show lowest sensitivity given operational criticality of foam control.
Supply Chain Analysis
Strategic stockpiling of silicone precursors dominates inventory strategy among integrated producers, while specialty distributors maintain just-in-time emulsion inventories for downstream formulation. High-purity silicone defoamer production draws from concentrated precursor supply in Germany and China, with polydimethylsiloxane fluids and hydrophobic silica as critical inputs. Single-source vulnerability in German chemical corridor methylchlorosilane capacity presents structural exposure for European formulation houses. Distribution runs through integrated chemical distributors for liquid emulsions and specialized logistics networks for powder formats serving remote mining operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
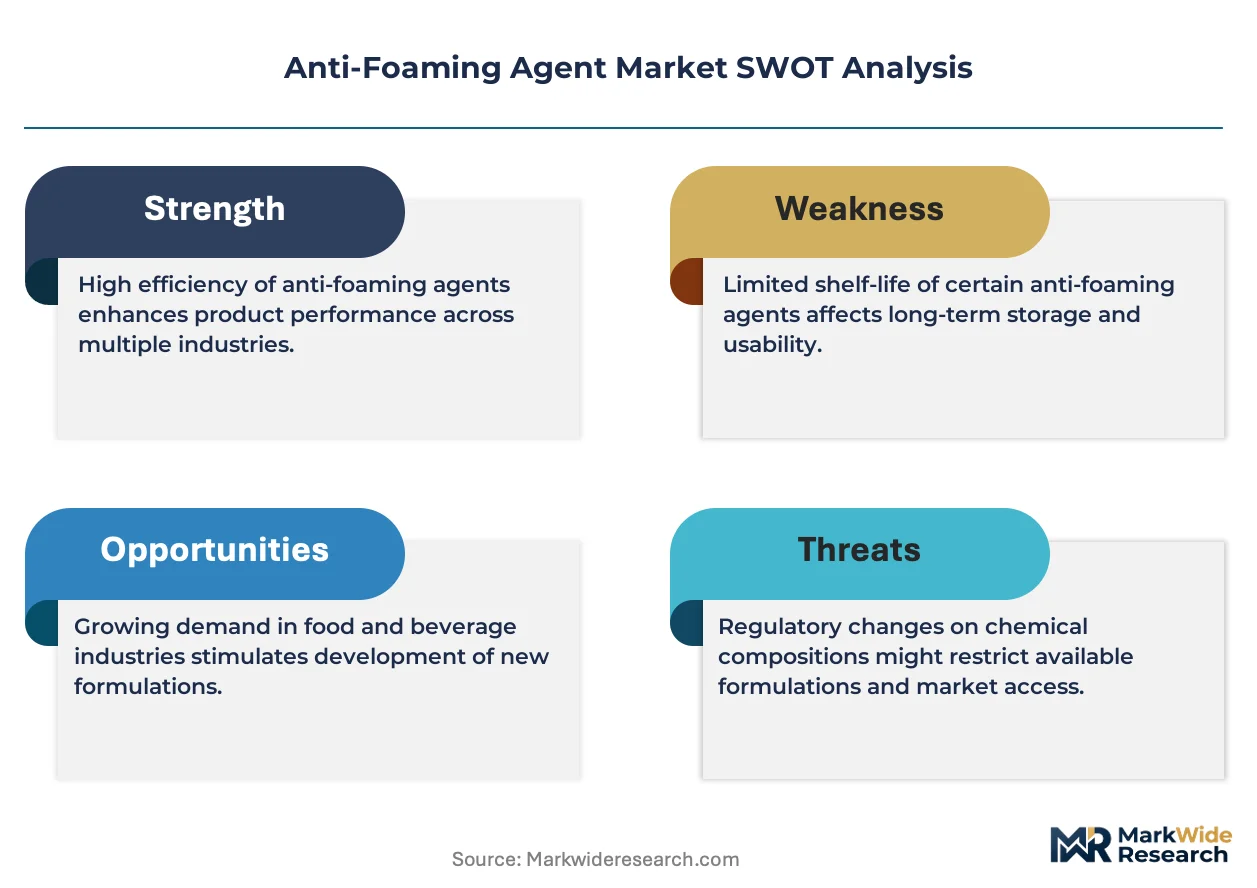
This market functions as a defensive-moat story anchored in regulatory entrenchment. Switching costs escalate dramatically once FDA food-contact substance notifications or ECHA REACH authorizations are embedded in buyer qualification systems.
For Market Incumbents: Shield market position through captive silicone precursor production and accelerated bio-polyether qualification to preempt ECHA substitution mandates. Mineral oil reformulation cost pressures threaten margin structures for non-integrated suppliers. Backward integration into methylchlorosilane synthesis and Burghausen-scale high-purity production facilities represent priority defensive investments.
For New Entrants and Emerging Players: FDA 21 CFR fast-track certification offers the most viable entry pathway for food-grade silicone defoamers serving North American dairy and brewing operations. Remote mining powder format applications in Western Australia's Pilbara region present underdeveloped white-space with limited incumbent technical service presence. Partner with regional construction chemical distributors to bypass capital-intensive liquid logistics infrastructure.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because divergence between FDA migration limits and ECHA REACH restrictions fragments product platforms and rewards multi-jurisdictional formulation expertise. Acquisition targets should display integrated silicone-polyether synthesis capabilities and validated application engineering teams serving pulp and paper mill process integration. Monitor ECHA authorization list expansion for persistent organic pollutants as the critical inflection signal for bio-polyether substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Precursor Production | Captive methylchlorosilane supply secures margin control against German and Chinese corridor concentration. |
| Bio-Polyether Formulation Qualification | EU Green Deal financing access and ECHA REACH preemption drive R&D prioritization in Ludwigshafen chemical clusters. |
| Pulp Mill Process Integration Partnership | Embedded dosing system contracts convert commodity defoamer sales into recurring technical service revenue streams. |
| Powder Format Capacity Expansion | Spray-dried production eliminates water freight costs for Australian and Canadian remote extraction operations. |
| Dual Regulatory Platform Maintenance | Parallel FDA and ECHA compliance portfolios capture food-contact and industrial demand without reformulation delays. |
Methodological Framework
Operator-level perspectives from pulp mill process engineers, municipal wastewater treatment plant managers, food and beverage procurement leads, and specialty chemical distribution channel partners anchored the qualitative base. Primary interview data combined with customs and trade flow records, ACC and Cefic industry reports, SEC 10-K specialty chemical segment disclosures, and EPA effluent guideline enforcement databases for secondary validation. Bottom-up volume modeling across formulation chemistry, physical state, and end-use application segments triangulated against top-down market sizing from producer capacity assessments.
Sensitivity analysis around silicone feedstock price volatility and ECHA authorization timeline scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry class, thermal stability grade, food-contact certification status, physical state, and regional regulatory cluster. CAGRs derived from installed base replacement cycle analysis and greenfield application penetration curves. Industry-specific inputs encompassed kraft pulp production capacity expansion schedules and municipal wastewater treatment facility upgrade timelines under Clean Water Act enforcement.
Decision-makers should treat outputs as directional under sustained ECHA REACH restriction expansion and FDA migration limit stability; material deviation would warrant model refresh. Forecasts embed assumptions regarding silicone precursor supply continuity from German chemical corridors and bio-polyether performance parity achievement. Revision becomes warranted when ECHA persistent organic pollutant authorization lists expand beyond current mineral oil formulations or FDA issues revised food-contact substance notification thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Low Melt Inclusions Market
Additives
Calcium Tartrate Market
Additives
Crack-Bridging Flexible Polymer Additives for Repair Mortars Market
Additives
Plasticizer Alcohols Market
Additives
Nucleotide Premix Market
Additives
Global UV Absorbers Market
Additives
Sodium Diacetate Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Water-Borne Coating Additives Market
Additives
Sodium Caprylate Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Inhibited Propylene Glycol Market
Additives
Hydroxyethyl Cellulose Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Global Corrosion Inhibitor Market
Additives
Enzyme Stabilizer Market