
 Tocopheryl Acetate Market | 2026-2036
Tocopheryl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Tocopheryl Acetate Market Outlook
Synthetic vitamin E is rebalancing toward natural-source tocopheryl acetate as feedstock volatility and consumer preference shifts compress margins on petrochemical-derived alternatives. DSM Firmenich leverages its integrated biotechnology platform to secure fermentation-derived tocopherol supply chains. BASF anchors its position through backward integration into isophytol and trimethylhydroquinone chemistry. Zhejiang Medicine competes on cost-optimized manufacturing scale from its Zhejiang Province facilities.
Tocopheryl acetate, the acetic acid ester of tocopherol with a molecular formula of C31H52O3, functions primarily as a fat-soluble antioxidant that stabilizes lipid-containing formulations against peroxidation while delivering skin-conditioning benefits upon enzymatic hydrolysis. The cosmetics application segment leads current value generation, with serum and cream formulation types capturing premium positioning through concentrated active delivery systems. Powder product type dominates pharmaceutical and nutraceutical channels where excipient compatibility and shelf-stability requirements favor solid-dose processing, while liquid and emulsion forms serve cosmetic manufacturers seeking direct incorporation into oil-phase or aqueous systems without pre-dissolution steps.
REACH registration requirements in Europe mandate full toxicological dossiers for tocopheryl acetate imports, while FDA oversight through the Cosmetic Ingredient Review program shapes permissible concentration thresholds in leave-on products. China's NMPA and GB standards for cosmetic raw materials impose additional heavy metal and solvent residue specifications that filter supplier eligibility. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines for cross-border product registrations.
Market Dynamics
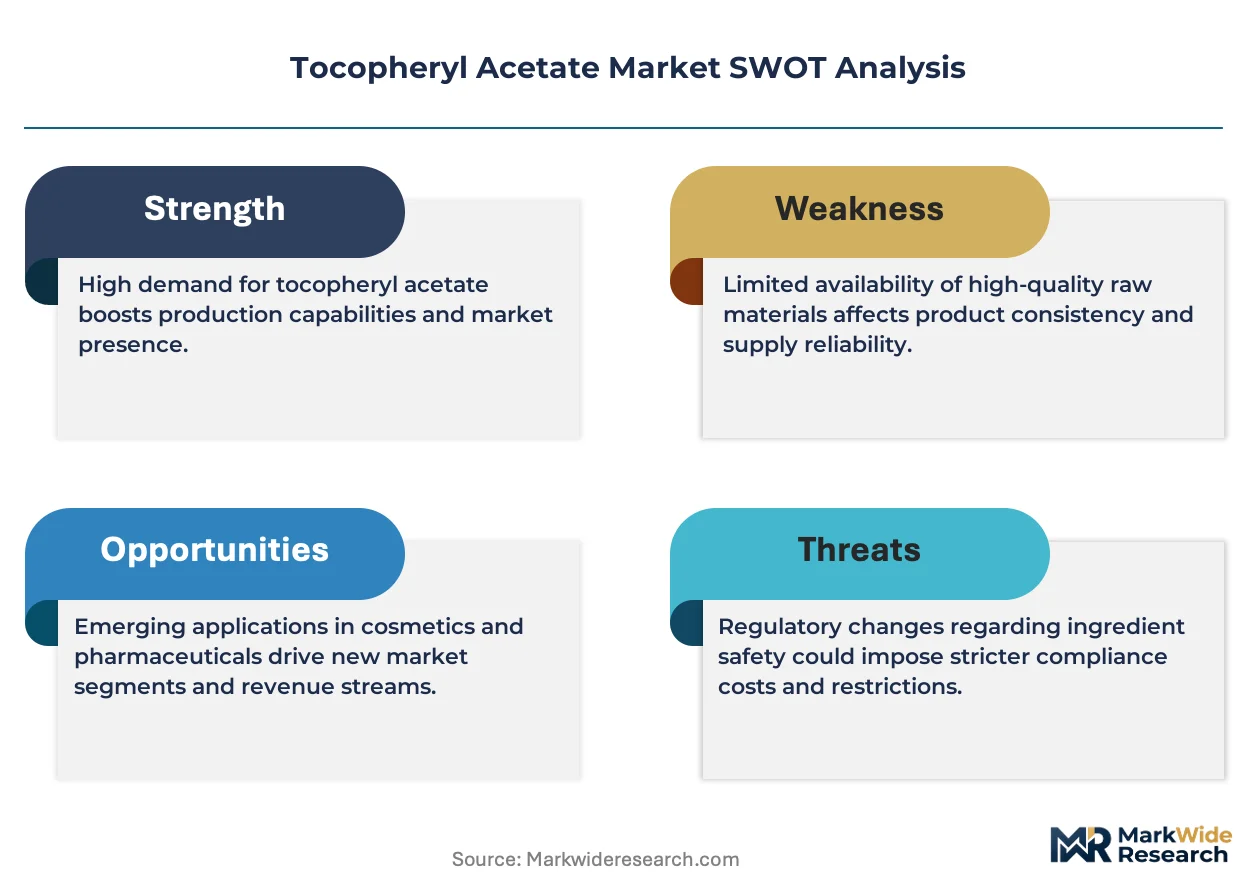
Clean-label positioning in cosmetics is compressing synthetic tocopheryl acetate margins while fermentation-derived natural alternatives capture formulation slots. REACH dossier requirements and China's GB standards are simultaneously raising supplier qualification barriers.
Growth Catalysts
- Fermentation biotechnology:Industrial-scale microbial production of tocopherol precursors reduces dependency on petrochemical feedstocks. DSM Firmenich and Zhejiang Medicine are expanding capacity.
- Anti-aging serum proliferation:Cosmetics formulators are doubling down on concentrated antioxidant delivery systems. Tocopheryl acetate's stability in oil-phase formulations makes it indispensable.
- EPA cosmetic ingredient guidance:Tightening purity thresholds for import acceptance into the US are filtering out substandard suppliers. Qualified producers gain shelf space.
Market Restraints
- Isophytol feedstock volatility:Petrochemical-derived synthetic vitamin E faces margin compression from crude oil price swings. BASF's backward integration into trimethylhydroquinone chemistry offers partial insulation.
- Supplier concentration in Zhejiang Province:China's domestic fermentation-based production clusters create geographic risk for international buyers. Disruption propagates quickly through supply chains.
- Enzymatic hydrolysis limitation:Skin conversion of tocopheryl acetate to active tocopherol varies by formulation pH and individual microbiome. Efficacy claims require careful qualification.
Strategic Opportunities
- India nutraceutical penetration:FSSAI regulatory alignment and PLI scheme incentives for domestic manufacturing create white space for local vitamin E derivative production. Underpenetrated relative to China.
- Solid-dose pharmaceutical expansion:Powder tocopheryl acetate formats for tablet and capsule applications remain underserved versus liquid cosmetic grades. Excipient compatibility requirements favor specialized suppliers.
- EU Green Deal chemistry transition:Bio-based feedstock mandates and CSRD disclosure requirements are tilting procurement toward fermentation-derived tocopherol. Early certifiers capture premium positioning.
Industry Challenges
- REACH dossier compilation timelines:Full toxicological registration for European import acceptance demands 18-24 month qualification cycles. Smaller suppliers lack regulatory affairs bandwidth.
- Fermentation scale-up capex intensity:Commercial-grade bioreactor infrastructure and downstream purification systems require substantial capital deployment. Debt financing remains constrained for mid-cap entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tocopheryl Acetate Market |
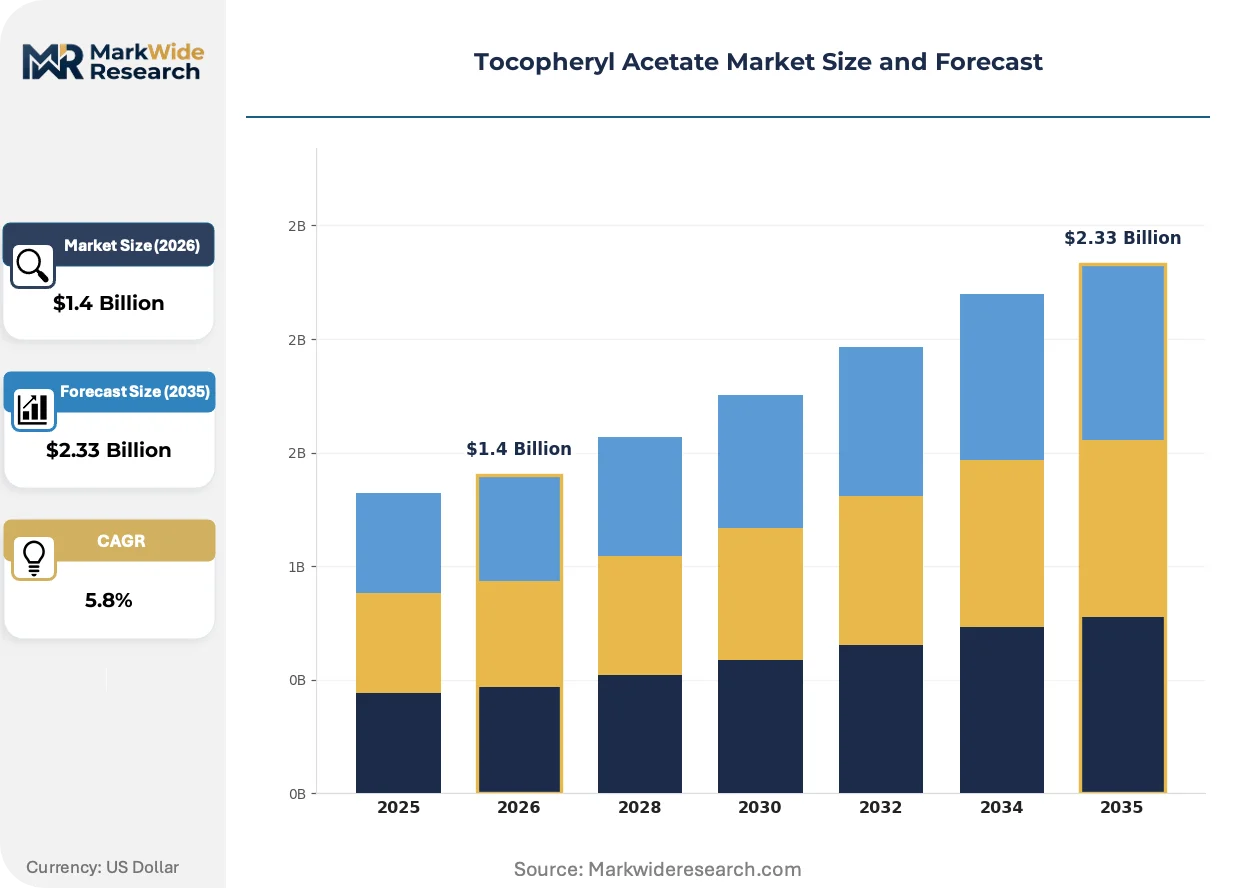
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Emulsion, Granules Application: Cosmetics, Food Additives, Pharmaceuticals, Nutraceuticals Formulation Type: Serum, Cream, Ointment, Gel Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | DSM Firmenich, BASF, Adisseo, Zhejiang Medicine, Wilmar International, BTSA, Eisen-GmbH, KLK Oleo, Zhejiang NHU, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tocopheryl Acetate Market Strategic Shifts
Fermentation-derived tocopherol production is absorbing capital and talent from traditional chemical synthesis routes. Regulatory divergence between jurisdictions and buyer preference shifts are forcing simultaneous adaptation across multiple fronts.
Enzymatic esterification processes using lipase biocatalysts are replacing acid-catalyzed chemical routes for tocopheryl acetate synthesis. Cosmetics manufacturers in South Korea and Japan are specifying biocatalytic grades for clean-label positioning. This technology is absorbing market share from conventional petrochemical processes as carbon footprint disclosure requirements tighten.
REACH registration mandates in Europe now require extended one-generation reproductive toxicity studies for cosmetic-grade tocopheryl acetate. The industrial consequence is a two-tier supplier base: dossier-holders versus traders. Pharmaceutical and nutraceutical channels face the steepest compliance burden, with several Asian suppliers withdrawing from European cosmetic raw material registration.
Direct sourcing contracts between nutraceutical brands and fermentation producers are displacing traditional distributor intermediaries. China's domestic brands are leading this disintermediation, negotiating volume commitments with Zhejiang Province manufacturers. The shift is most visible in vitamin E derivative procurement for tablet and softgel applications, where price transparency and supply security outweigh distributor service value.
Tocopheryl Acetate Market Segmentation
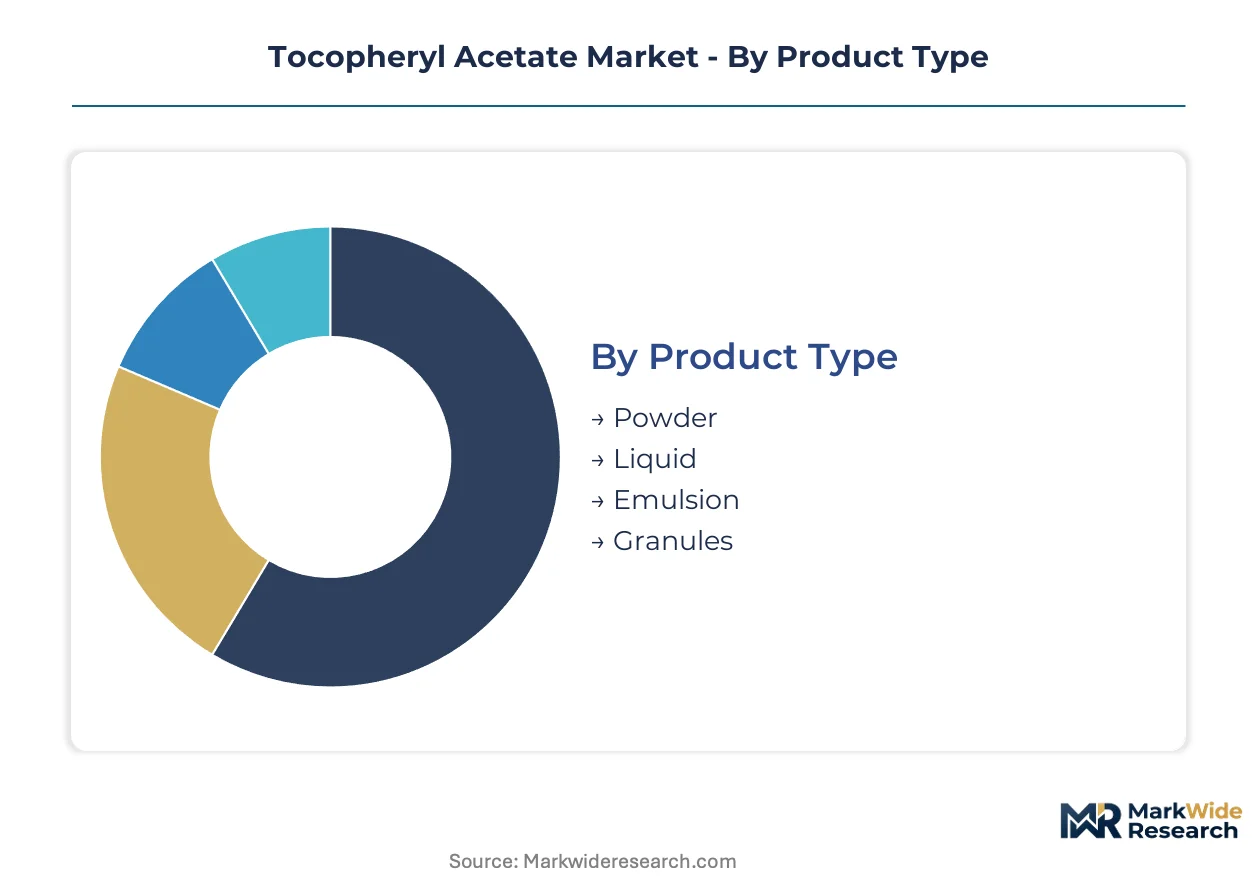
Tocopheryl acetate's molecular stability and formulation versatility create divergent value pools across physical formats and end-use channels. Manufacturers configure production assets around these segment boundaries, with purity grades and particle specifications determining addressable market scope.
Product Type:
Buyers in this category differentiate primarily by processing compatibility and shelf-stability requirements, with powder formats commanding pharmaceutical premiums and liquid grades serving cosmetic formulation efficiency.
- Powder:Micronized crystalline form with standardized mesh sizes enables direct compression into tablet matrices and capsule fills. Pharmaceutical manufacturers in Germany and Switzerland specify powder grades for solid-dose stability, though hygroscopicity constraints limit tropical distribution without specialized packaging.
- Liquid:Oil-phase concentrated solutions eliminate dissolution steps for cosmetic compounders. South Korean serum manufacturers source liquid tocopheryl acetate for direct incorporation into anhydrous antioxidant systems, bypassing pre-emulsification.
- Emulsion:Pre-dispersed aqueous systems reduce manufacturing complexity for small-batch cosmetics producers. The format suits formulators lacking high-shear homogenization equipment.
- Granules:Free-flowing agglomerated particles bridge powder handling ease with liquid dissolution speed. Nutraceutical contract manufacturers favor granules for continuous tablet press operations.
Powder leads volumes today; liquid is gaining share fastest.
Application:
Regulatory pathway complexity and purity certification tiers separate commercial buyers in this dimension, with pharmaceutical channels demanding GMP documentation that cosmetic formulators rarely require.
- Cosmetics:Antioxidant stabilization of lipid-rich emulsions and anti-aging positioning drive serum and cream incorporation. Japanese and South Korean clean-label brands specify fermentation-derived grades for marketing differentiation, accepting cost premiums over synthetic alternatives.
- Pharmaceuticals:Excipient-grade tocopheryl acetate requires full ICH Q3D elemental impurity compliance and stability data packages. European generic drug manufacturers source through qualified supplier audits that exclude trader intermediaries.
- Nutraceuticals:Vitamin E fortification of softgels and tablets concentrates demand in China's domestic brands. Direct sourcing contracts with Zhejiang Province fermentation producers are displacing traditional distributor relationships.
- Food Additives:E307 designation tocopheryl acetate preserves edible oils and fat-based products. FSSAI registration requirements in India filter supplier eligibility for domestic food manufacturers.
Cosmetics leads volumes today; nutraceuticals climbs the fastest.
Formulation Type:
Delivery system performance specifications and consumer application rituals determine buyer selection, with concentrated serum formats capturing unit value premiums over mass-market creams.
- Serum:High-actives anhydrous or hydrogel vehicles enable concentrated antioxidant delivery. Premium cosmetics houses in France and Switzerland formulate serums with tocopheryl acetate loadings that would destabilize conventional emulsions.
- Cream:Oil-in-water emulsions distribute tocopheryl acetate through skin-conditioning bases. Mass-market skincare manufacturers optimize cream formulations for cost-efficient manufacturing scale.
- Ointment:Occlusive petrolatum or lanolin bases suspend tocopheryl acetate for barrier repair indications. Pharmaceutical compounding pharmacies specify ointment grades for dermatological preparations.
- Gel:Hydroalcoholic or carbomer-thickened systems offer non-greasy application aesthetics. Men's grooming and body care lines specify gel formats for rapid absorption claims.
Cream leads volumes today; serum shows the steepest expansion trajectory.
Distribution Channel:
Order fragmentation patterns and technical service requirements distinguish buyers, with pharmaceutical channels demanding batch documentation that online retail transactions rarely support.
- Pharmacies:Licensed retail outlets stock pharmaceutical-grade tocopheryl acetate for compounding and OTC vitamin E products. German Apotheken and French officines maintain supplier qualification files that exceed supermarket requirements.
- Specialty Stores:Professional cosmetics ingredient suppliers and cosmetic chemist retailers serve small-batch formulators. These channels provide technical consultation that commodity distributors cannot match.
- Online Retail:E-commerce platforms aggregate fragmented demand from DIY cosmetics enthusiasts and small manufacturers. Alibaba and domestic Chinese platforms dominate B2B procurement for Zhejiang-sourced fermentation grades.
- Supermarkets:Mass-market vitamin E supplements and basic skincare products reach consumers through grocery retail. Shelf-space constraints favor established brands with marketing investment capacity.
Pharmacies leads volumes today; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang Province anchors fermentation-based tocopheryl acetate production, with domestic Chinese brands scaling direct sourcing contracts that displace traditional distributor channels. Regulatory divergence between REACH dossier requirements and China's GB standards is fragmenting supplier qualification pathways. Production clusters in Germany and Switzerland maintain pharmaceutical-grade certification advantages.
China
Domestic nutraceutical brands drive volume demand through direct procurement agreements with Zhejiang Province fermentation producers. NMPA cosmetic raw material standards and GB heavy metal specifications filter import eligibility for international suppliers. The Yangtze River Delta concentration around Zhejiang Medicine and NHU facilities is expanding bioreactor capacity for tocopherol precursor output.
Germany
European generic drug manufacturers source pharmaceutical-grade tocopheryl acetate through qualified supplier audits excluding trader intermediaries. REACH registration mandates require full toxicological dossiers with 18-24 month qualification cycles. The North Rhine-Westphalia chemical corridor maintains backward integration into trimethylhydroquinone chemistry for synthetic vitamin E production.
United States
Cosmetics formulators incorporate tocopheryl acetate into anti-aging serum lines as EPA guidance tightens purity thresholds for import acceptance. FDA oversight through the Cosmetic Ingredient Review program shapes concentration limits in leave-on products. New Jersey and Illinois specialty chemical clusters serve domestic pharmaceutical and nutraceutical contract manufacturers.
Switzerland
Premium cosmetics houses formulate concentrated serum delivery systems with tocopheryl acetate loadings exceeding conventional emulsion stability limits. Swissmedic pharmaceutical regulations enforce ICH Q3D elemental impurity compliance for excipient-grade supply. The Basel region concentration supports GMP-documentation capabilities that exceed supermarket channel requirements.
South Korea
Clean-label cosmetics manufacturers specify fermentation-derived tocopheryl acetate grades for marketing differentiation, accepting cost premiums over synthetic alternatives. MFDS cosmetic safety standards align with Japanese and Chinese regional protocols. Seoul-area formulators source liquid grades for direct incorporation into anhydrous antioxidant systems without pre-emulsification steps.
Tocopheryl Acetate Market Competitive Environment
Global majors compete with regional champions across fermentation technology and petrochemical synthesis routes. The supplier base concentrates around three strategic tiers: integrated biotechnology platforms controlling precursor supply chains, backward-integrated chemical conglomerates with captive isophytol production, and cost-optimized regional manufacturers leveraging provincial industrial clustering. Competitive positioning hardens through REACH dossier accumulation, fermentation scale-up capital deployment, and direct sourcing contract negotiation with nutraceutical brands.
Among biotechnology-integrated specialists, DSM Firmenich exemplifies the fermentation-derived platform archetype through microbial tocopherol production systems. BASF anchors the petrochemical synthesis tier with integrated access to trimethylhydroquinone chemistry. Zhejiang Medicine occupies the scale-driven regional manufacturer position within China's Zhejiang Province production cluster.
| Leading Market Players |
|---|
| DSM Firmenich |
| BASF |
| Adisseo |
| Zhejiang Medicine |
| Wilmar International |
| BTSA |
| Eisen-GmbH |
| KLK Oleo |
| Zhejiang NHU |
| Others |
Value Chain & Pricing Dynamics
Isophytol and trimethylhydroquinone feedstock costs transmit directly from petrochemical indices through synthetic vitamin E pricing tiers, while fermentation-derived tocopherol precursors anchor natural-source premiums to bioreactor operating economics and downstream purification yields. Buyers face divergent cost structures depending on their clean-label positioning requirements and regulatory qualification thresholds.
Pricing Analysis
Input-cost pass-through from crude oil volatility compresses margins on petrochemical-derived synthetic grades, while fermentation-based natural alternatives command premium-mid-economy pricing differentiation based on carbon footprint certification and REACH dossier completeness. Price differentiation separates GMP-documented pharmaceutical grades from cosmetic excipient tiers, with volume scale and geographic delivery cost as secondary drivers. Pricing pressure stems from Zhejiang Province capacity expansion flooding mid-tier cosmetic grades. Nutraceutical contract manufacturers show highest price sensitivity; premium Swiss cosmetics houses show least.
Supply Chain Analysis
Dual-sourcing requirements from European pharmaceutical manufacturers mandate qualified supplier audits across Germany, Switzerland, and China's Zhejiang Province to mitigate single-source vulnerability from geographic concentration. Raw material dependencies rest on isophytol from petrochemical streams, microbial feedstocks for fermentation, and acetic anhydride for esterification. Tariff exposure on Chinese fermentation-derived imports into Europe creates supply chain risk. Distribution runs through direct sourcing contracts displacing traditional distributor intermediaries, particularly for nutraceutical tablet and softgel applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tocopheryl acetate market functions as a stable compounder where anti-aging serum proliferation and fermentation biotechnology maturation deliver steady value accretion without cyclical disruption.
For Market Incumbents: Anticipate margin compression from Zhejiang Province capacity additions by deepening backward integration into isophytol chemistry or securing exclusive fermentation precursor supply agreements. DSM Firmenich and BASF should prioritize REACH dossier accumulation as a defensive moat against trader intermediaries. Certification investment in bio-based feedstock verification captures EU Green Deal procurement preferences. For New Entrants and Emerging Players: Nutraceutical contract manufacturers in India offer the most penetrable white space given FSSAI regulatory alignment and PLI scheme incentives for domestic vitamin E derivative production. Solid-dose pharmaceutical powder grades remain underserved versus liquid cosmetic formats. A go-to-market angle through direct sourcing contracts with domestic Indian brands bypasses established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up capex requirements exceed mid-cap debt financing capacity, creating acquisition opportunities for biotechnology-integrated platforms. The 5-10 year viability window favors dossier-holding suppliers with GMP-documentation capabilities over trader-dependent intermediaries. Target acquisition archetype: regional fermentation specialists with qualified European cosmetic raw material registration. The signal to watch is withdrawal of Asian suppliers from REACH registration due to toxicological study cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Scale-Up | DSM Firmenich and Zhejiang Medicine expand bioreactor capacity to reduce petrochemical dependency. |
| REACH Dossier Accumulation | Full toxicological registration creates two-tier supplier base excluding trader intermediaries from European cosmetic channels. |
| Direct Sourcing Contracts | Chinese nutraceutical brands disintermediate distributors through volume commitments with Zhejiang Province producers. |
| Enzymatic Esterification Transition | Lipase biocatalysts replace acid-catalyzed routes as South Korean and Japanese manufacturers specify clean-label grades. |
| India Market Penetration | FSSAI alignment and PLI incentives create white space for local vitamin E derivative manufacturing. |
Study Parameters
Coverage spans China, Germany, Switzerland, South Korea, and the United States, with primary inputs from each market through interviews with fermentation plant managers, cosmetic formulators, pharmaceutical procurement leads, and nutraceutical brand supply chain directors. Secondary validation draws from NMPA cosmetic raw material filings, REACH registration databases, ECHA toxicological dossiers, and SEC 10-K disclosures from listed chemical producers. Bottom-up demand modeling from end-use segments triangulates against top-down production capacity assessments across Zhejiang Province and European pharmaceutical corridors.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon, with segmentation modeling across product type (powder, liquid, emulsion, granules), application (cosmetics, pharmaceuticals, nutraceuticals, food additives), and formulation type (serum, cream, ointment, gel). CAGRs derive from regression analysis against anti-aging serum proliferation rates, fermentation capacity buildout schedules, and regulatory qualification timeline assumptions. Industry-specific inputs include enzymatic hydrolysis efficacy variability and clean-label positioning adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH dossier compilation delays, fermentation scale-up execution risk, and crude oil price volatility affecting synthetic vitamin E margins. Deviation in EU Green Deal bio-based feedstock mandate timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tragacanth Market
Additives
Binder Excipients Market
Additives
Shortstop Inhibitor Market
Additives
China Sodium Reduction Ingredient Market
Additives
Fluoropolymer Additives Market
Additives
Volatile Corrosion Inhibitors Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Inorganic Rheology Modifiers Market
Additives
Cosmetic Grade Color Additives Market
Additives
Deodorant and Antiperspirant Ingredients Market
Additives
Sodium Metabisulfite Market
Additives
Propyl Gallate Market
Additives
Metal Deactivators Market
Additives
Global Peptone Market
Additives
Sodium Citrate Anhydrous Market
Additives
Global PVC Stabilizer Market