
 China Feed Additives Market | 2026-2036
China Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
China Feed Additives Market Intelligence
China's 2020 feed antibiotic ban is restructuring capital allocation across the sector, forcing domestic mills to reformulate rations and validate alternative growth promoters. DSM Nutritional Products AG leverages its premix technology portfolio to capture premium positioning in enzyme and vitamin blends. Adisseo anchors its competitive stance through methionine capacity expansion at its Nanjing manufacturing complex. Cargill Inc. competes via integrated supply chain control from grain origination through finished additive distribution.
Feed additives comprise functional ingredients introduced to animal diets at inclusion rates typically below one percent by weight to enhance nutrient utilization, preserve feed quality, or support metabolic efficiency; formulations may incorporate organic acids, phytogenic compounds, or microbial cultures synthesized through submerged fermentation processes. Amino acids and enzymes command expanding share as producers substitute synthetic lysine and phytase for antibiotic growth promoters in poultry and swine rations. The aquaculture application segment exhibits accelerated formulation innovation as shrimp and freshwater fish producers adopt species-specific probiotic and immunostimulant protocols.
MIIT oversees feed-grade chemical production licensing while the Ministry of Agriculture and Rural Affairs enforces the national catalog of permitted additive categories and maximum inclusion thresholds. GB standards mandate heavy metal limits and mycotoxin screening protocols that shape import substitution dynamics for trace mineral and vitamin premixes. Stakeholders must monitor pending revisions to the feed additive use catalog and calibrate R&D pipelines toward microbiome-modulating solutions that satisfy both performance claims and regulatory scrutiny.
Market Dynamics
China's feed additive sector is restructuring around the post-antibiotic transition, where MIIT licensing requirements and the Ministry of Agriculture and Rural Affairs' permitted additive catalog are forcing domestic mills to validate alternative growth promoters at commercial scale.
Growth Catalysts
- Amino Acid Substitution:Swine and poultry operations in Shandong province are replacing antibiotic growth promoters with synthetic lysine and methionine formulations to maintain feed conversion ratios.
- GB Standards Enforcement:Mandatory heavy metal limits and mycotoxin screening protocols under national GB standards are accelerating import substitution for trace mineral and vitamin premixes.
- Herd Restocking Momentum:Disease-recovery programs across Henan province are concentrating demand in the swine application segment as commercial livestock operations expand capacity.
Market Restraints
- Feed-Grade Chemical Licensing:MIIT production licensing requirements create capital barriers for new entrants seeking to manufacture acidifiers and probiotic cultures.
- Grain Price Volatility:Corn and soybean meal input costs fluctuate with domestic harvest cycles and import dependency, compressing additive inclusion rate flexibility.
- Technical Validation Timelines:Microbiome-modulating solutions require extended field trials to substantiate performance claims under Ministry of Agriculture scrutiny.
Strategic Opportunities
- Aquaculture Formulation Gap:Shrimp and freshwater fish producers in coastal provinces lack species-specific immunostimulant protocols, creating white space for tailored probiotic development.
- Dual Carbon Alignment:China's national carbon neutrality targets are redirecting R&D investment toward fermentation-derived additives with lower process emissions.
- Premix Distribution Innovation:Direct-to-mill digital procurement platforms are emerging as alternatives to traditional distributor networks in provincial feed manufacturing clusters.
Industry Challenges
- Fermentation Specialist Scarcity:Submerged fermentation process expertise for microbial culture production remains concentrated among state-affiliated research institutes.
- Catalog Revision Uncertainty:Pending updates to the national feed additive use catalog force manufacturers to maintain parallel formulation pipelines for compliance contingencies.
- Integration Complexity:Legacy feed mill equipment requires retrofitting to handle heat-sensitive probiotic and enzyme formulations without compromising inclusion accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Feed Additives Market |
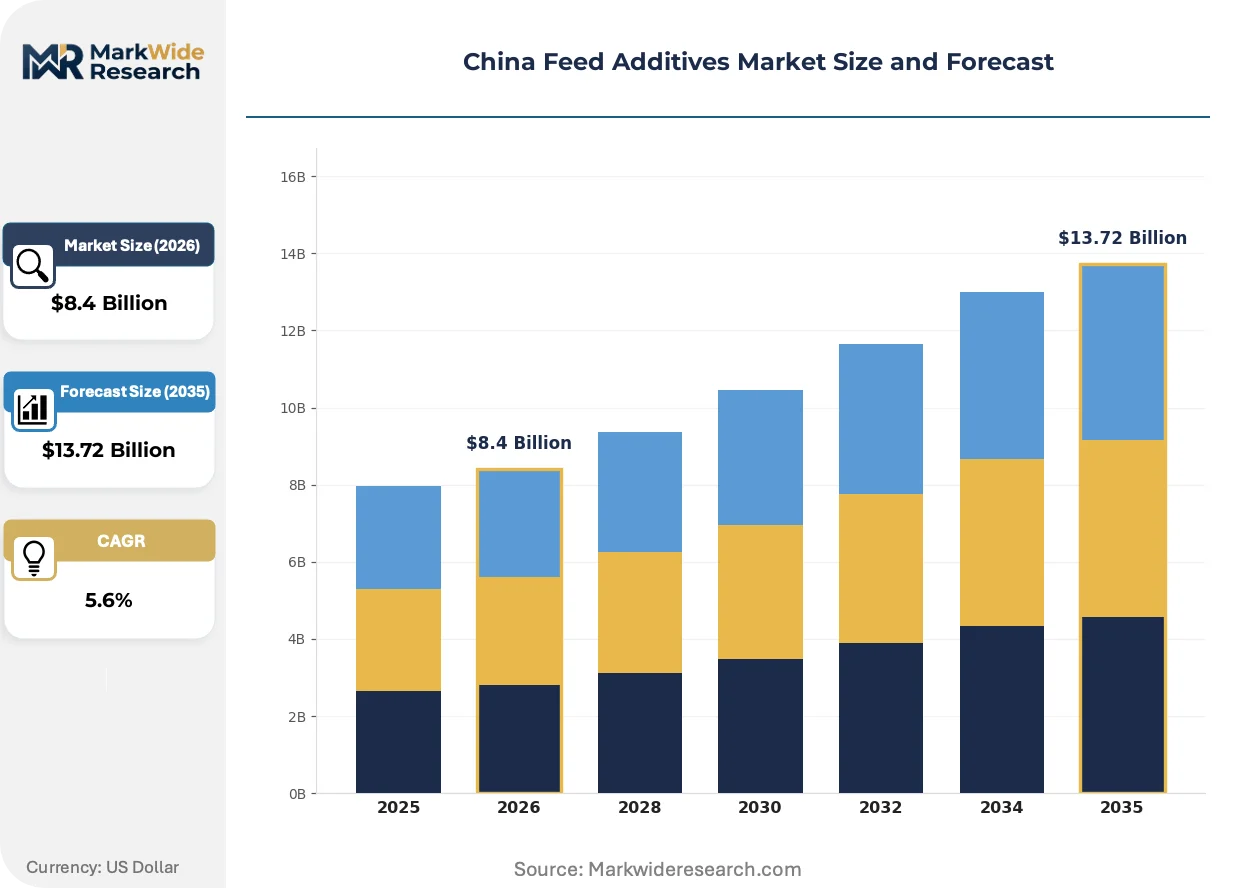
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vitamins, Amino Acids, Enzymes Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Tablet Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | DSM Nutritional Products AG, Ajinomoto Co., Inc., Adisseo, Alltech, Inc., Archer Daniels Midland Co., BASF SE, Evonik Industries, Nutreco, Cargill Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Feed Additives Market Strategic Shifts & Innovations
Formulation science is pivoting toward microbiome-targeted interventions as enzyme engineering and submerged fermentation capabilities mature. Three developments are compressing traditional additive categories and rewiring competitive positioning.
Phytase enzyme engineering is absorbing capital allocation previously directed toward mineral premixes. Layer and broiler operations in Hebei province are adopting next-generation phytase variants at accelerated trial-to-commercial cycles. The technology is absorbing market share from inorganic phosphorus sources by enabling complete substitution in corn-soy rations.
MIIT is tightening feed-grade chemical production licensing thresholds for acidifier manufacturing facilities. This regulatory friction is consolidating active ingredient synthesis capacity toward integrated chemical parks in Jiangsu province. Acidifier producers are responding by co-lating fermentation operations with existing amino acid facilities to share utilities and waste treatment infrastructure.
Commercial livestock buyers are unbundling technical service contracts from additive procurement agreements. Large swine integrators in Sichuan province are hiring in-house nutritionists to formulate rations independently, displacing traditional premix supplier advisory relationships. This behavior is most visible among operations exceeding 50,000 head annual throughput, where internal formulation capabilities justify dedicated staffing.
China Feed Additives Market Segmentation
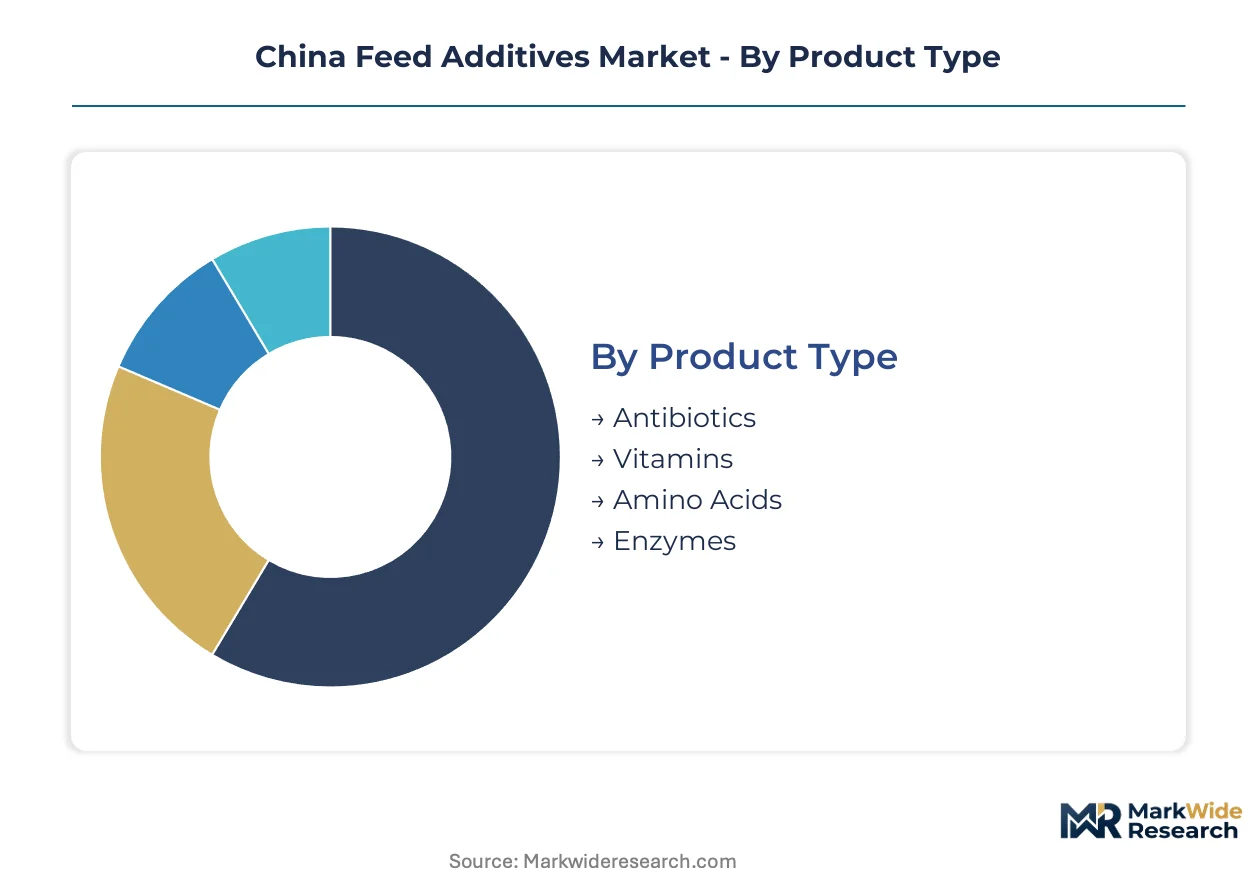
Feed additive segmentation in China reflects divergent capital requirements across manufacturing modalities. Fermentation-based categories demand submerged bioreactor infrastructure, while blending operations require lower fixed-asset thresholds.
Product Type:
Capital intensity peaks in microbial culture production, where submerged fermentation demands stainless-steel vessel networks and sterile utility systems.
- Amino Acids:Synthetic lysine and methionine production relies on Corynebacterium glutamicum fermentation at industrial scale. Shandong province hosts the densest concentration of fermentation capacity as producers expand threonine and tryptophan lines to complete the essential amino acid portfolio.
- Enzymes:Phytase and xylanase manufacturing requires precision-controlled submerged fermentation with downstream spray-drying infrastructure. Hebei poultry integrators are trialing next-generation thermostable variants that survive pelleting temperatures without coating protection.
- Antibiotics:Post-ban inventory drawdown continues for residual therapeutic applications under veterinary prescription protocols.
- Vitamins:Chemical synthesis and fermentation routes compete for fat-soluble and B-complex categories, with Nanjing chemical parks consolidating active ingredient production.
Amino Acids absorbs the bulk of installed capacity; Enzymes is expanding most quickly.
Application:
Volume concentration varies sharply by species, with monogastric operations driving formulation standardization.
- Swine:Sow and grower-finisher phases consume the largest additive volumes per head, with lysine inclusion rates exceeding poultry rations. Henan province restocking programs are concentrating demand as commercial operations rebuild breeding stock.
- Poultry:Layer and broiler cycles favor phytase-heavy formulations to reduce inorganic phosphorus discharge. Hebei integrators are adopting high-dose phytase protocols that enable complete corn-soy diet reformulation.
- Aquaculture:Shrimp and freshwater fish producers in coastal provinces lack species-specific immunostimulant standards, creating formulation white space.
- Ruminants:Dairy and beef operations in northern provinces utilize ionophores and yeast cultures for rumen efficiency, though penetration lags monogastric sectors.
Swine commands the dominant volume share; Aquaculture is gaining share fastest.
Form:
Physical presentation determines handling infrastructure requirements and heat stability margins.
- Powder:Standard presentation for amino acids and acidifiers, requiring pneumatic conveying systems and dust control infrastructure. Most Shandong mills operate dedicated powder handling lines.
- Granular:Coated enzyme and probiotic formats protect heat-labile actives during feed pelleting. Demand is climbing as extrusion temperatures rise in high-energy poultry diets.
- Liquid:Acidifiers and some vitamin premixes utilize tanker delivery to large integrators with on-site storage.
- Tablet:Niche presentation for veterinary-directed therapeutic additives in smaller herd contexts.
Powder retains the largest installed base; Granular is climbing the fastest.
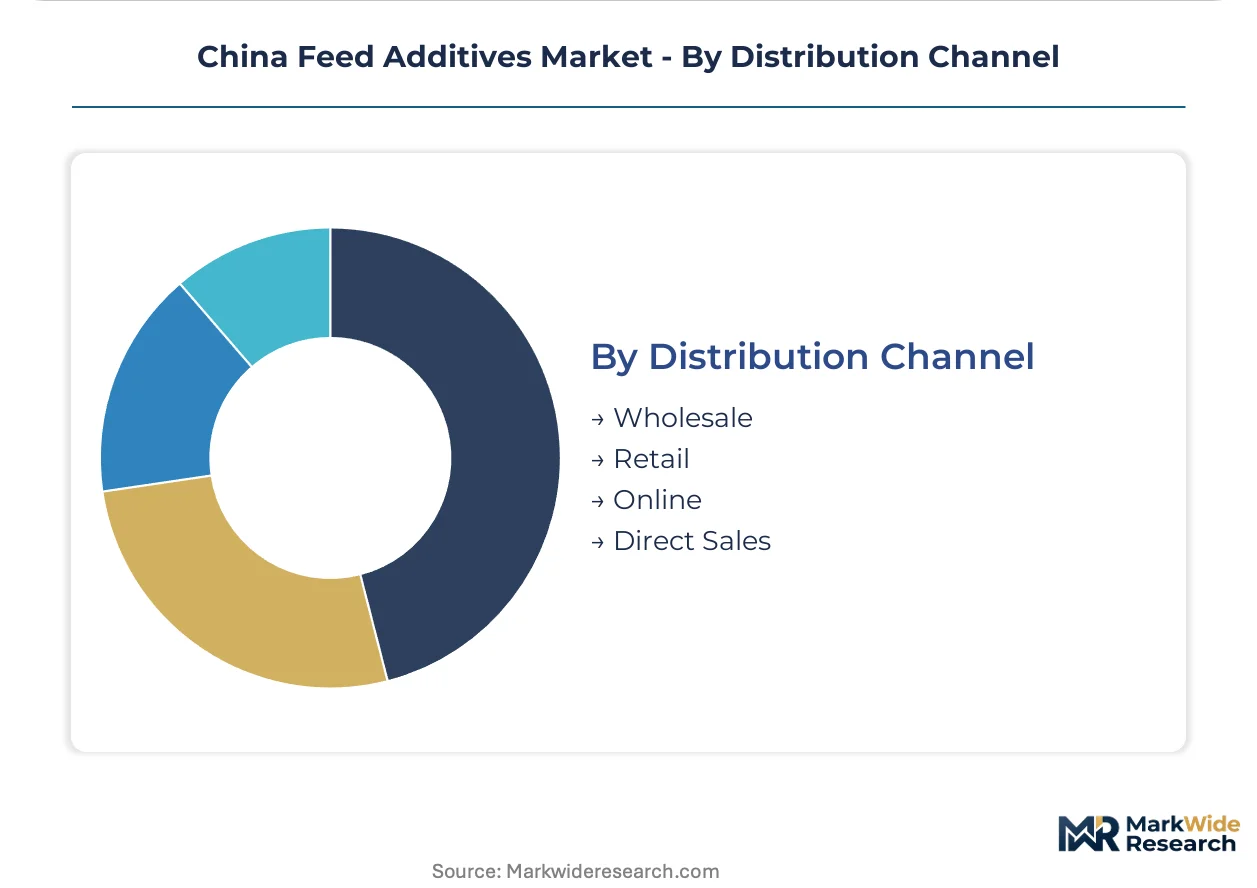
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements.
- Direct Sales:Large integrators above 50,000 head annual throughput negotiate directly with additive manufacturers, unbundling technical advisory from procurement. Sichuan swine operations are leading this disintermediation.
- Wholesale:Provincial distributors serve mid-tier feed mills with consolidated additive and raw material offerings.
- Online:Digital procurement platforms are emerging in feed manufacturing clusters, though penetration remains limited to standard products.
- Retail:Smallholder-focused channels serve backyard operations with pre-formulated premix packages.
Direct Sales captures the highest value concentration; Online is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate fermentation capacity and draw additive manufacturers seeking preferential tax treatment and streamlined MIIT licensing procedures.
Shandong Province
Commercial swine operations in Shandong consume the largest lysine volumes as herd restocking accelerates post-disease outbreaks. Provincial environmental bureaus enforce stricter wastewater discharge standards for fermentation facilities. Jinan chemical parks host dense amino acid manufacturing clusters where producers expand threonine and tryptophan lines.
Henan Province
Hog breeding stock rebuilding programs in Henan concentrate demand for grower-finisher additive formulations. Ministry of Agriculture and Rural Affairs inspectors validate alternative growth promoters through extended field trials here. Zhengzhou feed manufacturing clusters drive acidifier procurement as mills reformulate rations.
Jiangsu Province
Integrated chemical parks in Jiangsu consolidate active ingredient synthesis for acidifier and enzyme production. MIIT licensing thresholds for feed-grade chemical facilities tightened in 2023, favoring existing permit holders. Nanjing manufacturing complexes anchor methionine capacity expansion projects.
Hebei Province
Poultry integrators in Hebei trial next-generation thermostable phytase variants at accelerated commercial cycles. GB standards enforcement for heavy metal limits shapes trace mineral premix sourcing decisions. Baoding feed mill clusters adopt high-dose phytase protocols enabling complete corn-soy diet reformulation.
Sichuan Province
Large swine integrators exceeding 50,000 head annual throughput in Sichuan unbundle technical advisory from additive procurement. Provincial agricultural technology extension stations support in-house nutritionist staffing at commercial operations. Chengdu manufacturing basins witness direct-to-mill digital procurement platform emergence.
China Feed Additives Market Key Industry Players
European and Japanese producers anchor the premium premix tier; domestic Chinese specialists hold mid-market fermentation capacity. The vendor structure concentrates around amino acid and enzyme categories where capital requirements filter entrants. Three archetypes dominate: integrated chemical conglomerates with backward synthesis control, dedicated fermentation technology houses, and grain-trading houses with captive additive distribution. Capacity expansion and direct sales channel development constitute the primary competitive vectors.
Within the integrated chemical tier, DSM Nutritional Products AG and BASF SE occupy positions leveraging premix technology portfolios for premium enzyme and vitamin blend positioning. Among dedicated fermentation specialists, Ajinomoto Co., Inc. and Adisseo exemplify amino acid capacity concentration through Corynebacterium glutamicum industrial platforms. Cargill Inc. anchors the grain-integrated archetype, representing supply chain control from origination through finished additive distribution.
| Leading Market Players |
|---|
| DSM Nutritional Products AG |
| Ajinomoto Co., Inc. |
| Adisseo |
| Alltech, Inc. |
| Archer Daniels Midland Co. |
| BASF SE |
| Evonik Industries |
| Nutreco |
| Cargill Inc. |
| Others |
Cost & Logistics Intelligence
State-affiliated fermentation specialists and family-owned mid-cap premix blenders anchor supply ownership patterns across Shandong and Jiangsu, tightening pricing discipline through captive amino acid capacity and direct mill relationships that bypass distributor markups.
Pricing Analysis
Short lead-time premiums dominate amino acid contracting, with Shandong lysine producers commanding spreads over spot inventory held by provincial distributors. Contract-based long-term offtake structures separate DSM and Adisseo premix tiers from economy acidifier blends, where price differentiation hinges on GB certification grade and bundled technical advisory. Pricing pressure stems from corn and soybean meal cost volatility compressing inclusion rate flexibility at Henan feed mills. Smallholder-facing retail channels exhibit acute price sensitivity, while Sichuan integrators above 50,000 head tolerate premium enzyme formulations for feed conversion ratio gains.
Supply Chain Analysis
Reverse-logistics flows for expired vitamin premixes and heat-damaged probiotic shipments remain underdeveloped, creating working capital drag for distributors lacking cold-chain reclamation infrastructure. Active ingredient synthesis concentrates in China, with Nanjing chemical parks and Shandong fermentation clusters supplying domestic mills; specialty enzymes draw from Danish and Dutch toll manufacturers. Corynebacterium glutamicum cultures, corn-derived glucose feedstocks, and stainless-steel bioreactor vessels constitute critical input dependencies. Single-source vulnerability pervades submerged fermentation expertise concentrated at state-affiliated research institutes. Distribution runs through direct sales channels for large integrators and provincial wholesale networks for mid-tier mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where backward control over fermentation capacity and forward capture of direct mill relationships determine margin sustainability.
For Market Incumbents: Anticipate MIIT licensing threshold tightening by securing acidifier and enzyme permits in Jiangsu chemical parks before regulatory consolidation accelerates. Defend position against Sichuan integrator disintermediation through embedding in-house nutritionists at client operations, converting technical advisory from cost center to retention lever. Prioritize threonine and tryptophan line completion to close essential amino acid portfolio gaps against Adisseo methionine expansion. For New Entrants and Emerging Players: The premium-economy price-point gap in aquaculture immunostimulants offers white-space entry, as coastal shrimp producers lack species-specific protocols and tolerate formulation premiums for survival rate improvements. Target Hebei poultry integrators trialing thermostable phytase variants, where next-generation enzyme engineering displaces mineral premix inclusion. Deploy direct-to-mill digital procurement platforms in Chengdu manufacturing basins to bypass legacy distributor networks. For Investors and Strategic Acquirers: Pending revisions to the Ministry of Agriculture and Rural Affairs feed additive use catalog are the leading indicator that microbiome-modulating solution providers will face extended validation timelines, compressing venture-stage valuations and creating acquisition windows. Long-term viability centers on fermentation-derived additive platforms aligned with dual carbon targets. Target mid-cap premix specialists with captive Shandong amino acid capacity and unexploited direct sales infrastructure. Monitor GB standards enforcement intensity for heavy metal limits as the signal for import substitution acceleration in trace mineral categories.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adisseo methionine expansion at Nanjing anchors domestic supply security against import dependency. |
| Backward Integration | DSM premix technology portfolio leverages captive enzyme fermentation to capture GB-certified premium tiers. |
| Long-term Supply Agreement | Cargill grain origination-through-distribution control locks corn input costs for Shandong mill clusters. |
| Joint Venture | State-affiliated research institute partnerships unlock submerged fermentation expertise scarcity for probiotic culture production. |
| Geographic Expansion | Hebei poultry integrator trials of thermostable phytase variants accelerate next-generation enzyme commercial adoption. |
Research Approach
Document review covered MIIT licensing registries, Ministry of Agriculture and Rural Affairs feed additive use catalog revisions, and GB standards enforcement bulletins, complemented by interviews with Shandong fermentation plant managers, Henan feed mill procurement leads, Sichuan swine integrator nutritionists, and Jiangsu chemical park technical directors. Secondary validation drew from customs trade data for amino acid import flows, SEC 10-K filings for multinational additive producers, and provincial environmental bureau discharge monitoring reports. Bottom-up capacity surveys triangulated against top-down demand modeling from swine and poultry herd restocking statistics.
Segmentation outputs across product type, application species, physical form, and distribution channel were generated through the projection horizon. CAGRs were derived from weighted capacity expansion pipelines, regulatory transition timelines for antibiotic alternatives, and species-specific feed conversion ratio improvement trajectories. Modeled inputs included lysine inclusion rate elasticity, phytase substitution coefficients for inorganic phosphorus, and aquaculture probiotic penetration assumptions for coastal provinces.
Inputs from MIIT licensing databases and Ministry of Agriculture field trial registries were available through the study window; gaps in commercial-scale microbiome-modulating solution performance data introduce uncertainty bands around probiotic and acidifier growth projections. Forecasts reflect assumptions regarding catalog revision timing and dual carbon alignment enforcement intensity. Practitioners should monitor pending GB standards updates and provincial environmental bureau wastewater discharge tightening for early signals of fermentation capacity relocation and import substitution acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Choline Chloride Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Feedstuff Additives Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Adjustive Agents Market
Additives
Indonesia Feed Additives Market
Additives
Ethoxyquin Market
Additives
Magnesium Stearate Market
Additives
Green Polymer Additive Market
Additives
Texture Modifier Market
Additives
Alkyl Acetates Market
Additives
Hexyl Acetate Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Guanylic Acid Market
Additives
Global Chelated Trace Minerals Market
Additives
Sorbitan Esters Market