
 United Kingdom Sodium Reduction Ingredient Market | 2026-2036
United Kingdom Sodium Reduction Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Sodium Reduction Ingredient Market Analytics
The capability gap between capital-heavy multinationals and agile domestic specialists is bifurcating the United Kingdom Sodium Reduction Ingredient Market. Tate & Lyle PLC leverages its integrated sweetener and texture platforms to cross-sell sodium reduction systems into bakery and beverage accounts. Kerry Group plc sustains formulation partnerships with major UK retailers, embedding its taste modulation technologies into private-label development pipelines. Celtic Chemicals Ltd competes through regional distribution density and responsive mineral blend customization for mid-tier sauce producers.
Sodium reduction ingredients comprise functional compounds—potassium chloride, yeast extracts, mineral salts, and flavor modulators—engineered to replicate or enhance salt perception while delivering less than 40 percent sodium content by equivalent weight. These materials undergo spray-drying, fermentation, or controlled crystallization to achieve particle sizes and dissolution profiles matching standard table salt for seamless manufacturing substitution. Potassium chloride dominates product type value contribution due to its direct sodium replacement efficacy and established GRAS status, though mineral blends capture expanding share as manufacturers seek multi-ion solutions masking bitter off-notes. Within applications, processed foods anchor volume demand while meat products represent the fastest structural expansion as British processors reformulate cured and comminuted products ahead of evolving retail specifications.
Public Health England's voluntary salt reduction targets, enforced through the Food Standards Agency's monitoring framework, compel continuous reformulation investment across UK food manufacturing. The Competition and Markets Authority scrutinizes supply arrangements for potassium-based inputs, influencing long-term contracting behavior between ingredient suppliers and national retailers. Stakeholders must track the transition from voluntary to potential mandatory sodium limits, as this policy inflection would accelerate technical service intensity and reshape procurement criteria across British food production.
Market Dynamics
Public Health England's voluntary salt reduction targets, monitored through the Food Standards Agency framework, are compressing formulation timelines and forcing continuous ingredient substitution across British food manufacturing.
Growth Catalysts
- Regulatory pressure from Public Health England:The agency's progressive sodium reduction targets create mandatory reformulation cycles that lock in recurring demand for functional salt replacers across sauce, bread, and processed meat categories.
- Processed meat sector expansion:British cured and comminuted meat processors are accelerating sodium reduction ingredient adoption to meet evolving retail buyer specifications and avoid delisting from major supermarket chains.
- Yorkshire and Midlands industrial concentration:England's food processing corridors generate geographic clustering effects that reduce logistics costs and enable rapid technical service response for mid-tier manufacturers.
Market Restraints
- Potassium chloride supply concentration:UK sourcing depends heavily on limited European and Middle Eastern suppliers, exposing formulators to input volatility and currency-driven cost swings.
- Bitter off-note technical limitation:High-concentration potassium chloride creates metallic aftertastes that require expensive masking systems, compressing margins for price-sensitive sauce producers.
- Competition and Markets Authority scrutiny:The regulator's review of long-term potassium supply contracts is extending procurement timelines and discouraging exclusive supplier arrangements.
Strategic Opportunities
- Wales and Northern Ireland underpenetration:These regions host smaller meat processing clusters with limited technical formulation support, creating whitespace for mineral blend suppliers offering turnkey sodium reduction systems.
- Clean-label yeast extract convergence:The intersection of fermentation-derived umami technologies and natural positioning claims is opening premium positioning in organic and free-from product lines.
- Potential mandatory sodium limits:A policy shift from voluntary to compulsory thresholds would eliminate reformulation delays and accelerate technical service intensity across all British food production.
Industry Challenges
- Sensory science talent scarcity:British universities produce insufficient flavor chemists and food technologists trained in multi-ion salt replacer optimization, forcing suppliers to recruit from continental Europe.
- Legacy equipment incompatibility:Many Midlands bakeries and sauce plants operate aging mixing and drying equipment that cannot achieve the precise particle size distribution required for modern mineral salt blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Sodium Reduction Ingredient Market |
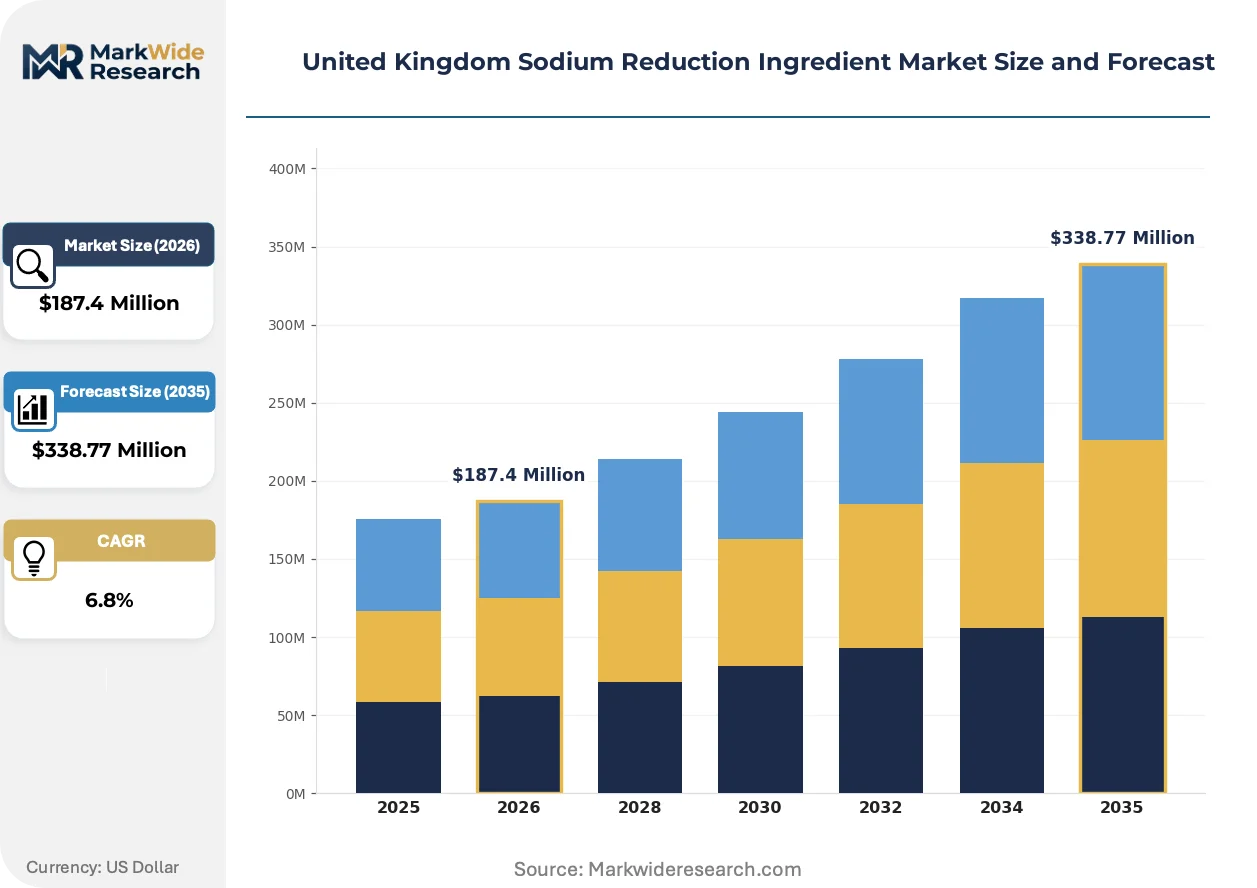
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt Substitutes, Flavor Enhancers, Potassium Chloride, Mineral Blends Application: Processed Foods, Sauces, Snacks, Meat Products Form: Granular, Liquid, Powder, Blends End User: Food Manufacturers, Restaurants, Retailers, Food Service Companies |
| Companies Covered | Lallemand Inc., ABF Ingredients Group (Ohly GmbH), Synergy Flavours, Celtic Chemicals Ltd, Absco Limited, Barentz, Kerry Group plc, Tate & Lyle PLC, Associated British Foods plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Sodium Reduction Ingredient Market Evolving Landscape
Fermentation-derived taste modulation technologies are displacing conventional mineral salt blends in premium formulation pipelines, while regulatory monitoring intensifies and procurement patterns compress.
Microencapsulated potassium chloride is decomposing the traditional trade-off between sodium reduction efficacy and sensory acceptability. Bakery manufacturers in England's industrial corridors are adopting these systems at accelerating rates to maintain texture integrity in reduced-salt bread. The technology is decomposing incumbent single-ingredient potassium chloride margins by enabling lower usage rates and cleaner label declarations.
Public Health England's salt reduction targets, enforced through Food Standards Agency monitoring, are mandating continuous reformulation investment rather than one-time product changes. The framework's progressive 2024 targets for bread, breakfast cereals, and processed meats have triggered technical service expansions by ingredient suppliers. Meat processors in Yorkshire are responding with dedicated sodium reduction R&D facilities to maintain retailer compliance.
Supermarket private-label development pipelines are consolidating supplier relationships around full-service formulation partners capable of delivering finished taste systems rather than commodity inputs. This behavior shift is displacing transactional mineral salt vendors from strategic accounts. The pattern is most visible in England, where Tesco, Sainsbury's, and Asda dominate processed food procurement and specify integrated sodium-taste-texture solutions.
United Kingdom Sodium Reduction Ingredient Market Segmentation
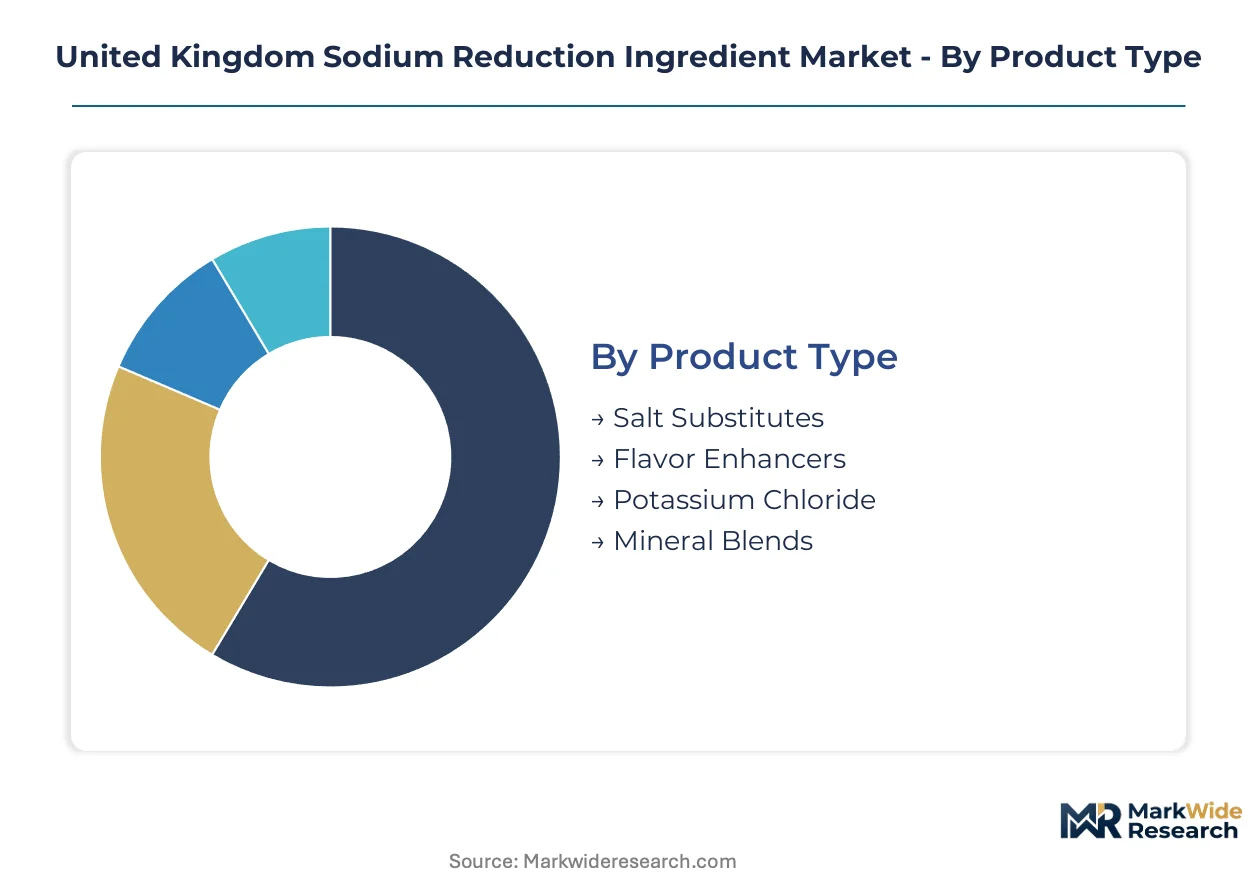
Segmentation in the United Kingdom Sodium Reduction Ingredient Market reveals distinct procurement patterns across product categories. Channel dynamics vary sharply between commodity mineral salts and integrated taste systems, with formulation complexity driving supplier selection criteria.
Product Type:
Channel mix varies by technical sophistication—potassium chloride and mineral blends flow through bulk chemical distributors to large manufacturers, while flavor enhancers and advanced salt substitutes route through specialty ingredient houses with technical service capabilities.
- Potassium Chloride:Crystalline potassium salt with established GRAS status delivers direct sodium replacement at 1:1 equivalence ratios. Demand concentrates in Yorkshire meat processing corridors where cured product reformulation accelerates ahead of retail compliance deadlines. Bitter off-notes at high inclusion rates force masking system investments that compress margins for mid-tier sauce producers.
- Mineral Blends:Multi-ion formulations combine potassium, magnesium, and calcium salts with optimized particle size distribution for seamless manufacturing substitution. England's industrial food processing clusters in the Midlands generate geographic clustering effects that reduce logistics costs and enable rapid technical response for bakery accounts seeking clean-label sodium reduction.
- Salt Substitutes:Engineered compounds replicate salt perception through synergistic mineral and organic component combinations.
- Flavor Enhancers:Yeast extracts and fermentation-derived umami compounds amplify salt perception at reduced sodium levels.
By volume, potassium chloride leads. By growth pace, mineral blends are expanding most quickly.
Application:
Cost tier differentiation separates premium positioning in meat products from commodity-grade supply into processed foods, with technical service intensity climbing across all tiers.
- Meat Products:Cured and comminuted applications demand precise ionic balance to maintain protein functionality and water-binding capacity. British processors in Yorkshire and the Midlands accelerate sodium reduction R&D facility investments to maintain Tesco, Sainsbury's, and Asda compliance specifications. Retail delisting risk drives premium pricing tolerance for integrated taste-texture systems.
- Processed Foods:Bread, breakfast cereals, and ready meals anchor baseline volume demand with standardized mineral blend specifications. England's industrial corridors generate procurement consolidation around full-service formulation partners capable of delivering finished taste systems rather than commodity inputs.
- Sauces:High-acid and emulsified formulations require specialized dissolution profiles to prevent phase separation.
- Snacks:Surface application and topical seasoning applications drive powder form factor preferences.
By volume, processed foods lead. By growth pace, meat products gain share fastest.
Form:
Volume concentration favors granular and powder formats compatible with legacy mixing equipment, while liquid and specialized blends capture premium positioning in reformulation-intensive accounts.
- Granular:Crystalline structure matches conventional salt handling characteristics for direct equipment substitution. Midlands bakeries with aging mixing infrastructure prefer this format to avoid capital expenditure on particle size-sensitive systems.
- Powder:Fine particle distribution enables rapid dissolution in high-moisture applications. Snack seasoning operations in England's processing corridors specify this form for uniform surface coating.
- Liquid:Pre-dissolved ionic solutions suit high-throughput injection and brining operations.
- Blends:Pre-mixed multi-component systems reduce formulation complexity for mid-tier manufacturers.
By volume, granular leads. By growth pace, specialized blends show the steepest expansion trajectory.
End User:
Customer type determines procurement pattern—national retailers and large food manufacturers consolidate around integrated suppliers, while food service and restaurant channels fragment across regional distributors.
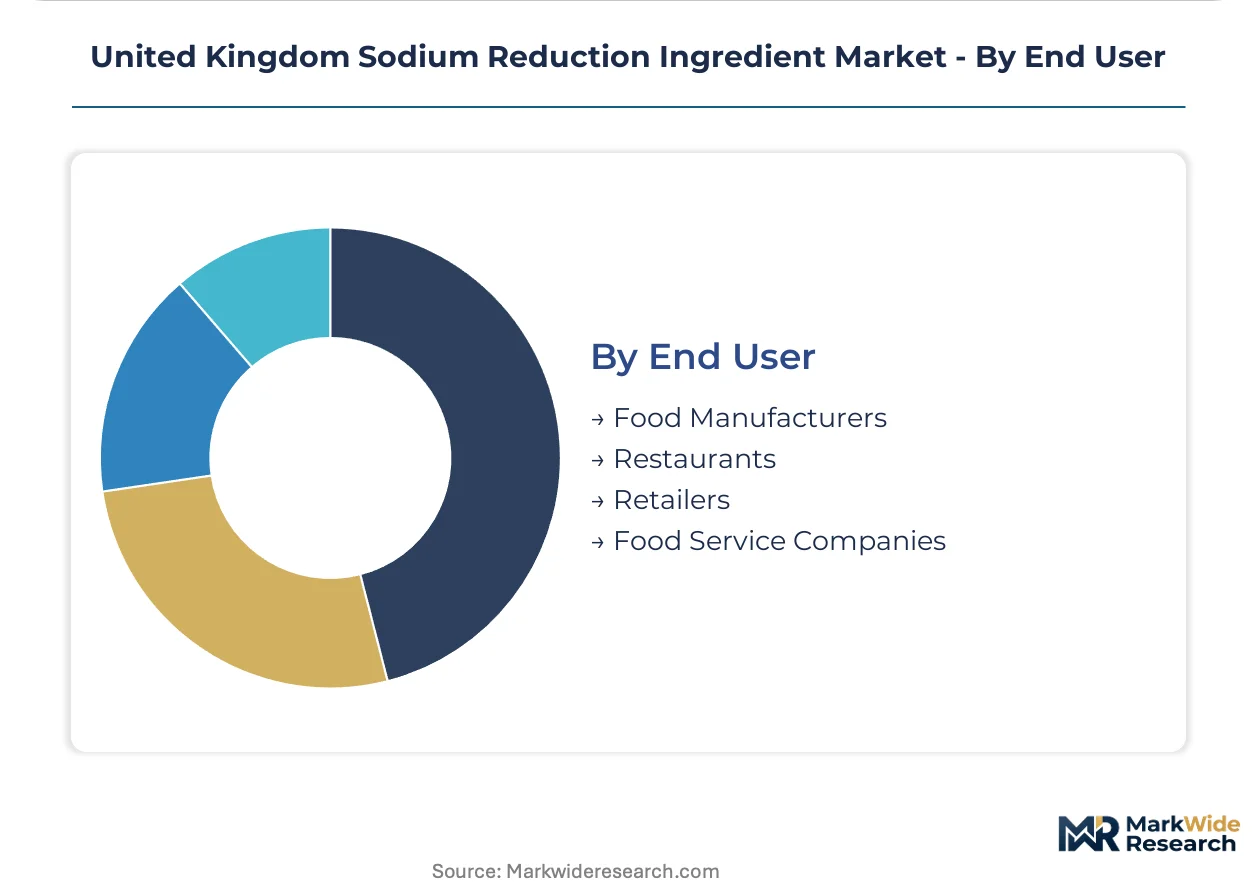
- Food Manufacturers:National processed food producers in England drive specification-setting for sodium reduction ingredient categories. Private-label development pipelines at Tesco, Sainsbury's, and Asda consolidate supplier relationships around full-service formulation partners delivering integrated sodium-taste-texture solutions.
- Retailers:Supermarket chains specify ingredient standards for supplier-branded and private-label products. Technical service intensity climbs as procurement teams demand finished taste system validation rather than commodity mineral salt certificates of analysis.
- Restaurants:Chain operators with centralized procurement specify sodium reduction ingredients for menu reformulation.
- Food Service Companies:Institutional caterers and contract food service operators lag in adoption due to cost sensitivity.
By volume, food manufacturers lead. By growth pace, retailers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's industrial food processing corridors command premium pricing power over Welsh and Northern Irish markets, where technical service infrastructure remains sparse and logistics costs inflate ingredient procurement. This asymmetry shapes supplier investment priorities and customer consolidation patterns across the United Kingdom.
England
Yorkshire and the Midlands anchor national demand for sodium reduction ingredients, with meat processors and bakery manufacturers driving bulk mineral blend procurement. Public Health England's voluntary salt reduction targets, enforced through Food Standards Agency monitoring, compress reformulation timelines for processors supplying Tesco, Sainsbury's, and Asda. The Yorkshire cured meat corridor hosts dedicated sodium reduction R&D facilities as processors invest to maintain retailer compliance specifications.
Scotland
Scottish meat and seafood processors generate concentrated demand for clean-label yeast extract systems, particularly in smoked salmon and premium sausage categories. The Scottish Government's dietary improvement programs align with UK-wide sodium reduction frameworks, though enforcement relies on Food Standards Agency Scotland coordination. Edinburgh and Glasgow food technology clusters attract fermentation-derived taste modulation specialists seeking proximity to premium protein processors.
Wales
Welsh meat processing clusters exhibit underpenetration by integrated sodium reduction suppliers, with mid-tier processors relying on commodity mineral salt distributors lacking technical formulation support. The Welsh Government's food and drink strategy references salt reduction targets without independent enforcement mechanisms beyond UK frameworks. The Wrexham and Newport processing zones present whitespace opportunities for turnkey mineral blend suppliers offering rapid-response technical service.
Northern Ireland
Northern Ireland's meat and dairy processors face elevated logistics costs for potassium chloride and specialized mineral blends sourced through English distribution hubs. The Food Standards Agency Northern Ireland implements UK-wide monitoring frameworks without region-specific acceleration of mandatory thresholds. Belfast-area processors concentrate procurement through cross-border Irish Republic suppliers to circumvent mainland UK supply chain friction.
United Kingdom Sodium Reduction Ingredient Market Competitive Landscape
Concentration sits with integrated multinational ingredient houses that combine sweetener, texture, and taste modulation platforms to deliver full-service sodium reduction systems. The vendor base stratifies into three tiers: capital-heavy multinationals with cross-category formulation partnerships, regional mineral blend specialists with responsive customization capabilities, and commodity distributors lacking technical service infrastructure. Dominant competitive moves include portfolio diversification into adjacent taste technologies and strategic partnerships with major UK retailers embedding supplier systems into private-label development pipelines.
Within the multinational tier, Tate & Lyle PLC and Kerry Group plc occupy positions as anchor suppliers to national food manufacturers and supermarket chains. Celtic Chemicals Ltd exemplifies the regional specialist archetype, competing through distribution density and mineral blend customization for mid-tier sauce and processed food producers. Lallemand Inc. represents the fermentation-derived technology vector, with yeast extract positioning converging with clean-label demand trends. These three companies illustrate the competitive spectrum spanning integrated platforms, regional responsiveness, and biotechnology specialization.
| Leading Market Players |
|---|
| Lallemand Inc. |
| ABF Ingredients Group (Ohly GmbH) |
| Synergy Flavours |
| Celtic Chemicals Ltd |
| Absco Limited |
| Barentz |
| Kerry Group plc |
| Tate & Lyle PLC |
| Associated British Foods plc |
| Others |
Value Network & Pricing Analysis
Scale economies in potassium chloride crystallization anchor price floors across the United Kingdom Sodium Reduction Ingredient Market, compressing margins for mid-tier mineral blend suppliers while concentrating procurement leverage among Yorkshire meat processors and Midlands bakery manufacturers operating at industrial volumes.
Pricing Analysis
The customization-premium spread separates commodity potassium chloride from configured mineral blends and integrated taste systems. Three-tier pricing structure across premium, standard, and economy levels tracks technical service intensity and formulation complexity. Price differentiation hinges on GRAS certification tier and geographic delivery cost from England's industrial corridors. Pricing pressure stems from Competition and Markets Authority scrutiny extending procurement timelines. Food manufacturers exhibit highest price sensitivity, while retailers tolerate premium positioning for compliant private-label systems.
Supply Chain Analysis
Belgium and the Netherlands anchor potassium chloride refining capacity feeding British formulators, with secondary flows from Israel and Jordan. Raw material dependencies center on potash ore, magnesium hydroxide, and fermentation substrates for yeast extract production. Single-source vulnerability concentrates in potassium chloride offtake agreements with limited European suppliers. Distribution runs through bulk chemical distributors to large manufacturers, with specialty ingredient houses routing advanced salt substitutes and flavor modulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Sodium Reduction Ingredient Market functions as a service-attach opportunity where technical formulation support and ongoing compliance consulting expand faster than commodity mineral salt volumes.
For Market Incumbents: Shield core Yorkshire and Midlands accounts by embedding dedicated R&D facilities within customer plants, matching Celtic Chemicals' regional responsiveness while exploiting scale advantages in potassium chloride procurement. Backward integration into fermentation capacity secures yeast extract supply against Lallemand's biotechnology specialization. Prioritize certification maintenance for evolving Food Standards Agency monitoring frameworks.
For New Entrants and Emerging Players: BRC certification fast-tracks access to Tesco, Sainsbury's, and Asda private-label pipelines, compressing incumbent relationship timelines. Wales and Northern Ireland meat processing clusters offer penetrable whitespace with limited technical service infrastructure. Position turnkey mineral blend systems with rapid-response formulation support as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated taste-texture suppliers embedding multi-year formulation partnerships with national retailers. Five-to-ten year viability favors mineral blend specialists with regional distribution density and responsive customization capabilities. Monitor Public Health England's transition trajectory from voluntary to mandatory sodium limits as the critical inflection signal accelerating technical service intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Facility Expansion | Dedicated Yorkshire R&D centers lock in meat processor compliance partnerships ahead of retail deadlines. |
| Fermentation Capacity Buildout | In-house yeast extract production secures clean-label positioning against biotechnology competitors. |
| Regional Distribution Densification | Wales and Northern Ireland hubs exploit underpenetrated meat processing clusters with rapid-response capabilities. |
| Retailer Private-Label Partnership | Embedded formulation teams at Tesco and Sainsbury's displace transactional mineral salt vendors. |
| Regulatory Compliance Certification | Food Standards Agency-aligned validation accelerates procurement approval for reformulation-intensive accounts. |
Research Methodology
A spread of perspectives from ingredient procurement managers, food technology directors, regulatory affairs leads at Public Health England, and commercial directors at potassium chloride distributors converged on the working assumptions shaping this analysis. Primary interviews combined with secondary validation from Food Standards Agency monitoring reports, Competition and Markets Authority filings, and British Retail Consortium certification databases. Bottom-up volume modeling triangulated against top-down value estimates across the projection horizon.
Segmentation dimensions modeled include product type tier, application category, form factor, and end-user archetype, with regional production cluster as an industry-specific overlay. CAGRs derived from trend extrapolation anchored in documented reformulation cycles and regulatory compliance timelines. Forecast inputs incorporated Public Health England target progression scenarios and supermarket private-label development pipeline velocities.
Underlying assumptions cover sustained regulatory pressure and stable potassium chloride supply availability, with deviation risk concentrated in policy shifts to mandatory sodium limits and currency-driven input cost volatility. Recalibration cycles align with material shifts in Food Standards Agency enforcement intensity and retailer compliance specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Monocalcium Phosphate Market
Additives
North America Phosphate Esters Market
Additives
Global Propyl Acetate Market
Additives
Grease Additives Market
Additives
Weighing Agents Market
Additives
Glacial Acetic Acid Market
Additives
Green Polymer Additive Market
Additives
Wax Additives Market
Additives
Global Cement and Concrete Additives Market
Additives
Sodium Citrate Dihydrate Market
Additives
Thermal Conductive Additives Market
Additives
Global Pour Point Depressant Market
Additives
Refinery Fuel Additives Market
Additives
Octane Improver Fuel Additives Market
Additives
Global Isononanoic Acid Market
Additives
Sorbitan Tristearate Market