
 Europe Superabsorbent Polymers Market | 2026-2036
Europe Superabsorbent Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Superabsorbent Polymers Market Foresight
Buyer concentration among European personal care manufacturers is consolidating as private-label brands and multinational hygiene companies scale procurement volumes. BASF SE leverages its Ludwigshafen production complex to sustain polymer supply continuity across Central European diaper producers. Evonik Industries AG anchors its position through specialized superabsorbent grades engineered for thin-core hygiene architectures.
Superabsorbent polymers are cross-linked hydrophilic networks, typically sodium or potassium polyacrylates, capable of absorbing hundreds of times their dry mass in aqueous fluid through osmotic gradient mechanisms; they function primarily as fluid-locking cores in disposable hygiene products and controlled-release matrices in agriculture. Sodium polyacrylate dominates volume consumption in diaper and adult incontinence applications where absorption capacity under load determines product performance. Agricultural aids represent the fastest-expanding end-user segment as European growers adopt hydrogel-infused substrates to reduce irrigation frequency amid water-stress regulations.
REACH registration requirements and the EU Green Deal's sustainable chemistry mandates are reshaping monomer sourcing and biodegradability testing protocols for SAP manufacturers operating within Europe. ECHA substance evaluations and the F-Gas Regulation indirectly influence process chemistry choices by restricting fluorinated compounds in related polymerization equipment. Stakeholders must monitor evolving Ecodesign criteria and national extended producer responsibility schemes that will determine cost structures for single-use absorbent products.
Market Dynamics
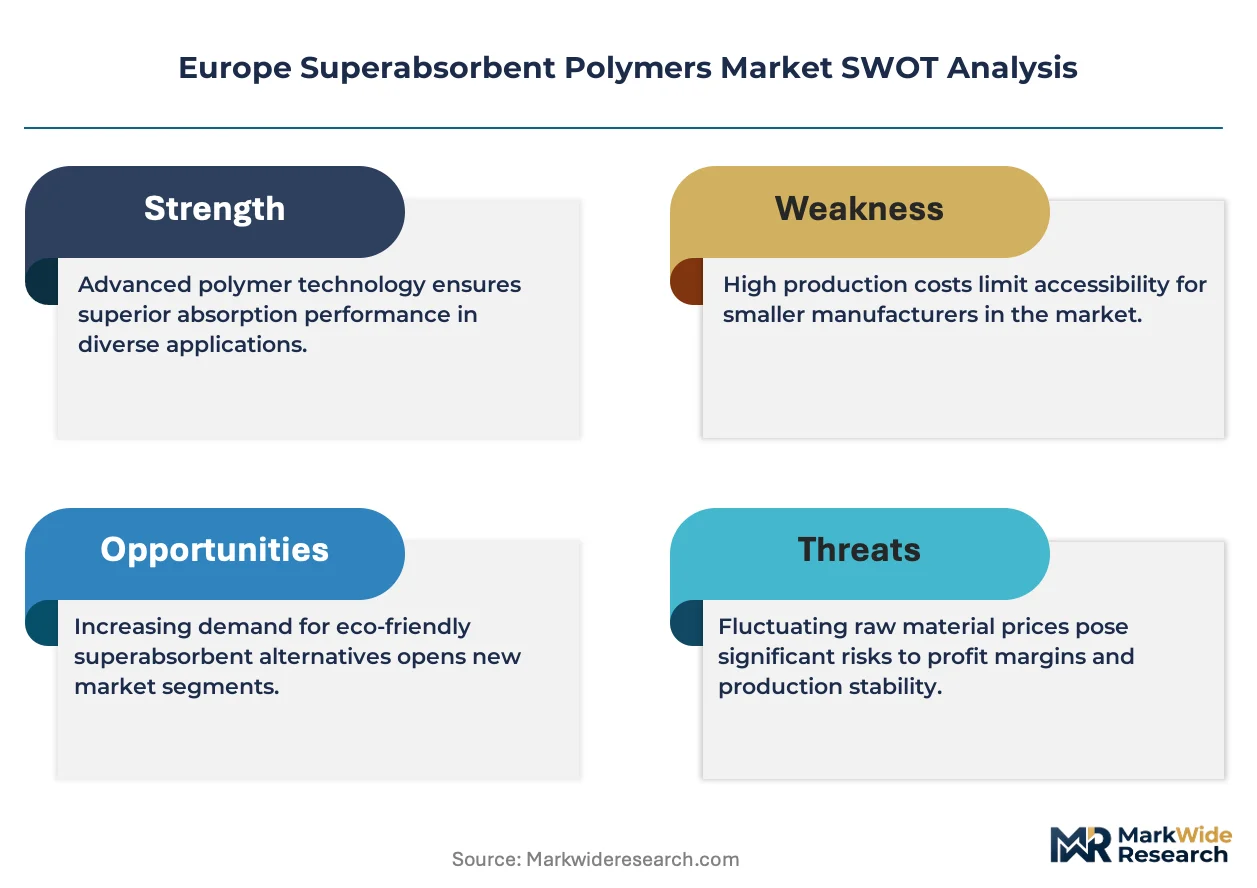
REACH substance evaluations and the EU Green Deal are forcing SAP manufacturers to reengineer monomer feedstocks and biodegradability testing protocols across European production networks.
Growth Catalysts
- Adult incontinence demand:Aging demographics in Germany and Italy are expanding absorbent hygiene consumption among institutional care providers and direct-to-consumer channels.
- REACH registration requirements:Chemical safety mandates are accelerating substitution toward bio-based acrylate precursors and post-consumer recycled content integration.
- Precision irrigation adoption:Spanish and Greek agricultural operations are embedding potassium polyacrylate hydrogels into substrate systems to comply with water-stress regulations.
Market Restraints
- Acrylic acid price volatility:Crude oil derivative costs and refinery capacity constraints in Rotterdam and Antwerp create margin compression for polymer producers.
- Supply concentration risk:Ludwigshafen and Marl production clusters account for disproportionate European SAP output, creating geographic vulnerability to energy disruption or force majeure events.
- Biodegradability technical limits:Cross-linked polyacrylate backbone chemistry resists enzymatic breakdown, complicating end-of-life processing under evolving Ecodesign criteria.
Strategic Opportunities
- Eastern European underpenetration:Polish and Romanian hygiene manufacturing capacity remains below Western European saturation levels, offering greenfield expansion potential for substrate suppliers.
- EU Green Deal procurement incentives:Public tender preferences for circular-economy-compliant absorbents are opening institutional healthcare and municipal segments to certified bio-based alternatives.
- Controlled-release agriculture:Convergence between hydrogel matrices and precision nutrient dosing systems is creating integrated substrate-fertilizer product categories for greenhouse operations.
Industry Challenges
- Polymer chemistry talent scarcity:European universities produce insufficient cross-linked hydrogel specialists to staff R&D functions at scale-up facilities.
- Extended producer responsibility compliance:National EPR scheme fragmentation across France, Germany, and Italy forces redundant packaging and waste-handling registrations for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Superabsorbent Polymers Market |
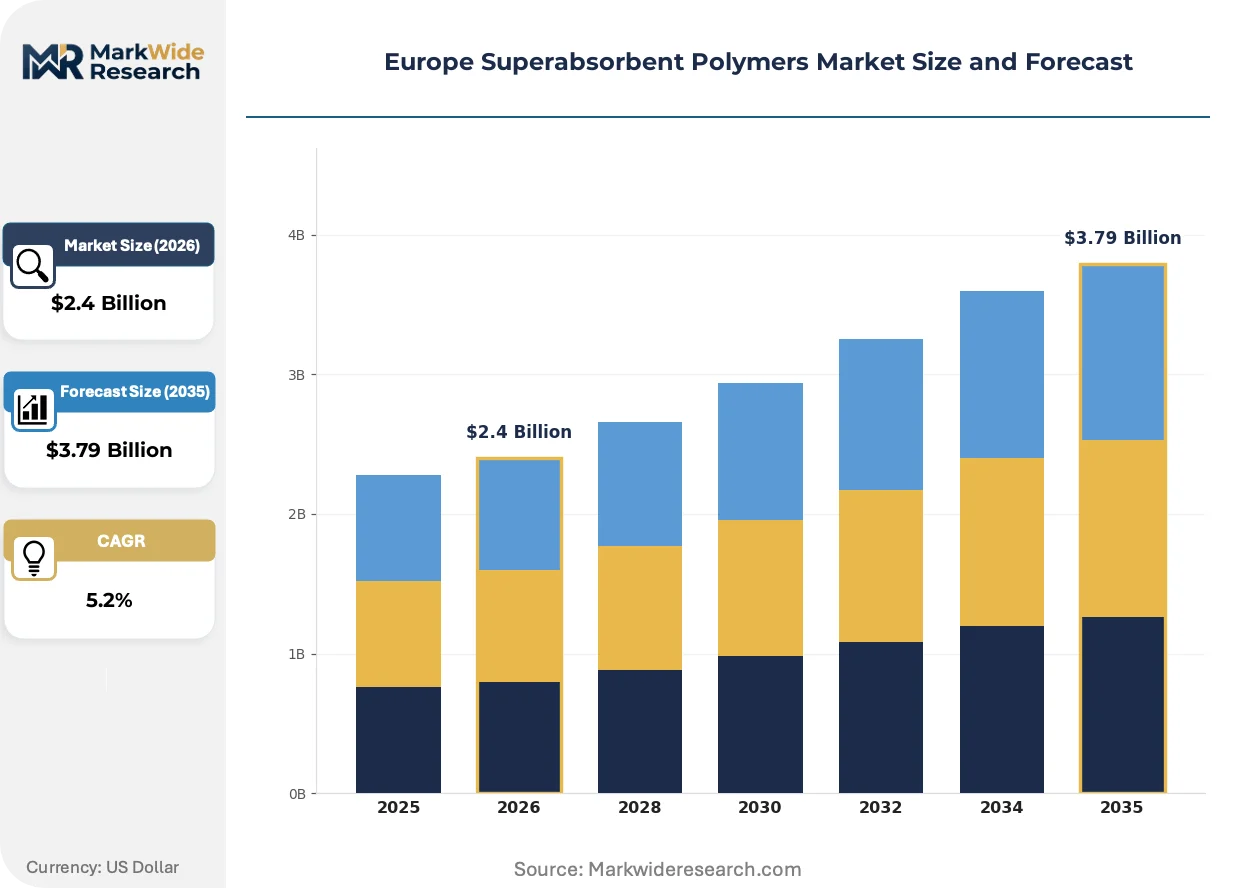
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Polyacrylate, Sodium Polyacrylate, Polyvinyl Alcohol, Others End User: Personal Care, Agriculture, Medical, Industrial Form: Granules, Powders, Films, Sheets Application: Diapers, Adult Incontinence Products, Agricultural Aids, Feminine Hygiene |
| Companies Covered | BASF SE, Evonik Industries AG, LG Chem, Nippon Shokubai Co Ltd, Kao Corporation, Sumitomo Seika Chemicals Co., Ltd., ADM, Wanhua Chemical Group Co., Ltd., Asahi Kasei Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Superabsorbent Polymers Market Shifts & Advancements
Bio-based feedstock substitution, regulatory chemistry reform, and buyer consolidation are restructuring how superabsorbent polymers are formulated, certified, and procured across European value chains.
Biodegradable polyacrylate alternatives derived from starch-grafted copolymers and cellulose-based networks are converging with thin-core diaper architectures to reduce petrochemical dependency while maintaining absorption-under-load performance. Scandinavian hygiene brands and German private-label manufacturers are piloting these materials at commercial scale. This convergence is compressing traditional petroleum-based SAP margins and forcing incumbent producers to dual-source bio-based and conventional grades.
ECHA substance evaluations under REACH Article 59 are restricting residual monomer thresholds and mandating updated safety data sheets for sodium polyacrylate imports. The regulatory consequence is a 12-18 month reformulation cycle for non-EU suppliers seeking European market access. Adult incontinence and feminine hygiene segments face the steepest compliance costs due to higher skin-contact exposure classifications.
Consolidated procurement by pan-European hygiene multinationals is displacing fragmented national distributor networks with direct mill-to-plant supply contracts. This channel compression concentrates volume commitments among three to four polymer suppliers per manufacturing region. The shift is most visible in Germany's Rhine-Ruhr corridor, where diaper producers now negotiate annual framework agreements rather than spot purchases.
Europe Superabsorbent Polymers Market Segmentation
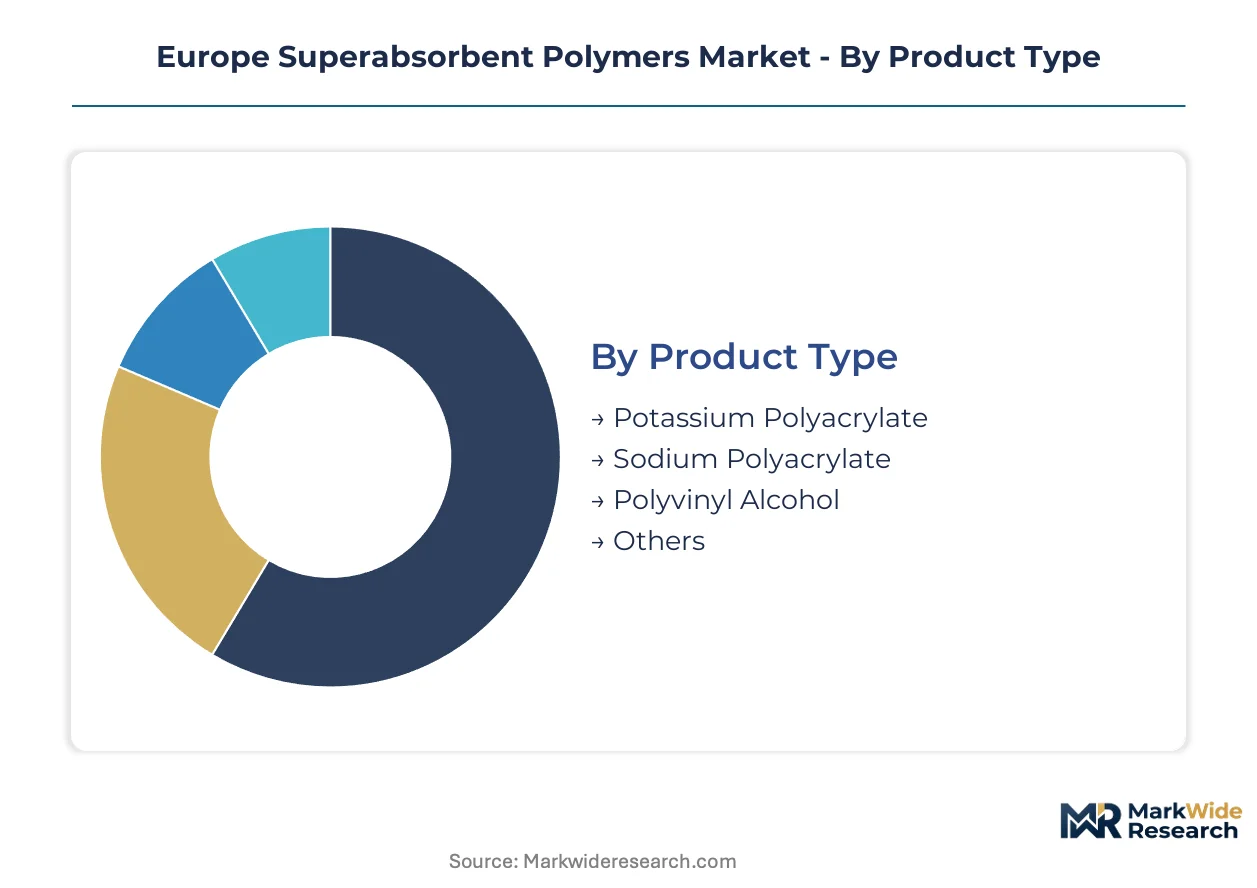
Segmentation in the Europe Superabsorbent Polymers Market reveals how polymer chemistry, end-use specifications, and product form factor determine procurement patterns and margin structures across hygiene and agricultural value chains.
Product Type:
Buyers select polymer chemistry based on absorption-under-load performance, biodegradability compliance costs, and feedstock price volatility exposure.
- Sodium Polyacrylate:Cross-linked sodium salt of polyacrylic acid delivers the highest fluid retention capacity per gram, making it indispensable for thin-core diaper architectures. German and French hygiene manufacturers consume the majority of European sodium polyacrylate volume, though REACH registration costs and acrylic acid price swings compress margins for producers.
- Potassium Polyacrylate:Potassium-based superabsorbent exhibits superior ionic compatibility with soil matrices, positioning it as the preferred hydrogel for precision irrigation systems in Spain and Greece. Water-stress regulations across Mediterranean agricultural zones are accelerating substitution from conventional irrigation toward potassium polyacrylate-infused substrates.
- Polyvinyl Alcohol:Water-soluble synthetic polymer serving niche medical and industrial applications where controlled dissolution rates matter more than maximum absorption.
- Others:Bio-based alternatives including starch-grafted copolymers and cellulose-derived networks emerging from Scandinavian pilot programs.
Sodium polyacrylate leads on scale; potassium polyacrylate leads on momentum.
End User:
Volume concentration and regulatory exposure vary sharply across customer categories, with personal care commanding procurement scale and agriculture offering expansion headroom.
- Personal Care:Diaper and incontinence product manufacturers in Germany's Rhine-Ruhr corridor and northern Italy drive the majority of European SAP procurement, negotiating multi-year framework agreements that lock in supply continuity.
- Agriculture:Greenhouse operators and field crop growers in Spain, Greece, and southern France embed hydrogels into substrate systems to reduce irrigation frequency under tightening water-use regulations.
- Medical:Wound dressings and surgical pads requiring sterile-grade absorbents with low residual monomer content face steepest ECHA compliance costs.
- Industrial:Cable jelly compounds, construction moisture barriers, and packaging desiccants utilizing SAP for humidity control in specialized manufacturing environments.
Personal care dominates revenue concentration; agriculture shows the steepest expansion trajectory.
Form:
Processing equipment compatibility and end-product manufacturing line speed determine form factor selection across customer facilities.
- Granules:Free-flowing spherical particles optimized for pneumatic conveying systems in high-speed diaper production lines; preferred by German and Italian hygiene manufacturers for consistent dosing accuracy.
- Powders:Finely milled polymer with rapid swelling kinetics used in agricultural substrate blending and medical dressing lamination where surface area drives performance.
- Films:Cast or extruded polymer sheets for moisture barrier applications in industrial cable and construction segments.
- Sheets:Pre-formed absorbent layers integrated directly into feminine hygiene and adult incontinence product assembly.
Granules capture the largest production volumes; powders are gaining share fastest in agricultural blending operations.
Application:
Performance specifications and skin-contact regulatory classifications create distinct procurement tiers across absorbent product categories.
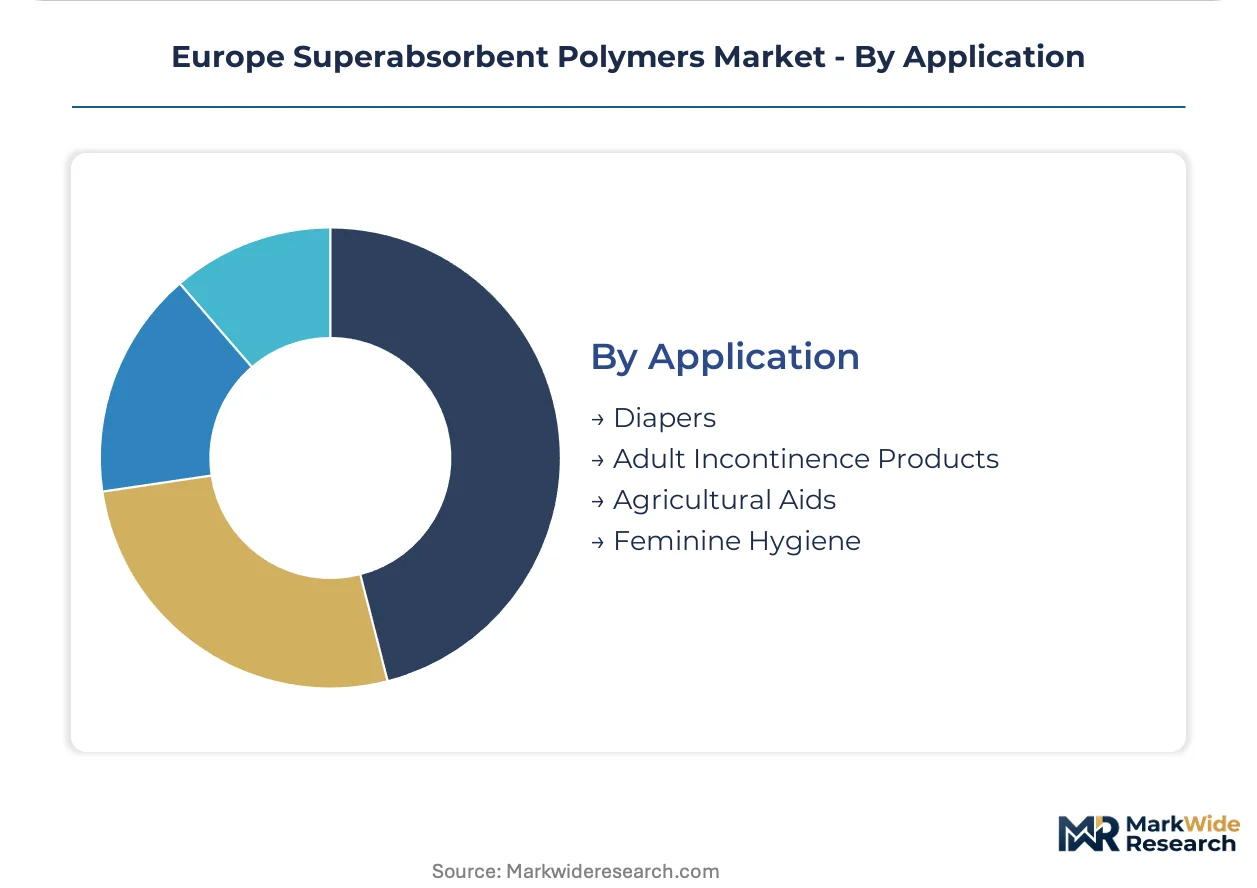
- Diapers:Infant hygiene products requiring maximum absorption-under-load with minimal core thickness; thin-core architectures in German and French manufacturing facilities demand specialized high-performance grades.
- Adult Incontinence Products:Institutional and retail channels serving aging populations in Germany and Italy; higher skin-contact exposure triggers stricter ECHA residual monomer thresholds than infant applications.
- Agricultural Aids:Hydrogel substrates for greenhouse and field crop operations, expanding most quickly in Spanish and Greek markets under water-stress compliance mandates.
- Feminine Hygiene:Tampons, pads, and liners with intermediate absorption requirements and elevated dermatological safety standards.
Diapers anchor volume consumption; agricultural aids offer the strongest growth momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest share of European SAP consumption while Spain drives the fastest agricultural uptake, creating divergent demand profiles across the continent.
Germany
Adult incontinence products and thin-core diaper architectures dominate SAP procurement from Rhine-Ruhr hygiene manufacturers. REACH registration requirements and ECHA substance evaluations impose strict residual monomer thresholds on sodium polyacrylate imports. The Ludwigshafen chemical cluster anchors production continuity for Central European supply chains.
France
Personal care manufacturers in northern France negotiate multi-year framework agreements for high-performance polymer grades. The EU Green Deal's sustainable chemistry mandates accelerate bio-based acrylate precursor testing. Paris Basin agricultural operations pilot potassium polyacrylate substrates under water-stress regulations.
Italy
Aging demographics expand institutional and retail incontinence channels throughout Lombardy and Emilia-Romagna. National extended producer responsibility schemes impose redundant packaging registrations for multi-market suppliers. Northern Italian hygiene manufacturing clusters concentrate granule consumption for high-speed production lines.
Spain
Mediterranean greenhouse operators embed hydrogels into substrate systems to comply with irrigation restrictions. Water-stress regulations across Andalusia and Valencia accelerate substitution from conventional irrigation toward potassium polyacrylate-infused agriculture. Barcelona-area precision farming suppliers integrate controlled-release matrices into commercial growing operations.
Poland
Emerging hygiene manufacturing capacity remains below Western European saturation levels, offering greenfield expansion potential. EU Green Deal procurement incentives open institutional healthcare segments to certified bio-based alternatives. Warsaw and Krakow industrial zones attract substrate suppliers seeking underpenetrated Eastern European markets.
Europe Superabsorbent Polymers Market Competitive Landscape
German producers anchor one tier; Japanese and South Korean specialists hold differentiated positions through material science capabilities. The vendor base clusters around three to four polymer suppliers per manufacturing region, with direct mill-to-plant contracts displacing fragmented distributor networks. Strategic archetypes include integrated petrochemical conglomerates, specialized hygiene-grade formulators, and agricultural hydrogel innovators. Competitive moves concentrate on backward integration into acrylic acid supply and bio-based feedstock substitution cycles.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated production archetype, leveraging Ludwigshafen and Marl manufacturing clusters to sustain supply continuity. Japanese specialists including Nippon Shokubai Co Ltd and Asahi Kasei Corporation occupy positions emphasizing material science differentiation. South Korean and Chinese producers such as LG Chem and Wanhua Chemical Group Co., Ltd. represent scale-driven supply alternatives seeking European market access through REACH compliance investments.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| LG Chem |
| Nippon Shokubai Co Ltd |
| Kao Corporation |
| Sumitomo Seika Chemicals Co., Ltd. |
| ADM |
| Wanhua Chemical Group Co., Ltd. |
| Asahi Kasei Corporation |
| Others |
Supply & Pricing Matrix
Bio-based acrylate precursor substitution is compressing conventional petroleum-grade margins while concentrating procurement leverage among Rhine-Ruhr hygiene manufacturers negotiating multi-year framework agreements. This dual shift simultaneously elevates cost structures for REACH-compliant formulations and consolidates volume discounts for buyers with direct mill-to-plant contracts.
Pricing Analysis
Capacity additions in Eastern European manufacturing zones are reshaping price floors for standard-grade sodium polyacrylate. Three-tier pricing structure across premium REACH-certified, standard industrial, and economy spot grades differentiates buyers by certification tier and volume commitment scale. Pricing pressure stems from acrylic acid feedstock volatility at Rotterdam-Antwerp refinery complexes. Institutional healthcare procurement teams exhibit highest price sensitivity due to public tender constraints, while premium diaper manufacturers prioritize supply continuity over unit cost.
Supply Chain Analysis
REACH registration and ECHA substance evaluation compliance now gate market access for non-EU suppliers seeking European distribution. Production gravity centers on Germany, Belgium, and the Netherlands, with Ludwigshafen and Marl clusters anchoring regional supply. The network draws from crude oil derivatives, bio-based starch feedstocks, and specialized cross-linking agents. Single-source vulnerability concentrates at acrylic acid production nodes. Distribution runs through direct mill-to-plant contracts displacing fragmented national distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Superabsorbent Polymers Market functions as a regulatory compounder where EU Green Deal sustainable chemistry mandates and REACH Article 59 substance evaluations continuously reshape formulation economics and procurement specifications.
For Market Incumbents: Deepen backward integration into bio-based acrylate precursors to deflect margin compression from petroleum feedstock volatility. Secure multi-year supply agreements with Rhine-Ru and northern Italian hygiene manufacturers before channel consolidation completes. Prioritize REACH registration maintenance for sodium polyacrylate grades facing ECHA residual monomer threshold tightening. For New Entrants and Emerging Players: Begin with agricultural hydrogel applications in Spanish and Greek greenhouse operations where water-stress regulations accelerate potassium polyacrylate adoption ahead of personal care saturation. Target certified bio-based alternatives for EU Green Deal procurement incentives opening institutional healthcare segments. Establish technical partnerships with precision irrigation equipment suppliers to embed substrate-fertilizer integration capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale bio-based formulation specialists lacking REACH registration portfolios but holding proprietary starch-grafted copolymer IP. Long-term viability favors producers with dual-source capabilities across petroleum and bio-based feedstocks. Monitor ECHA substance evaluation timelines for sodium polyacrylate as inflection indicator for incumbent reformulation cost spikes and substitute technology windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Reduces acrylic acid price exposure while satisfying EU Green Deal procurement criteria. |
| REACH Registration Acceleration | Shortens 12-18 month market access cycles for non-EU suppliers facing ECHA evaluations. |
| Precision Irrigation Partnerships | Locks in potassium polyacrylate volume commitments with Spanish greenhouse operators. |
| Thin-core Architecture R&D Investment | Aligns high-performance grades with German diaper manufacturer technical roadmaps. |
| Eastern European Capacity Expansion | Captures underpenetrated Polish and Romanian hygiene manufacturing growth. |
Research Methodology
Multiple input streams — technical discussions with polymer plant managers and R&D directors, procurement lead interviews at hygiene manufacturers, and regulatory affairs consultations — were reconciled against secondary validation from ECHA substance evaluation databases, Cefic chemical industry reports, and customs trade flow records. Bottom-up volume modeling across product grades and end-use segments was triangulated with top-down market sizing from production capacity assessments at Ludwigshafen and Marl chemical clusters.
Data-stream reconciliation anchored forecast construction across the projection horizon. Segmentation dimensions modeled include polymer chemistry type, end-use application, and regional regulatory cluster intensity. CAGRs were derived from demand elasticity analysis against adult incontinence demographic projections and agricultural water-stress compliance timelines. Industry-specific inputs incorporated acrylic acid price correlation coefficients and ECHA evaluation pipeline status.
Several conditions sit outside the modeled scope, including force majeure disruptions at Ludwigshafen production complexes and unilateral national EPR scheme fragmentation beyond current France-Germany-Italy divergence. Forecasts reflect documented assumptions regarding REACH implementation timelines and EU Green Deal procurement incentive continuity. A model refresh is warranted upon material change in ECHA substance evaluation outcomes for sodium polyacrylate residual monomer thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
UV Cure Resins Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Expanded Polystyrene (EPS) Market