
 Plastisols Market | 2026-2036
Plastisols Market Size, Share, and Industry Trends Forecast 2026-2036
Plastisols Market Intelligence
Consolidation among large-scale automotive and textile manufacturers is realigning procurement patterns for specialty plastisols, favoring suppliers with global reach. Avient Corporation leverages its extensive product portfolio to serve these multinational accounts across different geographies. In contrast, International Coatings specializes in the screen printing segment, targeting a more fragmented customer base of smaller apparel decorators. Huber Group competes on the basis of its colorant technologies integrated within its plastisol formulations.
Plastisols are dispersions of fine polymer particles, typically polyvinyl chloride (PVC), in a liquid plasticizer. When heated to a specific temperature, the mixture fuses into a solid, flexible, and durable plastic, making it ideal for coating and molding applications. Soft plastisols, used extensively in textile screen printing, represent a mature but high-volume category. Meanwhile, specialty plastisols for automotive dip coating and industrial applications command higher margins due to performance requirements.
The European Union's REACH framework and the US EPA's regulations on volatile organic compounds (VOCs) scrutinize the use of certain plasticizers like phthalates. This regulatory pressure directly influences formulation chemistry, pushing manufacturers toward bio-based or non-phthalate alternatives. Consequently, material selection and supply chain compliance will become critical decision points for both formulators and end-users.
Market Dynamics
Regulatory mandates from bodies like the European Union's ECHA and the US EPA are the central force, compelling a fundamental shift in formulation chemistry away from restricted phthalate plasticizers towards safer alternatives.
Growth Catalysts
- Automotive Sector Demand:The automotive industry's need for durable, corrosion-resistant coatings for underbody protection, wire harnesses, and interior components drives high-volume consumption of specialty plastisols.
- Textile Screen Printing:Continued demand for decorated apparel and textiles sustains a large market for soft plastisol inks, valued for their opacity, durability, and vibrant color capabilities on various fabrics.
- Phthalate-Free Formulations:The development of non-phthalate and bio-based plasticizers opens new markets and allows plastisols to meet stringent regulatory requirements for toys, medical devices, and food-contact articles.
Market Restraints
- Raw Material Volatility:Prices for key inputs like PVC resin and plasticizers are tied to petrochemical feedstocks, introducing significant price and margin volatility.
- Regulatory Compliance Costs:Reformulating products to comply with evolving standards under REACH and other chemical regulations requires substantial investment in research, testing, and certification, burdening manufacturers.
- Substitution from Alternatives:In certain applications, plastisols face competition from materials like thermoplastic elastomers and water-based or powder coating systems that offer different performance or environmental profiles.
Strategic Opportunities
- Medical Device Coatings:High-margin opportunities exist in coating medical instruments and tubing where plastisols provide biocompatibility and flexibility, subject to stringent FDA or EMA approval.
- Industrial Functional Coatings:Formulating plastisols with specialized additives to impart anti-static, antimicrobial, or enhanced UV-resistant properties creates value in demanding industrial applications like tool handles and electrical insulation.
- Expansion in Southeast Asia:Growing automotive production and construction activity in countries like Vietnam and Thailand present an untapped market for plastisol-based sealants, gaskets, and protective coatings.
Industry Challenges
- End-User Qualification Cycles:Lengthy customer testing and approval cycles for new phthalate-free formulations in the automotive sector can delay market adoption and revenue.
- Formulation Expertise Scarcity:A shortage of polymer chemists skilled in working with novel bio-based plasticizers and ensuring they meet the performance standards of traditional formulations hinders rapid innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastisols Market |
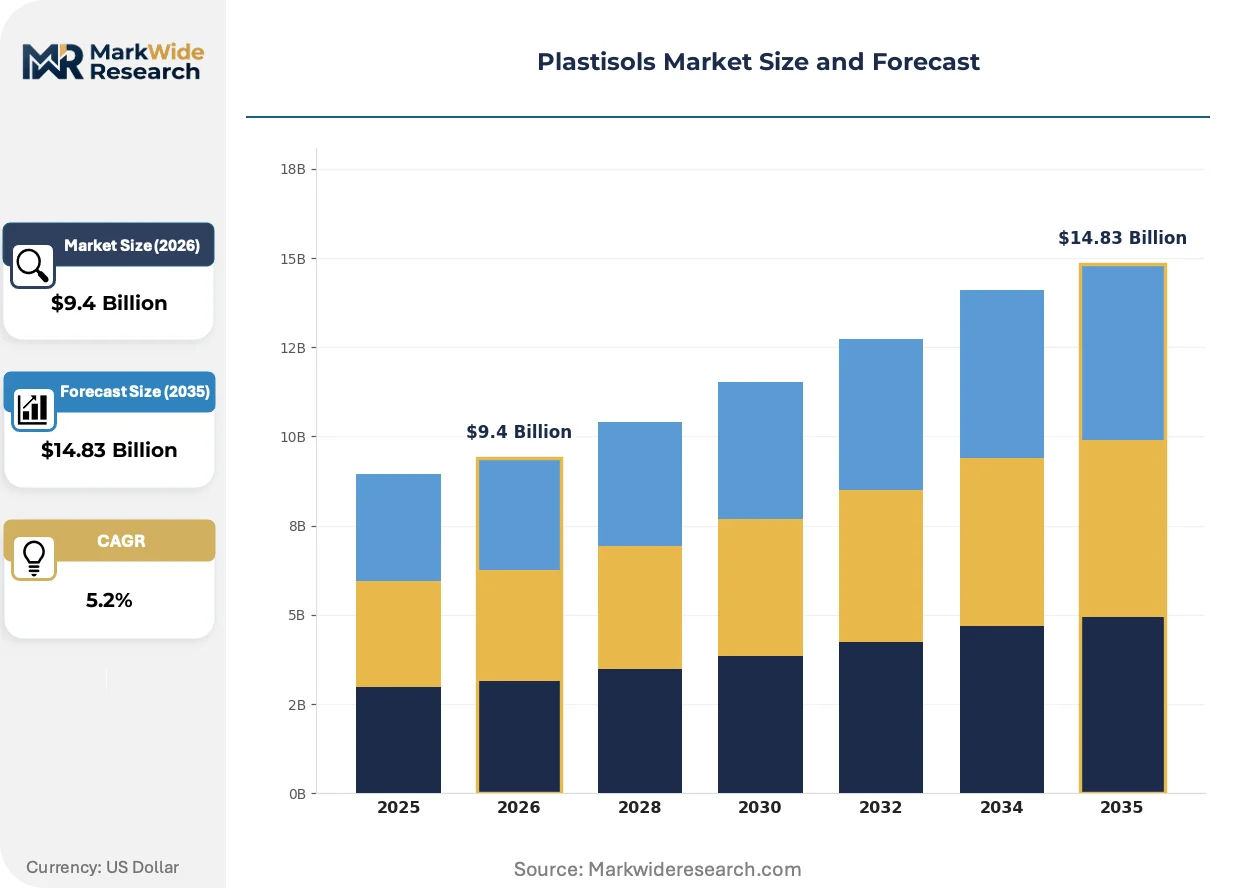
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $14.83 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Plastisols, Hard Plastisols, Specialty Plastisols, Coated Plastisols Application: Textiles, Automotive, Industrial Coatings, Furniture Delivery Mode: Screen Printing, Dip Coating, Injection Molding, Spray Coating End User: Manufacturers, Retailers, Distributors, Contractors |
| Companies Covered | Avient Corporation, Fujifilm Holdings Corporation, International Coatings, Carlisle Plastics Company, Huber Group, BASF, DuPont, Huntsman, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastisols Market Strategic Shifts & Innovations
Formulation science is advancing on two fronts, driven by regulatory pressures and end-user performance demands. This evolution is centered on developing safer, more sustainable materials without compromising the durability and processability that define plastisols.
Advanced color management systems integrate spectrophotometers with dispensing equipment. These systems are being adopted by large-scale textile screen printers and industrial coaters seeking absolute consistency. This technology is automating the complex, manual task of color matching, which reduces material waste and guarantees brand color fidelity across production runs.
Regulatory scrutiny under frameworks like the European Union's REACH program directly influences material selection. This forces manufacturers to phase out certain ortho-phthalates in favor of non-phthalate plasticizers such as DOTP or bio-based alternatives. The toy and childcare article segments are most impacted, requiring suppliers to provide extensive compliance documentation to maintain market access.
Consolidation among major automotive and textile manufacturers is changing buying behavior toward demanding greater supply chain transparency. This shift prioritizes documented proof of material origin and compliance over purely price-based decisions, disrupting traditional supplier relationships. This procurement evolution is most pronounced within Germany's automotive sector and for consumer-facing apparel brands in the United States.
Plastisols Market Segmentation
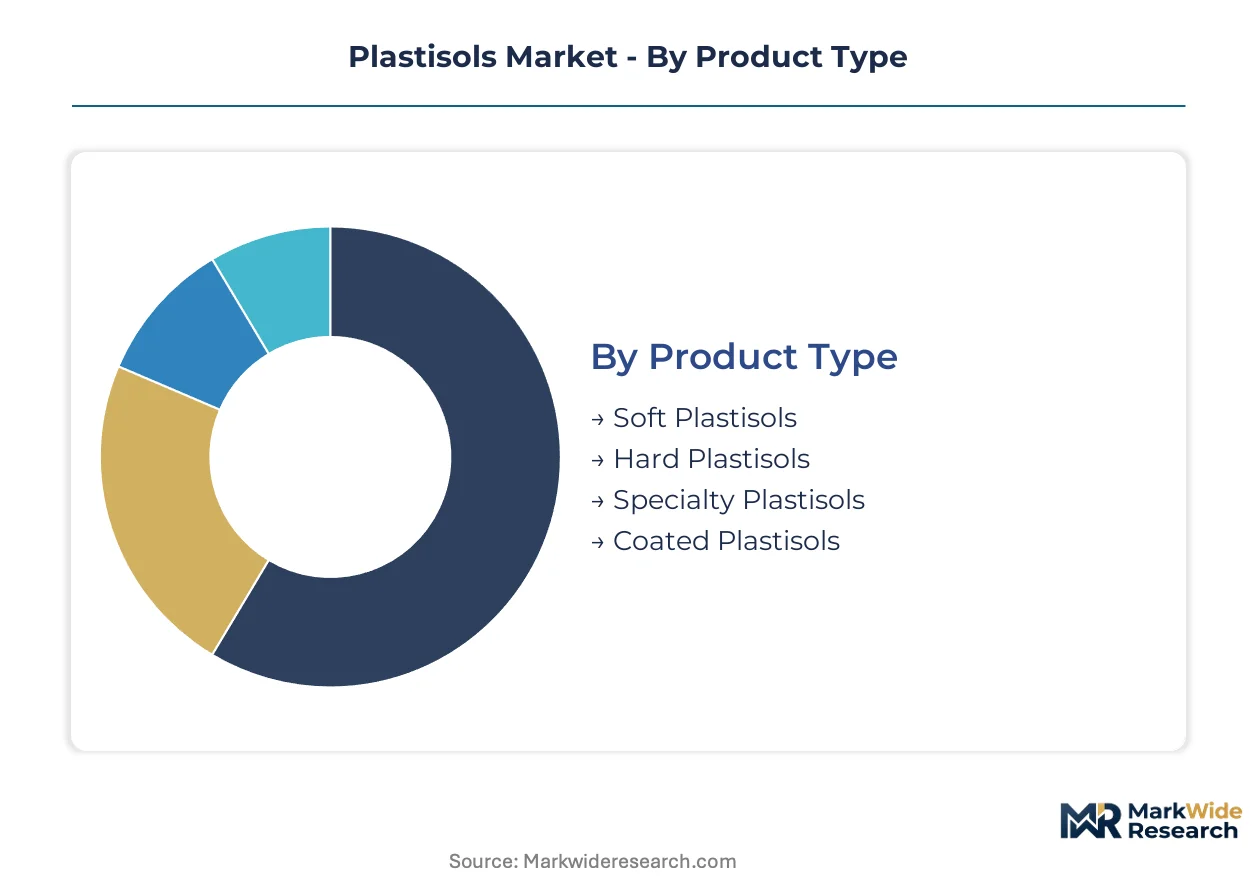
The plastisols market exhibits varied demand patterns and performance requirements across its diverse applications. Understanding these distinct segments is crucial for manufacturers to align product development with specific end-user needs and regulatory compliance. This segmentation analysis highlights the different forms, uses, and delivery methods of plastisol materials.
Product Type:
The product type segmentation differentiates between high-volume, cost-effective formulations and specialized, higher-value materials tailored for specific performance attributes.
- Soft Plastisols:These are dispersions of fine polymer particles in liquid plasticizer, designed for flexibility and ease of processing. High-volume demand originates from textile screen printing for apparel, driven by the need for durable and vibrant colors.
- Specialty Plastisols:Engineered for enhanced performance characteristics such as corrosion resistance, UV stability, or specific dielectric properties. These formulations command higher margins in automotive dip coating and industrial applications within Germany and the United States.
- Hard Plastisols:These formulations offer increased rigidity and impact resistance, finding use in applications like tool handles and certain protective coatings.
- Coated Plastisols:These involve a substrate pre-coated with a plastisol layer, often for enhanced weatherability or aesthetic appeal in construction materials.
Mature deployment sits with Soft Plastisols. Newer deployment is concentrated in Specialty Plastisols.
Application:
Plastisols find utility across a diverse range of end-use applications, each demanding specific material properties and processing characteristics.
- Textiles:Utilized extensively for screen printing on apparel and other fabric items due to their opacity, durability, and vibrant color retention. Continued demand for decorated clothing maintains a large market segment, particularly in consumer-facing brands.
- Automotive:Applied for underbody protection, wire harness coatings, and interior components, providing corrosion resistance, vibration damping, and electrical insulation. The German and US automotive industries are major consumers, seeking long-lasting functional coatings.
- Industrial Coatings:These encompass a broad array of protective and functional layers for various equipment and components, requiring specific chemical resistance or insulation properties.
- Furniture:Plastisols are used in furniture for protective coatings, flexible components, or decorative elements, offering durability and design versatility.
The automotive sector represents the fastest-growing trajectory for high-performance plastisols, driven by stringent durability requirements.
Delivery Mode:
The method of application significantly influences the rheological properties and formulation requirements of plastisols, adapting to various production processes.
- Screen Printing:Involves forcing plastisol ink through a mesh stencil onto a substrate, primarily used for textile decoration due to its excellent opacity and vibrant color reproduction. This method supports high-volume production of decorated apparel and promotional items.
- Dip Coating:Submerging an object into a plastisol bath to create a uniform, protective layer, commonly employed for automotive parts, tool handles, and electrical insulation. This technique ensures complete coverage and corrosion resistance for complex shapes.
- Injection Molding:Plastisols can be molded into intricate shapes by injecting the heated material into a mold cavity, suitable for producing flexible components and seals.
- Spray Coating:Applying plastisol as a fine mist onto surfaces provides protective or decorative finishes, often utilized for larger items or areas requiring extensive coverage.
Efficiency and consistency are paramount in Screen Printing operations, while Dip Coating prioritizes uniform coverage on complex geometries.
End User:
End-user classification illuminates the different points of consumption within the supply chain, from direct production to indirect sales channels.
- Manufacturers:Industrial entities that directly integrate plastisols into their production processes for creating finished goods like automotive components, textiles, or industrial tools. These users prioritize technical specifications and supply chain reliability for continuous operations.
- Distributors:Intermediaries who procure plastisols from producers and supply them to a diverse client base, including smaller manufacturers, print shops, and specialized contractors. They manage logistics and provide localized stock, facilitating market access for various end-users.
- Retailers:Primarily involved in selling finished products containing plastisols, such as decorated apparel or consumer goods, influencing demand through product specifications and consumer trends.
- Contractors:Businesses that apply plastisols as part of their service offerings, such as specialized industrial coating services or large-scale textile decorators, requiring consistent material performance.
Procurement patterns for Manufacturers increasingly favor direct supplier relationships, whereas Retailers rely on established distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for plastisols is particularly notable in the automotive sector within Germany and the United States. The textile industry's consistent need for screen printing on apparel also drives significant consumption globally. This global demand shapes regional production and regulatory compliance requirements.
United States
The US automotive industry drives substantial demand for specialty plastisols in underbody coatings and wire harnesses. US EPA regulations on volatile organic compounds (VOCs) influence formulation chemistry, pushing manufacturers toward compliant alternatives. Major automotive manufacturing hubs in Michigan and the Southeast utilize advanced plastisol applications for vehicle production.
Germany
Germany's robust automotive sector represents a significant consumer of high-performance plastisols for corrosion resistance and interior components. The European Union's REACH framework directly impacts material selection, mandating the phase-out of certain phthalate plasticizers. The industrial clusters around Stuttgart and Munich are centers for automotive component suppliers innovating with new plastisol formulations.
China
China's expanding automotive manufacturing and construction sectors create a large market for both soft and specialty plastisols. The country's environmental protection laws are increasingly scrutinizing chemical use, influencing local plastisol production. Industrial zones in the Yangtze River Delta are seeing increased adoption of plastisols for diverse industrial coatings and textile applications.
Vietnam
Vietnam's growing textile and apparel manufacturing industry sustains consistent demand for soft plastisols used in screen printing. The country's export-oriented economy requires adherence to international chemical regulations like REACH for product market access. Textile production hubs near Ho Chi Minh City are expanding their capacity for decorated apparel using plastisol inks.
France
France's automotive sector and diverse industrial applications contribute to the demand for specialized plastisols. European Union regulations, including ECHA guidelines, shape the development of non-phthalate plasticizers across the country. Manufacturing centers in regions like Auvergne-Rhône-Alpes are adopting advanced plastisol technologies for functional coatings and components.
Plastisols Market Key Industry Players
European Union producers anchor one tier, focusing on advanced phthalate-free formulations to meet stringent regulatory demands, while United States specialists hold significant market share in both the automotive and textile screen printing segments. The market structure exhibits a blend of large, diversified chemical companies and specialized niche players. Strategic archetypes include global material suppliers, regional screen printing specialists, and colorant technology integrators. Competitive moves center on portfolio diversification into sustainable chemistries and geographic expansion into emerging automotive markets.
Global suppliers like Avient Corporation exemplify extensive product portfolios designed to serve multinational accounts across varied geographies. International Coatings occupies a distinct position as a specialist in the screen printing segment, targeting a fragmented customer base of smaller apparel decorators. Huber Group anchors its competitive positioning on integrating advanced colorant technologies directly into its plastisol formulations, offering differentiated performance. These companies represent distinct approaches to market penetration and value creation within the plastisols industry.
| Leading Market Players |
|---|
| Avient Corporation |
| Fujifilm Holdings Corporation |
| International Coatings |
| Carlisle Plastics Company |
| Huber Group |
| BASF |
| DuPont |
| Huntsman |
| 3M |
| Others |
Cost & Logistics Intelligence
Skilled polymer chemists in innovation hubs like Germany command premium wages, influencing the development cost of specialty plastisols. These labor-cost differentials contribute to the wider pricing tiers observed between high-performance and commodity formulations.
Pricing Analysis
The volume-versus-margin split defines plastisol pricing. Contract-based long-term offtake dominates specialty plastisols for automotive OEMs, while per-unit transactional models serve textile screen printers. Performance requirements like corrosion resistance, UV stability, and non-phthalate regulatory compliance drive premium pricing for specialized formulations. Raw material volatility, stemming from petrochemical feedstocks, introduces significant price fluctuations, impacting all segments, with smaller apparel decorators exhibiting higher price sensitivity than large automotive manufacturers.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate plastisol movement to diverse end-users. China serves as a key source for PVC resin and plasticizers, with Germany and the United States representing major consumption hubs. The supply chain heavily draws from petrochemical feedstocks for PVC resin, various plasticizers, and colorants. Regulatory restrictions, particularly REACH on phthalates, create a structural risk, necessitating costly reformulation and pushing large manufacturers towards direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastisols market is evolving into a vertical-integration race, as companies pursue greater control over specialized phthalate-free plasticizer development. This strategic alignment aims to secure compliant raw material supply and differentiate product portfolios.
For Market Incumbents: Cement existing market leadership by accelerating investment in bio-based plasticizer research and development. Consolidate regional distributors to enhance supply chain control and service large multinational accounts. Regulatory substitution from alternative materials like thermoplastic elastomers poses a significant threat. Leverage extensive product portfolios to meet diverse global regulatory requirements, especially under REACH and US EPA. For New Entrants and Emerging Players: Price-point gaps exist between premium specialty plastisols and economy soft formulations, creating entry opportunities. Target high-margin niche applications such as medical device coatings requiring biocompatibility and stringent FDA approval. Focus on Southeast Asia, particularly Vietnam's textile sector, by offering rapid customization of phthalate-free screen printing inks. Emphasize compliance documentation and technical support as a key differentiator. For Investors and Strategic Acquirers: Re-rating potential sits with specialized formulators given the sustained regulatory push towards non-phthalate plasticizers. Plastisols maintain long-term viability across automotive and textile sectors due to their durability and performance. Seek mid-cap companies possessing proprietary bio-based plasticizer technologies or integrated advanced colorant capabilities. Accelerated adoption rates of non-phthalate formulations in automotive OEM supply chains will serve as a critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and aligns with EU Green Deal objectives for chemical production. |
| Long-term Supply Agreement | Secures stable supply of PVC resin and non-phthalate plasticizers amidst petrochemical volatility. |
| Joint Venture | Accelerates development of bio-based plasticizers and expands market access in Southeast Asia. |
| Capacity Expansion | Meets rising demand for specialty plastisols in German automotive and US industrial applications. |
| Certification Program | Achieves necessary compliance certifications for medical device coatings, opening high-margin opportunities. |
Research Approach
Document review covered industry reports, company filings, and regulatory guidelines, complemented by interviews with market participants. Primary insights came from R&D directors, automotive OEM procurement leads, textile screen printing specialists, and chemical distributors. Secondary data sources included EU REACH documentation, US EPA regulations, and polymer industry association reports. Bottom-up analysis of segment demand was validated against top-down market sizing.
Historical market data was cross-referenced with expert panel input to construct the forecast framework. Volume and value outputs were projected across the analysis window, considering product type, application, end user, and regional regulatory clusters. Compound annual growth rates, derived from linear and non-linear models, incorporated phthalate-free plasticizer adoption and automotive production volumes.
Inputs from regulatory bodies, industry associations, and primary interviews were available through the study window; gaps in supply chain cost data introduce uncertainty bands. Forecasts reflect assumptions regarding raw material price stability and regulatory framework evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Polystyrene Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Global Impregnating Resins Market