
 EVA Copolymer Market | 2026-2036
EVA Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
EVA Copolymer Market Analytics
Polyvinyl chloride is shifting out of flexible medical tubing and consumer goods applications as ethylene-vinyl acetate copolymers offer superior clarity and plasticizer-free performance. ExxonMobil Corporation leverages integrated polyethylene feedstock access to control resin cost volatility. Dow Inc. anchors its position through solution-phase EVA manufacturing technology that yields precise vinyl acetate incorporation. SABIC competes via petrochemical complexes in Saudi Arabia that supply Gulf and South Asian converters.
Ethylene-vinyl acetate copolymer consists of random copolymer chains with vinyl acetate content typically ranging from 2% to 40% by weight, produced through high-pressure free-radical polymerization in tubular or autoclave reactors; the material functions as a thermoplastic elastomer combining rubber-like softness with thermoplastic processability for bonding, sealing, and cushioning applications. Flexible films commands the largest volume share due to solar encapsulant and food packaging pull, while adhesives represents the fastest-expanding margin pool as hot-melt formulations displace solvent-based bonding in automotive and electronics assembly. Medical applications within the healthcare end use industry attract premium pricing for biocompatible grades that meet sterilization compatibility standards.
EPA regulates volatile organic compound emissions from EVA adhesive processing facilities under Clean Air Act provisions, while REACH restricts residual monomer content in copolymers sold across European Union member states. FDA maintains device master file requirements for medical-grade EVA used in pharmaceutical packaging and intravenous delivery systems. Stakeholders must monitor feedstock ethylene cost spreads and regulatory divergence between jurisdictions when siting compounding and conversion capacity.
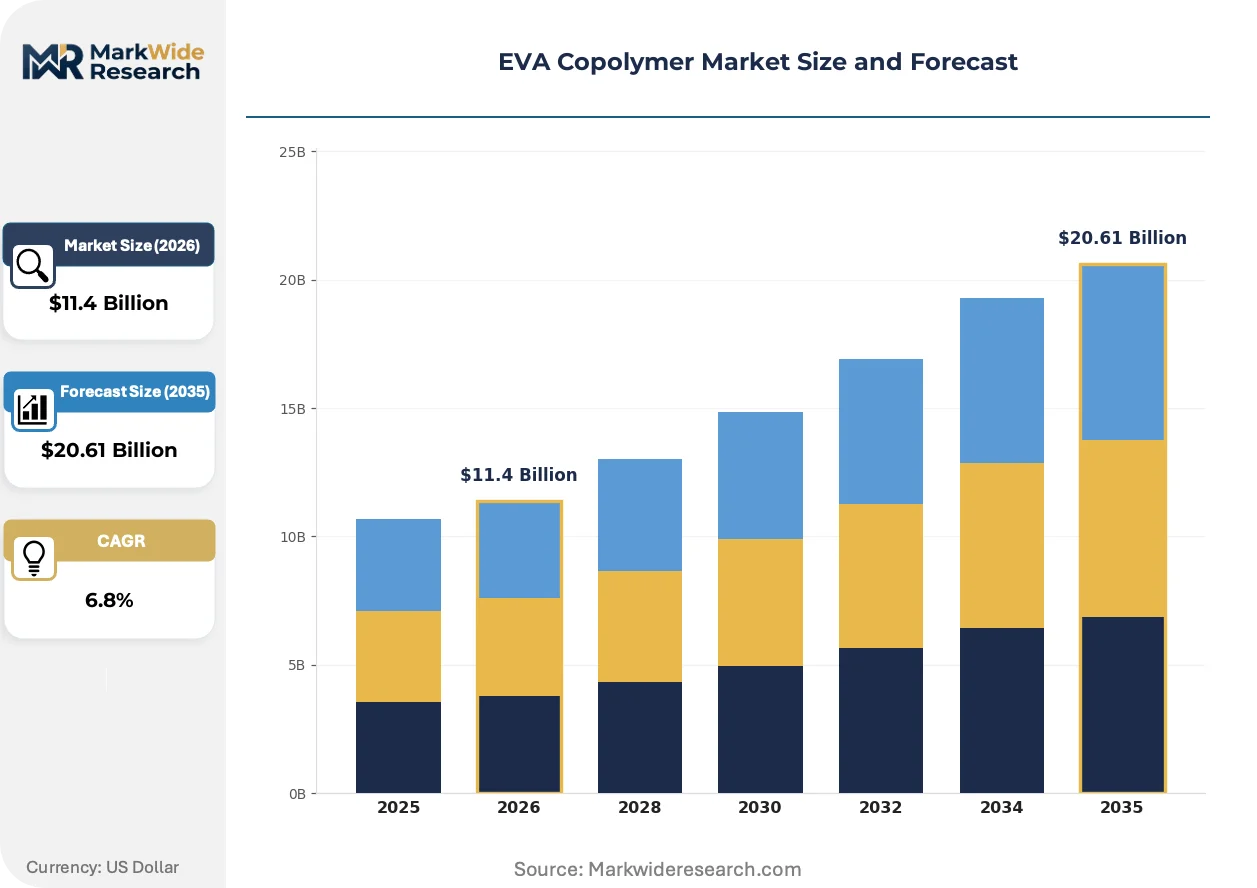
Market Dynamics
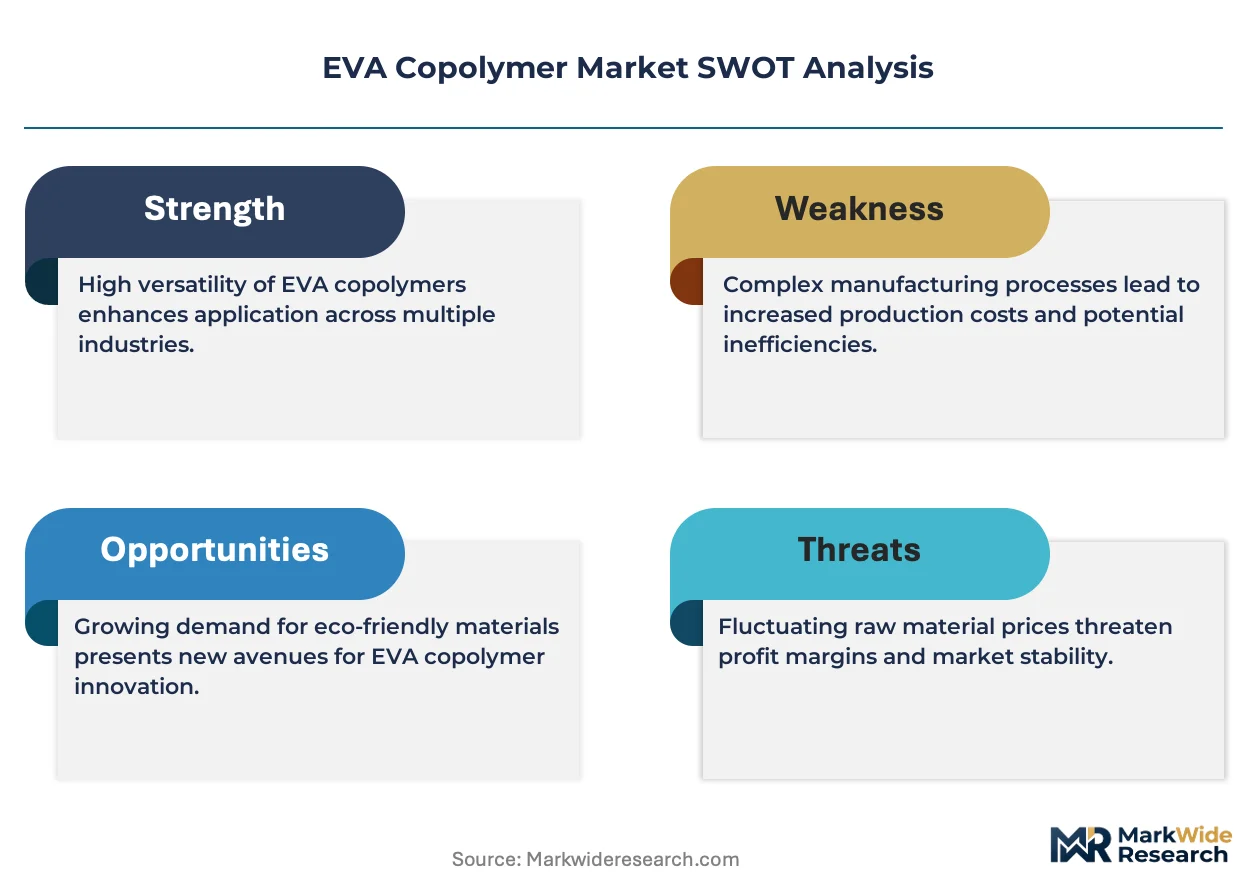
Solar encapsulant films are compressing procurement cycles as photovoltaic manufacturers lock in multi-year resin supply agreements ahead of capacity expansions. Feedstock ethylene volatility and REACH compliance costs are simultaneously squeezing converter margins while filtering marginal producers from medical-grade certification pools.
Growth Catalysts
- EU Green Deal chemical compliance:REACH restrictions on residual monomer content are accelerating reformulation investments among European compounders, creating first-mover certification advantages for compliant suppliers.
- Photovoltaic assembly concentration:China's dominance in solar panel manufacturing is pulling EVA resin volumes toward Asia-Pacific compounding hubs serving encapsulant film extruders.
- Hot-melt adhesive displacement:Solvent-based bonding systems in automotive and electronics assembly are yielding to EVA-based formulations as EPA volatile organic compound enforcement tightens.
Market Restraints
- Ethylene feedstock volatility:Naphtha-to-ethylene cost spreads swing converter margins unpredictably, particularly for non-integrated compounders lacking captive olefin supply.
- Supply concentration risk:Tubular reactor capacity for high-pressure EVA polymerization clusters among Gulf Coast and Middle Eastern petrochemical complexes, exposing buyers to regional disruption.
- Polypropylene substitution threat:Random copolymer polypropylene advances in flexible packaging applications where clarity requirements moderate and cost sensitivity dominates.
Strategic Opportunities
- India footwear export manufacturing:Duty-free access to European and North American markets under preferential trade agreements is attracting EVA sole molding operations from incumbent Chinese suppliers.
- Biocompatible medical grades:FDA device master file pathways for pharmaceutical packaging and intravenous delivery systems offer premium pricing pools with multi-year contract stability.
- Automotive lightweighting convergence:EVA foam cores bonded to thermoplastic composites are penetrating electric vehicle battery pack cushioning and interior trim applications.
Industry Challenges
- Sterilization compatibility certification:Gamma and electron-beam sterilization validation for medical-grade EVA requires 18-24 month testing timelines that delay revenue recognition.
- High-pressure reactor capex intensity:Autoclave and tubular polymerization units demand $200-400 million investment thresholds that exclude mid-scale entrants from vinyl acetate modification above 28% content.
- Dual carbon compliance integration:China's MEE emissions monitoring and EU CBAM carbon border adjustments impose parallel reporting systems on exporters serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EVA Copolymer Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Adhesives, Coatings, Extrusions Application: Footwear, Packaging, Medical, Automotive End Use Industry: Consumer Goods, Construction, Electronics, Healthcare Form: Granules, Pellets, Sheets, Powders |
| Companies Covered | ExxonMobil Corporation, Dow Inc., DuPont, SABIC, BASF, Celanese Corporation, Hanwha Total Petrochemical, Formosa Plastics Corporation, Sinopec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EVA Copolymer Market Evolving Landscape
Material science advances and regulatory chemistry are rewriting formulation priorities across encapsulant, adhesive, and medical applications. Process intensification and sustainability metrics now filter technology adoption decisions.
Peroxide-crosslinked EVA grades with enhanced damp-heat resistance are overtaking standard copolymers in photovoltaic encapsulant specifications. Tier-1 module manufacturers in China and Southeast Asia are mandating 85°C/85% relative humidity test performance that legacy formulations fail. This specification escalation is compressing qualified supplier lists to compounders with solution-phase manufacturing control.
REACH Annex XVII restrictions on residual vinyl acetate monomer are forcing reformulation of copolymers sold across European Union member states. ECHA enforcement actions against imported medical tubing have triggered batch-testing investments by Asian exporters. German and French converters are now requiring certificates of analysis with every resin delivery.
Direct mill relationships are displacing distributor intermediaries among large-volume solar film extruders. Procurement teams at Chinese photovoltaic manufacturers are negotiating resin supply contracts spanning 3-5 years with fixed-price escalators. This channel consolidation is most visible in Jiangsu and Zhejiang provinces where encapsulant production clusters within 200 kilometers of module assembly plants.
EVA Copolymer Market Segmentation
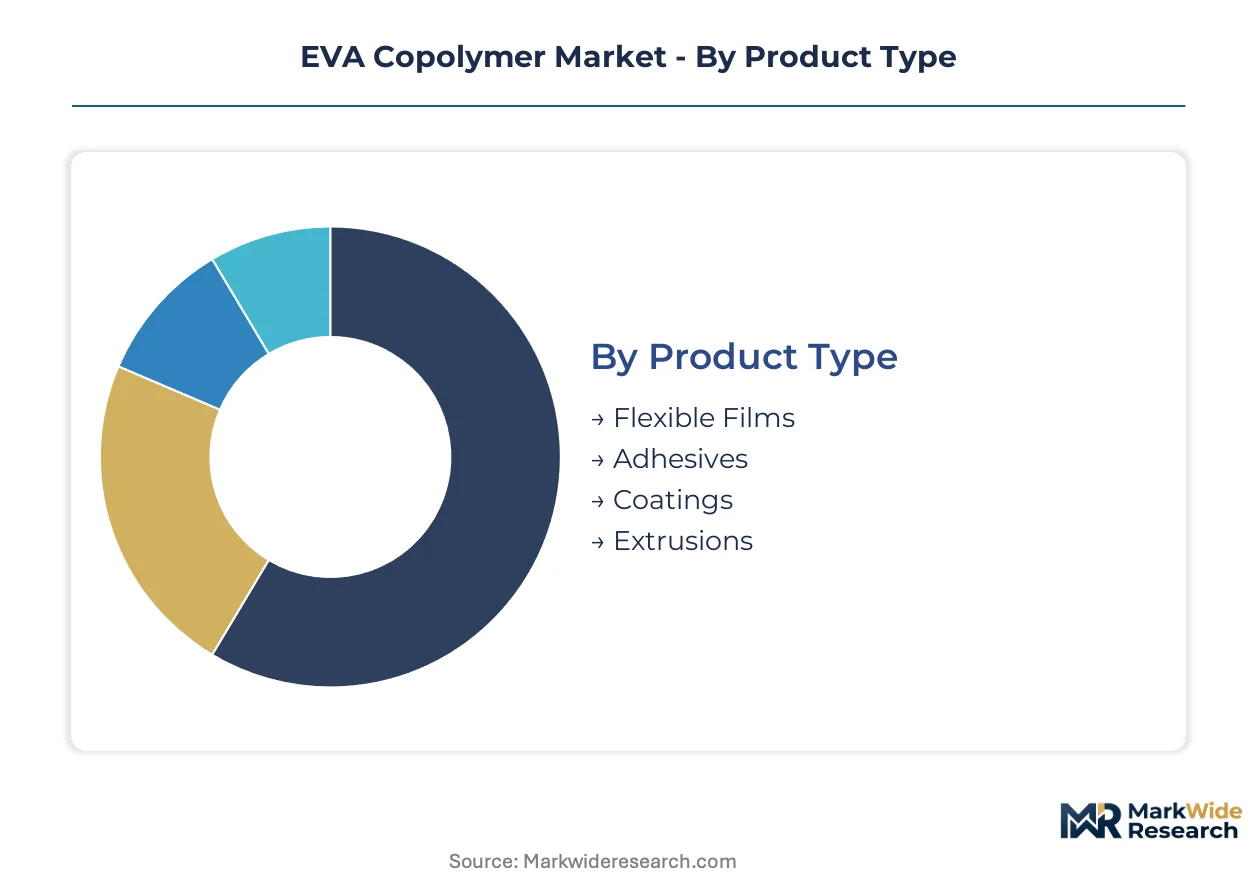
EVA copolymer procurement patterns diverge sharply across product forms and end-use specifications. Solar encapsulant films, medical tubing, and footwear soles each impose distinct vinyl acetate content requirements that filter qualified supplier pools.
Product Type:
Upgrade cycles in photovoltaic manufacturing and packaging automation are redrawing volume allocations across copolymer formats.
- Flexible Films:These formulations incorporate 28-33% vinyl acetate content for optimal optical clarity and damp-heat resistance. Procurement from Chinese photovoltaic manufacturers in Jiangsu and Zhejiang provinces is accelerating as tier-1 module producers mandate peroxide-crosslinked grades for 85°C/85% relative humidity performance testing.
- Adhesives:Hot-melt formulations with 18-25% vinyl acetate content displace solvent-based bonding systems under tightening EPA volatile organic compound enforcement. Automotive assembly plants in Michigan and electronics contract manufacturers in Mexico are locking in multi-year supply agreements ahead of capacity expansions.
- Coatings:Barrier coatings for food packaging applications leverage low-density grades with controlled melt flow indices.
- Extrusions:Foam profiles for cushioning and gasketing require precise cell structure control through blowing agent compatibility.
Volume placements concentrate in Flexible Films; the faster expansion belongs to Adhesives.
Application:
Cost sensitivity and certification intensity stratify demand across these four end-use arenas.
- Footwear:Midsole and outsole molding operations in China and Vietnam consume high-VA grades for cushioning and rebound resilience. Duty-free access to European markets under preferential trade agreements is pulling some molding capacity toward India.
- Packaging:Clarity requirements and seal strength specifications favor 9-12% vinyl acetate content for food-contact films.
- Medical:Biocompatible grades command premium pricing for pharmaceutical packaging and intravenous delivery systems. FDA device master file pathways and 18-24 month gamma sterilization validation timelines create multi-year contract stability for qualified compounders.
- Automotive:Lightweighting priorities are opening battery pack cushioning and interior trim applications to EVA foam cores bonded to thermoplastic composites.
Footwear absorbs the largest resin tonnage; Medical claims the steepest expansion trajectory.
End Use Industry:
Margin structure and customer concentration vary substantially across these four industrial demand pools.
- Consumer Goods:Footwear, sporting goods, and toy manufacturers drive high-volume, price-sensitive procurement with limited specification differentiation.
- Construction:Geomembrane and waterproofing membrane applications require UV-stabilized grades with extended outdoor durability certification.
- Electronics:Solar encapsulant films dominate this category, with procurement teams negotiating 3-5 year fixed-price contracts directly with resin producers.
- Healthcare:REACH Annex XVII residual monomer restrictions and ECHA enforcement actions against imported medical tubing have triggered batch-testing investments by Asian exporters serving German and French converters.
Electronics captures the dominant share; Healthcare is climbing the fastest.
Form:
Processing method and supply chain configuration dictate which physical formats converters specify.
- Granules:Standard extrusion and injection molding feedstock for high-volume compounding operations.
- Pellets:Dust-free handling properties suit cleanroom medical device manufacturing and automated packaging lines.
- Sheets:Pre-formed calendered products for thermoforming and die-cutting operations in automotive interior trim.
- Powders:Rotational molding and sintering applications in specialty footwear and protective equipment.
Pellets lead in value terms; Granules dominate tonnage shipments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Jiangsu province have concentrated photovoltaic encapsulant film production within 200 kilometers of tier-1 module assembly plants. This geographic clustering is reshaping resin procurement patterns across Asia-Pacific compounding hubs.
China
Jiangsu and Zhejiang provinces absorb the dominant share of solar-grade EVA resin as tier-1 photovoltaic manufacturers mandate peroxide-crosslinked grades for damp-heat resistance testing. MEE emissions monitoring requirements are filtering marginal compounders from medical-grade certification pools. Ningbo and Yiwu industrial clusters are expanding hot-melt adhesive compounding capacity to serve electronics contract manufacturers.
United States
Michigan automotive assembly plants are locking in multi-year EVA adhesive supply agreements as EPA volatile organic compound enforcement tightens. FDA device master file pathways for pharmaceutical packaging applications attract premium pricing from qualified compounders. Gulf Coast petrochemical corridors supply tubular reactor capacity for high-pressure polymerization to domestic converters.
Germany
REACH Annex XVII residual monomer restrictions are accelerating reformulation investments among European compounders seeking first-mover certification advantages. ECHA enforcement actions against imported medical tubing have triggered batch-testing requirements for Asian exporters. Frankfurt and Hamburg chemical processing clusters are consolidating solution-phase manufacturing control for solar encapsulant specifications.
India
Duty-free access to European markets under preferential trade agreements is pulling EVA sole molding operations from incumbent Chinese footwear suppliers. BIS standards for flexible packaging applications are tightening clarity and seal strength specifications for food-contact films. Tamil Nadu and Gujarat industrial corridors are attracting compounding capacity to serve domestic photovoltaic assembly expansion.
Saudi Arabia
Petrochemical complexes in the Eastern Province supply Gulf and South Asian converters with captive ethylene feedstock integration. SABIC's tubular reactor capacity anchors regional supply for high vinyl acetate content grades above 28 percent. Jeddah industrial clusters are expanding medical-grade certification pools to serve European healthcare demand.
EVA Copolymer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical majors controlling resin cost volatility through captive ethylene supply. The vendor base concentrates among Gulf Coast and Middle Eastern complexes with tubular reactor assets, filtering mid-scale entrants from vinyl acetate modification above 28 percent content. Three archetypes dominate: integrated petrochemical majors with backward feedstock control, solution-phase technology specialists with precise VA incorporation capabilities, and regional compounders serving footwear and packaging converters. Competitive moves center on multi-year procurement contracts with fixed-price escalators and sterilization compatibility certification investments for medical-grade pools.
Among integrated petrochemical majors, ExxonMobil Corporation and Dow Inc. exemplify the scale-driven archetype through polyethylene feedstock access and solution-phase manufacturing technology respectively. SABIC occupies a position within the Middle Eastern supply tier, leveraging regional petrochemical complex integration. These three companies represent the concentration of high-pressure polymerization capacity that shapes converter procurement options across photovoltaic, medical, and adhesive end uses.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Dow Inc. |
| DuPont |
| SABIC |
| BASF |
| Celanese Corporation |
| Hanwha Total Petrochemical |
| Formosa Plastics Corporation |
| Sinopec Corporation |
| Others |
Value Network & Pricing Analysis
Ethylene feedstock volatility cascades through EVA copolymer pricing tiers as naphtha-to-ethylene cost spreads compress converter margins unpredictably. Non-integrated compounders lacking captive olefin supply absorb the steepest price shocks, while Gulf Coast petrochemical corridors with tubular reactor assets command premium positioning for high vinyl acetate content grades above 28 percent.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, while spot inventory liquidations clear at discounted levels. Three-tier pricing structure across peroxide-crosslinked solar grades, standard medical certifications, and economy footwear compounds separates qualified suppliers from marginal producers. Price differentiation hinges on REACH Annex XVII compliance documentation and FDA device master file pathways. Cost compression in non-integrated compounding tiers is intensifying because feedstock ethylene volatility swings converter margins without warning. Footwear molding operations in Vietnam and India exhibit the highest price sensitivity, while photovoltaic manufacturers in Jiangsu province prioritize damp-heat resistance certification over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with tubular reactor capacity clustering in Gulf Coast and Middle Eastern petrochemical complexes, exposing buyers to regional disruption. Geographic supply concentration centers on Saudi Arabia, China, and the United States for high-pressure polymerization assets. Raw material dependencies rest on naphtha-derived ethylene, vinyl acetate monomer, and peroxide initiators for crosslinked grades. Regulatory restriction risk from REACH residual monomer enforcement and EPA volatile organic compound provisions filters marginal exporters from medical-grade certification pools. Distribution runs through direct mill relationships displacing distributor intermediaries among large-volume solar film extruders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EVA copolymer market sits in a technology-transition phase as peroxide-crosslinked grades with enhanced damp-heat resistance displace legacy formulations in photovoltaic encapsulant specifications. Tier-1 module manufacturers now mandate 85°C/85% relative humidity test performance that standard copolymers fail.
For Market Incumbents: Extend solution-phase manufacturing control advantages by locking in multi-year procurement contracts with Chinese photovoltaic manufacturers before capacity expansions saturate qualified supplier lists. Backward integration into captive ethylene supply buffers feedstock volatility swings that compress non-integrated converter margins. Prioritize sterilization compatibility certification investments for medical-grade pools to defend against emerging biocompatible grade specialists. For New Entrants and Emerging Players: Begin with India footwear export manufacturing corridors in Tamil Nadu and Gujarat, where duty-free access to European markets under preferential trade agreements is pulling sole molding operations from incumbent Chinese suppliers. Target hot-melt adhesive compounding for automotive assembly plants in Michigan as EPA volatile organic compound enforcement tightens. Establish direct mill relationships with electronics contract manufacturers in Mexico to bypass distributor markups. For Investors and Strategic Acquirers: Peroxide-crosslinked grade qualification announcements from Jiangsu province module manufacturers are the leading indicator that solution-phase technology specialists will capture disproportionate margin expansion. Long-term viability favors integrated petrochemical majors with tubular reactor assets and backward feedstock control over mid-scale entrants excluded from vinyl acetate modification above 28 percent content. Monitor ECHA enforcement actions against imported medical tubing as the signal for batch-testing investment requirements that filter Asian exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Ethylene Supply | Gulf Coast petrochemical corridors buffer naphtha-to-ethylene cost spread volatility for integrated compounders. |
| Peroxide-Crosslinked Grade Capacity Expansion | Tier-1 photovoltaic manufacturers in Jiangsu province mandate damp-heat resistance testing that legacy formulations fail. |
| FDA Device Master File Pathway Investment | Pharmaceutical packaging and intravenous delivery systems offer premium pricing pools with multi-year contract stability. |
| Long-Term Supply Agreement with Solar Film Extruders | Chinese procurement teams negotiate 3-5 year fixed-price contracts with direct resin producers in Zhejiang province. |
| REACH Annex XVII Compliance Certification | German and French converters now require certificates of analysis with every resin delivery from Asian exporters. |
Research Methodology
Document review covered customs and trade data, SEC 10-K filings from petrochemical majors, ACC and Cefic industry reports, and REACH Annex XVII regulatory filings, complemented by interviews with plant managers at high-pressure polymerization facilities, procurement leads at photovoltaic module manufacturers, distribution channel partners serving footwear molding operations, and technical R&D directors at solution-phase technology specialists. Bottom-up volume modeling from application-level demand and top-down validation from feedstock ethylene consumption patterns were triangulated to cross-check outputs.
Market size and growth trajectory outputs across the analysis window reflect segment-level modeling by vinyl acetate content tier, end-use industry concentration, and regional production hub configuration. CAGRs were derived from historical ethylene-vinyl acetate copolymer demand elasticity against photovoltaic installation forecasts and footwear export manufacturing shifts. Key forecast inputs included naphtha-to-ethylene cost spread projections and REACH enforcement intensity indicators from ECHA disclosure patterns.
Feedstock ethylene price volatility, regulatory enforcement divergence between EPA and REACH jurisdictions, and polypropylene substitution advances in flexible packaging are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about tubular reactor capacity expansion timelines and photovoltaic module manufacturer qualification protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
PEKK Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
United States Polyols Market