
 Global Cloud Managed Wi-Fi Market | 2026-2036
Global Cloud Managed Wi-Fi Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cloud Managed Wi-Fi Market Foresight
The gap between on-premises wireless controllers and fully cloud-native orchestration is narrowing as firmware abstraction layers mature. Cisco Systems leverages its Meraki platform to anchor cloud-first deployments across multinational corporate offices. Aruba Networks competes through its Edge Services Platform, which sustains deep integration with hybrid cloud environments. Extreme Networks differentiates via subscription-based network analytics that positions the vendor for recurring revenue in educational campuses.
Cloud Managed Wi-Fi denotes a wireless local area network architecture where access points, controllers, and policy engines are administered through centralized cloud infrastructure rather than localized hardware, typically operating on 802.11ax or 802.11be standards with zero-touch provisioning and AI-driven radio resource management. Its primary commercial purpose is to reduce operational overhead for distributed organizations while enabling real-time visibility into user density, application performance, and security posture across thousands of endpoints. The solution segment shows security management and network analytics commanding margin pools as organizations prioritize threat detection and bandwidth optimization over basic connectivity. The use case dimension reveals enterprise connectivity and hospitality networks as the most structurally entrenched categories, while retail engagement represents the fastest expansion path as brick-and-mortar operators deploy location-based services.
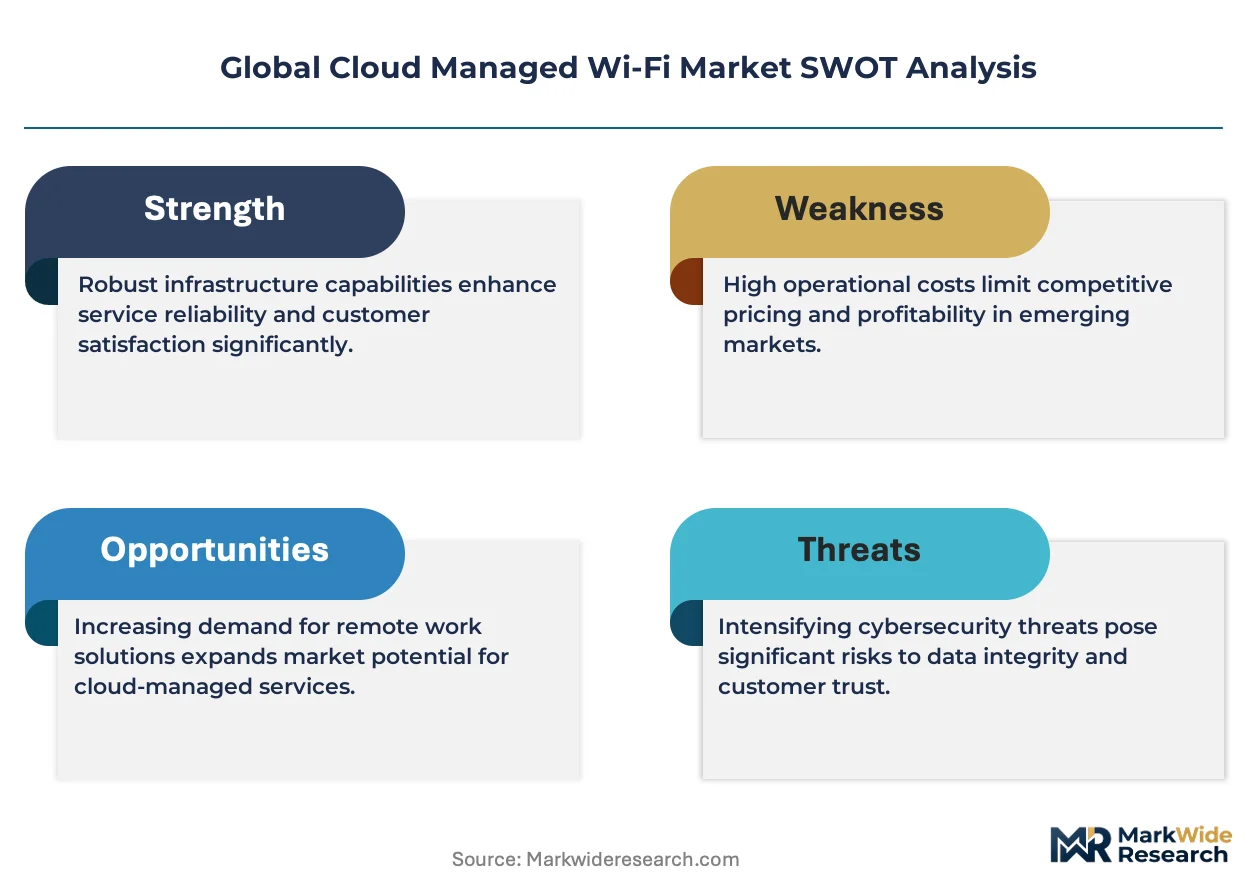
The FCC in the United States governs spectrum allocation and device certification for Wi-Fi equipment, directly shaping product roadmaps through 6 GHz unlicensed access rules. Europe's ETSI and GDPR framework impose data residency and encryption standards that vendors must embed at the controller level, creating compliance barriers for non-EU cloud providers. India's TRAI spectrum policies and data localization requirements add another layer of jurisdictional complexity for global platform operators. Stakeholders must monitor how fragmented sovereignty mandates affect multi-tenant cloud controller architectures and whether vendor consolidation accelerates as compliance costs mount.
Market Dynamics
Firmware abstraction layers are collapsing the traditional boundary between on-premises wireless controllers and cloud-native orchestration, forcing vendors to re-architect controller software for multi-tenant SaaS delivery rather than hardware-centric licensing models.
Growth Catalysts
- EU AI Act and GDPR compliance:European enterprises are migrating to cloud-native architectures to satisfy data residency and automated governance mandates, creating procurement pull for policy-engine-as-a-service models.
- Smart city infrastructure buildouts:Municipal governments in the United States, Germany, and India are issuing RFPs for city-wide Wi-Fi fabrics that require centralized visibility and zero-touch provisioning at scale.
- 802.11be (Wi-Fi 7) spectrum efficiency:The new standard's multi-link operation and 320 MHz channels are accelerating hardware refresh cycles among bandwidth-intensive campus environments.
Market Restraints
- Controller-level compliance costs:ETSI encryption standards and India's TRAI data localization rules force vendors to maintain jurisdiction-specific controller instances, fragmenting engineering resources.
- Silicon supply concentration:Wi-Fi 7 radio chip fabrication remains concentrated among a handful of foundries, creating procurement bottlenecks for access point manufacturers.
- Private 5G substitution threat:Industrial campuses in mining and logistics are piloting CBRS-based private cellular as an alternative to high-density Wi-Fi for mission-critical mobility.
Strategic Opportunities
- Retail engagement applications:Brick-and-mortar operators are deploying location-based services and footfall analytics, opening subscription revenue pools beyond connectivity.
- Educational campus analytics:K-12 and university networks represent underpenetrated demand for AI-driven radio resource management and behavioral visibility tools.
- Convergence of network and security stacks:SASE architecture adoption is creating attach opportunities for cloud-managed Wi-Fi vendors to bundle zero-trust network access with wireless infrastructure.
Industry Challenges
- Multi-cloud controller integration:Enterprises with hybrid Azure-AWS-GCP footprints demand seamless policy propagation across cloud instances, stretching vendor DevOps capacity.
- Legacy 802.11n/ac migration friction:Distributed organizations with thousands of aging access points face capital planning complexity and site-by-site deployment coordination.
- Radio frequency engineering talent scarcity:The specialized skill set for predictive modeling and interference mitigation in dense environments commands premium compensation, constraining service provider scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cloud Managed Wi-Fi Market |
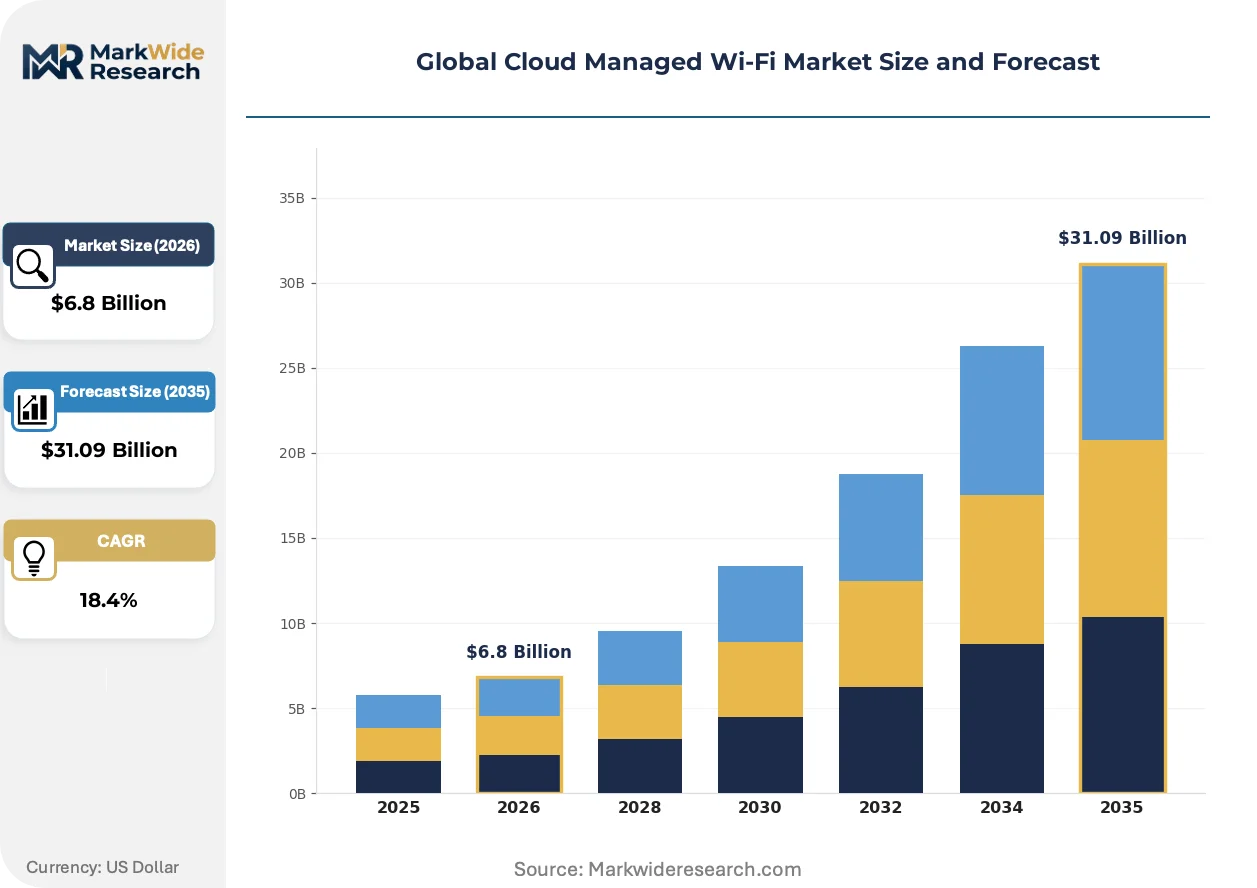
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution: Network Analytics, Security Management, Device Management, Bandwidth Optimization, Access Control Use Case: Guest Wi-Fi, Enterprise Connectivity, Retail Engagement, Educational Campuses, Hospitality Networks End User: Telecom Operators, Managed Service Providers, Educational Institutions, Hotels, Corporate Offices |
| Companies Covered | Cisco Systems, Aruba Networks, Extreme Networks, Juniper Networks, Ubiquiti, CommScope, Fortinet, Ruckus Networks, Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cloud Managed Wi-Fi Market Shifts & Advancements
Artificial intelligence is embedding into every layer of wireless infrastructure, from automated channel selection to predictive capacity planning, compressing the operational expertise required to manage enterprise-scale deployments.
Wi-Fi 7 silicon with multi-link operation and punctured preamble is digitizing how distributed enterprises architect their access layer, replacing hardware-centric controller clusters with API-driven orchestration planes. Large corporate campuses and hospitality chains are piloting these chipsets aggressively, treating 2024-2025 as a migration window before 6 GHz spectrum congestion intensifies. This transition is digitizing vendor business models toward recurring software revenue and away from perpetual hardware margins.
The EU AI Act's risk classification framework for automated decision-making systems is forcing cloud-managed Wi-Fi vendors to document and audit their radio resource management algorithms for transparency and human oversight. Controllers that autonomously adjust power levels or steer clients between bands now face conformity assessment requirements. European managed service providers are responding by demanding algorithmic explainability APIs from their platform suppliers, creating a compliance capability gap between established vendors and new entrants.
Enterprise buyers are consolidating wireless procurement under managed service contracts that bundle hardware, software, and operational support into single-vendor relationships. This pattern displaces the historical model of separate CAPEX purchases for access points and OPEX subscriptions for cloud management. The shift is most pronounced among mid-market healthcare systems and regional retail chains in the United States, where IT headcount constraints make fully outsourced network operations preferable to in-house expertise maintenance.
Global Cloud Managed Wi-Fi Market Segmentation
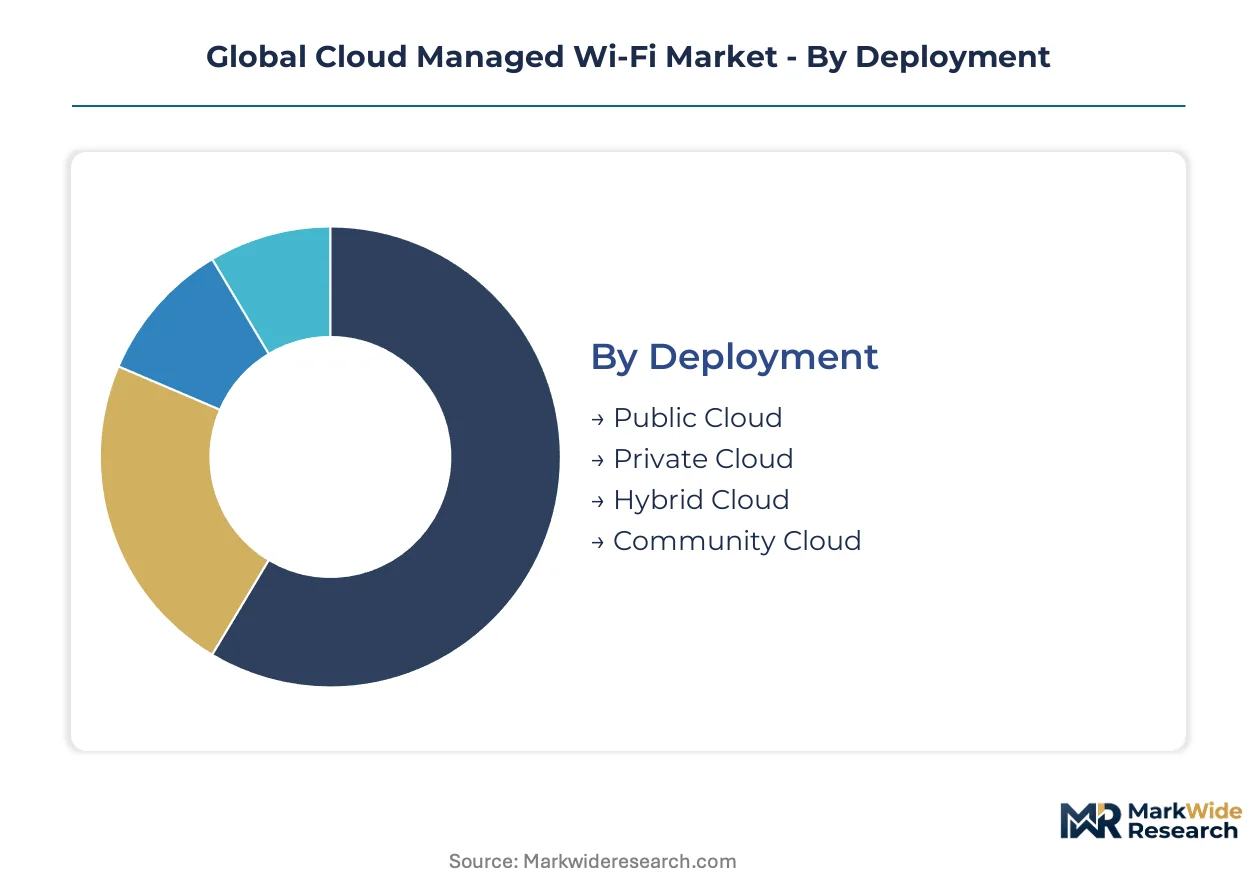
Cloud Managed Wi-Fi deployments fragment across infrastructure models, solution stacks, and operational contexts. Each dimension carries distinct margin profiles, compliance obligations, and vendor competitive dynamics that shape procurement patterns.
Deployment:
Use cases span from single-tenant sovereignty requirements to multi-tenant scale economies, with procurement decisions hinging on data residency mandates and operational control preferences.
- Public Cloud:Multi-tenant controller architectures deliver zero-touch provisioning and automatic firmware updates through hyperscaler infrastructure. Demand concentrates among mid-market retail chains and regional healthcare systems in the United States seeking to eliminate on-premises hardware maintenance overhead.
- Private Cloud:Dedicated controller instances run within enterprise data centers or sovereign cloud regions, satisfying GDPR data localization and India's TRAI data residency requirements. European financial institutions and German automotive suppliers anchor procurement volume here.
- Hybrid Cloud:Policy engines split between edge controllers and cloud orchestration planes, enabling seamless failover during WAN disruptions. Distributed logistics operators with mission-critical mobility requirements favor this architecture.
- Community Cloud:Shared infrastructure serving consortia of educational institutions or municipal governments achieves procurement scale while maintaining jurisdictional isolation. Smart city deployments in India leverage this model for city-wide Wi-Fi fabrics.
Established volume favors Public Cloud; emerging adoption favors Private Cloud.
Solution:
Margin pools concentrate where software-defined functionality displaces hardware-centric legacy approaches, with buyers prioritizing threat visibility and bandwidth intelligence over basic connectivity provisioning.
- Network Analytics:AI-driven radio resource management and predictive capacity planning compress operational expertise requirements for dense campus environments. K-12 districts and university systems in Germany drive procurement expansion.
- Security Management:Controller-embedded threat detection, rogue access point identification, and encrypted traffic inspection address zero-trust architecture mandates. GDPR and EU AI Act compliance obligations accelerate European enterprise procurement.
- Device Management:Zero-touch provisioning and lifecycle orchestration for heterogeneous access point fleets reduce truck-roll frequency. Managed service providers bundle this capability into fully outsourced network operations contracts.
- Bandwidth Optimization:Application-aware traffic shaping and dynamic quality-of-service enforcement prioritize latency-sensitive workloads. Hospitality chains deploy these tools to guarantee guest streaming experience.
- Access Control:Policy engines integrating with enterprise identity providers enable role-based network segmentation. Corporate offices with bring-your-own-device populations require granular guest and employee access differentiation.
Security Management commands premium pricing; Network Analytics climbs the fastest.
Use Case:
Operational contexts determine hardware density, coverage patterns, and software feature requirements, with location-based services opening subscription revenue beyond connectivity.
- Enterprise Connectivity:High-density 802.11ax and 802.11be deployments support thousands of concurrent users across corporate campuses. Multinational headquarters in the United States and India anchor replacement cycles.
- Retail Engagement:Footfall analytics, proximity marketing, and heat mapping transform wireless infrastructure into customer intelligence platforms. Brick-and-mortar operators deploy these capabilities to counter e-commerce displacement.
- Guest Wi-Fi:Captive portal authentication and branded splash pages deliver marketing touchpoints alongside basic connectivity. Hotels and coffee chains treat this as table stakes for customer experience.
- Educational Campuses:Behavioral visibility tools and classroom-specific bandwidth allocation address K-12 and university IT governance requirements. Federal E-Rate funding in the United States shapes procurement timing.
- Hospitality Networks:Seamless roaming across property portfolios and integration with property management systems define competitive requirements. International hotel chains standardize on single-vendor global deployments.
Enterprise Connectivity holds dominant share; Retail Engagement offers steepest expansion trajectory.
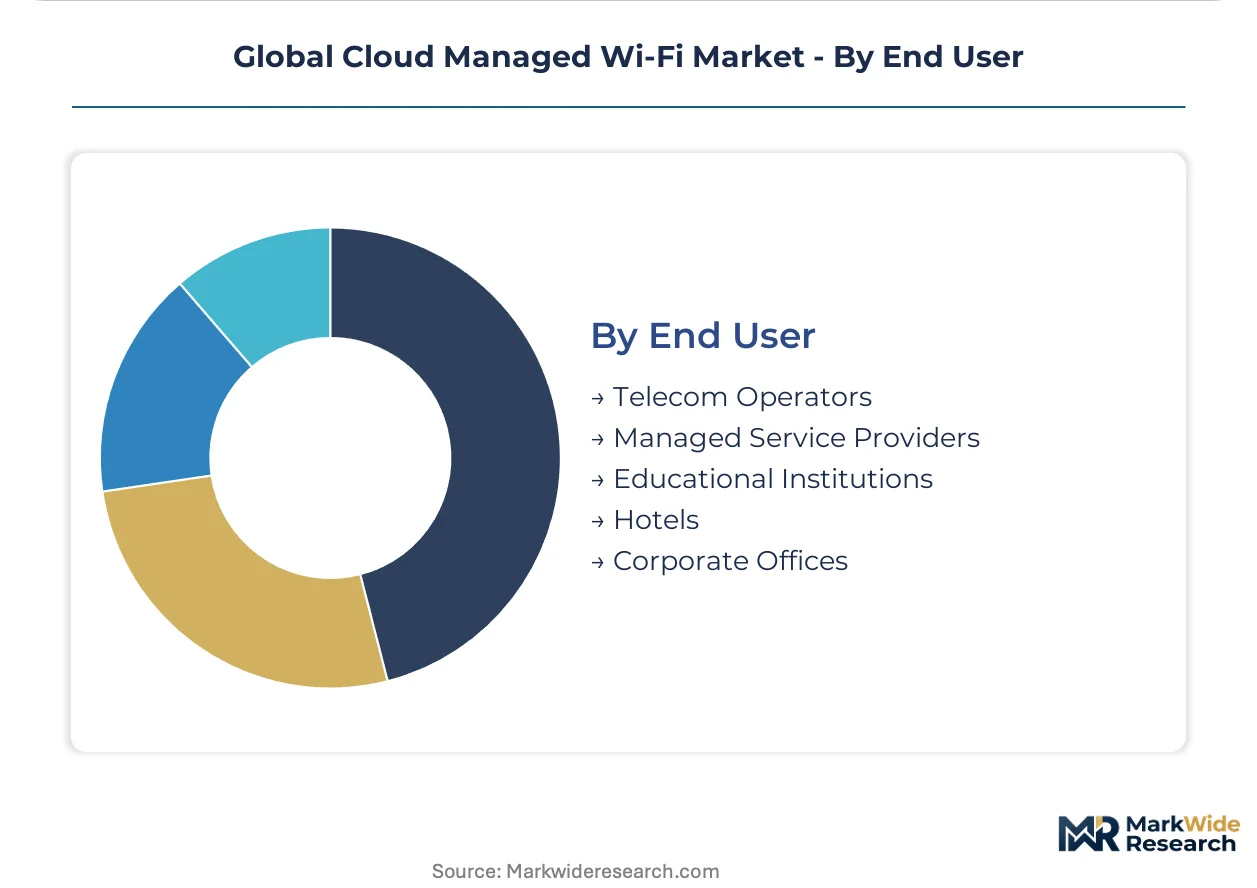
End User:
Procurement authority varies between internal IT organizations, outsourced managed service relationships, and carrier-led infrastructure builds, each with distinct vendor selection criteria and contract structures.
- Managed Service Providers:Multi-tenant cloud controllers enable economies of scale across heterogeneous client portfolios. MSPs consolidate wireless procurement under single-vendor relationships bundling hardware, software, and operational support.
- Telecom Operators:Carrier-grade Wi-Fi offloads cellular traffic in dense urban corridors and extends broadband service footprints. India's TRAI spectrum policies influence infrastructure investment timing.
- Corporate Offices:IT headcount constraints push mid-market enterprises toward fully outsourced network operations rather than in-house expertise maintenance. Regional retail chains exemplify this shift.
- Educational Institutions:E-Rate funding cycles and grant-dependent capital planning create lumpy procurement patterns. K-12 districts prioritize AI-driven radio management to compensate for limited RF engineering staff.
- Hotels:Property management system integration and guest experience standardization drive brand-level vendor consolidation. International chains demand global deployment consistency.
Managed Service Providers capture expanding wallet share; Educational Institutions remain underpenetrated relative to connectivity need.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based cloud controller vendors export subscription-based orchestration platforms to European and Indian enterprise buyers, with procurement flows concentrating in Germany's automotive corridor and India's smart city clusters.
United States
Enterprise headquarters in healthcare and retail drive dense campus deployments. FCC 6 GHz unlicensed access rules accelerate Wi-Fi 7 hardware refresh cycles. Dallas-Fort Worth and Atlanta metro areas host concentrated managed service provider operations serving mid-market chains.
Germany
Automotive suppliers and financial institutions demand sovereign controller instances. GDPR and EU AI Act compliance mandates push procurement toward private cloud architectures. Stuttgart and Munich industrial clusters anchor enterprise connectivity replacement programs.
India
Smart city infrastructure buildouts and digital campus initiatives scale multi-tenant deployments. TRAI data localization requirements force jurisdiction-specific controller engineering. Bangalore and Hyderabad tech corridors concentrate hospitality and educational network rollouts.
United Kingdom
Corporate office consolidation under managed service contracts accelerates cloud-first procurement. GDPR alignment post-Brexit maintains encryption and residency standards. London's financial district drives premium-tier security management attach rates.
Japan
Hospitality chains and corporate campuses pilot Wi-Fi 7 for high-density mobility. METI standards for wireless infrastructure interoperability shape vendor qualification. Tokyo-Osaka corridor anchors replacement demand from aging 802.11n/ac estates.
Global Cloud Managed Wi-Fi Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment archetypes, with consolidated platform vendors holding enterprise procurement relationships while point-solution vendors capture niche analytics and security attach opportunities. The structure tiers between multi-tenant SaaS orchestrators and hardware-centric legacy controllers. Strategic archetypes include cloud-native platform vendors, network-security convergence specialists, and managed service enablers. Competitive moves center on subscription model migration and SASE architecture bundling.
Within the cloud-native platform tier, Cisco Systems and Aruba Networks exemplify controller-software-as-a-service delivery at scale. Extreme Networks occupies a position emphasizing subscription-based network analytics for educational and hospitality verticals. Juniper Networks represents the network-security convergence archetype through cloud-managed wireless integrated with zero-trust frameworks. These three vendors collectively anchor the competitive dynamics shaping procurement patterns across enterprise, retail, and institutional segments.
| Leading Market Players |
|---|
| Cisco Systems |
| Aruba Networks |
| Extreme Networks |
| Juniper Networks |
| Ubiquiti |
| CommScope |
| Fortinet |
| Ruckus Networks |
| Huawei Technologies |
| Others |
Supply & Pricing Matrix
Overcapacity in Taiwan-based Wi-Fi 7 radio chip foundries is compressing component pricing while simultaneously constraining vendor margin expansion as buyers demand aggressive subscription discounts for cloud controller platforms.
Pricing Analysis
The Wi-Fi 7-to-Wi-Fi 6 pricing gap spans roughly 40-60 percent at the access point level, while legacy 802.11ac hardware trades at commodity levels as educational institutions liquidate aging estates. Subscription-based SaaS tiers dominate procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by analytics depth and security feature bundles. Cost compression in the mid-market tier is intensifying because managed service providers are consolidating procurement volume under single-vendor relationships. Corporate offices with constrained IT headcount exhibit highest price sensitivity, while German automotive suppliers accepting private cloud deployments show lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
US Commerce Department export controls on advanced semiconductor manufacturing equipment are fragmenting Wi-Fi 7 silicon sourcing strategies among access point vendors. Radio chip fabrication concentrates in Taiwan, South Korea, and select US facilities, while printed circuit board assembly draws from China, Vietnam, and Mexico. Supply chain risk centers on single-source vulnerability for 320 MHz-capable baseband processors from a handful of foundry operators. Distribution runs through direct OEM channels for enterprise accounts and tier-one distributors for mid-market verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of radio frequency engineering talent capable of predictive modeling in dense 6 GHz environments is constraining service provider scaling and creating premium compensation arbitrage opportunities for vendors with automated tooling.
For Market Incumbents: Insulate recurring revenue streams by embedding zero-trust network access capabilities into cloud controller platforms before SASE architecture bundling becomes table stakes. Acquire specialized Wi-Fi 7 RF engineering teams in Bangalore and Dallas-Fort Worth to offset talent scarcity in deployment-heavy verticals. Private 5G substitution threats in industrial logistics demand proactive campus mobility proof-of-concept programs. For New Entrants and Emerging Players: Establish a beachhead in educational campus analytics by targeting K-12 districts with AI-driven radio resource management tools that compensate for limited in-house RF expertise. Retail engagement applications represent the most penetrable expansion path, with location-based services opening subscription revenue pools beyond connectivity. A channel-centric go-to-market approach through regional managed service providers accelerates customer acquisition without direct enterprise sales overhead. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because wireless controllers are evolving into policy-engine-as-a-service platforms with security attach rates climbing. Acquisition targets should display deep vertical integration into cloud-native orchestration and existing MSP channel relationships. The signal to watch is FCC 6 GHz spectrum congestion intensity in major metro corridors, which would accelerate hardware refresh cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Model Migration | Recurring revenue from cloud controllers displaces perpetual hardware licensing at Cisco and Aruba. |
| SASE Architecture Bundling | Zero-trust network access integration creates attach opportunities with enterprise security budgets. |
| Wi-Fi 7 Platform Launch | Multi-link operation chipsets from Qualcomm and Broadcom enable 320 MHz channel deployments. |
| Vertical Market Specialization | Educational campus analytics from Extreme Networks captures E-Rate funding cycles. |
| Geographic Expansion | Private cloud controller instances in Frankfurt satisfy GDPR data localization mandates. |
Research Methodology
The analysis maps public cloud, private cloud, hybrid cloud, and community cloud deployment archetypes, each validated through primary interviews with CTOs, IT procurement officers, MSP operations directors, and channel integration specialists, combined with secondary triangulation across FCC spectrum filings, ETSI standardization documents, TRAI policy circulars, hyperscaler capex disclosures, and vendor SEC 10-K segment reporting. Bottom-up access point shipment modeling and top-down enterprise IT spending analysis were cross-referenced for convergence.
Assumptions around 6 GHz spectrum availability, Wi-Fi 7 silicon yield rates, and EU AI Act enforcement timelines were held fixed across base-case scenarios while tariff exposure and private 5G substitution elasticity were varied in sensitivity testing. Segmentation dimensions modeled include deployment model, solution stack, use case context, and end-user procurement authority. CAGRs were derived from installed base replacement curves and net new smart city infrastructure commitments.
Stress conditions across silicon supply concentration, data sovereignty mandate fragmentation, and RF engineering labor scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in FCC unlicensed spectrum allocation or EU AI Act risk classification thresholds for automated radio resource management would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Carrier Routing Equipment Market
Network Technology
Global Active Network Management Market
Network Technology
WAN Optimization Controllers Market
Network Technology
Network Telemetry Market
Network Technology
ISP Management Systems Market
Network Technology
Residential Routers Market
Network Technology
Network Management Systems (NMS) Market
Network Technology
Fiber to the Home (FTTH) Market
Network Technology
Cloud Gateway Module Market
Network Technology
Optical Network Equipment Market
Network Technology
Virtual Router Market
Network Technology
Global Wireless Router Market
Network Technology
Gigabit Ethernet Market
Network Technology
Router and Switch Market
Network Technology
CPE Router Market
Network Technology
Smart Network Interface Card (Smartnic) Market