
 Global Enterprise Content Collaboration Market | 2026-2036
Global Enterprise Content Collaboration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Content Collaboration Market Foresight
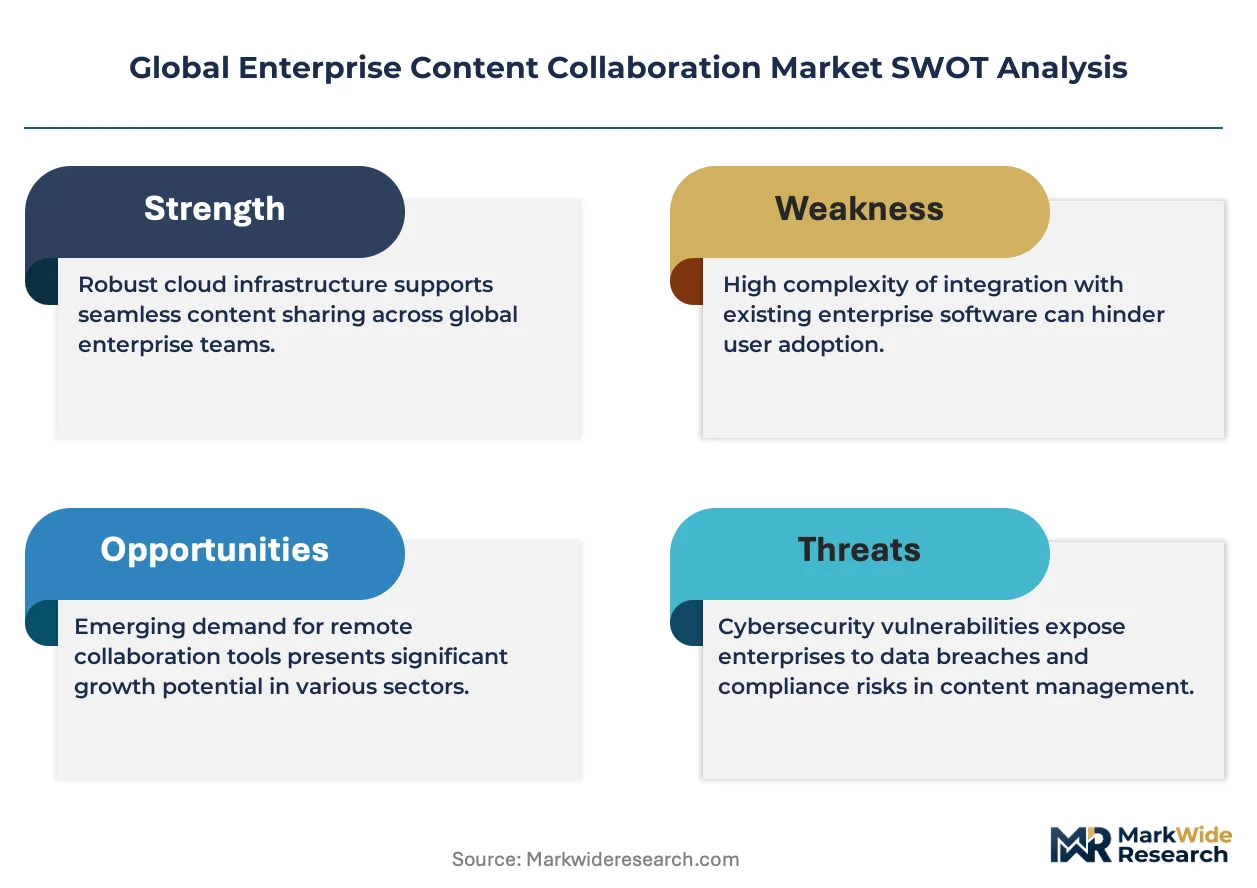
The gap between premium integrated suites and commodity file-sharing tools is broadening. Microsoft Corporation leverages its Office 365 ecosystem to anchor enterprise-grade workflow automation. Google competes through AI-native real-time editing embedded across Workspace applications. Box, Inc. specializes in regulated verticals where data residency and compliance certifications dominate procurement criteria.
Enterprise content collaboration encompasses software platforms that enable simultaneous document creation, version control, and cross-organizational information exchange through centralized repositories with granular permission architectures. These systems typically integrate API connectivity, single sign-on protocols, and end-to-end data encryption to secure intellectual property across distributed workforces. Deployment via hybrid cloud models is expanding fastest among manufacturing corporations and government agencies balancing accessibility with sovereignty requirements. Document management and workflow automation solutions capture disproportionate margin pools due to deep customization demands and recurring integration services.
GDPR enforcement by European data protection authorities, the EU AI Act's risk-classification framework for automated content processing, and ISO 27001 certification mandates collectively elevate compliance costs for cross-border data flows. HIPAA security rules in the United States impose parallel encryption and access-audit obligations on healthcare-adjacent collaboration deployments. Stakeholders must weigh sovereign cloud requirements against the interoperability limitations of region-locked infrastructure investments.
Market Dynamics
Real-time document co-authoring platforms are compressing procurement cycles as financial services firms demand instantaneous cross-border collaboration without compromising GDPR and EU AI Act compliance obligations.
Growth Catalysts
- GDPR enforcement:European data protection authorities are mandating encrypted sovereign-hosted stacks, forcing enterprises to upgrade from commodity file-sharing to certified enterprise-grade repositories.
- Financial services digitization:Real-time co-authoring platforms now anchor trading floor workflows and regulatory filing preparation across London, Frankfurt, and Singapore banking clusters.
- Hybrid cloud architectures:Manufacturing corporations in Germany are deploying on-premises hybrid models to balance workforce accessibility with data sovereignty requirements.
Market Restraints
- Compliance cost escalation:ISO 27001 certification mandates and HIPAA security rules impose parallel encryption and access-audit obligations that inflate total cost of ownership for healthcare-adjacent deployments.
- Interoperability friction:Region-locked infrastructure investments in France and Germany create technical silos that limit cross-border document exchange with non-EU partners.
- Technical debt accumulation:Legacy on-premises document management systems in industrial conglomerates resist API-native integration, delaying cloud migration timelines.
Strategic Opportunities
- EU AI Act risk classification:Automated content processing systems face mandatory algorithmic transparency requirements, creating demand for audit-ready collaboration platforms with embedded compliance documentation.
- Underpenetrated sovereign cloud:Saudi Arabia and UAE enterprises are constructing national cloud frameworks that require localized collaboration stacks with Arabic-language workflow support.
- AI-native editing convergence:Natural language processing engines embedded within document repositories are enabling generative contract drafting and automated clause extraction for legal departments.
Industry Challenges
- Zero-trust architecture implementation:Granular permission architectures require specialized cybersecurity talent scarce in mid-market IT departments across Italy and Spain.
- Cross-certification complexity:Simultaneous pursuit of SOC 2 Type II, ISO 27001, and national sovereign cloud certifications extends sales cycles by 8-14 months for vendor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Content Collaboration Market |
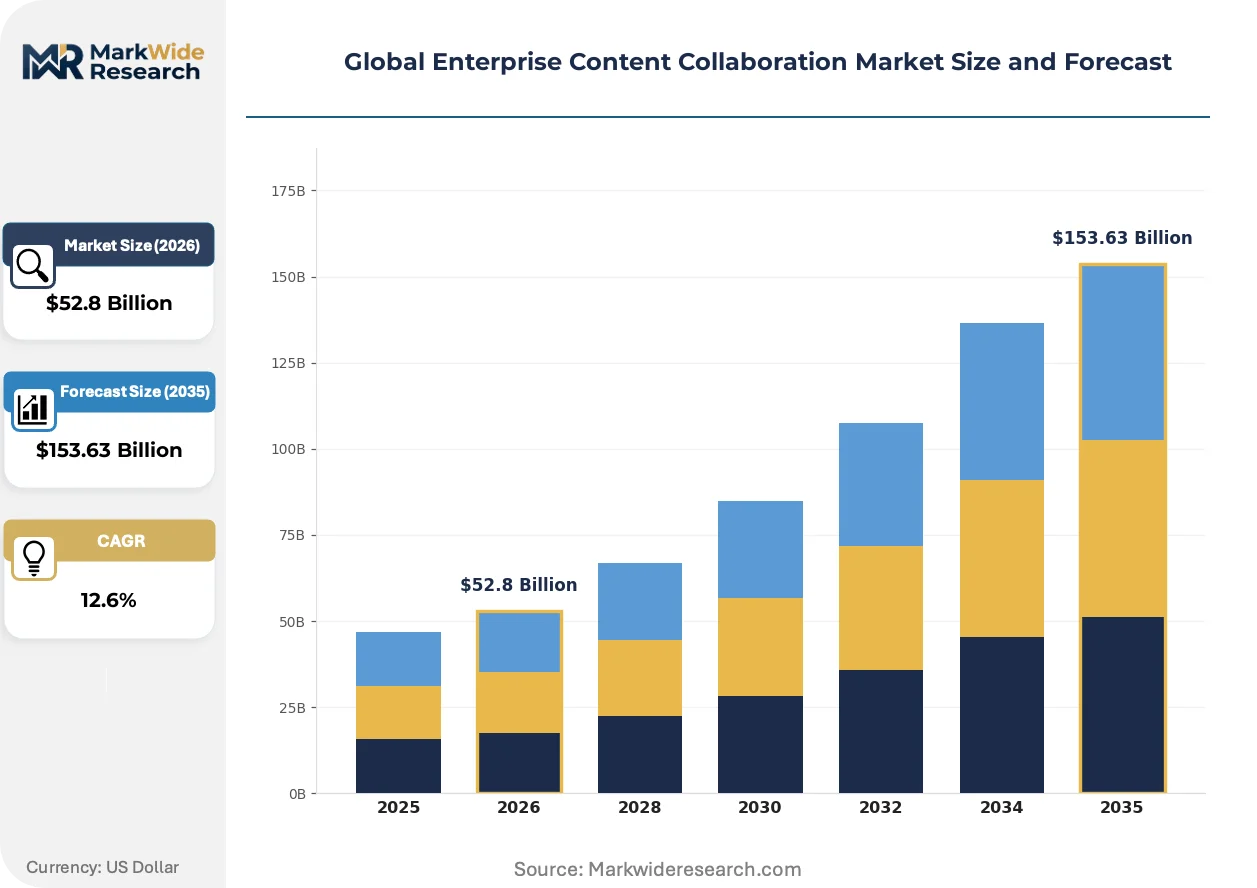
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $153.63 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Cloud Storage, Document Management, Workflow Automation, Real-Time Editing, Digital Asset Management, Enterprise Social Networking Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User Industry: Technology Firms, Financial Institutions, Government Agencies, Educational Entities, Manufacturing Corporations, Telecommunications Providers Integration Capability: API Connectivity, Single Sign-On, Artificial Intelligence, Mobile Access, Collaboration Bots, Data Encryption |
| Companies Covered | Microsoft Corporation, Oracle Corporation, Box, Inc., OpenText Corporation, IBM Corporation, Cisco Systems, Inc., Google, Atlassian Corporation, Slack Technologies, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Content Collaboration Market Shifts & Advancements
Artificial intelligence is embedding into document workflows faster than procurement frameworks can adapt, compressing the gap between draft creation and executive approval while introducing new algorithmic governance obligations.
Generative AI for contract drafting is converging with enterprise content repositories to automate clause generation and risk flagging. Legal departments at Fortune 500 industrials are piloting these tools for M&A due diligence and vendor agreement templating. The technology is converging with traditional version control systems, collapsing the boundary between document creation and compliance review into single-platform workflows.
The EU AI Act's risk-classification framework for automated content processing is mandating algorithmic impact assessments and human-in-the-loop documentation. Industrial consequence includes mandatory audit trails for AI-generated contract modifications and automated translation outputs. Healthcare and financial services deployments across Germany, France, and the Netherlands face the steepest compliance ramps, with procurement teams now requiring vendors to pre-certify high-risk system classifications.
Enterprise buying committees are consolidating vendor relationships from point solutions toward integrated suites, compressing evaluation cycles but raising switching costs. Channel disruption is visible as direct vendor-to-CIO relationships displace systems integrator intermediaries for initial platform selection. This pattern concentrates most visibly in the United States, where healthcare networks and federal contractors are mandating FedRAMP-authorized platforms that bundle document management with video conferencing and identity management.
Global Enterprise Content Collaboration Market Segmentation
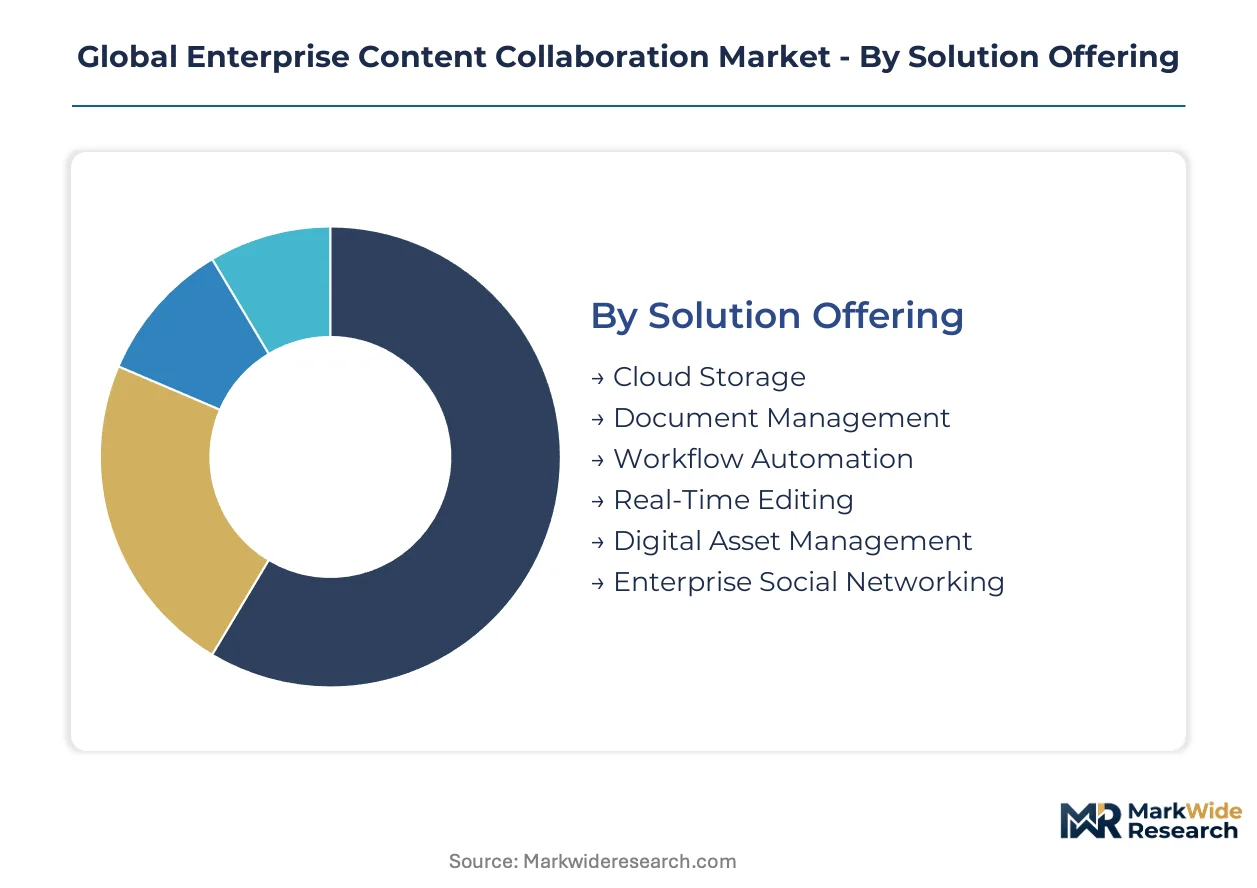
Enterprise content collaboration platforms fragment across multiple technical and commercial axes, each commanding distinct procurement criteria and margin structures. Buyers evaluate solutions through the lens of data sovereignty requirements, legacy system compatibility, and vertical-specific compliance obligations.
Solution Offering:
Functional architecture determines integration depth and recurring revenue potential across customer segments.
- Cloud Storage:Foundational object storage with tiered durability guarantees and geographic replication policies. Financial institutions in Frankfurt and Singapore clusters prioritize encrypted sovereign-hosted instances over commodity alternatives.
- Document Management:Centralized repositories with granular permission architectures and version control protocols. Manufacturing corporations in Germany anchor procurement decisions on ISO 27001 certification and API-native integration capabilities.
- Workflow Automation:Rules-based routing engines connecting document states to approval hierarchies.
- Real-Time Editing:Simultaneous co-authoring with operational transformation algorithms and conflict resolution.
- Digital Asset Management:Metadata-rich media repositories with transcoding pipelines and rights management.
- Enterprise Social Networking:Activity streams and expertise location layered atop document-centric workflows.
Document Management leads on scale; Real-Time Editing leads on momentum.
Deployment Model:
Infrastructure location directly shapes compliance posture and total cost of ownership for regulated buyers.
- Hybrid Cloud:Split architectures placing sensitive data on-premises while exposing collaboration interfaces through cloud gateways. German industrial conglomerates favor this model for balancing workforce accessibility with GDPR-mandated data residency.
- Public Cloud:Multi-tenant SaaS delivery with shared infrastructure economics. Technology firms and educational entities drive volume here, accepting standardized security models in exchange for rapid provisioning.
- Private Cloud:Dedicated single-tenant environments with custom security boundaries.
- On-Premises:Legacy server installations resisting cloud migration due to technical debt or air-gapped requirements.
Public Cloud dominates transaction volume; Hybrid Cloud climbs the fastest on regulatory tailwinds.
End User Industry:
Vertical specialization determines feature prioritization and sales cycle duration.
- Financial Institutions:Trading floor workflows and regulatory filing preparation demand sub-second synchronization with immutable audit trails. London and Frankfurt banking clusters compress procurement cycles for real-time co-authoring platforms.
- Government Agencies:Classified and unclassified document handling with FedRAMP or national sovereign cloud mandates. Federal contractors in the United States bundle requirements across document management, video conferencing, and identity management.
- Technology Firms:Developer-centric documentation and API specification collaboration.
- Educational Entities:Campus-wide licensing with learning management system integration.
- Manufacturing Corporations:Engineering document control and supplier collaboration portals.
- Telecommunications Providers:Network documentation and customer service knowledge bases.
Financial Institutions anchor premium pricing; Government Agencies extend sales cycles through certification complexity.
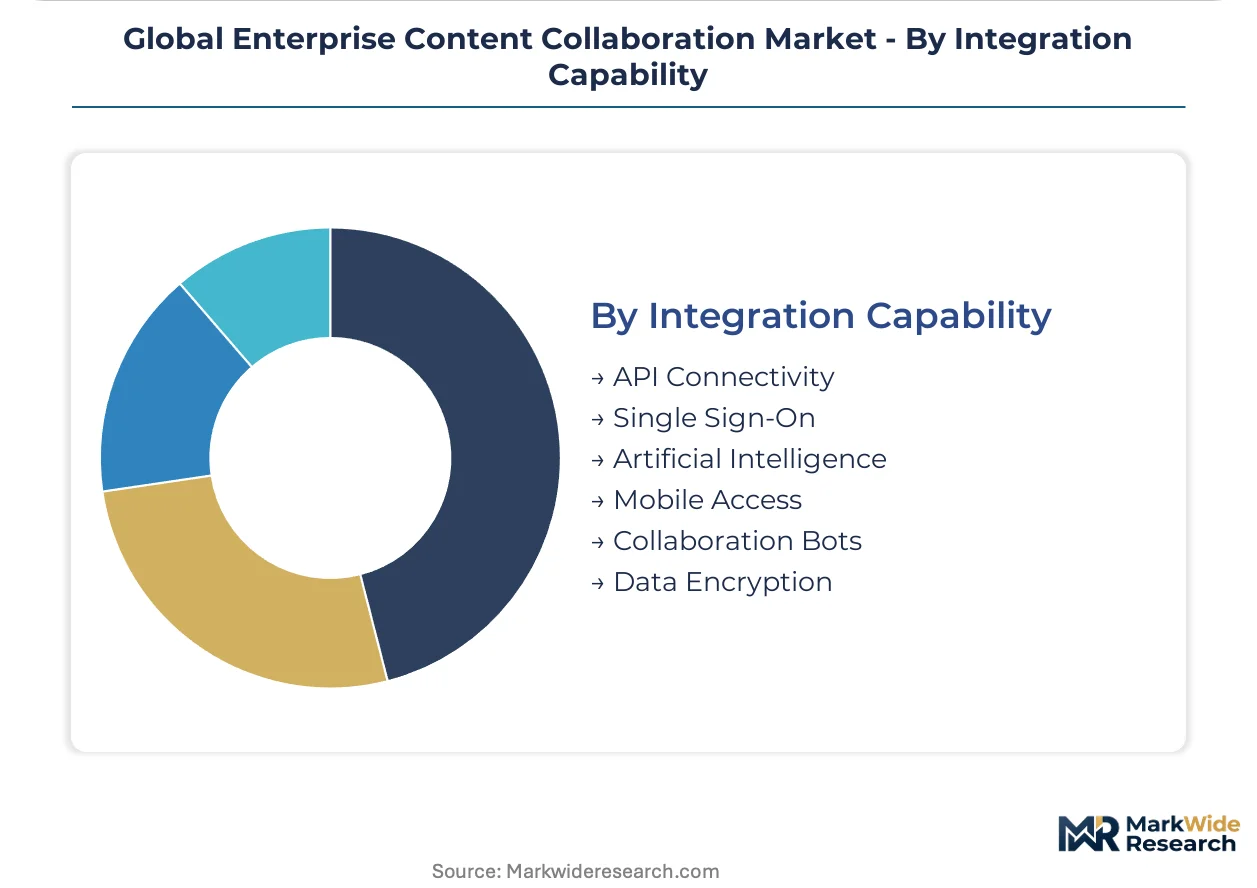
Integration Capability:
Technical connectivity layers determine platform stickiness and ecosystem lock-in.
- API Connectivity:REST and GraphQL endpoints enabling custom workflow orchestration and third-party system bridges. Enterprise IT departments in France and Germany evaluate openness before committing to vendor stacks.
- Artificial Intelligence:Natural language processing for generative drafting, clause extraction, and automated translation. Legal departments at Fortune 500 industrials pilot these tools for M&A due diligence workflows.
- Single Sign-On:SAML and OIDC federation with corporate identity providers.
- Mobile Access:Native iOS and Android applications with offline synchronization.
- Collaboration Bots:Chat-embedded agents surfacing documents and triggering workflows.
- Data Encryption:End-to-end and at-rest protection with customer-managed key options.
API Connectivity underpins ecosystem expansion; Artificial Intelligence commands the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep technical talent pools in Bangalore, Tel Aviv, and the Research Triangle anchor software development for enterprise collaboration platforms. These concentrations feed engineering centers in Seattle, Redmond, and Mountain View. Distributed workforce mandates since 2020 have permanently altered geographic deployment patterns.
United States
Federal contractors and healthcare networks mandate FedRAMP-authorized platforms that bundle document management with identity management. HIPAA security rules impose encryption and access-audit obligations on healthcare-adjacent deployments. The Washington D.C. corridor concentrates government-focused vendors navigating certification complexity.
Germany
Industrial conglomerates in automotive and machinery prioritize on-premises hybrid deployments balancing workforce accessibility with data sovereignty. GDPR enforcement and the EU AI Act's risk-classification framework elevate compliance costs for cross-border data flows. Frankfurt banking clusters compress procurement cycles for real-time co-authoring platforms with immutable audit trails.
United Kingdom
Financial services digitization drives demand for sub-second synchronization in trading floor workflows. Post-Brexit regulatory divergence complicates data transfer mechanisms with EU counterparts. London's fintech corridor anchors premium pricing for enterprise-grade workflow automation.
India
IT services exporters and GCCs (Global Capability Centers) deploy collaboration stacks for distributed delivery teams serving North American and European clients. The Digital Personal Data Protection Act introduces data localization considerations for multinational deployments. Bangalore and Hyderabad concentrate engineering talent building API-native integration layers.
Japan
Manufacturing corporations and keiretsu networks resist cloud migration due to legacy system technical debt and air-gapped requirements. METI guidelines on data sovereignty influence procurement criteria for industrial documentation. Tokyo-Osaka manufacturing corridors maintain hybrid architectures for engineering document control.
Global Enterprise Content Collaboration Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light platform designers for enterprise content collaboration contracts. The market structure concentrates around three tiers: integrated productivity suites, specialized compliance-centric repositories, and developer-centric workflow tools. Strategic archetypes include ecosystem bundlers, vertical specialists, and API-first platform builders. Dominant competitive moves encompass strategic partnerships with systems integrators and portfolio diversification into adjacent communication categories.
Within the ecosystem bundler tier, Microsoft Corporation and Google occupy positions anchoring enterprise-grade workflow automation through productivity suite integration. Box, Inc. exemplifies the vertical specialist archetype targeting regulated industries where data residency certifications dominate procurement criteria. Oracle Corporation sits within the legacy infrastructure tier, representing on-premises-to-cloud migration pathways for industrial conglomerates with technical debt constraints.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| Box, Inc. |
| OpenText Corporation |
| IBM Corporation |
| Cisco Systems, Inc. |
| Atlassian Corporation |
| Slack Technologies, LLC |
| Others |
Supply & Pricing Matrix
GDPR-mandated data residency requirements in Germany and France are forcing hyperscalers to deploy sovereign-hosted infrastructure instances, compressing margins on standardized SaaS tiers while inflating premiums for certified hybrid deployments.
Pricing Analysis
Bundled productivity suites command subscription premiums against unbundled point solutions. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized government stacks from commodity file-sharing. ISO 27001 and SOC 2 Type II certifications drive price differentiation of 40-60 percent above uncertified alternatives. Cost compression in mid-market SaaS is intensifying because Google and Microsoft are cross-subsidizing collaboration tools through adjacent cloud revenue streams. Healthcare networks and federal contractors show lowest price sensitivity due to compliance lock-in, while educational entities and technology startups anchor the economy tier.
Supply Chain Analysis
Certification gating through FedRAMP, ISO 27001, and national sovereign cloud frameworks concentrates vendor qualification cycles in the United States, Germany, and United Kingdom. Infrastructure provisioning draws from hyperscaler data center footprints in Northern Virginia, Frankfurt, and Singapore. API-native integration layers and customer-managed encryption key modules constitute critical component dependencies. Single-source vulnerability sits with Microsoft Azure and AWS hosting dominance for enterprise-grade deployments. Distribution runs through direct vendor-to-CIO relationships that displace systems integrator intermediaries for initial platform selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in enterprise content collaboration rests on compliance-driven premium tier migration and AI-native feature bundling that reduces customer acquisition costs per seat.
For Market Incumbents: Cement ecosystem lock-in by embedding generative AI contract drafting into existing version control workflows before point-solution specialists achieve feature parity. Prioritize FedRAMP High authorization investments to defend against emerging sovereign-cloud vendors in Saudi Arabia and UAE. Deepen API connectivity layers to raise switching costs for manufacturing clients in Germany with legacy ERP tethering. For New Entrants and Emerging Players: The EU AI Act in Germany, France, and Netherlands opens a window for audit-ready collaboration platforms with pre-certified high-risk system classifications. Target underpenetrated sovereign cloud frameworks in Saudi Arabia and UAE requiring Arabic-language workflow support. Lead with compliance documentation automation as the primary go-to-market wedge against incumbent productivity suites. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists holding dual ISO 27001 and national sovereign cloud certifications in regulated industries. Long-term viability favors vendors with demonstrated API-native architecture and recurring integration services revenue rather than pure subscription models. Watch for inflection when EU AI Act enforcement triggers mandatory algorithmic impact assessment procurement clauses.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundles document management with video conferencing and identity management for FedRAMP-authorized government contracts. |
| Acquisition of Specialist Firm | Absorbs vertical-specific compliance expertise in HIPAA or EU AI Act risk classification to accelerate certification timelines. |
| Strategic Partnership | Aligns with systems integrators in Germany to navigate on-premises hybrid deployment complexity for industrial conglomerates. |
| Geographic Expansion | Establishes sovereign-hosted instances in Saudi Arabia and UAE to capture national cloud framework construction demand. |
| Product Launch | Introduces generative AI contract drafting with embedded audit trails for legal departments at Fortune 500 industrials. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners against secondary validation through SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility data, and national sovereign cloud procurement databases. Bottom-up deployment modeling triangulates against top-down IT spending forecasts.
Granularity extends to deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from segment-level growth rate blending across the analysis window. Forecast inputs incorporate EU AI Act implementation timelines, FedRAMP authorization velocity, and manufacturing hybrid cloud adoption curves in Germany.
Revisions become necessary when EU AI Act enforcement intensity, sovereign cloud mandate scope, or hyperscaler pricing cross-subsidy levels materially shift. Forecasts reflect documented assumptions about compliance cost trajectories and AI-native feature adoption curves. A model refresh is warranted upon material change in GDPR enforcement patterns or national data localization legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Europe Managed Services Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Employee Engagement Market
Enterprise Services
IT Staffing Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Global Translation Services Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Qatar Managed Services Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Proactive Services Market
Enterprise Services
Asia Pacific Field Service Management Market