
 Asia-Pacific and US Warehouse Management System Market | 2026-2036
Asia-Pacific and US Warehouse Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific and US Warehouse Management System Market Outlook
Third-party logistics providers across the US Southeast and South Korea's Incheon Free Economic Zone are shifting toward API-first warehouse platforms that synchronize with autonomous mobile robots. Manhattan Associates leverages deep optimization algorithms for multi-node fulfillment networks. SAP SE anchors enterprise deployments through tight ERP integration. Oracle competes on database-native architectures that reduce latency for real-time inventory visibility.
A warehouse management system governs inventory tracking, labor allocation, and order fulfillment workflows within distribution facilities, typically processing SKU-level data through barcode, RFID, or vision-based identification protocols. Cloud-based solutions now attract the fastest upgrade spending as mid-market operators abandon server maintenance overhead. Integrated systems command premium positioning by embedding transportation management and yard planning within unified control towers. By end user, third-party logistics operators represent the most expansionary buyer segment as contract fulfillment volumes multiply across Asia-Pacific trade lanes.
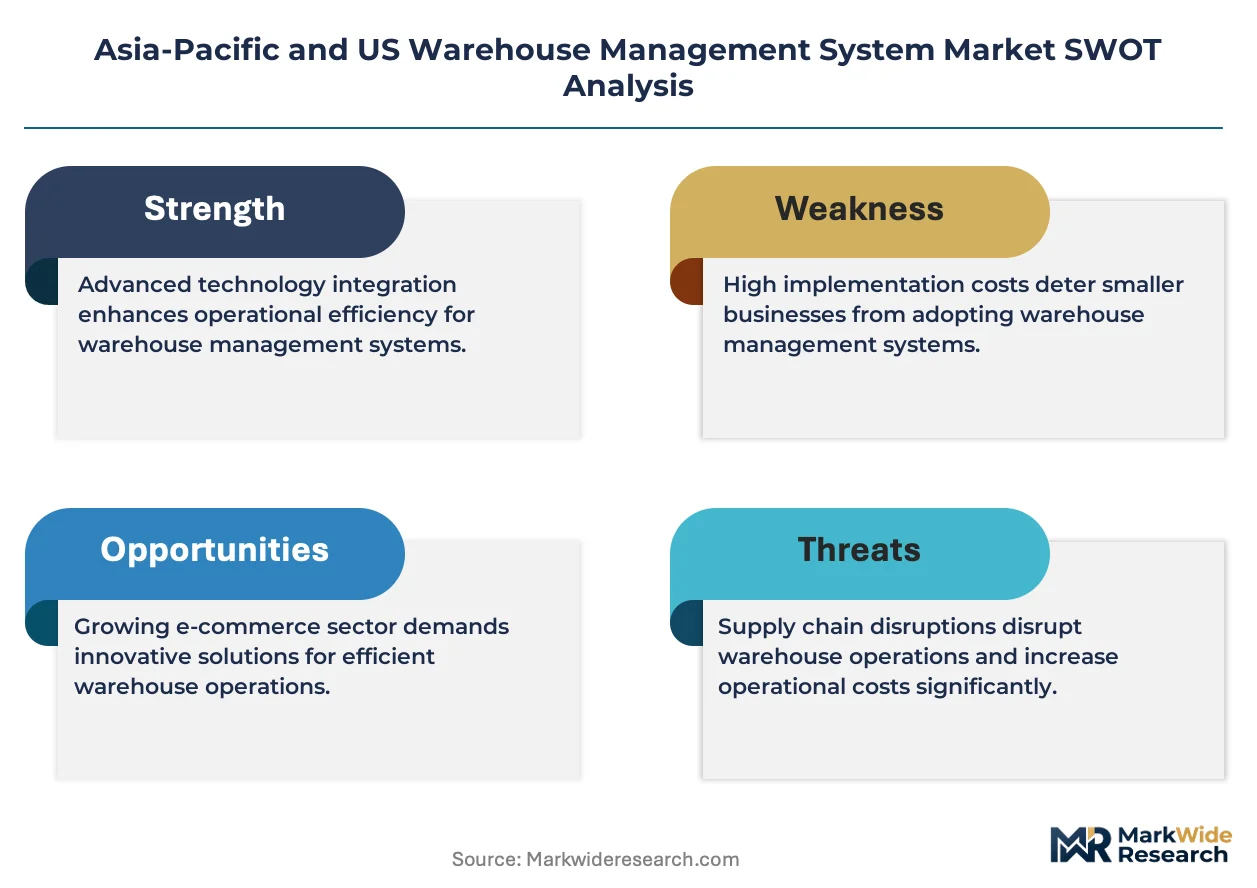
US operators face OSHA warehouse safety standards and FAA drone integration rules that shape automation interface requirements, while India's BIS cloud security guidelines and Japan's METI data governance frameworks constrain cross-border data architectures in multi-national deployments. Stakeholders must evaluate whether hybrid deployment models can satisfy India's data localization mandates without fragmenting operational visibility across regional warehouse networks.
Market Dynamics
Cloud migration mandates from Japan's METI and India's data localization requirements under the Digital Personal Data Protection Act are forcing replacement cycles for legacy on-premises warehouse management installations across the Asia-Pacific and US corridor.
Growth Catalysts
- Multi-channel inventory orchestration:E-commerce fulfillment networks in India and Vietnam are expanding software procurement budgets to synchronize direct-to-consumer, marketplace, and retail distribution flows within unified control towers.
- Warehouse-robotics integration:Distribution clusters in California's Central Valley and India's Gujarat-Maharashtra corridor require synchronized WMS-AMR orchestration layers that coordinate pick-path optimization with real-time robot fleet management.
- API-first platform architectures:Third-party logistics providers across South Korea's Incheon Free Economic Zone and the US Southeast are adopting modular systems that embed transportation management and yard planning within extensible software stacks.
Market Restraints
- Data localization compliance costs:India's Digital Personal Data Protection Act and Japan's METI governance frameworks constrain cross-border data architectures, fragmenting operational visibility for multi-national warehouse operators.
- Legacy system technical debt:Mid-market operators face integration complexity when migrating from server-based inventory tracking systems to cloud-native platforms, delaying upgrade timelines.
- Specialized talent scarcity:Shortages of WMS-robotics integration specialists and cloud infrastructure engineers in Vietnam and India's logistics corridors limit deployment velocity for automation projects.
Strategic Opportunities
- Underpenetrated Vietnamese logistics:E-commerce fulfillment infrastructure in Vietnam remains nascent relative to regional peers, creating first-mover positioning for cloud-native WMS providers serving cross-border trade lanes.
- FAA drone integration pathways:Evolving FAA rules for warehouse inventory drones are opening regulatory-compliant deployment channels for vision-based identification systems in US distribution facilities.
- Edge-to-cloud convergence:Synchronization of barcode, RFID, and computer vision protocols with centralized analytics platforms is expanding into time-sensitive fulfillment operations requiring sub-second latency.
Industry Challenges
- OSHA safety interface complexity:US operators must engineer automation interfaces that satisfy warehouse safety standards while maintaining throughput velocity, complicating AMR deployment specifications.
- Hybrid deployment fragmentation:Multi-national operators struggle to maintain unified operational dashboards when India's data localization mandates require on-premise data residency alongside cloud-based analytics in other jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific and US Warehouse Management System Market |
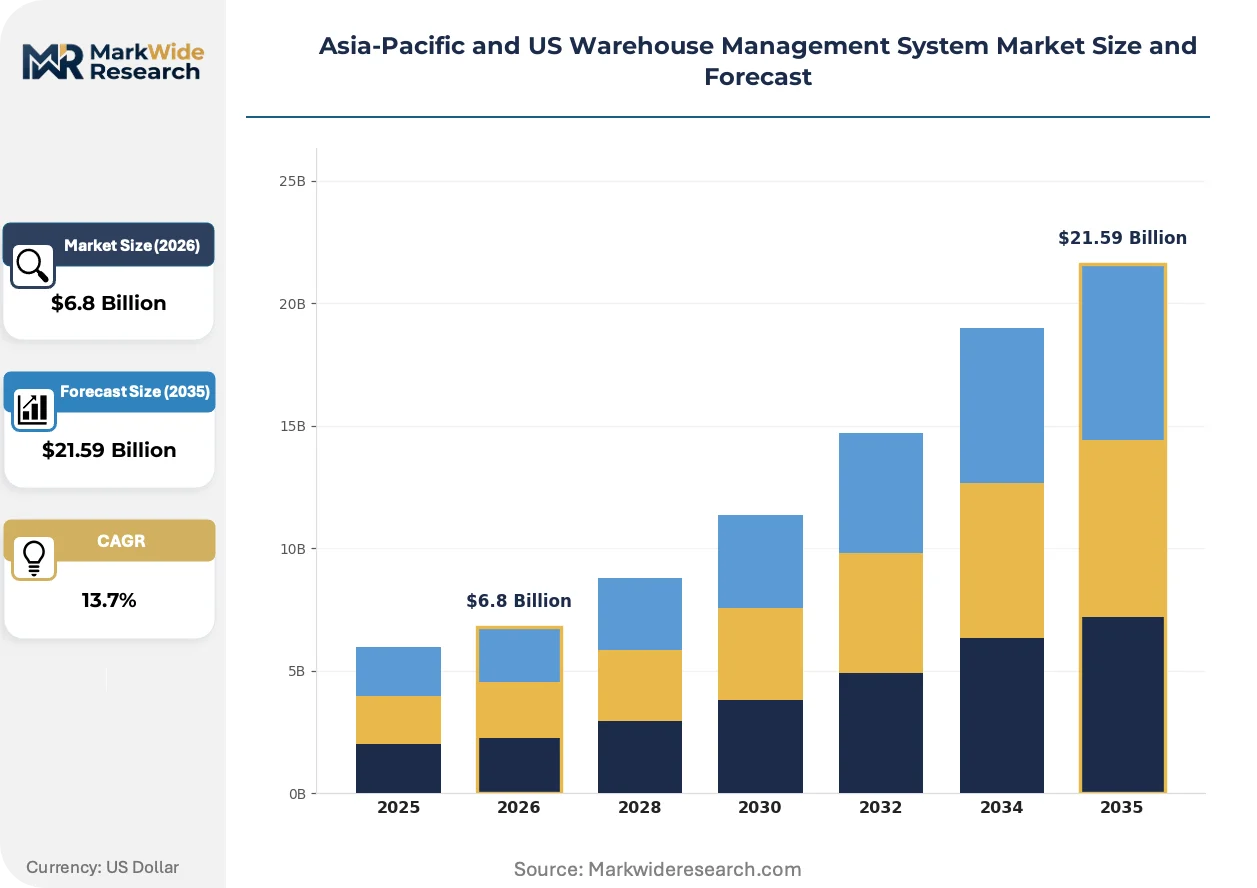
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-based Solutions, Integrated Systems, Mobile Applications End User: Retail, Manufacturing, E-commerce, Third-party Logistics Technology: RFID Solutions, Barcode Scanners, IoT Platforms, Artificial Intelligence Deployment Model: On-premises, Private Cloud, Public Cloud, Hybrid Deployment |
| Companies Covered | Manhattan Associates, SAP SE, Oracle, Blue Yonder Group, Körber AG, Infor, Epicor Software, International Business Machines Corp, Softeon, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific and US Warehouse Management System Market Strategic Shifts
Software architectures are pivoting from monolithic inventory databases toward modular, API-native platforms that embed machine learning optimization directly within fulfillment workflows.
Computer vision-based SKU identification is expanding into high-velocity sortation environments. These systems process package dimensions, damage detection, and label verification through neural network inference at the edge. Third-party logistics operators in California and Gujarat are adopting vision-native receiving workflows that compress dock-to-stock cycle times. The technology is expanding into quality assurance and returns processing functions previously handled through manual inspection.
Japan's METI cloud security guidelines and India's BIS standards are mandating encryption protocols and access controls that exceed baseline ISO certifications. These frameworks require audit trails for inventory data access and automated breach notification systems. US operators serving Asia-Pacific subsidiaries must engineer dual-compliance architectures that satisfy both FAA operational requirements for warehouse drones and Asia-Pacific data residency constraints.
Subscription pricing models are displacing perpetual license structures across mid-market buyer segments. Third-party logistics operators now prefer usage-based contracts that scale with seasonal volume fluctuations rather than fixed-capacity installations. This preference is most visible among US Southeast contract fulfillment providers and South Korean e-commerce enablers, where volume volatility makes capex-heavy software procurement economically unattractive.
Asia-Pacific and US Warehouse Management System Market Segmentation
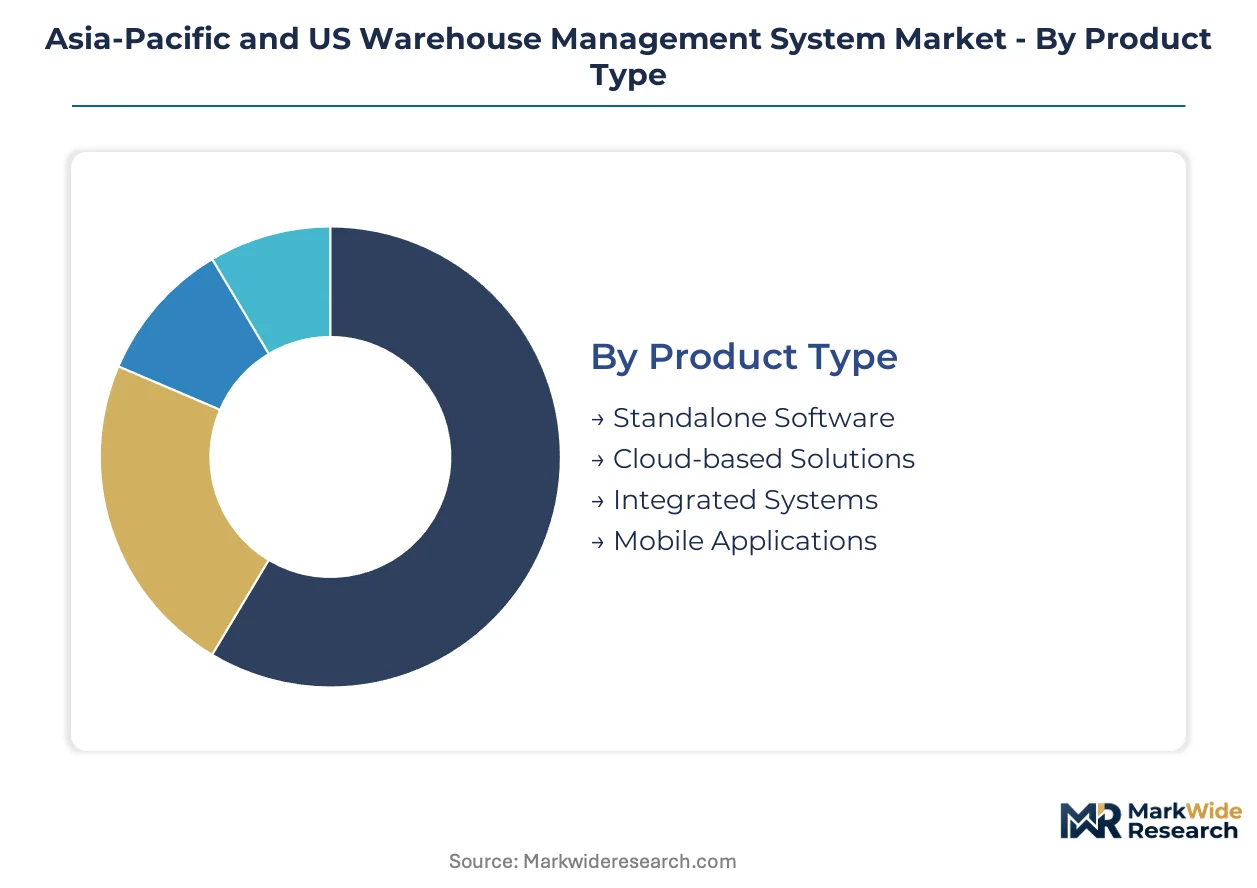
Warehouse management systems fragment across deployment architectures, technology stacks, and buyer sophistication levels. Segmentation reveals where cloud-native platforms displace legacy installations and which integration protocols dominate high-velocity fulfillment corridors.
Product Type:
Customization intensity varies sharply across this spectrum, from configurable cloud suites to rigid standalone modules requiring extensive professional services.
- Cloud-based Solutions:Multi-tenant architectures with API-native integration layers support real-time inventory synchronization across distributed nodes. Demand concentrates among third-party logistics operators in South Korea's Incheon Free Economic Zone and India's Gujarat-Maharashtra corridor, where seasonal volume spikes make usage-based economics essential.
- Integrated Systems:Unified control towers embed transportation management, yard planning, and labor optimization within single vendor stacks. E-commerce fulfillment networks in Vietnam and California's Central Valley prioritize these platforms for multi-channel orchestration complexity.
- Standalone Software:Modular inventory tracking modules serve mid-market operators with limited IT resources.
- Mobile Applications:Task-specific apps for floor supervisors and pick operators extend core platform functionality.
Most installed capacity flows through Integrated Systems. Expansion is steepest in Cloud-based Solutions.
End User:
Buyer sophistication tiers separate enterprise-grade automation requirements from standardized inventory visibility needs.
- Third-party Logistics:Contract fulfillment providers manage multi-client inventory pools with divergent SLA requirements. Operators across the US Southeast and Japan's Kanto logistics belt are expanding procurement for WMS-robotics orchestration layers that coordinate autonomous mobile robot fleets.
- E-commerce:Direct-to-consumer and marketplace sellers require sub-second inventory availability updates across fragmented sales channels. India's BIS cloud security guidelines and Japan's METI data governance frameworks shape platform selection for cross-border operators.
- Retail:Brick-and-mortar networks with omnichannel fulfillment obligations.
- Manufacturing:Plant-attached warehouses synchronizing production schedules with outbound distribution.
Third-party Logistics commands the largest procurement budgets. E-commerce is gaining share fastest.
Technology:
Identification protocol maturity determines integration complexity and edge infrastructure requirements.
- Artificial Intelligence:Machine learning models optimize pick-path sequencing, demand forecasting, and labor allocation in real time. Distribution clusters in California's Central Valley deploy neural network inference at the edge for computer vision-based SKU identification and damage detection.
- IoT Platforms:Sensor networks track environmental conditions, asset location, and equipment health across warehouse footprints. Japan's METI cloud security guidelines mandate encryption protocols exceeding baseline ISO certifications for these connected architectures.
- Barcode Scanners:Laser and imager-based identification remains the workhorse for high-velocity sortation.
- RFID Solutions:Passive and active tag systems enable bulk inventory counts without line-of-sight requirements.
Barcode Scanners anchor current installed base. Artificial Intelligence shows the steepest expansion trajectory.
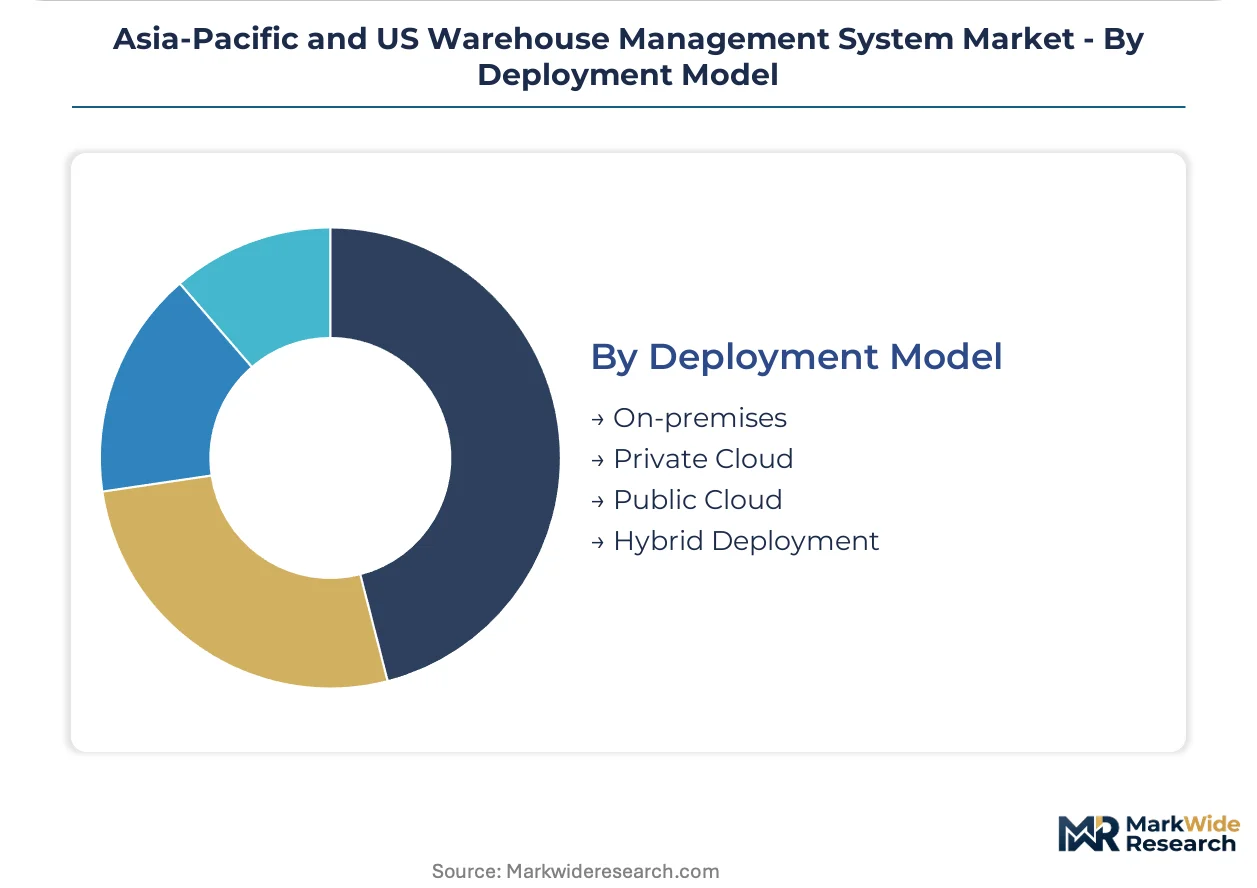
Deployment Model:
Data residency requirements and latency sensitivity create a fragmented migration pathway across buyer segments.
- Hybrid Deployment:Architectures split transactional processing between on-premise data residency and cloud-based analytics. Multi-national operators favor this model to satisfy India's Digital Personal Data Protection Act localization mandates without sacrificing centralized operational visibility.
- Public Cloud:Multi-tenant SaaS platforms with automatic scaling and zero infrastructure maintenance. Mid-market operators in Vietnam's nascent e-commerce corridor prefer these solutions to avoid server overhead.
- Private Cloud:Single-tenant dedicated instances for enterprises with stringent security requirements.
- On-premises:Legacy server-based installations facing replacement cycles driven by Japan's METI cloud migration mandates.
On-premises retains significant legacy footprint. Hybrid Deployment is climbing the fastest as compliance complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's logistics software procurement outpaces Vietnam's nascent fulfillment infrastructure, though both markets face similar cloud migration pressures from national data governance frameworks. Japan and South Korea anchor mature automation ecosystems where WMS-robotics integration commands premium investment. California's distribution density contrasts with the fragmented warehouse networks across Southeast Asian trade corridors.
United States
Third-party logistics operators across the US Southeast prioritize API-first platforms that synchronize with autonomous mobile robot fleets. FAA drone integration rules shape automation interface requirements for vision-based inventory systems. California's Central Valley distribution cluster drives demand for WMS-AMR orchestration layers that coordinate real-time robot fleet management with pick-path optimization.
India
E-commerce fulfillment networks in the Gujarat-Maharashtra logistics corridor are expanding software procurement budgets for multi-channel inventory orchestration. The Digital Personal Data Protection Act mandates data localization, forcing hybrid deployment architectures that split transactional processing between on-premise residency and cloud analytics. Mid-market operators face integration complexity when migrating from server-based systems to cloud-native platforms.
Japan
METI cloud security guidelines and cloud migration mandates accelerate replacement cycles for legacy on-premises warehouse management installations. The Kanto logistics belt concentrates demand for WMS-robotics orchestration layers among contract fulfillment providers. Encryption protocols and access controls exceed baseline ISO certifications, requiring audit trails for inventory data access.
South Korea
Third-party logistics providers in the Incheon Free Economic Zone adopt modular systems that embed transportation management and yard planning within extensible software stacks. Cloud-native platforms attract upgrade spending as operators abandon server maintenance overhead. The Seoul Capital Area anchors enterprise deployments through tight ERP integration requirements.
Vietnam
E-commerce fulfillment infrastructure remains underpenetrated relative to regional peers, creating first-mover positioning for cloud-native WMS providers. Specialized talent scarcity limits deployment velocity for automation projects. Cross-border trade lanes through Ho Chi Minh City and Hanoi drive demand for subscription pricing models that scale with seasonal volume fluctuations.
Asia-Pacific and US Warehouse Management System Market Competitive Environment
US-based software vendors anchor the enterprise tier; German and Japanese specialists hold positions in robotics-integrated fulfillment systems. The vendor base concentrates around three strategic archetypes: ERP-anchored suites with deep integration capabilities, best-of-breed optimization platforms, and cloud-native challengers with API-first architectures. Dominant competitive moves include strategic partnerships between WMS providers and autonomous mobile robot manufacturers, plus geographic expansion into underpenetrated Southeast Asian logistics corridors.
Within the ERP-anchored tier, SAP SE and Oracle exemplify database-native architectures that reduce latency for real-time inventory visibility. Manhattan Associates occupies a position among optimization specialists, leveraging deep algorithms for multi-node fulfillment networks. These three represent distinct competitive postures: SAP SE and Oracle anchor enterprise deployments through integration breadth, while Manhattan Associates exemplifies best-of-breed positioning for complex distribution networks.
| Leading Market Players |
|---|
| Manhattan Associates |
| SAP SE |
| Oracle |
| Blue Yonder Group |
| Körber AG |
| Infor |
| Epicor Software |
| International Business Machines Corp |
| Softeon |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure costs cascade through WMS vendor pricing tiers, with multi-tenant SaaS platforms absorbing hyperscaler rate fluctuations while on-premise deployments pass server maintenance overhead directly to India's Gujarat-Maharashtra logistics operators and California's Central Valley distribution clusters.
Pricing Analysis
Distributor margins compress as subscription pricing displaces perpetual licenses across mid-market third-party logistics providers. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity, with API-native platforms commanding premium positioning against standalone modules. Pricing pressure stems from usage-based contract demands in Vietnam's nascent e-commerce corridor, where seasonal volume volatility makes fixed-capacity procurement economically unattractive. Third-party logistics operators in South Korea's Incheon Free Economic Zone exhibit highest price sensitivity; enterprise manufacturers with ERP-anchored requirements show lowest.
Supply Chain Analysis
ISO 27001 and BIS cloud security certifications gate vendor participation in India's public sector procurement and Japan's METI-mandated migrations. Software development concentrates in the United States, India, and Germany, with implementation services drawing from Vietnam and South Korea's specialized talent pools. Component dependencies span hyperscaler compute instances, edge inference hardware for vision systems, and robotics middleware protocols. Single-source vulnerability sits with AWS and Azure dominance in multi-tenant architectures. Distribution runs through direct enterprise sales teams for integrated suites and channel partners for mid-market cloud solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific and US Warehouse Management System Market compounds steadily as e-commerce fulfillment volumes multiply across regional trade lanes, embedding recurring revenue visibility into vendor cash flows.
For Market Incumbents: Lock in multi-year subscription contracts with India's third-party logistics operators before data localization compliance costs escalate. Deepen robotics integration capabilities through captive development or specialist acquisition to defend against cloud-native challengers with API-first architectures. Prioritize hybrid deployment engineering to satisfy Japan's METI mandates without fragmenting operational visibility.
For New Entrants and Emerging Players: Capture underpenetrated Vietnamese e-commerce fulfillment infrastructure where first-mover positioning remains available for cloud-native WMS providers. Target mid-market operators abandoning server maintenance overhead in South Korea's Incheon Free Economic Zone. Lead with usage-based pricing models that scale with seasonal volume fluctuations, bypassing capex-heavy competitive procurement cycles.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized WMS-robotics integration talent scarcity limits deployment velocity for automation projects. Long-term viability favors vendors with hybrid deployment architectures spanning India's data residency requirements and cloud analytics in other jurisdictions. Target acquisition profiles emphasize API-native platforms with embedded transportation management. Monitor FAA drone integration rule finalization as inflection signal for vision-based inventory system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified control towers embedding transportation management and yard planning command premium positioning in California's Central Valley. |
| Strategic Partnership | WMS-AMR orchestration layer development with autonomous mobile robot manufacturers accelerates deployment in Japan's Kanto logistics belt. |
| Geographic Expansion | First-mover entry into Vietnam's nascent e-commerce fulfillment infrastructure captures cross-border trade lane growth. |
| Acquisition of Specialist Firm | Computer vision-native receiving workflow capabilities compress dock-to-stock cycle times for Gujarat-Maharashtra operators. |
| Product Launch | Edge-to-cloud convergence platforms address sub-second latency requirements in time-sensitive US Southeast fulfillment operations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with WMS vendor product managers, third-party logistics procurement directors, cloud infrastructure engineers, and robotics integration specialists with secondary validation against SEC filings, hyperscaler capex disclosures, customs records for logistics equipment imports, and Japan METI cloud migration policy documents. Bottom-up deployment counts across India's Gujarat-Maharashtra corridor and California's Central Valley distribution clusters triangulated against top-down vendor revenue estimates.
Historical reference periods anchored growth rate derivations across the projection horizon, with segmentation modeling spanning deployment architecture, end-user sophistication tier, identification protocol maturity, and regional regulatory cluster. CAGRs emerged from curve-fitting across disclosed vendor growth rates and logistics automation investment surveys. Forecast inputs incorporated FAA drone integration rule evolution timelines and India's Digital Personal Data Protection Act implementation phases.
Regulatory enforcement variance, hyperscaler pricing volatility, and robotics talent availability are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding compliance timeline adherence and cloud migration acceleration curves. A model refresh is warranted upon material change in India BIS cloud security certification requirements or Japan METI mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Enterprise Collaboration Service Market
Enterprise Services
United States Customer Technical Support Services Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market