
 Enterprise Social Graph Market | 2026-2036
Enterprise Social Graph Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Social Graph Market Analysis
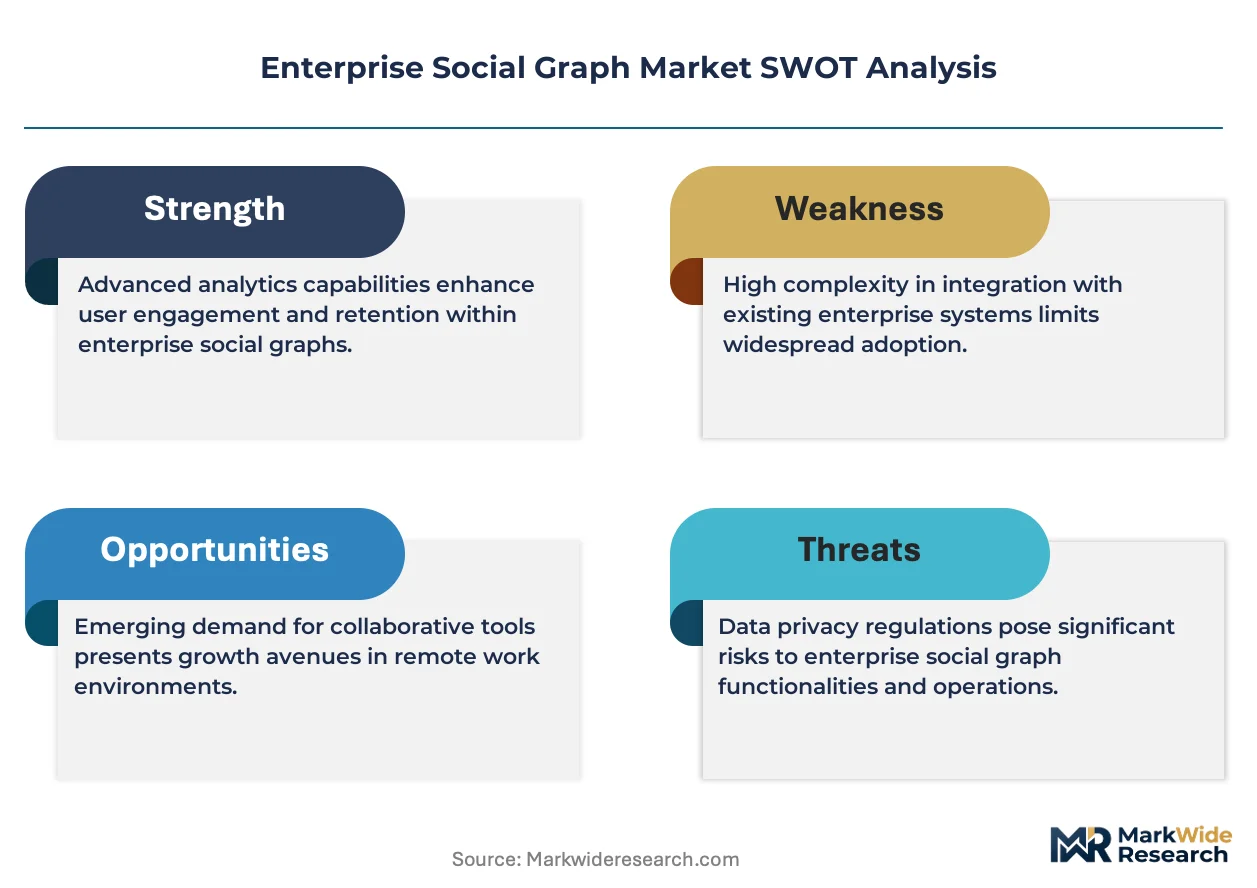
Fragmentation across new buyer segments is repositioning how vendors allocate sales resources, as mid-market professional services firms and healthcare systems join legacy Fortune 500 accounts in adopting enterprise social graph platforms. Microsoft Corporation leverages its Teams ecosystem to embed relationship intelligence directly into daily collaboration workflows. Salesforce.com, Inc. anchors its offering in CRM data gravity, connecting customer-facing interactions with internal expertise networks. SAP SE specializes in operationalizing knowledge graphs for supply-chain and procurement team alignment across multinational manufacturing footprints.
An enterprise social graph maps relational, interaction, and expertise data across an organization's personnel, systems, and content repositories, typically employing graph database architectures with node-edge property models to enable traversal queries across millions of connected entities. Its primary commercial purpose is surfacing hidden expertise, accelerating cross-functional collaboration, and exposing influence patterns that static organizational charts obscure. Cloud-based deployment leads adoption among organizations prioritizing elastic compute for large-scale graph analytics, while on-premises configurations persist in defense and intelligence sectors with strict data sovereignty requirements. Data analytics functionality captures expanding margin pools as buyers shift from basic social networking features toward predictive relationship intelligence and automated insight generation.
The EU AI Act imposes conformity assessments on automated decision systems that profile employee behavior or infer performance attributes from communication patterns, directly shaping product roadmaps for European deployments. The SEC's intensifying scrutiny of insider communication networks in financial services is driving demand for relationship-mapping tools with immutable audit trails and real-time anomaly detection. HIPAA constrains how healthcare systems deploy social graph analytics across clinical and administrative staff boundaries, requiring granular access control architectures. Stakeholders must weigh the speed of cloud-native feature development against the contractual and jurisdictional complexity of hosting employee relationship data across fragmented regulatory environments.
Market Dynamics
Algorithmic transparency mandates from the EU AI Act and GDPR are compressing product development cycles as vendors rearchitect graph analytics engines for explainable inference pathways across employee communication networks.
Growth Catalysts
- GDPR Article 22 Compliance:Financial services institutions in Germany deploy relationship-mapping platforms to demonstrate human oversight in automated profiling decisions, accelerating procurement of audit-ready graph systems.
- Remote Engineering Collaboration:Industrial conglomerates with dispersed R&D footprints use expertise-location algorithms to reduce knowledge-search latency across multinational project teams.
- Graph Neural Networks:Advances in GNN architectures enable real-time inference across billion-node enterprise graphs, expanding addressable use cases from static reporting to predictive relationship intelligence.
Market Restraints
- Data Sovereignty Fragmentation:Defense and intelligence sectors in France and Germany mandate on-premises deployment, constraining vendor margin structures against cloud-native competitors.
- HIPAA Boundary Enforcement:US healthcare systems face structural barriers deploying cross-functional graph analytics where clinical and administrative data domains require physically separated access architectures.
- Legacy ERP Integration Tax:SAP and Oracle system environments impose custom API development costs that extend implementation timelines by 8-14 months for mid-market buyers.
Strategic Opportunities
- CSRD Mandate Alignment:The EU Corporate Sustainability Reporting Directive creates demand for knowledge-graph platforms that map expertise networks against decarbonization project delivery timelines.
- Mid-Market Professional Services:Accounting and legal partnerships in Spain and Italy remain underpenetrated, lacking dedicated vendor sales coverage compared to Fortune 500 accounts.
- Federated Graph Architectures:Convergence of differential privacy with graph analytics enables cross-organizational collaboration networks without centralizing sensitive relationship data.
Industry Challenges
- Graph Data Science Talent Scarcity:Vendors compete for practitioners with combined expertise in Neo4j or TigerGraph administration and organizational network analysis methodology.
- Multi-Jurisdictional Compliance Engineering:Product teams must maintain parallel feature branches to satisfy simultaneous GDPR, SEC record-keeping, and sector-specific confidentiality requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Social Graph Market |
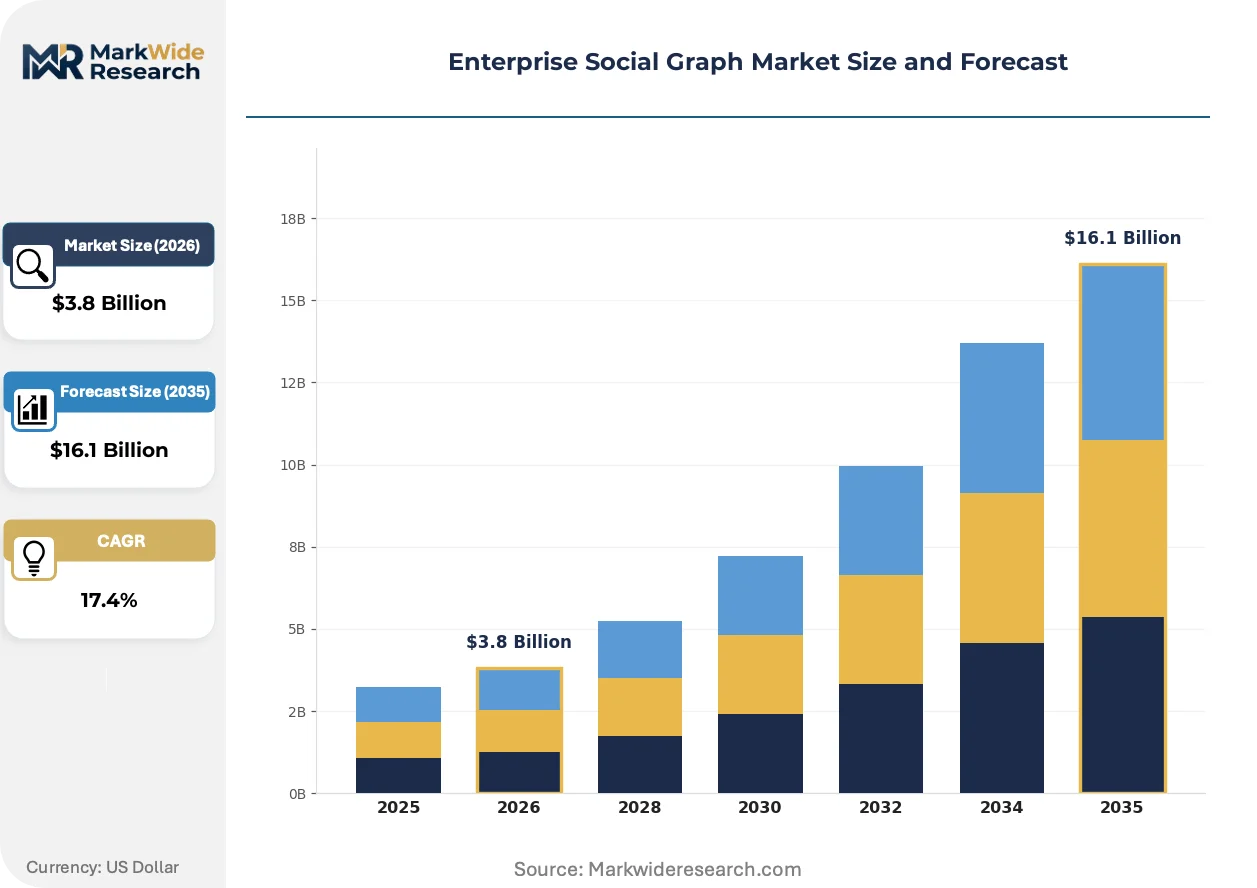
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.1 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Social Networking, Collaboration Tools, Data Analytics, Knowledge Management End User: Corporate Teams, HR Departments, IT Professionals, Marketing Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Functionality: User Engagement, Relationship Mapping, Insights Generation, Access Control |
| Companies Covered | Oracle Corporation, Google LLC, Microsoft Corporation, Lithium Technologies Inc., Sprinklr Inc., IBM Corporation, SAP SE, Cisco Systems, Inc., Salesforce.com, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Social Graph Market Emerging Trajectories
Explainable AI architectures are reshaping competitive positioning as buyers demand interpretable relationship inferences rather than black-box influence scores. Vendors now embed provenance tracing and counterfactual explanation modules directly into graph query engines.
Vector embeddings for semantic relationship search is overtaking keyword-based expertise retrieval in enterprise knowledge graphs. Automotive suppliers in Stuttgart and Munich adopt these systems to surface engineering competencies across 50,000-plus employee bases. The technology compresses vendor differentiation around raw graph scale toward inference quality and explanation fidelity.
The EU AI Act's conformity assessment framework for employee profiling systems imposes documentation burdens that favor established vendors with dedicated regulatory affairs functions. High-risk system classifications trigger third-party audit requirements before market deployment. Financial services buyers in Frankfurt and Paris now mandate pre-contractual evidence of completed conformity procedures.
Subscription-based pricing for relationship intelligence modules displaces perpetual licensing in mid-market professional services segments. Channel partners in Milan and Barcelona bundle graph analytics with managed IT services rather than standalone software sales. The shift concentrates margin capture in vendor-direct enterprise accounts while expanding volume through service-provider intermediation.
Enterprise Social Graph Market Segmentation
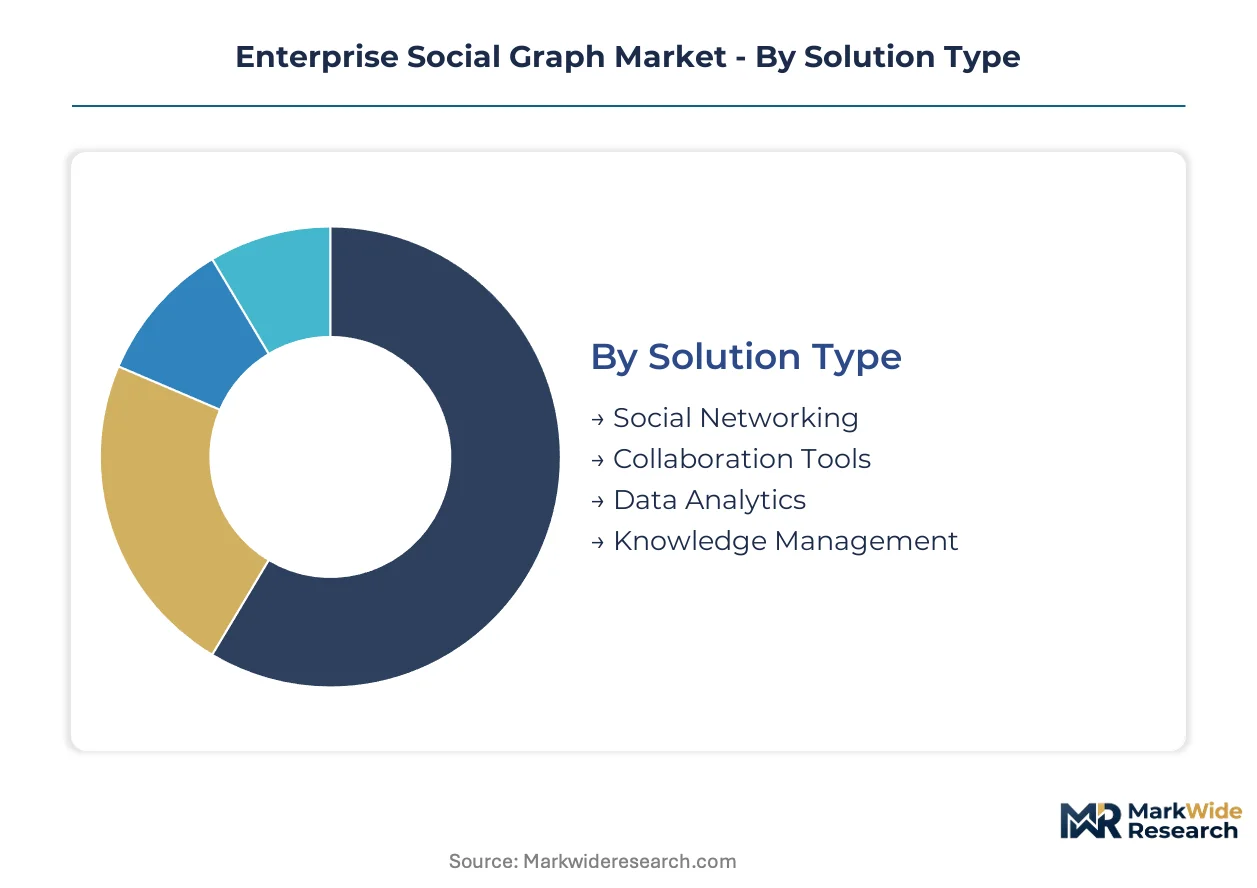
Segmentation in the enterprise social graph market reveals how compliance burdens, data sovereignty requirements, and functional sophistication divide procurement patterns across buyer types. Vendors must architect parallel product tracks to serve defense-grade on-premises deployments alongside elastic cloud-native configurations without fragmenting engineering resources.
Solution Type:
GDPR Article 22 and the EU AI Act impose divergent conformity assessment obligations across solution types, with automated profiling modules facing high-risk system classifications that trigger third-party audit mandates before market deployment.
- Data Analytics:Graph neural network architectures enable real-time inference across billion-node enterprise datasets, converting static relationship reporting into predictive intelligence. Financial services institutions in Frankfurt deploy these systems to satisfy SEC record-keeping requirements for immutable audit trails on insider communication networks.
- Knowledge Management:Vector embedding technologies power semantic expertise retrieval across dispersed engineering populations, replacing keyword-based search with contextual competency matching. Industrial conglomerates in Stuttgart adopt these platforms to reduce knowledge-search latency across multinational R&D footprints spanning Germany, Austria, and Switzerland.
- Social Networking:Basic connectivity features face commoditization pressure as buyers migrate toward inference-rich modules.
- Collaboration Tools:Teams-embedded and Slack-integrated deployments dominate mid-market professional services procurement in Spain and Italy.
Leading the category by volume: Data Analytics. Expanding most quickly: Knowledge Management.
End User:
Procurement authority concentrates in functions with direct regulatory exposure, where relationship-mapping investments defend against enforcement action or accelerate compliance demonstration.
- HR Departments:Employee profiling and performance inference systems fall under EU AI Act high-risk classifications, requiring explainable AI architectures with provenance tracing and human oversight documentation. German automotive suppliers invest heavily here to demonstrate GDPR-compliant automated decision processes.
- IT Professionals:Graph database administration and access control architecture design demand scarce practitioners combining Neo4j or TigerGraph expertise with organizational network analysis methodology. Cloud deployment decisions in this segment determine vendor margin structures through infrastructure commitment scale.
- Corporate Teams:Cross-functional collaboration use cases drive mid-market adoption in accounting and legal partnerships.
- Marketing Agencies:Customer-facing relationship intelligence applications connect external interaction data with internal expertise networks.
Dominating procurement volume: HR Departments. Gaining share fastest: IT Professionals.
Deployment:
Margin structures diverge sharply between elastic cloud configurations and sovereign-hosting mandates, with defense and intelligence sectors constraining vendor profitability through fixed-cost infrastructure requirements.
- Cloud-Based:Elastic compute provisioning enables large-scale graph analytics without capital infrastructure commitment, attracting mid-market buyers prioritizing feature velocity over data sovereignty. Channel partners in Milan and Barcelona bundle these deployments with managed IT services, expanding volume through service-provider intermediation.
- On-Premises:Physically isolated hosting satisfies French and German defense sector mandates for data sovereignty, extending implementation timelines and compressing vendor margins against cloud-native competitors. Immutable audit trail requirements from SEC scrutiny of insider networks reinforce persistence in financial services.
- Hybrid:Split architectures accommodate HIPAA boundary enforcement in US healthcare systems separating clinical and administrative data domains.
- Mobile:Field-accessible relationship intelligence supports distributed professional services teams in underpenetrated Spanish and Italian markets.
Capturing largest deployment share: Cloud-Based. Steepest expansion trajectory: Hybrid.
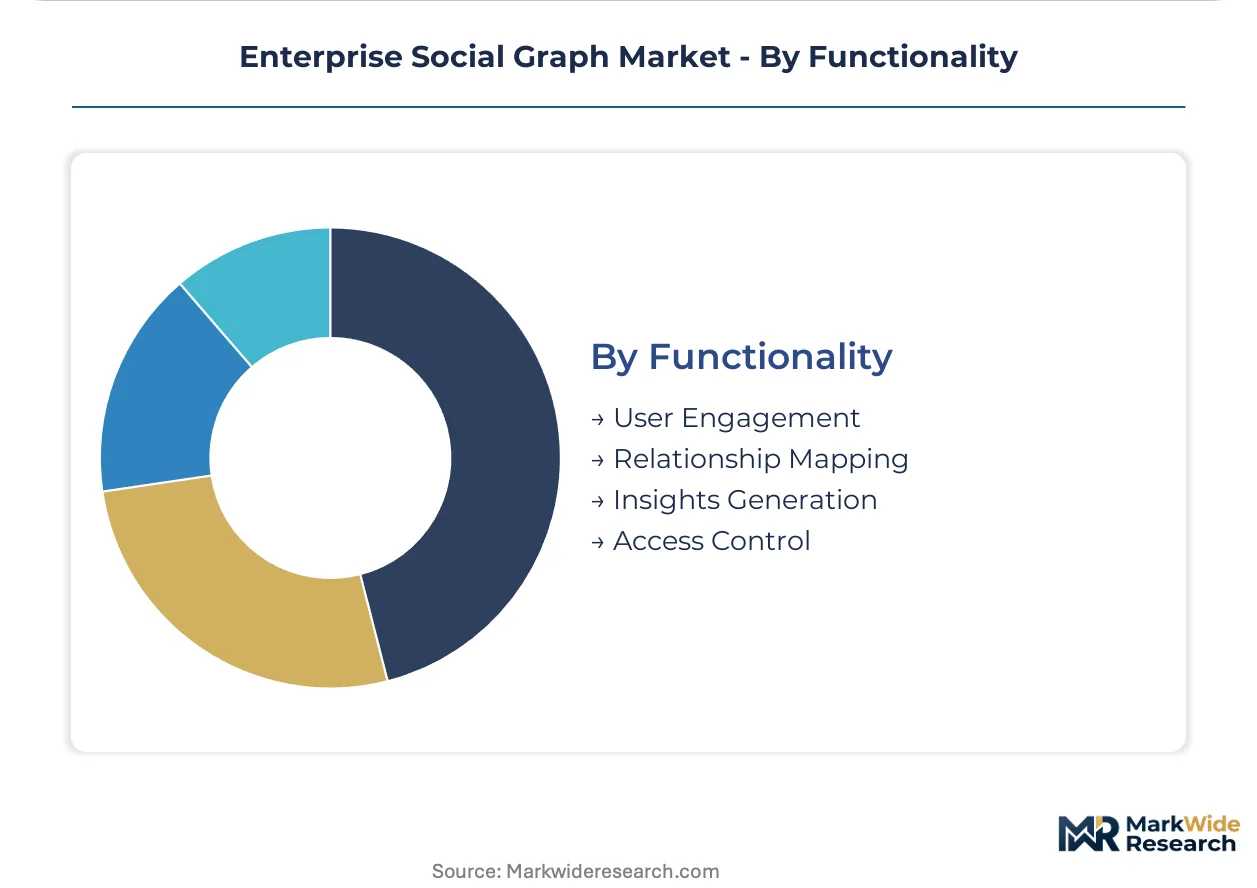
Functionality:
Pricing power concentrates in modules generating automated insight rather than passive connectivity, as buyers shift procurement criteria from user engagement metrics toward predictive relationship intelligence.
- Insights Generation:Counterfactual explanation modules and provenance tracing satisfy EU AI Act algorithmic transparency mandates, converting regulatory burden into vendor differentiation. Financial services buyers in Paris and Frankfurt now mandate pre-contractual evidence of completed conformity procedures.
- Relationship Mapping:Influence network visualization exposes hidden expertise and communication patterns obscured by static organizational charts. The EU Corporate Sustainability Reporting Directive creates demand for mapping expertise networks against decarbonization project delivery timelines.
- User Engagement:Basic activity metrics face displacement by inference-rich functionality in procurement evaluations.
- Access Control:Granular permission architectures enable HIPAA-compliant deployment across healthcare system boundaries.
Commanding highest pricing tier: Insights Generation. Climbing the fastest: Relationship Mapping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise social graph procurement concentrates in economies with dense regulatory complexity and dispersed engineering workforces. Germany, the United States, France, the United Kingdom, and Japan account for the dominant share of relationship-mapping platform deployment.
Germany
Industrial conglomerates in Stuttgart and Munich drive expertise-location platform adoption to reduce knowledge-search latency across multinational R&D teams. The EU AI Act and GDPR Article 22 impose conformity assessment obligations on automated employee profiling systems. Automotive suppliers in Baden-Württemberg invest heavily in explainable AI architectures to demonstrate human oversight in algorithmic decisions.
United States
Financial services institutions deploy relationship-mapping tools to satisfy SEC record-keeping requirements for insider communication networks. HIPAA constrains cross-functional graph analytics in healthcare systems requiring physically separated clinical and administrative data domains. Mid-market professional services firms in New York and Chicago accelerate adoption of Teams-embedded collaboration intelligence.
France
Defense and intelligence sectors mandate on-premises deployment for data sovereignty, extending implementation timelines and compressing vendor margins. The CNIL enforces strict algorithmic transparency requirements under GDPR for employee monitoring systems. Paris-based financial services buyers now mandate pre-contractual evidence of completed EU AI Act conformity procedures.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance engineering burdens for vendors maintaining EU and UK product branches. The Information Commissioner's Office scrutinizes automated decision systems profiling employee behavior. London's professional services sector drives subscription-based pricing for relationship intelligence modules.
Japan
Manufacturing conglomerates with dispersed Asian operations adopt knowledge graphs to map expertise across regional engineering centers. METI guidelines on AI governance shape procurement criteria for explainable inference systems. Tokyo-based IT departments prioritize elastic cloud configurations for large-scale graph analytics.
Enterprise Social Graph Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue federated graph architectures and differential privacy modules. The vendor base spans three maturity tiers: cloud-native specialists, legacy enterprise software incumbents, and vertical-focused mid-market players. Strategic archetypes include collaboration-platform embedders, CRM-anchored relationship intelligence providers, and standalone graph database vendors. Dominant competitive moves include strategic partnerships with channel intermediaries and portfolio diversification into explainable AI modules.
Within the cloud-platform tier, Microsoft Corporation exemplifies collaboration-embedded relationship intelligence through its Teams ecosystem integration. Salesforce.com, Inc. occupies a position connecting customer-facing interaction data with internal expertise networks. SAP SE represents the operational knowledge graph archetype for supply-chain and procurement alignment across multinational manufacturing footprints.
| Leading Market Players |
|---|
| Oracle Corporation |
| Google LLC |
| Microsoft Corporation |
| Lithium Technologies Inc. |
| Sprinklr Inc. |
| IBM Corporation |
| SAP SE |
| Cisco Systems, Inc. |
| Salesforce.com, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between explainable AI-enabled platforms and basic relationship-mapping tools manifests in both procurement premiums and supply chain sourcing strategies. Vendors with completed EU AI Act conformity assessments command pricing power in Frankfurt and Paris financial services sectors, while commodity social networking modules face margin compression from cloud-native competitors.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers for mid-market professional services, while margin pools accrue to on-premises deployments with immutable audit trail capabilities for defense and intelligence buyers. Price differentiation stems from GDPR Article 22 compliance documentation and graph neural network inference quality. Cost compression in basic collaboration modules is intensifying because Microsoft Teams and Slack embed native relationship intelligence. Mid-market accounting and legal partnerships in Milan and Barcelona exhibit highest price sensitivity; German automotive suppliers demonstrate lowest sensitivity given regulatory defense requirements.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from Fortune 500 financial services and industrial conglomerates, while managed service providers in Southern Europe intermediate mid-market procurement. Engineering talent concentrates in Germany, the United States, and the United Kingdom. Graph database infrastructure draws from cloud hyperscaler regions in Ireland, Frankfurt, and Virginia. Single-source vulnerability sits with Neo4j and TigerGraph specialist practitioners. Distribution runs through channel partners bundling analytics with IT services in underpenetrated Spanish and Italian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where control over graph neural network inference engines and explainable AI documentation capabilities determines pricing power. Incumbents and challengers alike must secure upstream talent pipelines and downstream channel access.
For Market Incumbents: To counter cloud-platform embedders like Microsoft and Salesforce, deepen proprietary graph database optimization and secure exclusive partnerships with channel intermediaries in Milan and Barcelona. Invest in dedicated regulatory affairs functions to accelerate EU AI Act conformity assessments ahead of mid-market competitors. Control over explainable AI documentation capabilities anchors enterprise retention in Frankfurt and Paris financial services sectors.
For New Entrants and Emerging Players: Cloud-native federated graph architectures with differential privacy modules offer the most penetrable wedge into defense and intelligence sectors constrained by data sovereignty mandates. Target underpenetrated mid-market professional services in Spain and Italy with subscription-based relationship intelligence bundled through managed IT service providers. Position around cross-organizational collaboration networks without centralizing sensitive relationship data.
For Investors and Strategic Acquirers: Re-rating potential sits with vendors combining graph neural network expertise with completed EU AI Act conformity documentation given regulatory enforcement acceleration. Long-term viability over the next decade hinges on explainable AI architecture differentiation rather than raw graph scale. Watch for inflection signals in pre-contractual conformity evidence requirements from Paris and Frankfurt financial services procurement committees.
| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Module Development | EU AI Act high-risk system classifications mandate provenance tracing and counterfactual explanations for employee profiling platforms. |
| Federated Graph Architecture Launch | Differential privacy enables cross-organizational collaboration without centralizing sensitive relationship data across GDPR jurisdictions. |
| Regulatory Affairs Function Buildout | Dedicated compliance teams accelerate conformity assessment completion ahead of third-party audit mandates in European deployments. |
| Channel Partner Network Expansion | Managed service intermediaries in Milan and Barcelona capture mid-market volume unreachable through vendor-direct enterprise sales. |
| Graph Neural Network Talent Acquisition | Practitioners combining Neo4j administration with organizational network analysis methodology remain scarce and defensible. |
Methodological Framework
Independent corroboration across primary interviews with CTOs, IT procurement officers, graph database engineers, and channel partners, combined with secondary validation through SEC filings, hyperscaler capex disclosures, EU regulatory documentation, and clinical procurement databases, underwrites the qualitative findings. Bottom-up triangulation across deployment models, organization sizes, vertical segments, and regional adoption patterns converges with top-down market sizing from vendor revenue disclosures and channel partner volume estimates.
Comparable-period anchoring to historical cloud software adoption curves and enterprise knowledge management deployment timelines structured the forecast window across the projection horizon. Segmentation dimensions modeled include solution type, end-user function, deployment architecture, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted adoption curves and compliance-driven procurement acceleration in financial services and defense sectors. Forecast inputs incorporate graph neural network inference latency improvements and EU AI Act enforcement trajectory assumptions.
The model holds under sustained regulatory enforcement intensity and cloud infrastructure cost curves; deviation in GDPR interpretation strictness or hyperscaler pricing would shift deployment architecture preferences. Forecasts reflect documented assumptions regarding compliance timeline acceleration and mid-market channel maturation. Periodic stress-testing of base assumptions is recommended given multi-jurisdictional regulatory evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
IT Staffing Market
Enterprise Services
Digital Mailroom Services Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Shared Services Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Network Outsourcing Market