
 North America Contingent Workforce Management Market | 2026-2036
North America Contingent Workforce Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Contingent Workforce Management Market Insights
The direct sourcing channel is rewriting how enterprises engage non-permanent talent across North America. SAP SE leverages its embedded HR software ecosystem to anchor contingent labor modules within existing enterprise resource planning workflows. Workday, Inc. competes through native workforce planning tools that unify permanent and temporary headcount analytics on a single architecture. ADP, LLC sustains payroll-centric dominance by extending tax compliance and benefits administration across 1099 and W-2 worker classifications simultaneously.
Contingent workforce management encompasses the strategic procurement, onboarding, compliance oversight, and offboarding of non-permanent labor including independent contractors, temporary staff, and statement-of-work consultants, typically orchestrated through vendor management systems or managed service providers with automated time-collection and regulatory classification engines. Its primary commercial purpose is to reduce fixed labor costs while maintaining operational flexibility against demand volatility. Cloud-based technology deployments now lead structural investment as enterprises abandon legacy on-premise installations that require dedicated IT maintenance for worker classification updates. AI-driven platforms represent the fastest-growing technology segment, embedding predictive analytics for skills matching and automated compliance screening that reduces misclassification exposure. The staffing service type retains the largest revenue pool, though consulting engagements command superior margins due to specialized expertise premiums and shorter fulfillment cycles.
The U.S. Department of Labor, the Internal Revenue Service, and Canada's Canada Revenue Agency collectively shape North American contingent workforce demand through divergent contractor classification tests and joint-employer liability standards that elevate compliance technology spending. The U.S. DOL's 2024 independent contractor rule restoration and pending provincial variations in Ontario and Quebec create a fragmented regulatory map that vendors must navigate through jurisdictional configuration engines. Stakeholders must monitor evolving cross-border tax treaty interpretations and real-time legislative tracking tools that flag classification rule shifts before client contracts reprice.
Market Dynamics
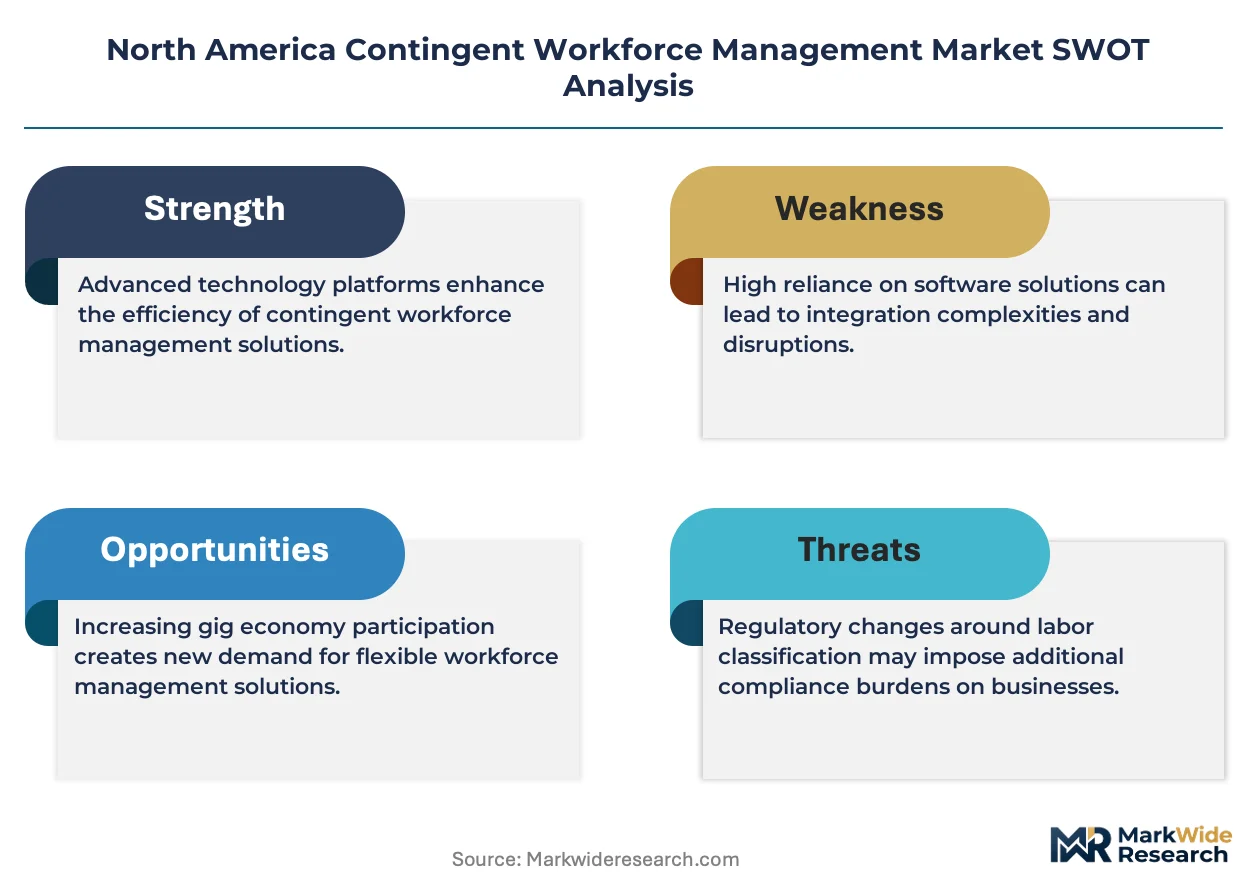
The U.S. Department of Labor's 2024 independent contractor rule restoration has triggered a compliance technology arms race, forcing enterprises to automate classification screening across W-2 and 1099 worker populations to avoid joint-employer liability exposure.
Growth Catalysts
- Healthcare surge staffing:Hospital systems in Texas and Florida deploy temporary clinical teams to manage seasonal patient influxes, expanding vendor management system penetration.
- IRS information reporting mandates:Expanded 1099-K and 1099-NEC filing thresholds drive automated tax documentation platform adoption among mid-market employers.
- AI-powered skills matching:Machine learning algorithms compress time-to-fill for specialized engineering roles across Austin-Raleigh technology corridors.
Market Restraints
- Regulatory fragmentation:Divergent contractor classification tests between U.S. federal standards and Ontario's Employment Standards Act create jurisdictional compliance engine complexity.
- Legacy system integration costs:Enterprises face substantial capital outlays to connect modern vendor management systems with decades-old HRIS architectures.
- Specialized talent scarcity:Shortage of certified compliance analysts familiar with both U.S. Fair Labor Standards Act and Canada Revenue Agency rules limits platform implementation velocity.
Strategic Opportunities
- Quebec provincial expansion:Distinct French-language labor regulations and civil law traditions create underserved demand for localized contingent workforce platforms.
- Direct sourcing channel maturation:Curated talent pools bypass traditional staffing markup structures, capturing margin from statement-of-work consulting engagements.
- Cross-border tax treaty automation:Real-time treaty interpretation engines address U.S.-Canada social security totalization agreement complexities for mobile contractors.
Industry Challenges
- Misclassification audit exposure:State-level wage-and-hour investigations in California and New York create retroactive liability risk for platform users.
- Interoperability friction:Vendor management systems struggle to synchronize worker data with enterprise resource planning modules from competing software ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Contingent Workforce Management Market |
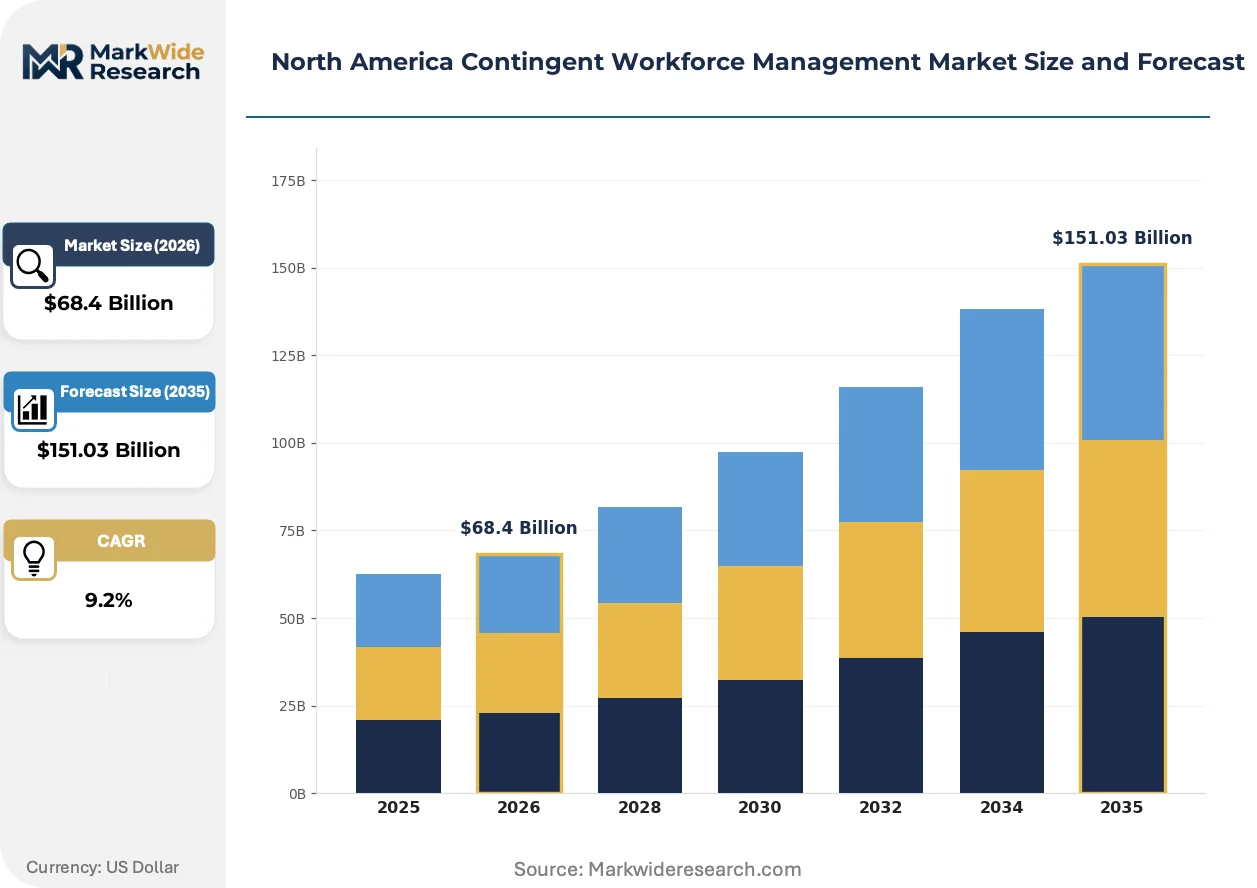
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $151.03 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Staffing, Recruitment, Consulting, Outsourcing Technology: Cloud-Based, On-Premise, Mobile Platforms, AI-Driven End User: Corporates, SMEs, Government, Nonprofits Market Segment: Finance, Healthcare, IT, Manufacturing |
| Companies Covered | SAP SE, Workday, Inc., ADP, LLC, Magnit, Beeline, Coupa Software, Inc., Avature Limited, IBM Corporation, The Bowen Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Contingent Workforce Management Market Trends and Innovations
Cloud-native architectures are displacing on-premise installations across contingent workforce technology stacks, embedding predictive analytics directly into hiring workflows rather than layering them atop legacy databases.
Artificial intelligence is digitizing candidate screening and compliance verification processes. Large hospital systems and technology firms deploy natural language processing to parse contract terms against jurisdictional classification rules. This compression of legal review cycles reduces time-to-productivity for contingent hires from weeks to days.
The U.S. Department of Labor's evolving joint-employer standards under the Fair Labor Standards Act force platform vendors to reengineer liability allocation features. Automated indemnification workflows now flag co-employment risk before contract execution. Technology and healthcare verticals absorb these compliance investments most aggressively.
Enterprise buyers increasingly unbundle managed service provider relationships to capture direct sourcing economics. Fortune 500 procurement functions build internal talent marketplaces, displacing traditional staffing markup structures. This behavior concentrates most visibly in software engineering procurement across Texas and North Carolina metropolitan clusters.
North America Contingent Workforce Management Market Segmentation
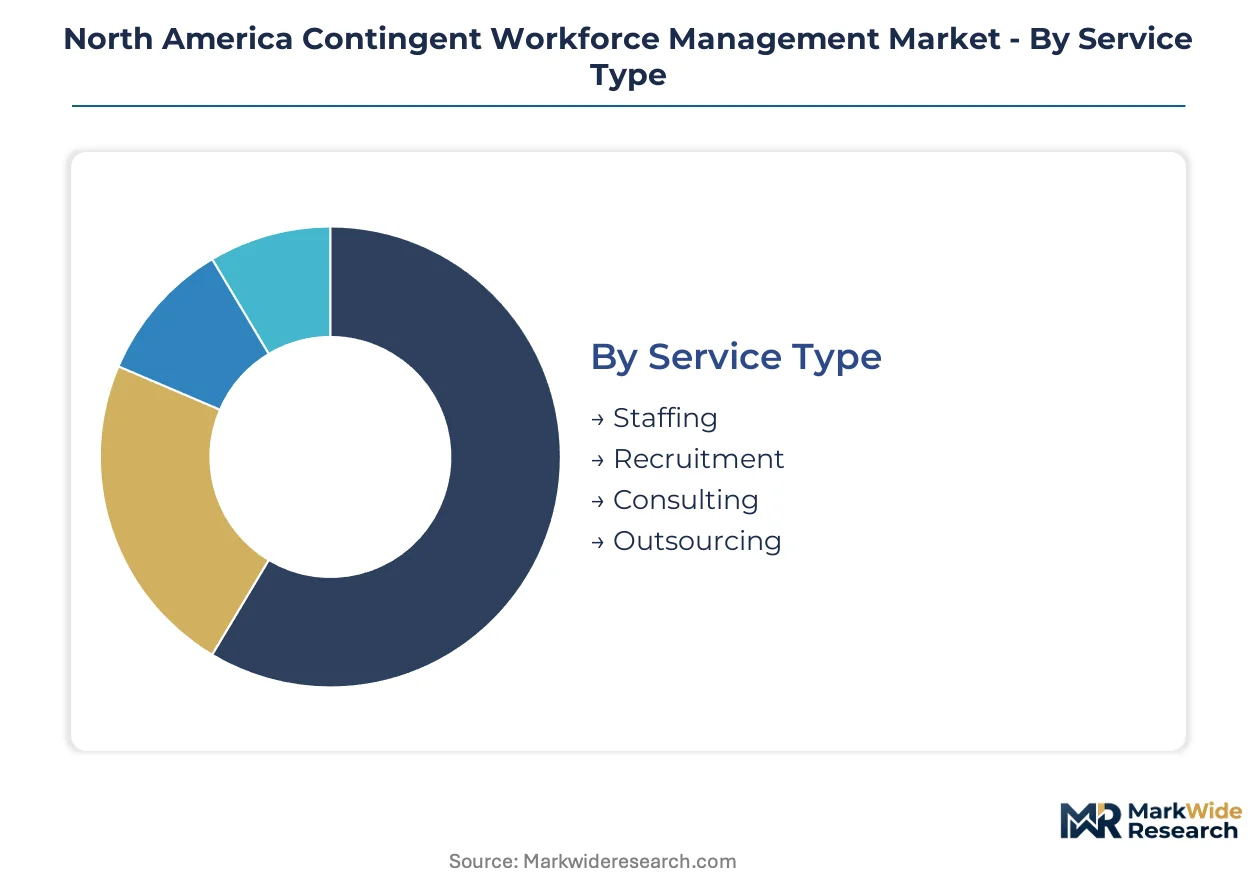
Segmentation in contingent workforce management reveals how procurement priorities diverge across client sophistication levels and regulatory exposure. Technology deployment choices and service configurations directly determine compliance automation capabilities and cost structures for buyers navigating multi-jurisdictional labor classifications.
Service Type:
Mature service lines anchor revenue stability while emerging configurations reshape margin capture.
- Staffing:Temporary labor placement encompassing clinical, administrative, and industrial roles with time-and-materials billing structures. Hospital systems in Texas and Florida deploy surge staffing for seasonal patient influxes, driving vendor management system integration mandates.
- Consulting:Statement-of-work engagements delivering specialized expertise through fixed deliverable contracts. Technology firms across Austin-Raleigh corridors compress fulfillment cycles for project-based engineering teams, commanding premium pricing through scarcity premiums.
- Recruitment:Direct sourcing and talent curation services bypassing traditional staffing markups. Enterprise procurement functions internalize candidate pipelines to capture margin from high-volume contingent hiring.
- Outsourcing:Business process delegation with embedded workforce management accountability. Mid-market employers adopt bundled payroll-tax-compliance packages to address IRS information reporting mandates.
Staffing handles the majority of throughput; consulting is the fastest mover on share.
Technology:
Deployment architecture determines compliance engine responsiveness and integration capital requirements.
- Cloud-Based:SaaS-delivered platforms with automatic regulatory update propagation and API-native ERP connectivity. Enterprises abandon legacy installations to eliminate dedicated IT maintenance for classification rule changes.
- AI-Driven:Machine learning systems embedding predictive skills matching and automated misclassification screening. Natural language processing parses contract terms against jurisdictional rules, compressing legal review cycles from weeks to days.
- On-Premise:Installed software requiring client-managed infrastructure and manual patch deployment. Remaining installations concentrate in highly regulated government contracting environments with data sovereignty requirements.
- Mobile Platforms:Native applications for time capture, credential verification, and shift management. Healthcare systems deploy clinical staffing apps to manage float pool rotations across multi-site networks.
Cloud-Based carries the volume base; AI-Driven platforms are climbing the fastest on adoption curves.
End User:
Organizational scale dictates procurement sophistication and compliance technology investment thresholds.
- Corporates:Fortune 500 enterprises with dedicated vendor management offices and direct sourcing programs. Unbundled MSP relationships concentrate in software engineering procurement across Texas and North Carolina metropolitan clusters.
- SMEs:Mid-market employers with limited procurement infrastructure and elevated audit exposure. Automated tax documentation platform adoption accelerates following expanded 1099-K and 1099-NEC filing thresholds.
- Government:Federal and state agencies with civil service backfill requirements and security clearance constraints. Classification compliance intensifies under U.S. Department of Labor joint-employer liability standards.
- Nonprofits:Mission-driven organizations with grant-funded staffing and restricted overhead allocations. Cost pressures drive shared service arrangements for payroll and benefits administration.
Corporates dominate absolute spend; SMEs represent the steepest expansion trajectory as compliance automation penetrates mid-market budgets.
Market Segment:
Vertical specialization determines regulatory complexity and skills scarcity premiums.
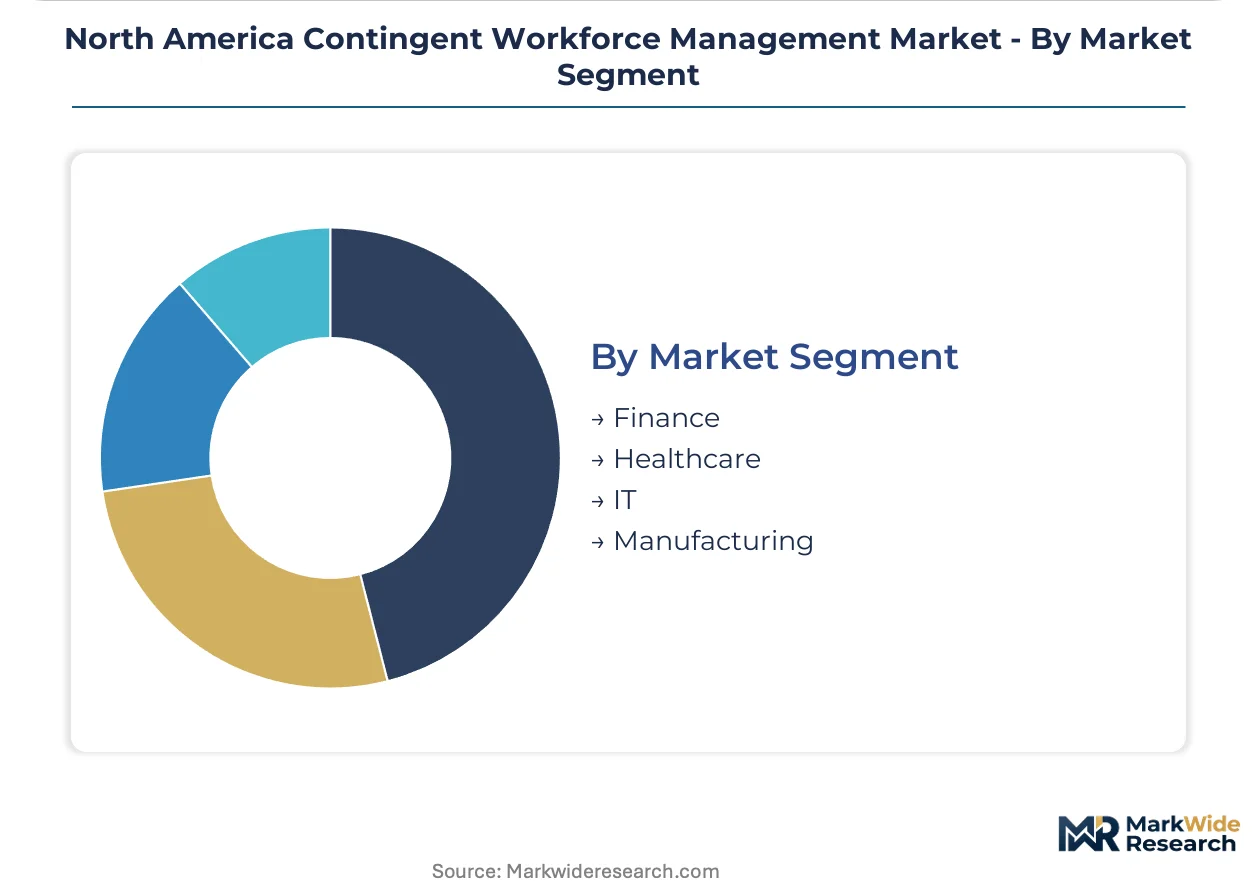
- Healthcare:Clinical and non-clinical temporary staffing with credential verification and shift flexibility requirements. Seasonal patient surges in Sun Belt states expand vendor management system penetration.
- IT:Software engineering and infrastructure project staffing with rapid time-to-fill imperatives. Skills matching algorithms compress placement timelines for specialized roles across technology corridors.
- Finance:Risk management and compliance consulting with regulatory expertise premiums. SOX and SEC reporting requirements sustain demand for statement-of-work engagements.
- Manufacturing:Production scaling and maintenance staffing with safety certification tracking. Just-in-time labor deployment aligns with demand volatility in automotive and electronics supply chains.
Healthcare absorbs the largest service volume; IT demonstrates the fastest share gain as project-based engineering scales accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Labor anchors regulatory complexity across North America, while provincial authorities in Canada fragment compliance requirements. Demand concentrates in technology corridors and healthcare systems facing seasonal staffing volatility.
United States
Hospital networks in Texas and Florida deploy temporary clinical teams to manage seasonal patient surges, expanding vendor management system penetration. The U.S. Department of Labor's 2024 independent contractor rule restoration forces enterprises to automate classification screening across W-2 and 1099 populations. The Austin-Raleigh technology corridor drives software engineering procurement as firms aggressively scale project-based teams.
Canada
Healthcare systems in Ontario and British Columbia expand reliance on temporary clinical staff to address workforce shortages and seasonal demand peaks. Provincial variations in Ontario's Employment Standards Act and Quebec's civil law traditions create jurisdictional compliance engine complexity for platform vendors. Toronto and Vancouver metropolitan clusters absorb the largest contingent workforce technology investments.
California
State-level wage-and-hour investigations create retroactive liability exposure for platform users employing misclassified workers. The California Labor Code's stringent contractor tests exceed federal Fair Labor Standards Act thresholds, elevating compliance technology spending. Silicon Valley technology firms unbundle managed service provider relationships to build internal talent marketplaces.
New York
Financial services firms sustain demand for risk management and compliance consulting with regulatory expertise premiums. The New York State Department of Labor enforces classification standards that trigger automated indemnification workflow investments. The New York metropolitan area concentrates statement-of-work engagements for SOX and SEC reporting requirements.
North America Contingent Workforce Management Market Competitive Landscape
Enterprise software incumbents and specialized workforce platforms split the market through divergent integration strategies. SAP SE and Workday anchor the consolidated tier through embedded HR ecosystem dominance, while standalone vendors compete on compliance automation depth. Two archetypes define competitive positioning: ERP-integrated suite providers and best-of-breed contingent labor specialists. Market evolution favors acquisition activity consolidating compliance engines with talent marketplace functionality.
Within the ERP-integrated tier, SAP SE, Workday, Inc., and ADP, LLC represent archetypal approaches to workforce management unification. SAP leverages its installed base to embed contingent labor modules within existing enterprise resource planning workflows. Workday competes through native workforce planning tools that unify permanent and temporary headcount analytics. ADP sustains payroll-centric dominance by extending tax compliance across 1099 and W-2 classifications simultaneously.
| Leading Market Players |
|---|
| SAP SE |
| Workday, Inc. |
| ADP, LLC |
| Magnit |
| Beeline |
| Coupa Software, Inc. |
| Avature Limited |
| IBM Corporation |
| The Bowen Group |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure providers in the United States anchor the technology stack for contingent workforce platforms, concentrating margin capture in SaaS subscription tiers and API integration layers rather than implementation services. This upstream concentration shapes downstream pricing power, as buyers face switching costs embedded in HRIS connectivity and compliance engine configuration.
Pricing Analysis
California and New York command 15-25% pricing premiums over Texas and Florida for equivalent contingent workforce management deployments. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance automation depth and ERP integration complexity. Pricing pressure stems from mid-market employers consolidating vendor relationships to reduce per-seat licensing overhead. SMEs exhibit highest price sensitivity, while Fortune 500 corporates prioritize functionality over per-user cost.
Supply Chain Analysis
U.S. Department of Commerce export controls on AI and machine learning technologies limit cross-border transfer of predictive workforce analytics engines, constraining platform development for vendors with offshore engineering centers. Software development concentrates in the United States, India, and Ireland, with compliance engine training data sourced from jurisdictional regulatory filings and court precedent databases. Single-source vulnerability runs through cloud infrastructure dependencies on hyperscale providers. Distribution runs through direct enterprise sales and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American contingent workforce management sits in early-cycle expansion as AI-powered compliance automation penetrates mid-market budgets previously priced out of enterprise-grade platforms.
For Market Incumbents: Build switching-cost moats through deeper ERP ecosystem embedding. SAP SE and Workday should accelerate native contingent labor module development to preempt standalone vendor displacement. Threat of direct sourcing channel maturation demands acquisition of curated talent marketplace technology. Capacity addition in Quebec French-language localization preserves pricing power in underserved provincial markets. For New Entrants and Emerging Players: Mid-market healthcare employers in Ontario and British Columbia represent the most penetrable entry point for compliance-automation-first platforms. SME government contractors with security clearance requirements face limited vendor options due to on-premise legacy dominance. Go-to-market through channel partnerships with regional staffing firms bypasses direct enterprise sales cycle friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-driven platform development as foundation models reduce proprietary training data requirements. Long-term viability favors vendors with jurisdictional rule engines covering both U.S. DOL and Canada Revenue Agency standards. Acquisition target archetype: standalone compliance automation vendors with healthcare vertical penetration. Watch U.S. federal contractor classification rulemaking as inflection signal for platform repricing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Compliance Engine Development | Natural language processing parsing contract terms against DOL and CRA rules compresses legal review cycles from weeks to days. |
| ERP Native Integration | Embedded contingent labor modules within Workday and SAP architectures preempt standalone vendor displacement. |
| Quebec Localization Investment | French-language labor regulations and civil law traditions create defensible market position in underserved provincial segment. |
| Direct Sourcing Marketplace Build | Curated talent pools bypass traditional staffing markups, capturing margin from statement-of-work consulting engagements. |
| Cross-Border Tax Treaty Automation | Real-time U.S.-Canada social security totalization agreement interpretation addresses mobile contractor compliance complexity. |
Research Methodology
Initial hypotheses were tested against primary input from vendor management system operators, managed service provider executives, enterprise procurement officers, and compliance technology architects and refined through secondary validation against U.S. Department of Labor enforcement data, IRS information reporting statistics, Canada Revenue Agency guidance documents, and vendor management system user conference proceedings. Bottom-up triangulation across platform deployment metrics and top-down reconciliation against employer staffing expenditure surveys anchored market sizing.
Demand-supply balance framing modeled contingent workforce management adoption across the analysis window through segmentation by service type, technology deployment architecture, organization scale, and vertical industry. CAGRs were derived from employer hiring volatility indices and compliance technology investment surveys. Forecast inputs included seasonal patient surge patterns in Sun Belt hospital systems and software engineering project staffing velocity across Austin-Raleigh technology corridors.
Practitioners should monitor U.S. Department of Labor joint-employer rulemaking and Ontario Employment Standards Act amendments for early signals of compliance engine reconfiguration requirements. Forecasts reflect assumptions regarding sustained healthcare staffing volatility and technology sector project-based hiring expansion. Material shifts in federal contractor classification standards or provincial labor law harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
IT Staffing Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
United States Management Consulting Services Market