
 HR Tech Consulting Market | 2026-2036
HR Tech Consulting Market Size, Share, and Industry Trends Forecast 2026-2036
HR Tech Consulting Market Insights
The shift from single-source to multi-source consulting engagements is hardening across enterprise procurement. Deloitte leverages its cloud implementation partnerships to anchor large-scale HR transformation programs. Accenture sustains technology leadership through AI-powered workforce analytics. IBM competes by integrating its proprietary Watson capabilities into talent management advisory.
HR Tech Consulting encompasses advisory and implementation services that configure software platforms, optimize human capital workflows, and align workforce strategy with enterprise technology architecture. Practitioners typically deploy cloud-native architectures with API-driven integrations across payroll, learning, and talent systems to reduce operational fragmentation. Strategy Advisory and Digital Transformation command the widest client bases, while AI-powered Analytics and Talent Acquisition Tools capture the fastest growth trajectories as organizations prioritize predictive workforce planning. Cloud-based Solutions dominate technology spending, though Managed Services delivery models are expanding margin pools through recurring revenue structures.
The EU AI Act and GDPR constrain algorithmic hiring tool deployments across European engagements, while the US EEOC and OSHA frameworks shape workplace surveillance and safety compliance parameters for domestic consulting scopes. ISO 30414 human capital reporting standards are elevating disclosure requirements, forcing advisory firms to build certified measurement methodologies. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of service line profitability and platform configurability.
Market Dynamics
The EU AI Act is compressing vendor compliance timelines while healthcare systems accelerate workforce analytics procurement, creating a bifurcation between regulated European engagements and faster-moving North American deployments.
Growth Catalysts
- Algorithmic Accountability Mandates:The EU AI Act's risk classification system for hiring tools is forcing enterprises to seek certified advisory partners, expanding implementation service contracts.
- Healthcare Workforce Analytics:Hospital systems facing clinician shortages are deploying predictive staffing platforms, driving demand for specialized configuration and change management services.
- Mittelstand Modernization:Germany's mid-sized manufacturers are replacing fragmented legacy HR infrastructure with integrated cloud suites, creating concentrated regional demand.
Market Restraints
- GDPR Compliance Architecture:Cross-border data residency requirements for workforce analytics platforms increase implementation complexity and extend project timelines.
- Technical Talent Scarcity:Shortages of consultants certified in ISO 30414 human capital reporting standards constrain service expansion.
- Algorithmic Audit Costs:Mandatory bias testing for AI hiring tools under the EU AI Act elevates ongoing compliance expenditures beyond smaller enterprise budgets.
Strategic Opportunities
- API-First Integration Layer:Convergence of payroll, learning, and talent systems through open architecture is enabling advisory firms to capture recurring managed services revenue.
- OSHA Workplace Surveillance Alignment:US safety compliance frameworks are expanding advisory scopes into environmental health analytics and IoT-enabled workforce monitoring.
- France's CSRD Implementation:Mandatory human capital disclosure requirements are creating demand for certified measurement methodologies and sustainability-linked workforce reporting.
Industry Challenges
- Multi-Source Engagement Coordination:Enterprise procurement's shift from single-vendor to distributed consulting models fragments project ownership and complicates accountability.
- Legacy System API Limitations:On-premise HR platforms lacking modern integration capabilities require costly middleware development, compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HR Tech Consulting Market |
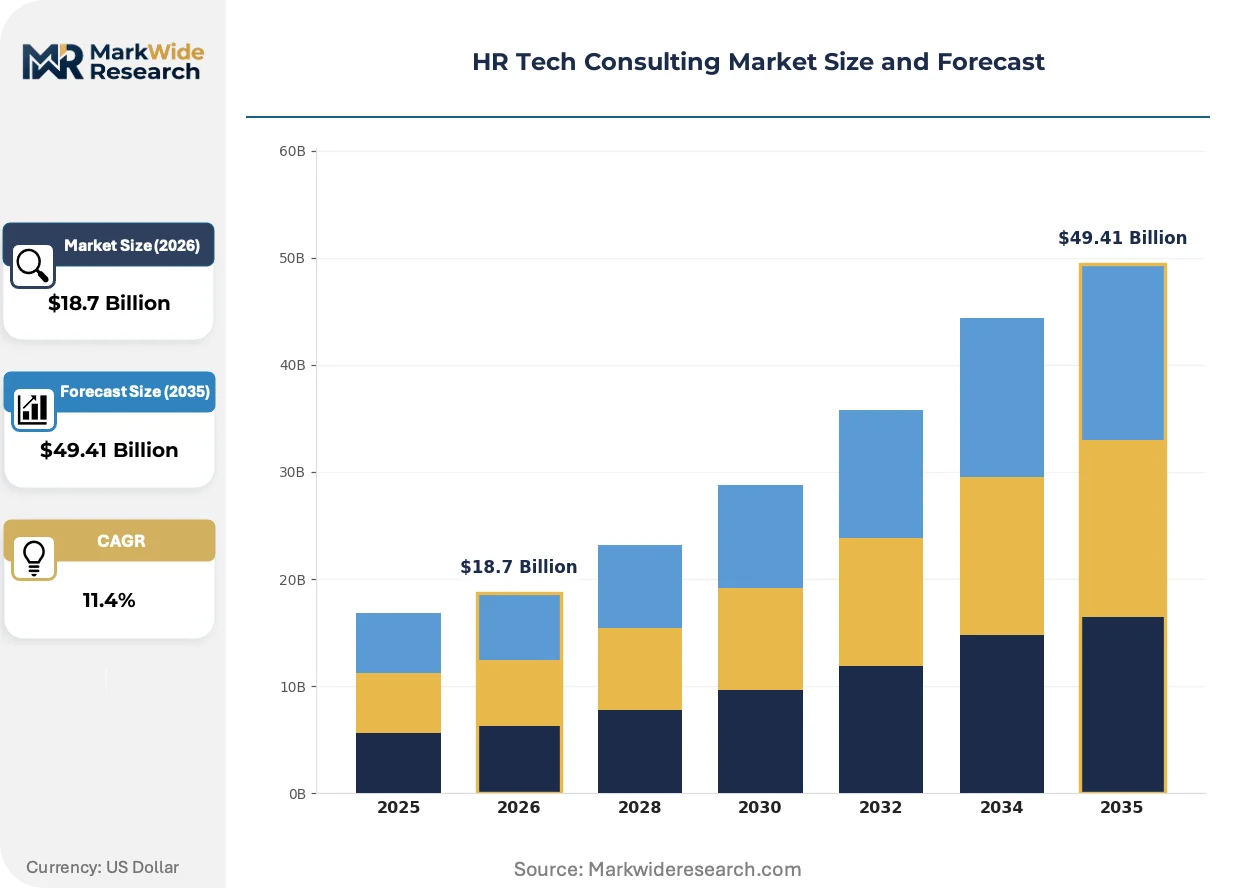
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Advisory, Digital Transformation, Change Management, Workforce Planning, Technology Implementation Technology: Cloud-based Solutions, AI-powered Analytics, Employee Engagement Platforms, Talent Acquisition Tools, Learning Management Systems, Payroll Automation End User: Large Enterprises, Mid-sized Corporations, Small Businesses, Startups, Nonprofit Organizations Delivery Model: On-premises Consulting, Remote Consulting, Hybrid Consulting, Managed Services |
| Companies Covered | Deloitte, Accenture, IBM, PwC, McKinsey & Company, Boston Consulting Group, Bain & Company, Mercer, Aon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HR Tech Consulting Market Trends and Innovations
Workforce technology architecture is fragmenting into composable components while regulatory jurisdictions diverge on algorithmic governance, forcing advisory firms to build modular compliance capabilities.
Composable HR architecture is modularizing enterprise technology stacks into discrete, API-connected services spanning payroll, benefits administration, and talent acquisition. Mid-market employers in the United States are adopting this approach fastest, replacing monolithic suites with best-of-breed configurations. This modularity is compressing implementation cycles while expanding integration service demand.
The EU AI Act's risk-based classification system for automated decision-making tools is reshaping vendor qualification requirements across European engagements. High-risk hiring algorithms now require conformity assessments, technical documentation, and human oversight protocols before deployment. Healthcare and financial services sectors in Germany and France are restructuring procurement processes to accommodate these pre-deployment validation steps.
Outcome-based contracting is displacing time-and-materials pricing for large-scale HR transformation programs. Enterprise buyers in the United Kingdom are piloting gain-share arrangements tied to measurable workforce productivity improvements. This shift is visible most acutely in public sector engagements where budget accountability requirements favor defined deliverables over open-ended advisory scopes.
HR Tech Consulting Market Segmentation
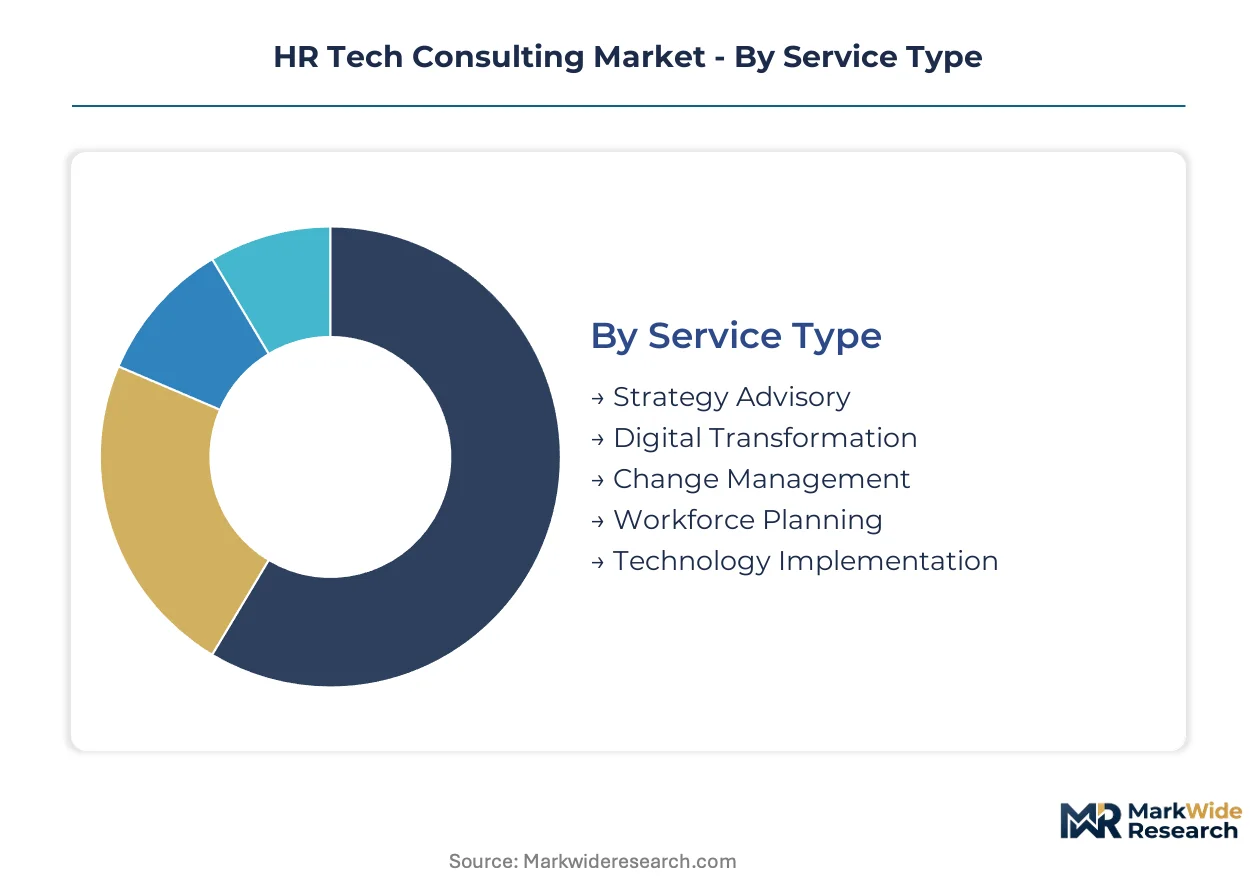
HR Tech Consulting procurement decisions hinge on organizational maturity, regulatory exposure, and legacy infrastructure complexity. Buyers select service configurations based on workforce scale, cloud readiness, and compliance jurisdiction rather than generic capability claims.
Service Type:
Enterprise buyers prioritize service bundles that reduce vendor fragmentation and accelerate time-to-value for workforce technology investments.
- Strategy Advisory:C-suite engagements aligning human capital architecture with enterprise transformation roadmaps. Demand concentrates among Fortune 500 firms in Germany and France navigating EU AI Act compliance for algorithmic workforce decisions.
- Digital Transformation:End-to-end re-platforming of HR systems onto cloud-native infrastructure. Germany's Mittelstand manufacturers drive regional concentration as fragmented legacy systems reach end-of-life support windows.
- Change Management:Organizational design and adoption services for technology rollouts. Healthcare systems in the United States deploy these services alongside predictive staffing platform implementations.
- Workforce Planning:Predictive analytics and scenario modeling for talent supply chains. Financial services firms in the United Kingdom adopt these services to meet CSRD human capital disclosure requirements.
- Technology Implementation:Technical configuration and integration of HR software platforms. Mid-sized corporations across North America and Europe represent the core demand base for SAP SuccessFactors and Workday deployments.
Volume sits with Technology Implementation; growth tilts toward Strategy Advisory.
Technology:
Technology selection follows data sovereignty requirements and integration complexity rather than feature breadth alone.
- Cloud-based Solutions:Multi-tenant SaaS architectures for core HR, payroll, and benefits administration. Mid-market employers in the United States are replacing monolithic suites with composable configurations fastest.
- AI-powered Analytics:Machine learning models for predictive retention, skills gap analysis, and workforce optimization. Hospital systems facing clinician shortages are deploying these platforms most aggressively.
- Employee Engagement Platforms:Pulse survey and sentiment analysis tools integrated with collaboration software. Large enterprises with distributed workforces drive procurement concentration.
- Talent Acquisition Tools:Applicant tracking systems with automated screening and interview scheduling. EU AI Act risk classifications are restructuring procurement processes in Germany and France to accommodate pre-deployment validation.
- Learning Management Systems:Skills-based training platforms with credential tracking and career pathing. Healthcare and financial services sectors prioritize compliance certification automation.
- Payroll Automation:Multi-country payroll engines with tax jurisdiction compliance and real-time payment processing. Global enterprises with complex cross-border workforces anchor demand.
Cloud-based Solutions dominate current spending; AI-powered Analytics is climbing the fastest.
End User:
Buyer scale determines service delivery model, pricing structure, and regulatory scrutiny intensity.
- Large Enterprises:Global organizations with 10,000+ employees requiring multi-country payroll and complex integration architectures. These buyers command dedicated account teams and outcome-based contracting structures.
- Mid-sized Corporations:Organizations with 500-10,000 employees modernizing fragmented HR infrastructure. Germany's Mittelstand segment represents concentrated regional demand for integrated cloud suite migrations.
- Small Businesses:Employers with under 500 employees adopting standardized SaaS configurations with minimal customization. Remote consulting delivery models serve this segment profitably.
- Startups:High-growth companies prioritizing scalable, API-first platforms that accommodate rapid headcount expansion. Venture-backed technology firms in the United States and United Kingdom anchor demand.
- Nonprofit Organizations:Mission-driven employers with constrained budgets seeking grant-compliant workforce reporting. ISO 30414 certification requirements are elevating advisory service needs in this segment.
Large Enterprises capture the greatest advisory spend; Mid-sized Corporations are expanding most quickly.
Delivery Model:
Delivery configuration reflects data residency mandates, project complexity, and margin optimization strategies for advisory firms.
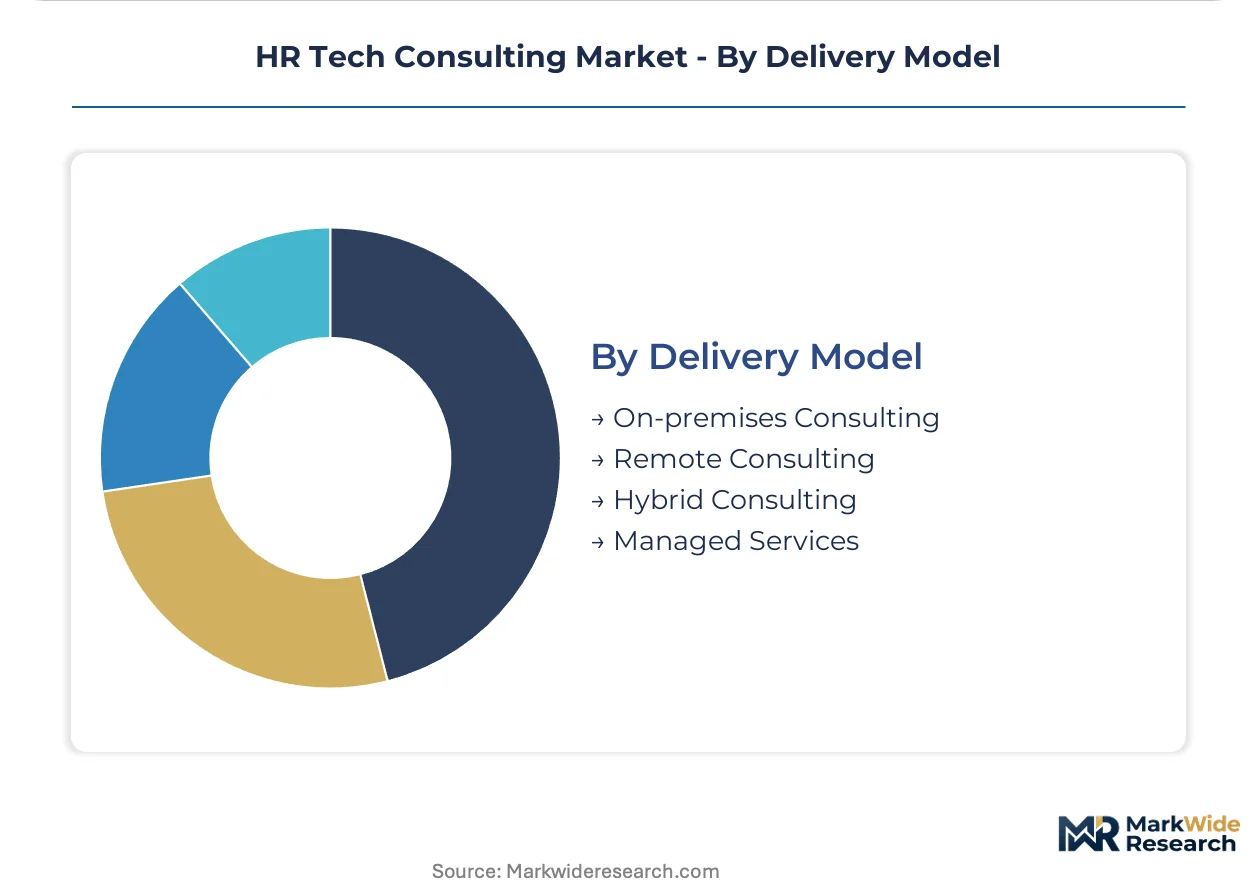
- On-premises Consulting:Embedded advisory teams working within client facilities for sensitive transformation programs. Financial services and government engagements in France require this model for data sovereignty compliance.
- Remote Consulting:Distributed delivery via collaboration platforms for standardized implementation and support services. Small businesses and technology-forward startups prefer this cost-optimized approach.
- Hybrid Consulting:Blended on-site and remote delivery combining relationship depth with operational efficiency. Large enterprises with multi-phase transformations are standardizing on this structure.
- Managed Services:Recurring operational support for platform administration, compliance monitoring, and continuous optimization. API-first integration architectures are enabling advisory firms to build predictable revenue streams in this model.
Hybrid Consulting commands the widest adoption; Managed Services is gaining share fastest through recurring revenue structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement of HR Tech Consulting concentrates in economies with complex regulatory environments and legacy infrastructure modernization cycles. Germany's Mittelstand manufacturers and United States hospital systems currently drive the highest contract volumes.
United States
Healthcare systems facing clinician shortages deploy predictive staffing platforms with specialized configuration services. OSHA workplace surveillance frameworks expand advisory scopes into environmental health analytics and IoT-enabled workforce monitoring. Hospital networks in Texas and California anchor demand for change management services alongside AI-powered analytics implementations.
Germany
Mid-sized manufacturers replace fragmented legacy HR infrastructure with integrated cloud suites, creating concentrated regional demand. EU AI Act risk classifications for algorithmic hiring tools force conformity assessments and human oversight protocol development. Industrial clusters in Bavaria and Baden-Württemberg restructure procurement processes to accommodate pre-deployment validation steps.
United Kingdom
Financial services firms adopt workforce planning services to meet CSRD human capital disclosure requirements with certified measurement methodologies. Outcome-based contracting displaces time-and-materials pricing for public sector HR transformation programs. London-based enterprises pilot gain-share arrangements tied to measurable workforce productivity improvements.
France
CSRD implementation mandates drive demand for sustainability-linked workforce reporting and certified human capital disclosure systems. ANSM and CNIL oversight shapes algorithmic governance requirements for hiring tool deployments. Financial services and healthcare sectors in Île-de-France restructure vendor qualification processes to accommodate technical documentation and bias testing protocols.
India
Mid-sized corporations modernize HR infrastructure through cloud-native architectures with API-driven integrations across payroll and talent systems. BIS standards and evolving data localization requirements influence platform configuration decisions. Technology services clusters in Karnataka and Telangana anchor demand for remote consulting delivery models serving standardized SaaS implementations.
HR Tech Consulting Market Competitive Landscape
Multi-source engagement expansion dominates the current landscape as enterprise procurement fragments project ownership across distributed consulting models. The vendor base organizes into three tiers: global professional services networks with cloud implementation partnerships, technology-forward specialists with proprietary AI capabilities, and regional boutiques with sector-specific compliance expertise. Consolidation pressures intensify through strategic partnerships anchoring large-scale transformation programs and API-first integration architectures enabling recurring managed services revenue.
Within the global network tier, Deloitte, Accenture, and IBM exemplify divergent competitive positioning. Deloitte leverages cloud implementation partnerships to anchor enterprise HR transformation programs across European and North American engagements. Accenture sustains technology leadership through AI-powered workforce analytics and predictive staffing platform configurations. IBM competes by integrating proprietary Watson capabilities into talent management advisory and algorithmic hiring tool deployments.
| Leading Market Players |
|---|
| Deloitte |
| Accenture |
| IBM |
| PwC |
| McKinsey & Company |
| Boston Consulting Group |
| Bain & Company |
| Mercer |
| Aon |
| Others |
Pricing and Supply Chain Analysis
Composable HR architecture adoption is compressing implementation timelines while fragmenting vendor ecosystems, simultaneously reducing per-project labor costs and dispersing supply concentration across specialized integration partners. This shift rewards advisory firms with API-first platforms while squeezing margins for legacy system integrators tethered to monolithic suite deployments.
Pricing Analysis
Warranty and post-implementation support bundling separates premium advisory tiers from unbundled economy offerings. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 30414 certification status and dedicated account team allocation. Cost compression in the economy tier is intensifying because remote delivery models commoditize standardized SaaS configurations. Mid-sized corporations exhibit highest price sensitivity due to budget constraints, while Fortune 500 firms prioritize compliance assurance over unit cost.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in Ireland, Germany, and the United States to satisfy data residency mandates. The advisory talent pool draws from India, Poland, and Portugal for remote delivery capacity. Single-source vulnerability in certified EU AI Act compliance expertise elevates project risk. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HR Tech Consulting market functions as a cost-of-compliance story where the EU AI Act erects substantial barrier-to-entry moats favoring advisory firms with pre-certified algorithmic governance capabilities.
For Market Incumbents: Anticipate margin compression from boutique specialists targeting Mittelstand modernization with leaner cost structures. Defensive consolidation through ISO 30414 certification investment and captive AI ethics review board development anchors enterprise retention. Vertical integration into proprietary workforce analytics platforms deepens switching costs. For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for compliance-native entrants lacking legacy technical debt. Target mid-sized healthcare systems in the United States with predictive staffing platform specialization. Lead with outcome-based contracting to bypass incumbent time-and-materials relationships. For Investors and Strategic Acquirers: Re-rating potential sits with regional boutiques possessing sector-specific compliance expertise given CSRD implementation acceleration across European financial services. Long-term viability favors firms with recurring managed services revenue exceeding fifty percent of total mix. Watch ISO 30414 certification penetration rates as inflection indicator for advisory margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Enables recurring managed services revenue through composable integration architectures. |
| EU AI Act Certification Investment | Creates defensible positioning for algorithmic hiring tool advisory in German and French markets. |
| Healthcare Workforce Analytics Specialization | Captures predictive staffing platform demand from hospital systems facing clinician shortages. |
| Outcome-Based Contracting Pilot | Aligns advisory incentives with measurable workforce productivity improvements in UK public sector. |
| ISO 30414 Methodology Certification | Supports CSRD human capital disclosure compliance for financial services firms in France and UK. |
Research Methodology
SEC filings, hyperscaler partnership announcements, and EU regulatory guidance documents formed the secondary backbone. Primary interviews with CHROs, HR technology procurement officers, cloud implementation specialists, and compliance auditors supplied qualitative grounding. Bottom-up and top-down triangulation validated segmentation outputs.
Bottom-up modeling anchored volume estimates while top-down macroeconomic cross-checks tested plausibility across the analysis window. Service type, technology deployment model, organization size tier, and regional regulatory cluster constituted the core segmentation dimensions. CAGRs derived from fitted growth curves incorporating healthcare workforce expansion rates and Mittelstand cloud migration velocity.
The model assumes a particular technology adoption path; alternative pathways for on-premise legacy system persistence would alter the outlook. Forecasts reflect documented assumptions around EU AI Act enforcement intensity and ISO 30414 adoption timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Europe Warehouse Management Systems Market
Enterprise Services
Managed Services Market
Enterprise Services
IT Staffing Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Cloud Enterprise Management Market