
 Proactive Services Market | 2026-2036
Proactive Services Market Size, Share, and Industry Trends Forecast 2026-2036
Proactive Services Market Intelligence
AI/ML engineering talent scarcity is rotating enterprise priorities toward vendor-managed proactive service models rather than in-house buildouts. Microsoft Corporation leverages its Azure cloud fabric to embed predictive analytics across industrial IoT estates. Cisco Systems anchors its position through edge-native telemetry architectures that reduce latency for critical infrastructure clients. IBM Corporation competes via Watson-driven condition assessment modules targeting utilities and telecom operators.
Proactive services encompass predictive intervention systems that apply sensor telemetry, statistical failure modeling, and automated remediation workflows to prevent asset degradation before operational impact occurs. These systems typically process vibration, thermal, and electrical signature data through machine learning pipelines to generate maintenance triggers with defined confidence intervals. Predictive maintenance commands the largest revenue share among service types due to its direct linkage with unplanned downtime reduction. Cloud-based deployment is expanding fastest as hyperscale infrastructure lowers barrier costs for mid-sized industrial operators. Manufacturing equipment application leads in contract value, though energy infrastructure is narrowing the gap as grid modernization investments deepen.
ISO 55000 asset management standards, NIST cybersecurity frameworks, and sector-specific OSHA process safety mandates collectively elevate compliance complexity for proactive service vendors seeking enterprise adoption. The EU AI Act introduces additional algorithmic transparency requirements for automated decision systems deployed across European critical infrastructure. Stakeholders must weigh build-versus-buy architectures against evolving liability frameworks for machine-generated maintenance recommendations.
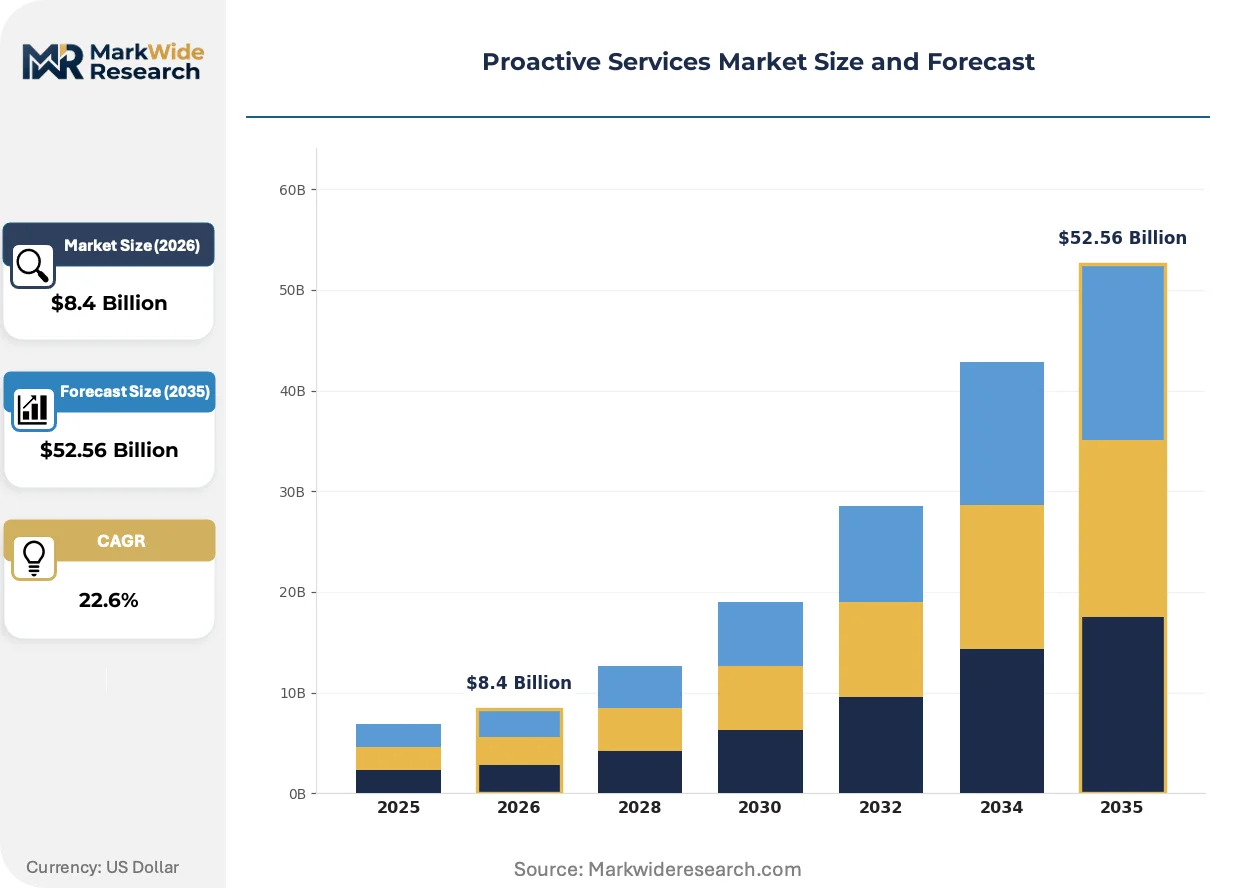
Market Dynamics
Cloud-based deployment architectures are compressing the cost barrier for mid-sized industrial operators, forcing incumbent vendors to abandon perpetual license models in favor of consumption-based telemetry subscriptions.
Growth Catalysts
- ISO 55000 asset management frameworks:European utilities and German manufacturers are mandating predictive maintenance protocols to satisfy auditor requirements for lifecycle optimization documentation.
- Edge computing integration:Japanese automotive plants are deploying latency-critical vibration analysis at the sensor level, bypassing round-trip delays to centralized cloud instances.
- Energy infrastructure modernization:US grid operators under FERC Order 2222 are procuring proactive monitoring suites to manage distributed energy resource intermittency.
Market Restraints
- AI/ML engineering talent scarcity:Enterprise build-versus-buy decisions are tilting toward vendor-managed models due to insufficient in-house pipeline development capacity.
- Semiconductor supply concentration:Edge device manufacturers face allocation constraints from Taiwan-based foundries, extending sensor deployment timelines.
- Cybersecurity compliance friction:NIST framework implementation costs are deterring smaller manufacturing operators from connected maintenance architectures.
Strategic Opportunities
- India industrial corridors:PLI scheme beneficiaries in Gujarat and Tamil Nadu are greenfield sites without legacy SCADA entanglements, enabling native proactive service deployment.
- EU AI Act algorithmic transparency:Mandates for explainable maintenance recommendations are creating first-mover advantages for vendors with interpretable model architectures.
- Digital twin convergence:Physics-based simulation layered atop machine learning is opening high-value contracts in US aerospace component lifecycle management.
Industry Challenges
- Interoperability with brownfield systems:OPC-UA translation layers require bespoke engineering for each legacy PLC manufacturer, inflating implementation costs.
- Condition-based maintenance certification timelines:ISO 17359 compliance documentation for vibration monitoring systems extends sales cycles by four to six months.
- Data sovereignty fragmentation:Cross-border telemetry flows face divergent national cloud localization requirements, complicating multi-site enterprise rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proactive Services Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $52.56 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Predictive Maintenance, Remote Monitoring, Condition Assessment, Asset Management, Performance Optimization Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing, Hosted Solutions Application: Manufacturing Equipment, Energy Infrastructure, Transportation Systems, Telecommunications Networks, Smart Buildings End User: Utilities, Transportation Providers, Industrial Operators, Facility Managers, Telecom Operators |
| Companies Covered | Juniper Networks, Huawei Technologies, Microsoft Corporation, DXC Technology, Avaya Holdings Corporation, Cisco Systems, Hewlett Packard Enterprise, Fortinet, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proactive Services Market Strategic Shifts & Innovations
Service delivery models are fragmenting along deployment topology lines, with edge-native and cloud-hybrid architectures diverging in capability emphasis and buyer profile.
Digital twin technology is bifurcating the high-value segment of the market. Aerospace and power generation operators are deploying physics-informed neural networks that fuse finite element models with real-time sensor streams. These systems command premium positioning against statistical-only alternatives. The structural consequence is compressing addressable market share for pure machine learning vendors lacking multiphysics simulation heritage.
REACH substance restrictions on industrial sensor coatings are forcing hardware redesigns across European deployments. Manufacturers are substituting fluoropolymer encapsulants with ceramic-based alternatives to maintain IP ratings. German automotive paint shops and French nuclear maintenance providers are absorbing twelve-to-eighteen-month recertification delays while awaiting ECHA guidance on acceptable material substitutions.
Buyer preference for performance-guaranteed contracts is displacing traditional time-and-materials service agreements. Energy utilities in Texas and California are procuring uptime commitments with penalty clauses rather than per-inspection fees. This compression of risk allocation onto vendors is most visible in US independent power producer segments, where merchant plant operators lack balance-sheet capacity to absorb unplanned outage costs.
Proactive Services Market Segmentation
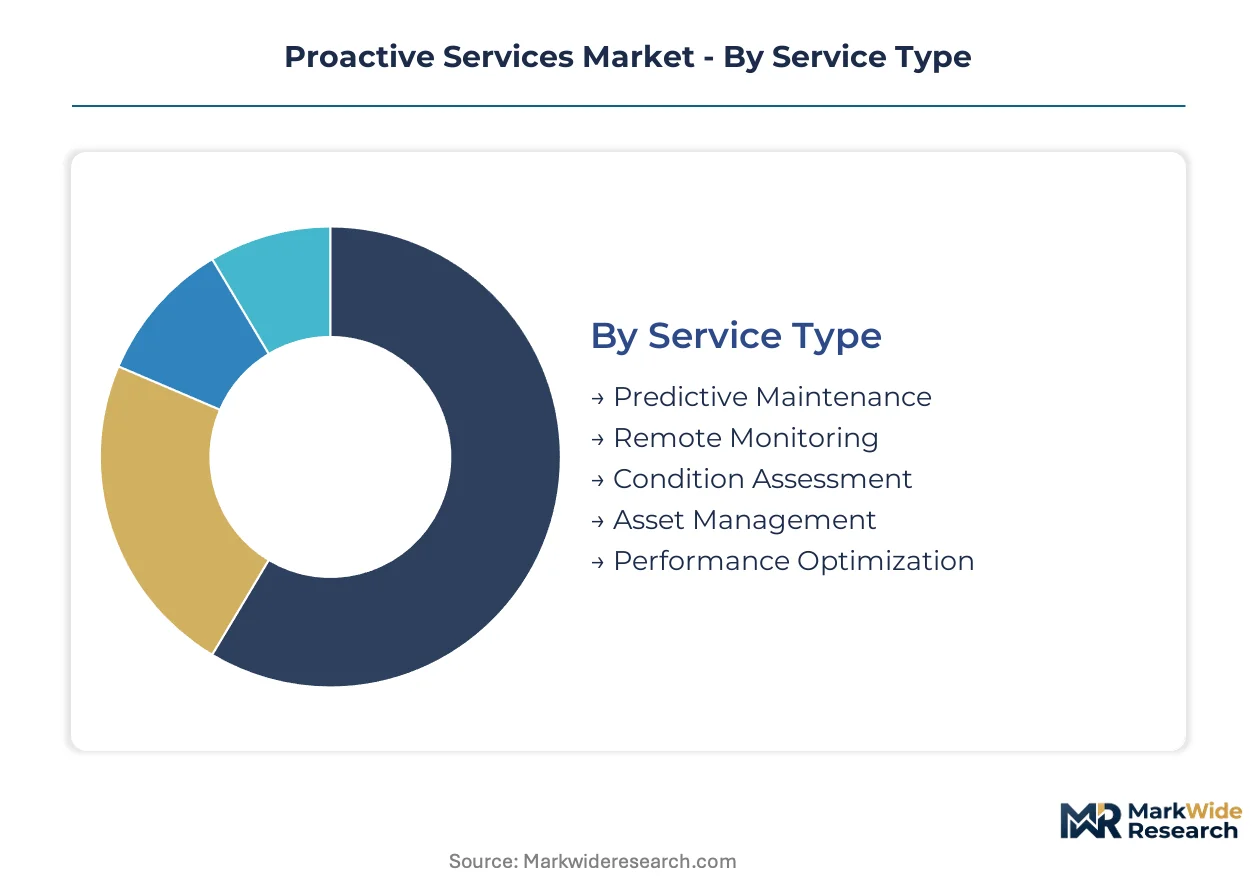
Proactive services fragment across four dimensions that determine vendor positioning and contract economics. Service type and deployment topology together dictate margin structure, while application and end-user profiles shape sales cycle duration and integration complexity.
Service Type:
Predictive maintenance contracts flow through multi-year enterprise agreements with penalty clauses, while remote monitoring and condition assessment increasingly route through consumption-based telemetry subscriptions.
- Predictive Maintenance:Combines sensor telemetry with statistical failure modeling to generate maintenance triggers before operational impact. German automotive manufacturers and US independent power producers are mandating these protocols to satisfy ISO 55000 auditor requirements for lifecycle documentation.
- Remote Monitoring:Continuous data ingestion from distributed asset estates enables centralized oversight of geographically dispersed operations. Japanese automotive plants are deploying latency-critical implementations that bypass round-trip delays to cloud instances.
- Condition Assessment:Periodic evaluation protocols determine asset health against baseline performance metrics. Texas energy utilities under FERC Order 2222 are procuring these suites to manage distributed energy resource intermittency.
- Asset Management:Lifecycle optimization frameworks align maintenance spend with replacement timing. European utilities face EU AI Act algorithmic transparency requirements for automated decision systems.
- Performance Optimization:Real-time parameter adjustment maximizes output efficiency. US aerospace component manufacturers are layering physics-based simulation atop machine learning for high-value contracts.
Predictive maintenance dominates installed base. Remote monitoring is where expansion concentrates.
Deployment:
Cost tier stratification separates hyperscale-accessible cloud architectures from capital-intensive edge installations requiring dedicated hardware procurement.
- Cloud-Based:Hyperscale infrastructure lowers barrier costs for mid-sized industrial operators, forcing incumbent vendors to abandon perpetual license models. Manufacturing equipment operators in Gujarat and Tamil Nadu industrial corridors are greenfield adopters without legacy SCADA entanglements.
- Edge Computing:Latency-critical processing at the sensor level enables real-time vibration analysis without centralized round-trips. Japanese automotive plants are deploying these architectures for mission-critical production line monitoring.
- Hybrid:Split processing between local and cloud instances balances responsiveness with analytical depth. German manufacturers are adopting these models to satisfy data sovereignty requirements while accessing centralized model training.
- On-Premise:Fully localized infrastructure addresses cybersecurity compliance friction deterring smaller operators from connected architectures. French nuclear maintenance providers absorb extended recertification timelines under REACH substance restrictions.
- Hosted Solutions:Vendor-managed private cloud deployments offer intermediate control without capital expenditure. US grid operators are procuring these for distributed energy resource management under FERC Order 2222.
Cloud-based deployments dominate new contract volume. Edge computing is climbing the fastest as latency requirements harden.
Application:
Application concentration tracks industrial digitization maturity, with manufacturing equipment leading contract value while energy infrastructure narrows the gap through grid modernization investments.
- Manufacturing Equipment:Vibration, thermal, and electrical signature monitoring through machine learning pipelines. German automotive paint shops are absorbing twelve-to-eighteen-month recertification delays for sensor coating material substitutions.
- Energy Infrastructure:Grid modernization and distributed resource integration drive procurement. US independent power producers are adopting performance-guaranteed contracts with uptime commitments and penalty clauses.
- Transportation Systems:Fleet-wide condition monitoring for rail and commercial vehicle operators. California utilities are procuring proactive monitoring for electric vehicle charging infrastructure.
- Telecommunications Networks:Base station and fiber optic cable health assessment. Telecom operators are deploying Watson-driven modules for condition assessment.
- Smart Buildings:HVAC and lighting system optimization through occupancy and environmental sensing. Facility managers are adopting these for operational expenditure reduction.
Manufacturing equipment commands largest revenue share. Energy infrastructure represents the steepest expansion trajectory as grid investments deepen.
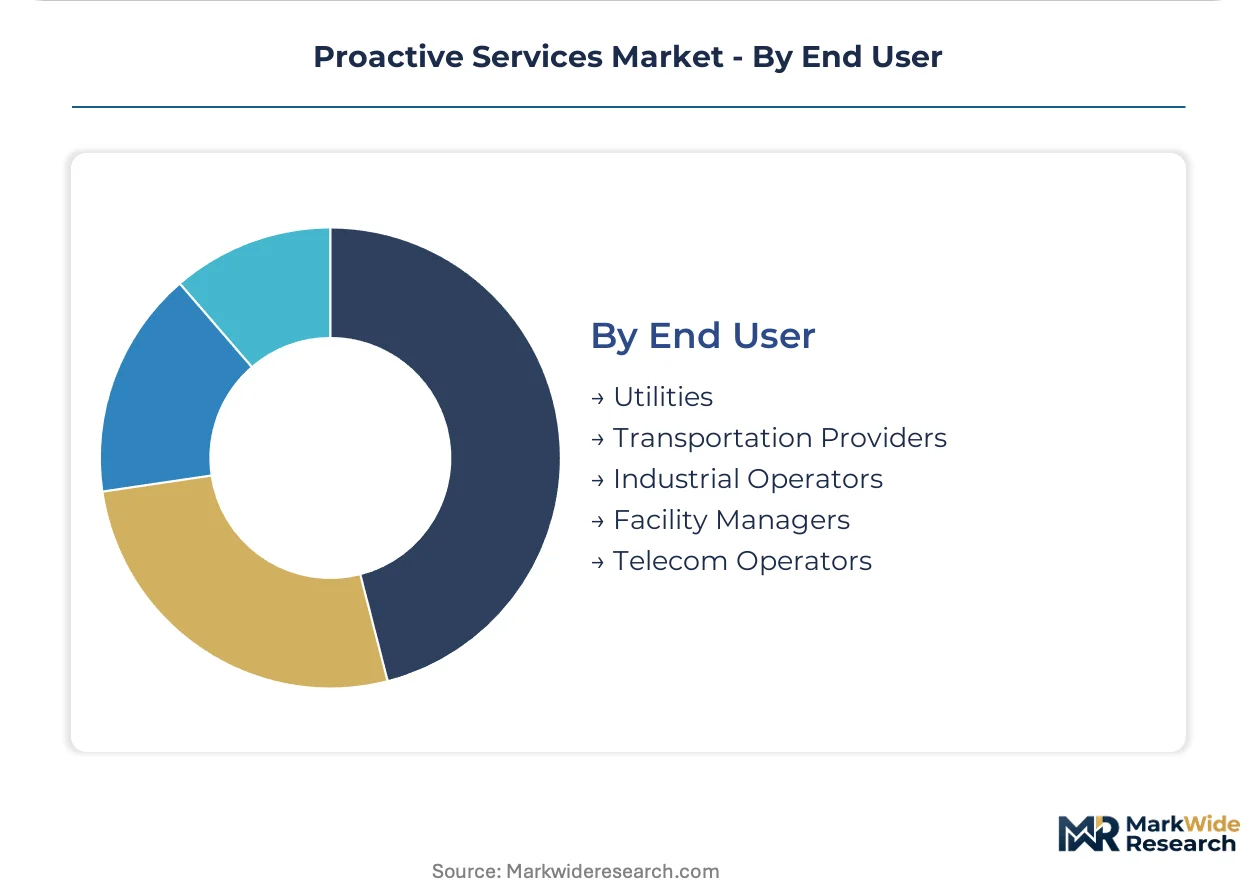
End User:
Customer type determines procurement modality, with utilities and industrial operators favoring performance-guaranteed contracts while facility managers prefer subscription-based remote monitoring.
- Utilities:Grid operators and independent power producers with balance-sheet exposure to unplanned outage costs. Texas and California utilities are displacing time-and-materials agreements with penalty-clause contracts.
- Industrial Operators:Manufacturing and process industry asset owners with ISO 55000 compliance obligations. German manufacturers are mandating predictive maintenance protocols for auditor documentation.
- Telecom Operators:Network infrastructure managers requiring continuous uptime for service level agreements. These buyers favor vendor-managed models due to AI/ML engineering talent scarcity.
- Transportation Providers:Rail and logistics operators with geographically distributed asset estates. Japanese automotive plants are deploying edge-native telemetry for latency-critical applications.
- Facility Managers:Commercial and institutional building operators with operational expenditure constraints. These buyers are concentrating in smart building applications with cloud-based deployment preferences.
Industrial operators anchor contract value. Utilities are gaining share fastest through grid modernization procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States utilities deploy proactive services for uptime-guaranteed contracts, while German manufacturers prioritize ISO 55000 compliance documentation, and Japanese automotive plants emphasize edge-native latency reduction.
United States
Independent power producers under FERC Order 2222 mandate proactive monitoring for distributed energy resource management. OSHA process safety mandates elevate compliance complexity for automated maintenance systems. Texas and California utilities are displacing time-and-materials agreements with penalty-clause uptime contracts.
Germany
Automotive manufacturers mandate predictive maintenance protocols to satisfy ISO 55000 auditor requirements. REACH substance restrictions on industrial sensor coatings force twelve-to-eighteen-month hardware recertification timelines. Bavarian automotive paint shops and Baden-Württemberg component suppliers absorb ECHA-guided material substitution delays.
Japan
Automotive plants deploy latency-critical vibration analysis at the sensor level, bypassing cloud round-trips. METI industrial digitization frameworks accelerate edge computing procurement for mission-critical production lines. Nagoya-area automotive clusters and Kanto-region electronics manufacturers lead native proactive service adoption.
India
PLI scheme beneficiaries in Gujarat and Tamil Nadu industrial corridors represent greenfield sites without legacy SCADA entanglements. Central Electricity Authority grid modernization directives expand monitoring suite procurement. Tamil Nadu automotive component parks and Gujarat chemical processing zones enable native cloud-based deployment architectures.
China
MIIT industrial internet policies accelerate predictive maintenance adoption across state-owned manufacturing enterprises. Dual carbon goals drive energy infrastructure monitoring investments for grid efficiency optimization. Yangtze River Delta electronics manufacturers and Pearl River Delta automotive clusters deploy hybrid cloud-edge architectures for data sovereignty compliance.
Proactive Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with hyperscale cloud providers and edge-native infrastructure vendors occupying distinct competitive vectors. The market structure favors players combining telemetry hardware with algorithmic service layers over pure software or pure hardware alternatives. Strategic archetypes include cloud-anchored analytics platforms, edge-native telemetry specialists, and vertically integrated industrial automation houses. Dominant competitive moves encompass consumption-based subscription model transitions and strategic partnerships bridging OT-IT convergence requirements.
Among cloud-anchored platform providers, Microsoft Corporation exemplifies the hyperscale integration archetype through Azure-embedded predictive analytics, while Cisco Systems occupies a position within edge-native infrastructure specialists leveraging telemetry architectures for latency-sensitive deployments. IBM Corporation represents the enterprise AI services tier with Watson-driven condition assessment modules targeting regulated infrastructure operators.
| Leading Market Players |
|---|
| Juniper Networks |
| Huawei Technologies |
| Microsoft Corporation |
| DXC Technology |
| Avaya Holdings Corporation |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Fortinet |
| IBM Corporation |
| Others |
Cost & Logistics Intelligence
Performance-guaranteed uptime contracts with penalty clauses lock in multi-year revenue visibility for proactive service vendors while binding buyer procurement to certified telemetry hardware suppliers. Texas and California utilities under FERC Order 2222 mandate these structures, compressing vendor margins through risk transfer while securing semiconductor allocation priority from Taiwan-based foundries.
Pricing Analysis
Consumption-based telemetry subscriptions are displacing perpetual license models as cloud-hybrid deployments dominate new contracts. Price differentiation rests on ISO 17359 certification tier and edge processing latency capability, with latency-critical Japanese automotive commands premium positioning over standard cloud-monitoring tiers. Pricing pressure stems from hyperscale cloud providers embedding predictive analytics into base infrastructure bundles. Mid-sized manufacturing operators in Gujarat and Tamil Nadu exhibit highest price sensitivity due to PLI scheme margin constraints, while US independent power producers absorb premium pricing for uptime guarantees.
Supply Chain Analysis
Taiwan Strait transit routes underpin critical semiconductor supply for edge device manufacturers, with allocation constraints extending sensor deployment timelines. Hardware production concentrates in Taiwan, South Korea, and China, drawing from fluoropolymer and ceramic substrate inputs for sensor encapsulation. REACH substance restrictions on industrial coatings in Germany and France force twelve-to-eighteen-month recertification delays. Distribution runs through vendor-managed private cloud deployments and direct OEM integration channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment topologies creates specialist niches as buyer preference splits between edge-native latency optimization and cloud-hybrid analytical depth.
For Market Incumbents: Shield installed base relationships through backward integration into telemetry hardware production, capturing semiconductor allocation priority from Taiwan foundries. Accelerate ISO 17359 certification pipelines to compress sales cycles against emerging cloud-native entrants. Prioritize consumption-based subscription transitions to match hyperscale competitor pricing transparency. For New Entrants and Emerging Players: Anchor in India industrial corridors where PLI scheme beneficiaries lack legacy SCADA entanglements, enabling native cloud-based deployment without brownfield integration costs. Target facility managers in smart building applications with subscription-based remote monitoring, the least penetrated end-user segment with lowest competitive density. Lead with EU AI Act algorithmic transparency compliance as first-mover differentiation. For Investors and Strategic Acquirers: Edge-native telemetry specialists with multiphysics simulation heritage represent the highest-conviction acquisition archetype as digital twin convergence compresses pure machine learning vendor margins. Evaluate targets against physics-informed neural network deployment capability and aerospace component lifecycle management contract backlog. Monitor FERC Order 2222 procurement velocity as grid modernization investment inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure-embedded predictive analytics locks manufacturing equipment operators into hyperscale infrastructure ecosystems. |
| Strategic Partnership | OPC-UA translation layer alliances with legacy PLC manufacturers reduce brownfield implementation friction. |
| Acquisition of Specialist Firm | Physics-based simulation capabilities address aerospace digital twin contract requirements. |
| Geographic Expansion | Gujarat and Tamil Nadu greenfield sites enable native deployment without SCADA legacy constraints. |
| Product Launch | Interpretable model architectures capture EU AI Act algorithmic transparency mandates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Secondary validation drew from SEC filings, hyperscaler capex disclosures, FERC Order 2222 procurement databases, and ISO 17359 certification registries. Bottom-up contract value aggregation triangulated against top-down industrial digitization spend estimates.
Across the analysis window, forecasts model service type, deployment topology, application vertical, and end-user procurement modality segmentation. CAGRs derive from telemetry subscription growth trajectories and edge device shipment projections. Inputs include semiconductor allocation forecasts from Taiwan foundries and EU AI Act implementation timelines.
Material uncertainties — Taiwan Strait logistics disruption, REACH substance restriction evolution, and AI/ML engineering talent scarcity persistence — sit outside the modeled envelope. Forecasts reflect assumptions around hyperscale cloud pricing stability and grid modernization investment continuity. Practitioners should keep alternative scenarios live as FERC regulatory enforcement and ECHA guidance timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Supplier Management Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Digital Talent Acquisition Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Shared Services Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
IT Staffing Market
Enterprise Services
Enterprise A2P SMS Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Bring Your Own Device Market
Enterprise Services
Qatar Cloud Managed Services Market