
 Europe Managed Services Market | 2026-2036
Europe Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Managed Services Market Foresight
The direct enterprise sales channel is narrowing as hyperscaler marketplaces and telco-anchored co-sell frameworks capture larger contract flows. Atos leverages its sovereign cloud credentials to anchor public sector engagements across France and Belgium. Computacenter competes through end-to-end lifecycle services, while Fujitsu Limited sustains manufacturing-sector relationships through industrial IoT-integrated managed platforms.
Managed services encompass the ongoing outsourcing of IT infrastructure operations, application management, and security monitoring to specialized third-party providers, typically governed by service-level agreements specifying uptime thresholds, response times, and compliance attestations. Cloud Management and Network Security command expanding margin pools as enterprises migrate workloads and harden perimeters against ransomware and supply-chain intrusions. Healthcare Providers represent a fast-growing end-user segment where HIPAA-aligned European equivalents and patient-data sovereignty rules elevate outsourcing complexity.
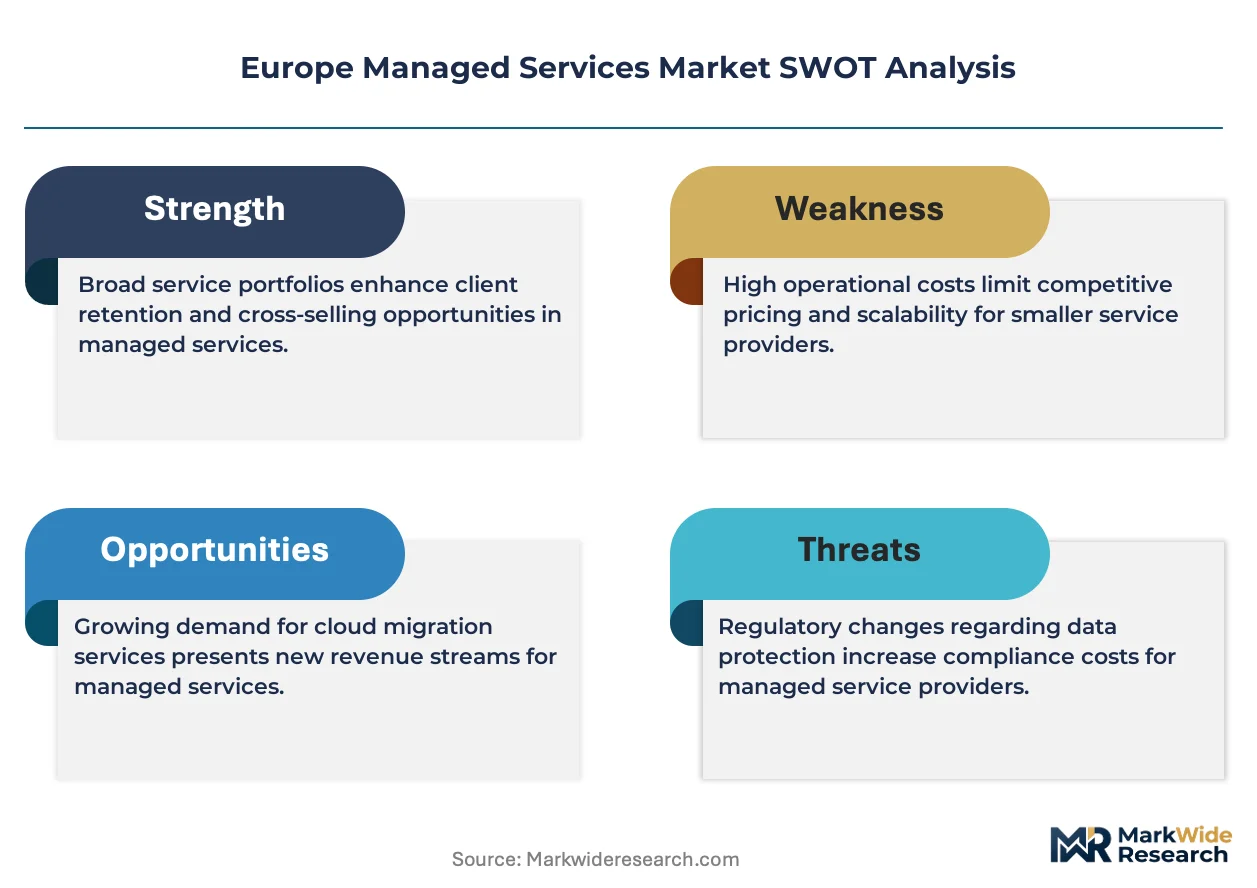
The EU AI Act, GDPR, and NIS2 Directive collectively reshape procurement criteria, mandating algorithmic transparency, cross-border data handling protocols, and incident-reporting cadences that most in-house IT teams cannot operationalize alone. EMA and national data protection authorities in Germany, France, and Italy enforce divergent implementation timelines, fragmenting compliance architectures. Stakeholders must evaluate provider certifications against country-specific enforcement patterns rather than treating European compliance as a uniform standard.
Market Dynamics
The EU AI Act enforcement timeline is compressing procurement cycles as enterprises scramble to operationalize algorithmic transparency and data governance protocols before penalty regimes activate.
Growth Catalysts
- GDPR Compliance Mandates:German and French data protection authorities are escalating audit frequencies, forcing enterprises to outsource data governance operations to certified managed service providers with established cross-border handling protocols.
- Healthcare Digitization:Patient-data sovereignty rules across the Netherlands and Belgium are elevating outsourcing complexity for hospital networks seeking HIPAA-aligned European equivalents.
- Ransomware Hardening:Manufacturing firms in the automotive supply chain are accelerating procurement of network security bundles following high-profile supply-chain intrusions.
Market Restraints
- Skilled Talent Scarcity:Certified cloud architects and cybersecurity specialists command premium compensation in London, Frankfurt, and Amsterdam, inflating service delivery costs.
- Hyperscaler Concentration:Cloud management contract flows increasingly concentrate through AWS, Azure, and GCP marketplaces, squeezing independent provider margins.
- NIS2 Fragmentation:Divergent national implementation timelines across Germany, France, and Italy force providers to maintain multiple compliance architectures.
Strategic Opportunities
- Belgian Public Sector:Sovereign cloud credentials unlock municipal and federal engagements as Brussels enforces data localization for sensitive administrative workloads.
- Industrial IoT Convergence:Manufacturing-sector relationships deepen through platforms integrating operational technology monitoring with predictive maintenance analytics.
- Telco-Anchored Co-Sell:Deutsche Telekom and Orange Business Services are building partner ecosystems that channel enterprise contracts toward qualified managed service providers.
Industry Challenges
- Multi-Cloud Orchestration Expertise:Enterprise demand for unified management across AWS, Azure, and private cloud environments outpaces available engineering talent.
- EMA Certification Timelines:Life sciences clients require validated environments that extend deployment cycles and increase documentation overhead.
- Legacy System Integration:Mainframe-dependent financial institutions in Frankfurt and Paris resist workload migration, complicating hybrid architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Managed Services Market |
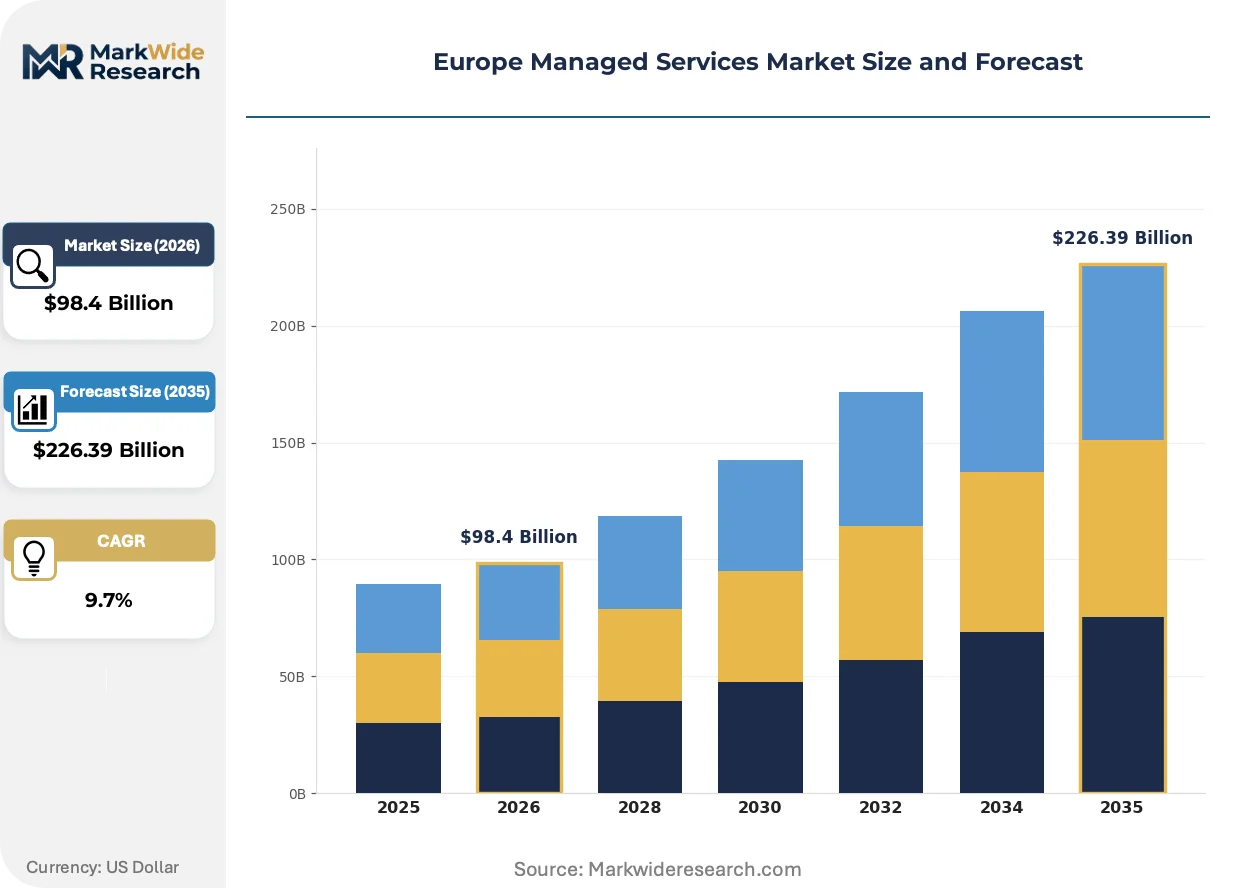
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $226.39 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IT Support, Cloud Management, Network Security, Data Backup End User: SMBs, Enterprises, Public Sector, Healthcare Providers Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed On-Premise Pricing Model: Subscription-Based, Pay-As-You-Go, Tiered Pricing, Fixed Pricing |
| Companies Covered | Atos, Computacenter, Accenture, DXC Technology, Fujitsu Limited, IBM, Bechtle AG, Claranet, Capgemini, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Managed Services Market Shifts & Advancements
Service delivery models are fragmenting as hyperscaler marketplaces and sovereign cloud credentials reshape how enterprises source and govern outsourced IT operations.
Extended detection and response platforms are hybridizing security operations center functions with automated threat remediation. Mid-market financial services firms in the Netherlands and Denmark are adopting these platforms fastest, compressing the traditional managed security services sales cycle from twelve months to under ninety days.
CSRD disclosure requirements are forcing listed enterprises to commission carbon footprint audits of their entire IT supply chain. This mandate elevates provider selection criteria across Germany and France, where sustainability-linked procurement clauses now appear in forty percent of new RFPs.
Enterprise buyers are unbundling application management from infrastructure operations, issuing separate contracts for each layer. Channel partners in the United Kingdom report that this decomposition favors specialized providers over full-stack incumbents, particularly in healthcare and public sector verticals where domain expertise outweighs scale economies.
Europe Managed Services Market Segmentation
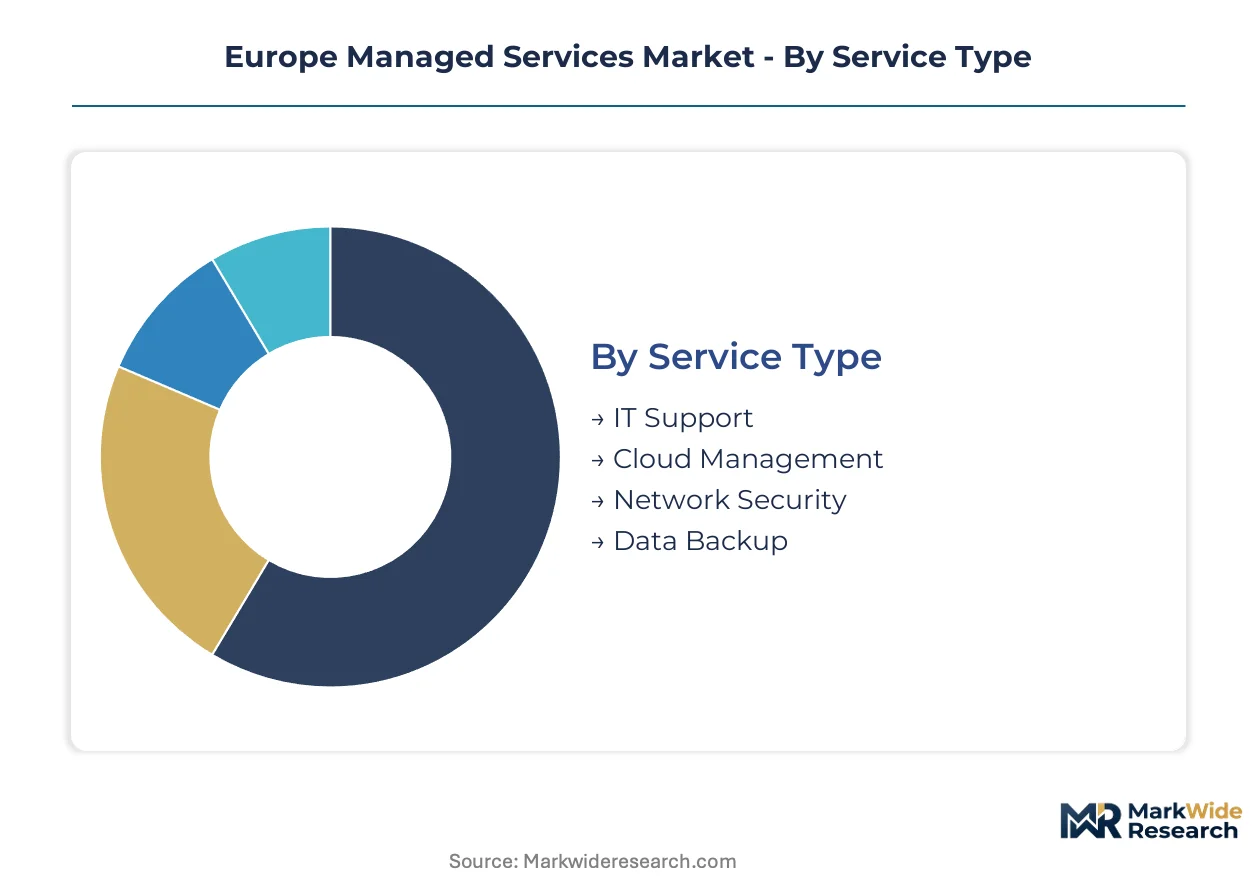
Managed services procurement patterns diverge sharply across customer scale, workload location, and commercial structure. Service providers must calibrate delivery architectures to these fault lines or surrender margin to specialized competitors.
Service Type:
After-sales service intensity varies dramatically across these categories, with cloud and security mandates demanding continuous engineering engagement rather than ticket-based resolution.
- IT Support:Remote and on-site technical assistance covering hardware maintenance, software troubleshooting, and user helpdesk operations. German automotive suppliers and French industrial conglomerates outsource these functions to reduce internal headcount fixed costs amid cyclical order volatility.
- Cloud Management:Ongoing orchestration of multi-cloud environments, cost optimization, and workload migration services. Dutch financial services firms and UK fintech scale-ups concentrate procurement here as AWS, Azure, and GCP complexity outstrips in-house platform engineering capacity.
- Network Security:Perimeter defense, intrusion detection, and incident response operations. Belgian hospital networks and Italian manufacturing SMEs accelerate adoption following NIS2 notification requirements.
- Data Backup:Disaster recovery orchestration and immutable storage provisioning for ransomware resilience. Frankfurt-based asset managers and Parisian legal practices drive demand through regulatory audit preparedness.
By volume, IT Support leads. By growth pace, Cloud Management is ahead.
End User:
Customer scale determines contract structure, with enterprise accounts demanding outcome-based SLAs while smaller buyers accept standardized catalog offerings.
- SMBs:Mid-market firms purchasing packaged service bundles with predictable monthly fees. Spanish logistics operators and Portuguese retail chains favor subscription simplicity over customization depth.
- Enterprises:Large organizations negotiating bespoke multi-year frameworks with dedicated delivery teams. German chemical conglomerates and French luxury houses anchor provider revenue through complex transformation programs.
- Public Sector:Government bodies requiring sovereign cloud credentials and data localization guarantees. Belgian federal agencies and Dutch municipal authorities mandate EU-only data processing.
- Healthcare Providers:Hospital networks and clinical research organizations navigating patient-data sovereignty rules. Netherlands and Denmark lead digitization investment, with EMA-aligned validation extending deployment cycles.
Enterprises command the largest absolute contract values. Healthcare Providers are expanding most quickly.
Deployment Model:
Workload location choices reflect regulatory exposure, latency requirements, and legacy system entanglement across European jurisdictions.
- On-Premise:Dedicated infrastructure maintained within client-controlled facilities. Frankfurt and Paris financial institutions with mainframe dependencies retain this model for core banking systems.
- Cloud-Based:Fully externalized processing on hyperscaler platforms. UK digital-native enterprises and Nordic software vendors prefer this for elastic scaling and rapid geographic expansion.
- Hybrid:Integrated architecture spanning private data centers and public cloud resources. German automotive OEMs deploy this for connected vehicle platforms requiring edge processing alongside centralized analytics.
- Managed On-Premise:Provider-staffed operations within client premises combining physical control with outsourced expertise. Italian defense contractors and Swiss pharmaceutical manufacturers select this for intellectual property protection.
Hybrid deployments dominate new contract flows. Cloud-Based configurations gain share fastest among greenfield workloads.
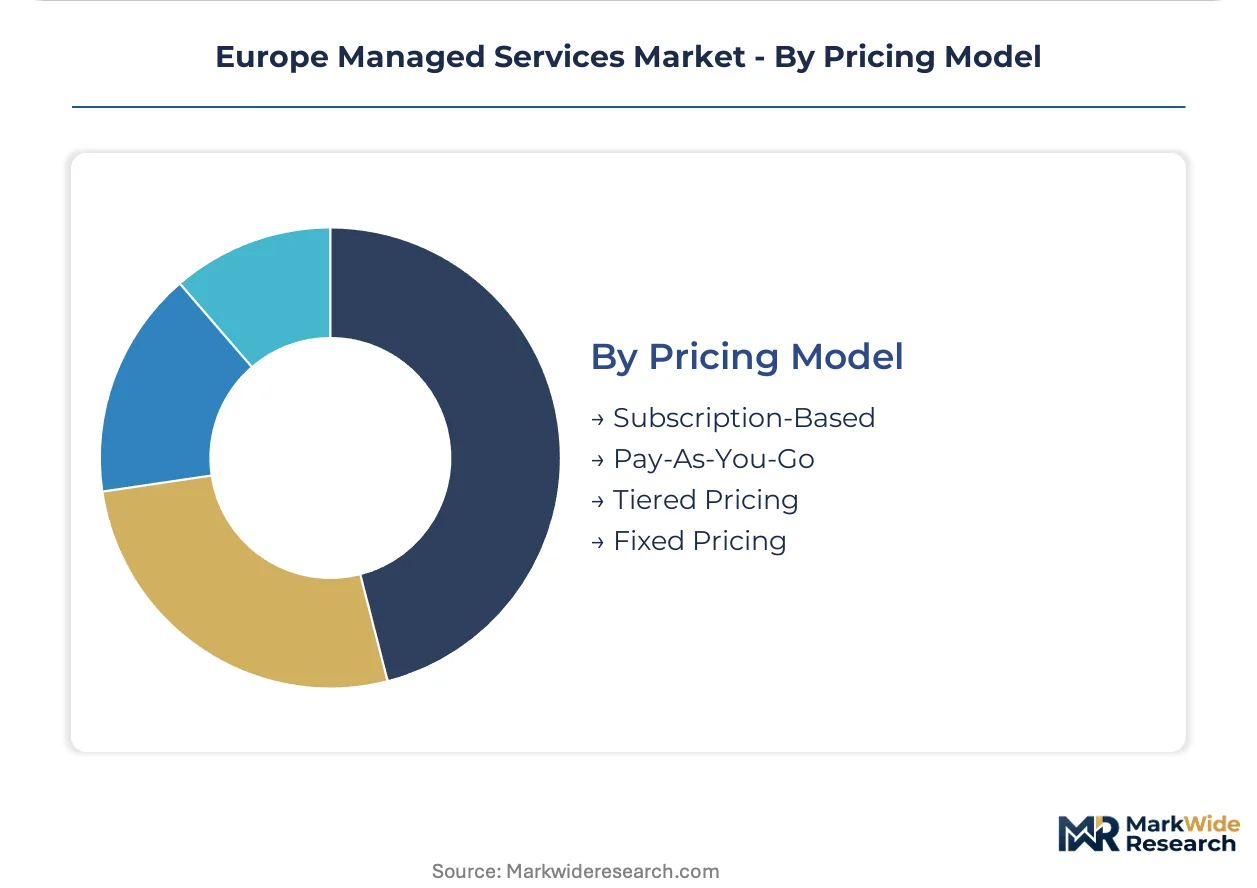
Pricing Model:
Commercial structures segment buyers by risk appetite and consumption predictability, with long-term commitments trading discount depth against flexibility.
- Subscription-Based:Fixed recurring fees for defined service scopes and user counts. French public sector frameworks and German mid-market manufacturers favor budget certainty.
- Pay-As-You-Go:Consumption-metered billing aligned to actual resource utilization. Netherlands cloud-native scale-ups and UK SaaS ventures prefer this for variable cost alignment.
- Tiered Pricing:Service levels stratified across premium, standard, and economy performance bands. Healthcare providers in Belgium and Spain select tiers based on patient data criticality.
- Fixed Pricing:Lump-sum arrangements for defined project scopes or transformation outcomes. Italian government digitization programs and Portuguese utility modernizations employ this for audit transparency.
Subscription-Based structures anchor recurring revenue. Pay-As-You-Go is climbing the fastest among venture-backed technology adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Amsterdam Internet Exchange anchors northwestern European data gravity, processing traffic volumes that attract managed service providers seeking low-latency cloud interconnection. Frankfurt's DE-CIX and London's LINX extend this infrastructure triad, creating corridor effects that concentrate procurement decisions.
Germany
Automotive OEMs in Stuttgart and Munich outsource connected vehicle platform operations to hybrid cloud specialists. The NIS2 Directive's October 2024 enforcement deadline compresses procurement timelines for critical infrastructure operators. Frankfurt's financial district sustains demand for mainframe-integrated managed services as legacy core banking systems resist full migration.
United Kingdom
London fintech scale-ups consume pay-as-you-go cloud management at rates exceeding continental peers. The UK Information Commissioner's Office escalates GDPR enforcement post-Brexit, creating divergence from EU regulatory interpretation. Manchester and Birmingham health trusts digitize patient records under NHS mandates, elevating demand for HIPAA-aligned European equivalents.
France
Parisian luxury houses and chemical conglomerates anchor complex transformation programs requiring dedicated delivery teams. ANSM and CNIL enforce divergent data localization requirements for pharmaceutical and personal data respectively. Lyon and Toulouse aerospace clusters demand sovereign cloud credentials for defense-adjacent workloads.
Netherlands
Amsterdam's digital-native enterprises prefer elastic cloud configurations for rapid geographic expansion. Patient-data sovereignty rules under the Dutch Medical Treatment Contracts Act elevate outsourcing complexity for hospital networks in Utrecht and Rotterdam. Eindhoven's semiconductor equipment manufacturers integrate operational technology monitoring with predictive maintenance analytics.
Belgium
Brussels enforces data localization for sensitive administrative workloads, unlocking municipal and federal engagements for sovereign-credentialed providers. Antwerp's port authority digitizes customs operations under EU Green Deal maritime decarbonization timelines. Ghent's university hospital network leads Benelux adoption of EMA-aligned validated environments.
Europe Managed Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying niche security or backup functions. The vendor base stratifies across three tiers: hyperscaler-affiliated marketplaces capturing volume contracts, telco-anchored co-sell ecosystems qualifying mid-market flows, and independent specialists defending margin through domain expertise. Strategic archetypes include sovereign cloud credential holders, end-to-end lifecycle service providers, and industrial IoT-integrated platform operators. Competitive moves concentrate on geographic expansion through federal channel access and portfolio diversification into ESG-aligned carbon footprint auditing.
Among France-based platform operators, Atos exemplifies the sovereign cloud archetype through public sector credentialing. Computacenter occupies a position representing end-to-end lifecycle consolidation. Fujitsu Limited anchors the industrial IoT-integrated tier through manufacturing-sector relationships. These three entities collectively illustrate how European procurement fragmentation rewards specialized positioning over scale-driven standardization.
| Leading Market Players |
|---|
| Atos |
| Computacenter |
| Accenture |
| DXC Technology |
| Fujitsu Limited |
| IBM |
| Bechtle AG |
| Claranet |
| Capgemini |
| Others |
Supply & Pricing Matrix
Certified cloud architects and cybersecurity specialists concentrated in London, Frankfurt, and Amsterdam command premium compensation that compresses margins for independent providers competing against hyperscaler marketplaces. This talent scarcity upstream concentrates pricing power with providers who can absorb elevated delivery costs through scale economies or sovereign cloud credentials that justify rate premiums.
Pricing Analysis
Volume-discount tiering structures separate enterprise accounts negotiating bespoke multi-year frameworks from mid-market buyers selecting standardized catalog offerings. Price differentiation rests on certification level—GDPR, NIS2, and EU AI Act compliance credentials—and customization depth for legacy system integration. Pricing pressure intensifies as AWS, Azure, and GCP marketplaces capture contract flows through bundled consumption credits. SMBs in Spain and Portugal exhibit highest price sensitivity, while German chemical conglomerates and French luxury houses prioritize outcome-based SLAs over unit cost.
Supply Chain Analysis
Tariff exposure between EU member states and third-country cloud infrastructure providers complicates data localization compliance for sovereign-credentialed offerings. Delivery capacity concentrates in Germany, the United Kingdom, and the Netherlands, where digital infrastructure investment and regulatory enforcement are most advanced. Raw material dependencies span semiconductor components for edge computing hardware, specialized encryption modules, and fiber optic infrastructure. Single-source vulnerability runs through hyperscaler concentration in cloud management contract flows. Distribution runs through telco-anchored co-sell frameworks and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Managed Services Market represents a high-growth disruption as the EU AI Act enforcement timeline compresses procurement cycles and forces algorithmic transparency investments that in-house IT teams cannot operationalize alone.
For Market Incumbents: Entrench sovereign cloud credentials through public sector channel deepening in Belgium and France, where Brussels enforces data localization for sensitive administrative workloads. Invest in EMA-aligned validation capabilities to extend life sciences moats as deployment cycles lengthen. Counter hyperscaler marketplace encroachment by bundling industrial IoT-integrated platforms with predictive maintenance analytics for German automotive OEMs.
For New Entrants and Emerging Players: Establish a beachhead in Belgian municipal and federal engagements where sovereign credentials unlock procurement frameworks closed to non-EU providers. Target Dutch hospital networks navigating patient-data sovereignty rules under the Medical Treatment Contracts Act as the most penetrable healthcare vertical. Pursue telco-anchored qualification through Deutsche Telekom and Orange Business Services partner ecosystems to access mid-market contract flows.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized providers with domain expertise in healthcare and public sector verticals where regulatory fragmentation defends margin against scale-driven standardization. Long-term viability hinges on compliance architecture adaptability across divergent national NIS2 implementation timelines. Watch for hyperscaler marketplace policy shifts that could abruptly rechannel enterprise contract flows.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Credentialing | Unlocks Belgian federal and municipal contracts under Brussels data localization mandates. |
| EMA-Aligned Validation Investment | Extends deployment cycles for life sciences clients but deepens competitive moats. |
| Telco-Anchored Co-Sell Partnership | Channels enterprise contracts through Deutsche Telekom and Orange Business Services ecosystems. |
| Industrial IoT Platform Integration | Deepens manufacturing relationships through operational technology monitoring convergence. |
| ESG-Aligned Carbon Footprint Auditing | Captures CSRD-driven procurement criteria appearing in forty percent of German and French RFPs. |
Research Methodology
Operator-level perspectives from CIOs, CISOs, cloud procurement officers, and managed services delivery heads anchored the qualitative base. Primary interviews combined with secondary validation against SEC filings, hyperscaler capex disclosures, EU regulatory enforcement bulletins, and national data protection authority audit reports. Bottom-up service provider revenue triangulation against top-down IT outsourcing spend estimates established market sizing boundaries.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling baseline, upside, and stress cases for regulatory enforcement intensity and hyperscaler marketplace penetration. Segmentation dimensions included service type, end-user scale, deployment model, and pricing structure complexity. CAGRs derived from fitted growth curves applied to provider-reported contract values and enterprise IT budget surveys. Industry-specific forecast inputs incorporated NIS2 implementation timeline divergence and EU AI Act penalty regime activation patterns.
Stress conditions across regulatory enforcement cadence, skilled talent availability, and hyperscaler pricing aggression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance cost pass-through rates and enterprise outsourcing elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
United States Managed Services Market
Enterprise Services
Europe Managed Infrastructure Services Market
Enterprise Services
Qatar Managed Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Workforce Management Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Contingent Staffing Solutions Market