
 Middle East and Africa IT Services Market | 2026-2036
Middle East and Africa IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa IT Services Market Foresight
Market Context
GDPR-equivalent data sovereignty frameworks across the Gulf Cooperation Council is consolidating compliance costs for foreign entrants while privileging localized joint ventures. Microsoft Corporation leverages its hyperscale cloud footprint and local datacenter certifications to sustain enterprise renewal rates across Saudi and Emirati government accounts. SAP SE anchors its position through deep ERP installations in oil and gas conglomerates that now require cloud migration pathways. Accenture plc competes on transformation consulting tied to national diversification visions, particularly in Saudi Arabia's Public Investment Fund portfolio companies.
Technical Definition and Structural Segments
Middle East and Africa IT Services encompass the design, implementation, management, and optimization of information technology infrastructure, software applications, and digital workflows across enterprise and government environments, typically delivered through service-level agreements specifying uptime, response time, and security compliance parameters. Cloud Services leads segment value as Gulf states mandate sovereign data residency, while Managed Services captures expanding margin pools from long-term operational contracts in healthcare and education sectors where local technical talent remains scarce. Hybrid Cloud deployment models dominate procurement specifications among financial institutions seeking to partition regulated workloads between on-premises cores and public edge capacity.
Regulatory Frame and Outlook
Saudi Arabia's National Cybersecurity Authority, the UAE's Telecommunications and Digital Government Regulatory Authority, and South Africa's Information Regulator collectively shape market access through divergent certification regimes and data localization mandates that fragment vendor operating models. Egypt's personal data protection law and Nigeria's data protection regulation add compliance layers that favor regional specialists with established legal navigation capabilities. Stakeholders must monitor accelerating divergence between Gulf data sovereignty requirements and sub-Saharan African frameworks as cloud providers weigh unified versus federated infrastructure strategies.
Market Dynamics
Gulf Cooperation Council cloud-first mandates and Saudi Arabia's National Data Management Office standards are compressing procurement timelines while elevating data sovereignty compliance to a primary vendor selection criterion.
Growth Catalysts
- Hybrid Cloud Mandates:Financial institutions across the United Arab Emirates now partition regulated workloads between on-premises cores and public edge capacity, expanding systems integration contracts.
- Saudi Vision 2030:Public Investment Fund portfolio companies are accelerating ERP cloud migration pathways, creating concentrated demand for transformation consulting.
- Smart City Infrastructure:Dubai's integrated municipal platforms and Abu Dhabi's AI strategy generate sustained contract flows for managed service providers specializing in IoT and analytics.
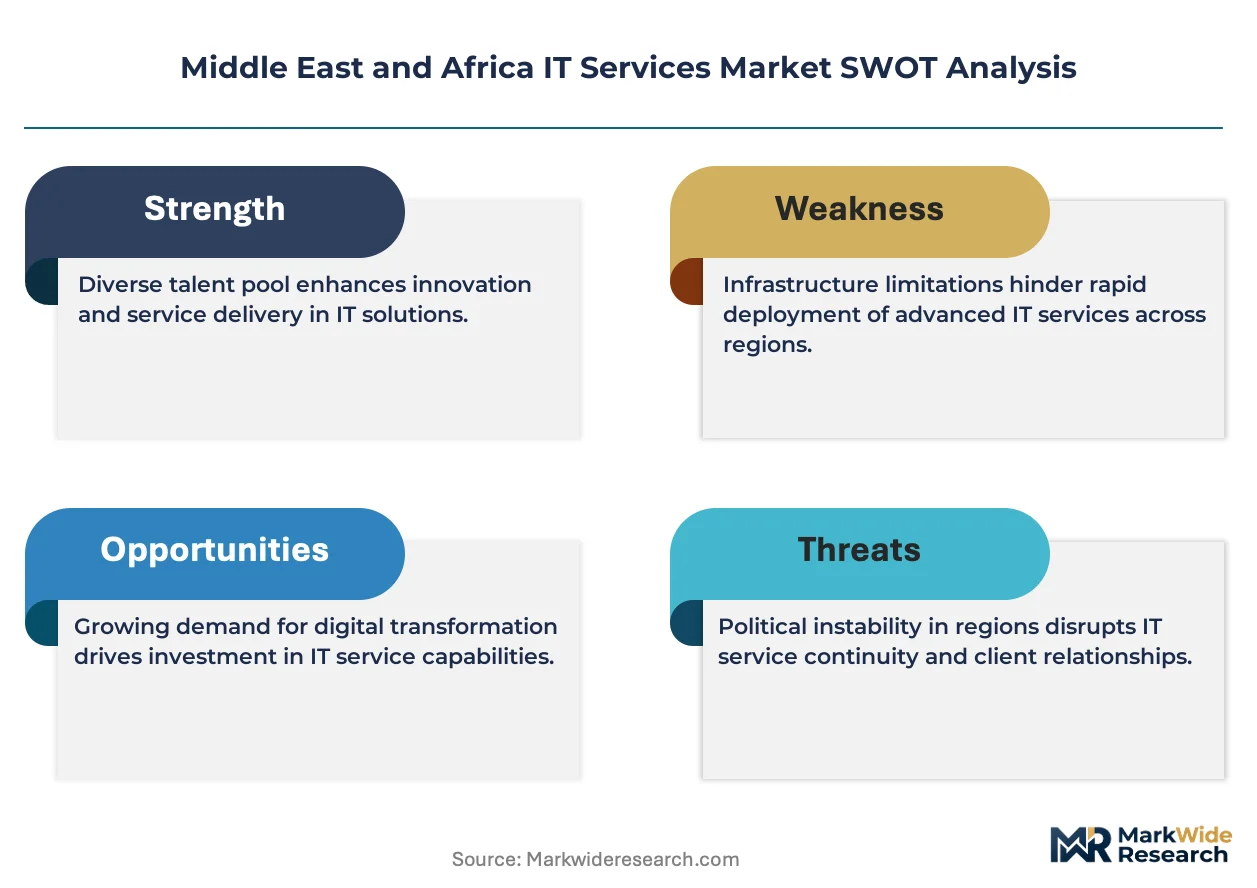
Market Restraints
- Certification Fragmentation:Divergent data localization mandates between Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority inflate vendor compliance costs.
- Technical Talent Scarcity:Healthcare and education sectors face acute shortages of local cybersecurity and cloud architecture specialists, constraining service delivery scale.
- Input Cost Volatility:Specialized data center construction materials and imported networking equipment face price instability due to supply chain concentration in East Asian manufacturing hubs.
Strategic Opportunities
- Egypt Data Protection:The country's personal data protection law creates compliance service white space for regional specialists with established legal navigation capabilities.
- Nigeria Regulatory Expansion:Data protection regulation implementation opens managed security service opportunities in West African banking and telecommunications.
- AI-Governance Convergence:Integration of machine learning operations with sovereign cloud frameworks enables new service tiers for government and defense clients across the Gulf.
Industry Challenges
- Multi-Cloud Integration Complexity:Enterprises struggle to harmonize legacy SAP installations with modern containerized workloads, extending project timelines and eroding margin predictability.
- Certification Timeline Compression:Accelerated regulatory deadlines for National Cybersecurity Authority compliance force rushed vendor assessments and elevated implementation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa IT Services Market |
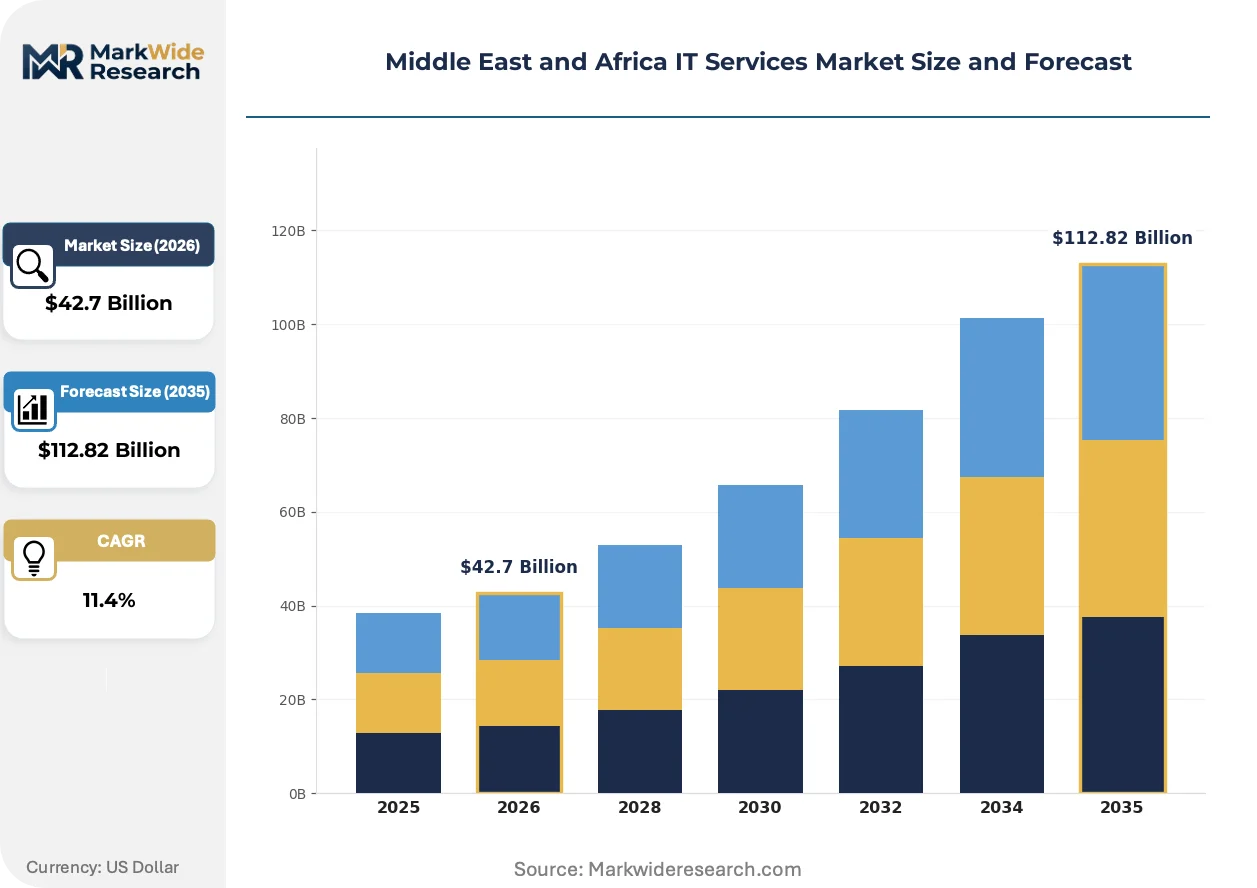
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $112.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Services, Managed Services, Consulting Services, Support Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-premises End User: Government, Healthcare, Retail, Education Technology: AI, Blockchain, IoT, Big Data |
| Companies Covered | Microsoft Corporation, SAP SE, Accenture plc, STC Solutions, Tata Consultancy Services Limited, International Business Machines Corporation (IBM), Amazon Web Services, Inc., e&, Oracle Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa IT Services Market Shifts & Advancements
Artificial intelligence operations platforms and sovereign cloud architectures are restructuring how Gulf enterprises procure, deploy, and govern IT infrastructure across hybrid environments.
Generative AI coding assistants are automating routine software development tasks across Saudi and Emirati financial services firms, compressing delivery timelines for custom application builds. Mid-tier banks deploy these tools for legacy COBOL modernization and API layer generation. The technology is automating substantial portions of the systems integration value chain, pressuring traditional body-shop margins.
Saudi Arabia's National Data Management Office standards now require government contractors to demonstrate certified data residency controls, forcing hyperscale providers to expand in-kingdom infrastructure footprints. Compliance audits have intensified for cloud service providers seeking renewal of Public Investment Fund-adjacent contracts. Healthcare and education procurement specifications increasingly embed these standards as mandatory evaluation criteria.
Subscription-based managed service contracts are displacing traditional time-and-materials arrangements in UAE healthcare and education sectors where internal technical capacity remains thin. Long-term operational agreements with guaranteed uptime and response time parameters now dominate RFP structures. This pattern is most pronounced in Dubai's health authority digitization programs and Abu Dhabi's federal school network modernization.
Middle East and Africa IT Services Market Segmentation
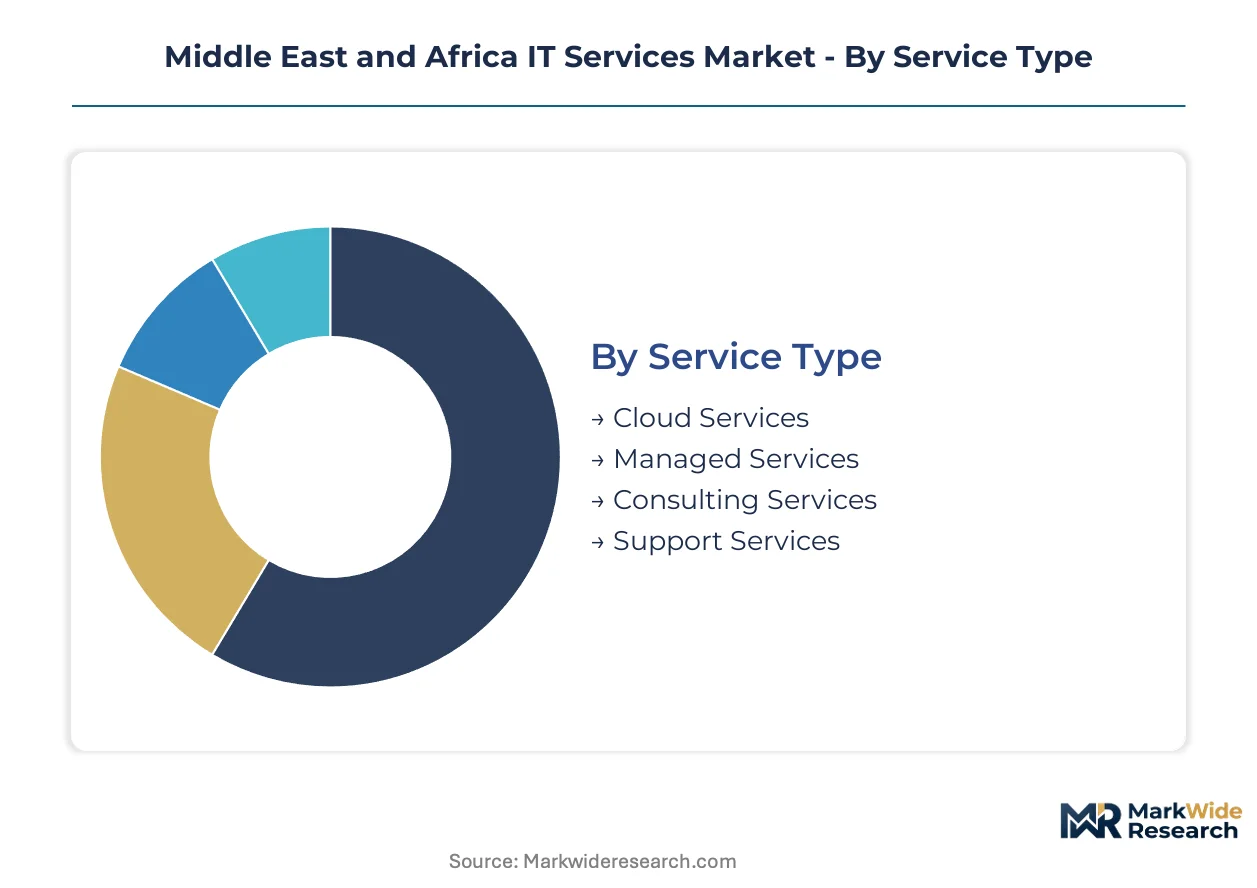
Segmentation in the Middle East and Africa IT Services Market reveals how procurement specifications diverge across certification regimes, deployment architectures, and sector-specific compliance burdens. Understanding these divides enables vendors to align capability investments with contract flow concentration.
Service Type:
Cloud Services and Managed Services carry distinct certification obligations under Saudi Arabia's National Cybersecurity Authority and the UAE's Telecommunications and Digital Government Regulatory Authority, while Consulting and Support Services face lighter sovereign data residency requirements.
- Cloud Services:Encompass infrastructure-as-a-service, platform-as-a-service, and software-as-a-service delivered through sovereign data centers certified for government access. Saudi Arabia's National Data Management Office mandates now require in-kingdom infrastructure for Public Investment Fund-adjacent contracts, compressing vendor qualification timelines.
- Managed Services:Long-term operational contracts specifying uptime, response time, and security compliance parameters dominate UAE healthcare and education procurement. Dubai's health authority digitization programs favor subscription-based arrangements over time-and-materials structures where internal technical capacity remains scarce.
- Consulting Services:Transformation advisory tied to national diversification visions, particularly ERP cloud migration pathway design for oil and gas conglomerates.
- Support Services:Technical helpdesk and maintenance contracts for legacy system estates, concentrated in Egyptian and Nigerian banking sectors.
Leading the category by volume: Cloud Services. Growing fastest: Managed Services.
Deployment Model:
Cost tier differentiation separates premium sovereign-certified deployments from standard commercial offerings, with hybrid configurations commanding intermediate pricing.
- Hybrid Cloud:Partitioning regulated workloads between on-premises cores and public edge capacity dominates financial institution procurement in the United Arab Emirates. Systems integrators capture expanded contract values from orchestration complexity.
- Private Cloud:Dedicated infrastructure meeting Saudi Arabia's National Data Management Office standards for government and defense clients. Compliance audits have intensified for hyperscale providers seeking renewal of sovereign contracts.
- Public Cloud:Shared multi-tenant infrastructure suitable for non-regulated workloads in retail and commercial banking.
- On-premises:Legacy core systems retention in Saudi oil and gas conglomerates requiring gradual cloud migration pathways.
Highest margin concentration: Hybrid Cloud. Steepest expansion trajectory: Private Cloud.
End User:
Application intensity varies sharply across sectors, with government and healthcare procurement embedding mandatory data residency controls absent from retail specifications.
- Government:National cybersecurity authority certifications and sovereign cloud mandates reshape vendor selection criteria across Gulf Cooperation Council states. Saudi Arabia's cloud-first directives compress procurement timelines while elevating compliance to primary evaluation weight.
- Healthcare:Dubai's health authority digitization programs and Abu Dhabi's federal hospital networks drive managed service contract flows where local cybersecurity specialists remain scarce.
- Retail:E-commerce platform modernization and customer analytics deployment, concentrated in UAE and Saudi urban centers.
- Education:Abu Dhabi's federal school network modernization generates sustained demand for guaranteed-uptime operational agreements.
Largest contract scale: Government. Gaining share fastest: Healthcare.
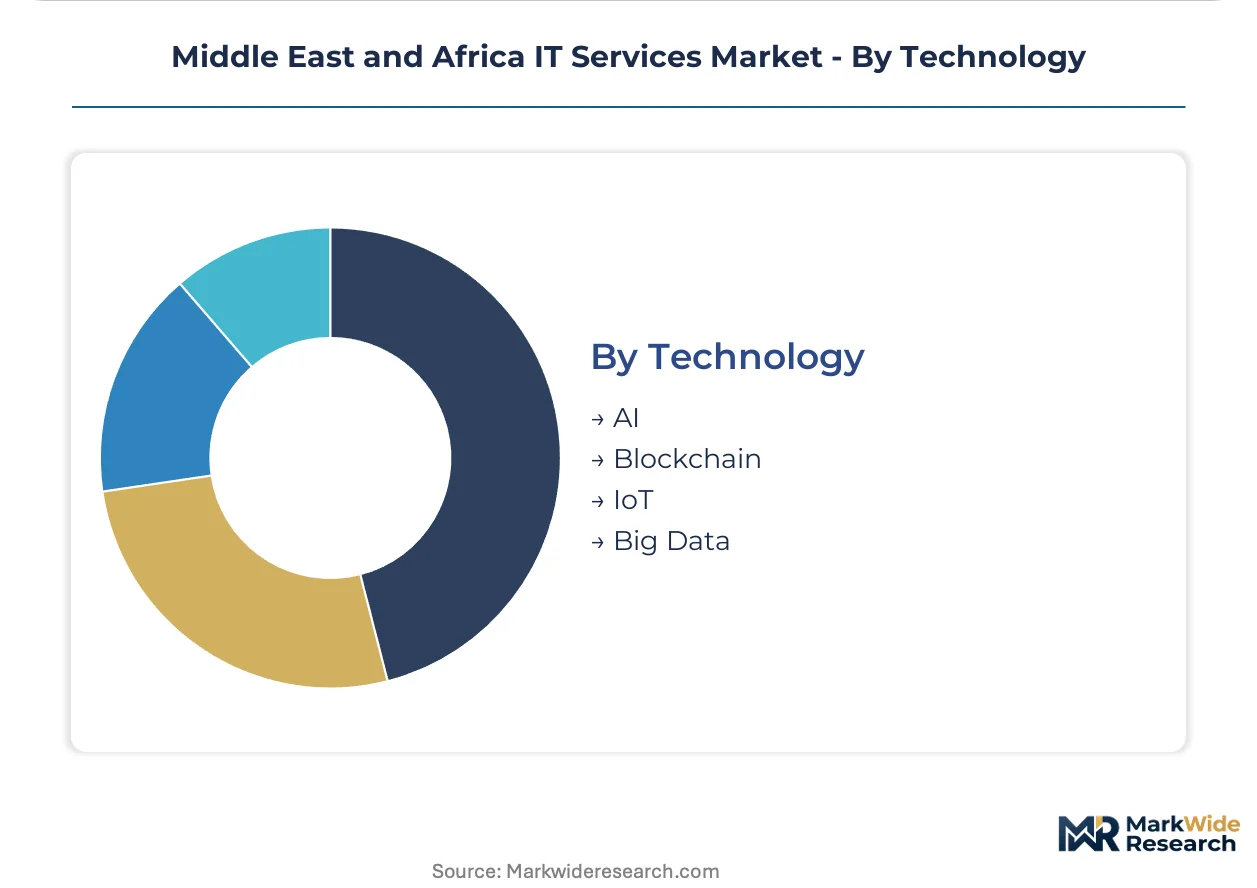
Technology:
Maturity stage determines implementation risk profiles, with AI and IoT deployments requiring specialized integration expertise absent from commoditized Big Data offerings.
- AI:Machine learning operations platforms and generative coding assistants automating software development tasks across Saudi and Emirati financial services firms. Abu Dhabi's national AI strategy creates concentrated demand for governance-integrated deployments.
- IoT:Smart city sensor networks and municipal platform integration, anchored in Dubai's integrated infrastructure programs.
- Big Data:Analytics layer deployment for oil and gas operational intelligence and retail customer segmentation.
- Blockchain:Supply chain traceability and trade finance applications in UAE logistics and banking corridors.
Deepest enterprise penetration: Big Data. Climbing the fastest: AI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's King Abdullah Economic City and the UAE's Dubai Internet City anchor regional IT services concentration through tax incentives and regulatory sandboxes that compress vendor establishment timelines.
United Arab Emirates
Dubai's smart city initiatives and Abu Dhabi's AI strategy generate sustained contract flows for managed service providers. The Telecommunications and Digital Government Regulatory Authority mandates sovereign data residency certifications for government cloud contracts. Dubai Health Authority digitization programs concentrate demand in healthcare operational technology.
Saudi Arabia
Public Investment Fund portfolio companies accelerate ERP cloud migration pathways, creating concentrated demand for transformation consulting. The National Data Management Office standards require in-kingdom infrastructure for sovereign contracts. Riyadh's financial district and NEOM Northwest development zone drive hyperscale data center investments.
South Africa
Johannesburg's banking sector and Cape Town's fintech cluster sustain enterprise software integration demand. The Information Regulator's data protection enforcement creates compliance service opportunities. Gauteng province concentrates cybersecurity consulting contracts for regional financial institutions.
Egypt
Cairo's public sector digitization and Alexandria's logistics technology upgrades expand systems integration markets. The personal data protection law creates compliance service white space for regional specialists. New Administrative Capital construction embeds smart city infrastructure procurement.
Nigeria
Lagos banking corridors and Abuja federal government networks drive managed security service demand. Data protection regulation implementation opens contract opportunities in West African telecommunications. Lagos Island commercial district anchors fintech platform modernization spending.
Middle East and Africa IT Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service delivery models. The vendor base clusters into three tiers: hyperscale cloud providers with sovereign certifications, regional systems integrators with local regulatory expertise, and global consultancies anchoring transformation advisory. Market consolidation accelerates through strategic partnerships between foreign technology vendors and domestic data center operators. Portfolio diversification into AI-governance integration represents the dominant competitive move.
Among hyperscale providers, Microsoft Corporation and Amazon Web Services, Inc. exemplify the certification-heavy archetype required for Gulf government contracts. SAP SE occupies a position within the enterprise application tier, anchoring ERP migration pathways for oil and gas conglomerates. Accenture plc sits within the transformation consulting segment, leveraging national diversification visions to secure Public Investment Fund-adjacent engagements.
| Leading Market Players |
|---|
| Microsoft Corporation |
| SAP SE |
| Accenture plc |
| STC Solutions |
| Tata Consultancy Services Limited |
| International Business Machines Corporation (IBM) |
| Amazon Web Services, Inc. |
| e& |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Cybersecurity and cloud architecture specialists concentrated in the UAE and Saudi Arabia drive labor-cost differentials that widen pricing-tier spreads between sovereign-certified deployments and standard commercial offerings. Gulf Cooperation Council data localization mandates compress vendor qualification timelines while elevating compliance premiums for in-kingdom infrastructure delivery.
Pricing Analysis
Lead-time compression commands premium positioning, with hyperscale providers charging substantial markups for expedited National Cybersecurity Authority certification timelines versus standard six-month qualification windows. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth, with sovereign-cloud contracts carrying 40-60 percent cost premiums over multi-tenant alternatives. Price differentiation rests on audit depth and data residency guarantees rather than compute performance alone. Cost compression in the mid-tier is intensifying because regional systems integrators are bundling managed services to offset commoditized infrastructure margins. Government and defense clients show least price sensitivity, while mid-market retail banks negotiate hardest on per-seat licensing.
Supply Chain Analysis
Freight cost volatility for specialized networking equipment from East Asian manufacturing hubs feeds into total cost of ownership calculations for Saudi data center construction projects. Hardware supply concentrates in China, South Korea, and Taiwan for server components, while software licensing flows from US and European headquarters operations. Raw material dependencies span advanced semiconductors, specialized cooling systems, and fiber-optic cabling. Single-source vulnerability around certified encryption hardware creates procurement bottlenecks for National Data Management Office-compliant deployments. Distribution runs through Dubai Internet City logistics clusters for UAE and re-export markets, with direct Riyadh channels serving Saudi sovereign contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where hyperscale providers are pursuing captive data center construction to lock in sovereign-cloud margins. Control over in-kingdom infrastructure assets represents the decisive upstream lever separating premium-tier vendors from margin-pressured resellers.
For Market Incumbents: To counter margin erosion from generative AI coding assistants automating routine integration tasks, Microsoft Corporation and Amazon Web Services must deepen certification moats through accelerated National Cybersecurity Authority audit pipelines. SAP SE should anchor ERP cloud migration pathways with captive professional services capacity in Riyadh and Dubai. Vertical integration into sovereign data center operations preserves renewal pricing power against regional specialist challengers. For New Entrants and Emerging Players: Enter via Egypt's personal data protection law compliance services, where legal navigation capabilities outrank technical scale in procurement evaluations. Nigeria's data protection regulation implementation in West African banking corridors offers the most penetrable geography for managed security service buildouts. STC Solutions and e& demonstrate that joint-venture structures with hyperscale providers accelerate credential acquisition without capital-heavy infrastructure commitment. For Investors and Strategic Acquirers: Re-rating potential sits with regional systems integrators possessing established National Data Management Office audit relationships given accelerating Public Investment Fund portfolio company cloud mandates. Long-term viability across the analysis window favors specialists with hybrid cloud orchestration expertise over pure-play resellers. Acquisition target archetype: UAE-based healthcare managed service providers with guaranteed-uptime contract structures. Signal to watch: hyperscale provider capex allocation toward additional Saudi in-kingdom zones.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | National Cybersecurity Authority compliance unlocks Public Investment Fund-adjacent contract flows in Saudi Arabia. |
| AI-Governance Integration | Machine learning operations platforms embedded with Saudi data residency controls capture government and defense premiums. |
| Managed Service Subscription Conversion | Guaranteed-uptime contracts displace time-and-materials structures in UAE healthcare digitization programs. |
| Regional Specialist Acquisition | Egyptian and Nigerian compliance service providers offer established legal navigation capabilities for data protection frameworks. |
| Hybrid Cloud Orchestration Capability | Partitioning regulated workloads between on-premises cores and public edge capacity commands systems integration premiums in UAE financial services. |
Research Methodology
SEC filings from hyperscale cloud providers, Saudi National Data Management Office regulatory bulletins, and UAE Telecommunications and Digital Government Regulatory Authority certification databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with CIOs at Gulf Cooperation Council financial institutions, procurement officers at Saudi Public Investment Fund portfolio companies, and managed service directors at Dubai Health Authority digitization programs validated demand assumptions and contract flow timing. Bottom-up and top-down triangulation cross-checked vendor revenue disclosures against public sector procurement award notices.
Bottom-up modeling aggregated individual contract values across service type, deployment model, and end-user segments, while top-down analysis tracked aggregate hyperscale capex allocation to Middle East and Africa zones. Segmentation dimensions modeled encompassed service delivery mode, certification tier, organization scale, vertical compliance burden, and regional regulatory cluster. CAGRs were derived from weighted-average growth assumptions across these dimensions, with cloud migration velocity and sovereign mandate implementation pace serving as primary forecast inputs.
Revisions become necessary when National Cybersecurity Authority certification timelines compress further or when Gulf data sovereignty requirements diverge from sub-Saharan African frameworks. Forecasts reflect assumptions around Public Investment Fund cloud-first adherence and UAE smart city procurement continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Employee Engagement Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Shared Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Global Managed Infrastructure Service Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Proactive Services Market