
 Enterprise Collaboration Service Market | 2026-2036
Enterprise Collaboration Service Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Collaboration Service Market Intelligence
Enterprise-grade security certification is unwinding legacy procurement patterns across the collaboration stack. Microsoft Corporation leverages its Azure sovereign cloud architecture to anchor public-sector deployments across European data-residency zones. Cisco Systems, Inc. competes through hardened Webex infrastructure that meets FedRAMP and NATO classification requirements. Zoom Video Communications, Inc. differentiates via specialized hardware-as-a-service bundles for hybrid courtroom and clinical environments.
Enterprise Collaboration Service denotes integrated software platforms enabling real-time messaging, document co-authoring, video conferencing, and workflow orchestration across distributed organizational boundaries, typically delivered through multi-tenant cloud architectures with sub-150 millisecond latency SLAs. These systems serve commercial and governmental users by collapsing email-thread fragmentation into persistent, searchable digital workspaces governed by role-based access controls. Cloud-based deployment leads absolute spending as financial institutions and government agencies retire on-premises Exchange and SharePoint estates. Video Conferencing as a service type captures disproportionate margin expansion due to dedicated room-system hardware attach rates and managed services overlays. Workflow Automation trails in current revenue share but posts the fastest growth trajectory as manufacturing units embed collaboration triggers directly into ERP and MES production sequences.
FDA 21 CFR Part 11 electronic records requirements shape collaboration product roadmaps for life-sciences adopters by mandating audit-trail immutability and digital-signature validation. The EU AI Act and GDPR jointly constrain training-data practices for generative features embedded in productivity suites, forcing providers to deploy regionally isolated inference clusters. NIST cybersecurity framework alignment has become a non-negotiable procurement filter for US federal contractors. Stakeholders must monitor whether emerging quantum-resistant encryption standards trigger premature infrastructure refresh cycles before current depreciation schedules conclude.
Market Dynamics
Enterprise collaboration infrastructure is bifurcating between sovereign-hosted stacks and hyperscale multi-tenant platforms as data-residency mandates harden procurement criteria across regulated industries.
Growth Catalysts
- FDA 21 CFR Part 11:Life-sciences organizations must deploy audit-trail immutable platforms with digital-signature validation, forcing systematic replacement of legacy document-management systems.
- Industrial Mittelstand modernization:German mid-market manufacturers are retiring on-premises Exchange estates for cloud-native alternatives that embed directly into ERP production sequences.
- Teleconsultation platform expansion:Healthcare providers require secure messaging architectures with sub-150 millisecond latency SLAs for remote clinical workflows.
Market Restraints
- Quantum-resistant encryption refresh cycles:Premature infrastructure replacement threatens depreciation schedules before current hardware reaches end-of-life.
- EU AI Act training-data constraints:Regionally isolated inference clusters impose redundant compute overhead for generative feature deployment.
- FedRAMP certification timelines:Federal contractors face 12-18 month approval windows that compress competitive windows for new entrants.
Strategic Opportunities
- Workflow Automation convergence:Manufacturing units embedding collaboration triggers into MES production sequences represent the fastest-expanding service type.
- Hybrid courtroom hardware bundles:Specialized room-system as-a-service models capture disproportionate margin expansion through managed services overlays.
- GDPR-compliant sovereign clouds:European data-residency zones create protected competitive terrain for regionally anchored providers.
Industry Challenges
- Role-based access control complexity:Financial institutions migrating from legacy SharePoint estates struggle to replicate granular permission architectures in multi-tenant environments.
- NIST framework alignment:Cybersecurity procurement filters demand continuous compliance monitoring that strains mid-market IT operational capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Collaboration Service Market |
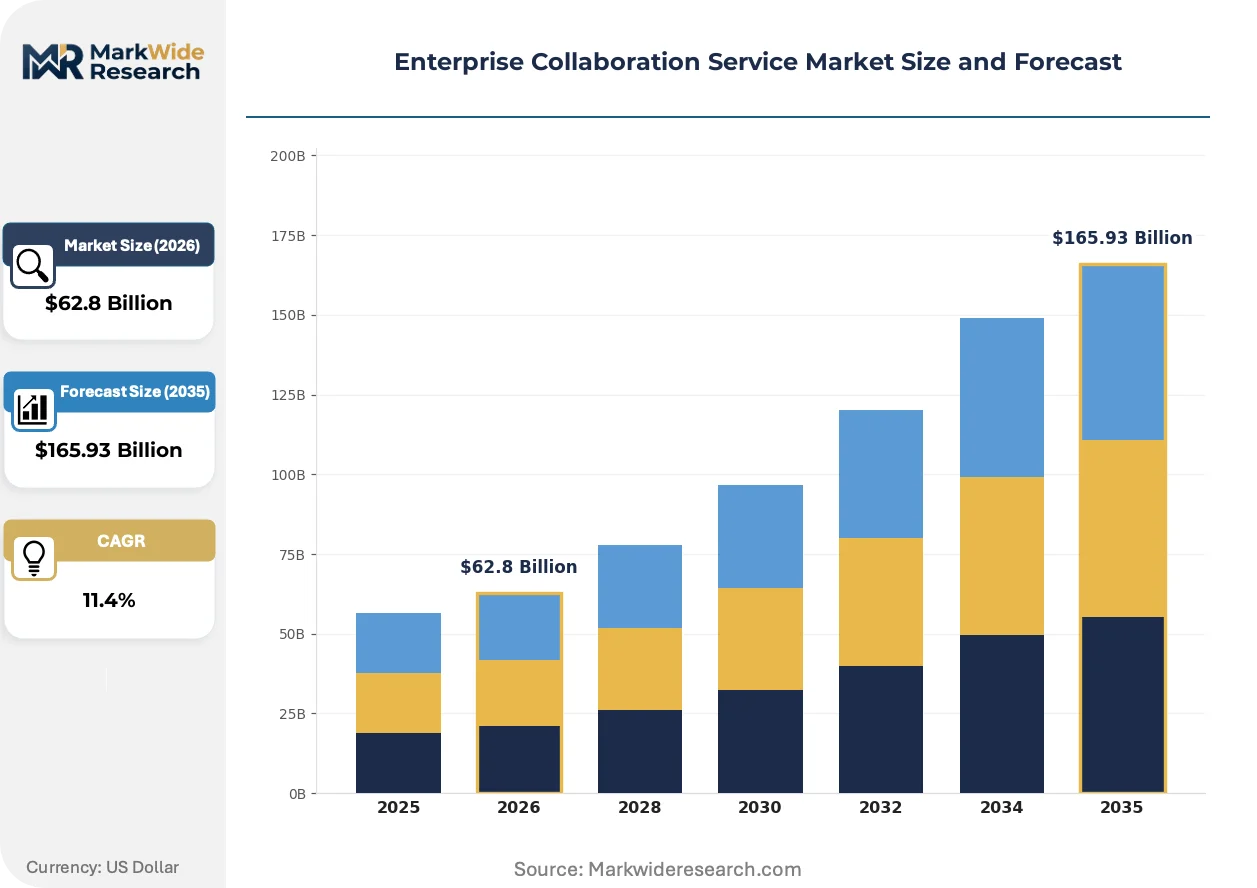
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $165.93 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Unified Communications, Project Management, File Sharing, Video Conferencing, Workflow Automation Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Application: Internal Communication, Client Collaboration, Remote Workforce Support, Training & Development, Knowledge Management End User: Information Technology Firms, Financial Institutions, Manufacturing Units, Educational Institutions, Government Agencies |
| Companies Covered | Microsoft Corporation, Cisco Systems, Inc., Google LLC, Salesforce, Inc., Zoom Video Communications, Inc., IBM Corporation, SAP SE, Atlassian Corporation Plc, Adobe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Collaboration Service Market Strategic Shifts & Innovations
Real-time collaboration architecture is splintering across latency, compliance, and integration vectors as buyers reject one-size-fits-all cloud consolidation.
Generative inference deployment is bifurcating between edge-resident and cloud-centralized models as EU AI Act data-sovereignty requirements force architectural duplication. Life-sciences and public-sector adopters now demand regionally isolated training clusters that prevent cross-border data leakage. This technical partition is compressing vendor economies of scale while creating protected submarkets for compliant regional specialists.
GDPR Article 44 transfer mechanism restrictions are hardening procurement criteria for cross-border collaboration stacks. European healthcare providers and financial institutions now specify in-country data residency as a non-negotiable contractual term. German industrial firms are responding by demanding sovereign-hosted alternatives to hyperscale platforms.
Consumption-based licensing for video room systems is displacing perpetual hardware ownership in hybrid workplace deployments. Corporate real estate teams now prioritize flexible subscription models that align collaboration infrastructure spend with actual utilization metrics. This shift is most visible in US federal courthouse and clinical environment refreshes where capital budget constraints favor operational expenditure treatment.
Enterprise Collaboration Service Market Segmentation
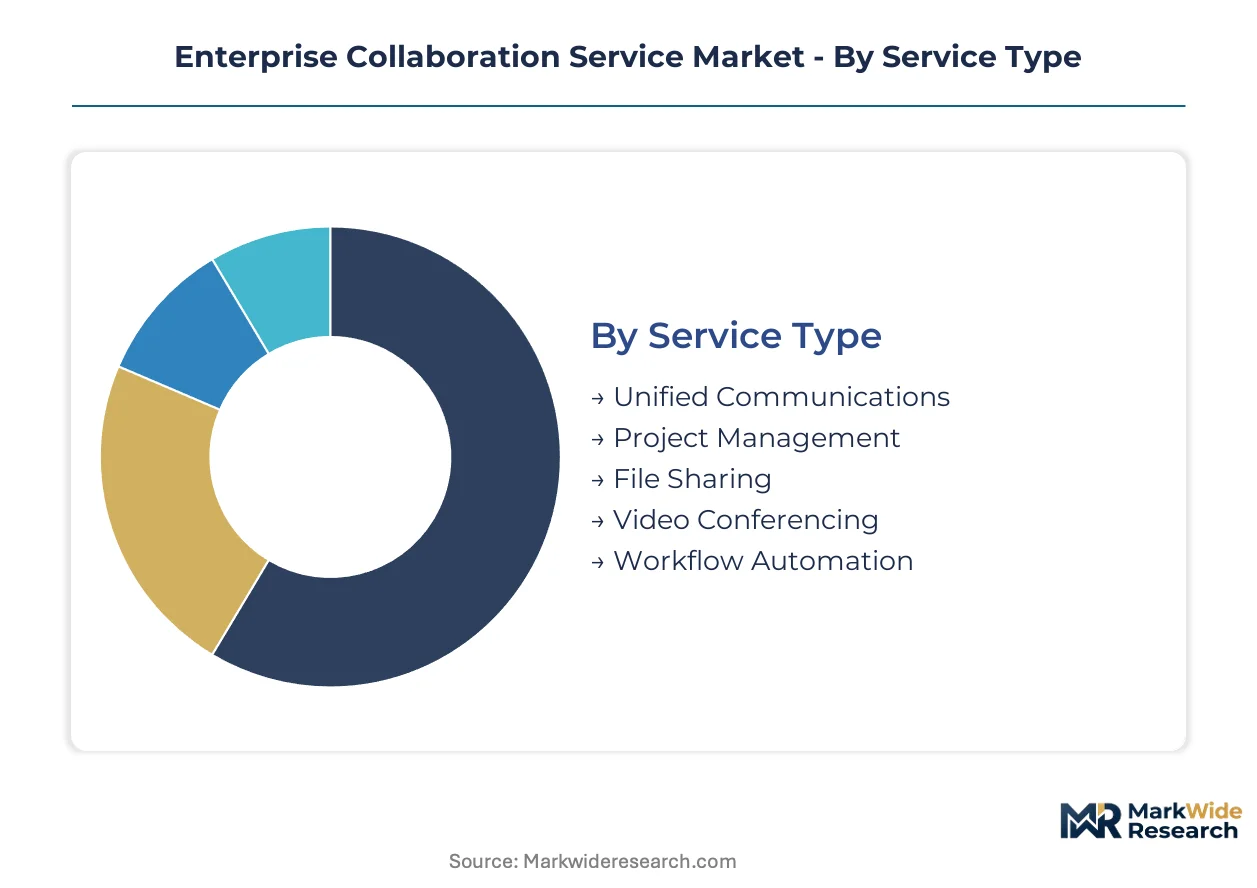
Enterprise collaboration purchasing bifurcates sharply between latency-sensitive clinical deployments and compliance-heavy sovereign installations. Channel strategy must align service packaging with distinct procurement velocities across regulated and commercial verticals.
Service Type:
Channel mix varies dramatically: Video Conferencing and Unified Communications flow through hardware-attach distributors, while Workflow Automation and Project Management reach buyers via direct SaaS marketplaces and systems integrators.
- Video Conferencing:Dedicated room-system hardware bundles with managed services overlays command premium pricing in federal courthouse and clinical environment refreshes. US federal contractors and German healthcare providers concentrate procurement here, driven by capital budget constraints favoring operational expenditure treatment.
- Workflow Automation:Collaboration triggers embedded directly into ERP and MES production sequences enable real-time manufacturing coordination. German Mittelstand manufacturers and industrial clusters in Stuttgart and Munich represent concentrated demand, propelled by legacy on-premises system retirement cycles.
- Unified Communications:Persistent messaging architectures with sub-150 millisecond latency SLAs serve teleconsultation workflows.
- Project Management:SaaS-native task orchestration platforms dominate mid-market IT firm procurement.
- File Sharing:Audit-trail immutable document repositories address FDA 21 CFR Part 11 requirements for life-sciences adopters.
By volume, Unified Communications leads. By growth pace, Workflow Automation is climbing the fastest.
Deployment:
Cost tier stratification separates perpetual-license on-premises estates from consumption-metered cloud alternatives, with hybrid deployments capturing mid-market buyers seeking staged migration paths.
- Cloud-Based:Multi-tenant architectures with regional data-residency zones dominate financial institution and government agency procurement. GDPR Article 44 transfer restrictions and EU AI Act training-data constraints accelerate sovereign-hosted stack demand across European banking and healthcare sectors.
- Hybrid:Staged migration configurations allow German industrial firms to retain sensitive ERP integration layers on-premises while shifting user-facing collaboration tools to cloud. Manufacturing units in Bavaria and North Rhine-Westphalia concentrate adoption, balancing depreciation schedule preservation against modernization pressure.
- On-Premises:Legacy Exchange and SharePoint estates persist in classified environments.
- Managed Services:Operational expenditure treatment for video room systems gains traction in constrained capital budgets.
Cloud-Based deployments capture the largest revenue share. Hybrid configurations are gaining share fastest as regulated industries navigate compliance transitions.
Application:
Customer type determines feature prioritization: clinical users demand sub-150 millisecond latency for Remote Workforce Support, while knowledge-intensive sectors prioritize searchability in Knowledge Management implementations.
- Remote Workforce Support:Secure messaging architectures with clinical-grade latency SLAs enable teleconsultation platform expansion. Healthcare providers in Germany and the United States concentrate procurement, driven by HIPAA and GDPR compliance requirements for patient data handling.
- Internal Communication:Persistent digital workspaces replacing email-thread fragmentation dominate enterprise IT firm adoption.
- Client Collaboration:External-facing document co-authoring with granular permission architectures serves financial advisory workflows.
- Training & Development:Video-based synchronous learning platforms expand in educational institutions.
- Knowledge Management:Searchable institutional memory systems with role-based access controls address NIST framework alignment requirements.
Internal Communication leads by installed base. Remote Workforce Support shows the steepest expansion trajectory.
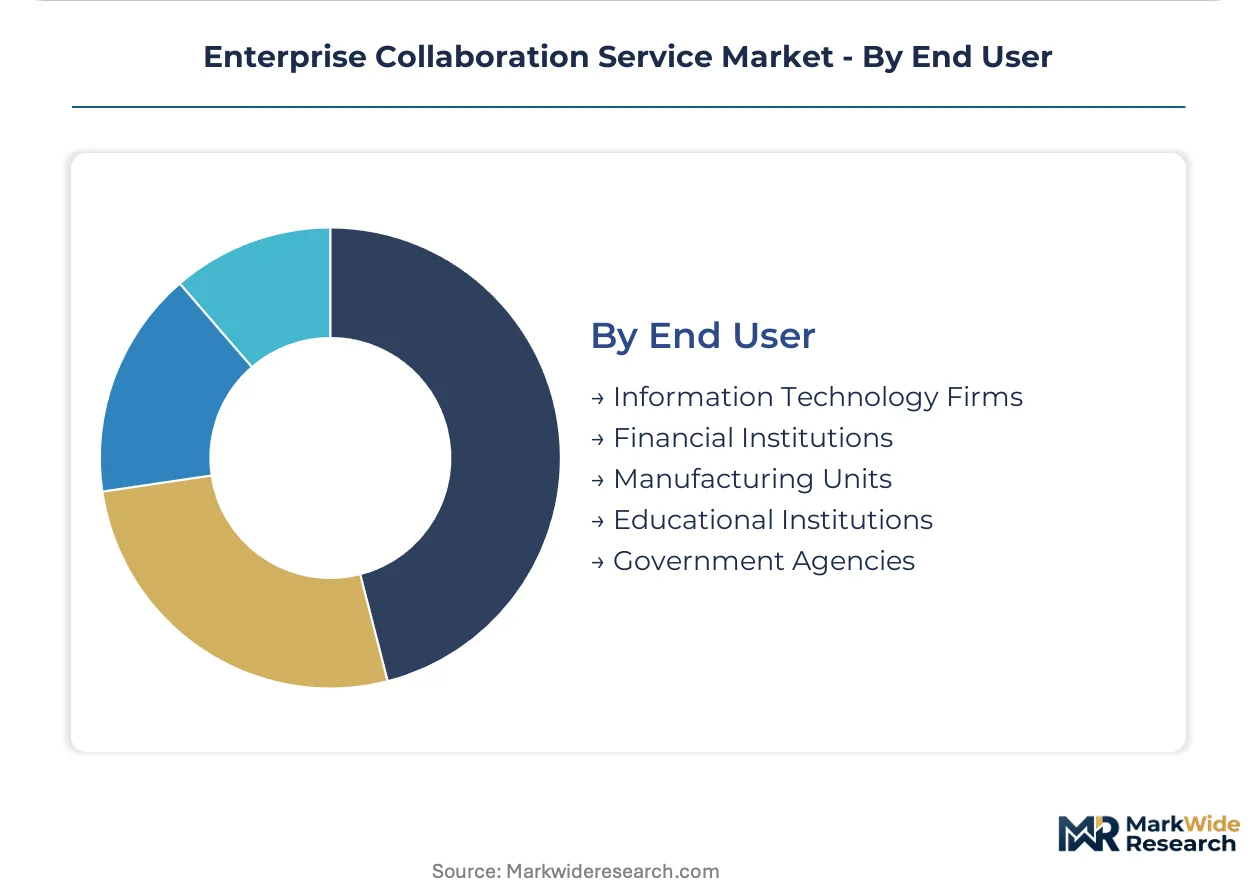
End User:
Maturity gradients separate early-cloud adopters in Information Technology Firms from compliance-lagged Government Agencies, with Manufacturing Units representing the fastest-converting legacy estate segment.
- Manufacturing Units:MES-embedded collaboration triggers and ERP production sequence integration define demand. German automotive and precision engineering clusters concentrate procurement, replacing on-premises Exchange estates with cloud-native alternatives.
- Government Agencies:FedRAMP and NATO classification requirements filter vendor eligibility, compressing competitive windows. US federal contractors and European public-sector bodies specify NIST cybersecurity framework alignment and GDPR-compliant sovereign clouds as non-negotiable procurement criteria.
- Information Technology Firms:Native cloud adoption without legacy migration burden enables fastest deployment velocity.
- Financial Institutions:Granular permission architecture replication from legacy SharePoint estates strains multi-tenant migration efforts.
- Educational Institutions:Cost-constrained procurement favors volume-discounted SaaS licensing.
Information Technology Firms lead by deployment velocity. Manufacturing Units are converting from legacy systems most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in enterprise collaboration services reflect asymmetric data-flow patterns. The United States and Germany generate surplus intellectual property in platform architecture while importing specialized compliance engineering from regional specialists.
United States
Federal courthouse digitization and clinical teleconsultation platforms drive procurement velocity. FDA 21 CFR Part 11 and FedRAMP certification requirements compress vendor eligibility windows. Washington DC and Boston clusters concentrate demand for hardened infrastructure meeting NIST cybersecurity framework alignment.
Germany
Industrial Mittelstand manufacturers replace on-premises Exchange estates with cloud-native ERP-embedded alternatives. EU AI Act training-data constraints and GDPR Article 44 transfer restrictions mandate sovereign-hosted inference clusters. Stuttgart and Munich automotive engineering clusters lead MES-integrated collaboration trigger adoption.
United Kingdom
Financial services firms migrate legacy SharePoint estates under post-Brexit data-sovereignty pressure. Financial Conduct Authority operational resilience requirements intersect with GDPR retention mandates. London City and Canary Wharf banking concentrations demand granular permission architecture replication.
Japan
Manufacturing keiretsu networks embed collaboration triggers into precision production sequences. METI digital transformation incentives accelerate legacy system retirement. Nagoya automotive and Osaka electronics clusters prioritize sub-150 millisecond latency SLAs for supplier coordination.
India
IT services exporters build captive collaboration stacks for client data-residency requirements. RBI data localization directives for financial services create domestic infrastructure demand. Bangalore and Hyderabad technology corridors concentrate SaaS-native platform development for global delivery.
Enterprise Collaboration Service Market Key Industry Players
Listed leaders compete with private specialists across certification depth and geographic coverage. The vendor base stratifies between hyperscale multi-tenant platforms and sovereign-hosted regional specialists. Three archetypes dominate: cloud-native suite providers, compliance-hardened infrastructure vendors, and vertical-specific workflow integrators. M&A activity concentrates on workflow automation capabilities while strategic partnerships address FedRAMP and GDPR certification gaps.
Within the compliance-hardened tier, Microsoft Corporation and Cisco Systems, Inc. exemplify divergent architectural bets on sovereign cloud versus federated infrastructure. Zoom Video Communications, Inc. occupies a position bridging hardware-as-a-service flexibility with specialized environment deployment. These three anchors represent distinct responses to latency, residency, and integration vectors splitting procurement criteria across regulated industries.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Cisco Systems, Inc. |
| Google LLC |
| Salesforce, Inc. |
| Zoom Video Communications, Inc. |
| IBM Corporation |
| SAP SE |
| Atlassian Corporation Plc |
| Adobe Inc. |
| Others |
Cost & Logistics Intelligence
FedRAMP certification timelines gate both vendor qualification and price differentiation in federal procurement corridors. Compliance investment requirements compress competitive windows while enabling premium positioning for accredited providers serving Washington DC and Boston courthouse digitization clusters.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing across video room-system bundles and managed services overlays. Price differentiation stems from certification grade (FedRAMP High vs Moderate) and hardware attach rates for hybrid courtroom deployments. Cost compression in mid-market SaaS tiers is intensifying because German Mittelstand manufacturers negotiate ERP-embedded workflow automation bundles. Healthcare providers show least price sensitivity due to HIPAA-mandated security requirements, while educational institutions drive hardest bargain for volume-discounted licensing.
Supply Chain Analysis
Just-in-time provisioning dominates hyperscale cloud infrastructure deployment, though sovereign-hosted stacks require strategic stockpiling of regionally isolated compute capacity. Supply concentrates in the United States, Ireland, and Singapore for primary data center nodes, with specialized hardware assembly feeding from Taiwan and South Korea. Raw material dependencies span advanced semiconductors, optical networking gear, and precision video conferencing endpoints. Single-source vulnerability in EU-based inference clusters creates exposure under GDPR Article 44 transfer restrictions. Distribution runs through systems integrators for workflow automation, hardware-attach distributors for video conferencing, and direct SaaS marketplaces for project management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise collaboration infrastructure sits in early-cycle expansion as sovereign data-residency mandates force systematic replacement of legacy on-premises estates. Workflow automation convergence with manufacturing ERP systems accelerates penetration beyond saturation in knowledge-worker segments.
For Market Incumbents: Consolidate certification depth across FedRAMP, NATO, and EU AI Act compliance tiers to defend against emerging sovereign-cloud specialists. Acquire workflow automation capabilities that embed collaboration triggers directly into MES production sequences, neutralizing vertical software entrants. Channel control through systems integrator exclusivity agreements protects margin position in German automotive clusters.
For New Entrants and Emerging Players: Regional sovereign-cloud infrastructure gaps in France and Italy present immediate white-space opportunity where hyperscale multi-tenant platforms face GDPR localization pressure. Target hybrid deployment configurations for Bavarian manufacturing units seeking staged migration paths. Go-to-market leverage rests on ERP-native integration partnerships with SAP and Oracle channel ecosystems.
For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape toward regionally isolated inference cluster operators. Long-term viability favors vertical workflow integrators with captive manufacturing relationships over horizontal platform plays. Acquisition target archetype: compliance-hardened specialists with existing German automotive or US federal contractor footprints. Signal to watch is FedRAMP authorization backlog clearance rates as inflection indicator for competitive window compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Buildout | EU AI Act training-data constraints force regionally isolated inference cluster deployment across Frankfurt and Amsterdam zones. |
| Workflow Automation Acquisition | MES-embedded collaboration triggers capture fastest-expanding service type in Stuttgart automotive engineering clusters. |
| FedRAMP Certification Investment | Twelve-to-eighteen month approval windows compress competitive entry for federal courthouse digitization contracts. |
| Hardware-as-a-Service Transition | Consumption-based licensing for video room systems aligns capital-constrained clinical and judicial procurement budgets. |
| ERP Native Integration Partnership | SAP and Oracle channel ecosystems provide distribution leverage for manufacturing-embedded collaboration platforms. |
Research Approach
The analysis maps video conferencing, workflow automation, unified communications, and project management segments, each validated through CTOs, IT procurement officers, platform engineers, and channel partners. Primary interviews with hospital biomedical engineers and federal contractor compliance leads intersect with secondary validation against SEC filings, hyperscaler capex disclosures, App Annie enterprise mobility data, and GPO contracts. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates across service types.
Consistency checks against external benchmarks validate projection outputs throughout the forecast period. The analytical framework segments by deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derive from installed base migration velocity and new customer acquisition curves. Industry-specific inputs include FDA 21 CFR Part 11 compliance adoption rates and German Mittelstand cloud migration survey data.
Forecasts assume regulatory continuity in FDA, FedRAMP, GDPR, and EU AI Act enforcement regimes; material policy shifts would require re-modeling. Quantum-resistant encryption standard acceleration or tariff disruption in Taiwan semiconductor supply chains represent specific revision triggers. Revision becomes warranted when sovereign data-residency mandate expansion crosses thresholds beyond current European banking and healthcare sector concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Supplier Management Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Managed Services Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market