
 IoT Professional Services Market | 2026-2036
IoT Professional Services Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Professional Services Market Intelligence
The direct-to-enterprise sales channel for bespoke IoT solutions is narrowing as platform-based service delivery gains traction. Accenture leverages its extensive consulting network to secure large-scale digital transformation projects. IBM differentiates through its deep expertise in data analytics and cloud integration platforms. Tata Consultancy Services competes by offering a broad portfolio of system integration and managed services, particularly for clients in the United States and Europe.
IoT professional services encompass the strategic consulting, system integration, and operational management required to deploy connected device networks. These services facilitate the convergence of operational technology with enterprise information technology, enabling real-time data collection and control. System integration services command significant value due to the complexity of legacy system modernization. Within use cases, predictive maintenance in the manufacturing sector and fleet monitoring in transportation represent high-growth applications, while managed services are becoming critical for long-term operational stability.
Regulatory frameworks like the EU's GDPR and the US's HIPAA impose strict data privacy and security obligations on IoT service providers. Concurrently, adherence to ISO/IEC standards for interoperability and device management is essential for market access and ensuring system compatibility across different vendors. Stakeholders must now decide whether to build in-house expertise in areas like edge computing and AI or rely on specialized service partners to bridge the talent gap.
Market Dynamics
The convergence of operational technology (OT) with enterprise information technology (IT) is the central force shaping the IoT professional services market. This integration enables real-time data flows from physical assets to business analytics platforms, creating demand for specialized integration and management expertise.
Growth Catalysts
- Predictive Maintenance Demand:The manufacturing sector's pursuit of operational efficiency and reduced downtime drives significant investment in IoT services for predictive maintenance, especially in the advanced industrial economies of Germany and Japan.
- Data Governance Mandates:Regulations like the EU's GDPR are creating a substantial market for consulting services focused on data privacy, security, and compliant analytics architectures for IoT-generated data.
- Edge Computing Adoption:The need for low-latency data processing in applications like industrial robotics and autonomous vehicles is fueling demand for professional services that design and manage edge computing infrastructure.
Market Restraints
- Legacy System Integration:The high complexity and cost associated with integrating modern IoT platforms into decades-old, proprietary OT systems in factories and utilities remains a significant barrier to adoption.
- Cybersecurity Vulnerabilities:The expanded attack surface created by connecting industrial equipment to enterprise networks introduces security risks that can deter deployment without expert security services, which are often costly.
- Talent Scarcity:A persistent shortage of professionals with dual expertise in operational technology and enterprise IT, coupled with data science skills, constrains the ability of providers to scale service delivery.
Strategic Opportunities
- Managed Services Expansion:A growing opportunity exists in offering long-term, subscription-based managed services for monitoring, maintaining, and securing IoT deployments, providing a stable recurring revenue stream.
- AI and IoT Convergence:Integrating artificial intelligence and machine learning into IoT service offerings enables advanced analytics, autonomous operations, and new predictive capabilities, creating high-value differentiation.
- Smart City Initiatives:Government-led smart city projects in regions like the Middle East and Asia-Pacific create large-scale opportunities for system integrators to deploy and manage urban IoT infrastructure for utilities, transport, and public safety.
Industry Challenges
- Interoperability Standards:A lack of universally accepted communication protocols and data standards across IoT device vendors complicates integration efforts, increasing project timelines and costs for service providers.
- Securing the Device Lifecycle:Managing security from device provisioning and deployment through to decommissioning is a complex operational challenge, requiring constant vigilance against evolving cyber threats.
- Proving Return on Investment:Service providers face the ongoing challenge of clearly demonstrating tangible financial returns from complex IoT projects to clients who are often skeptical of high upfront consulting and integration fees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Professional Services Market |
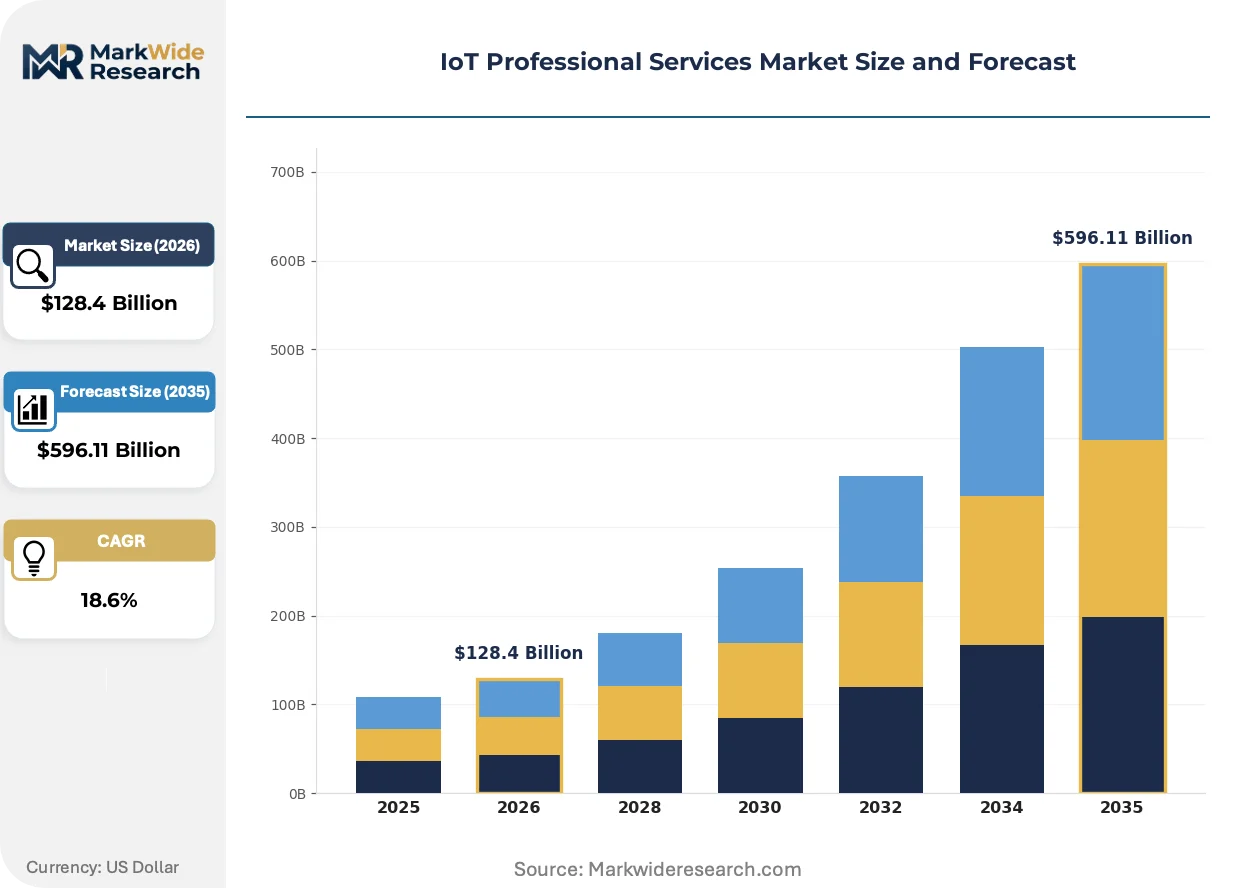
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $596.11 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, System Integration, Managed Services, Support & Maintenance, Training Solution Offering: Device Management, Network Security, Data Analytics, Cloud Integration, Application Development Use Case: Smart Cities, Asset Tracking, Energy Management, Fleet Monitoring, Predictive Maintenance End User Industry: Manufacturing, Telecommunications, Transportation, Agriculture, Utilities |
| Companies Covered | Cognizant, Infosys, Tata Consultancy Services, IBM, Accenture, EPAM Systems, Capgemini Engineering, Deloitte, Wipro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Professional Services Market Strategic Shifts & Innovations
The service delivery model is evolving from bespoke, project-based engagements toward scalable, platform-centric solutions. This shift allows providers to deploy solutions faster and manage them more efficiently, altering the competitive landscape and client expectations for long-term value from IoT investments.
Digital twin technology provides a virtual representation of a physical asset, system, or process, updated with real-time sensor data. The manufacturing, energy, and aerospace sectors are steadily adopting this for complex simulations and lifecycle analysis. This technology is digitizing the entire asset management cycle, from design and commissioning to predictive maintenance, enabling more sophisticated operational strategies.
Regulatory frameworks for artificial intelligence, such as the EU AI Act, are introducing new compliance obligations. The regulation establishes a risk-based approach, placing stringent requirements on high-risk AI systems often used in IoT analytics. Service providers offering AI-driven IoT solutions for critical infrastructure or healthcare in Europe must now embed auditable data governance and risk management into their service design.
Enterprises are progressively moving away from large, upfront capital expenditures for IoT projects. This change disrupts the traditional system integrator model, favoring subscription-based managed services that align costs with operational outcomes. This trend is particularly visible in the transportation sector, where fleet operators prefer as-a-service models for vehicle telematics and asset tracking over purchasing and managing the systems in-house.
IoT Professional Services Market Segmentation
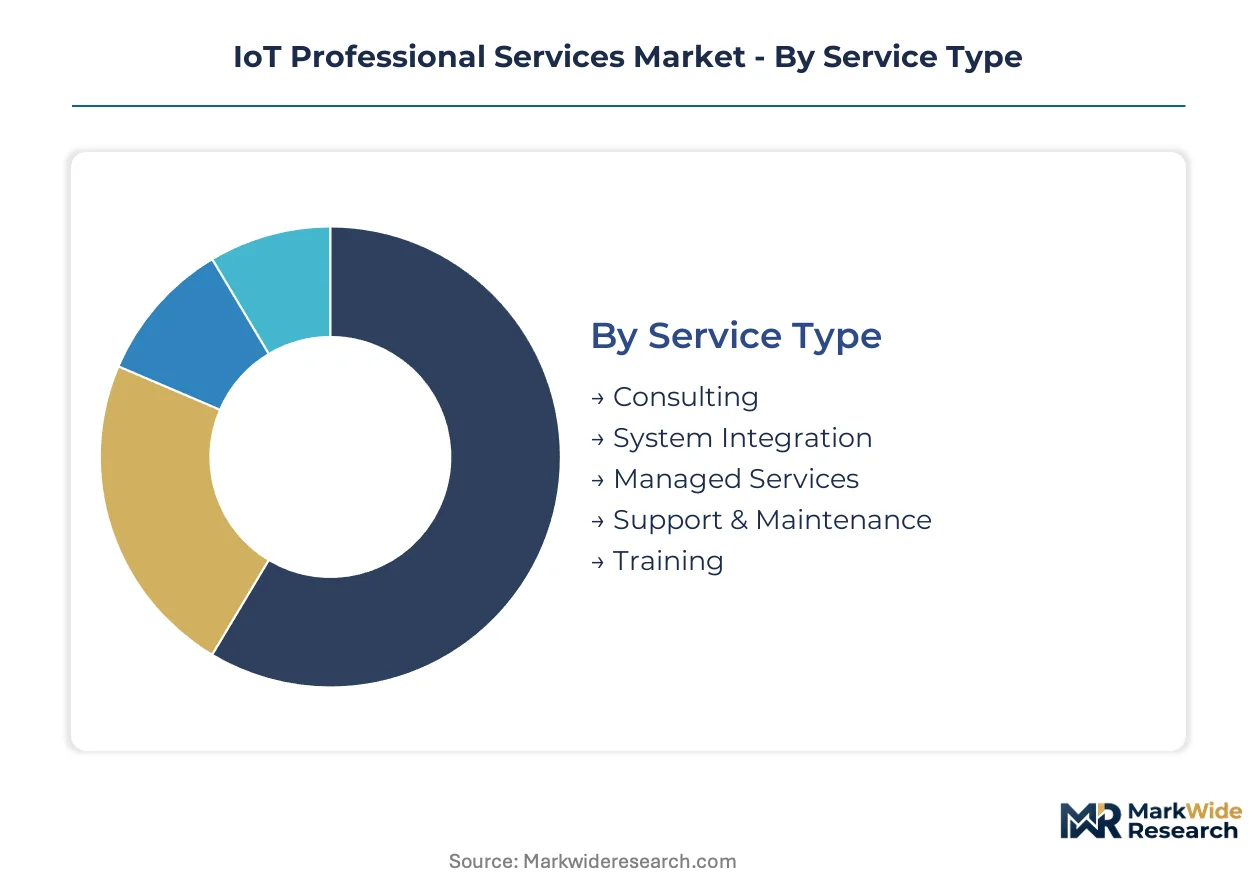
The IoT professional services market segmentation provides a granular view of how specialized expertise addresses the diverse technological and operational needs of enterprises. Understanding these distinct segments helps service providers align their offerings with specific client requirements and industry challenges.
Service Type:
The service type segmentation outlines the diverse range of engagements clients seek, spanning from strategic advice to ongoing operational support.
- System Integration:This service involves connecting disparate IoT devices, platforms, and enterprise IT systems into a cohesive operational framework. Manufacturing clients often require complex integration for legacy machinery, driving demand for specialized expertise.
- Managed Services:These services provide ongoing monitoring, maintenance, and optimization of IoT deployments on a subscription basis. Transportation sector operators increasingly adopt managed services for fleet telematics, preferring operational expenditure models.
- Consulting:Strategic guidance helps enterprises define IoT strategies, assess readiness, and plan digital transformation roadmaps.
- Support & Maintenance:These services ensure the continuous operation and performance of deployed IoT solutions and underlying infrastructure.
- Training:Programs educate client personnel on IoT platform usage, data interpretation, and system administration.
The dominant share belongs to System Integration, while Managed Services is closing the gap fastest.
Solution Offering:
Solution offerings are differentiated by the technical complexity and value proposition they deliver, often influencing project costs and long-term operational efficiencies.
- Data Analytics:This offering processes raw IoT data into actionable insights for business intelligence and operational optimization. Manufacturing firms leverage advanced analytics for predictive maintenance, improving asset uptime.
- Cloud Integration:Services connect IoT edge devices and platforms with central cloud infrastructure for scalable data storage, processing, and application hosting. Enterprises in Germany prioritize secure cloud integration for their industrial IoT initiatives.
- Device Management:These services provision, monitor, and update connected devices throughout their lifecycle.
- Network Security:Specialized services protect IoT networks and devices from cyber threats, ensuring data integrity and operational resilience.
- Application Development:Custom software creation enables tailored functionalities and user interfaces for specific IoT use cases.
Data Analytics commands a significant portion of solution offering revenue, with Cloud Integration experiencing the steepest expansion trajectory.
Use Case:
The diverse application of IoT professional services across various operational scenarios defines the use case segmentation.
- Predictive Maintenance:This involves using IoT sensor data and analytics to forecast equipment failures and schedule maintenance proactively. The manufacturing sector, particularly in Japan, significantly invests in predictive maintenance to minimize downtime.
- Fleet Monitoring:Services track vehicle location, performance, and driver behavior to optimize logistics and operational efficiency. Transportation companies globally adopt fleet monitoring for real-time asset visibility and cost reduction.
- Smart Cities:These projects integrate IoT for urban infrastructure management, including traffic, waste, and public safety.
- Asset Tracking:Solutions monitor the location and status of high-value physical assets across supply chains and industrial environments.
- Energy Management:Services optimize energy consumption in buildings and industrial facilities through connected devices and data analysis.
Predictive Maintenance remains a primary revenue generator, while Fleet Monitoring is gaining share fastest due to its clear ROI.
End User Industry:
Segmentation by end-user industry highlights how specific sector requirements and operational contexts drive demand for tailored IoT professional services.
- Manufacturing:This sector leverages IoT for factory automation, supply chain optimization, and quality control. German manufacturers are significant adopters, driven by advanced industrial automation needs.
- Transportation:IoT services support fleet management, logistics, and infrastructure monitoring for road, rail, and maritime operations. Operators in the United States increasingly seek services for telematics and asset visibility.
- Telecommunications:Providers deploy IoT for network infrastructure monitoring, smart connectivity solutions, and new service offerings.
- Utilities:Services enable smart grid management, remote asset monitoring, and efficient resource distribution for power and water.
- Agriculture:IoT solutions support precision farming, livestock monitoring, and environmental sensing for improved yields.
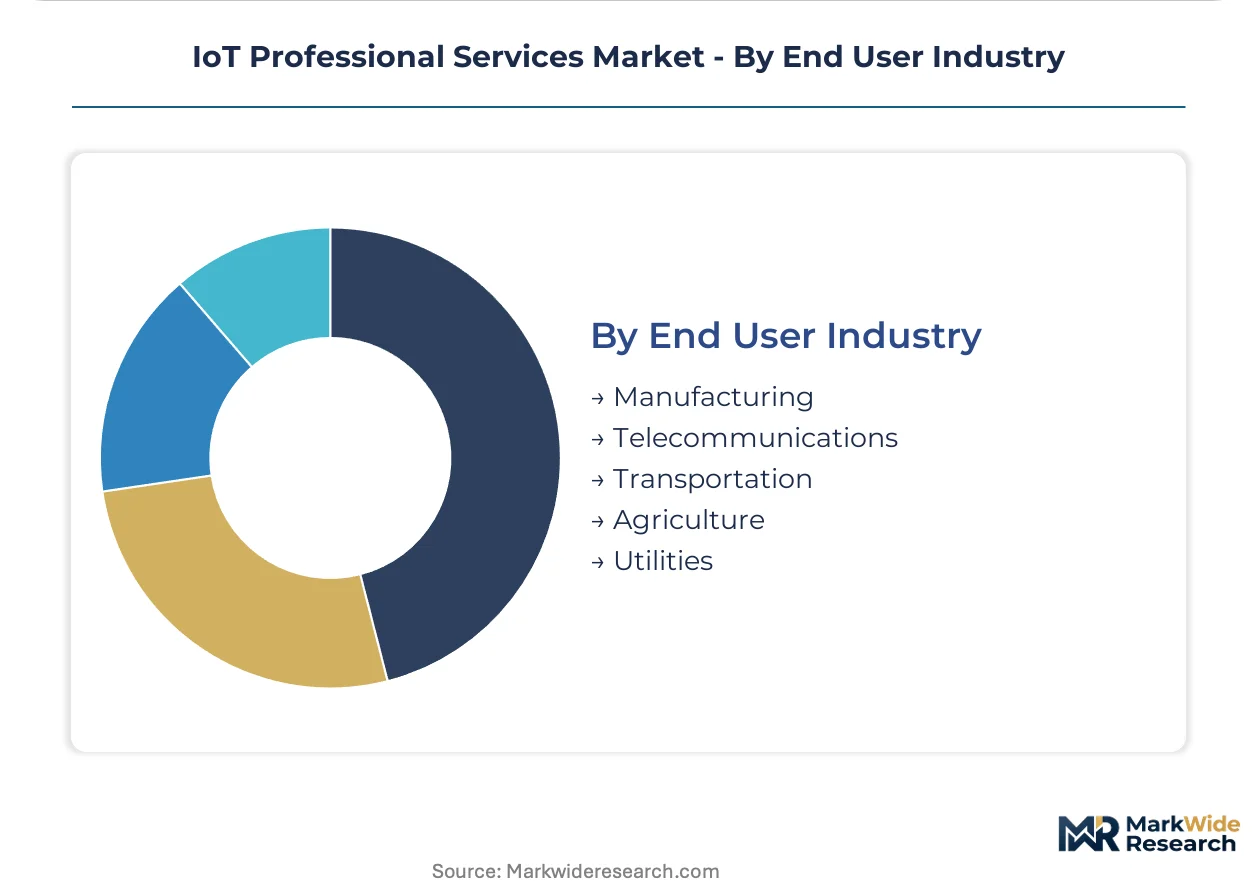
Manufacturing consistently drives the largest portion of service demand, with Transportation expanding most quickly as digital transformation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global IoT professional services market is shaped by advanced industrial infrastructure, particularly in manufacturing hubs, driving specialized service demand. This infrastructure, ranging from automated factories to complex logistics networks, necessitates sophisticated IoT deployments. These deployments require extensive strategic consulting and system integration to optimize operations and ensure data compliance across diverse regions.
Germany
German manufacturers pursue operational efficiency and reduced downtime, driving significant investment in IoT services for predictive maintenance. The EU AI Act introduces compliance obligations for high-risk AI systems used in critical infrastructure, impacting service design. The Bavaria region actively adopts digital twin technologies for complex simulations and lifecycle analysis.
United States
Demand for fleet monitoring and asset tracking solutions fuels IoT professional services adoption across the United States. HIPAA regulations impose strict data privacy and security obligations on IoT service providers in healthcare, influencing service delivery. The Silicon Valley cluster drives innovation in edge computing and AI integration, forming partnerships for advanced IoT solutions.
Japan
Japanese industrial companies prioritize predictive maintenance and operational technology convergence to enhance manufacturing productivity. METI initiatives support digital transformation across various sectors, encouraging IoT adoption and related services. The Kansai region heavily invests in IoT-enabled smart factory initiatives to maintain global competitiveness.
China
China's extensive manufacturing base and smart city initiatives generate substantial demand for IoT professional services. GB standards for interoperability and device management are essential for market access and system compatibility for service providers. The Yangtze River Delta region is a focal point for large-scale urban IoT infrastructure deployments.
United Kingdom
Digital transformation projects in the UK's manufacturing and transportation sectors drive demand for system integration and managed services. The UK's data protection regulations, aligned with GDPR principles, necessitate robust data governance strategies for IoT deployments. London acts as a hub for consulting services focused on IoT strategy and regulatory compliance.
IoT Professional Services Market Key Industry Players
On the supply side, the industry is characterized by a mix of established IT services giants and specialized consulting firms. The market exhibits a tiered structure, with large global players competing alongside niche providers offering specialized expertise. Key strategic archetypes include broad-spectrum digital transformation partners, data analytics specialists, and system integration experts. Dominant competitive moves involve strategic partnerships to expand solution portfolios and geographic expansion to capture emerging market opportunities.
Within the broad-spectrum digital transformation archetype, Accenture leverages its extensive consulting network to secure large-scale projects globally, emphasizing comprehensive digital shifts. IBM differentiates through its deep expertise in data analytics and cloud integration platforms, particularly for complex enterprise environments requiring advanced analytical capabilities. Tata Consultancy Services competes by offering a broad portfolio of system integration and managed services, particularly for clients in the United States and Europe, focusing on long-term operational support. These firms represent the diverse approaches to delivering IoT professional services, from strategic advisory to full-scale operational management across multiple industry verticals.
| Leading Market Players |
|---|
| Cognizant |
| Infosys |
| Tata Consultancy Services |
| IBM |
| Accenture |
| EPAM Systems |
| Capgemini Engineering |
| Deloitte |
| Wipro |
Cost & Logistics Intelligence
Underutilized consulting capacity in certain geographic pockets drives provider pricing posture, while specialized talent scarcity elsewhere influences service delivery models. This dynamic shapes the cost structures and competitive landscape for IoT professional services.
Pricing Analysis
Volume-based tiering structures characterize subscription-based managed services, offering scaled pricing based on device count or data throughput for long-term engagements. Pricing for bespoke system integration projects reflects the customization level, specialized expertise, and the complexity required for legacy system modernization. Upfront pricing pressure stems from client skepticism regarding high initial consulting and integration fees. Transportation sector clients exhibit particularly high price sensitivity towards capital expenditure, preferring operational expenditure models for fleet telematics and asset tracking solutions.
Supply Chain Analysis
Talent scarcity in dual operational technology and enterprise IT expertise represents a significant supply chain risk for IoT professional services providers. Service delivery relies heavily on highly specialized personnel sourced globally, particularly from established IT hubs in India and Eastern Europe. Key dependencies include access to advanced cloud platforms, proprietary IoT solution frameworks, and secure hardware components. Distribution runs through direct enterprise engagements and expanding platform-centric service models, shifting from project-based to subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the convergence of operational technology and enterprise IT. The EU AI Act introduces a significant regulatory inflection point, necessitating embedded compliance in AI-driven IoT solutions.
For Market Incumbents:Pre-empt talent scarcity by investing heavily in specialized training programs for dual OT-IT expertise and AI integration. Incumbents should acquire niche service providers with deep expertise in edge computing to counter emerging specialized firms. Deepen platform integration capabilities to reduce project complexity and defend against commoditization. Focus R&D on auditable AI governance frameworks to address upcoming regulatory shifts like the EU AI Act.
For New Entrants and Emerging Players:Build out highly specialized offerings in niche areas like AI-driven predictive maintenance for specific industrial machinery types. Target mid-market fleet operators with outcome-based managed services for clear return on investment in telematics. The smart city segment in Asia-Pacific presents white-space opportunities for infrastructure management solutions. Focus on delivering pre-configured, platform-centric solutions to accelerate deployment and reduce upfront costs.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among managed services providers offering long-term subscription-based IoT operational support. Investors should target specialized system integrators with proprietary platforms and strong compliance expertise for the long-term viability of this market. Acquisition archetypes include firms specializing in AI-driven analytics or edge computing infrastructure. The increasing integration of digital twin technology in manufacturing serves as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Talent Development Programs | Addressing the persistent talent scarcity in dual OT-IT expertise directly impacts service delivery capacity. |
| Platform-as-a-Service Expansion | Shifting to platform-centric models enables scalable delivery and reduces bespoke project overhead for enterprises. |
| AI Governance Consulting | Embedding compliance with regulations like the EU AI Act becomes critical for high-risk AI-driven IoT solutions. |
| Edge Computing Specialization | Developing deep expertise in edge infrastructure supports low-latency applications in industrial robotics. |
| Managed Services Portfolio Growth | Expanding subscription-based offerings secures recurring revenue streams and aligns with client OpEx preferences. |
Research Approach
Operator-level perspectives from CTOs, plant managers, IT procurement officers, and regulatory affairs specialists anchored the qualitative base for this analysis. This primary research combined with extensive secondary validation from SEC filings, industry association reports, and government technology initiatives. Bottom-up data aggregation and top-down market sizing provided robust triangulation for market estimates.
Scenario-bracketing around optimistic and conservative adoption rates informed the forecast trajectory across the analysis window. The analytical framework modeled segmentation by service type, solution offering, use case, end-user industry, and regional adoption patterns. Compound Annual Growth Rates were derived from historical trends and projected technological advancements. Key inputs included IoT device deployment rates and industrial automation investment levels.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers or specialized AI firms would shift outcomes. Forecasts reflect assumptions regarding talent availability and client digital transformation budgets. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
IT Staffing Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Global Remote Infrastructure Management Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Europe Managed Infrastructure Services Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Contingent Staffing Solutions Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Travel and Expense Management Market