
 Online Corporate Meeting Services Market | 2026-2036
Online Corporate Meeting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Online Corporate Meeting Services Market Intelligence
Enterprise IT talent scarcity is reorganizing how corporations evaluate meeting infrastructure, pushing buyers toward vendors with embedded managed services. Zoom Video Communications sustains broad channel penetration through carrier partnerships and hardware bundling. Microsoft Teams dominates enterprise suites by leveraging Office 365 install bases. Cisco Webex anchors security-sensitive verticals with end-to-end encryption certifications.
Online corporate meeting services encompass real-time audio, video, and data collaboration delivered over IP networks with latency thresholds typically below 150 milliseconds for acceptable conversational quality. These platforms integrate scheduling, authentication, and analytics to replace or augment physical conference facilities. Cloud-based deployment leads absolute spending as enterprises retire on-premises PBX bridges, while hybrid configurations capture margin pools from regulated clients requiring local data sovereignty. Video conferencing occupies the largest share of service-type revenue, yet virtual events represents the fastest-growing category as experiential marketing budgets shift from physical to immersive digital formats.
FCC net-neutrality frameworks influence last-mile quality for real-time video, while GDPR and the EU AI Act impose consent and algorithmic transparency obligations on meeting analytics features. HIPAA constrains how healthcare enterprises in the United States configure recording and transcription workflows. Stakeholders must weigh interoperability commitments against proprietary ecosystem lock-in when selecting long-term platform partners.
Market Dynamics
Hybrid work mandates are compressing refresh cycles for meeting infrastructure as financial services and professional services firms consolidate dispersed vendor relationships onto persistent collaboration platforms.
Growth Catalysts
- GDPR and EU AI Act:Data residency requirements are forcing enterprises to upgrade from consumer-grade tools to certified enterprise platforms with local processing nodes.
- Texas and California headquarters clusters:Consolidated procurement power among technology and energy sector buyers is accelerating platform standardization across multi-location deployments.
- Immersive event formats:Experiential marketing budgets are shifting from physical venues to virtual events with spatial audio and 3D environments.
Market Restraints
- Last-mile quality volatility:FCC net-neutrality framework uncertainty degrades real-time video performance for remote participants on non-prioritized networks.
- Cloud concentration risk:Three hyperscalers control the majority of meeting infrastructure substrate, creating single-point-of-failure exposure for enterprise tenants.
- Latency physics:Sub-150 millisecond thresholds for acceptable conversational quality hard-cap geographic distribution of processing nodes.
Strategic Opportunities
- Healthcare HIPAA workflows:Configurable recording and transcription consent layers for telemedicine encounters remain underdeveloped relative to demand.
- AI-powered real-time translation:Convergence of neural machine translation with low-latency audio streaming opens cross-border deal-making applications.
- Carrier-managed service bundles:Telecommunications providers are embedding meeting platforms into connectivity contracts, creating new channel access.
Industry Challenges
- Enterprise IT talent scarcity:Managed service capabilities now dominate vendor selection criteria as internal teams lack bandwidth for platform administration.
- Interoperability certification delays:Proprietary ecosystem lock-in conflicts with multi-platform deployment requirements, extending procurement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Corporate Meeting Services Market |
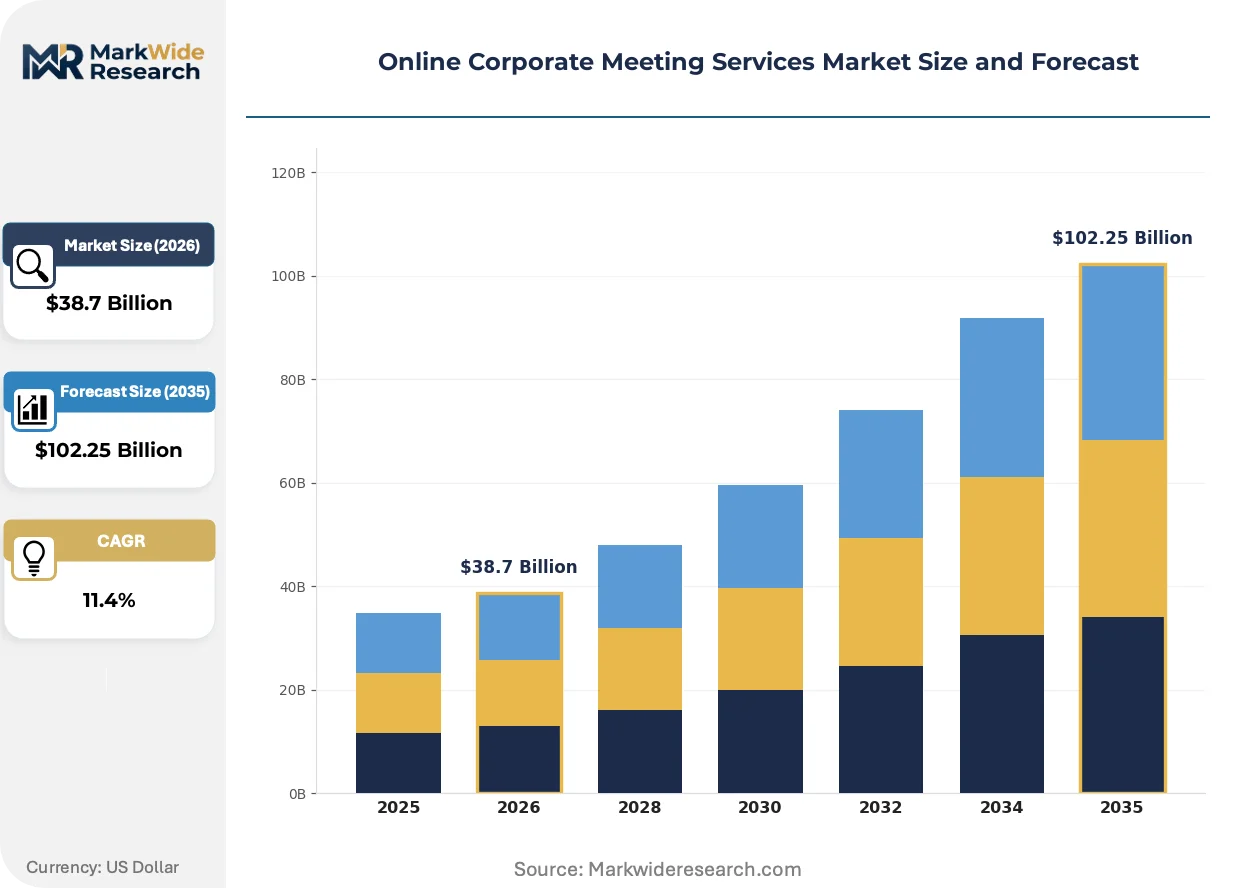
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video Conferencing, Webinars, Virtual Events, Collaboration Tools End User: Enterprises, Government, Educational Institutions, Non-Profit Organizations Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Technology: WebRTC, VoIP, Screen Sharing, Recording Features |
| Companies Covered | Cvent, GoGather, Zoom Video Communications, BCD Meetings & Events, CWT Meetings & Events, Cisco Webex, Bizzabo, MeetingPlay, Microsoft Teams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Corporate Meeting Services Market Strategic Shifts & Innovations
Meeting platforms are splitting into two functional categories: lightweight browser-based tools for ad-hoc collaboration and heavy infrastructure for regulated, persistent workspaces. This bifurcation is reshaping R&D allocation and partnership strategies across the vendor landscape.
Spatial audio with head-related transfer function processing is bifurcating the premium tier of corporate meeting services. Financial services trading floors and executive boardrooms are adopting it first, compressing differentiation for legacy stereo-conferencing hardware. The technology enables directional attention cues that reduce cognitive load during multi-party negotiations.
The EU AI Act's algorithmic transparency obligations are forcing vendors to document how meeting analytics features process participant data. This is triggering redesigns of sentiment analysis and attention-tracking tools. Healthcare enterprises in Germany and France are now requiring audit trails for any AI-generated meeting summaries before procurement approval.
Buying committees are unbundling hardware, software, and managed services into separate contracts rather than accepting bundled suites. This fragments vendor relationships and extends sales cycles. The pattern is most visible among professional services firms in London and New York, where procurement teams now run competitive tenders for each layer independently.
Online Corporate Meeting Services Market Segmentation
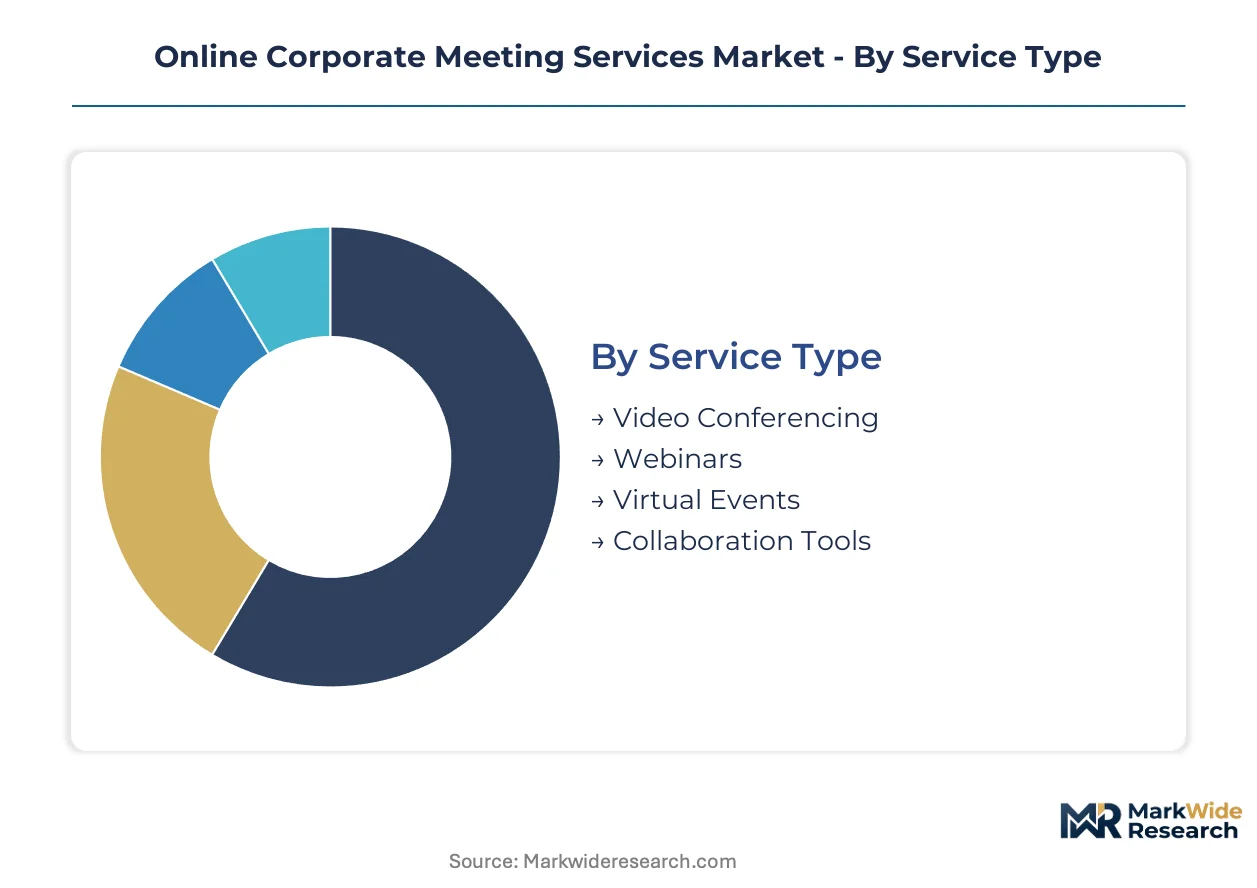
Segmentation in online corporate meeting services reveals how procurement patterns diverge between regulated verticals seeking persistent workspaces and distributed teams needing lightweight browser access. Buyers unbundle hardware, software, and managed services into separate contracts, fragmenting vendor relationships across each layer.
Service Type:
Video conferencing dominates domestic procurement as headquarters clusters consolidate onto persistent platforms. Virtual events and webinars concentrate in export-led experiential marketing budgets shifting from physical venues.
- Video Conferencing:Real-time audio-video transmission with sub-150 millisecond latency thresholds for acceptable conversational quality. Financial services trading floors in New York and London drive premium-tier demand for spatial audio with head-related transfer function processing.
- Virtual Events:Immersive digital formats with 3D environments and spatial audio replacing physical venue budgets. German and French healthcare enterprises now require audit trails for AI-generated summaries before procurement approval, tightening vendor selection criteria.
- Webinars:Scalable one-to-many presentation formats with integrated registration and analytics workflows.
- Collaboration Tools:Persistent messaging and file-sharing layers embedded within meeting platforms for asynchronous follow-through.
Video conferencing commands the established base. The steepest expansion runs through virtual events.
End User:
Enterprises absorb the majority of cloud-based deployment spending as IT talent scarcity pushes buyers toward managed service bundles. Government and educational procurement concentrates in hybrid configurations requiring local data sovereignty nodes.
- Enterprises:Multi-location deployments consolidating dispersed vendor relationships onto standardized platforms. Texas and California headquarters clusters exercise consolidated procurement power across technology and energy sector buyers.
- Government:Security-sensitive configurations with end-to-end encryption certifications and domestic data residency mandates. GDPR and the EU AI Act impose consent and algorithmic transparency obligations on meeting analytics features for cross-border traffic.
- Educational Institutions:Scalable licensing for distributed student populations with accessibility compliance requirements.
- Non-Profit Organizations:Cost-constrained deployments prioritizing browser-based accessibility over infrastructure investment.
Enterprises anchor volume procurement. Government segments show the most rapid compliance-driven upgrade cycles.
Deployment:
Cloud-based deployment leads absolute spending as enterprises retire on-premises PBX bridges. Hybrid configurations capture margin pools from regulated clients in Germany and France requiring local processing nodes.
- Cloud-Based:Multi-tenant infrastructure with automatic scaling and centralized vendor management. Three hyperscalers control the majority of meeting infrastructure substrate, creating concentration risk for enterprise tenants.
- Hybrid:Local data sovereignty nodes with cloud burst capacity for peak demand. HIPAA constrains how United States healthcare enterprises configure recording and transcription workflows, favoring hybrid architectures with on-premises consent layers.
- On-Premises:Dedicated hardware stacks for air-gapped environments with complete operational control.
- SaaS:Subscription licensing with embedded managed services addressing internal IT bandwidth constraints.
Cloud-based deployment holds the revenue base. Hybrid configurations are climbing the fastest on regulatory tailwinds.
Technology:
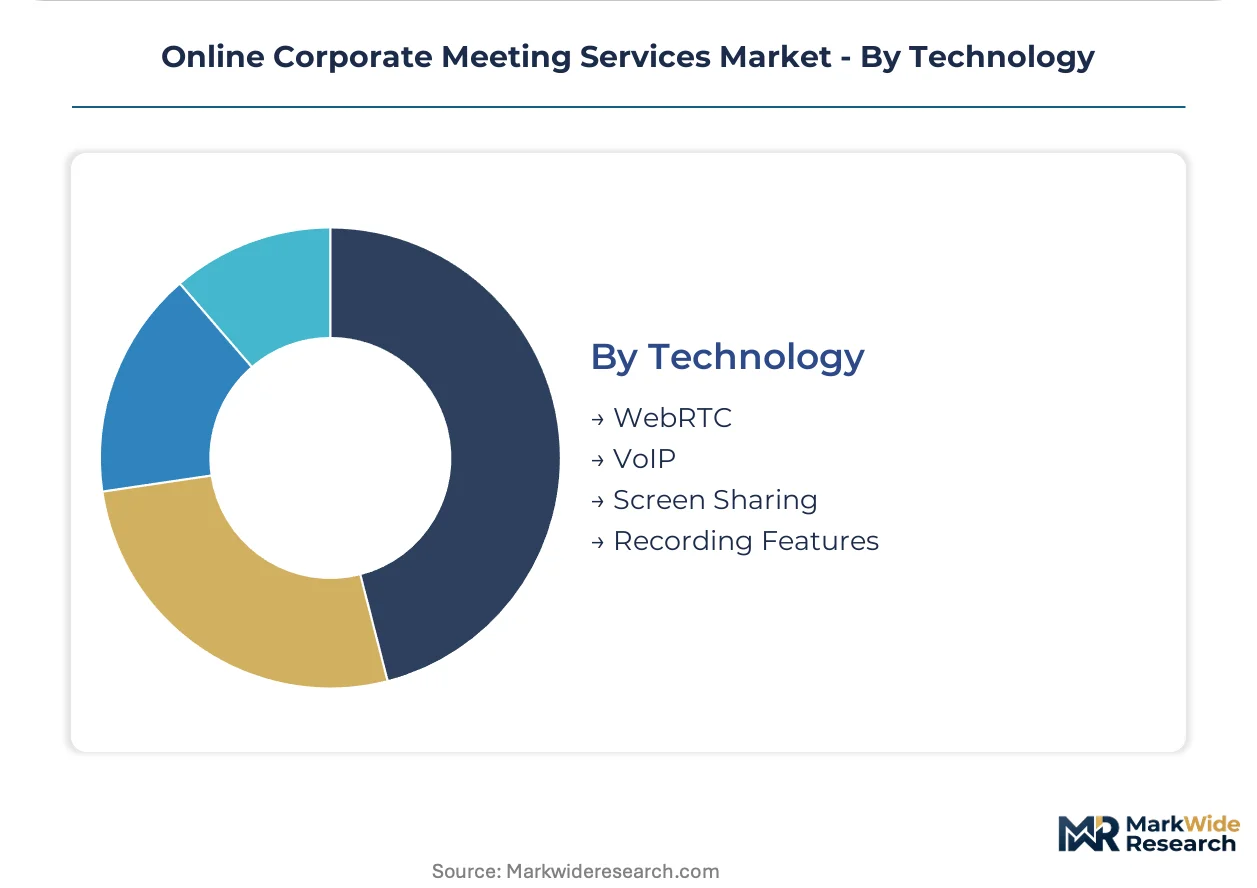
WebRTC enables browser-based access without client installation, expanding addressable markets to external participants. VoIP and recording features concentrate in premium tiers where carrier-managed service bundles create new channel access.
- WebRTC:Peer-to-peer media transmission through standardized browser APIs eliminating plugin dependencies. Lightweight deployment suits ad-hoc collaboration across dispersed professional services teams in London and New York.
- VoIP:Packet-switched voice transmission with quality-of-service prioritization for real-time conversational clarity. FCC net-neutrality framework uncertainty degrades performance for remote participants on non-prioritized networks.
- Screen Sharing:Real-time video codec compression for document and application broadcast with annotation overlays.
- Recording Features:Cloud or local storage of meeting archives with configurable consent workflows and retention policies.
WebRTC underpins mass-market accessibility. AI-powered real-time translation layered over VoIP streams is gaining share fastest for cross-border deal-making applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States headquarters clusters while European procurement cycles elongate under compliance burdens. German and French enterprises now require algorithmic audit trails before platform approval, compressing vendor margins. This asymmetry reshapes how meeting services firms allocate sales resources across geographies.
United States
Texas and California headquarters clusters exercise consolidated procurement power across technology and energy sector buyers. FCC net-neutrality framework uncertainty degrades real-time video performance for remote participants on non-prioritized networks. HIPAA constrains how healthcare enterprises configure recording and transcription workflows, favoring hybrid architectures with on-premises consent layers in Boston and Minneapolis medical corridors.
Germany
Healthcare enterprises in Frankfurt and Munich now require audit trails for any AI-generated meeting summaries before procurement approval. GDPR and the EU AI Act impose consent and algorithmic transparency obligations on meeting analytics features for cross-border traffic. Industrial manufacturing clusters in Baden-Württemberg drive demand for persistent collaboration platforms with local data sovereignty nodes.
United Kingdom
Professional services firms in London run competitive tenders for hardware, software, and managed services independently, fragmenting vendor relationships. Buying committees unbundle bundled suites into separate contracts, extending sales cycles. Financial services trading floors in the City of London drive premium-tier demand for spatial audio with head-related transfer function processing.
France
German and French healthcare enterprises require audit trails for AI-generated meeting summaries, tightening vendor selection criteria. ANSM and CNIL oversight shapes how pharmaceutical and medical device firms configure consent layers for telemedicine encounters. Paris-based experiential marketing agencies shift budgets from physical venues to virtual events with 3D environments and spatial audio.
Japan
METI guidelines influence how enterprises evaluate cloud concentration risk across meeting infrastructure substrates. Financial services firms in Tokyo and Osaka consolidate dispersed vendor relationships onto persistent collaboration platforms. Manufacturing headquarters in Nagoya and Kyoto demand low-latency processing nodes to satisfy sub-150 millisecond thresholds for acceptable conversational quality.
Online Corporate Meeting Services Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the online corporate meeting services landscape. The market structure consolidates around three hyperscalers controlling infrastructure substrate while specialist vendors capture margin pools in regulated verticals. Two dominant strategic archetypes emerge: carrier-integrated platform providers and vertical-specific compliance specialists. Competitive moves concentrate on strategic partnerships with telecommunications providers and portfolio diversification into managed services bundles.
Among platform providers with broad channel penetration, Zoom Video Communications and Microsoft Teams occupy positions exemplifying the carrier-partnership archetype, while Cisco Webex anchors the security-sensitive vertical tier. Cvent and Bizzabo represent the experiential marketing specialization vector. These companies illustrate how vendor selection criteria now prioritize embedded managed services capabilities over pure technology features, reflecting enterprise IT talent scarcity across United States and European procurement committees.
| Leading Market Players |
|---|
| Cvent |
| GoGather |
| Zoom Video Communications |
| BCD Meetings & Events |
| CWT Meetings & Events |
| Cisco Webex |
| Bizzabo |
| MeetingPlay |
| Microsoft Teams |
| Others |
Cost & Logistics Intelligence
GDPR and the EU AI Act certification gates both supply qualification and price differentiation simultaneously, forcing vendors to maintain local processing nodes for regulated buyers while standardizing cloud infrastructure for cost-sensitive segments. This dual-track architecture compresses margins in European markets while concentrating pricing power with carriers bundling managed services in United States headquarters clusters.
Pricing Analysis
The customization-premium spread separates configured-to-order hybrid deployments from standard SaaS subscriptions, with HIPAA-compliant healthcare configurations commanding substantial uplifts over browser-based tiers. Price differentiation rests on certification grade and vertical integration depth, with end-to-end encryption certifications and embedded managed services driving tier separation. Cost compression in the standard SaaS tier is intensifying because hyperscaler concentration commoditizes baseline features. Small and mid-market enterprises exhibit highest price sensitivity, while financial services trading floors in New York and London show lowest sensitivity due to regulatory non-negotiables.
Supply Chain Analysis
Just-in-time capacity scaling dominates cloud-native vendors, while regulated healthcare and government buyers demand strategic stockpiles of on-premises hardware for data sovereignty compliance. Infrastructure substrate concentrates in United States, Ireland, and Singapore hyperscaler regions, with specialized edge nodes in Germany and Japan for latency-sensitive applications. Component dependencies include WebRTC codec libraries, VoIP gateway hardware, and AI inference accelerators for real-time translation. Single-source vulnerability runs through three hyperscalers controlling majority substrate. Distribution runs through telecommunications carriers embedding platforms into connectivity contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where switching costs lock enterprises into persistent collaboration platforms, with regulatory entrenchment deepening as GDPR and the EU AI Act impose algorithmic audit requirements that favor incumbent certification investments.
For Market Incumbents: Compound carrier partnership density to deepen channel control against emerging vertical specialists threatening regulated segments. Prioritize backward integration into edge infrastructure to capture hybrid deployment margins from German and French healthcare enterprises requiring local processing nodes. Accelerate AI-powered real-time translation R&D to defend premium tier positioning against neural machine translation specialists. For New Entrants and Emerging Players: Telemedicine consent-layer configurability represents a service-layer gap where incumbents under-serve HIPAA-constrained United States healthcare workflows. Target Boston and Minneapolis medical corridors with modular compliance tools that unbundle from full-stack platforms. Pursue direct hospital system partnerships bypassing incumbent carrier channels. For Investors and Strategic Acquirers: The EU AI Act's algorithmic transparency obligations reshape the acquisition landscape toward vendors with documented AI audit trails. Long-term viability favors platforms with embedded managed services capabilities addressing enterprise IT talent scarcity. Watch carrier-managed service bundle penetration rates as the signal indicating when vertical specialization becomes acquisition-accretive versus organic build.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier Partnership Expansion | Telecommunications providers in Texas and California embed meeting platforms into connectivity contracts, locking multi-location enterprise deployments. |
| Hybrid Infrastructure Buildout | Local data sovereignty nodes in Frankfurt and Munich capture GDPR-driven upgrade cycles from German healthcare enterprises. |
| AI Translation Layer Development | Neural machine translation convergence with low-latency audio opens cross-border financial services deal-making applications. |
| Spatial Audio Certification | Head-related transfer function processing differentiates premium tier for New York and London trading floors. |
| Managed Services Bundling | Embedded platform administration addresses IT talent scarcity compressing procurement timelines for professional services firms. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with platform engineering directors, IT procurement officers at financial services firms, healthcare compliance leads, and telecommunications carrier partnership managers; and secondary validation through SEC filings from listed vendors, hyperscaler capex disclosures, GDPR enforcement actions, and hospital procurement database records. Bottom-up triangulation across deployment model, organization size, vertical regulatory cluster, and regional adoption pattern anchored value estimates, while top-down cross-checks against carrier contract values ensured consistency.
Across the projection horizon, the analytical framework modeled service type, end user vertical, deployment architecture, and technology stack dimensions. CAGRs derived from segment-level growth drivers including regulatory upgrade cycles, carrier bundle penetration, and experiential marketing budget shifts. Forecast inputs incorporated FCC net-neutrality framework uncertainty effects on last-mile quality and EU AI Act compliance timeline assumptions for algorithmic transparency obligations.
Material uncertainties — hyperscaler concentration disruptions, geopolitical data localization mandates, and generative AI capability leaps — sit outside the modeled envelope. Forecasts reflect documented assumptions about enterprise refresh cycle timing and carrier partnership exclusivity terms. Revision becomes warranted when regulatory enforcement intensity crosses thresholds triggering accelerated compliance-driven procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Global Enterprise Content Collaboration Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Helpdesk Management Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Proactive Services Market
Enterprise Services
Middle East and Africa IT Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Managed Services Market
Enterprise Services
US Enterprise Asset Management Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Europe IT Services Market