
 Employee Engagement Market | 2026-2036
Employee Engagement Market Size, Share, and Industry Trends Forecast 2026-2036
Employee Engagement Market Analysis
Enterprise software procurement channels for HR technology are tilting toward direct platform sales and embedded marketplace distribution. Workhuman leverages its global reward fulfillment network to sustain long-term contracts with Fortune 500 employers. Lattice competes through integrated performance management modules that extend into goal-setting and career development workflows. Culture Amp anchors its position with psychometric science and benchmarked survey methodologies across multinational clients.
Employee engagement encompasses the measurable emotional and behavioral commitment of workers toward organizational objectives, typically assessed through pulse surveys, sentiment analysis algorithms, and recognition frequency metrics with response-rate benchmarks above 70%. The primary commercial purpose centers on reducing voluntary turnover costs and lifting productivity per full-time equivalent. Cloud-based delivery models lead the market as subscription economics replace perpetual license structures, while large enterprises generate the deepest margin pools due to multi-module implementations and dedicated customer success resources. Healthcare verticals represent an emerging application area as patient-safety outcomes correlate with nursing staff engagement scores.
The U.S. Department of Labor enforces record-keeping standards that shape how engagement data interfaces with overtime and wage calculations, while the Equal Employment Opportunity Commission monitors survey instruments for discriminatory question design. ISO 30414 human capital reporting standards from Geneva are pressuring multinational employers to disclose workforce sentiment metrics in annual filings. Stakeholders must weigh platform interoperability against the risk of vendor lock-in as engagement data becomes embedded in broader people-analytics architectures.
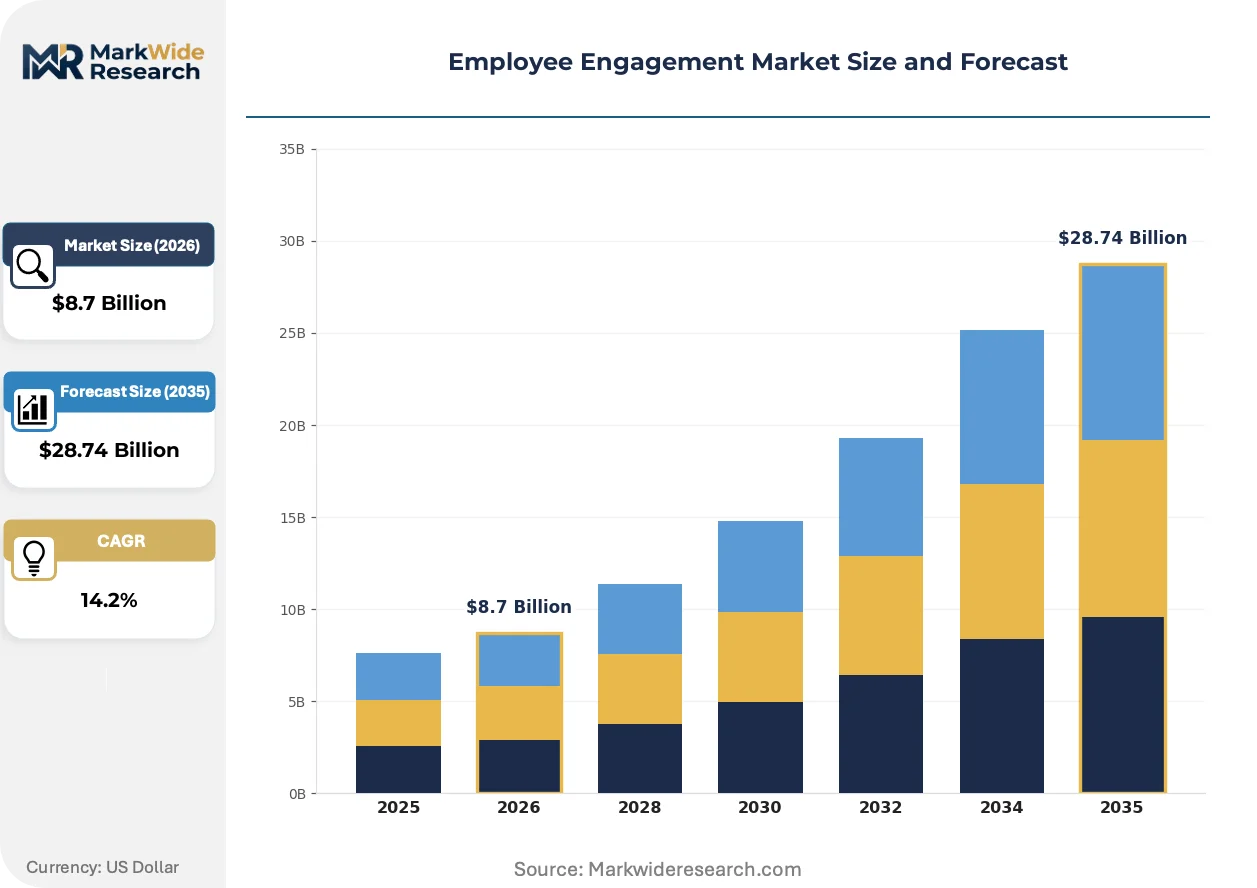
Market Dynamics
Hybrid work arrangements are fragmenting traditional engagement touchpoints, forcing HR technology stacks to consolidate pulse feedback, recognition systems, and performance analytics into unified cloud architectures that can sustain workforce connection across distributed geographies.
Growth Catalysts
- ISO 30414 Disclosure Mandates:Geneva-based human capital reporting standards now require workforce sentiment metrics in annual filings, compelling Fortune 500 employers to procure certified engagement platforms that generate auditable sentiment data.
- Healthcare Staffing Correlation:Patient-safety outcome studies linking nursing engagement scores to mortality reduction are driving hospital systems to adopt real-time feedback systems for clinical workforce retention.
- Cloud Subscription Economics:Perpetual license structures are yielding to recurring revenue models, lowering upfront procurement barriers and expanding platform access to mid-market employers previously priced out of enterprise implementations.
Market Restraints
- Vendor Lock-in Risk:Deep embedding of engagement data within broader people-analytics architectures creates switching costs that deter platform migration even when functionality lags competitive alternatives.
- Survey Fatigue Saturation:Response-rate benchmarks above 70% are becoming harder to sustain as employees face redundant pulse instruments across overlapping HR systems, degrading data quality.
- EEOC Compliance Friction:The Equal Employment Opportunity Commission monitors survey instruments for discriminatory question design, creating legal review overhead that extends implementation timelines for multinational employers.
Strategic Opportunities
- AI-Enhanced Sentiment Analysis:Natural language processing convergence with behavioral analytics is enabling real-time emotion detection in written communications, opening predictive intervention capabilities for attrition risk.
- Embedded Marketplace Distribution:Human capital management suites are opening API ecosystems that allow engagement modules to integrate as native features within payroll and benefits platforms, reducing standalone sales friction.
- Frontline Worker Penetration:Manufacturing and logistics verticals with high hourly employee concentrations remain underpenetrated relative to knowledge-worker sectors, representing expansion headroom for mobile-first feedback tools.
Industry Challenges
- Data Science Talent Scarcity:Interpretation of psychometric survey outputs requires specialized organizational psychology expertise that outstrips supply, forcing vendors to build automated insight engines or absorb consulting costs.
- Legacy HRIS Integration Complexity:Synchronization with decades-old payroll and benefits administration systems demands custom middleware development that erodes margins on mid-market contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Employee Engagement Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platforms, Tools, Solutions Delivery Model: Cloud-based, On-premises, Hybrid, Managed Services Industry Vertical: Healthcare, Manufacturing, Technology, Retail Client Type: SMEs, Large Enterprises, Non-profits, Government |
| Companies Covered | Achievers, WorkTango, Workhuman, Peakon, Motivosity, Lattice, Leapsome, Quantum Workplace, Culture Amp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Employee Engagement Market Emerging Trajectories
Artificial intelligence is compressing the feedback loop between workforce sentiment detection and managerial action, transforming engagement from retrospective measurement into real-time intervention capability.
Virtual reality training environments are virtualizing onboarding and team-building experiences for distributed workforces. Technology sector employers with fully remote engineering teams are deploying immersive spaces for cultural transmission at scale. This modality is virtualizing the spatial proximity that previously sustained informal social cohesion in headquarters-centric organizations.
The EU AI Act's risk classification framework is imposing algorithmic accountability requirements on automated sentiment scoring systems. Vendors must now document training data provenance and bias testing for emotion-recognition features deployed in European workplaces. Multinational platform providers are segregating EU instances to isolate compliance scope, adding operational overhead that favors larger vendors with dedicated legal engineering resources.
Buyer concentration among technology sector employers is consolidating procurement authority within centralized people-operations functions. Discrete departmental purchases of point solutions are giving way to enterprise-wide platform selections governed by chief human resource officers with multi-year roadmap authority. This pattern is most pronounced in the United States, where venture-backed employers with rapid headcount growth prioritize scalable infrastructure over best-of-breed feature depth.
Employee Engagement Market Segmentation
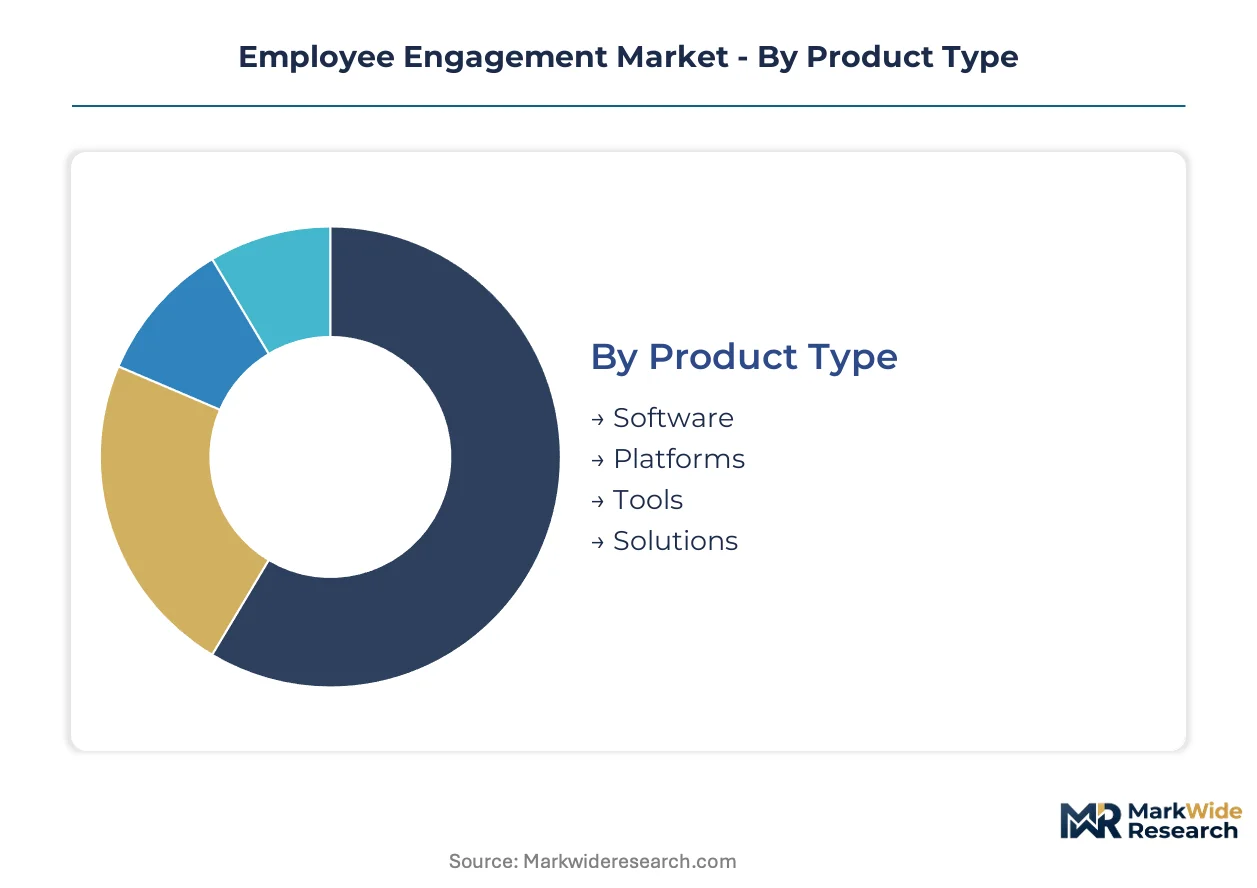
Segmentation in employee engagement technology reveals how procurement patterns diverge by infrastructure maturity, regulatory exposure, and workforce composition. Vendors must align subscription tiers, deployment architectures, and vertical feature sets against these fault lines to capture margin pools.
Product Type:
After-sales service intensity varies sharply across product categories, with integrated platforms demanding dedicated customer success teams while standalone tools rely on self-service knowledge bases.
- Software:Modular applications addressing single use cases such as pulse surveys or recognition catalogs. Healthcare systems in the United States prioritize these for rapid deployment without platform overhaul.
- Platforms:Unified architectures combining feedback, analytics, and action workflows. Technology sector employers concentrate demand here for scalable infrastructure across distributed engineering teams.
- Tools:Point solutions with narrow functional scope. Manufacturing verticals adopt these for shop-floor feedback kiosks where integration depth matters less than deployment speed.
- Solutions:Bundled offerings combining software, consulting, and change management. Large enterprises procuring multi-year contracts generate the deepest margin pools for this category.
By volume, Software leads. By growth pace, Platforms are climbing the fastest.
Delivery Model:
Cost tier differentiation separates subscription-heavy cloud offerings from capital-intensive on-premises installations, with hybrid architectures capturing mid-market employers seeking phased migration paths.
- Cloud-based:Multi-tenant SaaS architectures with monthly or annual subscription billing. United States technology employers drive concentration here due to rapid headcount scaling requirements.
- On-premises:Single-tenant deployments within client data centers. European healthcare systems facing GDPR data residency mandates sustain demand despite higher total cost of ownership.
- Hybrid:Split architectures with sensitive data on-premises and analytics in cloud instances. Manufacturing clients with legacy ERP dependencies favor this model for staged modernization.
- Managed Services:Vendor-operated private cloud with dedicated infrastructure. Government clients in the United States requiring FedRAMP authorization concentrate procurement in this tier.
By deployment count, Cloud-based dominates. By contract value expansion, Managed Services is gaining share fastest.
Industry Vertical:
Application-specific requirements reshape feature roadmaps, with healthcare demanding patient-safety correlation tools and manufacturing prioritizing offline-capable mobile interfaces.
- Healthcare:Systems linking nursing engagement scores to mortality outcomes. Hospital networks in the United States and Germany are expanding procurement of real-time feedback tools for clinical workforce retention.
- Manufacturing:Environments with high hourly worker concentrations and limited desktop access. Mobile-first platforms with offline synchronization capture demand across automotive and logistics sub-sectors.
- Technology:Knowledge-worker dense employers with distributed teams. Fully remote engineering organizations drive adoption of VR-enabled onboarding and asynchronous recognition systems.
- Retail:High-turnover frontline workforces with seasonal scaling needs. Franchise operators prioritize low per-seat pricing and rapid deployment without IT infrastructure investment.
By current platform penetration, Technology leads. By expansion trajectory, Healthcare shows the steepest growth.
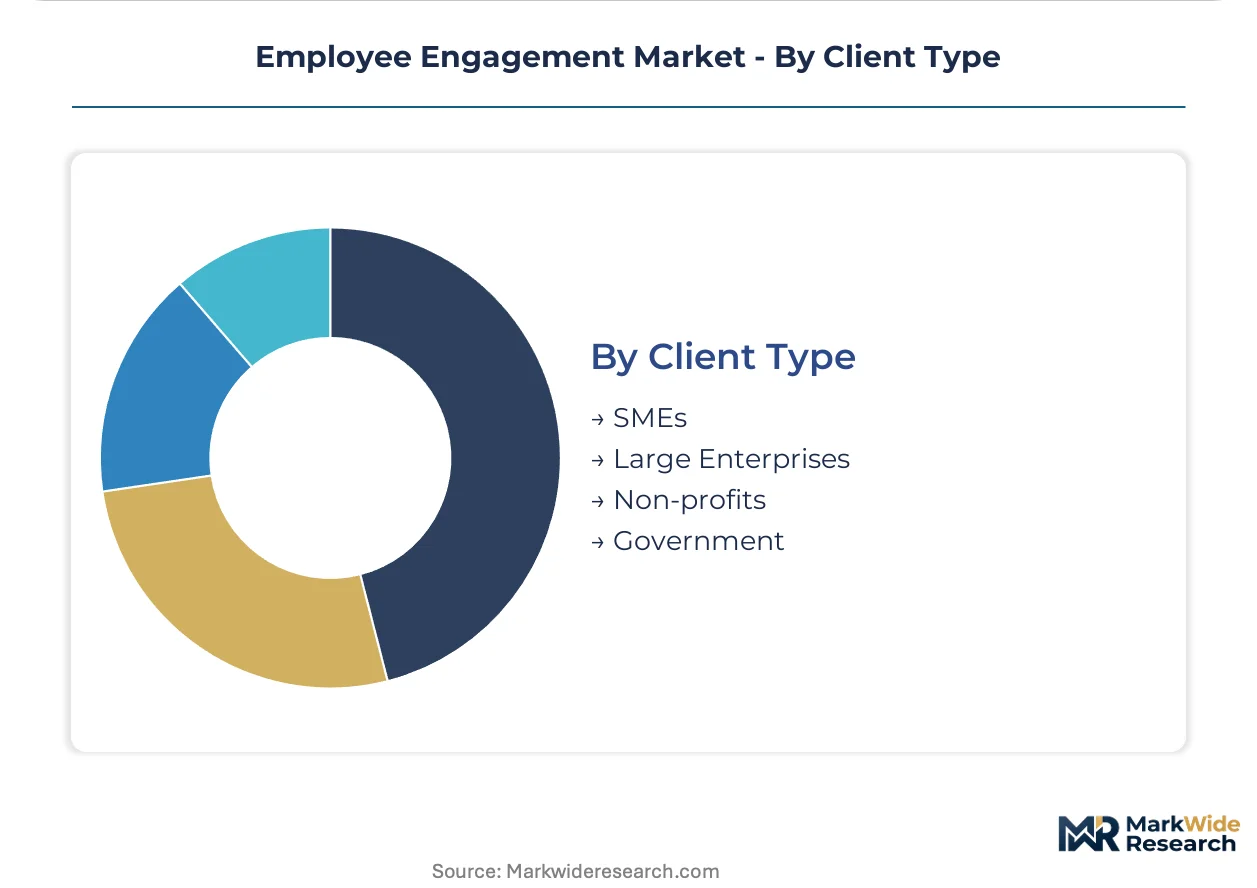
Client Type:
Customer type determines sales motion complexity, with large enterprises demanding security audits and custom integrations while SMEs self-serve through product-led growth channels.
- SMEs:Employers with under 500 employees seeking rapid deployment without dedicated IT resources. Cloud-based subscription tiers with standardized configurations capture this segment.
- Large Enterprises:Organizations with multi-module implementations and dedicated customer success resources. These clients generate recurring revenue stability through three to five year contract structures.
- Non-profits:Mission-driven organizations with constrained procurement budgets. Discounted pricing tiers and grant-funded implementations characterize this segment.
- Government:Public sector employers with stringent security and accessibility requirements. FedRAMP, Section 508, and country-specific compliance certifications gate vendor participation.
By active platform count, Large Enterprises lead. By new customer acquisition velocity, SMEs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' dense fiber-optic backbone and cloud data center concentration underwrites its dominance in enterprise SaaS procurement for workforce analytics platforms.
United States
Corporate HR departments at technology sector employers drive concentrated demand for integrated engagement platforms with multi-module implementations. The Equal Employment Opportunity Commission monitors survey instruments for discriminatory question design, extending implementation timelines for multinational employers. The San Francisco Bay Area and Seattle metropolitan clusters anchor venture-backed employers prioritizing scalable infrastructure over best-of-breed feature depth.
Germany
Industrial manufacturing employers with high hourly worker concentrations sustain demand for mobile-first feedback tools with offline synchronization capabilities. The EU AI Act's risk classification framework imposes algorithmic accountability requirements on automated sentiment scoring systems deployed in European workplaces. The Bavaria and Baden-Württemberg automotive clusters are expanding procurement of shop-floor feedback kiosks for workforce retention.
United Kingdom
Financial services and professional services firms in London drive adoption of pulse survey and recognition systems for distributed knowledge workers. The UK Information Commissioner's Office enforces GDPR-aligned data residency mandates that shape cloud procurement decisions for multinational employers. The London-Southeast corridor concentrates demand for platforms combining psychometric science with benchmarked survey methodologies.
India
Technology sector employers with rapid headcount growth and hybrid work arrangements are accelerating procurement of cloud-based engagement platforms. The country's national data protection authority is developing localization requirements that influence vendor selection for workforce analytics. The Karnataka and Telangana technology corridors in Bangalore and Hyderabad are expanding adoption of digital feedback systems for engineering workforce retention.
Japan
Large enterprises with lifetime employment traditions are modernizing engagement measurement through sentiment analysis and asynchronous recognition systems. METI's human capital disclosure guidelines pressure listed companies to report workforce sentiment metrics in annual filings. The Tokyo metropolitan area concentrates demand for platforms integrating with legacy HRIS systems prevalent in established corporations.
Employee Engagement Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform architectures that combine pulse feedback, recognition systems, and performance analytics into unified cloud offerings. Tiered competitive positioning separates global reward fulfillment networks, psychometric science specialists, and modular performance management providers. Dominant competitive moves include strategic partnerships with human capital management suites and embedded marketplace distribution through API ecosystems.
Within the integrated platform tier, Workhuman and Lattice exemplify archetypes leveraging global infrastructure and modular workflow extension respectively. Culture Amp occupies a position anchoring psychometric methodology specialization for multinational clients. Among recognition-centric providers, Achievers and WorkTango represent vendors competing through reward fulfillment networks and feedback system integration. These companies collectively illustrate how vendor strategies diverge between deep vertical integration into reward logistics and horizontal platform expansion across HR technology stacks.
| Leading Market Players |
|---|
| Achievers |
| WorkTango |
| Workhuman |
| Peakon |
| Motivosity |
| Lattice |
| Leapsome |
| Quantum Workplace |
| Culture Amp |
| Others |
Supply Flow & Price Mechanics
The trans-Pacific fiber-optic cable corridor connecting Singapore to Los Angeles carries the bulk of cloud data traffic for engagement platform providers, with bandwidth cost dynamics concentrating supply among vendors operating multi-tenant SaaS architectures while forcing three-tier pricing differentiation between enterprise, mid-market, and self-service tiers.
Pricing Analysis
Volume-discount tiering structures separate Fortune 500 deployments from mid-market subscriptions, with pricing stratifying across enterprise-grade, professional, and basic tiers based on module count and dedicated customer success resources. ISO 30414 certification premiums add margin to top-tier offerings, while cost compression in the self-service segment intensifies as product-led growth vendors compete for SME acquisition. Healthcare systems exhibit the highest price sensitivity due to constrained capital budgets, whereas technology sector employers prioritize scalability over per-seat economics.
Supply Chain Analysis
Supplier-financing facilities from cloud infrastructure providers extend payment terms for platform vendors, anchoring supply concentration in the United States, Ireland, and Singapore where hyperscaler data center density supports low-latency service delivery. Software development draws from specialized talent pools in India and Poland, while reward fulfillment networks rest on logistics partnerships across Germany and the Netherlands. Single-source vulnerability in AI model training data creates exposure, with distribution running through direct enterprise sales and embedded marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent engagement platform vendors face substitution pressure from human capital management suites integrating native feedback modules, requiring defensive repositioning to preserve standalone platform relevance.
For Market Incumbents: Pre-empt HCM suite absorption by deepening API ecosystem partnerships that embed engagement functionality within payroll and benefits workflows. Fortify data moats through psychometric methodology patents and longitudinal workforce benchmark databases that resist replication by generalist competitors. Prioritize ISO 30414 certification investment to capture Fortune 500 procurement mandates.
For New Entrants and Emerging Players: Manufacturing shop floors in Germany and the United States present underpenetrated white space, with hourly worker populations lacking desktop access and demanding mobile-first offline-capable interfaces. Target franchise retail operators through low per-seat pricing and rapid deployment without IT infrastructure investment. Pursue vertical-specific positioning linking engagement metrics to patient safety outcomes in hospital systems.
For Investors and Strategic Acquirers: Specialized sentiment analysis engines with natural language processing capabilities represent the priority acquisition archetype, as AI-enhanced emotion detection becomes table stakes for attrition prediction. Monitor EEOC enforcement patterns around survey question design as an inflection indicator for compliance overhead and vendor consolidation pressure. Long-term viability favors platforms with demonstrated healthcare vertical traction and established FedRAMP authorization pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Embedding engagement modules within Workday and SAP SuccessFactors reduces standalone sales friction for enterprise procurement. |
| ISO 30414 Certification Investment | Auditable sentiment data capabilities unlock Fortune 500 mandates driven by Geneva human capital disclosure standards. |
| Healthcare Vertical Specialization | Nursing engagement correlation tools capture hospital system budgets linking workforce metrics to mortality reduction outcomes. |
| Mobile-First Frontline Development | Offline-capable shop-floor interfaces address manufacturing and logistics sectors with limited desktop infrastructure. |
| AI Sentiment Engine Acquisition | Natural language processing capabilities enable real-time attrition prediction that differentiates platform value propositions. |
Methodological Framework
Initial hypotheses were tested against primary input from chief human resource officers, people operations directors, platform engineers, and healthcare workforce executives and refined through secondary validation against SEC filings, ISO standard documentation, hospital procurement databases, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated with top-down market sizing across deployment models, organization scales, vertical applications, and regional adoption patterns.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with growth trajectories derived from modeled expansion in cloud subscription economics, healthcare staffing correlation adoption, and frontline worker penetration. Segmentation dimensions included product architecture, delivery model, industry vertical, and client size tier. Forecast inputs incorporated ISO 30414 implementation timelines and EU AI Act compliance cost assumptions.
Practitioners should monitor EEOC enforcement intensity, EU AI Act implementation pace, and healthcare labor shortage severity for early signals of forecast revision triggers. Macroeconomic contraction affecting enterprise software budgets, regulatory deviation in data residency requirements, or technological disruption from generative AI interfaces would prompt forecast reassessment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Global Intranet As a Service Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Proactive Services Market
Enterprise Services
Digital Mailroom Services Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
Asia Pacific Enterprise Collaboration Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Middle East and Africa Enterprise Software Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Global Enterprise Data Integration Market