
 Enterprise Content Management (ECM) Market | 2026-2036
Enterprise Content Management (ECM) Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Content Management (ECM) Market Intelligence
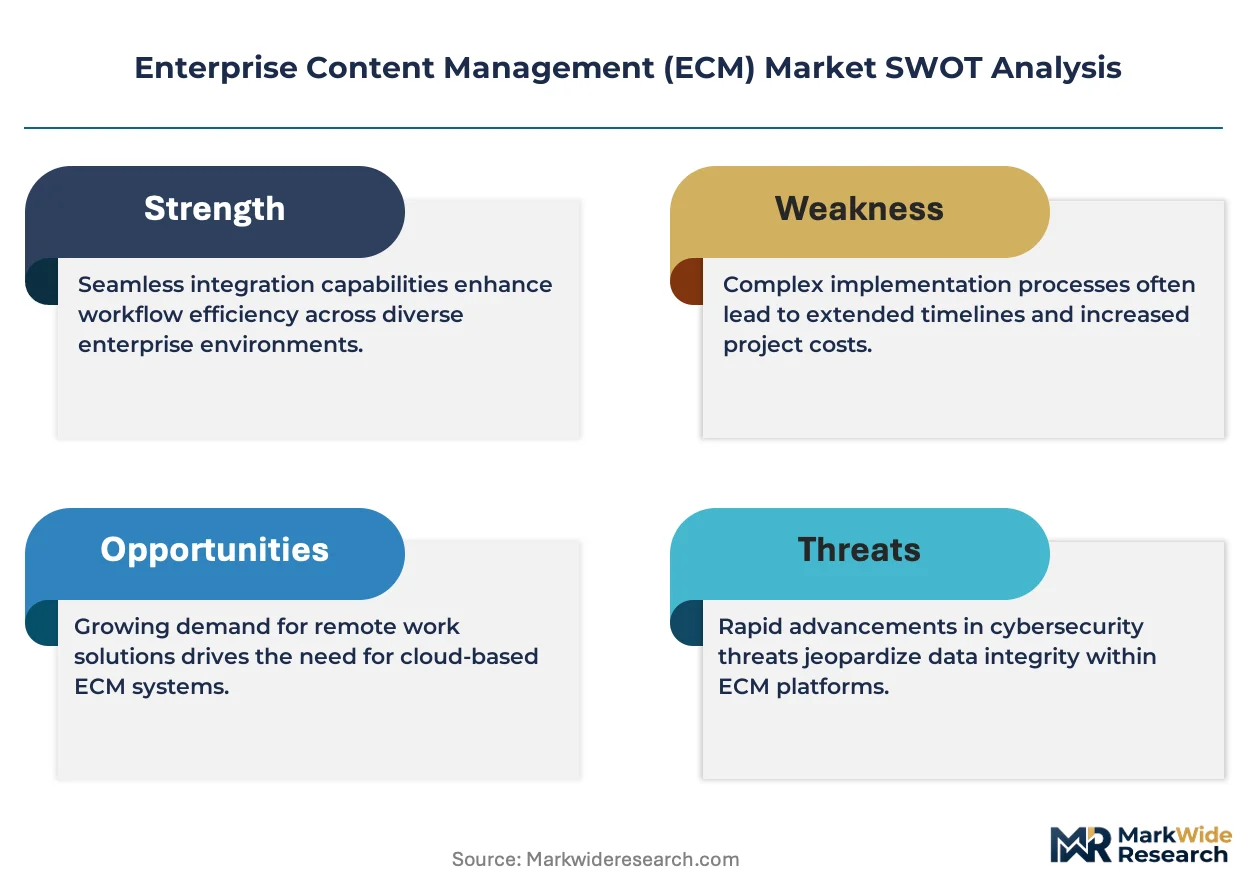
ISO 27001 certification is redrawing competitive boundaries in ECM procurement, as enterprise buyers disqualify vendors lacking audited information security management systems. OpenText leverages deep vertical integration across capture-to-archive workflows to sustain large government contracts. Microsoft SharePoint anchors hybrid deployment strategies for organizations navigating cloud transitions. Hyland specializes in industry-specific content services, differentiating through configurable records management for regulated sectors.
Enterprise Content Management encompasses software systems that ingest, store, manage, and deliver structured and unstructured content across document lifecycles, typically supporting full-text indexing, metadata tagging, version control, and retention policy enforcement to ensure information discoverability and legal defensibility. Its primary commercial purpose is to reduce operational risk while accelerating process velocity in document-intensive workflows. Cloud-based deployment now leads new implementations as organizations retire on-premises infrastructure, though hybrid architectures retain strong positioning in financial services where data residency requirements persist. Document Management solutions occupy the largest solution segment by installed base, while Workflow Automation captures expanding margin pools as enterprises prioritize process orchestration over passive storage.
FDA 21 CFR Part 11 in the United States and EU GDPR impose stringent audit trails and data integrity requirements that directly shape ECM feature roadmaps, particularly in pharmaceutical and healthcare deployments where electronic records must withstand regulatory inspection. BIS data localization guidelines in India and China's GB/T standards for electronic document management further fragment compliance requirements for multinational vendors. Organizations must evaluate whether their ECM architecture can satisfy divergent sovereignty mandates without proliferating instance sprawl.
Market Dynamics
Cloud migration mandates from EU data sovereignty requirements are forcing enterprises to re-architect legacy document repositories while maintaining cross-border compliance, compressing procurement cycles and elevating security certification to a disqualifying threshold.
Growth Catalysts
- EU GDPR enforcement:Article 30 record-keeping obligations compel mid-market enterprises to deploy auditable ECM platforms, expanding addressable demand beyond traditional regulated industries.
- Pharmaceutical serialization:FDA 21 CFR Part 11 mandates for electronic batch records drive validated system upgrades across contract manufacturing organizations.
- India's BIS localization:Data residency guidelines for public sector procurement create captive demand for domestic-hosted document management infrastructure.
Market Restraints
- Hyperscaler concentration:Cloud infrastructure dependency on three dominant providers concentrates supply risk and limits negotiation leverage for enterprise buyers.
- Encryption export controls:US EAR regulations create deployment friction for multinational organizations requiring consistent security architectures across jurisdictions.
- Legacy system entrenchment:Decades of on-premises document repositories with custom integrations generate technical debt that retards cloud transition velocity.
Strategic Opportunities
- Process mining convergence:Integration of ECM with Celonis-style workflow analytics creates new value pools in operational excellence consulting.
- US state-level privacy laws:California CPRA and Virginia VCDPA patchwork generates compliance complexity that favors modular, policy-engine-driven platforms.
- Small-molecule pharma outsourcing:Contract research organizations in Eastern Europe and India lack mature document governance, representing greenfield deployment potential.
Industry Challenges
- Information governance expertise scarcity:Shortage of certified records managers capable of designing retention schedules across multinational regulatory regimes slows implementation timelines.
- API standardization gaps:Proprietary connector ecosystems between ECM platforms and adjacent enterprise applications force expensive custom integration work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Content Management (ECM) Market |
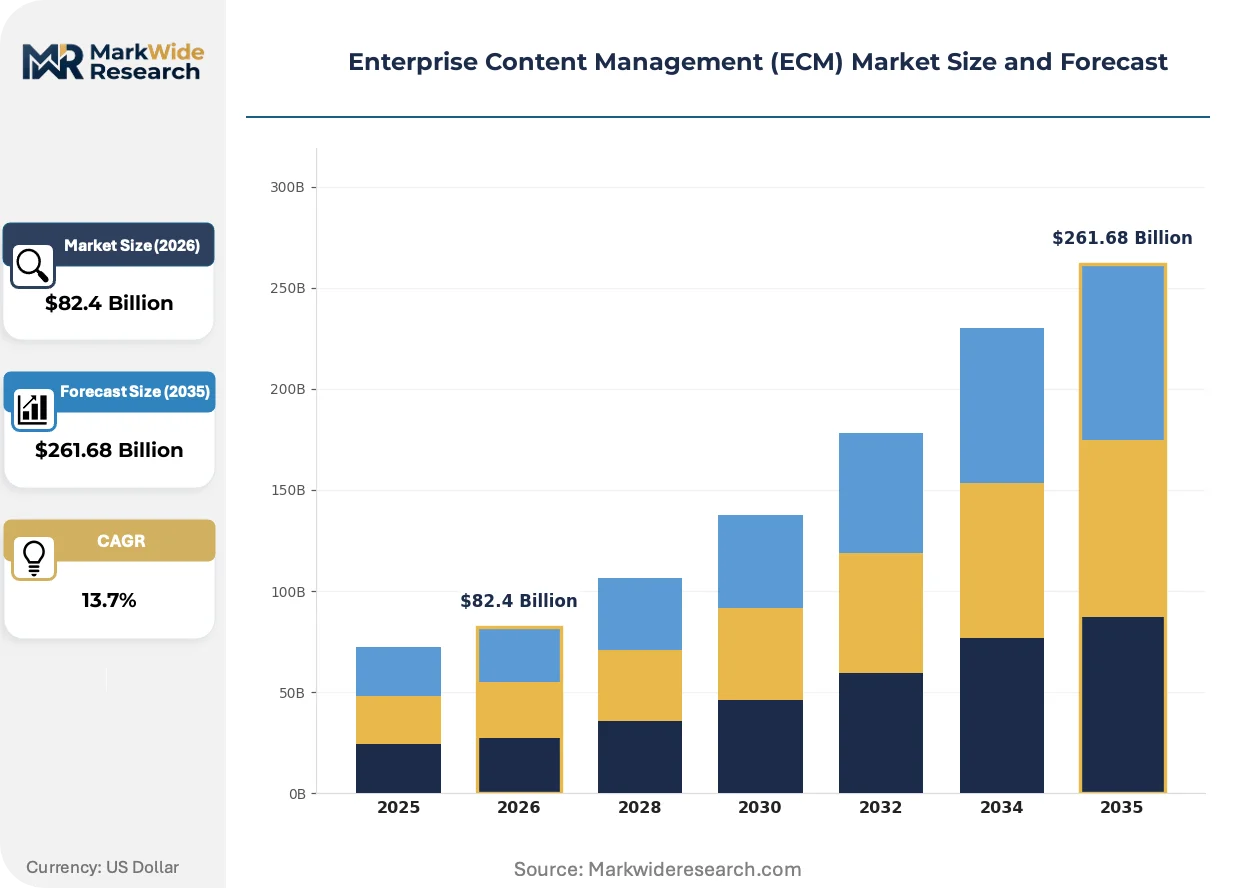
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $261.68 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution/Offering: Document Management, Workflow Automation, Records Management, Digital Asset Management, Capture Solutions, Process Management Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Managed Services Application: Compliance Management, Business Process Optimization, Knowledge Management, Risk Mitigation, Customer Communication, Contract Management End User: Banking Institutions, Legal Firms, Government Agencies, Education Institutions, Manufacturing Plants, Telecommunications Providers |
| Companies Covered | iManage, Oracle, Box, Xerox DocuShare, M-Files, Hyland, Microsoft SharePoint, OpenText, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Content Management (ECM) Market Strategic Shifts & Innovations
Artificial intelligence is embedding into content services at three distinct vectors: automated classification, predictive retention, and generative extraction. These capabilities are compressing implementation cycles while raising new governance questions about algorithmic decision-making in regulated workflows.
Intelligent document processing is bifurcating the capture market into two tiers. Machine learning models now extract structured data from unstructured sources with minimal template configuration. Financial services operations teams are deploying these tools for loan origination and claims processing at unprecedented scale. The technology is bifurcating vendor positioning between horizontal platform providers and vertical specialists with pre-trained industry models.
EMA's evolving GxP data integrity guidance is tightening audit trail requirements for electronic records in pharmaceutical manufacturing. The guideline's emphasis on ALCOA+ principles is forcing legacy system upgrades or replacement. European biotech firms are prioritizing platforms with pre-validated configurations to accelerate regulatory inspection readiness.
Subscription consumption models are displacing perpetual licensing in enterprise procurement. Chief information officers now demand usage-based pricing aligned to actual document volumes rather than seat counts. This shift is most pronounced in North American healthcare systems navigating capital constraint pressures from reimbursement compression.
Enterprise Content Management (ECM) Market Segmentation
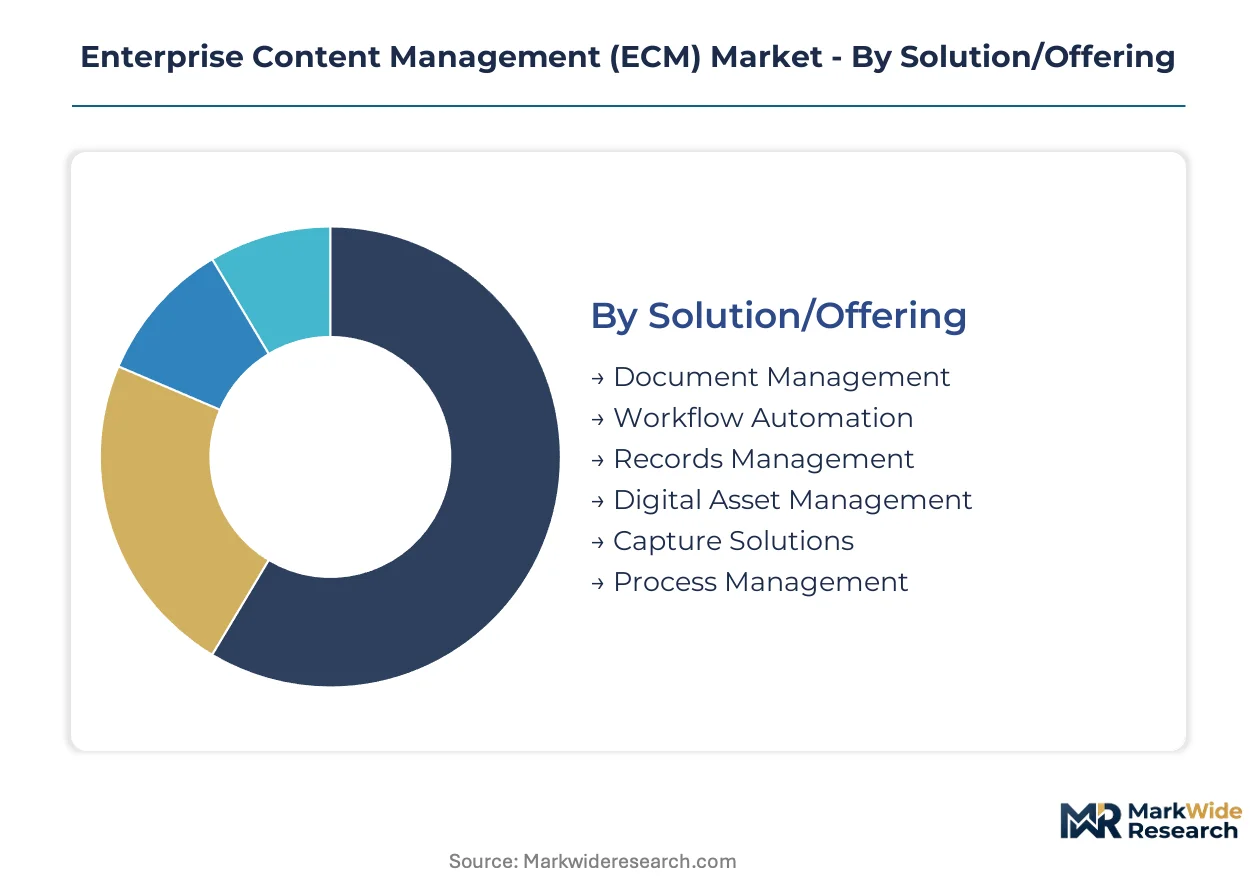
ECM procurement patterns diverge sharply across solution architectures and deployment models. Buyers prioritize segments that compress compliance cycles while minimizing infrastructure transition risk.
Solution/Offering:
Margin pools concentrate in workflow orchestration capabilities rather than passive storage infrastructure.
- Document Management:Core repository functionality with full-text indexing, metadata schemas, and version control. Banking institutions in the United States drive replacement demand as legacy file shares reach end-of-life.
- Workflow Automation:Process engines that route content through approval hierarchies with SLA enforcement. Pharmaceutical manufacturers deploy these systems to compress batch record review cycles under FDA 21 CFR Part 11 pressure.
- Records Management:Retention schedule enforcement with legal hold capabilities. GDPR Article 30 obligations expand mid-market adoption beyond traditional regulated sectors.
- Digital Asset Management:Media-centric libraries with transcoding and rights management. Marketing organizations in consumer goods sectors deploy for brand consistency across distributed teams.
- Capture Solutions:Scanning and ingestion infrastructure with OCR and classification. Insurance claims departments prioritize these tools for straight-through processing.
- Process Management:Low-code workflow design with case management capabilities. Government agencies adopt for citizen service delivery modernization.
Document Management holds installed capacity. Workflow Automation is rotating up the share rankings.
Deployment:
Cloud migration velocity varies by data residency constraints and integration complexity.
- On-Premises:Dedicated infrastructure with direct hardware control. Defense contractors and classified government facilities maintain this architecture for air-gapped security requirements.
- Cloud-Based:Multi-tenant SaaS with elastic scaling and automatic updates. North American healthcare systems favor this model to shift capital expenditure to operational budgets under reimbursement compression.
- Hybrid:Split architecture with sensitive content on-premises and collaborative workflows in cloud. European financial services deploy this pattern to satisfy GDPR data sovereignty while enabling remote access.
- Hosted:Single-tenant cloud with dedicated instance isolation. Mid-market legal firms select this for client-matter confidentiality without internal infrastructure management.
- Managed Services:Outsourced administration with SLA-guaranteed uptime. Organizations lacking internal information governance expertise contract these arrangements.
Cloud-Based deployments are climbing the fastest. On-Premises retains defensive positions in sensitive sectors.
Application:
Functional use cases map directly to regulatory pressure intensity and process digitization maturity.
- Compliance Management:Audit trail generation and regulatory reporting automation. FDA-regulated manufacturers prioritize this application for inspection readiness.
- Business Process Optimization:Cycle time reduction through elimination of manual handoffs. Loan origination in banking institutions achieves measurable throughput gains.
- Knowledge Management:Expertise capture and enterprise search across unstructured repositories. Professional services firms deploy to reduce knowledge attrition from employee turnover.
- Risk Mitigation:Early warning systems combining content analytics with policy enforcement. Insurance underwriters integrate claims documentation for fraud detection.
- Customer Communication:Omni-channel correspondence management with preference enforcement. Telecommunications providers centralize billing disputes and service requests.
- Contract Management:Lifecycle tracking from negotiation through renewal with obligation extraction. Procurement organizations in manufacturing reduce revenue leakage from unfavorable terms.
Compliance Management anchors procurement budgets. Business Process Optimization is gaining share fastest.
End User:
Vertical specialization requirements fragment vendor positioning across buyer categories.
- Banking Institutions:Transaction documentation with anti-money laundering integration. Basel III record-keeping obligations drive platform refreshes in commercial and retail banking.
- Legal Firms:Matter-centric organization with ethical wall enforcement and billing integration. AmLaw 200 firms invest in AI-assisted contract analysis for due diligence acceleration.
- Government Agencies:FOIA response automation and long-term archival with format migration. Federal records schedules mandate retention periods exceeding commercial norms.
- Education Institutions:Student record management with FERPA privacy controls. Research universities add grant administration and intellectual property tracking.
- Manufacturing Plants:Engineering change orders and supplier quality documentation. ISO 9001 certification audits require demonstrable document control.
- Telecommunications Providers:Interconnection agreements and regulatory filing management. FCC compliance drives retention of spectrum license documentation.
Banking Institutions command the largest contract values. Legal Firms are expanding fastest in AI-enhanced segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 enforcement and GDPR Article 30 record-keeping obligations are accelerating ECM procurement across document-intensive industries, with sovereign data requirements fragmenting deployment architectures by jurisdiction.
United States
Banking institutions in New York and Chicago drive replacement demand as legacy file shares reach end-of-life. FDA 21 CFR Part 11 mandates for electronic batch records force validated system upgrades across pharmaceutical manufacturers in New Jersey and Massachusetts. Boston's contract research organization cluster prioritizes platforms with pre-validated configurations to accelerate regulatory inspection readiness.
Germany
Automotive suppliers in Stuttgart and Munich deploy ECM for engineering change order documentation under ISO 9001 certification pressure. EU GDPR data sovereignty requirements compel mid-market enterprises to deploy auditable platforms with local hosting. Frankfurt's financial services sector adopts hybrid architectures to satisfy regulatory mandates while enabling remote access.
United Kingdom
London's legal sector invests in AI-assisted contract analysis for due diligence acceleration amid competitive pressure. The Information Commissioner's Office enforces GDPR compliance with escalating fines, expanding ECM demand beyond traditional regulated industries. Edinburgh's asset management firms centralize correspondence management for regulatory filing automation.
India
BIS data localization guidelines for public sector procurement create captive demand for domestic-hosted document management infrastructure. Mumbai's banking sector accelerates platform refreshes under RBI record-keeping obligations. Bangalore's technology services firms build offshore delivery capabilities for Western pharmaceutical clients requiring 21 CFR Part 11 compliant documentation.
Japan
Pharmaceutical manufacturers in Osaka and Tokyo face PMDA inspection readiness pressure for electronic batch records. METI industrial digitization incentives support SME migration from paper-based document control. Yokohama's chemical sector implements retention schedule enforcement systems under tightening environmental documentation requirements.
Enterprise Content Management (ECM) Market Key Industry Players
Player mix skews toward diversified enterprise software conglomerates with adjacent productivity platform leverage. Market structure concentrates around vendors with vertical integration across capture-to-archive workflows and those anchoring hybrid deployment strategies. Three strategic archetypes dominate: legacy enterprise software providers with deep government relationships, cloud-native collaboration platforms extending into content services, and specialists in regulated industry compliance. Competitive moves center on ISO 27001 certification acquisition as a procurement threshold and AI-driven intelligent document processing capability integration.
Within the enterprise software tier, OpenText and Oracle exemplify vendors sustaining large government contracts through deep workflow integration. Hyland occupies a position as a specialist in configurable records management for regulated sectors. Microsoft SharePoint anchors hybrid deployment strategies for organizations navigating cloud transitions, representing the productivity-platform-extension archetype.
| Leading Market Players |
|---|
| iManage |
| Oracle |
| Box |
| Xerox DocuShare |
| M-Files |
| Hyland |
| Microsoft SharePoint |
| OpenText |
| IBM |
| Others |
Cost & Logistics Intelligence
Capacity reservation contracts with tier-one cloud infrastructure providers lock in both compute access and cost visibility for enterprise ECM deployments, insulating pharmaceutical manufacturers from spot-market volatility while embedding data sovereignty compliance into procurement terms.
Pricing Analysis
Certification level creates the primary spread between ECM tiers, with ISO 27001-audited platforms commanding substantial premiums over uncertified alternatives. Subscription consumption models now dominate enterprise procurement, displacing perpetual licensing as healthcare systems shift capital expenditure to operational budgets. Price differentiation stems from compliance grade and integration complexity, with mid-market buyers exhibiting acute sensitivity to per-seat costs while federal contractors prioritize security accreditation regardless of premium. Cost compression in the standard tier intensifies as hyperscaler bundling erodes standalone vendor margins.
Supply Chain Analysis
Just-in-time provisioning dominates cloud-native ECM delivery, though European financial services maintain strategic stockpiles of on-premises infrastructure to satisfy GDPR data residency mandates. Supply concentrates in the United States, Germany, and India, with hyperscaler data center expansion in Frankfurt and Mumbai reshaping regional availability. Raw material dependencies center on specialized encryption hardware, high-availability storage arrays, and GPU clusters for AI-enabled document processing. Single-source vulnerability runs through dominant cloud infrastructure providers, with distribution running through direct enterprise sales teams and systems integrator channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECM vendors capture expanding margin pools in managed services and compliance consulting, with recurring revenue from governance-as-a-service offerings expanding faster than core platform licensing.
For Market Incumbents: Compound defensive positioning through backward integration into AI training infrastructure and captive development of vertical-specific compliance modules. Cloud-native entrants threaten established government contracts with faster deployment cycles, making certification maintenance and pre-validated configuration libraries essential levers for retention. For New Entrants and Emerging Players: Anchor in contract research organizations across Eastern Europe and India, where 21 CFR Part 11 compliance gaps create immediate deployment opportunities. White-space concentration in mid-market pharmaceutical outsourcing favors modular, policy-engine-driven platforms with rapid implementation timelines over entrenched enterprise suites. For Investors and Strategic Acquirers: Capital is best deployed toward specialists with pre-trained industry models and validated regulatory configurations that compress customer time-to-inspection-readiness. Long-term viability hinges on AI differentiation rather than storage commoditization, with the signal to watch being FDA warning letter volume citing electronic record deficiencies as an inflection indicator for replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acquisition | Enterprise procurement teams now disqualify unaudited vendors from RFP shortlists. |
| AI-Enabled Document Processing Integration | Machine learning extraction reduces loan origination cycle times for banking clients. |
| Hybrid Deployment Architecture Development | Split cloud-on-premises models satisfy GDPR sovereignty while enabling remote collaboration. |
| Pre-Validated Regulatory Configuration Libraries | FDA 21 CFR Part 11 compliant templates accelerate pharmaceutical customer inspection readiness. |
| Managed Services Capability Buildout | Governance-as-a-service offerings address certified records manager scarcity in mid-market segments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and regulatory guidance documents from FDA, EMA, and EU data protection authorities. Primary interviews engaged chief information officers, compliance officers at pharmaceutical manufacturers, records managers in financial services, and procurement leads at federal agencies. Bottom-up sizing of installed bases triangulates against top-down addressable market estimates from trade association data and government procurement records.
Segmentation dimensions modeled span deployment architecture, solution type, vertical industry, organization size tier, and regional regulatory cluster across the projection horizon. CAGRs derive from trend extrapolation of replacement cycles, cloud migration velocity, and compliance mandate enforcement intensity, with pharmaceutical serialization timelines and EU data sovereignty rulings serving as industry-specific demand anchors.
Material uncertainties — regulatory enforcement variance, hyperscaler pricing volatility, and AI governance framework evolution — sit outside the modeled envelope. Forecasts reflect assumptions about sustained compliance pressure and cloud infrastructure availability. Revision becomes warranted when FDA 21 CFR Part 11 inspection volume or EU GDPR fine issuance crosses thresholds that accelerate enterprise replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Crop Management Software Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Virtual Workspace Solutions Market
Digital Solutions
In-App Purchase Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Supply Chain Digital Twin Market
Digital Solutions
Business Information Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Ediscovery Solution Market
Digital Solutions
Infrastructure As Code (Iac) Market
Digital Solutions
Europe Electronic Contract Manufacturing and Design Services Market