
 IT Staffing Market | 2026-2036
IT Staffing Market Size, Share, and Industry Trends Forecast 2026-2036
IT Staffing Market Outlook
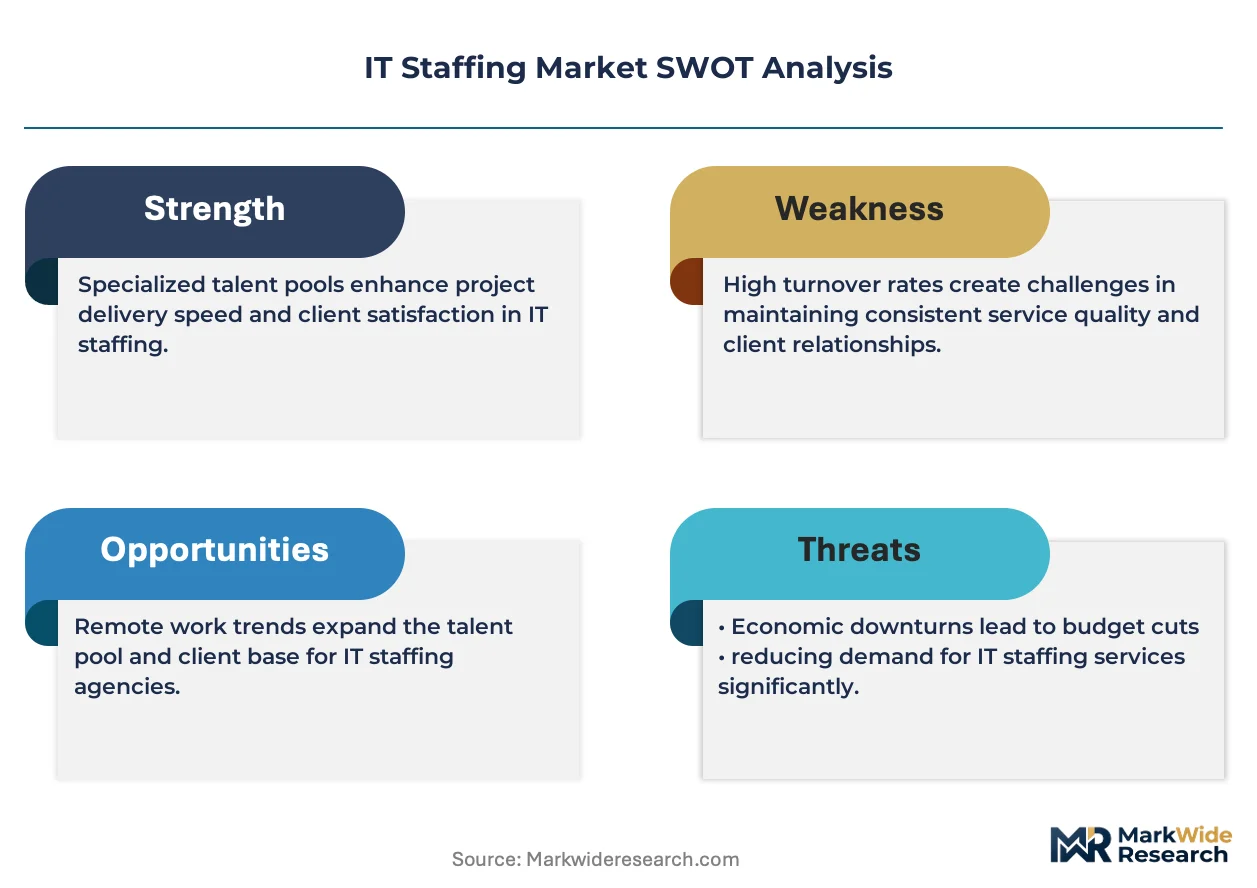
CompTIA Security+ certification renewal cycles is collapsing from three years to annual micro-credentialing, forcing staffing firms to rebuild talent verification pipelines. TEKsystems leverages its proprietary skills assessment platform to sustain placement velocity across cleared government contracts. Robert Half anchors its premium positioning through specialized technology practice groups that compete on speed-to-fill for cybersecurity roles.
IT staffing encompasses the sourcing, vetting, and deployment of technology professionals across temporary, permanent, and project-based engagement models, with deliverables typically governed by service-level agreements specifying time-to-fill metrics and technical competency benchmarks. The practice serves enterprises requiring scalable access to specialized capabilities without fixed employment overhead. Temporary staffing dominates transaction volume while managed services captures disproportionate margin pools through outcome-based pricing tied to system uptime or project completion. Cloud computing and cybersecurity specializations command premium bill rates as client type stratification intensifies, with government agencies imposing stricter clearance requirements than startup clients.
US Equal Employment Opportunity Commission guidelines intersect with ISO 30414 human capital reporting standards to reshape how staffing firms document demographic parity in technology placements. The EU AI Act imposes algorithmic accountability requirements on automated candidate screening tools, compelling vendors to retrofit compliance architectures. Stakeholders must monitor evolving cross-border data localization mandates that determine where talent databases can reside and which credentialing bodies carry reciprocal recognition.
Market Dynamics
CompTIA Security+ certification renewal cycles collapsing from three years to annual micro-credentialing is forcing staffing firms to rebuild talent verification pipelines from scratch. This structural compression in credential validity is reshaping how firms qualify candidates for cleared government contracts and cybersecurity placements.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic accountability requirements for automated candidate screening tools are creating specialized demand for human-in-the-loop vetting services that staffing firms can monetize.
- Financial services contingent workforce expansion:Banks and insurance carriers are scaling temporary technology talent programs to manage regulatory technology implementation without fixed overhead.
- India captive center construction:Multinational corporations building technology centers in Bangalore and Hyderabad are sourcing local staffing partners for scalable workforce deployment.
Market Restraints
- Clearance pipeline bottlenecks:Government agencies impose stricter security clearance requirements than commercial clients, elongating time-to-fill for defense and intelligence placements.
- Cross-border data localization mandates:Talent database residency restrictions in Germany, France, and India fragment credential verification infrastructure across jurisdictional boundaries.
- ISO 30414 reporting complexity:Human capital disclosure standards intersect with EEOC guidelines to increase documentation overhead for demographic parity in technology placements.
Strategic Opportunities
- Cloud specialization premiums:Amazon Web Services and Microsoft Azure certified professionals command bill rate multiples that generalist staffing models cannot capture.
- Managed services outcome pricing:System uptime and project completion guarantees allow margin expansion beyond hourly staffing markups.
- Cybersecurity micro-credential bundling:Rapid certification cycles enable staffing firms to package verified skill stacks as differentiated product offerings.
Industry Challenges
- Skills assessment platform capex:Proprietary technical evaluation tools require continuous investment to maintain placement velocity across cleared contracts.
- Legacy HRIS integration friction:Client enterprise systems demand custom API development for time-tracking and billing reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IT Staffing Market |
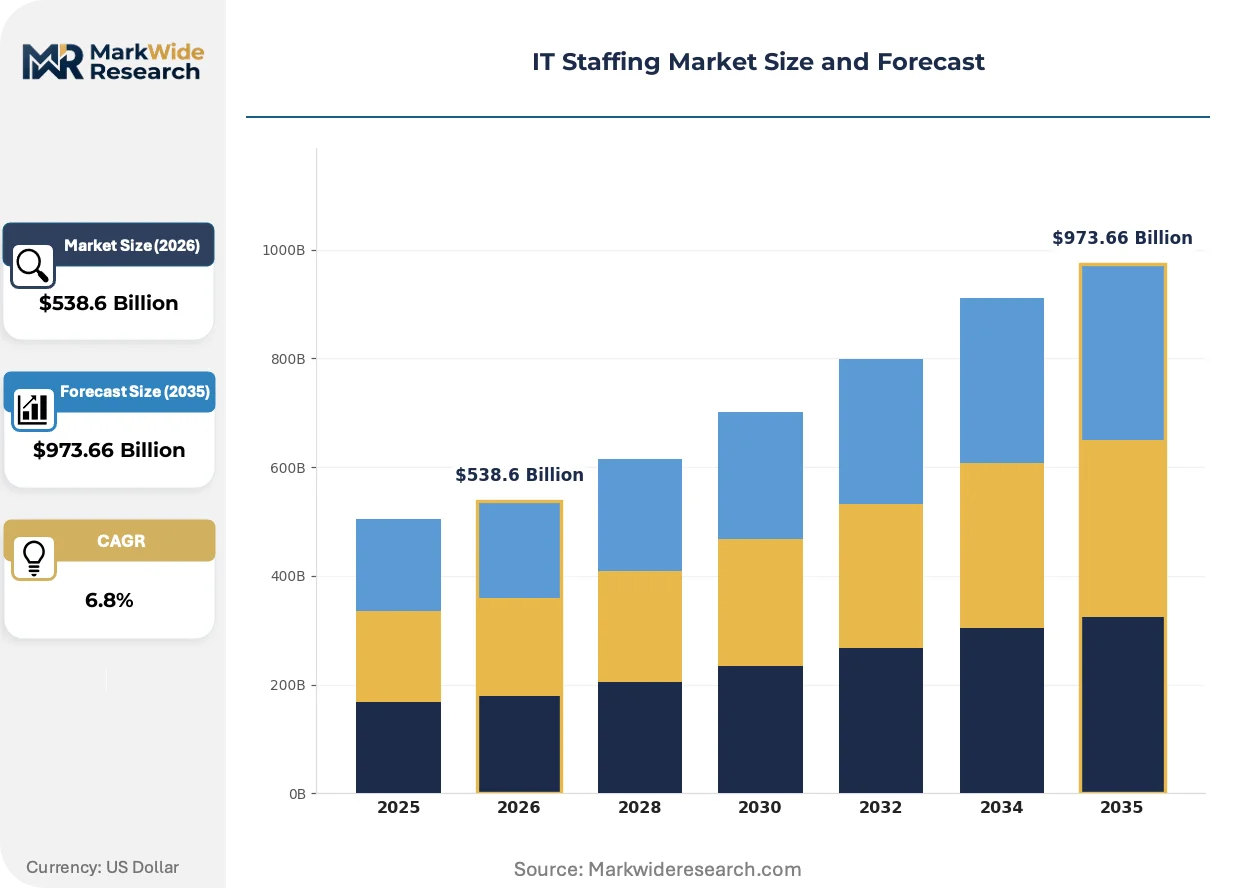
| Market Size in 2026 | $538.6 Billion |
| Market Size in 2035 | $973.66 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Temporary Staffing, Permanent Staffing, Managed Services, Consulting Client Type: Corporates, Startups, Government Agencies, Non-Profits Skill Level: Entry-Level, Mid-Level, Senior-Level, Executive Technology Focus: Cloud Computing, Cybersecurity, Data Analytics, Software Development |
| Companies Covered | Insight Global, Kforce, TEKsystems, Toptal, Akkodis, Robert Half, Adecco, CyberCoders, Randstad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IT Staffing Market Strategic Shifts
Artificial intelligence is fragmenting traditional candidate sourcing workflows while regulatory pressure and procurement model evolution reshape how technology talent is contracted and deployed across enterprise environments.
Generative AI screening tools automate initial resume parsing and skills matching against job requisitions. Mid-market enterprises adopt these platforms faster than Fortune 500 firms with entrenched vendor management systems. The technology is fragmenting sourcing work between algorithmic filtering and human relationship management, compressing margins on commodity placement services.
The EU AI Act imposes mandatory algorithmic impact assessments on automated hiring tools used by staffing firms operating in European markets. Vendors must document bias testing protocols and maintain human oversight checkpoints. French and German staffing operations face the steepest retrofit costs due to existing heavy reliance on AI-driven candidate ranking systems.
Enterprise buyers are unbundling managed service provider relationships to direct-source specialized cybersecurity and cloud architecture talent. Healthcare and defense contractors lead this disintermediation, building internal talent marketplaces with embedded staffing firm APIs. The United States shows the fastest adoption of this hybrid procurement model where platforms replace full-service contracts for technical roles.
IT Staffing Market Segmentation
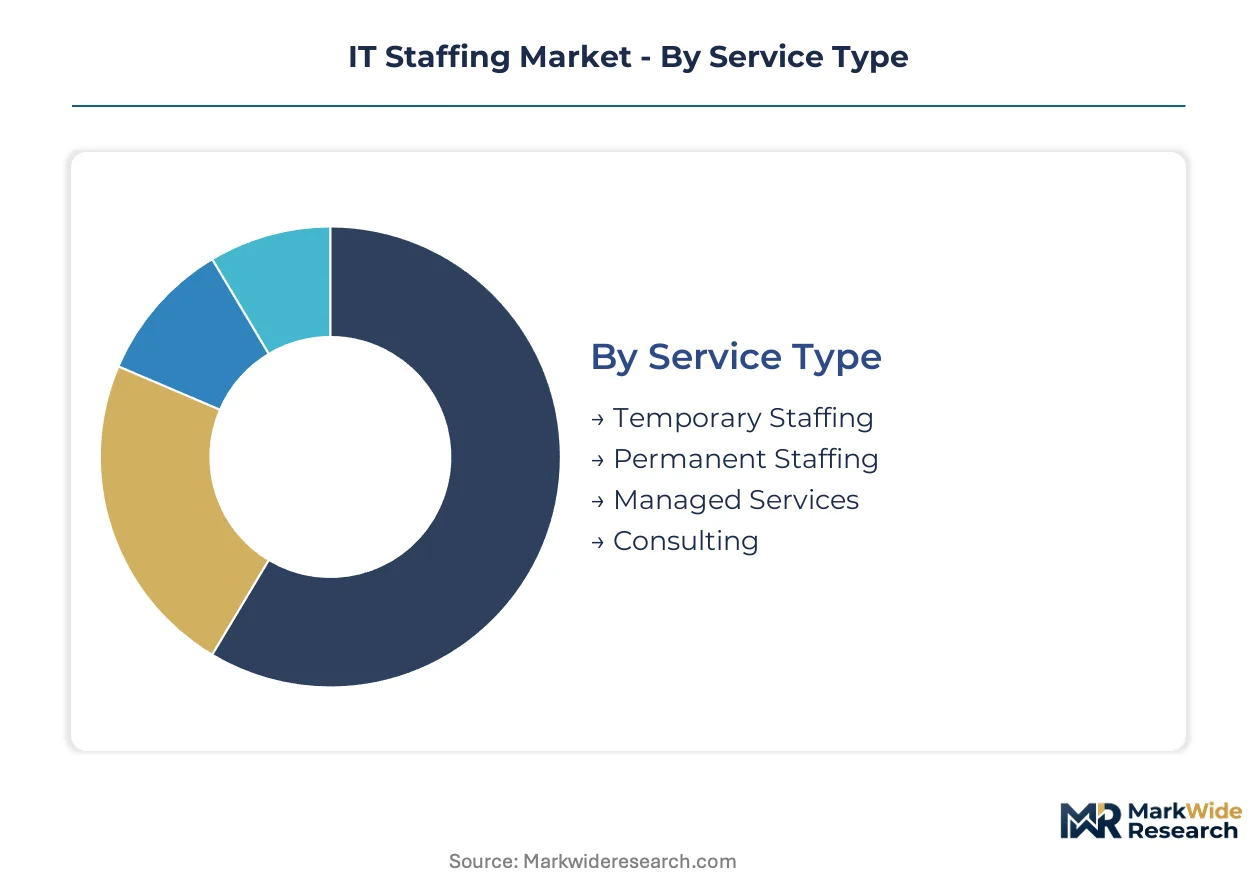
IT staffing segmentation reveals how procurement models and credential requirements fragment revenue pools across service delivery modes and client risk profiles. Distinct margin architectures apply to cleared government placements versus commodity temporary staffing, while technology specialization determines bill rate multiples.
Service Type:
Temporary staffing faces acute substitution pressure from vendor management system automation and direct-sourcing platforms that disintermediate traditional markup structures.
- Temporary Staffing:Short-term contract placements governed by time-to-fill service level agreements, with demand concentrating in financial services firms scaling contingent workforce programs to manage regulatory technology implementation cycles without fixed overhead commitment.
- Managed Services:Outcome-based engagements tied to system uptime or project completion guarantees, capturing disproportionate margin pools through accountability metrics that extend beyond hourly staffing markups into operational risk transfer.
- Permanent Staffing:Full-time placement fees typically structured as percentage of first-year compensation, with search intensity varying by seniority tier and exclusivity arrangements.
- Consulting:Project-based advisory engagements blending staff augmentation with deliverable-based pricing, common in cloud migration and cybersecurity transformation programs.
Temporary staffing anchors the volume base while managed services gains share at the steepest rate through outcome-based pricing expansion.
Client Type:
Cost tier stratification separates security-cleared government contracts with elongated verification pipelines from high-velocity startup engagements with compressed decision cycles.
- Government Agencies:Defense and intelligence placements impose stricter clearance requirements than commercial clients, elongating time-to-fill metrics while sustaining premium bill rates for cleared talent pools.
- Corporates:Fortune 500 enterprises with entrenched vendor management systems demand custom API integration for time-tracking and billing reconciliation, creating procurement friction that favors established staffing relationships.
- Startups:Equity-compensation hybrid structures and rapid hiring cycles characterize early-stage technology company engagements, with velocity prioritized over credential verification depth.
- Non-Profits:Budget-constrained engagements with mission-aligned talent attraction strategies, typically sourcing generalist technology roles rather than specialized cybersecurity or cloud architecture positions.
Corporates dominate current revenue contribution while government agencies expand most quickly through classified program staffing mandates.
Skill Level:
Supply concentration in senior-level cybersecurity and cloud architecture credentials creates pricing power asymmetries against fragmented entry-level markets.
- Senior-Level:Ten-plus-year practitioners with specialized certifications in AWS, Azure, or CompTIA Security+, commanding bill rate multiples that generalist staffing models cannot replicate through volume scaling.
- Executive:C-suite technology leadership placements including CTO and CISO searches, with retained search fees and equity negotiation complexity distinguishing this tier from contingency-based staffing.
- Mid-Level:Three-to-seven-year professionals forming the core deployment volume across project-based engagements, with skills assessment platform verification replacing traditional resume screening.
- Entry-Level:Recent graduates and career transitioners requiring credential bundling and micro-credential verification as annual renewal cycles compress from three-year cycles.
Mid-Level talent anchors placement volume while Senior-Level positions climb the fastest through cloud specialization premiums.
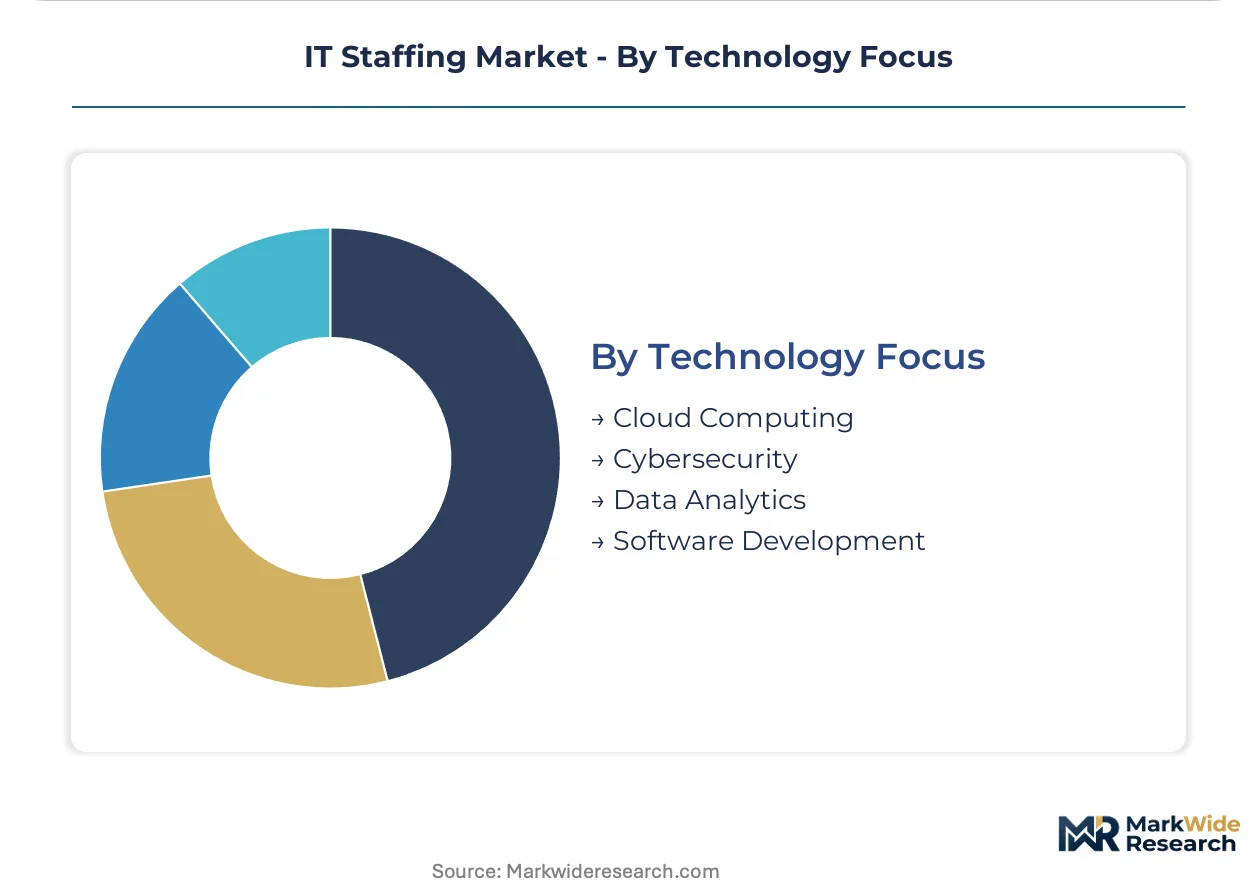
Technology Focus:
Application maturity separates established software development staffing from emerging cybersecurity micro-credential markets with compressed certification validity windows.
- Cybersecurity:CompTIA Security+ and specialized clearance requirements dominate this segment, with annual micro-credentialing cycles forcing staffing firms to rebuild verification pipelines from scratch.
- Cloud Computing:Amazon Web Services and Microsoft Azure certified professionals command premium positioning, with TEKsystems and Robert Half anchoring specialized practice groups around speed-to-fill for architecture roles.
- Software Development:Established programming language staffing across Java, Python, and JavaScript ecosystems, with generative AI screening tools fragmenting traditional sourcing workflows into algorithmic filtering and relationship management layers.
- Data Analytics:Business intelligence and machine learning operations talent, with demand concentrating in India as multinational corporations build captive technology centers in Bangalore and Hyderabad.
Software Development maintains the broadest placement base while Cybersecurity expands most quickly through regulatory compliance mandates and clearance pipeline constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government technology modernization programs and regulatory compliance mandates are redrawing IT staffing demand patterns across major economies. The EU AI Act, US federal procurement reforms, and India's PLI scheme for technology manufacturing are creating distinct talent sourcing requirements that favor localized staffing partnerships.
United States
Defense and intelligence agencies are accelerating classified program staffing through cleared contractor pipelines. The US Equal Employment Opportunity Commission intersects with ISO 30414 standards to reshape demographic documentation requirements. TEKsystems anchors placement velocity across government contracts from its Baltimore operational hub.
Germany
Automotive and industrial conglomerates are scaling contingent technology workforces for regulatory technology implementations. The country's national data protection regulator enforces strict talent database residency restrictions under GDPR-aligned mandates. Stuttgart and Munich clusters concentrate demand for embedded systems and manufacturing IT specialists.
India
Multinational corporations are constructing captive technology centers in Bangalore and Hyderabad for scalable workforce deployment. The country's central bank and technology ministry coordinate data localization requirements affecting cross-border credential verification. Karnataka and Telangana states compete through specialized economic zones for staffing firm registrations.
United Kingdom
Financial services firms in the City of London are expanding temporary technology talent programs for post-Brexit regulatory compliance builds. The Information Commissioner's Office governs automated hiring tool accountability under retained EU law frameworks. The Thames Valley corridor anchors cybersecurity placement demand for defense contractors.
France
CNIL enforcement of algorithmic impact assessments is retrofitting staffing firm compliance architectures for AI-driven candidate screening. Aerospace and luxury goods conglomerates are unbundling managed service provider relationships for direct-sourced cloud architecture talent. The Paris-Saclay cluster concentrates demand for data analytics and machine learning operations staffing.
IT Staffing Market Competitive Environment
Listed leaders compete with private specialists across credential verification depth and government clearance access. The market structure fragments across three tiers: global staffing conglomerates with diversified service portfolios, technology-specialized mid-market firms with proprietary assessment platforms, and boutique cybersecurity placement shops with cleared talent pipelines. Strategic differentiation centers on micro-credential bundling capabilities and outcome-based pricing models for managed services engagements.
Within the technology-specialized tier, TEKsystems and Robert Half exemplify archetypes competing on speed-to-fill for cloud and cybersecurity roles. TEKsystems leverages proprietary skills assessment infrastructure to sustain placement velocity across cleared government contracts. Robert Half anchors premium positioning through specialized technology practice groups with dedicated credential verification pipelines. Kforce occupies a position bridging mid-market scale with federal contracting access.
| Leading Market Players |
|---|
| Insight Global |
| Kforce |
| TEKsystems |
| Toptal |
| Akkodis |
| Robert Half |
| Adecco |
| CyberCoders |
| Randstad |
| Others |
Value Chain & Pricing Dynamics
Generative AI screening tools substituting for human sourcers are compressing margins in commodity placement tiers while simultaneously shifting supply geography toward India and Eastern European talent pools where technical assessment infrastructure costs less to deploy.
Pricing Analysis
Certification level creates the primary spread across bill rate tiers, with CompTIA Security+ and AWS/Azure credentials commanding premium positioning over uncredentialed generalist placements. Three-tier pricing structure separates cleared government contractors from commercial cybersecurity specialists from entry-level temporary staff, with the latter facing acute compression from vendor management system automation. Pricing pressure stems from enterprise buyers unbundling managed service provider relationships to direct-source cloud architecture talent. Startups exhibit highest price sensitivity with equity-compensation hybrid structures, while defense contractors accept premium markups for security-cleared pipelines.
Supply Chain Analysis
Just-in-time talent deployment dominates client preference, though cybersecurity micro-credentialing cycles are forcing staffing firms toward strategic pre-verification stockpiles of cleared candidates. Supply concentrates in India for data analytics and software development, the United States for defense-cleared cybersecurity, and Germany for embedded systems and manufacturing IT. Raw material dependencies include proprietary skills assessment platforms, government security clearance databases, and cross-border credential verification infrastructure. Single-source vulnerability runs through clearance pipeline bottlenecks where government agencies control candidate pool access. Distribution runs through embedded APIs in client enterprise HRIS systems and direct vendor management system integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as enterprise procurement unbundles full-service contracts into specialized component sourcing, creating defendable niches for credential-specific and geography-focused staffing models.
For Market Incumbents: Secure proprietary assessment platform moats through continuous investment in cleared government contract pipelines where TEKsystems and Robert Half currently anchor placement velocity. Defend margin position by deepening vertical integration into cybersecurity micro-credential bundling as annual renewal cycles compress from three-year windows. Channel control through embedded client HRIS APIs creates switching costs that commodity staffing competitors cannot replicate.
For New Entrants and Emerging Players: Anchor in India captive center construction as multinational corporations build technology centers in Bangalore and Hyderabad for scalable workforce deployment. Target mid-market enterprises adopting generative AI screening tools faster than Fortune 500 firms with entrenched vendor relationships. White-space exists in human-in-the-loop vetting services mandated by EU AI Act compliance, with regulatory technology implementation creating specialized demand niches.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-specialized mid-market firms with proprietary assessment infrastructure and federal contracting access bridging commercial and cleared government pipelines. Long-term viability favors models capturing outcome-based pricing through managed services guarantees rather than hourly markup dependency. Watch for inflection when enterprise direct-sourcing platform adoption crosses thresholds that permanently disintermediate generalist temporary staffing tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Skills Assessment Platform Development | TEKsystems leverages continuous platform investment to sustain cleared government contract placement velocity against commoditized competitors. |
| Cybersecurity Micro-Credential Bundling | Annual CompTIA Security+ renewal cycles enable staffing firms to package verified skill stacks as differentiated product offerings. |
| Embedded HRIS API Integration | Custom time-tracking and billing reconciliation APIs create procurement friction that favors established staffing relationships over new entrants. |
| India Captive Center Partnership | Multinational corporations building Bangalore and Hyderabad technology centers source local staffing partners for scalable workforce deployment. |
| EU AI Act Compliance Architecture | French and German staffing operations face steepest retrofit costs for algorithmic impact assessments on automated candidate screening tools. |
Study Parameters
Operator-level perspectives from staffing firm managing directors, enterprise technology procurement officers, government contracting officers, and cybersecurity practice group leaders anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from SEC filings of listed staffing conglomerates, CompTIA certification disclosure databases, EU regulatory impact assessments, and Indian PLI scheme documentation. Bottom-up placement volume estimates triangulated against top-down market sizing from service-level agreement benchmarks and bill rate survey data.
Sensitivity analysis tested forecast robustness across alternative scenarios for clearance pipeline velocity, AI screening tool adoption curves, and captive center construction timelines. Segmentation dimensions modeled include service delivery mode, client risk profile, technology specialization, and credential tier across the projection horizon. CAGRs derived from historical placement growth patterns adjusted for structural shifts in procurement model evolution and regulatory compliance mandates. Industry-specific inputs incorporated government technology modernization program budgets and multinational captive center investment announcements.
Decision-makers should treat outputs as directional under assumptions of sustained government contracting demand and continued EU AI Act enforcement; material deviation in either driver would warrant model refresh. Revision becomes warranted when enterprise direct-sourcing platform adoption crosses thresholds that accelerate temporary staffing tier compression beyond modeled rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Qatar Managed Services Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Shared Services Center Market
Enterprise Services
Bring Your Own Device Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Global Translation Services Market