
 Global Enterprise Data Warehouse (EDW) Market | 2026-2036
Global Enterprise Data Warehouse (EDW) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Data Warehouse (EDW) Market Foresight
GDPR is shifting the cost-of-entry calculus for EDW vendors serving European enterprises, forcing architectural investments in data residency and lineage tracking. Oracle Corporation leverages its autonomous database portfolio to anchor on-premises-to-cloud migration pathways for regulated industries. Microsoft Corporation competes through deep integration between Azure Synapse and Power BI, sustaining enterprise stickiness across analytics workflows. Snowflake Inc. differentiates via its multi-cloud abstraction layer, positioning data consumers independent of underlying infrastructure providers.
An enterprise data warehouse is a centralized, subject-oriented repository designed for integrated querying across structured and semi-structured sources, typically supporting petabyte-scale storage with massively parallel processing architectures. Its primary commercial purpose is to enable unified business intelligence, regulatory reporting, and predictive analytics by consolidating disparate operational data into consistent, time-variant schemas. Cloud-based deployment now captures the fastest expansion as organizations retire capital-intensive on-premises appliances, while hybrid architectures retain stronghold status among manufacturing units and energy firms with latency-sensitive operational technology feeds. Security and compliance solutions command premium pricing within the solution type dimension, reflecting escalated requirements from HIPAA in US healthcare and PCI-DSS in financial services.
The US Federal Trade Commission scrutinizes data broker practices, indirectly elevating demand for governed EDW implementations with auditable access controls. EMA pharmacovigilance guidelines and Japan's METI data governance frameworks similarly pressure multinational enterprises toward certified metadata management and quality tooling. China's SAMR personal information protection standards add complexity for EDW operators with cross-border data flows. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of architecture investment and vendor selection criteria.
Market Dynamics
Cloud hyperscaler consolidation is compressing deployment timelines while fragmenting vendor loyalty across multi-cloud abstraction layers. Regulators in three continents now mandate auditable data lineage, forcing architectural reinvestment in governance tooling.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making systems require certified metadata management, pulling regulated enterprises toward governed EDW implementations with embedded quality controls.
- Petabyte-scale MPP architectures:Manufacturing and energy firms with latency-sensitive OT feeds demand hybrid deployments that unify edge processing with centralized analytics.
- Financial services workload unification:HIPAA-covered entities and PCI-DSS-bound payment processors consolidate transactional and analytical systems to reduce data movement risk.
Market Restraints
- Cross-border data friction:China's SAMR personal information protection standards impose localization requirements that fragment global EDW architectures and inflate replication costs.
- Specialized talent scarcity:Data engineering expertise for massively parallel query optimization concentrates in Seattle, Bangalore, and Dublin clusters, constraining deployment velocity elsewhere.
- Legacy appliance stranded assets:Capital-intensive on-premises Teradata and Oracle Exadata installations resist cloud migration due to embedded stored procedures and proprietary SQL dialects.
Strategic Opportunities
- India's PLI scheme for data centers:Domestic cloud infrastructure incentives create captive EDW demand from BFSI and telecom verticals seeking sovereign data residency.
- Real-time streaming convergence:Apache Kafka and Apache Flink integration with batch warehouses enables operational analytics on sensor telemetry from connected industrial equipment.
- EMA pharmacovigilance guidelines:Adverse event reporting mandates drive specialized metadata tooling sales to pharmaceutical multinationals with European manufacturing footprints.
Industry Challenges
- Schema evolution complexity:Data mesh decentralization conflicts with centralized warehouse governance models, forcing architectural compromises that satisfy neither purists.
- Certification timeline compression:ISO 27001 and SOC 2 Type II audits for cloud EDW deployments now require continuous control monitoring rather than point-in-time assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Data Warehouse (EDW) Market |
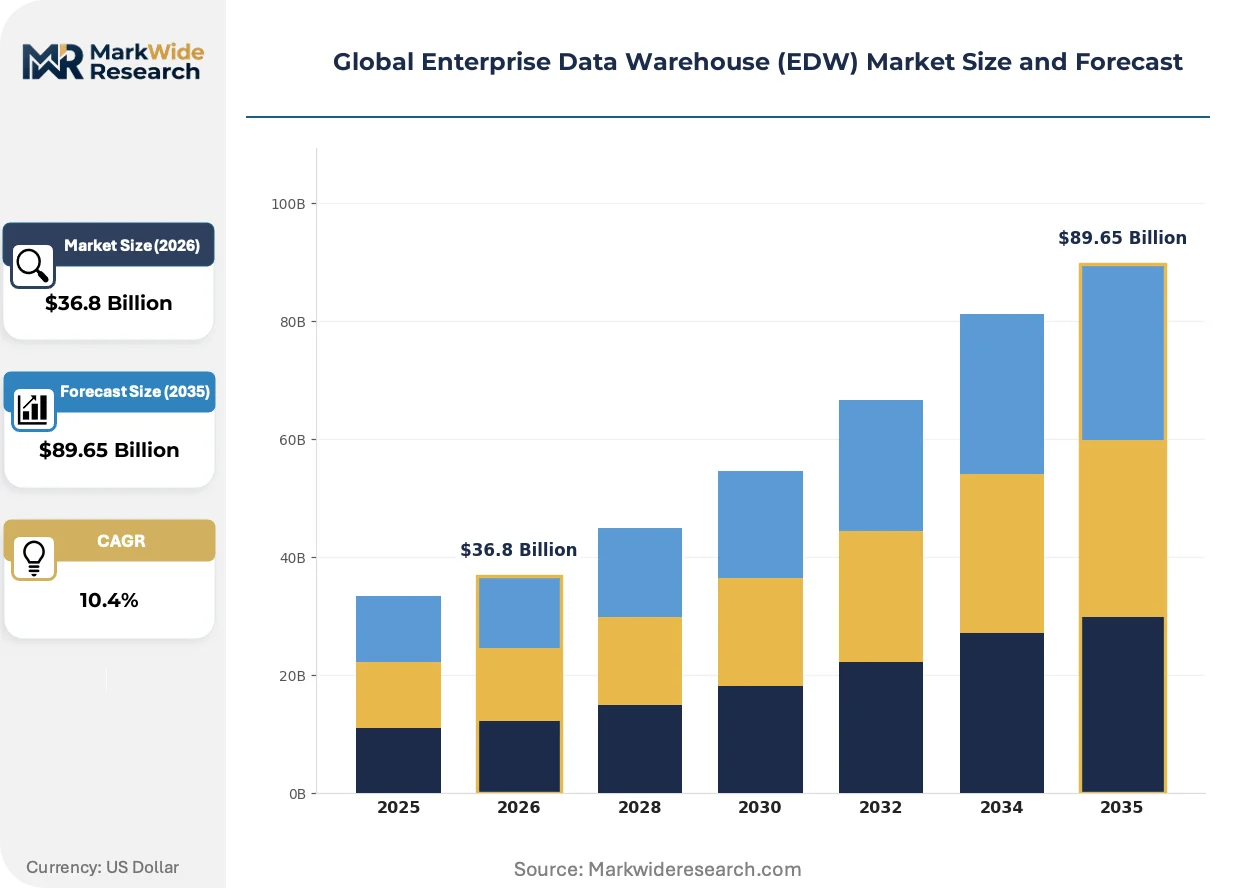
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $89.65 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution Type: Data Integration, Data Quality, Metadata Management, Data Governance, Security & Compliance Application: Customer Analytics, Risk Management, Supply Chain Optimization, Fraud Detection, Financial Reporting End User Industry: Telecommunication Providers, Manufacturing Units, Energy Firms, Government Agencies, Hospitality Chains |
| Companies Covered | Oracle Corporation, International Business Machines Corporation, Microsoft Corporation, Snowflake Inc., Teradata Corporation, SAP SE, Amazon.com Inc., Alphabet Inc., Databricks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Data Warehouse (EDW) Market Shifts & Advancements
Query optimization engines are automating performance tuning that previously consumed dedicated database administrator hours. Three convergent forces are compressing time-to-insight while expanding governance surface area.
Autonomous query rewriting technology is automating index selection and materialized view maintenance that previously required manual intervention. Healthcare providers bound by HIPAA audit requirements adopt these capabilities fastest, eliminating human configuration errors that expose protected health information. The technology is automating compliance documentation by embedding policy enforcement directly into execution plans.
REACH chemical substance tracking mandates and RoHS conflict mineral disclosure rules force EDW operators to maintain granular component-level provenance across extended supply chains. Automotive and electronics manufacturers with European assembly plants face the steepest compliance burden, retrofitting existing warehouses with graph-based lineage engines. These investments cascade into premium pricing for certified metadata management modules.
Consumption-based billing for compute and storage is displacing capacity reservations as the dominant procurement model. Mid-market enterprises previously locked out of petabyte-scale analytics now access on-demand query processing through credit-based purchasing. This pattern concentrates in United States SaaS startups and digital-native retailers with spikey, unpredictable query volumes.
Global Enterprise Data Warehouse (EDW) Market Segmentation
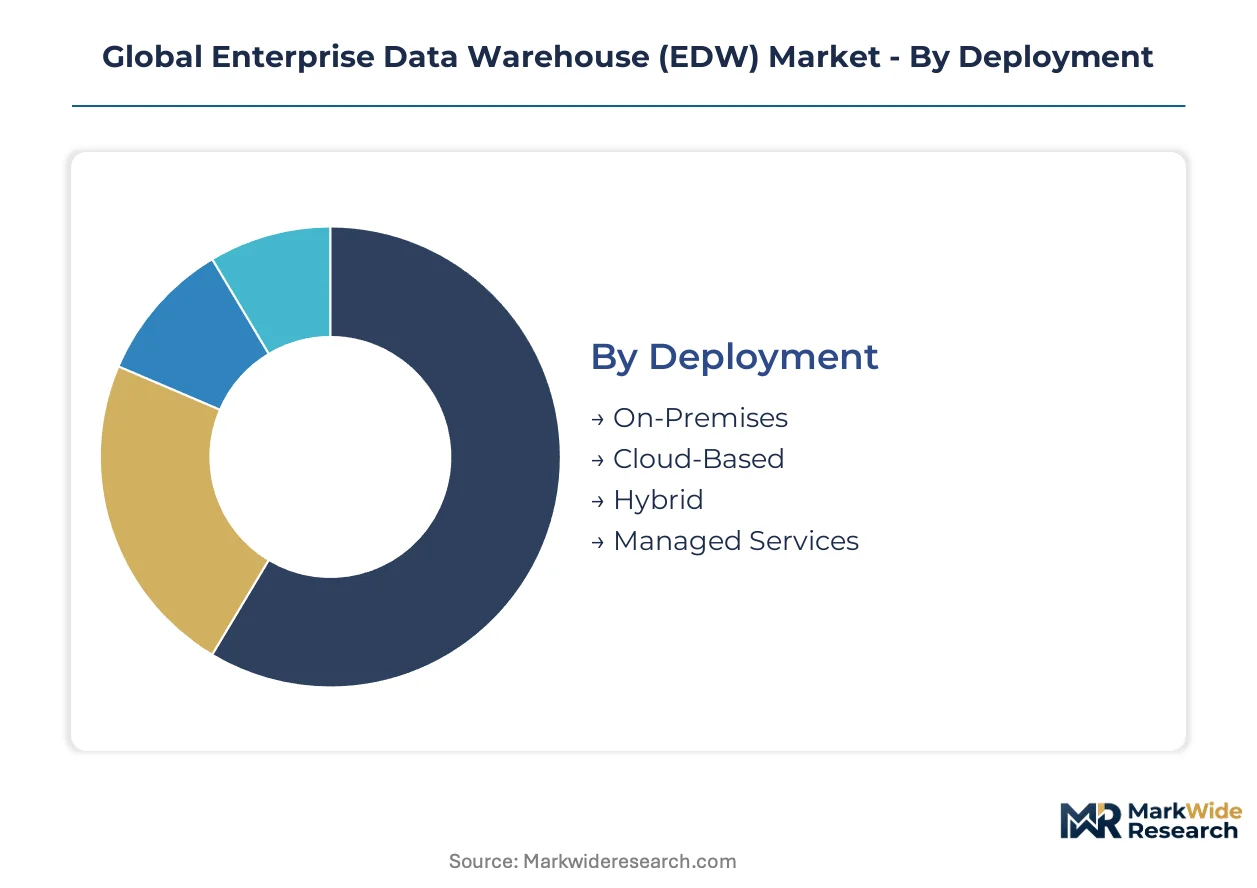
EDW procurement decisions pivot on workload latency requirements, regulatory exposure, and existing infrastructure sunk costs. Buyers evaluate deployment models against data sovereignty mandates and operational technology integration needs.
Deployment:
Latency tolerance and capital recovery timelines determine deployment selection for manufacturing and energy buyers with edge computing dependencies.
- Cloud-Based:Massively parallel processing architectures eliminate upfront appliance capital expenditure while enabling elastic scaling for spikey analytics workloads. United States SaaS startups and digital-native retailers concentrate procurement here, drawn by consumption-based billing that aligns costs with query volume.
- Hybrid:Unified edge-to-cloud pipelines serve manufacturing units and energy firms with latency-sensitive operational technology feeds requiring local preprocessing. These architectures retain stronghold status where sub-second response times govern production safety systems.
- On-Premises:Capital-intensive appliance installations persist in regulated financial services with embedded stored procedures resisting migration.
- Managed Services:Third-party operational outsourcing appeals to mid-market enterprises lacking Seattle, Bangalore, or Dublin cluster talent pools for query optimization.
Cloud-based deployment leads on scale; hybrid leads on momentum among industrial buyers.
Solution Type:
Compliance exposure severity drives solution tier prioritization, with HIPAA-covered entities and PCI-DSS-bound processors front-loading governance investments.
- Security & Compliance:Auditable access controls and continuous control monitoring command premium pricing from financial services and healthcare providers facing FTC and FDA scrutiny. Embedded policy enforcement in execution plans automates documentation for ISO 27001 and SOC 2 Type II audits.
- Metadata Management:Certified lineage tracking tools satisfy EU AI Act mandates for automated decision-making systems while supporting EMA pharmacovigilance adverse event reporting. Graph-based provenance engines address REACH chemical substance tracking and RoHS conflict mineral disclosure across automotive supply chains.
- Data Integration:ETL pipeline orchestration unifies transactional and analytical workloads for risk reduction.
- Data Quality:Automated profiling and cleansing modules reduce protected health information exposure errors.
- Data Governance:Policy definition and stewardship workflows enable cross-functional data ownership.
Security & compliance leads on scale; metadata management leads on momentum from regulatory mandate acceleration.
Application:
Analytical use case maturity determines solution sophistication requirements, with real-time operational analytics demanding streaming-batch convergence.
- Customer Analytics:Unified behavioral profiling across touchpoints drives hospitality chains and telecommunication providers toward petabyte-scale storage with sub-second query response. Apache Kafka and Apache Flink integration enables operational analytics on unpredictable volume patterns.
- Risk Management:Consolidated counterparty exposure calculation requires governed EDW implementations with embedded quality controls for Basel III and Dodd-Frank reporting. Financial services firms accelerate adoption to unify transactional and analytical workloads.
- Fraud Detection:Real-time pattern recognition on payment streams demands low-latency infrastructure.
- Supply Chain Optimization:Sensor telemetry from connected industrial equipment feeds predictive maintenance models.
- Financial Reporting:Time-variant schema consistency supports regulatory submission automation.
Customer analytics leads on scale; risk management leads on momentum from workload unification trends.
End User Industry:
Operational technology integration depth and cross-border data flow exposure shape industry-specific architecture requirements.
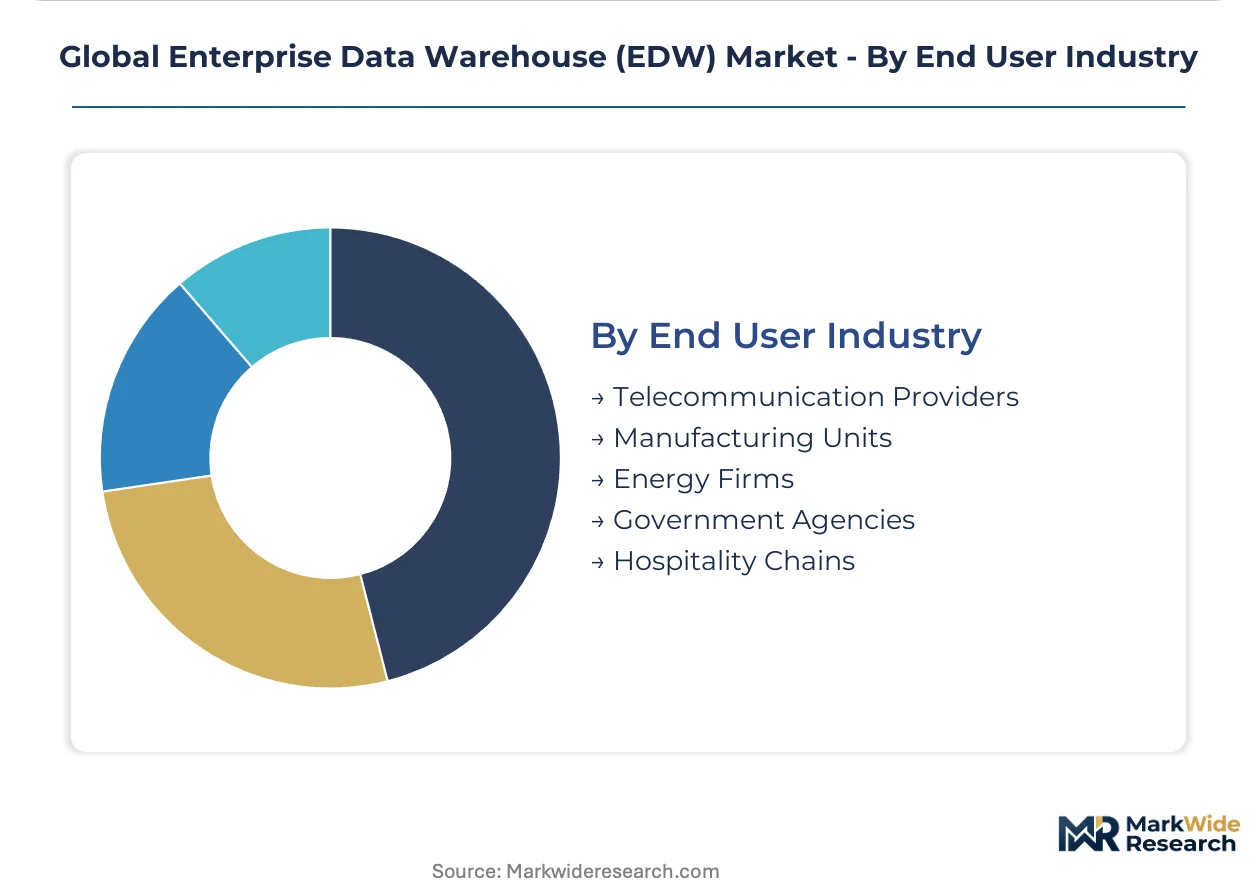
- Manufacturing Units:Latency-sensitive production line analytics demand hybrid deployments unifying edge processing with centralized quality control. REACH and RoHS mandates force granular component-level provenance tracking across extended supplier networks.
- Energy Firms:Predictive maintenance on generation and distribution infrastructure requires real-time sensor data ingestion with local preprocessing for safety-critical systems. China's SAMR personal information protection standards fragment global architectures for multinationals with cross-border flows.
- Telecommunication Providers:Subscriber churn prediction and network optimization drive India's PLI scheme captive demand.
- Government Agencies:Sovereign data residency requirements concentrate procurement in domestic cloud regions.
- Hospitality Chains:Dynamic pricing and personalization engines leverage unified guest profiles.
Manufacturing units lead on scale; energy firms lead on momentum from infrastructure modernization cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data engineering expertise concentrates in Seattle, Bangalore, and Dublin clusters, anchoring deployment velocity and vendor proximity decisions. Cloud hyperscaler regions and enterprise headquarters clusters drive procurement scale in mature markets. Regulatory divergence between jurisdictions shapes architecture investment patterns.
United States
Financial services firms accelerate EDW adoption to unify transactional and analytical workloads. The FTC scrutinizes data broker practices, elevating demand for governed implementations with auditable access controls. Seattle anchors hyperscaler engineering talent while New York and Chicago headquarters clusters sustain procurement scale.
Germany
Automotive and electronics manufacturers face REACH chemical substance tracking and RoHS conflict mineral disclosure mandates. The EU AI Act shifts compliance requirements for automated decision-making systems. Bavaria and Baden-Württemberg industrial corridors retrofit warehouses with graph-based lineage engines.
China
Cross-border data flows fragment global architectures for multinationals operating in the market. SAMR personal information protection standards impose localization requirements that inflate replication costs. Yangtze River Delta and Pearl River Delta manufacturing hubs demand hybrid deployments for latency-sensitive operational technology feeds.
India
BFSI and telecom verticals seek sovereign data residency through domestic cloud infrastructure. The PLI scheme for data centers creates captive EDW demand from regulated enterprises. Bangalore and Mumbai talent pools constrain deployment velocity elsewhere while anchoring managed services growth.
Japan
Pharmaceutical multinationals with European manufacturing footprints face EMA pharmacovigilance adverse event reporting mandates. METI data governance frameworks pressure enterprises toward certified metadata management. Tokyo and Osaka headquarters clusters drive procurement for quality tooling investments.
Global Enterprise Data Warehouse (EDW) Market Competitive Landscape
The competitive structure tilts toward cloud-native abstraction layers over legacy appliance incumbents. Database specialists and infrastructure providers fragment across deployment model preferences. Three archetypes dominate: autonomous database platforms, multi-cloud abstraction engines, and integrated analytics suites. Strategic moves concentrate on hybrid migration pathways and governance tooling acquisitions.
Within the autonomous database tier, Oracle Corporation leverages on-premises-to-cloud migration pathways for regulated industries. Microsoft Corporation competes through deep integration between analytics and business intelligence workflows. Snowflake Inc. differentiates via multi-cloud abstraction, positioning data consumers independent of underlying infrastructure providers.
| Leading Market Players |
|---|
| Oracle Corporation |
| International Business Machines Corporation |
| Microsoft Corporation |
| Snowflake Inc. |
| Teradata Corporation |
| SAP SE |
| Amazon.com Inc. |
| Alphabet Inc. |
| Databricks Inc. |
| Others |
Supply & Pricing Matrix
Compute instance costs cascade through EDW vendor pricing tiers, with Seattle hyperscaler engineering talent premiums embedding into managed service rates downstream. Cloud storage egress fees and cross-region replication charges concentrate pricing power with infrastructure providers serving HIPAA-covered healthcare entities and PCI-DSS-bound payment processors.
Pricing Analysis
Bundled consumption-based billing dominates cloud-native EDW procurement while unbundled licensing persists for on-premises appliance retention. Three-tier pricing structure across premium, standard, and economy levels separates governed implementations with embedded compliance automation from basic query processing tiers. Pricing pressure stems from India's PLI scheme subsidizing domestic cloud infrastructure for BFSI captive demand. Mid-market SaaS startups exhibit highest price sensitivity; regulated financial services show lowest due to audit risk transfer value.
Supply Chain Analysis
Warehouse-distribution layer concentration in Dublin, Bangalore, and Seattle clusters anchors query optimization talent proximity for managed service delivery. Hardware component sourcing draws from Taiwan semiconductor fabrication, South Korea memory production, and United States hyperscaler capex deployment. Single-source vulnerability concentrates in specialized data engineering expertise pools. Distribution runs through direct cloud marketplace procurement and systems integrator channel partnerships serving manufacturing units with hybrid deployment requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EDW procurement arbitrage favors cloud infrastructure buildout in India against EU AI Act compliance cost inflation in Germany, with talent scarcity in Seattle and Dublin compressing margins for location-agnostic providers.
For Market Incumbents: Deepen vertical integration into autonomous query optimization tooling to defend against Snowflake's multi-cloud abstraction threat. Anchor capacity addition in India's PLI scheme corridors to capture sovereign data residency demand from BFSI verticals. Certification investment in ISO 27001 continuous control monitoring preserves pricing power against unbundled challengers. For New Entrants and Emerging Players: Capture real-time streaming convergence white space in manufacturing sensor telemetry analytics, the most penetrable segment where Apache Kafka and Apache Flink integration remains incomplete. Target energy firms with latency-sensitive operational technology feeds in China's Yangtze River Delta. Pursue channel partnerships with regional systems integrators lacking Seattle cluster talent pools. For Investors and Strategic Acquirers: Roll-up economics work for metadata management specialists because EU AI Act and EMA pharmacovigilance mandates are fragmenting governance tooling procurement across pharmaceutical multinationals. Five-to-ten year viability hinges on acquisition of graph-based lineage engine providers serving automotive REACH compliance. Watch India's domestic cloud infrastructure utilization rates as inflection indicator for sovereign data residency demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure Synapse-Power BI workflow unification sustains Microsoft enterprise stickiness against Snowflake abstraction. |
| Acquisition of Specialist Firm | Graph-based lineage engine purchases address REACH chemical tracking mandates for European automotive manufacturers. |
| Geographic Expansion | India PLI scheme data center buildout captures BFSI and telecom sovereign residency demand from RBI and TRAI pressure. |
| Strategic Partnership | Apache Kafka integration partnerships enable operational analytics on manufacturing sensor telemetry for hybrid deployments. |
| Product Launch | Autonomous query rewriting releases automate HIPAA audit documentation for healthcare providers eliminating human configuration errors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cloud infrastructure procurement officers, EDW platform engineers, healthcare compliance leads, financial services data governance directors, and manufacturing OT integration specialists with secondary validation. SEC 10-K filings, hyperscaler capex disclosures, EU AI Act regulatory texts, and EMA pharmacovigilance guideline documents anchored top-down market sizing. Bottom-up triangulation cross-checked vendor revenue disclosures against end-user deployment scale estimates.
Segment-weighting distributed value across deployment models, solution types, application use cases, and end-user industries with regional adoption pattern overlays. CAGRs derived from regression analysis of historical procurement velocity against regulatory mandate implementation timelines. Forecast inputs incorporated cloud storage pricing trajectories and data engineering talent cluster expansion rates across the projection horizon.
Regulatory divergence acceleration, hyperscaler pricing volatility, and talent pool geographic concentration are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Proactive Services Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Asia-Pacific and US Warehouse Management System Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Cloud Enterprise Management Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
Asia-Pacific Enterprise Asset Management Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Shared Services Center Market
Enterprise Services
United States Customer Technical Support Services Market