
 Asia Pacific Field Service Management Market | 2026-2036
Asia Pacific Field Service Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Field Service Management Market Outlook
Partner ecosystems for field service software are tilting toward cloud-native platforms across Southeast Asia and Oceania. Microsoft Corporation leverages its Azure infrastructure to anchor enterprise deployments in Australian utilities and telecommunications providers. SAP SE competes through deep ERP integration, sustaining advantage among large industrial conglomerates in India and Japan. ServiceMax Inc. specializes in asset-centric workflows, dominating niche segments where equipment uptime dictates contract profitability.
Field service management encompasses software systems that coordinate mobile workforces, schedule technician dispatches, track inventory in transit, and capture real-time service data through GPS-enabled handheld devices and IoT-connected machinery. These platforms typically integrate work-order routing algorithms, parts-availability databases, and customer notification portals to minimize mean-time-to-repair across geographically dispersed asset bases. Cloud-based deployment leads adoption momentum across the region, while workforce management and scheduling solutions capture disproportionate investment as labor-intensive sectors automate dispatch decisions. On-premise installations retain footholds in Japanese and South Korean manufacturing, where data sovereignty requirements and legacy system interdependencies slow migration timelines.
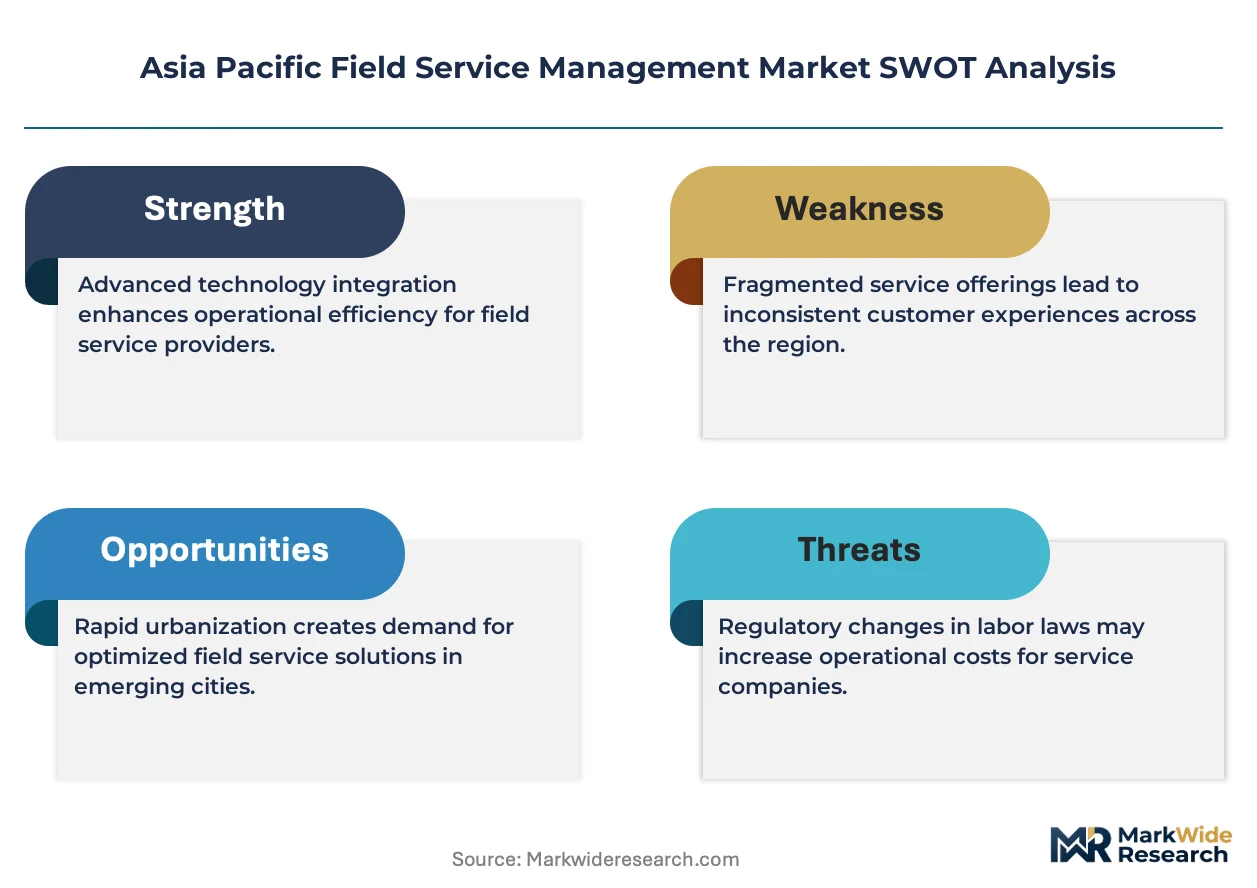
Australia's Essential Services Commission enforces reliability benchmarks that compel utilities to adopt predictive field dispatch systems, while India's BIS framework mandates cybersecurity certification for software managing critical infrastructure networks. Japan's METI promotes SME digitalization subsidies that lower barriers to mobile workforce platform adoption among mid-sized service contractors. Stakeholders must weigh cloud migration speed against data localization requirements as regulatory fragmentation intensifies across the region's heterogeneous compliance landscape.
Market Dynamics
Cloud-native dispatch architectures are compressing deployment timelines for utilities managing distributed renewable assets across Southeast Asian grids, forcing legacy on-premise vendors into defensive integration partnerships.
Growth Catalysts
- India's BIS cybersecurity certification:Mandatory standards for critical infrastructure software are compelling state-owned utilities to replace unverified legacy systems with compliant cloud platforms.
- Manufacturing digitization in Pune and Chennai:Industrial conglomerates in these corridors are consolidating fragmented technician fleets under unified workforce management systems.
- IoT sensor proliferation:Predictive maintenance triggers from connected grid assets are automating work-order generation before equipment failures occur.
Market Restraints
- Data sovereignty requirements in Japan and South Korea:Manufacturing clients in these markets resist cloud migration due to proprietary process data restrictions, prolonging on-premise maintenance burdens.
- Telecom infrastructure gaps:Field technicians in Indonesian archipelago operations face connectivity dead zones that disrupt real-time dispatch synchronization.
- Legacy ERP interdependencies:Decades-old enterprise resource planning systems in Japanese industrial conglomerates require expensive middleware layers for mobile workforce integration.
Strategic Opportunities
- Philippine utility privatization:Distribution network concessions are creating first-mover openings for cloud-native vendors to establish platform standards before incumbent lock-in solidifies.
- METI SME digitalization subsidies:Japan's Ministry of Economy, Trade and Industry funding is lowering adoption barriers for mid-sized service contractors previously priced out of enterprise systems.
- Convergence of AR remote assistance and mobile FSM:Technician headsets streaming expert guidance are integrating with dispatch platforms to compress resolution times for complex equipment repairs.
Industry Challenges
- Certification bottlenecks under India's BIS framework:Testing backlogs for cybersecurity compliance are delaying product launches by six to nine months for vendors targeting critical infrastructure clients.
- Integration complexity with SCADA systems:Utilities require seamless data flows between field dispatch platforms and supervisory control infrastructure, demanding specialized protocol engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Field Service Management Market |
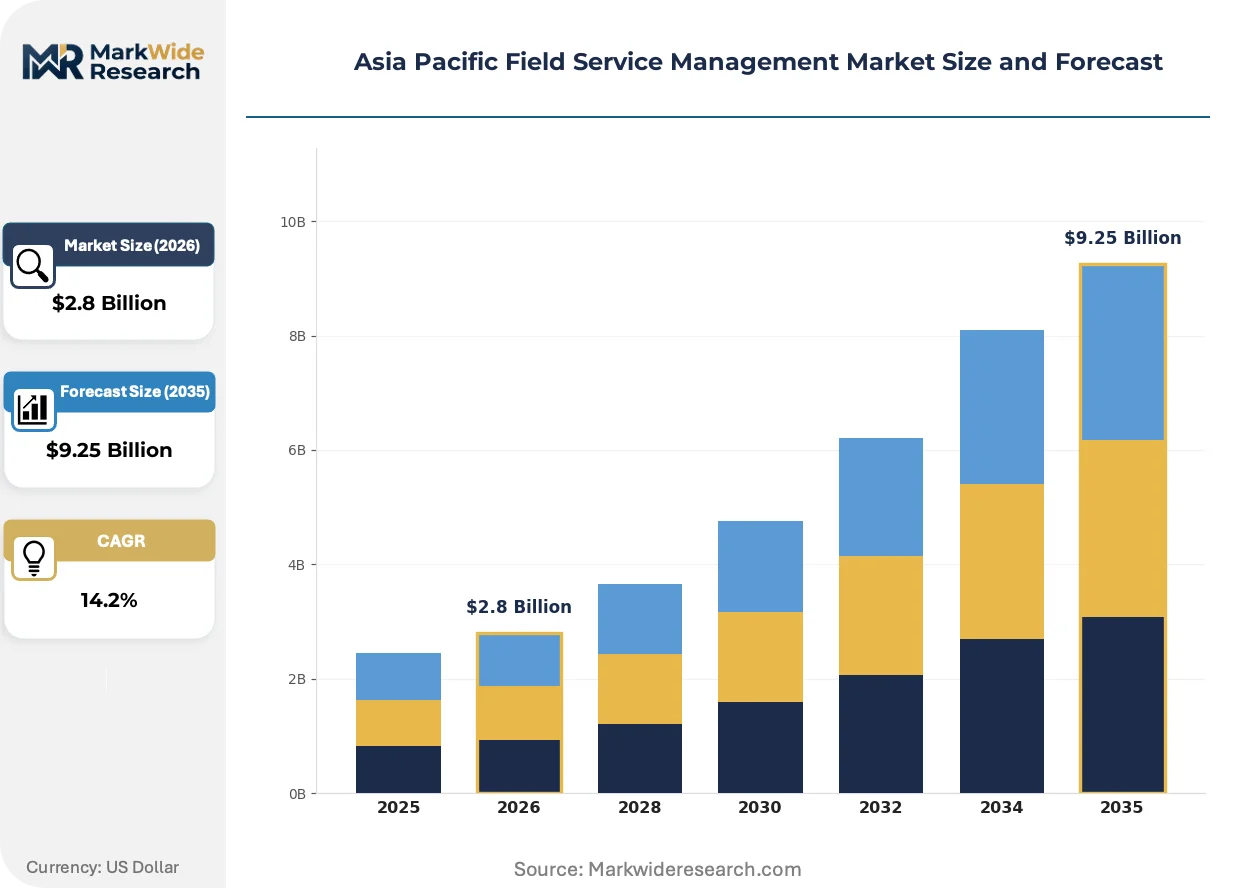
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Workforce Management, Dispatch Management, Inventory Management, Scheduling Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Telecommunications, Utilities, Healthcare, Construction Solution: Field Service Automation, Customer Engagement, Reporting Tools, Analytics |
| Companies Covered | Salesforce.com, Inc., Microsoft Corporation, IFS AB, Oracle Corporation, Trimble Inc., SAP SE, ServiceMax Inc., IBM Corporation, Tata Consultancy Services Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Field Service Management Market Strategic Shifts
Artificial intelligence is restructuring how dispatch decisions are made across Asia Pacific utilities, compressing the gap between fault detection and technician deployment from hours to minutes.
Edge computing nodes deployed at substations and renewable generation sites are rendering obsolete the centralized cloud processing model for time-critical dispatch decisions. Australian utilities operating remote wind farms are adopting these distributed architectures to maintain dispatch functionality during backbone network outages. The shift is compressing vendor margins by eliminating premium connectivity charges previously bundled with SaaS contracts.
Australia's Essential Services Commission reliability mandates are forcing distribution utilities to demonstrate measurable reductions in customer outage duration through predictive field response systems. The regulatory pressure is accelerating procurement cycles for platforms with embedded outage prediction algorithms. Victorian and New South Wales utilities are prioritizing vendors with native integration to network digital twin systems.
Asset owners are unbundling field service contracts from original equipment manufacturer maintenance agreements, creating direct procurement relationships with specialized workforce management platforms. This disintermediation is most visible in India's solar farm operations, where independent power producers are bypassing panel manufacturer service networks to optimize technician utilization across heterogeneous equipment fleets. The procurement shift is fragmenting vendor account control and intensifying price competition for multi-site contracts.
Asia Pacific Field Service Management Market Segmentation
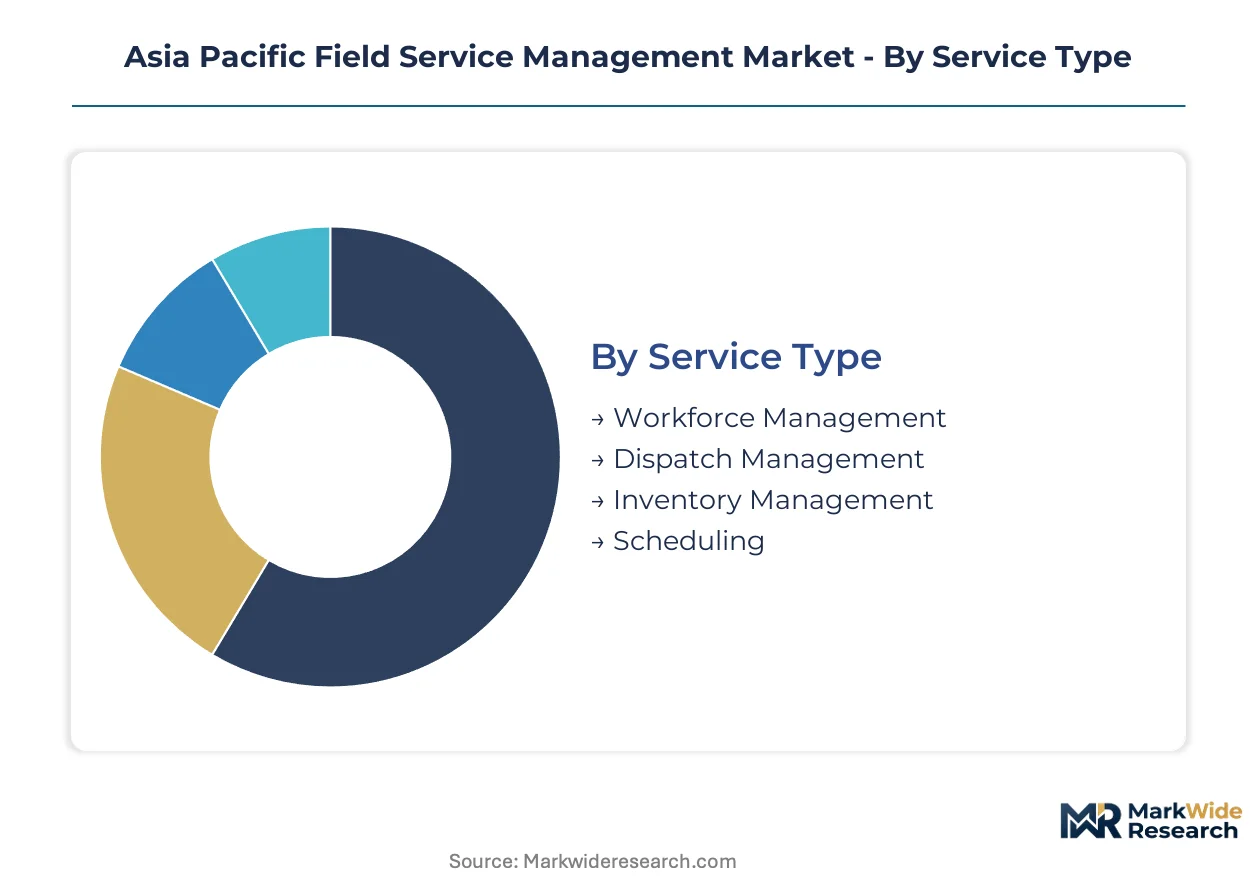
Field service management platforms fragment across multiple technical and commercial dimensions. Understanding these divisions clarifies where procurement budgets concentrate and which deployment architectures utilities and industrial operators prioritize.
Service Type:
Mature scheduling and dispatch modules anchor enterprise spending, while emerging workforce optimization layers capture incremental investment.
- Workforce Management:Comprehensive modules tracking technician certifications, shift allocation, and labor compliance across distributed teams. Indian manufacturing conglomerates in Pune and Chennai corridors are consolidating fragmented contractor fleets under unified workforce platforms to meet BIS cybersecurity mandates for critical infrastructure access.
- Dispatch Management:Real-time routing algorithms optimizing technician travel sequences against priority thresholds and skill matrices. Australian utilities under Essential Services Commission reliability mandates are deploying predictive dispatch systems to compress outage response intervals across Victorian and New South Wales distribution networks.
- Inventory Management:Parts-availability databases synchronizing warehouse stock with mobile technician vehicles. Japanese industrial clients maintain hybrid visibility across on-premise legacy systems and cloud replenishment triggers.
- Scheduling:Calendar optimization engines balancing preventive maintenance windows against emergency interruption protocols. Southeast Asian renewable operators use these tools to coordinate turbine technician rotations across archipelago geographies with intermittent connectivity.
Workforce Management handles the majority of throughput; Dispatch Management is expanding most quickly on share as predictive maintenance triggers automate work-order generation.
Deployment:
Cost tier stratification separates premium cloud-native architectures from maintenance-heavy legacy installations.
- Cloud-Based:SaaS platforms delivering elastic compute for seasonal demand spikes without capital infrastructure commitment. Southeast Asian utilities managing distributed solar and wind assets are accelerating migration to cloud dispatch platforms, though Indonesian archipelago operations face synchronization challenges in connectivity dead zones.
- On-Premise:Perpetual-license installations retaining full data custody within client firewall boundaries. Japanese and South Korean manufacturing clients resist cloud migration due to proprietary process data restrictions and legacy ERP interdependencies, prolonging on-premise maintenance burdens.
- Hybrid:Architectures partitioning sensitive operational data on-site while routing customer-facing workflows through cloud portals. Australian utilities use hybrid models to satisfy reliability reporting mandates while limiting exposure of SCADA integration points.
- Mobile:Lightweight field applications executing core dispatch functions on technician smartphones and ruggedized handhelds. These deployments concentrate in Indonesian and Philippine operations where cellular infrastructure gaps necessitate offline-capable synchronization protocols.
Cloud-Based deployments command the dominant procurement volume; Mobile is gaining share fastest as field technician smartphone penetration eliminates dedicated hardware requirements.
End User:
Application intensity varies sharply across sector-specific asset complexity and regulatory exposure.
- Utilities:Grid operators managing generation, transmission, and distribution infrastructure across geographically dispersed asset bases. India's state-owned utilities are replacing unverified legacy systems with BIS-certified cloud platforms to satisfy mandatory cybersecurity standards for critical infrastructure software.
- Telecommunications:Network operators coordinating tower maintenance, fiber splicing, and customer premise equipment installations. Australian providers leverage Azure-anchored enterprise deployments for nationwide workforce coordination.
- Healthcare:Medical device servicers and hospital engineering teams maintaining diagnostic equipment uptime. Compliance requirements around patient data restrict cloud adoption in this segment relative to other end uses.
- Construction:Project-based contractors tracking equipment maintenance and subcontractor dispatch across temporary job sites. Japan's METI SME digitalization subsidies are lowering adoption barriers for mid-sized service contractors previously priced out of enterprise systems.
Utilities absorb the largest platform investment; Construction is climbing the fastest as project digitization extends beyond design into field execution.
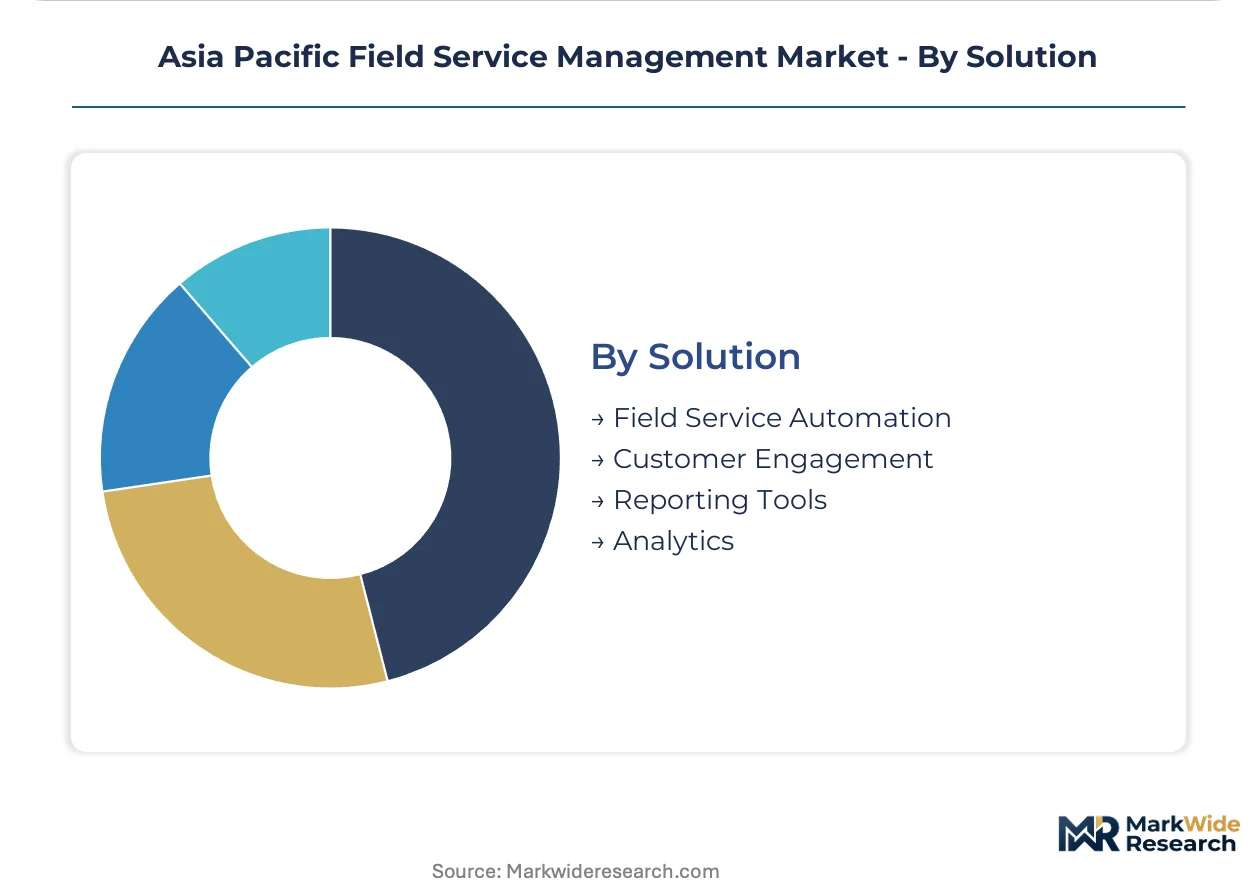
Solution:
Margin concentration sits with automation engines that compress mean-time-to-repair, while engagement layers compete on price.
- Field Service Automation:Core workflow engines integrating work-order generation, technician dispatch, and completion documentation. These platforms dominate contract profitability in asset-centric segments where equipment uptime dictates service level agreements.
- Customer Engagement:Notification portals and appointment self-service interfaces reducing inbound call center volume. Australian utilities prioritize native integration to network digital twin systems for outage prediction and proactive customer communication.
- Reporting Tools:Compliance documentation generators and operational dashboards for regulatory submission and internal performance review. Essential Services Commission reliability mandates force distribution utilities to demonstrate measurable customer outage duration reductions through these systems.
- Analytics:Predictive modules forecasting equipment failure probability and optimizing preventive maintenance intervals. IoT sensor proliferation from connected grid assets is automating work-order generation before failures occur, accelerating analytics procurement.
Field Service Automation carries the heaviest deployment weight; Analytics is advancing fastest as predictive maintenance triggers displace reactive dispatch models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian utilities extract premium pricing for predictive dispatch platforms while Indonesian operators face margin compression from connectivity infrastructure gaps. This asymmetry concentrates vendor investment toward regulatory-driven procurement in developed Asia Pacific markets while forcing adaptation strategies for archipelago deployment challenges.
Australia
Victorian and New South Wales distribution utilities prioritize native integration to network digital twin systems under Essential Services Commission reliability mandates. The regulatory pressure accelerates procurement cycles for platforms with embedded outage prediction algorithms. Azure-anchored enterprise deployments dominate nationwide workforce coordination among telecommunications providers and grid operators.
India
State-owned utilities replace unverified legacy systems with BIS-certified cloud platforms to satisfy mandatory cybersecurity standards for critical infrastructure software. Manufacturing conglomerates in Pune and Chennai industrial corridors consolidate fragmented technician fleets under unified workforce management systems. METI SME digitalization subsidies lower adoption barriers for mid-sized service contractors previously priced out of enterprise systems.
Japan
Manufacturing clients resist cloud migration due to proprietary process data restrictions and legacy ERP interdependencies, prolonging on-premise maintenance burdens. METI SME digitalization subsidies accelerate mobile workforce platform adoption among mid-sized service contractors. Kanto and Kansai industrial zones retain hybrid architectures partitioning sensitive operational data on-site while routing customer-facing workflows through cloud portals.
South Korea
Data sovereignty requirements in manufacturing sectors slow cloud-native adoption despite government digitalization initiatives. Seoul Capital Area conglomerates maintain perpetual-license installations retaining full data custody within client firewall boundaries. Busan-Ulsan industrial clusters require expensive middleware layers for mobile workforce integration with decades-old enterprise resource planning systems.
Indonesia
Telecom infrastructure gaps create connectivity dead zones that disrupt real-time dispatch synchronization for field technicians across archipelago operations. Distribution network concessions from utility privatization create first-mover openings for cloud-native vendors to establish platform standards. Javanese industrial zones concentrate mobile deployment investment where cellular infrastructure supports offline-capable synchronization protocols.
Asia Pacific Field Service Management Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in scheduling algorithms and mobile middleware. The vendor base concentrates around three strategic layers: cloud-native SaaS providers anchoring utility-scale deployments, ERP-integrated incumbents defending manufacturing accounts, and asset-centric workflow specialists capturing equipment uptime contracts. Dominant competitive moves include defensive integration partnerships between legacy on-premise vendors and cloud architectures, plus geographic expansion through METI subsidy-aligned distribution channels in Japan.
Within the cloud infrastructure tier, Microsoft Corporation and Salesforce.com, Inc. represent platform anchoring strategies, while ServiceMax Inc. exemplifies asset-centric specialization. Microsoft leverages Azure infrastructure to secure enterprise deployments in Australian utilities and telecommunications providers. Salesforce anchors customer engagement layers that reduce inbound call center volume for outage notification workflows. ServiceMax occupies a position where equipment uptime dictates contract profitability, dominating niche segments among independent power producers in Indian solar farm operations.
| Leading Market Players |
|---|
| Salesforce.com, Inc. |
| Microsoft Corporation |
| IFS AB |
| Oracle Corporation |
| Trimble Inc. |
| SAP SE |
| ServiceMax Inc. |
| IBM Corporation |
| Tata Consultancy Services Ltd. |
| Others |
Value Chain & Pricing Dynamics
Pune and Chennai industrial corridors concentrate cloud-native platform development capacity, with vendor engineering centers in these clusters translating localized R&D intensity into pricing leverage for configured-to-order deployments across Indian utilities and manufacturing conglomerates.
Pricing Analysis
The customization-premium spread separates standard SaaS subscriptions from enterprise-configured deployments requiring BIS cybersecurity certification and SCADA protocol integration. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because Indonesian archipelago connectivity gaps force redundant offline-capability investments. Mid-sized service contractors in Japan's construction segment exhibit highest price sensitivity due to METI subsidy dependency, while Australian utilities under Essential Services Commission mandates show lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Upstream feedstock for field service platforms draws from cloud infrastructure provisioning, mobile middleware development, and IoT sensor manufacturing concentrated in India, Japan, and Australia. Software development talent pools, hyperscaler data center capacity, and ruggedized hardware fabrication rest on these geographic anchors. Single-source vulnerability runs through Azure-anchored enterprise deployments dominating Australian telecommunications and utility sectors. Distribution runs through direct vendor-to-enterprise sales channels for large utilities, with systems integrator intermediaries serving mid-market manufacturing clients across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified cybersecurity engineering talent capable of navigating India's BIS framework and Australia's SCADA integration requirements is constraining vendor scaling velocity and compressing timelines for compliant product launches.
For Market Incumbents: Entrench platform stickiness through deep ERP integration partnerships with Japanese and South Korean manufacturing conglomerates resisting cloud migration, while accelerating defensive certification investments to preempt BIS compliance bottlenecks that delay challenger market entry by six to nine months. For New Entrants and Emerging Players: Build out white-space presence in Philippine utility privatization concessions and Indonesian archipelago mobile deployments where offline-capable synchronization protocols create technical differentiation against cloud-native incumbents, leveraging direct procurement relationships with independent power producers disintermediating OEM service networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors asset-centric workflow specialists with native IoT integration capabilities over generic scheduling platforms, as predictive maintenance automation displaces reactive dispatch models across the analysis window. Acquisition targets should demonstrate proven SCADA protocol engineering and established BIS certification pathways. The signal to watch is consolidation velocity among independent power producers in Indian solar farm operations, where contract unbundling from OEM maintenance agreements accelerates specialized platform procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP interconnection with SAP and Oracle systems secures manufacturing accounts in Japan and South Korea. |
| Geographic Expansion | METI subsidy-aligned distribution channels unlock mid-sized contractor segments previously priced out of enterprise systems. |
| Product Launch | BIS-certified cloud platforms capture procurement cycles at Indian state-owned utilities replacing legacy infrastructure. |
| Strategic Partnership | Azure infrastructure anchoring secures Australian utility and telecommunications provider deployments nationwide. |
| Acquisition of Specialist Firm | Asset-centric workflow capabilities address equipment uptime requirements at independent power producers. |
Study Parameters
The analysis maps cloud-native dispatch platforms, on-premise legacy systems, mobile field applications, and hybrid architectures, each validated through utility planning officers, IT procurement officers at manufacturing conglomerates, platform engineers, and systems integration specialists. Primary interviews with these stakeholders combined with secondary validation against Essential Services Commission reliability filings, BIS cybersecurity certification databases, METI SME digitalization subsidy records, and hyperscaler capex disclosures. Bottom-up deployment volume estimates and top-down addressable market sizing were triangulated to reconcile segment-level figures.
Assumptions held fixed include regulatory enforcement timelines for India's BIS framework and Australia's reliability mandates, while cloud migration velocity and IoT sensor penetration were varied across scenarios. The analytical framework modeled deployment mode, organization size, vertical sector, integration complexity, and regional adoption pattern across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated utility infrastructure investment cycles and manufacturing digitization subsidy disbursement patterns.
Stress conditions across BIS certification backlog duration, Indonesian telecom infrastructure deployment timelines, and Japanese ERP interdependency resolution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumption sets and acknowledge that regulatory enforcement intensity, connectivity infrastructure gaps, or legacy system modernization delays could revise trajectory. Cross-checking against Essential Services Commission outage duration reporting benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
GCC Managed Service Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Shared Services Center Market
Enterprise Services
United States Management Consulting Services Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Europe IT Services Market
Enterprise Services
Global Supply Chain As a Service (Scaas) Market
Enterprise Services
Employee Engagement Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
United States Managed Services Market
Enterprise Services
Network Outsourcing Market
Enterprise Services
North America Managed Services Market