
 Collaboration Tools Market | 2026-2036
Collaboration Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Collaboration Tools Market Analysis
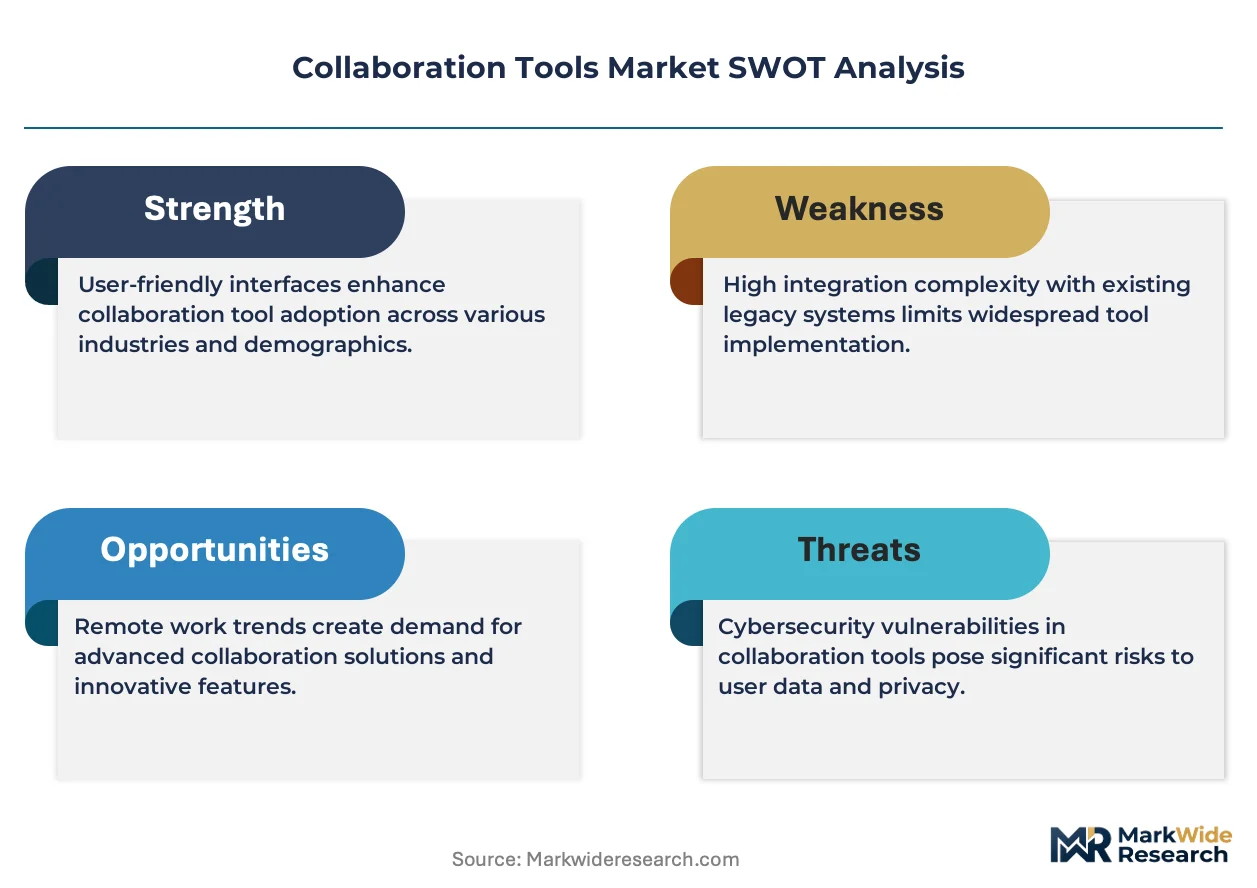
GDPR enforcement is hardening the cost-of-entry calculus for new collaboration vendors targeting European enterprises. Microsoft leverages its compliance infrastructure to sustain large-account retention across regulated industries. Google competes through native integration density with productivity suites, while Zoom anchors its position in video conferencing through specialized healthcare and education verticals.
Collaboration tools encompass software platforms enabling real-time communication, file synchronization, and workflow orchestration across distributed teams, typically delivered through cloud-native architectures with API extensibility. Their primary commercial purpose is reducing coordination friction in geographically dispersed organizations. Video conferencing and messaging command the largest revenue pools among product types, reflecting persistent hybrid work norms, while public cloud deployment dominates structural investment due to elastic scaling requirements. API integration represents the fastest-growing configuration dimension as enterprises demand seamless connectivity with existing ERP and CRM systems.
FDA guidelines on electronic health record interoperability shape collaboration tool requirements for US healthcare providers, while GDPR and the EU AI Act impose data residency and algorithmic transparency obligations across European deployments. ISO 27001 certification has become a non-negotiable procurement filter for financial services and government buyers. Stakeholders must monitor evolving cross-border data transfer mechanisms and emerging sector-specific AI governance frameworks to anticipate compliance-driven vendor selection criteria.
Market Dynamics
Enterprise procurement of collaboration platforms is compressing around compliance-certified vendors as GDPR and EU AI Act enforcement hardens data residency requirements across European healthcare and financial services deployments.
Growth Catalysts
- Hybrid work normalization:Healthcare delivery networks in Germany, the United Kingdom, and France are accelerating platform procurement to support distributed clinical teams and cross-facility care coordination.
- GDPR certification thresholds:EU AI Act transparency obligations are elevating vendor selection criteria, filtering procurement toward established providers with pre-built compliance infrastructure.
- API integration demand:Enterprises require seamless connectivity with existing ERP and CRM systems, driving configuration investment in modular, cloud-native architectures.
Market Restraints
- Compliance cost escalation:ISO 27001 certification and cross-border data transfer mechanism compliance impose substantial fixed costs on vendor operations, elevating barriers for new entrants.
- Input concentration risk:Public cloud infrastructure dependence creates scaling constraints tied to hyperscaler capacity and pricing power in concentrated markets.
- Regulatory fragmentation:Divergent FDA electronic health record interoperability requirements versus GDPR data residency rules force product architecture divergence across Atlantic deployments.
Strategic Opportunities
- Underpenetrated verticals:Specialized healthcare and education segments remain open to purpose-built collaboration tools with vertical-specific workflow templates and compliance pre-certification.
- Regulatory tailwinds:CSRD sustainability reporting mandates in Europe are creating demand for collaboration platforms with embedded carbon accounting and supply chain transparency features.
- Technology convergence:Integration of real-time video conferencing with AI-powered transcription and clinical decision support is automating documentation workflows in US hospital systems.
Industry Challenges
- Legacy system integration friction:Healthcare providers face extended deployment timelines connecting cloud-native platforms to on-premise electronic health record systems.
- Talent scarcity in compliance engineering:Vendors struggle to recruit specialists capable of navigating simultaneous FDA, GDPR, and ISO 27001 certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaboration Tools Market |
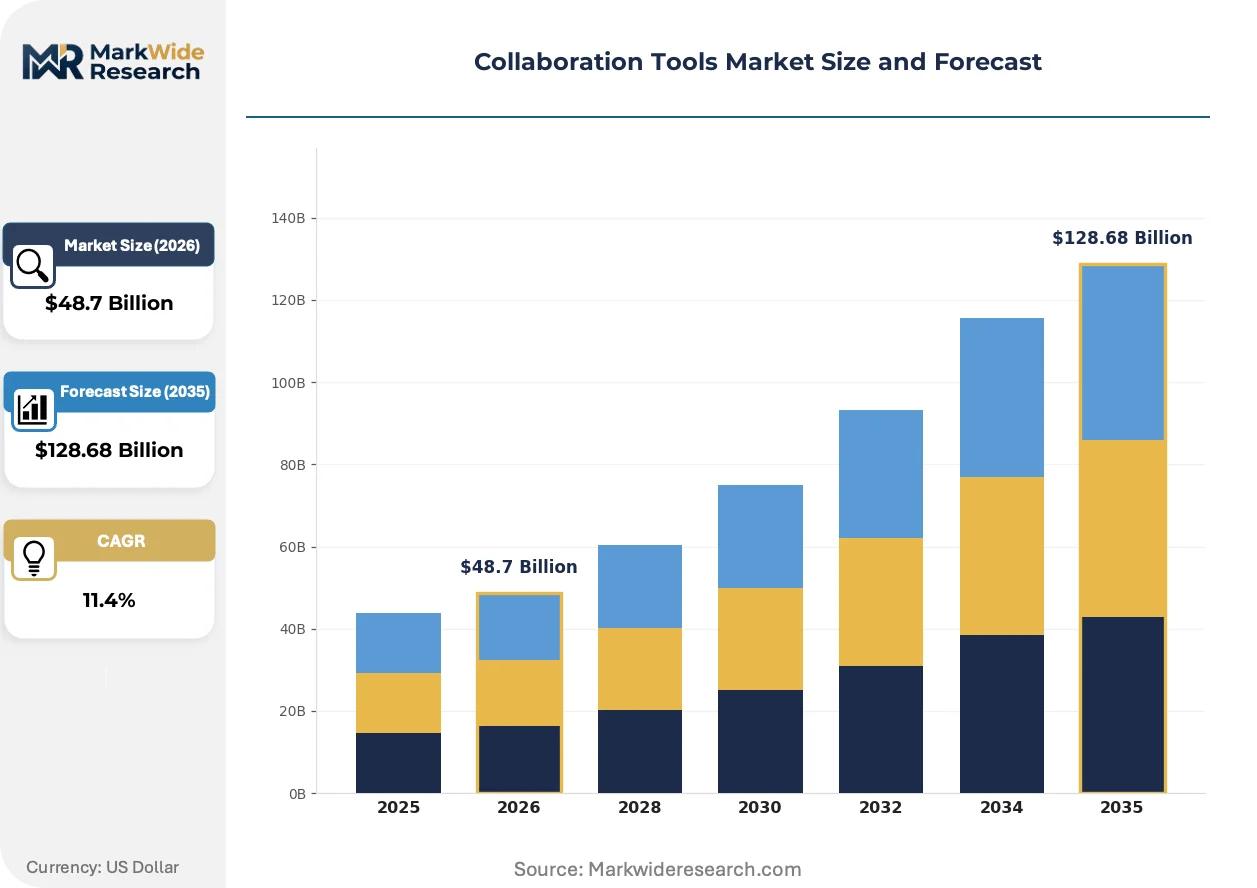
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Messaging, Video Conferencing, Project Management, Document Sharing Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud User Type: Small Businesses, Enterprises, Freelancers, Nonprofits Integration Level: API Integration, Third-Party Integration, Native Integration, Custom Integration |
| Companies Covered | Microsoft, Google, Zoom, Cisco, Salesforce, Slack, Atlassian, SAP SE, Zoho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaboration Tools Market Emerging Trajectories
Artificial intelligence is embedding into collaboration workflows, reshaping how distributed teams generate, distribute, and act on organizational knowledge across regulated and unregulated sectors alike.
Generative AI assistants are automating meeting summarization, action item extraction, and cross-platform workflow triggering in enterprise deployments. Financial services firms in London and Frankfurt are piloting these capabilities at scale, compressing the time between virtual collaboration and downstream CRM or ERP system updates. The technology is automating routine coordination tasks previously requiring dedicated administrative support.
The EU AI Act algorithmic transparency framework is mandating explainability features in AI-enabled collaboration tools deployed across European enterprises. Vendors must now document training data provenance and decision logic for automated content recommendations. Healthcare and legal services segments in Germany and France are demanding these disclosures as standard procurement criteria, filtering vendor shortlists toward compliant providers.
Enterprise buyers are consolidating vendor relationships around integrated productivity suites rather than point solutions for video, messaging, and file synchronization. Mid-market organizations in the United Kingdom are displacing standalone conferencing subscriptions with bundled offerings that reduce contract complexity and administrative overhead. This concentration is visible most acutely in professional services and technology sectors where IT procurement teams prioritize interoperability over best-of-breed feature depth.
Collaboration Tools Market Segmentation
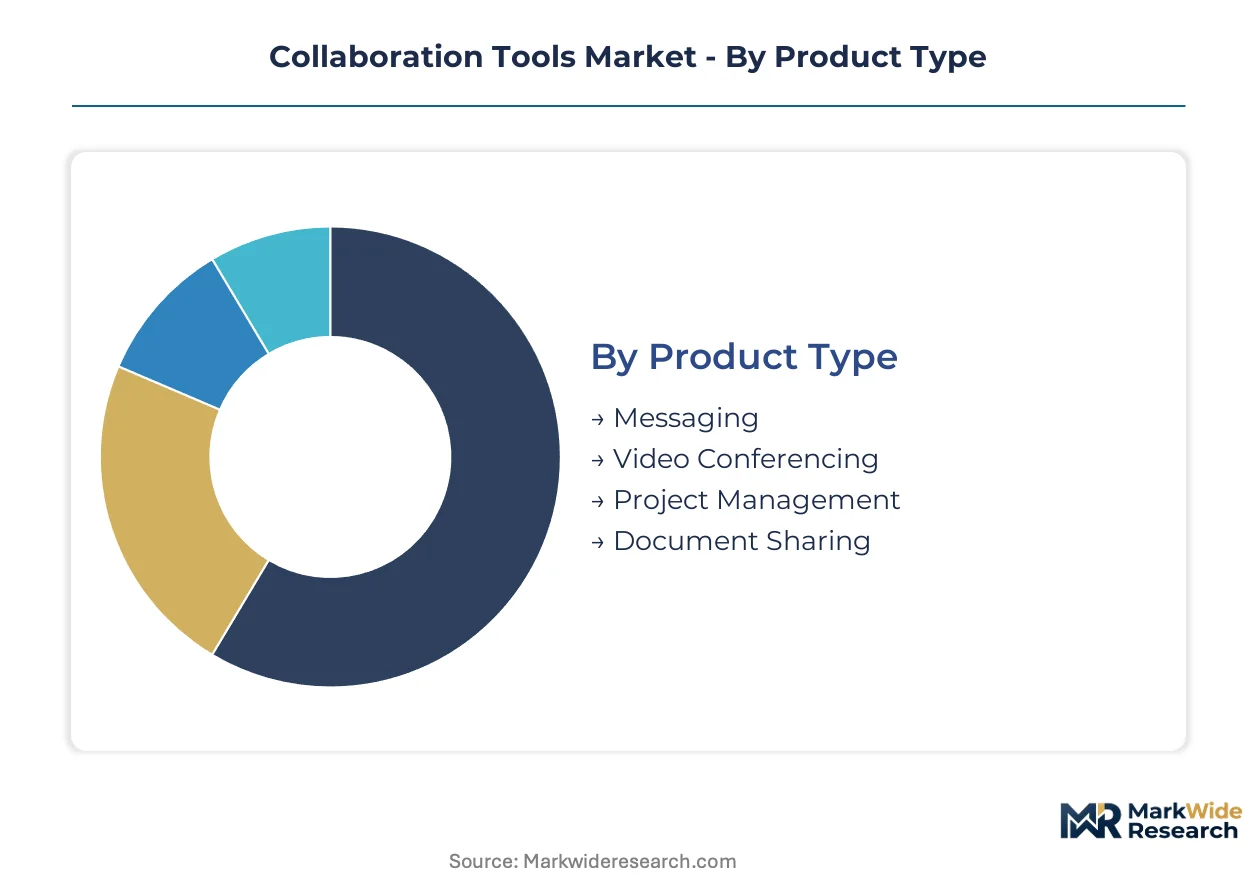
Segmentation in the collaboration tools market reveals how procurement criteria diverge across technical environments and organizational maturity. Buyers prioritize different configuration dimensions based on regulatory exposure, existing infrastructure, and workforce distribution patterns.
Product Type:
Enterprise buyers select product categories based on coordination friction points and compliance requirements specific to their operational workflows.
- Video Conferencing:Real-time audiovisual communication platforms with end-to-end encryption and recording capabilities. Healthcare delivery networks in Germany and the United Kingdom are prioritizing HIPAA and GDPR-compliant deployments for telemedicine consultations.
- Messaging:Persistent chat channels with threaded conversations and searchable history. Financial services firms in London and Frankfurt are driving demand for AI-assisted transcription with EU AI Act-mandated explainability features.
- Project Management:Task tracking and resource allocation systems with Gantt visualization and dependency mapping.
- Document Sharing:Cloud-based file synchronization with version control and granular permission architecture.
Video conferencing leads on scale; messaging leads on momentum.
Deployment Model:
Architecture decisions hinge on data residency obligations and elastic scaling requirements across regulated and unregulated industries.
- Public Cloud:Multi-tenant infrastructure with consumption-based pricing and automatic capacity expansion. Mid-market technology firms are displacing on-premise installations to reduce capital expenditure and accelerate deployment timelines.
- Hybrid Cloud:Split architecture keeping sensitive data on-premise while leveraging cloud elasticity for compute-intensive workloads. German healthcare providers are adopting this configuration to satisfy GDPR data localization while enabling cross-facility collaboration.
- Private Cloud:Single-tenant dedicated infrastructure with isolated security boundaries.
- On-Premises:Self-hosted installations with full administrative control over hardware and software stacks.
Public cloud dominates current procurement volumes; hybrid cloud is climbing the fastest as compliance complexity intensifies.
User Type:
Organizational scale determines feature requirements, contract structures, and integration sophistication demanded from vendors.
- Enterprises:Organizations with 500+ employees requiring SSO, advanced analytics, and dedicated support tiers. Large account procurement in France and the United Kingdom is consolidating around bundled productivity suites with pre-certified compliance infrastructure.
- Small Businesses:Companies with under 50 employees prioritizing rapid deployment and minimal administrative overhead. Freelancer collectives and boutique professional services firms are driving subscription growth in tiered pricing tiers.
- Freelancers:Individual contractors needing lightweight, pay-as-you-grow access without long-term commitments.
- Nonprofits:Mission-driven organizations with constrained budgets and volunteer coordination requirements.
Enterprises command the largest contract values; small businesses are gaining share fastest as vendor pricing stratifies downward.
Integration Level:
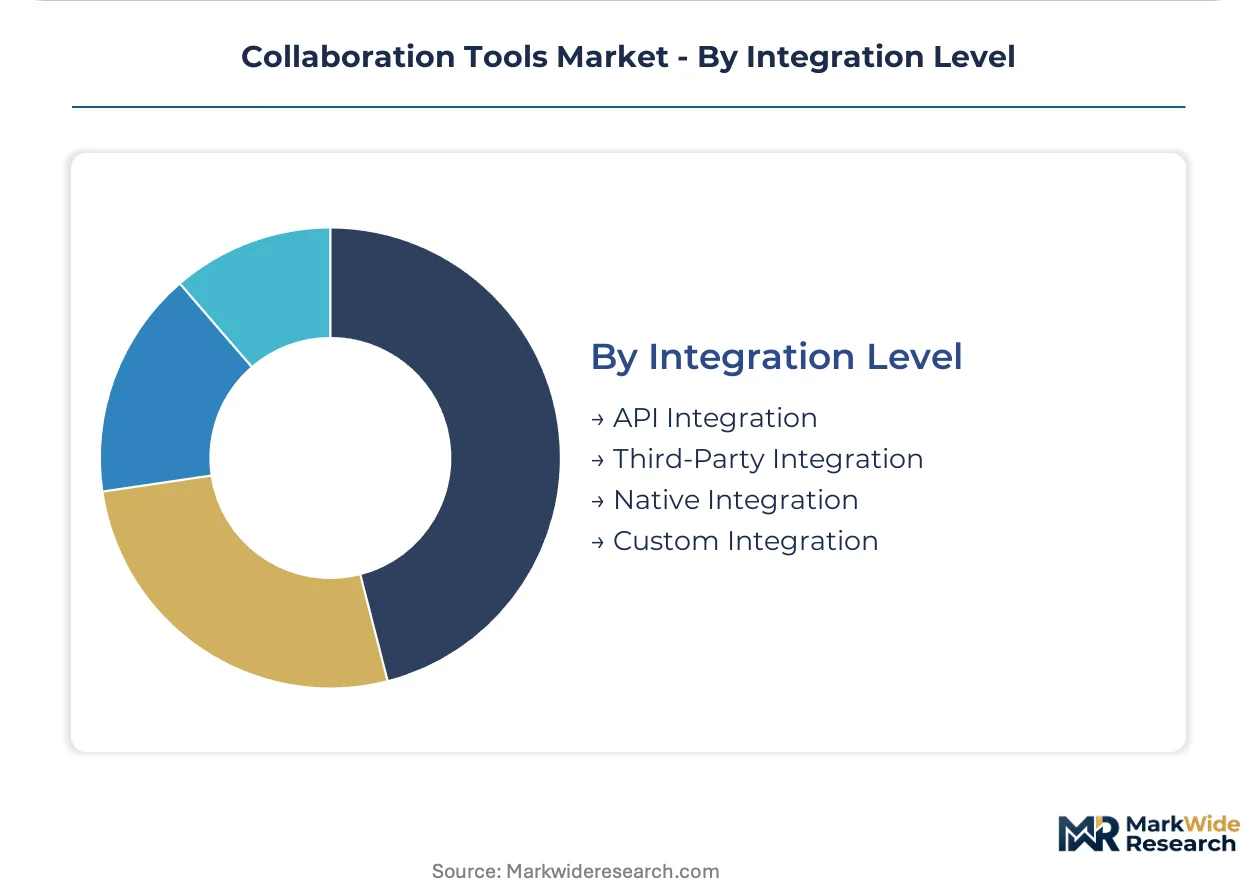
Connectivity depth with existing enterprise systems has become a primary selection criterion as IT teams reduce vendor fragmentation.
- API Integration:Programmatic interfaces enabling custom workflow automation and data exchange with ERP and CRM systems. This configuration is expanding most quickly as enterprises demand seamless connectivity across their technology stacks.
- Native Integration:Pre-built connectors to productivity suites and cloud storage platforms without additional development. Professional services firms in the United Kingdom are displacing standalone tools for bundled offerings with embedded interoperability.
- Third-Party Integration:Middleware-dependent connections requiring external integration platforms.
- Custom Integration:Bespoke development projects linking proprietary or legacy systems to modern collaboration infrastructure.
Native integration leads on current deployment scale; API integration is expanding most quickly as modular architecture preferences harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent clusters in Seattle, Bangalore, and London anchor platform development capacity for enterprise-grade collaboration infrastructure.
United States
FDA electronic health record interoperability guidelines drive healthcare provider procurement of HIPAA-compliant platforms. Hospital networks in Boston and the Research Triangle deploy integrated video conferencing for telemedicine consultations. Enterprise buyers in financial services concentrate procurement decisions in New York and Chicago.
Germany
GDPR data residency requirements and EU AI Act transparency obligations elevate vendor certification thresholds for healthcare delivery networks. Baden-Württemberg and Bavaria host manufacturing enterprises consolidating around bundled productivity suites with pre-certified compliance infrastructure. Munich-based automotive groups demand seamless ERP integration.
United Kingdom
Financial services firms in London pilot generative AI assistants for meeting summarization and CRM workflow automation. The Information Commissioner's Office enforces cross-border data transfer compliance for cloud deployments. Professional services clusters in Manchester and Edinburgh displace standalone tools for integrated offerings.
France
Healthcare delivery networks accelerate platform procurement to support distributed clinical teams across Île-de-France and Auvergne-Rhône-Alpes. CNIL oversight of algorithmic decision-making shapes vendor selection criteria for AI-enabled transcription services. Paris-based legal services firms mandate explainability documentation.
India
IT services exporters in Bangalore and Hyderabad drive demand for API-extensible platforms supporting global client coordination. The Digital Personal Data Protection Act establishes emerging compliance frameworks for cross-border data flows. Mumbai financial services firms prioritize native integration with existing enterprise systems.
Collaboration Tools Market Vendor Landscape
The competitive structure tilts toward productivity-suite bundlers with pre-built compliance infrastructure. Vendor consolidation compresses procurement decisions around integrated platforms rather than point solutions for video, messaging, or file synchronization. Three archetypes dominate: hyperscaler-backed productivity suites, specialized vertical platforms, and API-first modular tools. Strategic moves center on M&A for compliance certification assets and geographic expansion through localized data residency offerings.
Within the hyperscaler tier, Microsoft and Google exemplify integrated-platform dominance through bundled offerings that reduce contract complexity. Zoom occupies a position as the vertical-specialist archetype for healthcare and education deployments. Salesforce represents the ecosystem-extender model through CRM-native collaboration capabilities.
| Leading Market Players |
|---|
| Microsoft |
| Zoom |
| Cisco |
| Salesforce |
| Slack |
| Atlassian |
| SAP SE |
| Zoho Corporation |
| Others |
Supply Flow & Price Mechanics
Public cloud compute pricing indices cascade through collaboration tool supply chains, compressing margins for vendors dependent on hyperscaler infrastructure while enabling tiered service differentiation across enterprise, mid-market, and freelancer segments. The cost structure of API extensibility and compliance certification propagates into subscription pricing, with GDPR-ready deployments commanding premium positioning against basic cloud-native offerings.
Pricing Analysis
The bundled-versus-unbundled service split structures pricing across the collaboration tools market, with integrated productivity suites capturing enterprise accounts through consolidated contracts while point solutions compete on specialized feature depth. Subscription SaaS-tiered models dominate, with price differentiation driven by ISO 27001 certification grade and vertical integration depth with ERP systems. Pricing pressure stems from hyperscaler capacity constraints elevating infrastructure costs, with small businesses exhibiting highest price sensitivity and financial services enterprises showing lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
Certification and qualification gating concentrates vendor qualification around ISO 27001, HIPAA, and GDPR compliance infrastructure, filtering procurement toward established providers with pre-built audit frameworks. Supply concentrates in the United States, Ireland, and Singapore for cloud infrastructure, with raw material dependencies on semiconductor components, fiber optic capacity, and data center real estate. Single-source vulnerability in hyperscaler routing creates supply chain risk. Distribution runs through direct enterprise sales teams and cloud marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collaboration tools market functions as a geographic-arbitrage play where GDPR compliance costs in Germany and France exceed equivalent certification burdens in India, creating cost-advantaged development positioning for vendors serving price-sensitive segments.
For Market Incumbents: Hedge against API-first modular competitors by deepening native integration density with dominant productivity suites. Invest in localized data residency infrastructure across German and French deployments to defend against emerging vendors lacking EU AI Act transparency documentation. Prioritize certification maintenance as the primary retention lever against compliance-driven displacement.
For New Entrants and Emerging Players: Cloud marketplace distribution routes offer lowest-friction customer acquisition for specialized healthcare and education verticals where incumbent bundling creates feature gaps. Target underpenetrated mid-market professional services in the United Kingdom where contract complexity drives demand for simplified, compliance-pre-certified offerings. Lead with vertical-specific workflow templates as the primary go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where compliance engineering talent scarcity intersects with escalating certification thresholds, favoring acquisition of specialist firms with pre-built GDPR and FDA infrastructure. Long-term viability centers on platform ecosystems with embedded AI transparency features. Watch for EU AI Act enforcement intensity as the signal indicating inflection toward compliance-dominant vendor selection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native ERP connectivity reduces procurement friction for Munich automotive groups. |
| Acquisition of Specialist Firm | GDPR-certified targets accelerate market entry for US vendors targeting European healthcare. |
| Geographic Expansion | Localized data residency in Frankfurt satisfies CNIL oversight for Paris legal services firms. |
| Product Launch | AI-powered transcription with explainability documentation meets EU AI Act procurement criteria. |
| Strategic Partnership | Hospital system partnerships in Boston anchor HIPAA-compliant telemedicine platform adoption. |
Methodological Framework
Direct dialogue with CTOs, IT procurement officers, platform engineers, and healthcare compliance directors grounded qualitative insights, validated against SEC filings, hyperscaler capex disclosures, App Annie usage data, and hospital procurement databases. Secondary sources included FDA guidance documents, EU AI Act regulatory texts, and ISO certification registries. Bottom-up deployment modeling and top-down market sizing triangulated volume and value estimates.
Segment-level projections across deployment model, organization size, vertical specialization, integration complexity, and regional adoption pattern generated consistent growth trajectories across the analysis window. CAGRs derived from historical penetration rates adjusted for regulatory enforcement timelines and cloud infrastructure expansion curves. Inputs included healthcare delivery network procurement cycles and financial services technology refresh patterns.
Regulatory enforcement delays, hyperscaler capacity constraints, and cross-border data transfer mechanism rulings are the dominant revision risks to projection assumptions. A model refresh is warranted upon material change in EU AI Act implementation intensity or FDA interoperability guideline finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Advanced Process Control Software Market
Software & Services
Global Product Management and Road Mapping Tool Market
Software & Services
Europe Servicenow Store Apps Market
Software & Services
Europe Drone Software Market
Software & Services
Real Estate Software Market
Software & Services
Global Microscopy Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Global Investor Relationship Management Software Market
Software & Services
US Software Consulting Market
Software & Services
Low Code Development Platform Market
Software & Services
Semiconductor Fabrication Software Market
Software & Services
Global DevOps Software Market
Software & Services
Towing Software Market
Software & Services
VFX Software Market
Software & Services
Data Conversion Services Market