
 Travel and Expense Management Market | 2026-2036
Travel and Expense Management Market Size, Share, and Industry Trends Forecast 2026-2036
Travel and Expense Management Market Outlook
Market Context
Professional services is pivoting toward integrated travel and expense platforms as hybrid work policies entrench permanent mobility budgets. SAP Concur leverages its enterprise ERP connectivity to sustain dominance across Fortune 500 accounts. Navan anchors its position through vertical integration into corporate card issuance and negotiated hotel rates. Expensify competes on freemium user acquisition, converting individual contractors into departmental deployments.
Technical Definition and Segment Structure
Travel and expense management encompasses software systems that capture, validate, reconcile, and report employee-incurred business costs through automated receipt scanning, policy enforcement algorithms, and general ledger synchronization. Cloud-based service models lead current deployments, though hybrid architectures retain share among financial institutions with data residency requirements. The client type dimension shows SMEs representing the fastest-growing adoption curve as subscription pricing removes upfront capital barriers. Integrative tools command premium positioning by embedding directly into accounting suites and HR information systems, while standalone mobile apps face margin compression from feature commoditization.
Regulatory Environment
GDPPR governs cross-border expense data processing for European deployments, while the EU AI Act imposes transparency obligations on automated policy enforcement algorithms. The US Internal Revenue Service maintains strict substantiation standards for deductible business travel, creating compliance-driven demand for audit-trail completeness. Organizations must monitor evolving VAT e-invoicing mandates across EU member states, as real-time reporting requirements force platform upgrades.
Market Dynamics
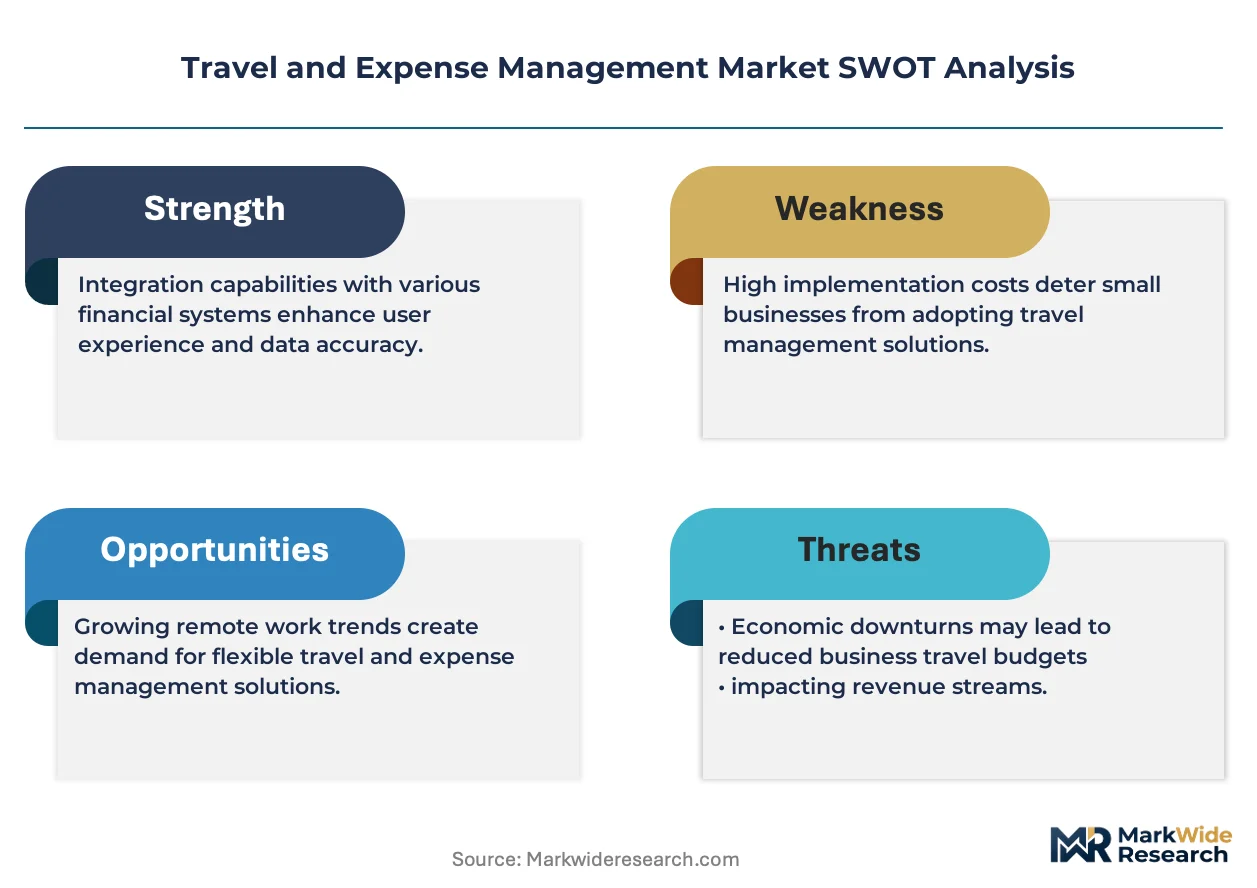
Hybrid work normalization has permanently embedded mobility budgets into corporate operating models, forcing vendors to rebuild expense platforms around continuous travel rather than episodic events. This structural shift demands real-time policy engines that adapt to fluid work arrangements.
Growth Catalysts
- EU AI Act transparency mandates:Automated policy enforcement algorithms now require explainable decision trails, driving upgrades to audit-ready platforms.
- Mittelstand digitalization:German mid-market professional services firms are replacing on-premise SAP workflows with cloud-native alternatives that synchronize with modern banking APIs.
- Real-time VAT e-invoicing:European member states are mandating instant transaction reporting, forcing legacy systems toward API-first architectures.
Market Restraints
- Data residency requirements:Financial institutions in Switzerland and Germany demand hybrid architectures that fragment vendor operating leverage.
- GDPR cross-border friction:Reimbursement data flowing between EU and non-EU entities triggers complex legal entity structuring.
- Receipt verification labor:Manual exception handling for non-compliant submissions persists as a fixed cost anchor.
Strategic Opportunities
- Embedded finance convergence:Corporate card issuance integrated with expense capture is rewriting margin structures for platform providers.
- India's PLI scheme:Manufacturing incentives are expanding business travel volumes among domestic mid-market enterprises.
- Carbon accounting mandates:Scope 3 emissions tracking is creating attach opportunities for travel data platforms.
Industry Challenges
- Legacy ERP integration complexity:SAP on-premise instances resist API connectivity, extending implementation timelines.
- Algorithmic bias auditing:EU AI Act requires ongoing validation of automated approval thresholds across diverse employee populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel and Expense Management Market |
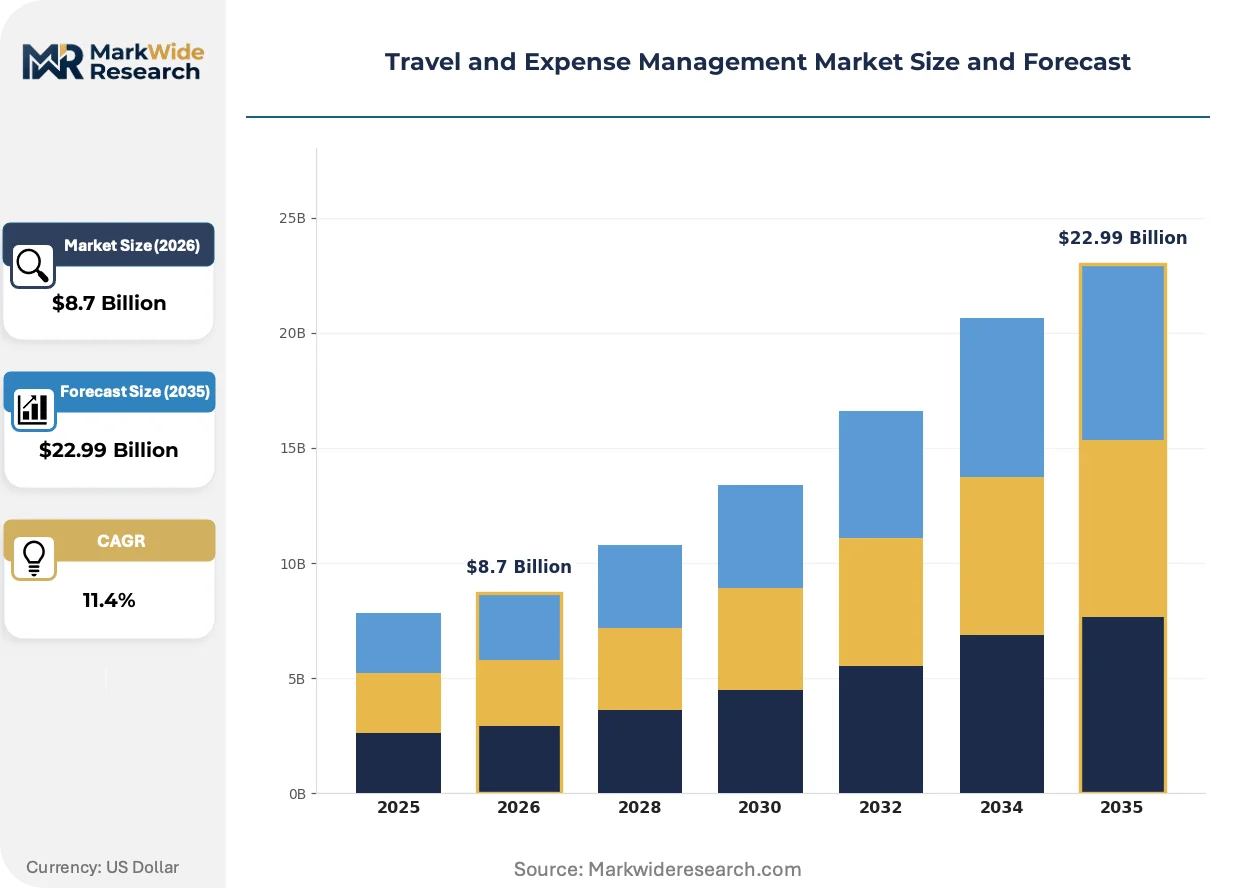
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Software, Mobile App, Web Platform, Integrative Tool Expense Category: Travel, Meals, Lodging, Transportation Client Type: SMEs, Large Enterprises, Government Agencies, Non-Profits Service Model: On-Premise, Cloud-Based, Hybrid, Subscription |
| Companies Covered | TravelPerk, Coupa, Navan, Happay, Zoho Expenses, SAP Concur, Rydoo, SpendMantra, Expensify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel and Expense Management Market Strategic Shifts
Expense management platforms are converging with adjacent financial infrastructure, erasing boundaries between travel booking, payment issuance, and accounting reconciliation. This integration is compressing vendor stacks and elevating data sovereignty as a competitive differentiator.
Optical character recognition combined with large language models is rewriting how receipt data enters corporate systems. Mid-market professional services firms in Germany and the Netherlands are deploying these tools at scale, compressing the gap between transaction occurrence and ledger posting from days to minutes. The structural consequence is margin pressure on standalone mobile capture apps that lack upstream payment or downstream ERP connectivity.
GDPR enforcement actions by CNIL in France and supervisory authorities in Germany are tightening consent requirements for automated expense categorization. Industrial consequence includes mandatory human-in-the-loop review for high-value transactions. Platforms serving cross-border workforces are responding by segmenting processing logic across regional cloud instances.
Subscription fatigue among finance departments is shortening software evaluation cycles and elevating proof-of-concept requirements. Procurement teams now demand sandbox access before contractual commitment, displacing traditional vendor-led demonstrations. This pattern is most visible in the United Kingdom and Nordic markets, where centralized procurement functions have consolidated vendor evaluation authority.
Travel and Expense Management Market Segmentation
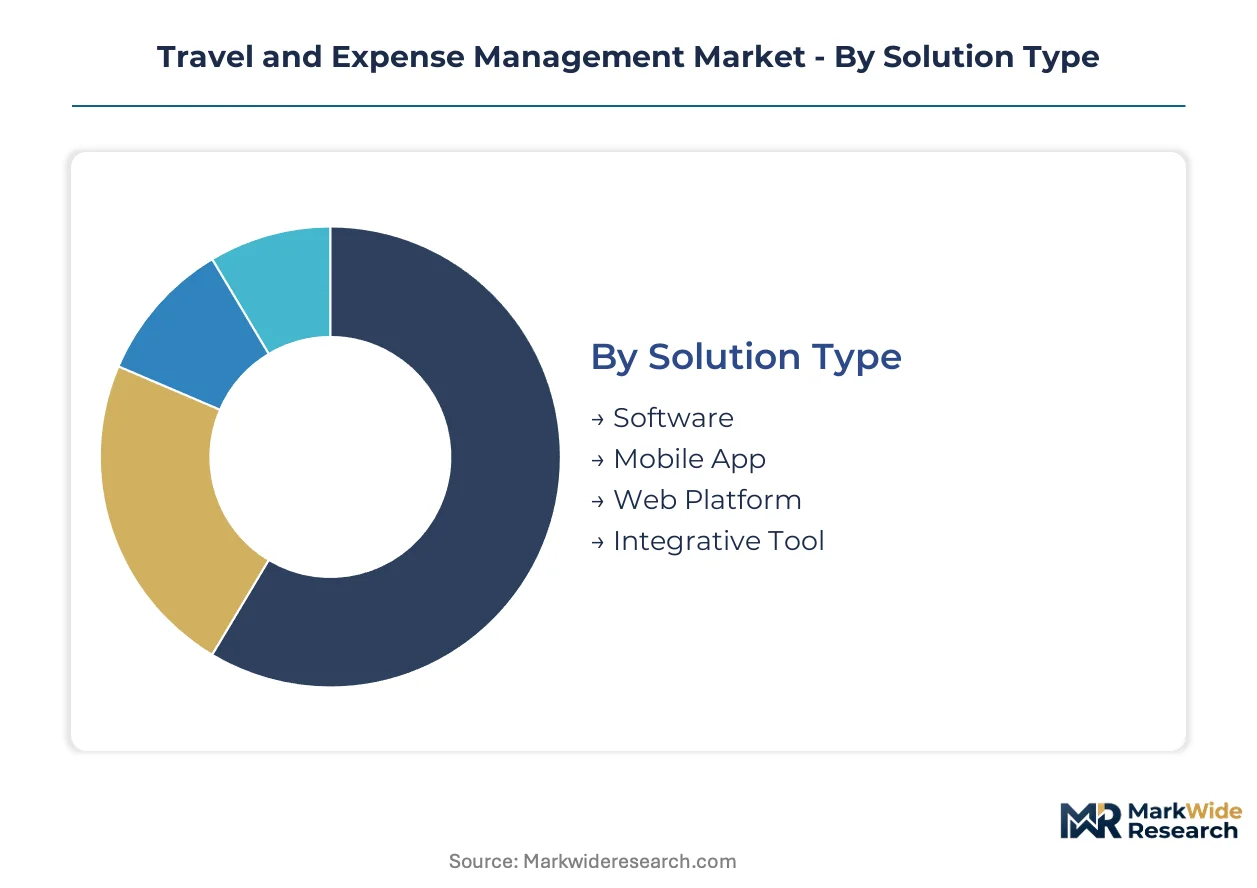
Expense management platforms fragment across deployment architectures, user interfaces, and client scale. Each segmentation dimension carries distinct margin profiles and integration requirements that reshape vendor competitive positioning.
Solution Type:
Supply concentration in this category clusters around platforms that embed directly into corporate financial infrastructure rather than standalone point solutions.
- Software:Desktop-deployed applications with deep ERP synchronization capabilities dominate Fortune 500 procurement cycles. German Mittelstand firms are replacing legacy SAP modules with API-first alternatives that automate general ledger posting.
- Mobile App:Receipt capture tools with optical character recognition compress submission-to-reimbursement timelines from weeks to hours. Mid-market professional services firms in the Netherlands deploy these at scale for field-based consultants.
- Web Platform:Browser-accessible dashboards enable centralized policy administration across distributed workforces. These solutions absorb the bulk of installed capacity; integrative tools are expanding most quickly.
- Integrative Tool:Embedded modules within accounting suites and HR information systems eliminate data re-entry friction.
Software absorbs the bulk of installed capacity; integrative tools are expanding most quickly.
Expense Category:
Cost tier differentiation in this dimension separates high-velocity transaction types from compliance-intensive categories requiring audit-grade documentation.
- Travel:Airfare and ground transportation bookings demand real-time policy enforcement against negotiated corporate rates. EU AI Act transparency mandates are forcing upgrades to explainable approval algorithms for cross-border itineraries.
- Meals:Per-diem calculations and receipt verification generate disproportionate administrative overhead. French CNIL enforcement actions now require explicit consent for automated categorization of dining expenses.
- Lodging:Hotel bookings integrate with corporate rate programs and sustainability reporting for Scope 3 emissions tracking. Travel commands the highest transaction values; meals processing volumes are climbing the fastest.
- Transportation:Ride-hailing and rental car expenses require mileage validation against policy thresholds.
Lodging commands the highest transaction values; meals processing volumes are climbing the fastest.
Client Type:
Volume concentration in this category tilts toward organizations with sufficient procurement leverage to demand custom workflow configurations.
- SMEs:Subscription pricing models remove upfront capital barriers, accelerating adoption among professional services firms with 50-500 employees. India's PLI scheme is expanding domestic mid-market manufacturing travel volumes.
- Large Enterprises:Multi-entity structures require sophisticated cross-border data routing compliant with GDPR residency requirements. Swiss and German financial institutions demand hybrid architectures that fragment vendor operating leverage.
- Government Agencies:Public sector procurement mandates elevate audit-trail completeness above feature velocity. Large enterprises absorb the bulk of installed capacity; SMEs are gaining share fastest.
- Non-Profits:Grant-funded operations impose restricted-use compliance layers on expense categorization.
Large enterprises absorb the bulk of installed capacity; SMEs are gaining share fastest.
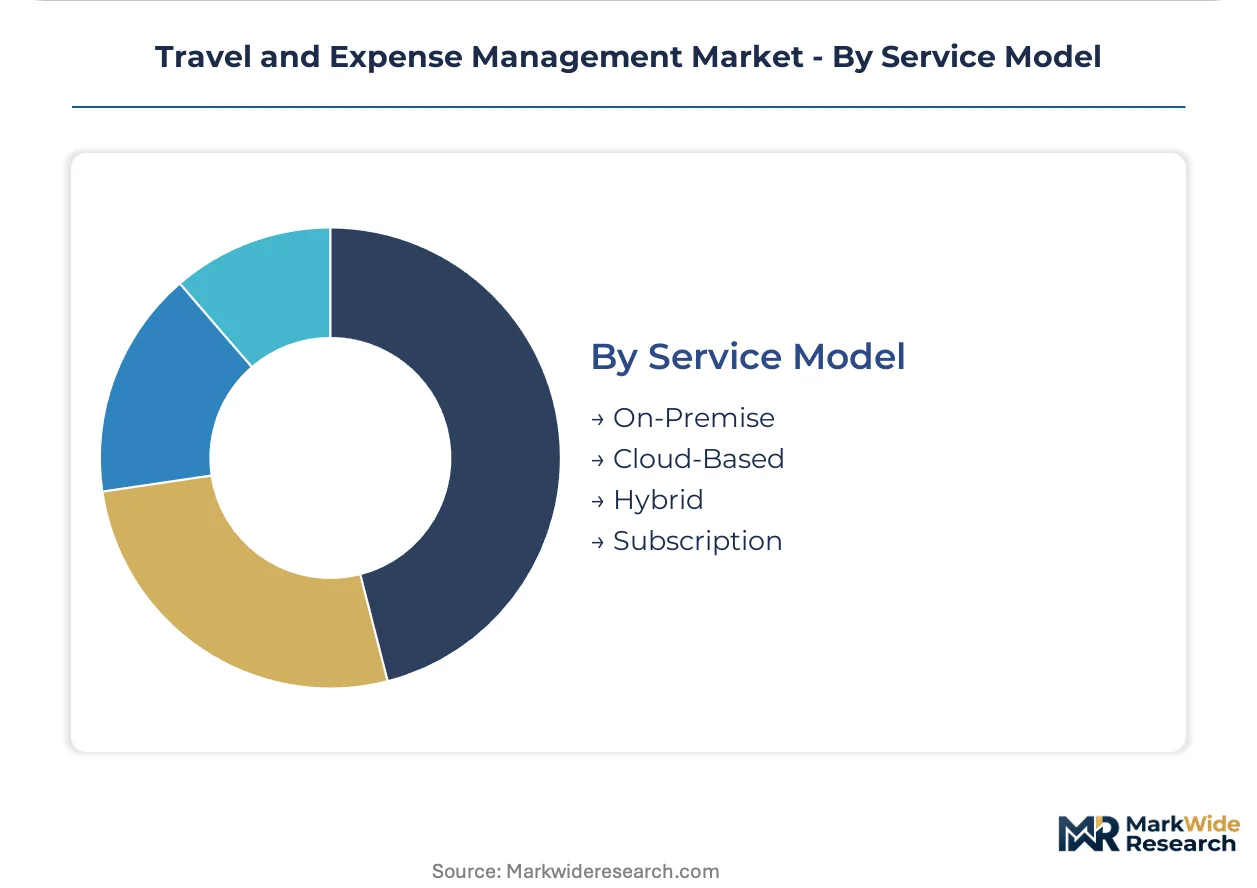
Service Model:
Margin structure in this dimension separates capital-intensive on-premise deployments from recurring-revenue cloud subscriptions with divergent customer lifetime values.
- On-Premise:Legacy installations within financial institutions resist API connectivity, extending implementation timelines. These systems retain share where data residency requirements prohibit third-party cloud processing.
- Cloud-Based:SaaS architectures enable continuous feature deployment and real-time VAT e-invoicing compliance across EU member states. Real-time reporting mandates are forcing legacy migrations toward API-first architectures.
- Hybrid:Segmented processing logic across regional cloud instances addresses cross-border GDPR friction. Cloud-based deployments absorb the bulk of new bookings; hybrid configurations are expanding most quickly in regulated sectors.
- Subscription:Predictable pricing reduces procurement evaluation cycles but intensifies vendor switching risk.
Cloud-based deployments absorb the bulk of new bookings; hybrid configurations are expanding most quickly in regulated sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Special Economic Zones and software technology parks of India (STPI) scheme have concentrated SaaS development centers in Bengaluru and Hyderabad, anchoring regional capacity for cloud-native expense platforms serving mid-market professional services firms.
United States
Fortune 500 procurement cycles drive demand for deep ERP synchronization capabilities, particularly among financial services and technology sectors. The Internal Revenue Service maintains strict substantiation standards for deductible business travel, forcing platform upgrades for audit-trail completeness. New York and San Francisco metropolitan areas host the densest concentrations of hybrid work policies, embedding permanent mobility budgets into corporate operating models.
Germany
Mittelstand professional services firms with 50-500 employees are replacing legacy SAP workflows with API-first alternatives that automate general ledger posting. The EU AI Act and GDPR compliance requirements from supervisory authorities reshape how vendors process cross-border reimbursement data. Munich and Frankfurt clusters concentrate financial institutions demanding hybrid architectures that fragment vendor operating leverage.
United Kingdom
Centralized procurement functions in London and the Southeast have consolidated vendor evaluation authority, shortening software evaluation cycles and elevating proof-of-concept requirements. Subscription fatigue among finance departments demands sandbox access before contractual commitment. The Information Commissioner's Office enforces GDPR consent requirements for automated expense categorization.
Netherlands
Mid-market professional services firms deploy mobile receipt capture tools at scale for field-based consultants, compressing submission-to-reimbursement timelines. Amsterdam's fintech corridor integrates corporate card issuance with expense capture, rewriting margin structures for platform providers. Real-time VAT e-invoicing mandates force legacy systems toward API-first architectures.
India
The Production-Linked Incentive (PLI) scheme expands domestic mid-market manufacturing travel volumes, creating attach opportunities for expense data platforms. Bengaluru and Hyderabad technology parks concentrate SaaS development capacity serving global mid-market deployments. The Reserve Bank of India and central bank regulations govern cross-border data flows for financial institutions.
Travel and Expense Management Market Competitive Environment
Top-tier vendors anchor enterprise ERP connectivity, while mid-market specialists compete on freemium user acquisition and vertical integration into corporate card issuance. The vendor base stratifies across three tiers: ERP-integrated incumbents with Fortune 500 lock-in, cloud-native challengers with API-first architectures, and mobile-first capture tools facing margin compression. Dominant competitive moves include embedded finance convergence and strategic partnerships with banking API providers.
Within the ERP-integrated tier, SAP Concur occupies a position exemplifying enterprise connectivity dominance. Among cloud-native challengers, Navan and Expensify represent divergent archetypes—Navan anchors vertical integration into payment issuance, while Expensify exemplifies freemium conversion strategies targeting departmental deployments. TravelPerk sits within the mid-market specialist vector, reflecting geographic concentration in European technology corridors.
| Leading Market Players |
|---|
| TravelPerk |
| Coupa |
| Navan |
| Happay |
| Zoho Expenses |
| SAP Concur |
| Rydoo |
| SpendMantra |
| Expensify |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up expense management platforms anchor supply concentration in cloud infrastructure and banking API partnerships, tightening pricing discipline through subscription lock-in and embedded finance convergence. This ownership pattern compresses margin flexibility for standalone vendors while elevating data sovereignty as a premium pricing lever.
Pricing Analysis
Short lead-time deployments command SaaS subscription premiums as finance departments demand sandbox access before contractual commitment. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth and ERP connectivity, with SAP synchronization tiers extracting highest willingness-to-pay. Pricing pressure stems from subscription fatigue shortening evaluation cycles, while mid-market professional services firms in Germany and the Netherlands exhibit highest price sensitivity due to fragmented vendor alternatives.
Supply Chain Analysis
Direct-to-enterprise channels handle Fortune 500 procurement cycles, while partner-mediated distribution serves SME segments through accounting suite integrations. Cloud infrastructure concentrates in the United States, Ireland, and Germany to satisfy GDPR residency requirements, with optical character recognition engines drawing from Bengaluru and Hyderabad development clusters. Single-source vulnerability in banking API partnerships creates supply chain risk, as platform functionality hinges on real-time payment rail connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where corporate card issuance and negotiated hotel rates constitute the decisive downstream lever. Players capturing payment flow upstream of expense capture are rewriting margin structures and displacing standalone software vendors.
For Market Incumbents: Extend ERP connectivity moats through deeper SAP S/4HANA integration and real-time general ledger synchronization to defend against API-first challengers. Fortify position by acquiring regional banking API specialists in Germany and the Netherlands, where Mittelstand digitalization accelerates. Prioritize hybrid architecture investments to satisfy Swiss and German financial institution data residency requirements. For New Entrants and Emerging Players: Mid-market manufacturing enterprises in India under India's PLI scheme represent the most penetrable buyer archetype, as expanding domestic travel volumes outpace incumbent platform localization. Carbon accounting mandates create attach opportunities for travel data platforms with Scope 3 emissions tracking. Pursue sandbox-first go-to-market strategies mirroring UK procurement patterns to accelerate departmental conversion. For Investors and Strategic Acquirers: Distressed-cycle entries favor mobile-first capture tools facing margin compression in the United Kingdom and Nordic markets, where subscription fatigue has elongated sales cycles. Long-term viability centers on platforms with embedded payment issuance or captive corporate card programs. Monitor EU AI Act enforcement actions by CNIL and German supervisory authorities as inflection indicators for compliance-driven upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures automate general ledger posting for SAP S/4HANA migrations in German Mittelstand firms. |
| Embedded Finance Convergence | Corporate card issuance integrated with expense capture rewrites margin structures for platform providers. |
| Geographic Expansion | India's PLI scheme expands domestic mid-market manufacturing travel volumes for localized platform deployments. |
| Strategic Partnership | Banking API alliances enable real-time VAT e-invoicing compliance across EU member states. |
| Acquisition of Specialist Firm | OCR engine providers with large language model capabilities compress transaction-to-ledger timelines from days to minutes. |
Study Parameters
Independent corroboration across finance department procurement leads, SaaS platform product managers, banking API integration specialists, and corporate travel managers underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SEC filings of publicly traded vendors, EU regulatory databases tracking GDPR enforcement actions, and customs records of software service exports anchors the evidence base. Bottom-up deployment sizing and top-down market aggregation triangulate volume estimates.
Rate-of-change decomposition across solution type, expense category, client scale, and service model dimensions structures the analytical framework over the projection horizon. CAGRs derive from modeled adoption curves by organization size and regional regulatory cluster, with hybrid work policy permanence and EU AI Act compliance timelines as industry-specific forecast inputs. Deployment architecture migrations and real-time reporting mandate deadlines inform trajectory assumptions.
Revisions become necessary when EU member states accelerate VAT e-invoicing deadlines, banking API providers alter data access terms, or GDPR enforcement actions mandate human-in-the-loop processing requirements. Practitioners should monitor CNIL algorithmic bias rulings and German supervisory authority consent requirement expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Asia Pacific Field Service Management Market
Enterprise Services
Workforce Management Market
Enterprise Services
Global Small Office Home Office (SOHO) Service Market
Enterprise Services
Internet of Things (IoT) Managed Services Market
Enterprise Services
Africa Managed Services Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Europe Managed Services Market
Enterprise Services
South-East Asia Consulting Services Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Field Service Management Market
Enterprise Services
Enterprise Social Graph Market
Enterprise Services
Qatar Cloud Managed Services Market
Enterprise Services
Asia-Pacific Warehouse Management Systems Market
Enterprise Services
Open Source ERP Market
Enterprise Services
Proactive Services Market