
 Qatar Managed Services Market | 2026-2036
Qatar Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Managed Services Market Analytics
Qatar's National Cybersecurity Strategy is shifting procurement priorities across government and critical infrastructure verticals, mandating continuous monitoring and incident response capabilities that internal IT teams cannot sustain. MEEZA QSTP LLC leverages its sovereign cloud infrastructure to anchor public-sector contracts requiring data residency. Hexaware Technologies competes through AI-augmented service desk automation tailored to regional labor constraints. Gulf Business Machines Qatar W.L.L. dominates enterprise network management through its long-standing channel control with multinational oil and gas operators.
Managed services encompass the ongoing administration, optimization, and security of IT infrastructure, applications, and end-user systems under contractual service-level agreements specifying uptime thresholds, mean-time-to-resolution, and compliance attestations. Cloud Services leads segment revenue as Qatar Energy and Qatar Airways migrate legacy workloads to sovereign and hyperscale environments. Security Solutions represents the fastest-expanding category, driven by regulatory pressure and ransomware exposure across financial services and healthcare. SMBs remain an underpenetrated client type where standardized remote monitoring and management tools could unlock recurring revenue pools.
The National Cybersecurity Agency and Qatar Central Bank issue binding operational resilience directives that shape vendor qualification criteria, audit frequency, and data localization requirements for managed security providers. The Communications Regulatory Authority enforces telecom-grade reliability standards on cloud and network management services delivered over national infrastructure. Stakeholders must monitor evolving certification mandates and sovereign data requirements as procurement authorities tighten vendor eligibility frameworks.
Market Dynamics
Qatar's National Cybersecurity Strategy is compressing procurement cycles for managed security services, forcing government entities and critical infrastructure operators to outsource continuous monitoring and incident response capabilities that internal IT teams cannot sustain.
Growth Catalysts
- Energy Sector Outsourcing Mandates:Qatar Energy and downstream petrochemical operators are expanding multi-year contracts for IT infrastructure operations, transferring operational risk to specialized providers.
- Sovereign Cloud Requirements:Data localization directives from the National Cybersecurity Agency are disqualifying non-compliant vendors and channeling public-sector spending toward domestic data center operators.
- Smart City Deployments:Lusail City and Msheireb Downtown Doha's integrated command centers require 24/7 managed services for IoT networks, video analytics, and building automation systems.
Market Restraints
- Specialized Talent Scarcity:Qatar's domestic labor pool lacks certified cybersecurity architects and cloud infrastructure engineers, forcing providers to import expertise at premium compensation levels.
- Vendor Concentration Risk:Hyperscale cloud services depend on a limited set of international providers with regional presence, creating single-point-of-failure exposure for enterprise clients.
- Regulatory Compliance Friction:Qatar Central Bank's operational resilience directives impose audit frequency and capital reserve requirements that elevate service delivery costs for financial services contracts.
Strategic Opportunities
- Underpenetrated SMB Segment:Small and medium enterprises in Al Wakrah and Al Rayyan municipalities remain underserved by standardized remote monitoring and management tools.
- AI-Augmented Service Desk Convergence:Machine learning-based ticket classification and predictive incident resolution are converging with regional labor constraints to automate tier-one support functions.
- Healthcare Digitalization:Hamad Medical Corporation's electronic health record expansion and private hospital network upgrades are creating demand for HIPAA-aligned managed security services.
Industry Challenges
- Certification Timeline Compression:Qatar's Communications Regulatory Authority is accelerating telecom-grade reliability standards, forcing providers to compress ISO 27001 and PCI-DSS audit cycles.
- Legacy System Integration Complexity:Oil and gas operators' decades-old SCADA environments resist seamless cloud migration, requiring costly middleware development and extended transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Managed Services Market |
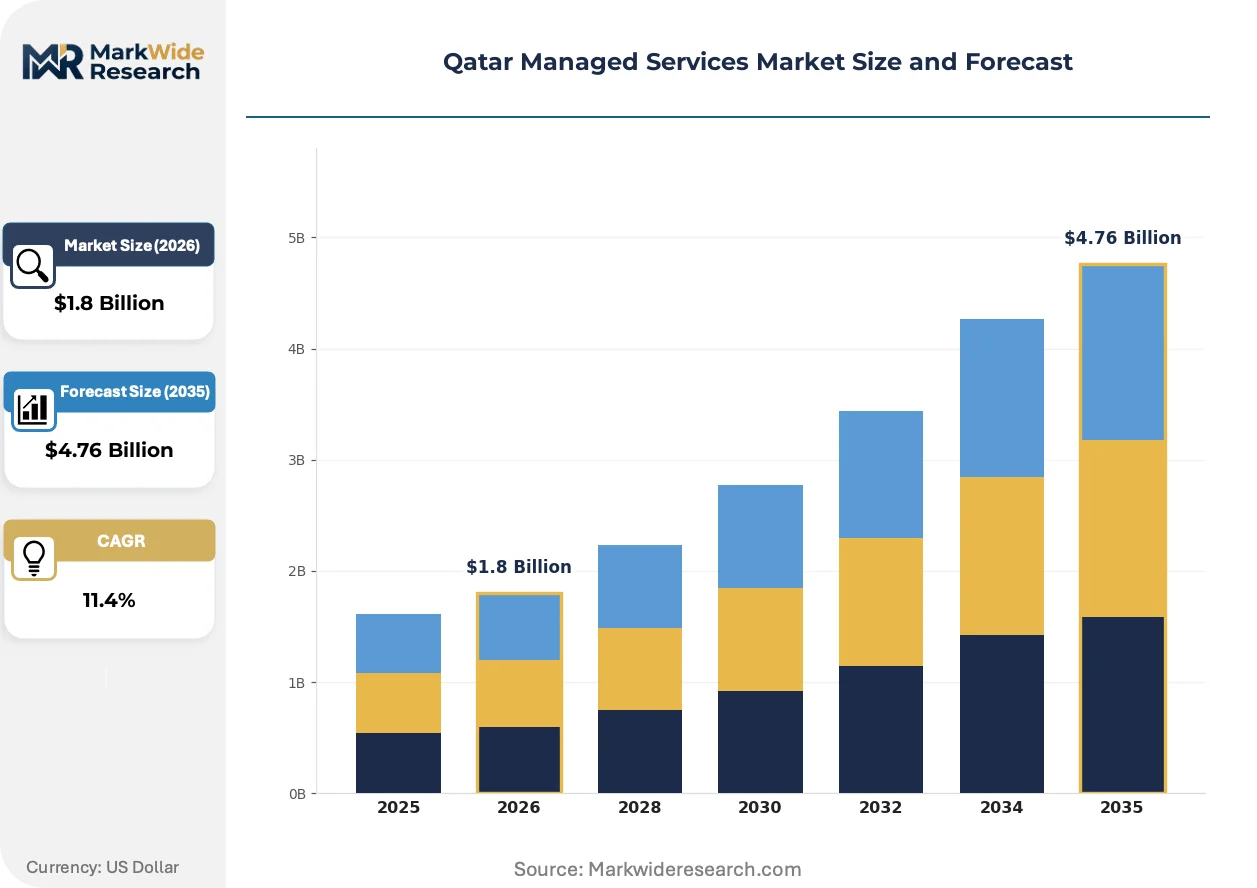
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, Cloud Services, Security Solutions, Data Backup Client Type: SMBs, Enterprises, Government, Nonprofits Delivery Model: On-Premise, Cloud-Based, Hybrid, Managed Technology: AI, IoT, Big Data, Automation |
| Companies Covered | Paramount Computer Systems FZ-LLC, Hexaware Technologies, MEEZA QSTP LLC, Zazz, Systems Limited, Gulf Business Machines Qatar W.L.L., Ooredoo Q.P.S.C., Net at Work LLC, Diyar Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Managed Services Market Evolving Landscape
Managed services in Qatar are pivoting from infrastructure maintenance toward predictive security operations and sovereign data governance, reshaping how providers architect service delivery and qualify for public-sector contracts.
Extended detection and response platforms aggregate telemetry across endpoints, networks, and cloud workloads to enable automated threat containment. Qatar's financial services sector is adopting these capabilities fastest, driven by Qatar Central Bank incident reporting mandates. This convergence is compressing mean-time-to-response metrics and displacing traditional managed security service provider architectures that relied on human-led investigation.
The National Cybersecurity Agency's binding operational resilience directives now prescribe minimum service continuity thresholds and mandatory penetration testing frequencies for critical infrastructure operators. Industrial consequence includes disqualification of providers lacking certified security operations centers within Qatar's borders. Energy and healthcare verticals are responding by re-tendering contracts with explicit data residency and sovereign infrastructure clauses.
Enterprise buyers are unbundling managed services from hardware procurement, separating network equipment purchases from ongoing operational support. Systems integrators and value-added distributors are losing attach-rate leverage as direct procurement teams negotiate standalone service-level agreements. This pattern is most visible among Qatar Airways and Qatar Steel's IT divisions, where multi-source vendor strategies now dominate infrastructure refresh cycles.
Qatar Managed Services Market Segmentation
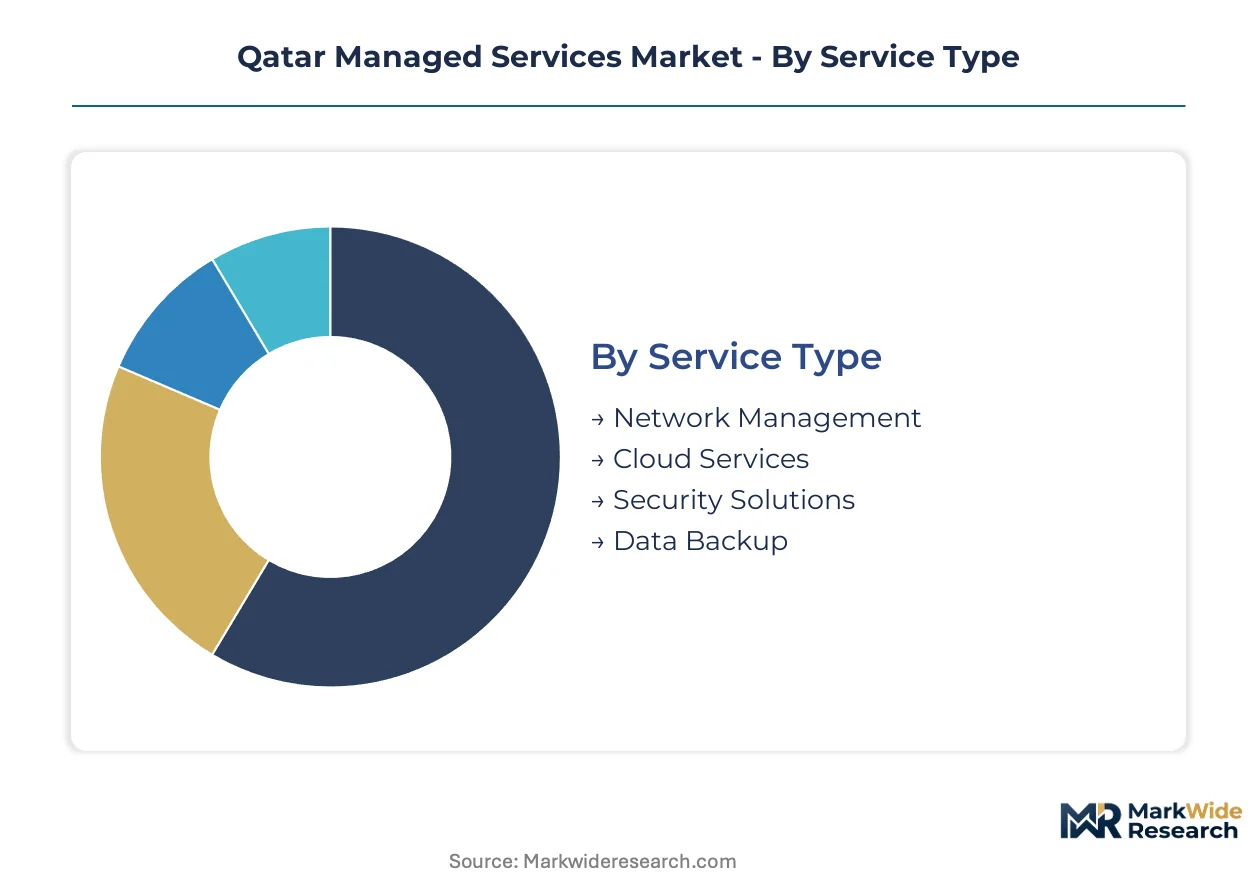
Procurement teams in Qatar segment managed services by compliance burden and operational criticality. Certification requirements from the National Cybersecurity Agency and Qatar Central Bank create divergent vendor qualification pathways across service categories.
Service Type:
ISO 27001 certification is mandatory for Security Solutions and Cloud Services contracts with government entities, while Network Management and Data Backup face lighter audit requirements.
- Cloud Services:Sovereign infrastructure provisioning and hyperscale workload migration dominate Qatar Energy and Qatar Airways procurement. Data residency mandates from the National Cybersecurity Agency disqualify non-compliant vendors from public-sector tenders.
- Security Solutions:Continuous monitoring, incident response, and threat intelligence platforms face the steepest certification requirements. Qatar Central Bank directives mandate quarterly penetration testing for financial services deployments.
- Network Management:SD-WAN optimization and enterprise connectivity maintenance carry moderate compliance overhead.
- Data Backup:Disaster recovery and archival storage solutions require basic operational resilience attestations.
Leading the category by volume: Cloud Services. Growing fastest: Security Solutions.
Client Type:
Cost tier structures diverge sharply, with Government contracts demanding sovereign infrastructure premiums and SMBs seeking standardized remote monitoring packages.
- Enterprises:Multi-year outsourcing agreements with Qatar Energy and Qatar Airways transfer operational risk to specialized providers. These contracts specify 99.99% uptime SLAs and dedicated security operations center access.
- Government:National Cybersecurity Agency mandates prescribe minimum service continuity thresholds and mandatory data localization for all critical infrastructure operators.
- SMBs:Al Wakrah and Al Rayyan municipalities remain underserved by remote monitoring and management tools.
- Nonprofits:Limited procurement budgets restrict adoption to basic managed security offerings.
Highest contract values: Enterprises. Steepest expansion trajectory: SMBs.
Delivery Model:
Application criticality determines architecture choice, with financial services favoring hybrid deployments and healthcare prioritizing on-premise control.
- Hybrid:Split workloads across sovereign data centers and hyperscale cloud enable Qatar Central Bank compliance without sacrificing elasticity. Hamad Medical Corporation deploys this architecture for electronic health record systems.
- Cloud-Based:Full public cloud migration accelerates among Qatar Airways and Qatar Steel IT divisions pursuing multi-source vendor strategies.
- On-Premise:Legacy SCADA environments in oil and gas resist seamless migration.
- Managed:End-to-end operational responsibility transfers dominate government procurement.
Dominant deployment: Hybrid. Gaining share fastest: Cloud-Based.
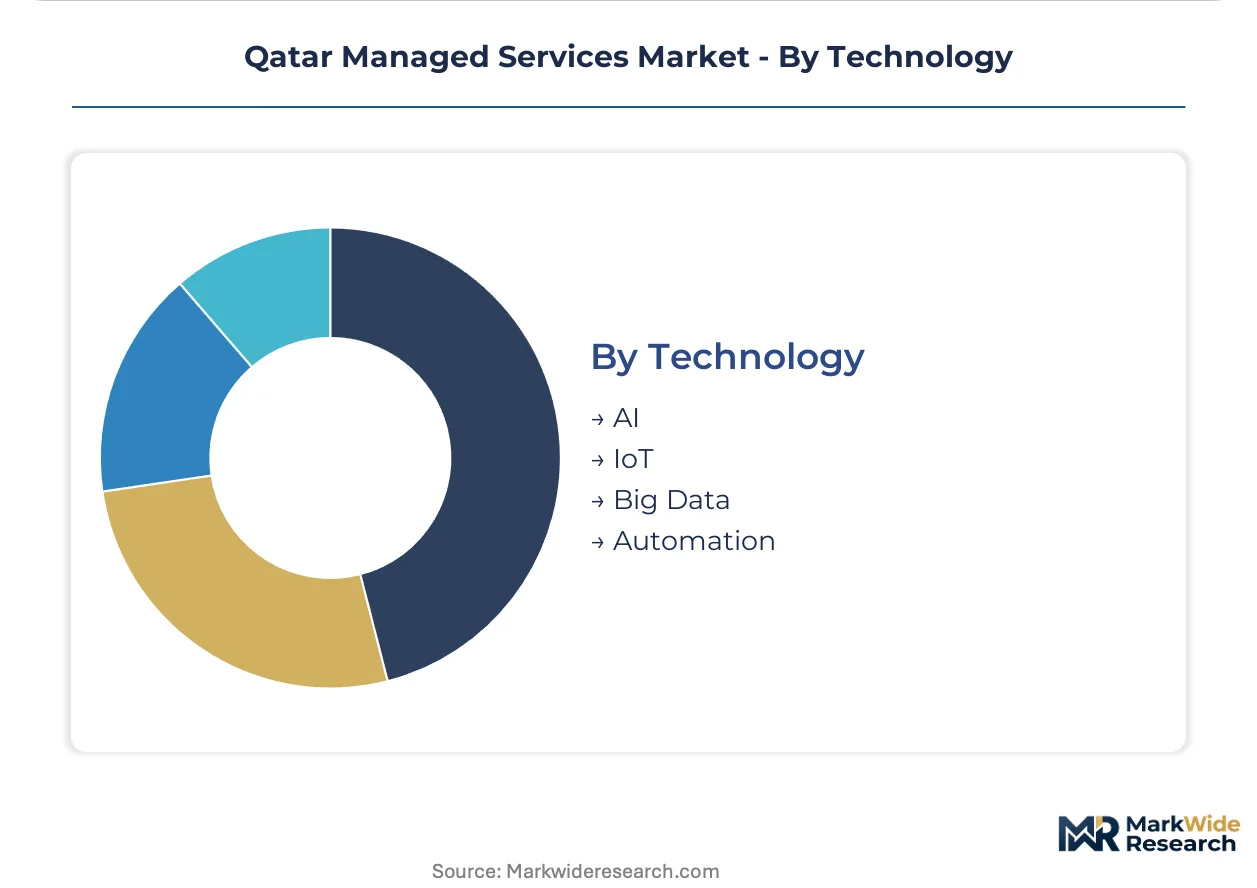
Technology:
Margin profiles vary by implementation maturity, with AI-augmented service desks commanding premium pricing and IoT networks requiring heavy integration investment.
- AI:Machine learning-based ticket classification and predictive incident resolution automate tier-one support. Regional labor constraints accelerate adoption among providers serving constrained talent markets.
- Automation:Robotic process automation for routine infrastructure tasks reduces mean-time-to-resolution metrics across financial services clients.
- IoT:Lusail City and Msheireb Downtown Doha integrated command centers require 24/7 sensor network management.
- Big Data:Analytics platforms for operational intelligence remain nascent outside energy sector pilots.
Widest deployment: Automation. Climbing the fastest: AI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Doha metropolitan area concentrates Qatar's managed services demand, hosting hyperscale data center clusters and smart city deployments that anchor procurement activity for IT infrastructure outsourcing.
Doha
Qatar Energy and Qatar Airways headquarters drive enterprise outsourcing contracts for cloud migration and security operations. The National Cybersecurity Agency mandates data localization for government tenders, channeling public-sector spending toward sovereign infrastructure providers. Lusail City and Msheireb Downtown Doha's integrated command centers require continuous IoT network management and building automation support.
Al Wakrah
Industrial zones south of Doha generate demand for SCADA-integrated managed services among petrochemical operators. The Communications Regulatory Authority enforces telecom-grade reliability standards on network services delivered over national infrastructure. Manufacturing facilities in this municipality remain underserved by standardized remote monitoring tools targeting mid-market clients.
Al Rayyan
Educational and research institutions cluster around Education City, creating specialized requirements for research data management and HPC workload support. Qatar Central Bank's operational resilience directives shape vendor qualification criteria for financial services contracts. Healthcare digitalization at Hamad Medical Corporation facilities drives demand for HIPAA-aligned managed security services.
Umm Salal
Logistics and distribution centers north of Doha require edge computing infrastructure and warehouse automation system management. The National Cybersecurity Strategy accelerates compliance requirements for critical infrastructure operators handling supply chain data. Barzan Industrial Area manufacturing plants are expanding outsourced IT operations to specialized providers.
Qatar Managed Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and sovereign infrastructure ownership. The vendor base stratifies into three tiers: global systems integrators with regional delivery capabilities, domestic data center operators leveraging data residency mandates, and specialized security providers targeting financial services compliance. Competitive positioning depends on National Cybersecurity Agency certifications and Qatar Central Bank audit qualifications. Market consolidation is accelerating through public-sector contract awards and multi-year energy sector outsourcing mandates.
Among Qatar-based operators, MEEZA QSTP LLC exemplifies the sovereign infrastructure archetype, anchoring public-sector contracts through certified data center assets within national borders. Hexaware Technologies occupies a position representing the AI-augmented automation tier, competing through service desk modernization tailored to regional talent constraints. Gulf Business Machines Qatar W.L.L. sits within the enterprise network management segment, maintaining channel relationships with multinational oil and gas operators.
| Leading Market Players |
|---|
| Paramount Computer Systems FZ-LLC |
| Hexaware Technologies |
| MEEZA QSTP LLC |
| Zazz |
| Systems Limited |
| Gulf Business Machines Qatar W.L.L. |
| Ooredoo Q.P.S.C. |
| Net at Work LLC |
| Diyar Group |
| Others |
Value Network & Pricing Analysis
Certified cybersecurity talent compensation flows through managed services pricing tiers, with Qatar-based security operations center staffing costs anchoring premium quotations for government contracts while remote monitoring automation compresses mid-market service desk rates in Al Wakrah and Al Rayyan municipalities.
Pricing Analysis
Uptime-guarantee pricing anchors enterprise contracts, with Qatar Energy and Qatar Airways procurement teams negotiating service-level agreements tied to 99.99% availability thresholds and mean-time-to-resolution guarantees. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-cloud government deployments from hybrid enterprise arrangements and SMB remote monitoring packages. Pricing pressure stems from regional talent scarcity forcing providers to import certified architects at premium compensation levels. Government entities show least price sensitivity due to data residency mandates, while manufacturing facilities in industrial zones exhibit highest cost consciousness.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale buyer demand from Qatar Energy and Qatar Airways, bypassing traditional systems integrators as procurement teams unbundle hardware from operational support. India, the United Arab Emirates, and the United Kingdom concentrate certified security operations center talent pools that Qatar providers draw from through expatriate recruitment. Hyperscale cloud infrastructure, sovereign data center real estate, and specialized cybersecurity tooling constitute critical input dependencies. Single-source vulnerability runs through international cloud provider regional presence. Distribution runs through certified domestic operators for public-sector contracts and direct vendor relationships for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed services providers are racing to deepen control over sovereign data center assets and certified security workforce pipelines, with National Cybersecurity Agency compliance requirements forcing backward integration into domestic infrastructure ownership.
For Market Incumbents: Hedge against hyperscale cloud provider encroachment by securing long-term sovereign data center leases in Doha metropolitan clusters and accelerating ISO 27001 certification renewal cycles ahead of Communications Regulatory Authority timeline compression. Channel relationships with Qatar Energy and multinational oil operators require reinforcement as procurement teams adopt multi-source vendor strategies. For New Entrants and Emerging Players: Launch via standardized remote monitoring and management platforms targeting underserved SMB manufacturing facilities in Al Wakrah industrial zones, where talent constraints and compliance overhead have discouraged incumbent penetration. AI-augmented service desk automation offers the most penetrable entry vector for providers lacking sovereign infrastructure assets. For Investors and Strategic Acquirers: National Cybersecurity Agency disqualification of providers lacking certified security operations centers within Qatar's borders is the leading indicator that sovereign infrastructure ownership will determine long-term contract viability. Acquisition targets should demonstrate domestic data center assets and established relationships with Qatar Central Bank-regulated financial institutions. Periodic monitoring of public-sector tender award patterns signals inflection points in competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Certification | Domestic security operations center accreditation unlocks National Cybersecurity Agency contract eligibility. |
| AI-Augmented Service Desk Deployment | Machine learning ticket classification addresses regional cybersecurity architect scarcity constraints. |
| Multi-Source Vendor Strategy Adoption | Qatar Airways and Qatar Steel procurement teams separate hardware from operational support contracts. |
| Healthcare Digitalization Partnership | Hamad Medical Corporation electronic health record expansion demands HIPAA-aligned managed security. |
| Smart City Infrastructure Management | Lusail City integrated command centers require continuous IoT network and building automation support. |
Research Methodology
Regulatory filings from the National Cybersecurity Agency, Qatar Central Bank operational resilience directives, and Communications Regulatory Authority standards formed the secondary backbone, supplemented by customs data on technology imports and hyperscaler regional capex disclosures. Primary interviews with managed services procurement officers at Qatar Energy, cybersecurity architects at domestic data center operators, and IT directors at Hamad Medical Corporation facilities combined with secondary validation through bottom-up and top-down triangulation.
Bottom-up modeling aggregated contract value estimates across Cloud Services, Security Solutions, Network Management, and Data Backup segments, while top-down analysis cross-referenced Qatar's national IT spending projections and energy sector outsourcing budget disclosures. Deployment model, client type, and technology sophistication dimensions structured the segmentation framework across the analysis window. CAGRs derived from historical contract renewal patterns and regulatory mandate acceleration timelines, with sovereign cloud migration velocity and ransomware incident frequency serving as industry-specific forecast inputs.
Regulatory timeline compression, talent import restriction tightening, and hyperscale provider market entry are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding sustained National Cybersecurity Agency enforcement intensity and continued energy sector outsourcing appetite. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Asia-Pacific Contingent Workforce Management Market
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Network Consulting Services Market
Enterprise Services
North America Contingent Workforce Management Market
Enterprise Services
Enterprise Internet Reputation Management Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Supplier Management Market
Enterprise Services
Workforce Management Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Global AWS Managed Services Market