
 ENT Endoscopy Market | 2026-2036
ENT Endoscopy Market Size, Share, and Industry Trends Forecast 2026-2036
ENT Endoscopy Market Analysis
A capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is reorganizing competitive tiers in ENT endoscopy. Karl Storz SE & Co. KG leverages its German manufacturing base to sustain in-house optical production. Olympus Corporation anchors its position through fiber-optic technology leadership across Asian and European channels. Medtronic plc competes by extending its hospital direct-sales infrastructure into outpatient settings.
ENT endoscopy encompasses the diagnostic and surgical visualization of the ear, nose, and throat using rigid or flexible optical instruments, typically featuring rod-lens systems with diameters of 2.7–4.0 mm and integrated light guides for illumination. These devices enable minimally invasive examination, biopsy, and operative intervention within anatomically constrained spaces. Flexible endoscopes dominate procedural volume in laryngology and vocal cord examination due to their navigational adaptability through curved airway passages, while video endoscopes capture expanding margin pools as hospitals convert from fiber-optic to digital imaging platforms. Rigid endoscopes retain durable demand in sinus surgery where optical clarity and instrument stability prove essential.
FDA 510(k) premarket notification requirements shape product entry timelines for US-bound manufacturers, while the EU Medical Device Regulation imposes stricter clinical evidence standards on reusable endoscope reprocessing claims. ISO 13485 quality management certification functions as a baseline threshold for supplier qualification across OECD procurement frameworks. Stakeholders must monitor how FDA guidance on disposable endoscope components interacts with sustainability mandates under the EU Green Deal to anticipate portfolio restructuring requirements.
Market Dynamics
The conversion from fiber-optic to digital imaging platforms is compressing replacement cycles and redistributing margin pools toward video endoscope manufacturers with captive sensor supply.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification for digital imaging endoscopes shortens commercialization timelines for US market entry.
- Ambulatory Surgical Center Expansion:Outpatient facilities across the United States are building dedicated ENT service lines requiring flexible endoscope fleets.
- German Precision Manufacturing Cluster:Concentrated optical component production in Tuttlingen and Berlin sustains supplier proximity for European OEMs.
Market Restraints
- Rod-Lens Optical Component Concentration:Specialized glass grinding and sapphire lens fabrication remain concentrated among German and Japanese suppliers.
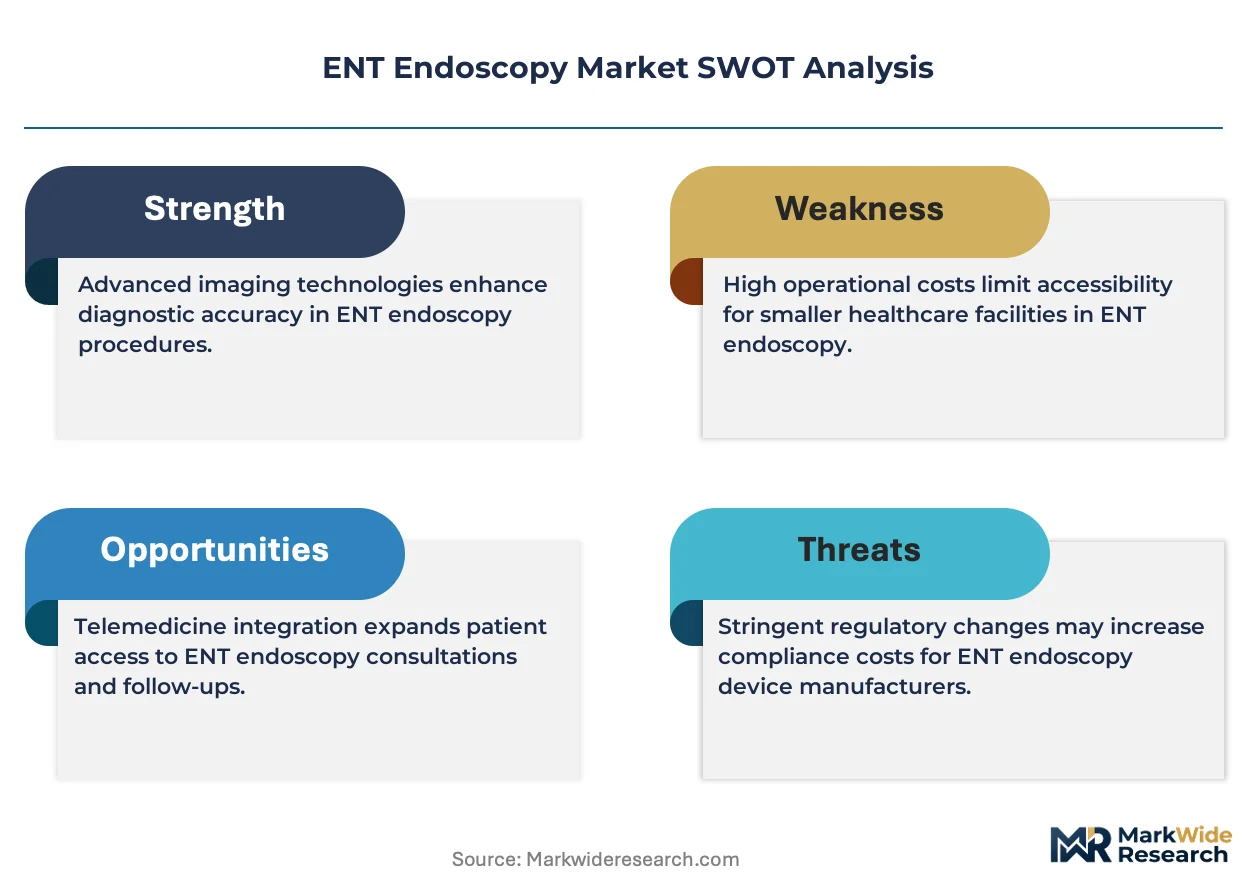
- EU MDR Clinical Evidence Burden:Stricter reprocessing validation requirements for reusable endoscopes extend certification timelines and inflate documentation costs.
- Single-Use Endoscope Cost Differential:Disposable bronchoscope and rhinolaryngoscope alternatives carry per-procedure cost premiums that constrain hospital adoption.
Strategic Opportunities
- India Outpatient Infrastructure Buildout:Government hospital modernization programs and private clinic chains create first-time demand for flexible nasopharyngoscopy.
- AI-Assisted Pathology Integration:Convergence of high-definition digital capture with real-time lesion detection algorithms enables premium positioning in tertiary hospitals.
- EU Green Deal Reprocessing Mandates:Sustainability disclosure requirements favor manufacturers with validated low-temperature sterilization protocols and repairable instrument designs.
Industry Challenges
- Biomedical Engineer Specialization Gap:Maintenance of rod-lens systems and video processor calibration requires scarce technicians trained on legacy optical architectures.
- ISO 13485 Supplier Qualification Friction:Tier-two component vendors face extended audit cycles that bottleneck OEM production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ENT Endoscopy Market |
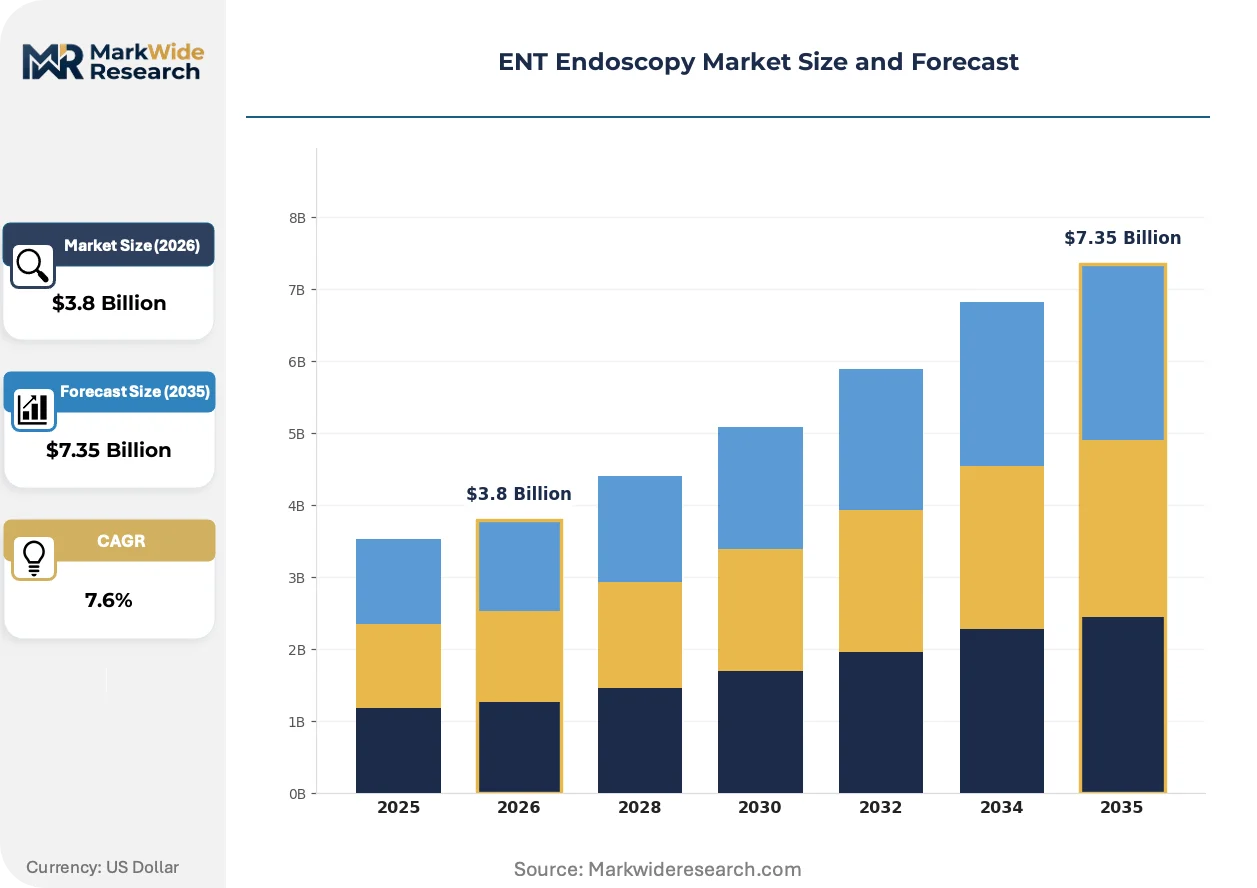
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Video Endoscopes, Accessories Technology: Optical Imaging, Digital Imaging, Fiber Optics, Laser Technology End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Research Institutions Application: Sinus Surgery, Otology, Laryngology, Vocal Cord Examination |
| Companies Covered | Fujifilm Holdings Corporation, Medtronic plc, Olympus Corporation, Richard Wolf GmbH, Hoya Corporation, Karl Storz SE & Co. KG, Stryker Corporation, Pentax Medical, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ENT Endoscopy Market Emerging Trajectories
Digital sensor miniaturization and disposable component architectures are rewriting cost structures across diagnostic and surgical ENT procedures. Three developments merit close tracking.
CMOS image sensor technology is miniaturizing. Chip-on-tip designs with sub-2.0 mm outer diameters enable transnasal approaches previously requiring rigid instrumentation. Tertiary academic medical centers in Germany and South Korea are piloting these platforms for pediatric airway examination. The shift is compressing the addressable market for traditional fiber-optic bundles while expanding procedural indications into neonatal populations.
EU Medical Device Regulation reprocessing claims now demand clinical evidence for reusable endoscope sterilization validation. Manufacturers must document bacterial load reduction across specified high-level disinfection protocols. German and French notified bodies are applying divergent interpretation standards, fragmenting certification timelines for pan-European product launches.
Hospital procurement departments are unbundling service contracts from capital equipment purchases. Standalone preventive maintenance agreements and per-procedure disposable subscriptions now compete with traditional bundled leases. This shift is most visible in United States health systems consolidating vendor relationships under centralized supply chain governance.
ENT Endoscopy Market Segmentation
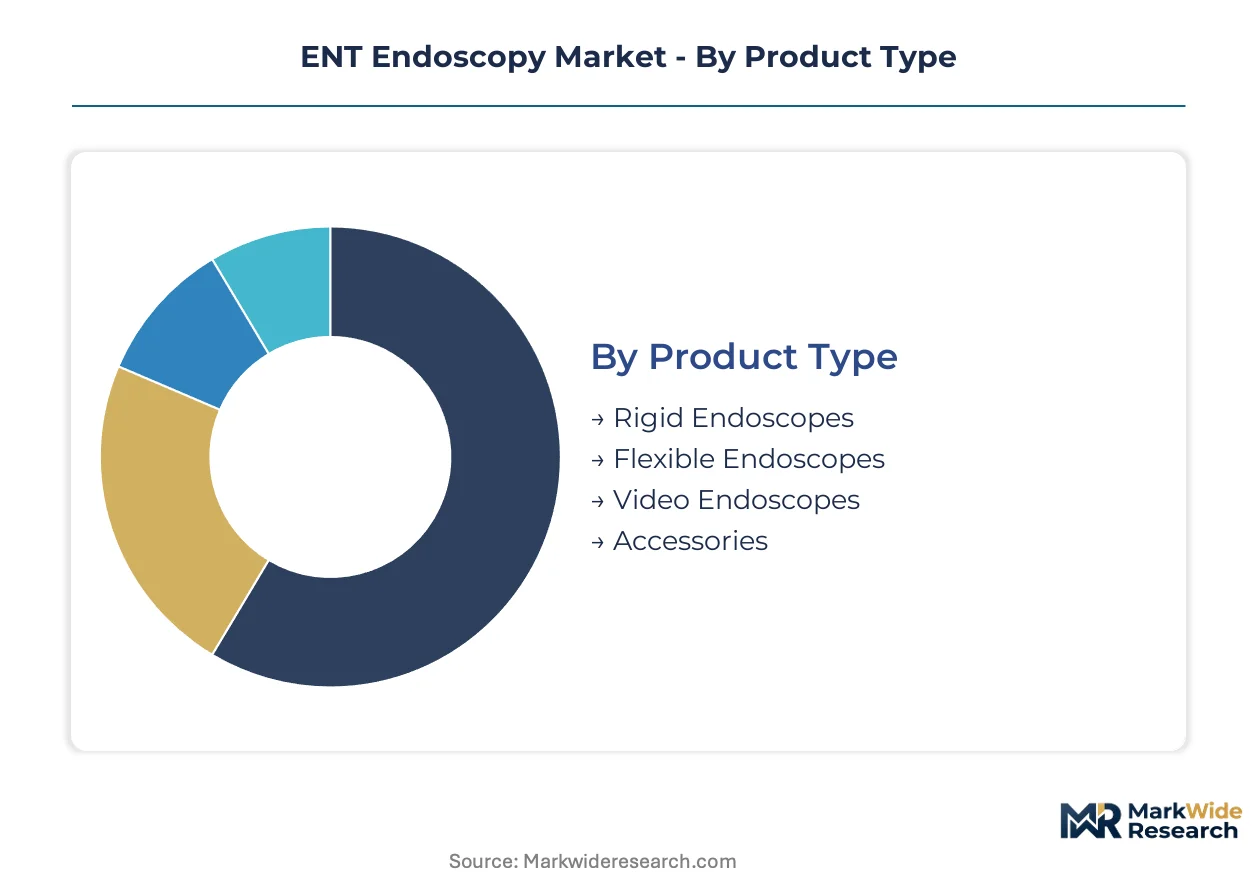
Segmentation in ENT endoscopy reveals how procurement authority, procedural setting, and imaging modality interact to determine vendor access and margin capture. Manufacturers must align product configurations with distinct channel economics across acute care, outpatient, and ambulatory environments.
Product Type:
Rigid endoscopes flow through hospital capital equipment committees with bundled service contracts, while flexible and video platforms increasingly route through outpatient clinic procurement with per-procedure disposable attachments.
- Rigid Endoscopes:Rod-lens optical systems with 2.7–4.0 mm diameters deliver superior image clarity for sinus surgery. German precision manufacturing clusters in Tuttlingen supply sapphire lenses and specialized glass grinding that constrain alternative sourcing. Demand concentrates in tertiary hospitals performing functional endoscopic sinus surgery where instrument stability outweighs flexibility requirements.
- Flexible Endoscopes:Fiber-optic bundles enable navigation through curved airway passages during laryngology procedures. Ambulatory surgical centers across the United States are building dedicated fleets for outpatient vocal cord examination. The conversion from fiber-optic to digital chip-on-tip designs is compressing replacement cycles and redistributing margin pools toward sensor-integrated platforms.
- Video Endoscopes:CMOS sensor integration captures expanding share as hospitals convert from fiber-optic visualization to digital imaging platforms with integrated light-emitting diode illumination.
- Accessories:Biopsy forceps, suction tubes, and irrigation channels generate recurring revenue streams through disposable or limited-reuse configurations tied to specific endoscope models.
Flexible endoscopes dominate installed base in outpatient settings. Video endoscopes represent where expansion concentrates as digital imaging platforms displace legacy fiber-optic infrastructure.
Technology:
Cost tier stratification separates premium digital imaging systems from standard fiber-optic platforms, with laser technology occupying a narrow specialty tier for surgical intervention.
- Optical Imaging:Traditional rod-lens and fiber-optic architectures rely on glass grinding expertise concentrated among German and Japanese component suppliers.
- Digital Imaging:CMOS and CCD sensor miniaturization enables chip-on-tip designs below 2.0 mm diameter for pediatric airway examination. Tertiary academic medical centers in Germany and South Korea pilot these platforms for neonatal populations previously excluded from endoscopic evaluation.
- Fiber Optics:Coherent fiber bundles transmit illumination and image data through flexible shafts, retaining cost advantage in high-volume screening applications where digital sensor economics remain prohibitive.
- Laser Technology:Integrated surgical lasers enable precise tissue ablation during laryngology procedures, commanding premium positioning in voice surgery centers with specialized reimbursement pathways.
Digital imaging claims the steepest expansion trajectory as FDA 510(k) pathways accelerate commercialization timelines. Fiber optics retains volume leadership in cost-sensitive screening environments.
End User:
Procurement authority varies sharply across settings, with hospitals consolidating vendor relationships under centralized supply chain governance while ambulatory surgical centers prioritize standalone preventive maintenance agreements.
- Hospitals:Integrated delivery networks negotiate bundled capital equipment and service contracts spanning multi-year replacement cycles. Biomedical engineering departments maintain in-house rod-lens repair capabilities that reduce per-procedure costs.
- Outpatient Clinics:Independent otolaryngology practices prioritize portable flexible endoscope systems for office-based laryngoscopy. Government hospital modernization programs in India create first-time demand for nasopharyngoscopy infrastructure.
- Ambulatory Surgical Centers:United States outpatient facilities building dedicated ENT service lines require rapid instrument turnover and validated low-temperature sterilization protocols compatible with high procedural volume.
- Research Institutions:Academic medical centers pilot AI-assisted pathology integration and high-definition digital capture platforms, generating clinical evidence for regulatory submissions and technology adoption.
Hospitals anchor capital equipment procurement volume. Ambulatory surgical centers represent where vendor expansion concentrates as outpatient migration accelerates.
Application:
Procedural complexity and reimbursement intensity vary across anatomical targets, with sinus surgery and laryngology commanding distinct instrument specifications and service requirements.
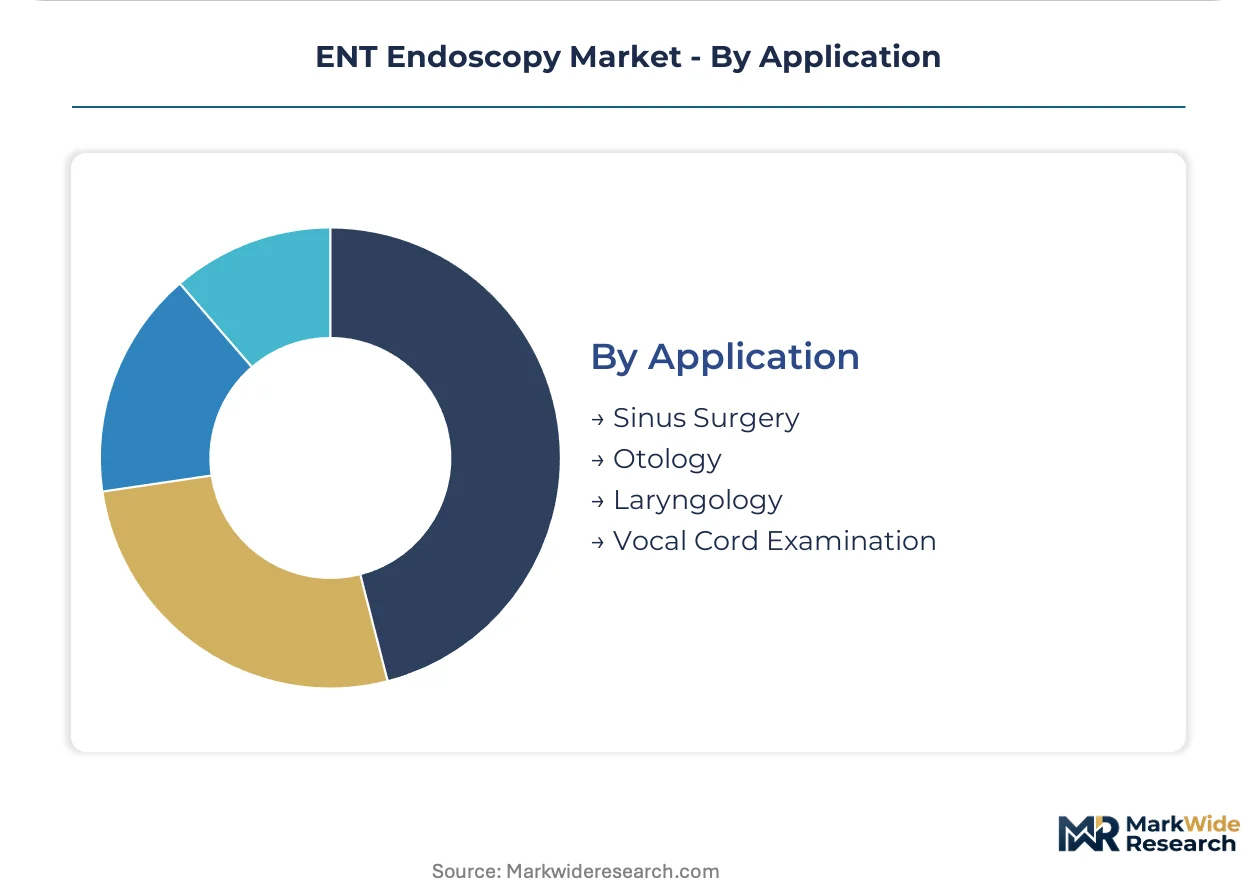
- Sinus Surgery:Functional endoscopic sinus surgery demands rigid instrumentation with superior optical clarity and instrument stability for precise tissue removal. Optical imaging retains durable demand in this application where fiber flexibility provides no navigational advantage.
- Otology:Middle ear examination and surgical intervention require specialized rigid endoscopes with angled optics for visualization around ossicular structures. Pediatric applications drive demand for reduced-diameter instrumentation.
- Laryngology:Flexible endoscope navigation through the oropharynx and hypopharynx enables vocal fold examination without general anesthesia. Office-based procedures concentrate demand in outpatient clinic channels.
- Vocal Cord Examination:Stroboscopic laryngoscopy and high-speed digital capture enable precise mucosal wave assessment. AI-assisted lesion detection algorithms are piloting in tertiary hospitals to enable real-time pathology flagging.
Sinus surgery anchors rigid endoscope demand. Vocal cord examination represents where digital imaging and AI integration concentrate as premium positioning strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in ENT endoscopy equipment reveal concentrated manufacturing bases supplying dispersed demand centers. German and Japanese optical component exports feed assembly operations across multiple continents while finished instrument trade flows toward hospital procurement networks in North America and Asia-Pacific.
United States
Ambulatory surgical centers in Texas and Florida are building dedicated ENT service lines requiring flexible endoscope fleets. FDA 510(k) premarket notification pathways accelerate commercialization timelines for digital imaging platforms entering the US market. The Minneapolis medical device corridor hosts repair and refurbishment operations serving hospital biomedical engineering departments.
Germany
Tuttlingen anchors precision manufacturing clusters supplying sapphire lenses and specialized glass grinding for rod-lens optical systems. EU Medical Device Regulation imposes stricter clinical evidence standards on reusable endoscope reprocessing claims. Berlin academic medical centers pilot AI-assisted pathology integration with high-definition digital capture platforms.
Japan
Coherent fiber bundle production concentrates in Nagoya and Osaka industrial zones serving Asian and European OEM channels. METI industrial policy supports medical device export competitiveness through standardization alignment. Tokyo tertiary hospitals drive demand for sub-2.0 mm chip-on-tip designs in pediatric airway examination.
India
Government hospital modernization programs in Maharashtra and Karnataka create first-time demand for flexible nasopharyngoscopy infrastructure. CDSCO regulatory pathways for imported medical devices shape procurement timelines for private clinic chains. Delhi-NCR and Chennai emerge as distribution hubs for outpatient ENT service expansion.
South Korea
Seoul academic medical centers pilot CMOS sensor miniaturization for neonatal endoscopic applications previously excluded from evaluation. MFDS approval frameworks for digital imaging platforms align with FDA 510(k) documentation standards. Busan-Ulsan manufacturing zones supply LED illumination components to regional OEM assembly operations.
ENT Endoscopy Market Vendor Landscape
Concentration sits with integrated optical manufacturers possessing captive lens grinding and sensor sourcing capabilities. The vendor base stratifies across three tiers: German precision houses with in-house rod-lens production, Asian conglomerates leveraging fiber-optic scale, and mid-cap specialists focused on disposable component architectures. Dominant competitive moves include backward integration into sapphire lens supply and geographic expansion of direct-sales infrastructure into ambulatory settings.
Among German precision manufacturers, Karl Storz SE & Co. KG and Richard Wolf GmbH exemplify integrated optical production archetypes with Tuttlingen-based manufacturing. Olympus Corporation occupies a position bridging Asian volume production with European channel presence. Medtronic plc represents the hospital infrastructure extension model, converting acute care direct-sales relationships into ambulatory surgical center penetration.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Medtronic plc |
| Olympus Corporation |
| Richard Wolf GmbH |
| Hoya Corporation |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| Pentax Medical |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German sapphire lens grinding facilities shapes both supply concentration and price floors for rod-lens optical systems. Scale economies in Tuttlingen manufacturing clusters compress per-unit costs for integrated producers while assembly-dependent competitors face margin compression from component sourcing premiums.
Pricing Analysis
Hospital capital equipment committees anchor three-tier pricing structure across premium, standard, and economy levels in ENT endoscopy procurement. Price differentiation rests on FDA 510(k) clearance tier and bundled service contract scope, with premium digital imaging platforms commanding substantial markups over fiber-optic alternatives. Cost compression in standard-tier flexible endoscopes is intensifying because ambulatory surgical centers prioritize per-procedure disposable economics over capital ownership. Outpatient clinic buyers exhibit highest price sensitivity, while tertiary academic medical centers demonstrate lowest sensitivity due to grant-funded research procurement.
Supply Chain Analysis
Rod-lens sapphire fabrication in Tuttlingen underwrites optical clarity benchmarks for sinus surgery instrumentation. German, Japanese, and South Korean suppliers concentrate coherent fiber bundle and CMOS sensor production, with raw material dependencies spanning rare-earth phosphors for LED illumination, high-purity optical glass, and semiconductor-grade silicon wafers. Single-source vulnerability in specialized glass grinding equipment creates structural risk for OEMs lacking captive lens production. Distribution runs through hospital procurement networks and GPO contracts in North America, with direct-sales infrastructure dominating European channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ENT endoscopy is exiting a replacement-cycle trough as hospitals accelerate fiber-optic-to-digital platform conversion. Equipment refresh timing aligns with FDA 510(k) pathway maturation for chip-on-tip designs.
For Market Incumbents: Shield installed base relationships by embedding AI-assisted pathology software into video processor platforms, creating switching costs against emerging sensor-integrated competitors. Deepen backward integration into sapphire lens supply through Tuttlingen facility expansion or exclusive grinding equipment partnerships, denying component access to assembly-dependent challengers facing ISO 13485 supplier qualification friction.
For New Entrants and Emerging Players: FDA 510(k) pre-submission pathways for pediatric-diameter chip-on-tip designs enable fast-track positioning in neonatal airway examination, a segment underserved by legacy fiber-optic bundles. Target Indian outpatient clinic chains building first-time nasopharyngoscopy infrastructure through portable flexible endoscope systems with standalone preventive maintenance agreements, bypassing hospital capital committee procurement cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated optical manufacturers with captive sensor sourcing and validated EU MDR reprocessing protocols. Long-term viability hinges on sustainability disclosure readiness under EU Green Deal mandates and repairable instrument design capabilities. Watch CDSCO regulatory pathway streamlining for imported devices as inflection indicator for Indian market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Digital Imaging Submission | FDA 510(k) clearance accelerates US commercialization timelines for CMOS-integrated platforms against fiber-optic incumbents. |
| EU MDR Reprocessing Validation Investment | Clinical evidence for sterilization protocols secures pan-European market access amid divergent notified body interpretations. |
| Hospital System Partnership Expansion | Direct-sales infrastructure conversion into ambulatory surgical centers captures outpatient migration volume in Texas and Florida. |
| AI-Assisted Pathology Software Development | Real-time lesion detection algorithms enable premium positioning in tertiary academic medical centers piloting digital platforms. |
| Indian Distribution Hub Establishment | Delhi-NCR and Chennai logistics nodes reduce procurement timelines for government hospital modernization programs. |
Methodological Framework
Operator-level perspectives from otolaryngology department heads, hospital biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators anchored the qualitative base for this analysis. Primary interview findings triangulated against FDA 510(k) filing databases, EU MDR notified body guidance documents, hospital procurement contract records, and German optical component trade statistics. Bottom-up demand modeling across product type, technology, end user, application, and regional regulatory clusters converged with top-down market sizing validation.
Sensitivity analysis tested forecast outputs against alternative scenarios for digital imaging conversion velocity and EU MDR certification timeline divergence. Segmentation dimensions modeled encompassed rigid versus flexible versus video endoscope platforms, optical versus digital versus fiber-optic versus laser technology tiers, hospital versus outpatient clinic versus ambulatory surgical center procurement channels, and sinus surgery versus laryngology versus otology procedural applications. CAGRs derived from equipment replacement cycle analysis and installed base conversion assumptions, with procedure volume elasticity to reimbursement rate changes incorporated as demand-side input.
Decision-makers should treat outputs as directional under assumptions of continued FDA 510(k) pathway stability and EU MDR reprocessing claim interpretation convergence; material deviation in either regulatory trajectory would warrant model refresh. Practitioners should keep alternative scenarios live as disposable endoscope cost economics and sustainability mandate stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Endoscopic Stricture Management Market
Endoscopy
UAE Endoscopy Devices Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Europe Sinus Tissue Resection Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Colonic Stents Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Endoscopic Mucosal Resection Market
Endoscopy
Robot-Assisted Endoscope Market