
 North America Disposable Endoscopes Market | 2026-2036
North America Disposable Endoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Disposable Endoscopes Market Intelligence
Ambulatory surgery centers is realigning the North America disposable endoscopes landscape as outpatient procedural volumes climb and infection control protocols tighten. Ambu A/S leverages its single-use visualization platform to dominate the bronchoscopy segment across freestanding surgical facilities. Boston Scientific Corporation anchors its position through extensive channel relationships with integrated delivery networks.
Disposable endoscopes are single-use, sterile visualization instruments manufactured from medical-grade polymers with integrated optical or video imaging channels, designed to eliminate cross-contamination risks between patients during diagnostic or interventional procedures. Bronchoscopes lead product-type demand due to their high utilization in intensive care and emergency settings where reprocessing turnaround constrains workflow. Gastroscopes and colonoscopes within the application segment for screening procedures represent the fastest-growing margin pool as payers expand coverage for colorectal cancer prevention programs.
FDA reprocessing guidelines and Joint Commission infection control standards shape product design requirements and hospital purchasing criteria across the United States. Health Canada and the Canadian Standards Association maintain parallel oversight for single-use device approvals in the Canadian market. Stakeholders must monitor how CMS reimbursement adjustments for outpatient endoscopic procedures influence capital allocation between disposable and reusable platforms.
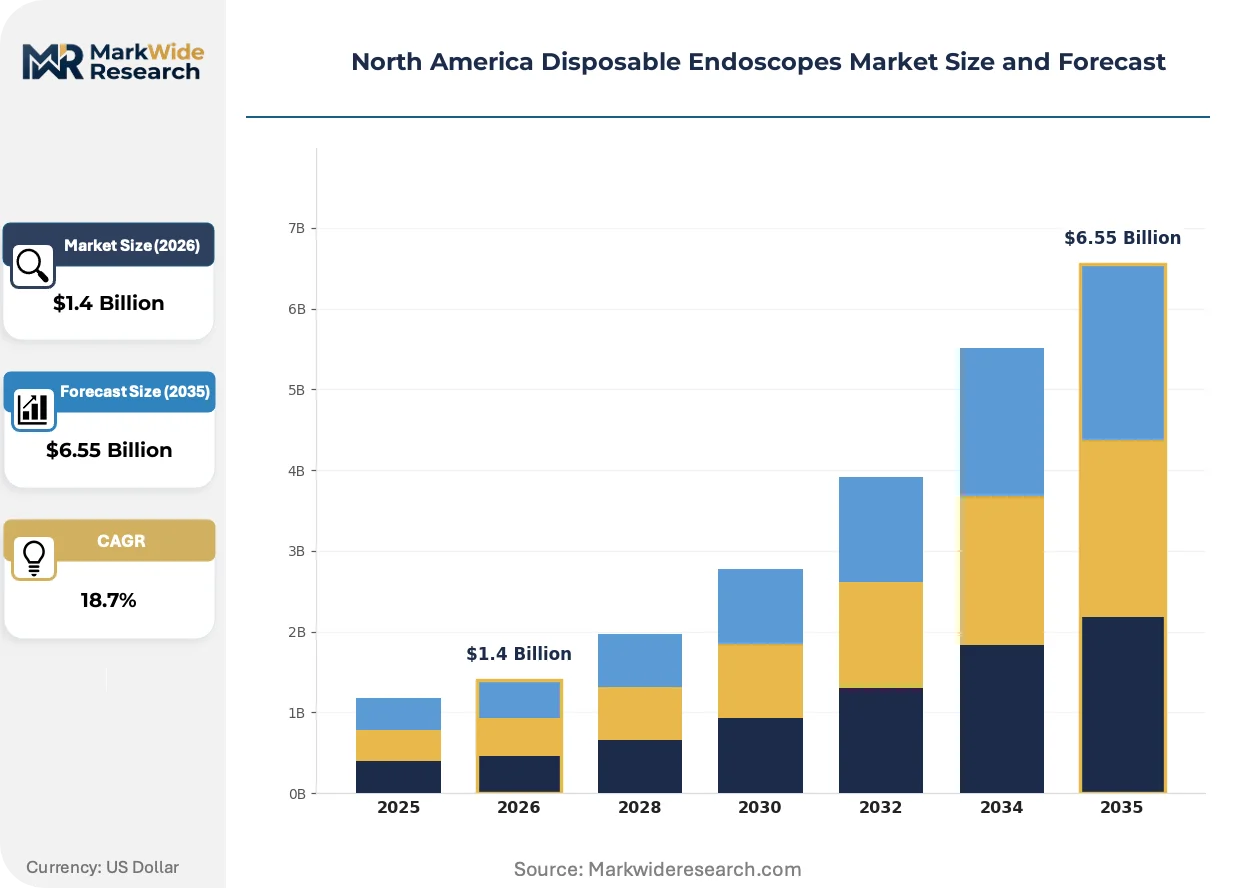
Market Dynamics
FDA enforcement of enhanced reprocessing standards for duodenoscopes is forcing hospitals toward single-use alternatives, while ambulatory surgery centers expand procurement of disposable bronchoscopes and gastroscopes to eliminate cross-contamination risks.
Growth Catalysts
- Joint Commission infection control standards:These protocols mandate rigorous sterilization documentation that disposable endoscopes bypass entirely, accelerating hospital conversion in the United States.
- Intensive care utilization:Bronchoscopes face high demand in emergency settings where reprocessing turnaround constrains workflow, making single-use variants operationally essential.
- Texas, California, and Florida:These three states account for the bulk of regional volume as large health systems consolidate purchasing power around infection prevention.
Market Restraints
- Medical-grade polymer supply concentration:Specialized optical polymers for single-use endoscope manufacturing concentrate among limited chemical suppliers, creating input vulnerability.
- Reusable duodenoscope installed base:Hospitals retain substantial capital investment in reprocessable systems, slowing full-platform replacement cycles despite regulatory pressure.
- Waste disposal compliance:Single-use devices generate regulated medical waste streams that impose ongoing operational costs and EPA oversight obligations.
Strategic Opportunities
- Canadian market expansion:Health Canada and the Canadian Standards Association maintain parallel oversight frameworks where single-use device penetration remains below United States levels.
- Colorectal cancer screening programs:Payer coverage expansion for preventive gastroscopy and colonoscopy creates volume tailwinds for disposable screening platforms.
- Integrated delivery networks:Centralized procurement within IDNs enables bulk contracting for single-use platforms across multi-site hospital systems.
Industry Challenges
- ISO 13485 certification timelines:New disposable endoscope manufacturers face extended quality management system audits that delay market entry.
- Legacy reprocessing infrastructure:Hospital capital allocation committees must reconcile sunk costs in sterilization departments against disposable conversion benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Disposable Endoscopes Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchoscopes, Gastroscopes, Duodenoscopes, Colonoscopes End User: Hospitals, Ambulatory Surgery Centers, Clinics, Specialty Practices Technology: Optical Imaging, Video Processing, Wireless Transmission, Fiber Optics Application: Diagnostic Procedures, Surgical Procedures, Therapeutic Procedures, Screening |
| Companies Covered | Olympus Corporation, Boston Scientific Corporation, Ambu A/S, PENTAX Medical, FUJIFILM Holdings Corporation, Karl Storz SE & Co. KG, Stryker, Medtronic, STERIS plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Disposable Endoscopes Market Strategic Shifts & Innovations
Disposable endoscope technology is converging with advanced imaging and connectivity platforms, reshaping how sterile visualization instruments integrate into procedural workflows across North American healthcare facilities.
Chip-on-tip digital imaging is automating the transition from fiber-optic bundles to CMOS sensors embedded at the distal end of single-use bronchoscopes and gastroscopes. Ambulatory surgery centers are adopting these platforms at accelerated pace to eliminate reprocessing bottlenecks. The technology is automating quality standardization by removing variability inherent in manual sterilization protocols.
FDA enhanced reprocessing guidance for duodenoscopes imposes validation requirements that reusable device manufacturers struggle to satisfy consistently. The industrial consequence is a structural migration of hospital purchasing committees toward single-use alternatives that sidestep reprocessing liability entirely. Gastroenterology departments within United States academic medical centers are responding fastest, embedding disposable platforms into ERCP and EUS procedural suites.
Consignment inventory models are displacing capital purchase arrangements for high-volume disposable endoscope categories. Distributors are establishing direct-to-facility replenishment systems that bypass traditional GPO contracting layers for urgent procedural needs. This behavioral shift is most visible in Texas and Florida freestanding surgical facilities where case volume unpredictability favors flexible supply arrangements.
North America Disposable Endoscopes Market Segmentation
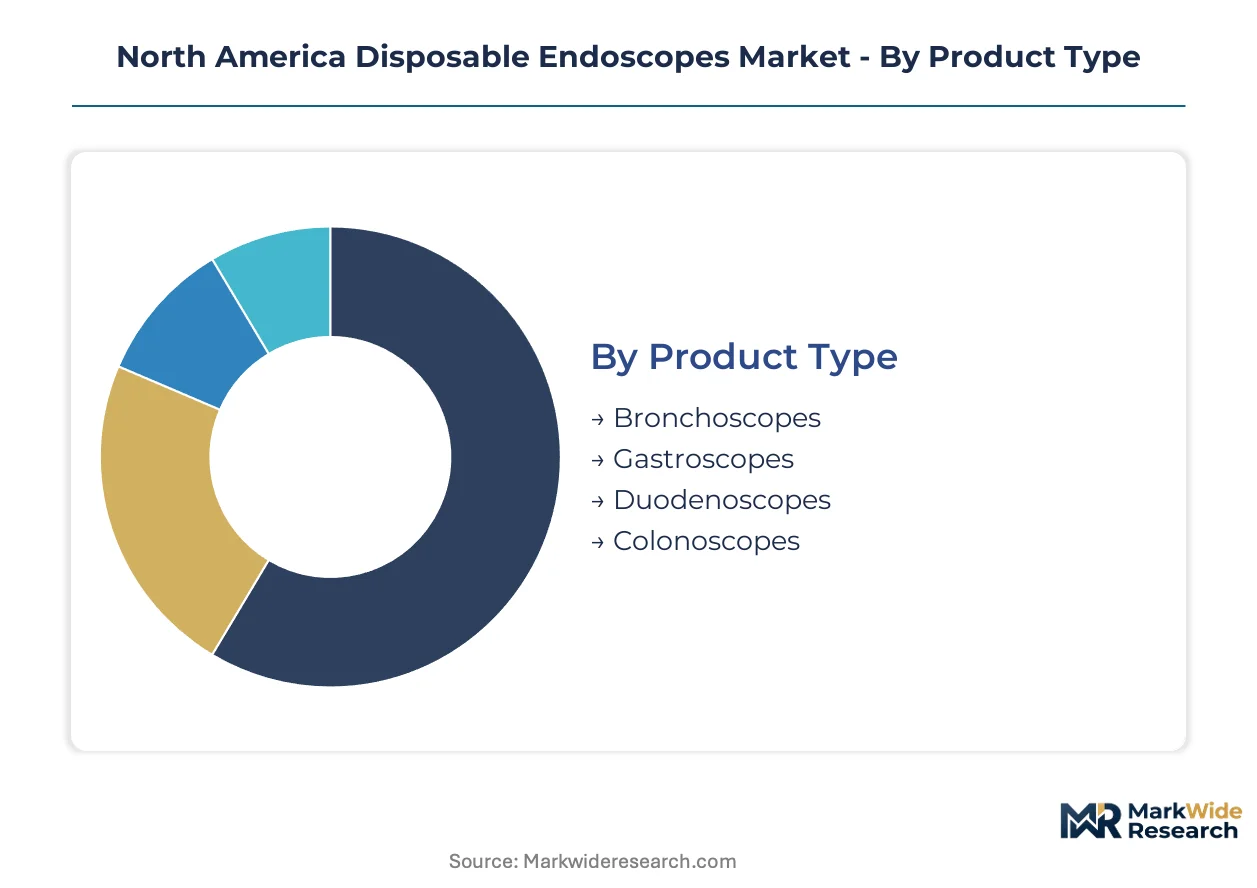
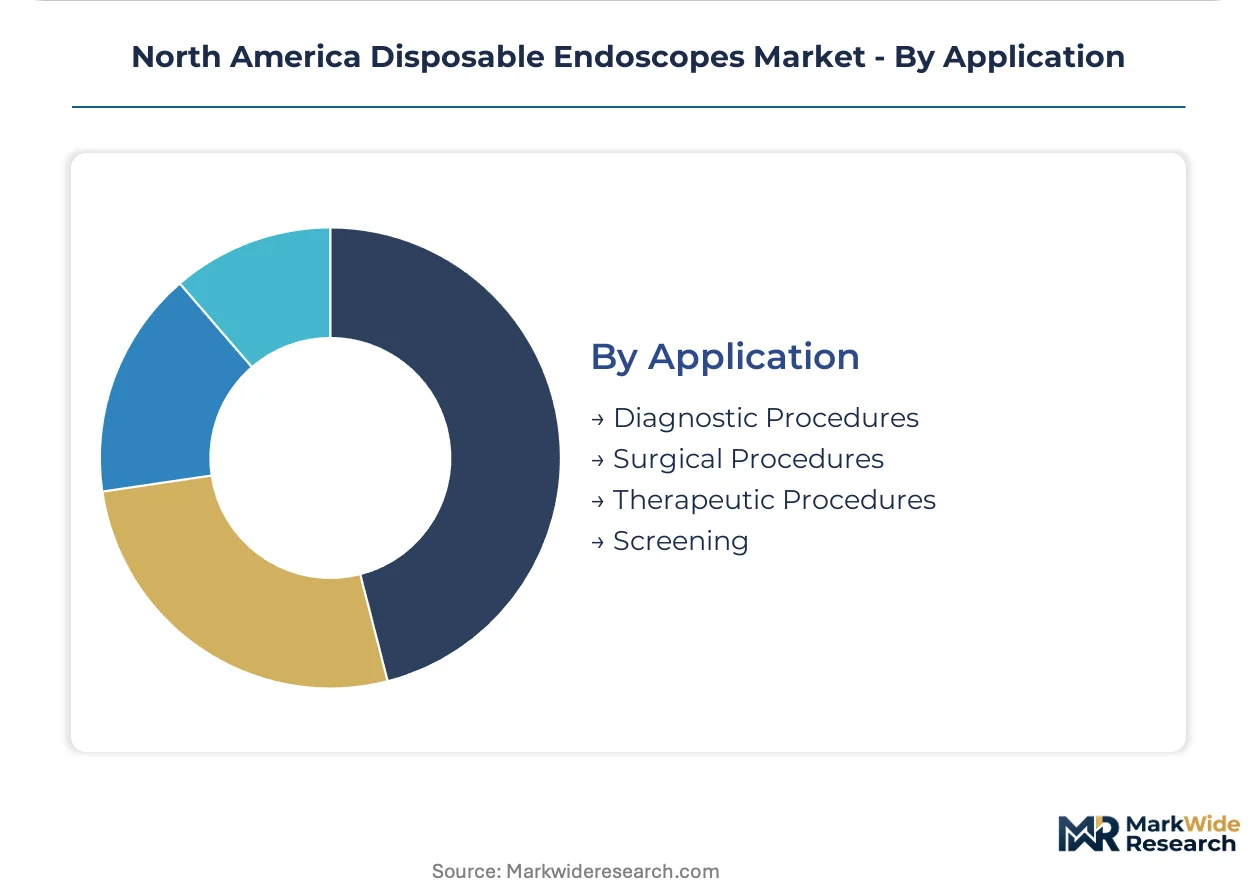
Segmentation in the North America disposable endoscopes market reveals distinct procurement patterns across clinical settings and technological platforms. Product type and end-user dimensions drive purchasing committee decisions, while application and technology segments determine margin structures and regulatory pathways.
Product Type:
Standardization dominates bronchoscope and gastroscope specifications, whereas duodenoscope designs retain customization for ERCP complexity.
- Bronchoscopes:Single-use bronchoscopes integrate CMOS sensors at the distal tip with working channels for suction and biopsy. Intensive care units in Texas and California health systems drive procurement volumes where reprocessing turnaround threatens emergency airway management workflows.
- Gastroscopes:These instruments feature flexible insertion tubes with integrated light sources and irrigation channels for upper GI examination. Ambulatory surgery centers across Florida are converting capital budgets to per-procedure gastroscope purchasing as payer coverage for diagnostic esophagogastroduodenoscopy expands.
- Duodenoscopes:Specialized side-viewing designs for ERCP retain higher complexity and per-unit cost due to elevator mechanism integration.
- Colonoscopes:Longer insertion lengths with enhanced maneuverability support colorectal cancer screening programs gaining CMS reimbursement traction.
Leading the category by volume: Bronchoscopes. Growing fastest: Gastroscopes.
End User:
Cost tier stratification separates capital-rich hospital systems from volume-lean ambulatory facilities with constrained sterilization infrastructure.
- Hospitals:Academic medical centers and integrated delivery networks command bulk purchasing leverage for multi-site standardization. FDA duodenoscope reprocessing enforcement is accelerating conversion within gastroenterology departments at United States tertiary facilities.
- Ambulatory Surgery Centers:Freestanding surgical facilities prioritize single-use platforms to eliminate reprocessing capital expenditure and Joint Commission documentation burdens. California and Texas ASCs are expanding disposable bronchoscope consignment arrangements.
- Clinics:Outpatient diagnostic centers favor lower-complexity gastroscope models for routine upper endoscopy with rapid patient turnover.
- Specialty Practices:Pulmonology and GI specialty groups concentrate demand for procedure-specific disposable platforms with dedicated distributor relationships.
Highest procurement concentration: Hospitals. Expanding most quickly: Ambulatory Surgery Centers.
Technology:
Application maturity separates legacy fiber-optic platforms from digital imaging systems displacing them across procedural workflows.
- Optical Imaging:Chip-on-tip CMOS sensor arrays deliver high-definition visualization without fragile fiber bundles. United States bronchoscopy suites are standardizing on optical imaging for bedside emergency procedures where equipment durability concerns dominate.
- Video Processing:Integrated image signal processors enable real-time enhancement and documentation compatibility with electronic health record systems.
- Wireless Transmission:Bluetooth and proprietary low-latency protocols eliminate tethered connections to processor towers, enabling mobile deployment.
- Fiber Optics:Legacy illumination and image transmission via glass fiber bundles persists in cost-sensitive clinic environments.
Dominant installed base: Optical Imaging. Steepest expansion trajectory: Wireless Transmission.
Application:
Margin concentration varies across procedure reimbursement codes, with screening applications capturing payer prevention program allocations.
- Diagnostic Procedures:Tissue sampling and visual examination for unexplained symptoms constitute high-frequency utilization. United States hospitals deploy disposable platforms for diagnostic bronchoscopy in immunocompromised patient populations where cross-contamination risks carry severe clinical consequences.
- Surgical Procedures:Interventional applications including stent placement and stone retrieval demand specialized channel configurations and instrument compatibility.
- Therapeutic Procedures:Dilation, ablation, and foreign body removal procedures require robust construction for instrument passage.
- Screening:Asymptomatic colorectal cancer prevention programs reimbursed by CMS are converting to disposable colonoscopy platforms in Florida and California health systems.
Highest procedure volume: Diagnostic Procedures. Gaining share fastest: Screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device free-trade zones in the United States and Canada concentrate disposable endoscope manufacturing and distribution infrastructure. These zones accelerate FDA and Health Canada clearance pathways while reducing tariff exposure on imported optical polymers. Texas, California, and Florida anchor procurement volumes through large integrated delivery networks.
United States
Texas health systems deploy single-use bronchoscopes across intensive care networks where emergency airway management demands immediate instrument availability. FDA enhanced reprocessing standards for duodenoscopes accelerate hospital conversion toward disposable alternatives in academic medical centers. The Dallas-Fort Worth metroplex hosts major distribution hubs serving ambulatory surgery centers throughout the Southwest.
Canada
Ontario hospitals adopt disposable gastroscope platforms as Health Canada streamlines single-use device approval pathways under Medical Device Licensing requirements. The Canadian Standards Association maintains parallel infection control standards that validate sterile manufacturing protocols. Toronto-based procurement consortia negotiate bulk contracts for multi-site health system standardization across the province.
Mexico
Baja California medical device maquiladoras assemble disposable endoscope components for re-export to United States distribution channels. COFEPRIS regulatory alignment with FDA quality system requirements enables integrated North American supply chains. Tijuana manufacturing clusters specialize in polymer molding for single-use instrument housings serving California health systems.
North America Disposable Endoscopes Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated device companies commanding hospital procurement committees and component fabricators supplying private-label distributors. The United States market concentrates around three to five dominant platform providers with established FDA 510(k) portfolios and Joint Commission reference accounts. Strategic archetypes include full-stack visualization platform developers, single-use instrument pure-plays, and diversified medtech conglomerates with endoscopy divisions. Competitive moves center on distributor exclusivity arrangements with integrated delivery networks and vertical integration into polymer compounding to secure optical-grade resin supply.
Within the visualization platform tier, Olympus Corporation and Boston Scientific Corporation anchor procurement relationships with United States academic medical centers. Ambu A/S exemplifies the single-use pure-play archetype through concentrated investment in sterile manufacturing scale. Karl Storz SE & Co. KG represents European-origin precision engineering applied to disposable instrument channels.
| Leading Market Players |
|---|
| Olympus Corporation |
| Boston Scientific Corporation |
| Ambu A/S |
| PENTAX Medical |
| FUJIFILM Holdings Corporation |
| Karl Storz SE & Co. KG |
| Stryker |
| Medtronic |
| STERIS plc |
| Others |
Cost & Logistics Intelligence
FDA enhanced reprocessing enforcement is compelling United States hospital purchasing committees toward single-use duodenoscopes regardless of per-unit cost premiums, forcing supply chains to prioritize sterile manufacturing scale over commodity polymer sourcing and compressing margins on standard bronchoscope categories.
Pricing Analysis
Short lead-time premiums dominate disposable endoscope contracting as ambulatory surgery centers in Texas and Florida pay surcharges for consignment inventory models that bypass traditional GPO procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated duodenoscopes from standard bronchoscopes and basic clinic-grade gastroscopes. Price differentiation rests on ISO 13485 certification tier and optical imaging resolution grade. Margins are tightening due to medical-grade polymer feedstock concentration among limited chemical suppliers. Ambulatory surgery centers exhibit highest price sensitivity; academic medical centers prioritize infection control compliance over unit economics.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Toronto anchor hub-and-spoke replenishment networks serving United States and Canadian health systems with direct-to-facility delivery. Manufacturing concentrates in Mexico's Baja California maquiladoras, United States medical device free-trade zones, and German precision component clusters. Raw material dependencies include optical-grade polycarbonate resins, CMOS sensor arrays, and sterile packaging films. Single-source vulnerability in specialized polymer compounding creates input bottleneck risk. Distribution runs through integrated delivery network consignment arrangements and distributor direct partnerships bypassing traditional GPO layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade polymer supply concentration functions as the binding capacity constraint propping pricing power for sterile manufacturers with captive resin relationships.
For Market Incumbents: Anchor market position through backward integration into optical polymer compounding and exclusive distributor arrangements with Texas and California integrated delivery networks. FDA enforcement timelines threaten reusable duodenoscope incumbents; sterile manufacturing scale serves as the priority defensive lever. Channel control through consignment inventory models locks out emerging competitors from high-volume ambulatory surgery center accounts. For New Entrants and Emerging Players: Health Canada streamlined Medical Device Licensing in Ontario opens a window for single-use gastroscope penetration in underpenetrated Canadian health systems. Target freestanding pulmonology clinics in Florida with wireless transmission-enabled bronchoscope platforms that eliminate capital expenditure barriers. Reimbursement strategy alignment with CMS colorectal cancer screening expansion serves as the most penetrable go-to-market angle for disposable colonoscopy entrants. For Investors and Strategic Acquirers: The window for entry favors sterile manufacturing pure-plays with established FDA 510(k) portfolios and Health Canada parallel approvals. Long-term viability centers on acquisition of single-use instrument specialists with integrated CMOS sensor supply relationships rather than diversified reusable endoscopy divisions. Watch Health Canada approval velocity versus FDA clearance timelines as the inflection signal for North American market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Expedited clearance pathways capture hospital conversion demand from reusable duodenoscope replacements. |
| Health Canada Parallel Approval | Dual-jurisdiction positioning unlocks Ontario and Quebec health system procurement contracts. |
| Integrated Delivery Network Partnership | Multi-site standardization agreements secure volume commitments across Texas and California systems. |
| Consignment Inventory Model Deployment | Direct replenishment systems bypass GPO layers for ambulatory surgery center urgent procurement. |
| CMOS Sensor Platform Integration | Chip-on-tip technology differentiation commands premium positioning in emergency bronchoscopy settings. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and sterile manufacturing operations leads with bottom-up and top-down triangulation. Secondary sources included FDA 510(k) clearance databases, Health Canada Medical Device Licensing records, CMS reimbursement code filings, and hospital procurement database extracts. Primary fieldwork validated polymer supply concentration assumptions and distributor channel structure.
Granularity-level modeling proceeded at product-type, end-user, and technology-tier dimensions across the analysis window, with separate trajectory builds for bronchoscope, gastroscope, duodenoscope, and colonoscope categories. CAGRs derived from procedure volume elasticity to reimbursement expansion, infection control protocol adoption curves, and sterile manufacturing capacity buildout timelines. Forecast inputs incorporated Joint Commission audit frequency trends and EPA medical waste disposal compliance cost projections.
The model assumes a particular technology adoption path; alternative pathways for wireless transmission protocols would alter the outlook if latency standards shift. Forecasts reflect documented assumptions regarding FDA enforcement consistency and Health Canada approval velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Robot-Assisted Endoscope Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Chip-On-The-Tip Endoscopes Market
Endoscopy
Endoscopy Video Systems Market
Endoscopy
Global Endoscopic Ultrasound Needles Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Hysteroscopy Procedures Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Endoscopy Equipment Market
Endoscopy
Endoscope Optics Objective Lenses Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Global Colonoscopes Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Endoscopic Mucosal Resection Market