
 Endoscope Detergents and Disinfectants Market | 2026-2036
Endoscope Detergents and Disinfectants Market Size, Share, and Industry Trends Forecast 2026-2036
Endoscope Detergents and Disinfectants Market Foresight
Germany's manufacturing base for enzymatic cleaners is reshaping supply dynamics across Europe. Ecolab leverages its healthcare hygiene infrastructure to sustain dominance in hospital-grade formulations. STERIS anchors its position through integrated reprocessing systems paired with proprietary chemistries. Cantel Medical competes via specialized high-level disinfectant portfolios tailored to flexible endoscope channels.
Endoscope detergents and disinfectants comprise enzymatic and chemical formulations engineered to remove bioburden and achieve sporicidal kill on heat-sensitive medical devices, typically requiring neutral pH ranges of 6.5–7.5 to preserve delicate instrument optics and elastomer components. Their primary purpose centers on breaking down proteinaceous soils and eliminating microbial contamination between patient procedures. Enzymatic cleaners command the largest volume share due to mandatory pre-cleaning steps in reprocessing protocols, while liquid solutions generate premium pricing as ready-to-use formats reduce dilution error risk in clinical settings. Surface disinfectants represent the fastest-expanding category as ambulatory surgical centers adopt point-of-use wipe protocols.
FDA reprocessing guidance, the EU Medical Device Regulation, and Germany's Robert Koch Institute hygiene requirements collectively mandate validated cleaning efficacy data before market authorization. These frameworks elevate barriers for novel chemistries while accelerating replacement cycles for legacy formulations that fail updated biocompatibility thresholds. Stakeholders must monitor evolving sporicidal claim standards and automated reprocessor compatibility certifications as the decisive filters for product viability.
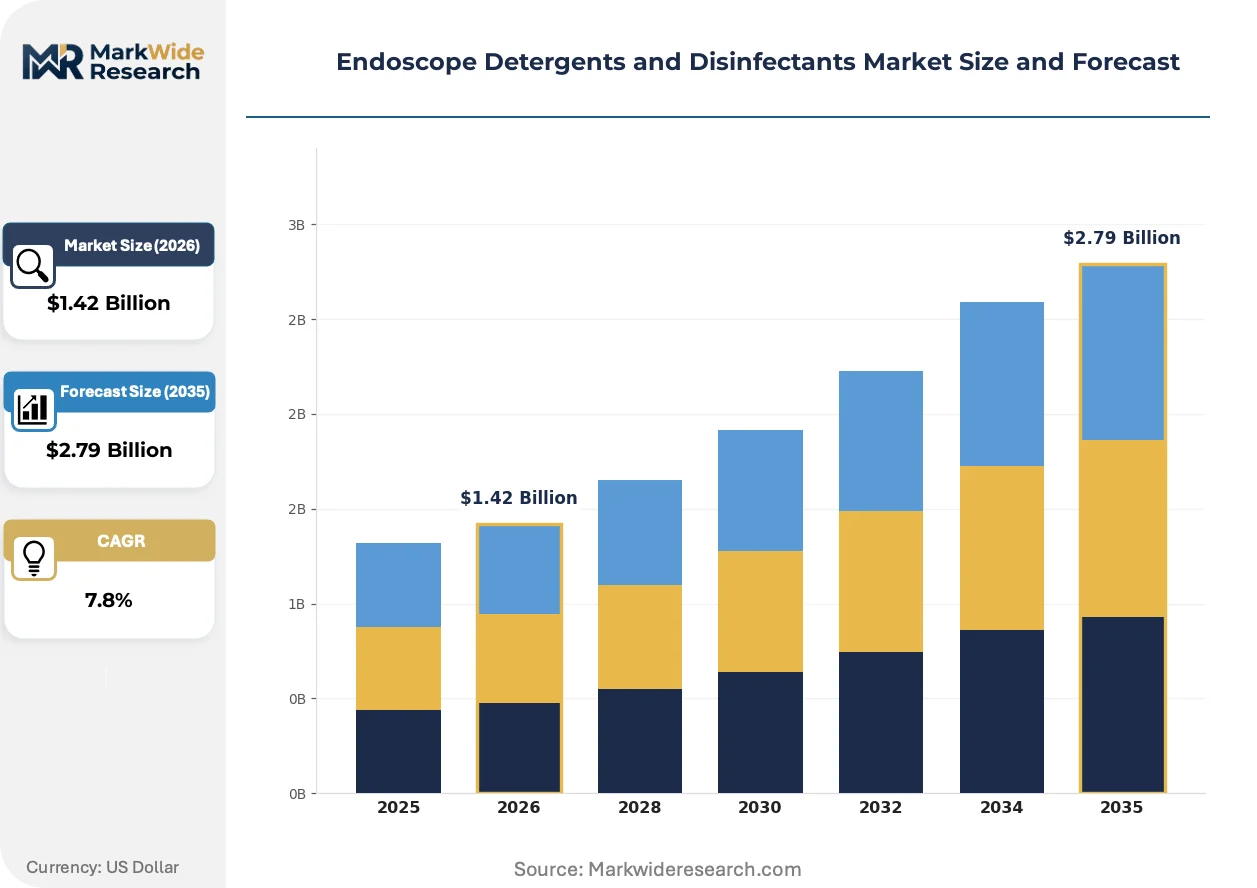
Market Dynamics
FDA's updated reprocessing validation guidance is compressing replacement cycles for legacy chemistries while automated reprocessor fleet expansions in US hospitals concentrate demand for higher-efficacy formulations. This regulatory pressure is the dominant structural force reshaping competitive positioning across enzymatic and chemical disinfectant categories.
Growth Catalysts
- Automated Reprocessor Compatibility Mandates:US hospitals expanding AER fleets require chemistries validated for specific machine chemistries, locking in recurring revenue streams for compatible detergent suppliers.
- Germany's Outpatient Volume Surge:The Robert Koch Institute's intensified hygiene enforcement in ambulatory endoscopy centers is accelerating standardization of high-level disinfectant protocols across federal states.
- EU MDR Biocompatibility Thresholds:Updated medical device regulation requirements for cleaning efficacy data are disqualifying legacy formulations and creating authorization barriers for new market entrants.
Market Restraints
- Quaternary Ammonium Input Volatility:Petrochemical feedstock price swings for surfactant precursors compress margin stability for liquid disinfectant manufacturers.
- German Manufacturing Concentration:Enzymatic cleaner production clusters in Baden-Württemberg and Bavaria create geographic supply vulnerability for European distribution networks.
- Sporicidal Claim Validation Costs:EPA and FDA dual-registration requirements for emerging chemistries extend commercialization timelines and elevate R&D expenditure floors.
Strategic Opportunities
- Point-of-Use Wipe Formats:Ambulatory surgical centers in Texas and Florida are adopting pre-saturated surface disinfectant protocols that bypass traditional sink-based reprocessing workflows.
- Neutral pH Enzyme Stabilization:Convergence of protease engineering and buffer chemistry is enabling shelf-stable concentrated formulations that reduce shipping costs for remote hospital systems.
- US IRA Hospital Infrastructure Funding:Federal capital injection into infection control infrastructure is subsidizing automated reprocessor acquisitions that bundle proprietary chemistries.
Industry Challenges
- Reprocessing Technician Certification Gaps:Shortage of SPD professionals credentialed in FDA-validated cleaning protocols creates compliance execution risk in high-throughput endoscopy units.
- Legacy AER Integration Friction:New high-efficacy chemistries require retrofit compatibility testing against installed base of older washer-disinfector models, slowing adoption cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoscope Detergents and Disinfectants Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymatic Cleaners, Chemical Agents, Sterilants, Surface Disinfectants Application: Medical Facilities, Dental Clinics, Laboratories, Veterinary Clinics End User: Hospitals, Outpatient Clinics, Research Institutions, Rehabilitation Centers Formulation Type: Liquid Solutions, Wipes, Concentrates, Powdered Form |
| Companies Covered | Borer Chemie, Ecolab, STERIS, Advanced Sterilization Products, MEDIVATORS Inc., Cantel Medical, Olympus Corporation, Metrex, Getinge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoscope Detergents and Disinfectants Market Shifts & Advancements
Single-use endoscope proliferation is bifurcating the reprocessing market, forcing detergent manufacturers to pivot formulation portfolios toward hybrid models serving both reusable and disposable device workflows. This structural tension is accelerating chemistry specialization rather than standardization.
Peracetic acid-based chemistries are collapsing the distinction between high-level disinfection and sterilization claims for heat-sensitive flexible endoscopes. US hospital systems with duodenoscopy and bronchoscopy volumes exceeding 10,000 procedures annually are adopting these chemistries at accelerated replacement cycles. The technology is collapsing traditional tiered efficacy categories into unified sporicidal disinfectant segments, compressing pricing differentiation between legacy glutaraldehyde and emerging peracetic formulations.
EU MDR's enhanced post-market surveillance requirements are mandating real-world cleaning efficacy data submissions that exceed pre-market validation standards. German notified bodies are rejecting legacy 510(k) equivalency pathways for novel enzymatic cleaners, forcing prospective clinical validation studies. Flexible endoscope channels with complex elevator mechanism designs face the strictest scrutiny, driving reformulation toward lower-foaming surfactant systems that pass automated leak-test compatibility.
Hospital procurement committees are consolidating detergent purchasing under infection control department authority rather than general supply chain management. This shift elevates clinical efficacy data over unit cost in vendor selection, displacing price-driven group purchasing organization dominance in large health systems. The behavioral change is most visible in integrated delivery networks across Pennsylvania and Ohio, where standardization across 15-plus facility footprints now prioritizes FDA master file cross-referencing over legacy sole-source contracts.
Endoscope Detergents and Disinfectants Market Segmentation
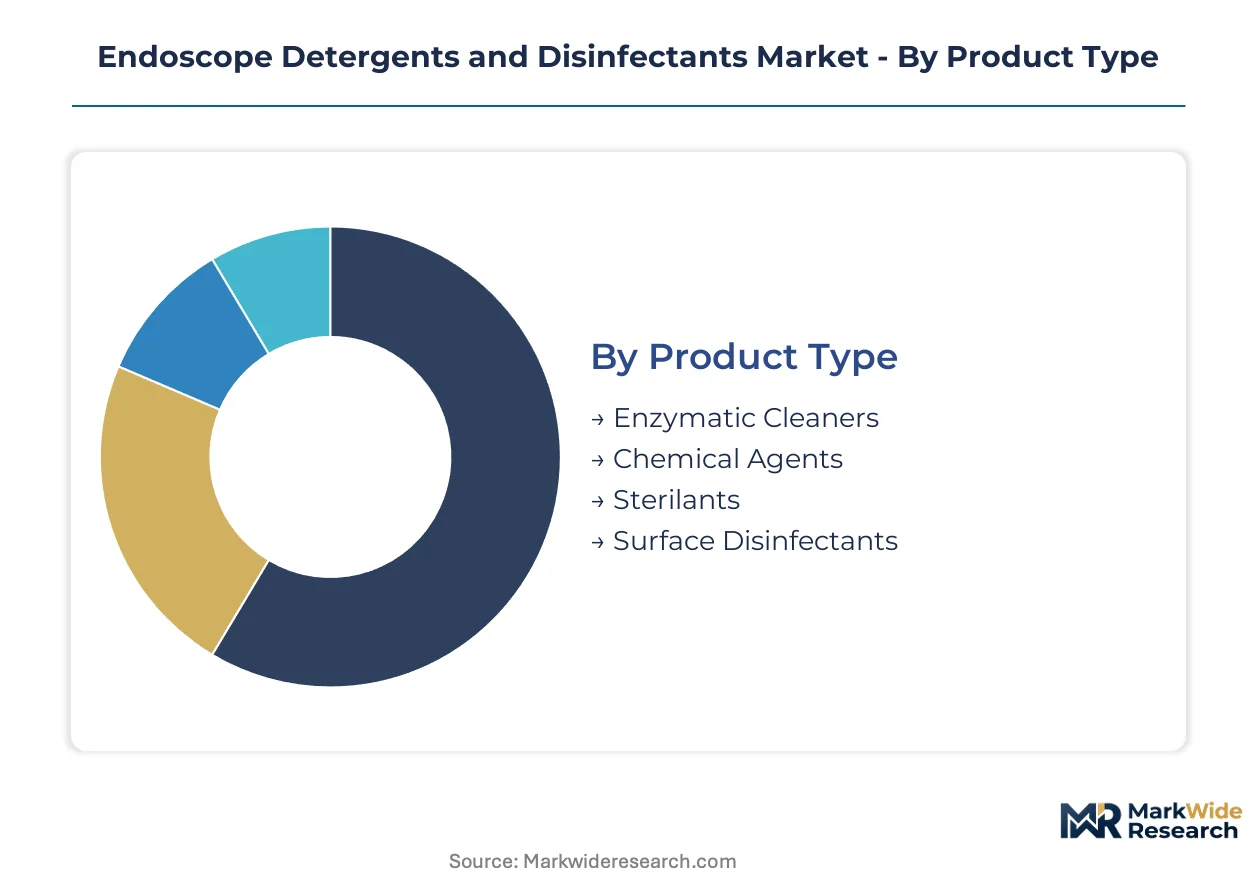
Endoscope reprocessing workflows fragment into distinct chemical and physical formats, each governed by compatibility constraints with automated equipment, manual cleaning protocols, and device material specifications. Segmentation discipline reveals where formulation innovation concentrates versus where commoditization pressures dominate procurement decisions.
Product Type:
Use-case spectrum spans protein-degrading enzymatic pre-cleaning through terminal sporicidal sterilization, with efficacy claims and contact time requirements determining clinical placement.
- Enzymatic Cleaners:Protease-lipase-amylase blends operating at neutral pH 6.5–7.5 break down blood and tissue soils without damaging flexible endoscope elastomers. German outpatient endoscopy centers in Bavaria and Baden-Württemberg mandate these for mandatory pre-cleaning steps under Robert Koch Institute protocols.
- Chemical Agents:Glutaraldehyde, ortho-phthalaldehyde, and hydrogen peroxide formulations deliver high-level disinfection for heat-sensitive devices. US hospital automated reprocessor fleet expansions in Texas and Florida concentrate demand for chemistries validated to FDA 510(k) reprocessing guidance.
- Sterilants:Peracetic acid and hydrogen peroxide vapor systems achieve sporicidal kill on flexible endoscopes.
- Surface Disinfectants:Quaternary ammonium and alcohol-based wipes for point-of-use equipment decontamination.
Established volume favors enzymatic cleaners; emerging adoption favors sterilants.
Application:
Facility type dictates throughput intensity, regulatory scrutiny depth, and chemistry format preference.
- Medical Facilities:Hospitals and ambulatory surgery centers performing gastrointestinal and pulmonary endoscopy. German federal state hygiene enforcement accelerates standardization of high-level disinfectant protocols across outpatient networks.
- Dental Clinics:Lower-volume settings using semi-critical device reprocessing with intermediate-level disinfectants.
- Laboratories:Research-grade sterilization for experimental endoscopy and prototype device testing.
- Veterinary Clinics:Companion animal endoscopy with reduced regulatory validation requirements.
Medical facilities absorb the dominant procurement volume; dental clinics present the steepest expansion trajectory for wipe-format adoption.
End User:
Capital intensity and staffing credential levels separate institutional tiers.
- Hospitals:Integrated delivery networks across Pennsylvania and Ohio consolidate detergent purchasing under infection control department authority. FDA master file cross-referencing now supersedes legacy sole-source contracts in vendor selection.
- Outpatient Clinics:Ambulatory endoscopy centers in Germany's federal states face intensified Robert Koch Institute hygiene audits.
- Research Institutions:Academic medical centers validating novel reprocessing chemistries through prospective clinical studies.
- Rehabilitation Centers:Long-term care facilities with limited endoscopy volumes and basic disinfection protocols.
Hospitals anchor procurement value; outpatient clinics are gaining share fastest.
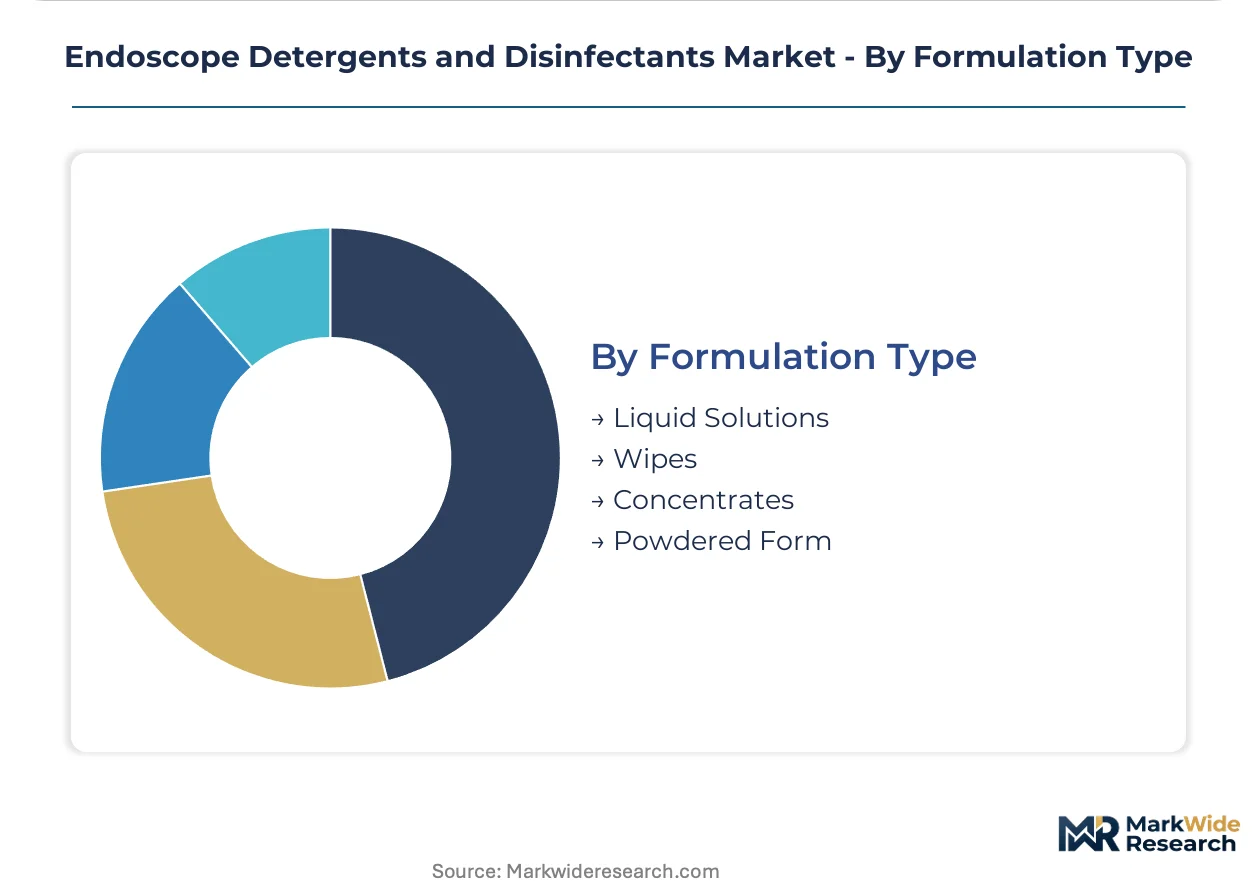
Formulation Type:
Physical format determines dilution error risk, shipping economics, and shelf stability.
- Liquid Solutions:Ready-to-use formats eliminate concentration errors in high-throughput settings. Premium pricing reflects clinical risk reduction.
- Wipes:Pre-saturated surface disinfectant protocols bypass sink-based workflows in Texas and Florida ambulatory surgical centers.
- Concentrates:Neutral pH enzyme stabilization via protease engineering reduces shipping costs for remote hospital systems.
- Powdered Form:Legacy enzymatic formulations requiring reconstitution before use.
Liquid solutions dominate current procurement; concentrates represent the fastest-growing trajectory for cost-sensitive networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzymatic cleaner production clusters in southwestern Germany and Bavaria concentrate European supply capacity, while US hospital automated reprocessor fleet expansions drive North American demand intensity. Regulatory divergence between FDA validation protocols and EU MDR biocompatibility thresholds fragments authorization pathways. Procurement standardization accelerates fastest in German outpatient networks and integrated US delivery systems.
United States
Texas and Florida ambulatory surgical centers are adopting point-of-use wipe protocols at accelerated rates. FDA's updated reprocessing validation guidance compresses replacement cycles for legacy chemistries in high-throughput endoscopy units. Pennsylvania and Ohio integrated delivery networks now consolidate detergent purchasing under infection control department authority.
Germany
Robert Koch Institute hygiene enforcement intensifies across Bavaria and Baden-Württemberg outpatient endoscopy centers. EU MDR requirements disqualify legacy formulations lacking prospective clinical validation data. Enzymatic cleaner manufacturing concentrates in Stuttgart and Munich industrial corridors serving European distribution networks.
Japan
PMDA post-market surveillance requirements elevate biocompatibility documentation thresholds for imported enzymatic cleaners. Tokyo and Osaka metropolitan hospital systems standardize high-level disinfectant protocols for duodenoscopy volumes exceeding institutional thresholds. Kanto region endoscope reprocessor installations favor chemistries with validated automated compatibility.
China
NMPA medical device regulation amendments mandate cleaning efficacy data submissions for novel disinfectant chemistries. Yangtze River Delta hospital procurement committees prioritize FDA master file cross-referenced formulations. Shanghai and Jiangsu province manufacturing clusters supply domestic enzymatic cleaner demand for expanding endoscopy service networks.
United Kingdom
London and Southeast England integrated care systems adopt infection control department-led detergent procurement frameworks. MHRA recognition of FDA 510(k) validation pathways accelerates US-formulation market entry. Midlands region ambulatory endoscopy centers face NHS England hygiene audit standardization pressures.
Endoscope Detergents and Disinfectants Market Competitive Landscape
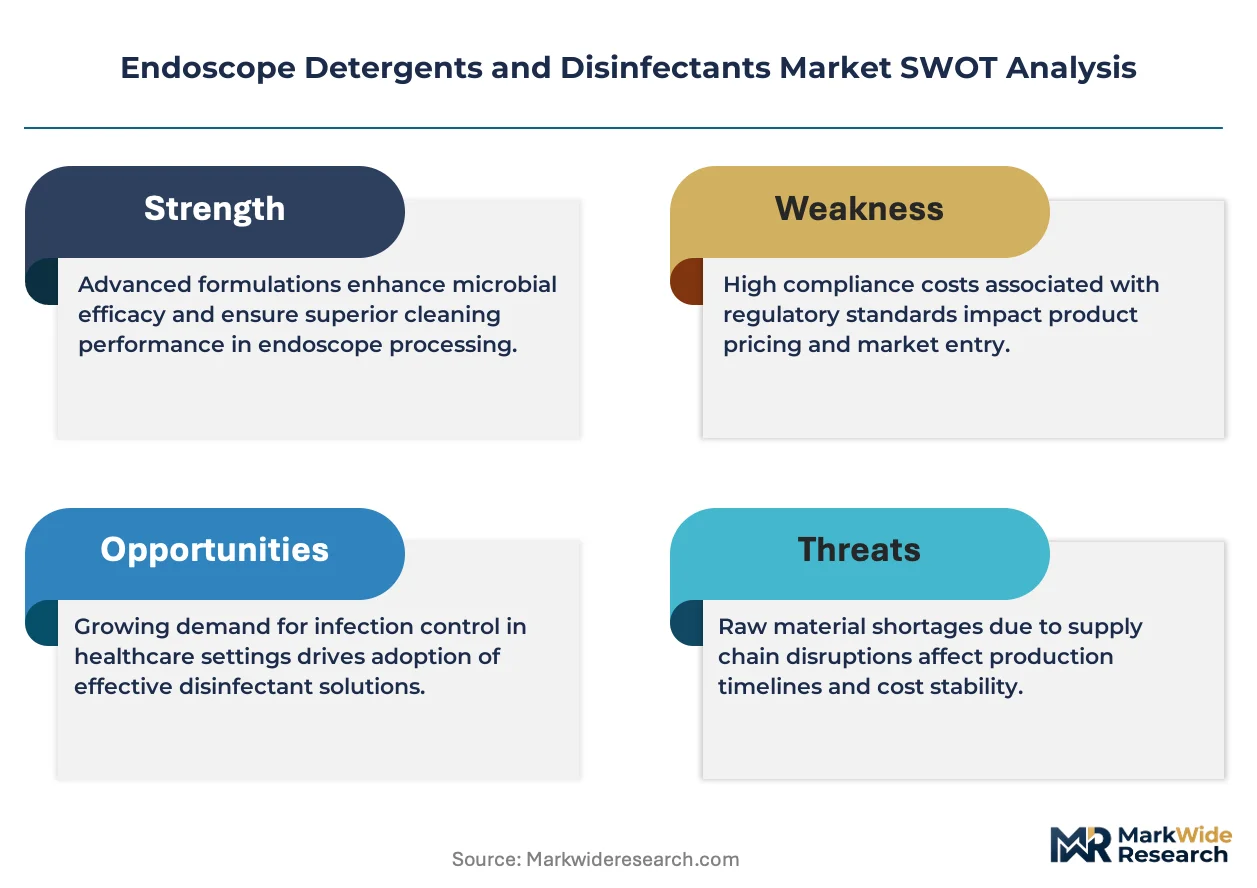
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry. The market structure consolidates around three strategic archetypes: integrated reprocessing system vendors bundling proprietary chemistries, standalone disinfectant manufacturers competing on efficacy validation, and enzymatic cleaner specialists serving pre-cleaning protocol mandates. Dominant competitive moves include automated reprocessor compatibility certification races and infection control department direct procurement channel cultivation.
Among diversified hygiene platform operators, Ecolab and STERIS exemplify system-tier positioning through healthcare infrastructure leverage and integrated reprocessing portfolio anchoring. Cantel Medical occupies a specialized high-level disinfectant niche. Borer Chemie represents the European enzymatic cleaner manufacturing concentration. Olympus Corporation and Getinge sit within the medical device manufacturer adjacency tier, leveraging endoscope installed base relationships.
| Leading Market Players |
|---|
| Borer Chemie |
| Ecolab |
| STERIS |
| Advanced Sterilization Products |
| MEDIVATORS Inc. |
| Cantel Medical |
| Olympus Corporation |
| Metrex |
| Getinge |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container rate volatility amplifies cost differentials between enzymatic cleaner manufacturing clusters in southwestern Germany and peripheral European markets, compressing margin buffers for distributors while enabling Baden-Württemberg producers to command premium pricing on validated formulations. This logistics-cost wedge reinforces the pricing power of automated reprocessor-compatible chemistry suppliers against commodity disinfectant traders.
Pricing Analysis
FDA's updated reprocessing validation guidance dictates the pricing tier structure across the endoscope detergent landscape. Three-tier pricing separates FDA master file cross-referenced premium formulations from standard 510(k) validated chemistries and economy-grade legacy disinfectants lacking updated biocompatibility data. Price differentiation hinges on automated reprocessor certification tier and sporicidal claim validation depth. Pricing pressure stems from quaternary ammonium surfactant feedstock volatility squeezing liquid disinfectant margins. Outpatient clinics in Texas and Florida exhibit highest price sensitivity due to volume-constrained procurement budgets, while integrated delivery networks in Pennsylvania prioritize efficacy validation over unit cost.
Supply Chain Analysis
Petrochemical-derived surfactant precursors and protease enzyme cultures anchor upstream feedstock dependencies for endoscope detergent manufacturing. Production gravity centers on Germany, the United States, and China, with enzymatic cleaner formulation clustering in Stuttgart and Munich industrial corridors. Raw material sourcing draws from specialty chemical producers in Belgium, enzyme fermentation facilities in Denmark, and quaternary ammonium precursor plants on the US Gulf Coast. Single-source vulnerability concentrates in German protease supply for neutral pH formulations. Distribution runs through healthcare GPOs and infection control department direct channels, with automated reprocessor OEM bundling displacing standalone chemical procurement in high-volume hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The endoscope detergent market functions as a service-attach opportunity where recurring chemistry revenue from automated reprocessor fleets expands faster than capital equipment sales. Chemistry validation subscriptions and automated compatibility certification programs now generate higher margin persistence than standalone disinfectant transactions.
For Market Incumbents: Pre-empt peracetic acid chemistry commoditization by locking in exclusive automated reprocessor compatibility certifications with expanding US hospital fleets. Defend position through backward integration into protease enzyme fermentation capacity in Denmark or Belgium, securing supply continuity against German manufacturing concentration risk. Prioritize infection control department direct channel cultivation over legacy GPO relationships as procurement authority shifts.
For New Entrants and Emerging Players: Build out point-of-use wipe format manufacturing capacity targeting ambulatory surgical centers in Texas and Florida where sink-based reprocessing workflow bypass creates white-space demand. Target veterinary clinic and dental clinic segments with intermediate-level disinfectant portfolios facing reduced EPA registration barriers. Pursue chemistry validation partnerships with mid-tier automated reprocessor OEMs lacking proprietary formulation capabilities.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified hygiene conglomerates where endoscope detergent units represent non-core revenue pools with underexploited healthcare channel leverage. Long-term viability favors specialists with validated automated reprocessor compatibility moats rather than commodity disinfectant traders. Monitor FDA master file submission velocity as inflection signal for chemistry innovation pipeline health.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Reprocessor Compatibility Certification | Locks in recurring chemistry revenue streams with expanding US hospital AER fleets. |
| Backward Integration into Enzyme Fermentation | Secures captive protease supply against German manufacturing geographic concentration. |
| Point-of-Use Wipe Format Launch | Captures ambulatory surgical center demand bypassing traditional sink-based workflows. |
| Infection Control Department Direct Channel | Aligns sales engagement with procurement authority shift away from GPO dominance. |
| Peracetic Acid Chemistry Validation | Collapses high-level disinfection and sterilization tiers into unified sporicidal claims. |
Research Methodology
Desk research of FDA 510(k) reprocessing guidance documents, EU MDR technical files, and automated reprocessor compatibility certification databases preceded structured interviews with hospital infection control directors, sterile processing department managers, GPO contracts specialists, and detergent formulation chemists. Primary fieldwork across Pennsylvania, Ohio, Texas, and Florida hospital systems combined with secondary validation against EPA registration data and Robert Koch Institute hygiene protocol publications. Bottom-up chemistry volume modeling triangulated against top-down healthcare expenditure projections.
Assumptions held FDA validation pathway stability and automated reprocessor fleet expansion rates fixed across the analysis window, while varying EU MDR enforcement intensity and quaternary ammonium feedstock price scenarios. Segmentation dimensions modeled include product type tier, facility application, end-user capital intensity, and formulation physical format. CAGRs derived from procedure volume elasticity to detergent consumption ratios and replacement cycle compression factors. Forecast inputs incorporated duodenoscopy and bronchoscopy procedure growth trajectories alongside outpatient endoscopy center expansion patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by peracetic acid specialists or single-use endoscope manufacturers would shift outcomes beyond projected ranges. Cross-checking against hospital capital expenditure surveys and infection control department budget allocation data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Neuroendoscopy Market
Endoscopy
Global Bronchoscopes Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Bronchoscopy Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Duodenoscope Market
Endoscopy
Asia-Pacific Optical Fibers in Endoscopy Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Endoscopic Submucosal Dissection Market
Endoscopy
Gastrointestinal Endoscopy Devices Market