
 Sweden Endoscopy Devices Market | 2026-2036
Sweden Endoscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Endoscopy Devices Market Analytics
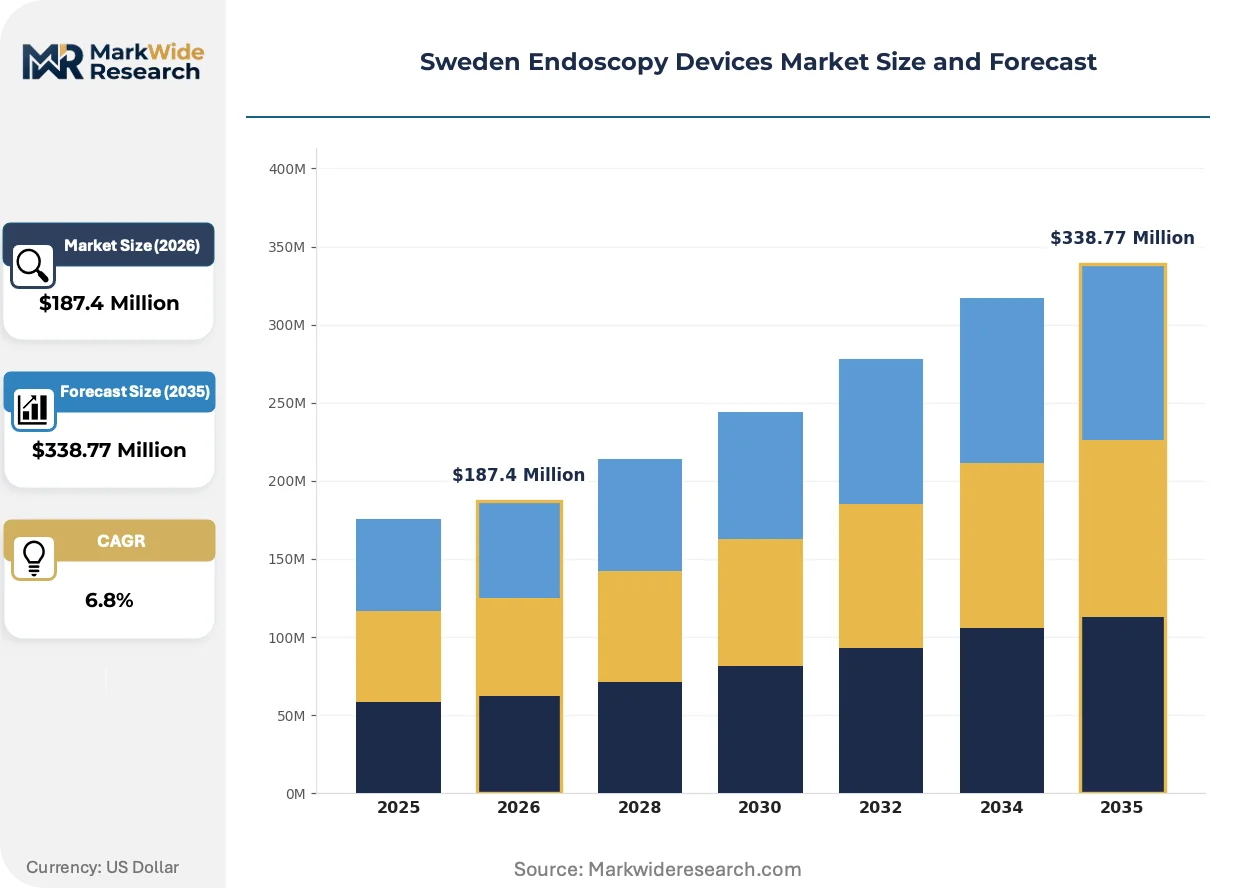
Hospital procurement channels in Sweden is fragmenting as county councils consolidate purchasing through regional frameworks while specialty clinics pursue direct vendor relationships. KARL STORZ SE & Co. KG leverages its rigid endoscope specialization to anchor premium surgical suites at Karolinska University Hospital. Olympus Corporation competes through broad visualization system portfolios that sustain recurring service contracts across county health authorities.
Sweden endoscopy devices comprise instrument systems designed for internal visualization, tissue sampling, and therapeutic intervention through natural orifices or small incisions, typically employing charge-coupled device or CMOS image sensors with working channel diameters of 2.0 to 6.0 millimeters for diagnostic and surgical access. Endoscopes command the largest product type position due to replacement cycles tied to sterilization durability standards, while robotic technology segments attract development investment from academic medical centers seeking remote surgical capability. Fiber optic delivery retains installed base dominance in outpatient settings where capital constraints limit digital platform conversion.
Swedish market access requires compliance with EU MDR conformity assessment, CE marking under notified body oversight, and adherence to ISO 13485 quality management systems that shape product registration timelines and clinical evidence requirements. The Swedish Medical Products Agency coordinates post-market surveillance with county-level procurement boards, creating dual compliance pressure on manufacturers seeking public sector contracts. Stakeholders must monitor how regional purchasing consolidation affects pricing negotiation leverage against specialized product portfolios.
Market Dynamics
County council purchasing consolidation across Sweden's 21 regions is compressing vendor margins while simultaneously elevating technical specification requirements for tender participation.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation's 2024-2026 transition period is forcing Swedish hospitals to accelerate replacement of legacy endoscope fleets with certified platforms, creating concentrated procurement windows.
- Academic medical center robotics programs:Karolinska Institutet's surgical innovation hub is validating remote telesurgery protocols that require compatible visualization infrastructure.
- Outpatient procedure migration:Specialty clinics in Gothenburg and Malmö are expanding ambulatory endoscopy capacity, driving demand for portable fiber optic systems.
Market Restraints
- Notified body capacity constraints:EU MDR certification backlogs at TÜV SÜD and BSI are extending product registration timelines by 12-18 months for Swedish market entry.
- CMOS sensor supply concentration:Japanese and Korean component manufacturers control 70% of high-definition image sensor output, creating single-source vulnerability for Swedish OEMs.
- Capital intensity of digital platform conversion:Full-stack visualization system upgrades require simultaneous investment in processors, displays, and data infrastructure that county budgets absorb unevenly.
Strategic Opportunities
- Regional health authority framework contracts:Stockholm-Gotland and Västra Götaland regions are consolidating purchasing into multi-year agreements that favor vendors with comprehensive service networks.
- AI-assisted polyp detection:Computer vision algorithms integrated with colonoscopy systems are creating reimbursement differentiation for screening programs.
- Reusable endoscope reprocessing services:Third-party sterilization providers are capturing value from hospitals outsourcing high-level disinfection compliance.
Industry Challenges
- Specialized biomedical engineering talent scarcity:Swedish universities produce insufficient graduates with combined optical engineering and clinical application expertise to support vendor field service expansion.
- Legacy system integration complexity:County hospitals operating mixed fleets of analog and digital endoscopes face interoperability failures that disrupt surgical scheduling.
- Post-market surveillance reporting burdens:The Swedish Medical Products Agency's vigilance requirements demand dedicated regulatory affairs staffing that mid-sized distributors struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Endoscopy Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Visualization Systems, Biopsy Instruments, Accessories Technology: Digital, Fiber Optic, Wireless, Robotic Delivery Mode: Invasive, Non-Invasive, Point-of-Care, Outpatient End User: Hospitals, Clinics, Surgical Centers, Research Labs |
| Companies Covered | KARL STORZ SE & Co. KG, Richard Wolf GmbH, Boston Scientific Corporation, Olympus Corporation, Fujifilm Holdings Corporation, Medtronic PLC, PENTAX Medical, Stryker Corporation, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Endoscopy Devices Market Evolving Landscape
Computational imaging and disposable component architectures are compressing the traditional capital equipment replacement cycle while redistributing value capture across the supply chain.
Single-use endoscope technology is virtualizing the sterilization-dependent business model that has sustained rigid endoscope manufacturers for decades. Swedish day surgery centers are piloting bronchoscope and ureteroscope platforms that eliminate reprocessing infrastructure entirely. This shift is virtualizing the capital allocation decisions of procurement committees, transferring expenditure from fixed asset budgets to per-procedure consumable accounting.
EU MDR's enhanced clinical evidence requirements are extending product development timelines and elevating post-market study obligations. Swedish notified bodies are applying stricter scrutiny to equivalence claims for iterative device modifications. High-risk class III endoscopic accessories face the steepest compliance cost increases, pushing some manufacturers toward declassification strategies or market withdrawal.
County council tender specifications are increasingly bundling equipment procurement with decade-long service and upgrade commitments. Stockholm's university hospital cluster is negotiating total cost of ownership contracts that internalize maintenance, training, and technology refresh obligations within single-vendor relationships. This compression of the supplier base is most visible in Skåne and Uppsala regions, where framework agreements now cover 80% of endoscope purchases.
Sweden Endoscopy Devices Market Segmentation
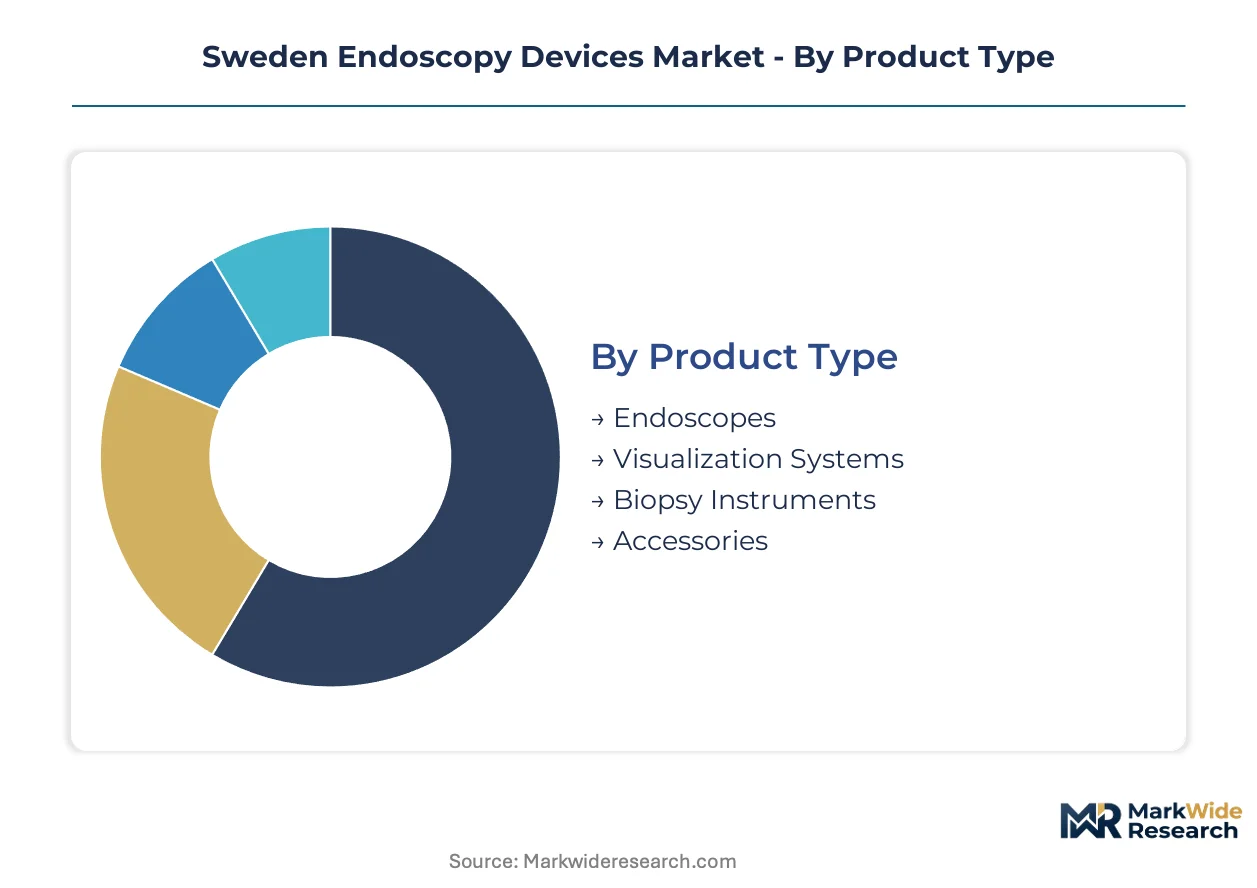
Swedish endoscopy procurement patterns diverge sharply between capital-intensive university hospital installations and ambulatory clinic equipment refresh cycles. Segmentation reveals how EU MDR compliance timelines and regional purchasing consolidation reshape vendor prioritization across product categories.
Product Type:
Use-case spectrum spans rigid surgical platforms for orthopedic and ENT intervention through flexible systems dominating gastrointestinal screening programs.
- Endoscopes:Rigid and flexible instrument systems incorporating CMOS image sensors with 2.0-6.0 millimeter working channels serve diagnostic visualization and therapeutic tissue access. Karolinska University Hospital's replacement cycles for sterilization-durable platforms anchor demand in Stockholm's procurement frameworks.
- Visualization Systems:Processor units, displays, and data infrastructure enabling high-definition image capture and transmission command premium positioning in county council tenders. Västra Götaland region's multi-year service bundling elevates these systems to central vendor relationship anchors.
- Biopsy Instruments:Forceps, needles, and retrieval devices for tissue sampling during endoscopic procedures.
- Accessories:Irrigation pumps, insufflators, and cleaning adapters supporting procedural workflow efficiency.
The dominant share belongs to Endoscopes, while Visualization Systems is closing the gap fastest.
Technology:
Cost tier stratification separates premium digital platforms from fiber optic systems serving budget-constrained outpatient settings.
- Digital:CMOS and charge-coupled device sensor platforms delivering high-definition imaging with integrated data management capabilities. Stockholm-Gotland region's framework specifications increasingly mandate digital compatibility for tender eligibility.
- Fiber Optic:Light-transmitting glass fiber bundles enabling visualization without electronic components at the distal tip. Malmö and Gothenburg day surgery centers retain substantial installed base due to lower capital thresholds and simplified maintenance.
- Wireless:Battery-powered capsule and portable systems eliminating tethered connections for enhanced mobility.
- Robotic:Teleoperated manipulation platforms enabling remote surgical intervention and precision instrument control.
Digital technology captures the largest procurement volume, with Robotic platforms gaining share fastest through Karolinska Institutet validation programs.
Delivery Mode:
Application context determines equipment specification, from sterile surgical suites to community-based screening environments.
- Invasive:Percutaneous and natural orifice entry methods requiring full sterilization protocols and surgical suite infrastructure. County hospital consolidation concentrates procurement for these systems through regional sterilization service contracts.
- Non-Invasive:Capsule endoscopy and external imaging approaches eliminating instrument insertion. Skåne region's colorectal screening expansion drives demand for patient-compliant alternatives to conventional colonoscopy.
- Point-of-Care:Portable systems enabling immediate diagnostic assessment outside centralized facilities.
- Outpatient:Ambulatory-optimized platforms supporting same-day procedure and discharge workflows.
Invasive delivery maintains institutional preference, though Non-Invasive modalities are expanding most quickly in population screening applications.
End User:
Customer type segmentation reflects Sweden's tiered healthcare structure, from specialized academic centers to distributed primary care networks.
- Hospitals:University and county council facilities performing complex surgical and diagnostic endoscopy with full sterilization infrastructure. Uppsala and Linköping university hospitals anchor high-value procurement through integrated operating room renovations.
- Clinics:Specialist gastroenterology and ENT practices performing routine diagnostic and minor therapeutic procedures. Regional purchasing consolidation increasingly subsumes clinic procurement within hospital framework agreements.
- Surgical Centers:Dedicated ambulatory facilities focused on high-volume, low-acuity endoscopic interventions.
- Research Labs:Academic and clinical trial settings employing endoscopy for protocol-driven investigation and device validation.
Hospitals command the dominant procurement volume, while Clinics face absorption pressure from regional framework expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm's university hospital cluster commands pricing premiums that county procurement frameworks in Skåne and Västra Götaland struggle to match. This asymmetry reflects concentration of complex surgical volume versus distributed screening demand across Sweden's 21 regions.
Stockholm-Gotland Region
Karolinska University Hospital's integrated operating room renovations drive demand for sterilization-durable rigid endoscope platforms. EU MDR compliance deadlines accelerate replacement cycles at flagship institutions. The Stockholm county council's multi-year service bundling concentrates vendor relationships around comprehensive visualization infrastructure.
Västra Götaland Region
Gothenburg's Sahlgrenska University Hospital anchors gastrointestinal screening expansion alongside day surgery center proliferation. Regional framework agreements now subsume 80% of endoscope purchases through consolidated tender specifications. Fiber optic systems retain installed base dominance in budget-constrained outpatient settings.
Skåne Region
Malmö's ambulatory endoscopy capacity expansion drives portable system demand for same-day discharge workflows. The county's colorectal screening program creates procurement volume for patient-compliant non-invasive alternatives. Lund University Hospital validates robotic telesurgery protocols requiring compatible visualization infrastructure.
Uppsala Region
Uppsala University Hospital's academic medical center status attracts development investment for remote surgical capability platforms. County council purchasing consolidation compresses vendor margins while elevating technical specification requirements. The region's sterilization service contracts centralize procurement for invasive delivery systems.
Sweden Endoscopy Devices Market Competitive Landscape
Specialized optical manufacturers and diversified medical technology conglomerates split the market between premium surgical suite anchoring and broad service network coverage. Consolidation pressure from regional purchasing frameworks favors vendors with comprehensive field service organizations. Two archetypes dominate: rigid endoscope specialists leveraging sterilization durability reputations, and visualization system integrators capturing recurring maintenance contracts. Competitive moves center on multi-year framework contract capture and AI-assisted diagnostic feature differentiation.
Among Germany-based precision instrument fabricators, KARL STORZ SE & Co. KG and Richard Wolf GmbH exemplify the rigid endoscope specialist archetype through their anchoring positions in university hospital premium surgical suites. Olympus Corporation and Fujifilm Holdings Corporation represent the diversified visualization integrator model, sustaining recurring service relationships across county health authorities. These four entities occupy positions that reflect the market's structural bifurcation between specialized surgical platforms and comprehensive screening infrastructure.
| Leading Market Players |
|---|
| KARL STORZ SE & Co. KG |
| Richard Wolf GmbH |
| Boston Scientific Corporation |
| Olympus Corporation |
| Fujifilm Holdings Corporation |
| Medtronic PLC |
| PENTAX Medical |
| Stryker Corporation |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Japanese and Korean CMOS image sensor manufacturers determines both pricing tier spreads and supply chain shape across Swedish endoscopy procurement. County council framework consolidation amplifies this concentration risk as standardized tender specifications reduce vendor differentiation leverage while simultaneously elevating technical compliance costs.
Pricing Analysis
Configured-to-order pricing for sterilization-durable rigid endoscope platforms commands substantial premiums over standard flexible system configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under EU MDR and after-sales service bundling intensity. Pricing pressure stems from regional purchasing consolidation compressing vendor margins in framework negotiations. University hospital surgical suites exhibit lowest price sensitivity due to total cost of ownership contracting, while ambulatory clinics in Gothenburg and Malmö face acute capital constraints driving fiber optic retention.
Supply Chain Analysis
Export-control regimes governing high-definition image sensor technology limit component flows from Japan and South Korea to Swedish OEMs and system integrators. Manufacturing concentration in Germany for precision rigid endoscope fabrication and China for disposable component production creates geographic bifurcation. Raw material dependencies encompass optical glass fibers, CMOS wafers, and medical-grade polymers. Single-source vulnerability in sensor supply chains threatens production continuity for digital platform vendors. Distribution runs through regional health authority procurement boards with increasing direct-to-hospital service contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swedish endoscopy markets approach a platform-economics inflection as visualization system interoperability becomes the decisive procurement criterion. Karolinska Institutet's telesurgery validation programs are redistributing competitive advantage toward vendors with integrated data infrastructure capabilities.
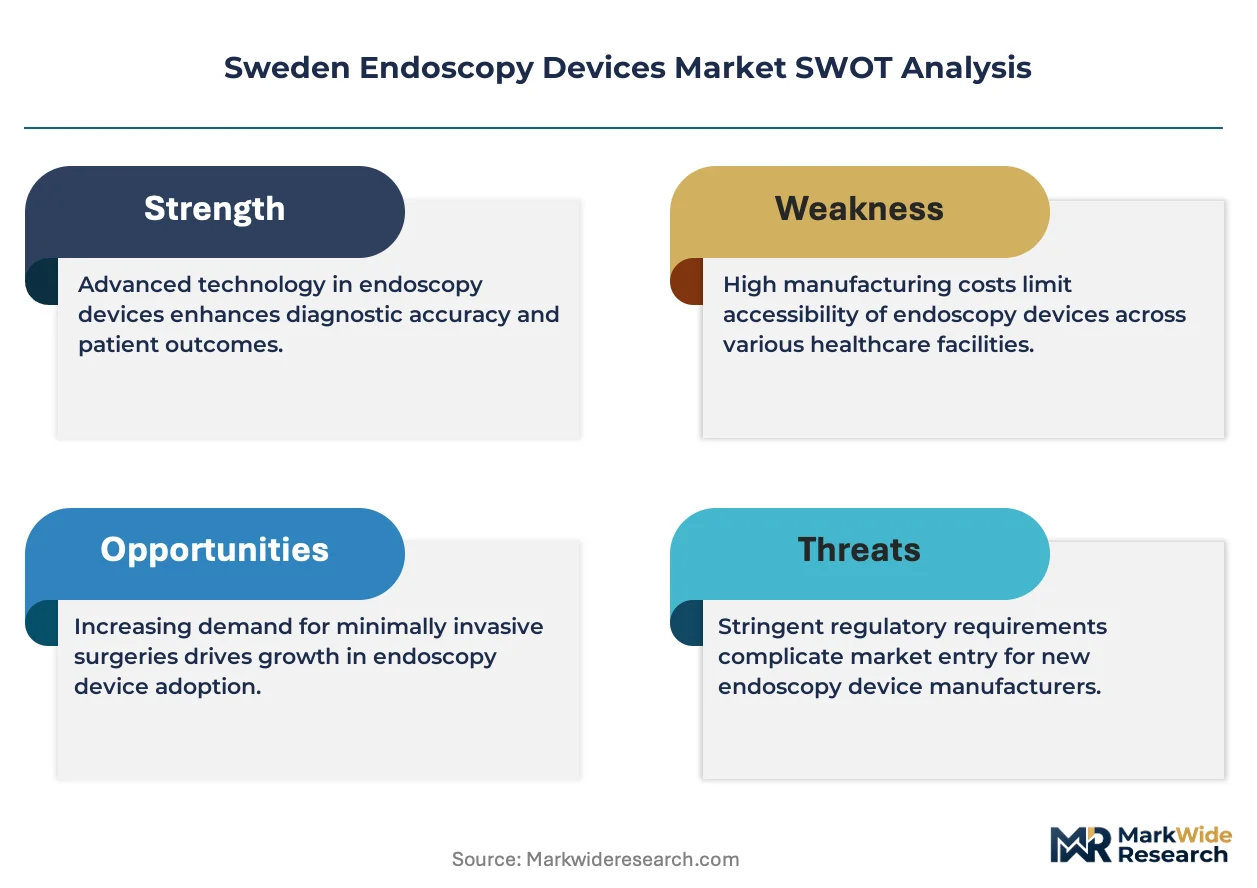
For Market Incumbents: Pre-empt framework contract displacement by embedding AI-assisted diagnostic modules into existing visualization system installed bases before tender renewal cycles. County council consolidation threatens specialized rigid endoscope manufacturers lacking comprehensive service networks; backward integration into reprocessing services preserves margin capture from sterilization-dependent legacy platforms. For New Entrants and Emerging Players: Build out disposable single-use endoscope offerings targeting Malmö and Gothenburg day surgery centers where capital constraints block digital conversion. The most penetrable segment lies in bronchoscope and ureteroscope platforms eliminating reprocessing infrastructure entirely. A direct-to-clinic consumable accounting model bypasses hospital capital budget committees. For Investors and Strategic Acquirers: Reprocessing service providers with EU MDR-compliant sterilization infrastructure represent the most defensible acquisition target archetype amid outsourcing acceleration. Long-term viability over the next decade hinges on capturing recurring revenue streams detached from capital equipment replacement cycles. Watch for framework contract award announcements from Stockholm-Gotland and Västra Götaland regions as inflection indicators for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment timelines determine market entry sequencing for iterative device modifications. |
| Hospital System Partnership | Stockholm-Gotland framework agreements internalize decade-long service obligations within single-vendor relationships. |
| Software Companion Development | AI-assisted polyp detection algorithms create reimbursement differentiation for colorectal screening programs. |
| Reimbursement Strategy | County council procurement boards weight total cost of ownership against per-procedure consumable accounting models. |
| Backward Integration | In-house CMOS sensor sourcing mitigates supply concentration risk from Japanese and Korean component manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and regulatory affairs leads at notified bodies, then refined through secondary validation against EU MDR submission databases, county council tender documentation, hospital procurement registries, and ISO 13485 certification records. Bottom-up equipment installation tracking and top-down regional health expenditure analysis were triangulated to establish market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning product type, technology tier, delivery mode, and end-user facility category. CAGRs were derived from equipment replacement cycle analysis and regional purchasing consolidation trajectories. Forecast inputs incorporated EU MDR transition deadlines and academic medical center robotics program validation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by single-use disposable platform entrants would shift outcomes beyond modeled parameters. Material shifts in notified body certification capacity or CMOS sensor export control enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Colonoscopy Devices Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Endoscopy Visualization Systems Market
Endoscopy
Endoscopy Procedures Estimates Market
Endoscopy
Global Endoscopic Clips Market
Endoscopy
Veterinary Video Endoscopy Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Netherlands Endoscopy Devices Market
Endoscopy
Sigmoidoscope Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
China Arthroscopy Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
Endoscopic Tattooing Market
Endoscopy
North America Endoscopy Devices Market
Endoscopy
Asia Pacific Endoscopy Devices Market