
 Global Encephalitis Vaccine Market | 2026-2036
Global Encephalitis Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Encephalitis Vaccine Market Foresight
mRNA platform convergence is narrowing the development gap between prototype pathogen preparedness and licensed encephalitis vaccines. Sanofi Pasteur leverages decades of yellow fever vector expertise to anchor its neurotropic flavivirus manufacturing network across multiple continents. Biological E Limited specializes in bulk antigen supply for government tender programs, while Valneva SE differentiates through its purified Vero cell-derived Japanese encephalitis formulation that dominates travel medicine channels in Europe and North America.
Encephalitis vaccines are prophylactic biological preparations designed to induce neutralizing antibodies against neurotropic viruses such as Japanese encephalitis virus, tick-borne encephalitis virus, or West Nile virus, typically formulated with aluminum hydroxide adjuvants and administered in two- or three-dose primary series to achieve protective titers. The live attenuated segment occupies the largest procurement volumes in endemic country programs due to single-dose convenience and cost efficiency, while the mRNA category represents the fastest-growing pipeline as developers apply SARS-CoV-2 platform learnings to universal flavivirus candidates. Pediatric target populations sustain the deepest margin pools through multiyear tender contracts, though adult travel indications command premium pricing in private pharmacy and clinic channels.
WHO prequalification status shapes demand trajectories by determining eligibility for Gavi Alliance procurement and UNICEF supply agreements, while national regulators such as India's CDSCO and China's NMPA enforce localized lot-release testing that extends time-to-market for imported products. The EU's CE marking under the Medical Devices Regulation and FDA's biologics licensing pathway create divergent evidence requirements that fragment clinical development strategies. Stakeholders must monitor platform technology transfer agreements between originators and emerging-market manufacturers, as these partnerships will determine which production networks capture the next wave of national immunization program expansions.
Market Dynamics
The transition from mouse-brain-derived substrates to Vero cell culture platforms is compressing production timelines and expanding manufacturing capacity across emerging-market supply networks. This substrate shift simultaneously addresses safety concerns while unlocking volume scalability for national immunization programs.
Growth Catalysts
- WHO Prequalification Pathways:Gavi Alliance eligibility criteria are accelerating procurement access for Vero cell-derived Japanese encephalitis formulations across Southeast Asian national programs.
- Pediatric Schedule Integration:India's Universal Immunization Programme incorporates single-dose live attenuated vaccines into routine childhood visits, creating sustained demand visibility through multiyear tender cycles.
- mRNA Platform Adaptation:SARS-CoV-2 manufacturing infrastructure is being repurposed for universal flavivirus candidates, narrowing development timelines for prototype pathogen preparedness.
Market Restraints
- Input Cost Volatility:Bovine serum albumin and specialized cell culture media prices fluctuate with agricultural commodity markets, squeezing margin structures for bulk antigen suppliers.
- Regulatory Friction:India's CDSCO enforces localized lot-release testing that extends time-to-market for imported products by six to eighteen months versus domestic manufacturers.
- Technical Limitation:Thermostability requirements for last-mile distribution in tropical climates constrain formulation options and elevate cold-chain infrastructure costs.
Strategic Opportunities
- Underpenetrated Geography:Sub-Saharan African markets lack routine Japanese encephalitis vaccination despite ecological suitability for viral transmission, presenting first-mover positioning for prequalified suppliers.
- Technology Convergence:Combination vaccines pairing encephalitis antigens with measles or dengue components are capturing procurement interest from ministries seeking simplified immunization schedules.
- Channel Innovation:Travel medicine clinics in Europe and North America are expanding private-pay adult vaccination services, commanding premium pricing outside tender-constrained pediatric channels.
Industry Challenges
- Specialized Workforce Scarcity:Vero cell culture expertise concentrates among a limited pool of bioprocessing engineers, constraining technology transfer velocity to emerging-market manufacturing partners.
- Certification Timeline Compression:WHO prequalification dossiers require extensive clinical immunogenicity data that delays market entry by three to five years for novel platform candidates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Encephalitis Vaccine Market |
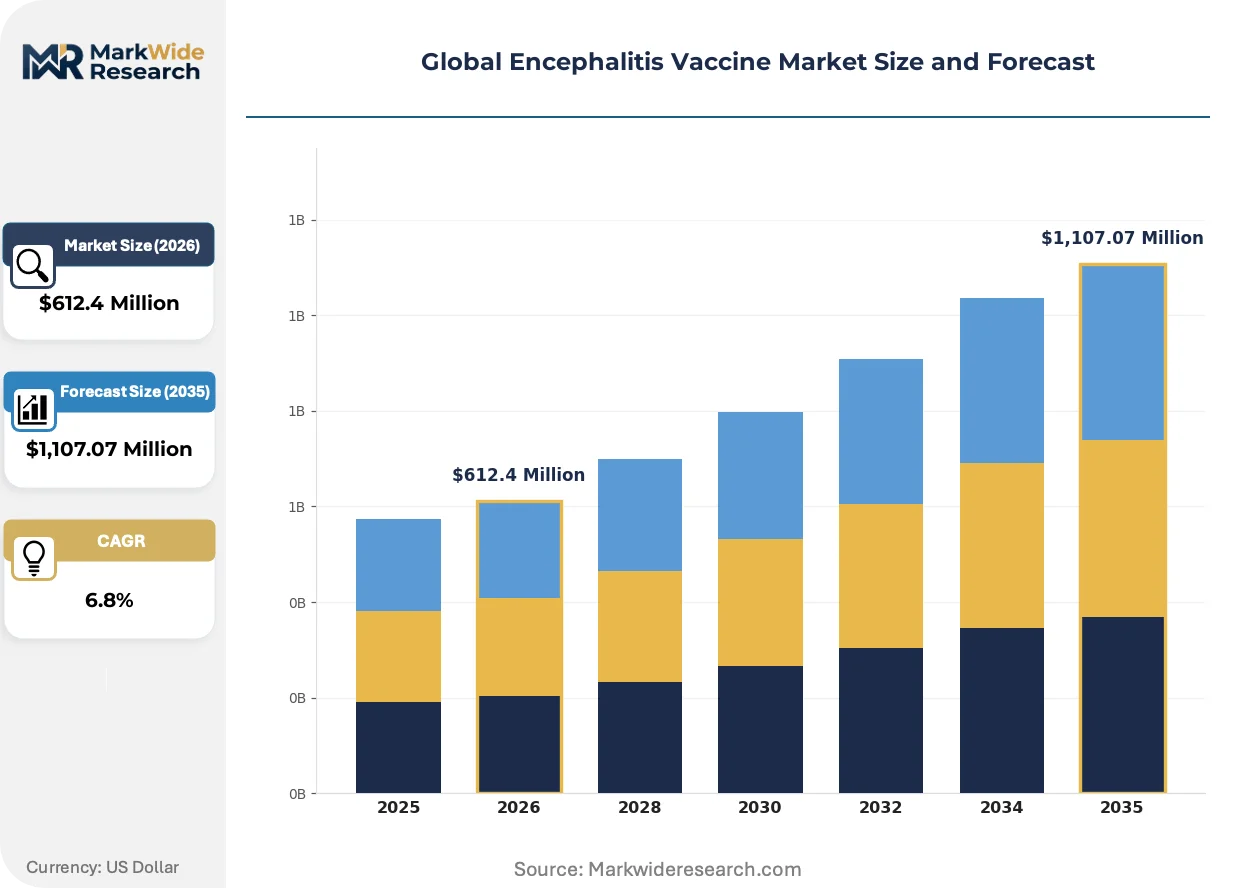
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Attenuated, Inactivated, Subunit, mRNA Administration Route: Intramuscular, Subcutaneous, Intradermal, Oral Target Population: Pediatric, Adult, Elderly, Immunocompromised Distribution Channel: Hospitals, Pharmacies, Clinics, Online |
| Companies Covered | China National Biotec Group, Biological E Limited, Sanofi Pasteur, Chengdu Institute of Biological Products, Takeda Pharmaceutical, GlaxoSmithKline, Valneva SE, Wuhan Institute of Biological Products, Bharat Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Encephalitis Vaccine Market Shifts & Advancements
Platform technology convergence is collapsing the historical gap between pandemic preparedness prototyping and commercially licensed encephalitis vaccines. Manufacturers are repurposing COVID-19 infrastructure while regulators adapt review frameworks for novel modalities.
Vero cell culture technology is migrating from niche travel-medicine supply toward dominant procurement volumes in national immunization programs. CDSCO and WHO prequalified manufacturers in India are converting yellow fever production lines to Japanese encephalitis bulk antigen output. This substrate shift is compressing safety-related regulatory objections while expanding annual dose capacity into the hundreds of millions.
EMA's Medical Devices Regulation and the FDA's biologics licensing pathway are diverging on adjuvant safety data requirements, fragmenting clinical development strategies for multinational sponsors. European travel medicine providers now demand CE-marked purified Vero cell formulations, while US purchasers prioritize FDA-licensed live attenuated alternatives. Developers must maintain parallel dossier tracks or accept geographic market exclusion.
Ministry of Health procurement offices are consolidating tender awards toward single-source multiyear contracts with integrated supply guarantees. Vietnam, Thailand, and Cambodia have shifted from annual competitive bidding to five-year partnership frameworks with prequalified manufacturers. This buyer concentration is squeezing spot-market suppliers while rewarding vertically integrated producers with captive Vero cell capacity and established cold-chain distribution networks.
Global Encephalitis Vaccine Market Segmentation
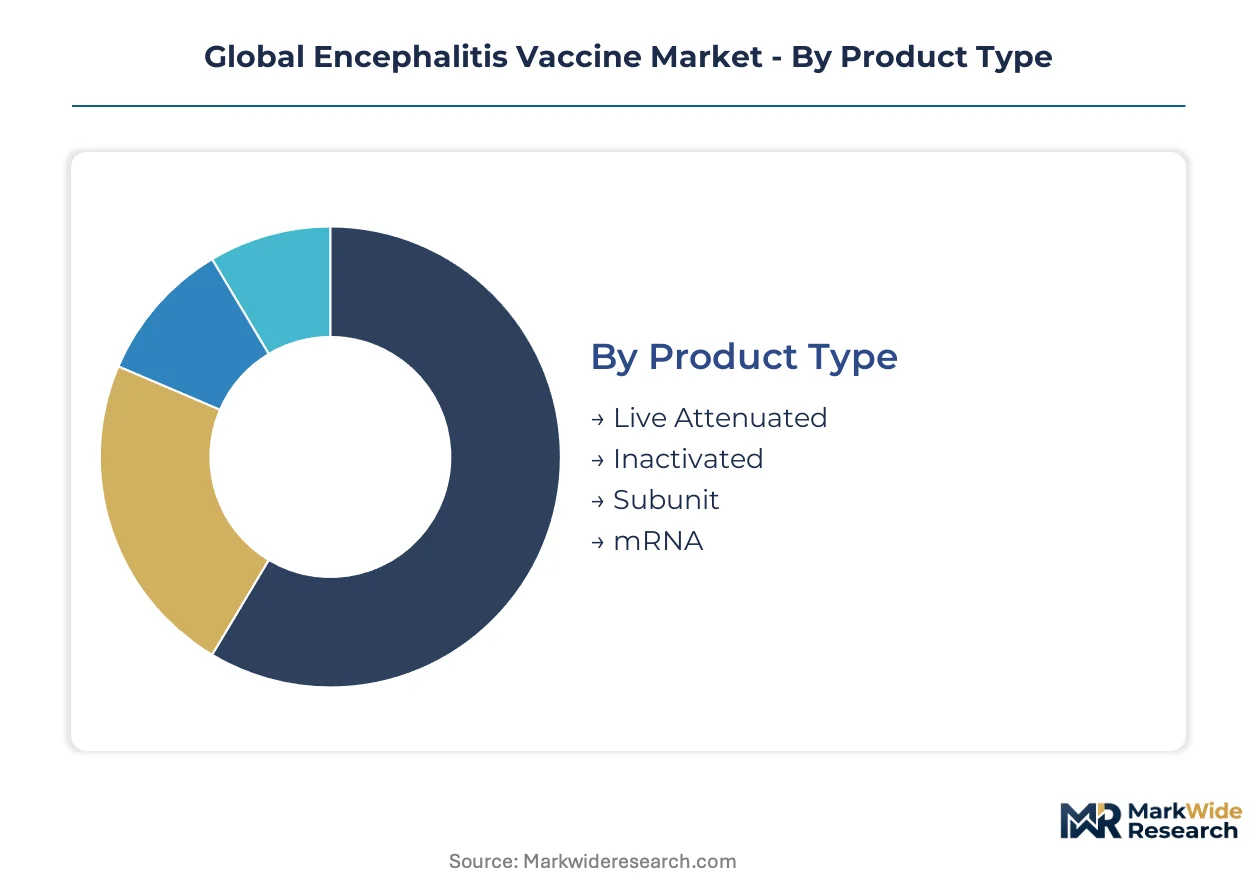
Segmentation in encephalitis vaccines reveals divergent margin structures across production platforms and delivery channels. Manufacturers optimize formulation strategies based on whether doses flow through government tender programs or private travel medicine networks.
Product Type:
After-sales service intensity varies sharply across production platforms, with live attenuated vaccines requiring minimal post-distribution pharmacovigilance while mRNA candidates demand extensive cold-chain monitoring and adverse event surveillance infrastructure.
- Live Attenuated:Single-dose formulations derived from SA14-14-2 or related strains dominate India's Universal Immunization Programme procurement. CDSCO-prequalified domestic manufacturers capture multiyear tender awards through cost efficiency and established distribution networks in Bihar, Uttar Pradesh, and Assam.
- Inactivated:Vero cell-derived purified formulations command premium positioning in European travel medicine channels. EMA's Medical Devices Regulation compliance requirements and thermostability constraints shape formulation development priorities for Valneva SE and comparable suppliers.
- Subunit:Recombinant protein approaches reduce safety concerns in immunocompromised populations. Limited commercial availability constrains procurement scale.
- mRNA:Platform adaptation from SARS-CoV-2 manufacturing infrastructure is narrowing development timelines for universal flavivirus candidates. WHO prequalification pathways remain unestablished for this modality.
By volume, Live Attenuated leads. By growth pace, mRNA is ahead.
Administration Route:
Cost tier differentiation separates mass immunization programs from premium private channels, with intramuscular delivery dominating high-volume tenders while alternative routes target specific population constraints.
- Intramuscular:Standard delivery for inactivated Japanese encephalitis vaccines in pediatric schedules across Vietnam, Thailand, and Cambodia. Cold-chain requirements and trained healthcare worker availability constrain last-mile implementation in rural districts.
- Subcutaneous:Live attenuated SA14-14-2 administration enables single-dose coverage in India's routine immunization visits. WHO prequalification status determines Gavi Alliance eligibility for this delivery mode.
- Intradermal:Dose-sparing approaches show promise in preclinical evaluation. Regulatory acceptance remains limited.
- Oral:No licensed encephalitis vaccines currently utilize this route. Development programs target thermostability advantages for tropical distribution.
Intramuscular administration captures procurement volume leadership. Intradermal approaches are climbing the fastest on pipeline activity.
Target Population:
Application focus determines pricing architecture, with pediatric programs operating under tender-constrained margins while adult travel indications support premium positioning.
- Pediatric:Routine immunization integration in endemic countries sustains the deepest procurement volumes. India's CDSCO enforces localized lot-release testing that favors domestic manufacturers over imported alternatives.
- Adult:Travel medicine demand concentrates in European and North American private-pay channels. CE-marked purified Vero cell formulations command substantial price premiums over live attenuated alternatives.
- Elderly:Immunosenescence considerations drive adjuvant selection in tick-borne encephalitis formulations. Limited dedicated clinical data constrains label expansion.
- Immunocompromised:Inactivated or subunit approaches are preferred over live attenuated options. Market size remains constrained by indication specificity.
Pediatric segments anchor procurement volume. Adult travel indications are gaining share fastest on pricing expansion.
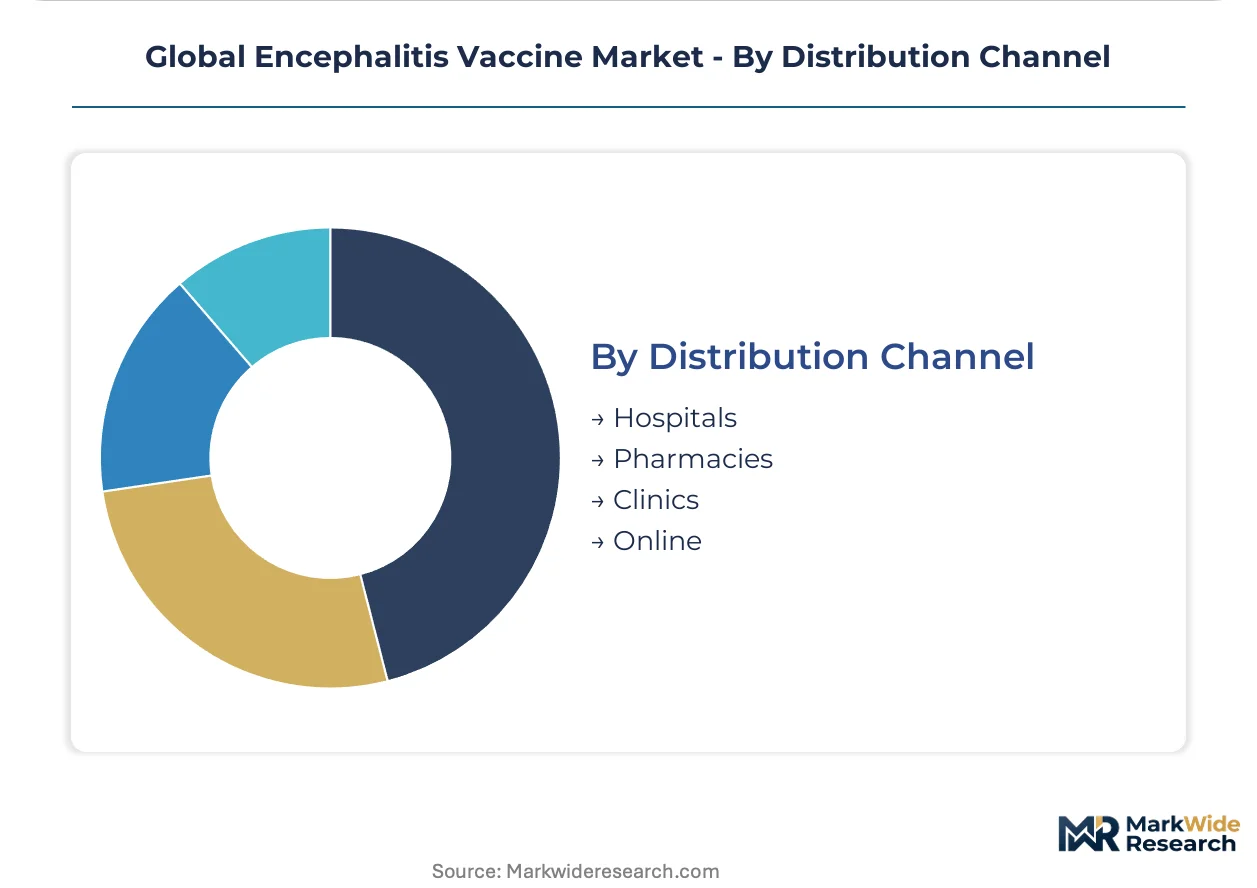
Distribution Channel:
Customer type separation defines competitive dynamics, with institutional purchasers consolidating toward multiyear partnerships while retail channels fragment across regional pharmacy networks.
- Hospitals:Centralized procurement in Vietnam, Thailand, and Cambodia has shifted from annual competitive bidding to five-year partnership frameworks. Vertically integrated manufacturers with captive Vero cell capacity secure preferred supplier status.
- Pharmacies:European travel medicine clinics in Germany, France, and Switzerland expand private-pay adult vaccination services. Premium pricing outside tender constraints rewards differentiated formulation positioning.
- Clinics:Specialized travel health centers in the United States prioritize FDA-licensed live attenuated alternatives. Parallel dossier requirements fragment development strategies for multinational sponsors.
- Online:Direct-to-consumer channels remain nascent for prescription vaccines. Regulatory frameworks for cold-chain verification in last-mile delivery are evolving.
Hospitals lead by procurement volume. Online channels show the steepest expansion trajectory on digital health infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers in India and China supply bulk antigens to procurement agencies across Southeast Asia, while European and North American markets remain net importers of finished vaccine formulations. Trade flows concentrate through WHO prequalification channels, with CDSCO and NMPA lot-release protocols governing outbound shipments.
India
Domestic demand from the Universal Immunization Programme drives annual procurement exceeding one hundred million doses of live attenuated Japanese encephalitis vaccines. CDSCO enforces localized lot-release testing that extends time-to-market for imported products by six to eighteen months. Manufacturing clusters in Hyderabad and Pune house vertically integrated producers with captive Vero cell capacity serving government tender programs.
China
State-owned biological institutes anchor production of both live attenuated and inactivated encephalitis vaccines for domestic immunization schedules and export markets. NMPA regulates substrate transitions from mouse-brain-derived to Vero cell platforms through centralized lot-release protocols. Chengdu and Wuhan host concentrated manufacturing infrastructure with technology transfer agreements extending to Southeast Asian partners.
United States
Travel medicine demand concentrates in private-pay adult channels, with FDA-licensed live attenuated vaccines preferred by specialized clinics and occupational health programs. Biologics licensing pathway requirements diverge from European CE marking standards, fragmenting development strategies for multinational sponsors. Cold-chain distribution networks in major metropolitan areas support premium pricing outside tender-constrained pediatric segments.
Thailand
National immunization program expansion integrates Japanese encephalitis vaccines into routine pediatric schedules across endemic provinces. Ministry of Health procurement offices have shifted from annual competitive bidding to five-year partnership frameworks with prequalified suppliers. Bangkok anchors regional distribution infrastructure with established cold-chain networks extending to provincial health centers.
Germany
Travel medicine clinics in Munich, Frankfurt, and Berlin command premium pricing for CE-marked purified Vero cell formulations targeting adult outbound travelers. EMA Medical Devices Regulation compliance requirements shape formulation development priorities for European market access. Private pharmacy channels sustain margin pools unavailable in government tender programs elsewhere.
Global Encephalitis Vaccine Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive Vero cell capacity and established WHO prequalification status. Three strategic archetypes dominate: state-backed biological institutes with domestic market priority, emerging-market specialists securing multiyear government tenders, and European travel-medicine focused developers commanding premium pricing. Competitive moves center on technology transfer partnerships for substrate platform migration and five-year procurement framework negotiations with national immunization programs.
Within the state-backed tier, China National Biotec Group and Chengdu Institute of Biological Products exemplify production-scale anchoring through centralized biological manufacturing infrastructure. Among emerging-market specialists, Biological E Limited occupies a position representing bulk antigen supply integration with government tender programs. At the premium-formulation end, Valneva SE and Sanofi Pasteur sit within travel-medicine channels where regulatory differentiation supports pricing architecture outside procurement-constrained segments.
| Leading Market Players |
|---|
| China National Biotec Group |
| Biological E Limited |
| Sanofi Pasteur |
| Chengdu Institute of Biological Products |
| Takeda Pharmaceutical |
| GlaxoSmithKline |
| Valneva SE |
| Wuhan Institute of Biological Products |
| Bharat Biotech |
| Others |
Supply & Pricing Matrix
Regulatory lot-release bottlenecks at India's CDSCO compress pricing power for imported formulations while amplifying margin capture for domestic Vero cell manufacturers with captive antigen production. This chokepoint stratifies the market into premium travel-medicine channels and tender-constrained pediatric procurement tiers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across government tender, institutional procurement, and private travel medicine segments. WHO prequalification status and FDA versus CE marking differentiation separate premium purified Vero cell formulations from economy live attenuated alternatives. Pricing pressure stems from multiyear tender consolidation in Vietnam, Thailand, and Cambodia squeezing spot-market suppliers. Government immunization programs exhibit extreme price sensitivity while European travel clinics tolerate substantial premiums for thermostable formulations.
Supply Chain Analysis
Biological E Limited, Valneva SE, and Chengdu Institute of Biological Products hold concentrated Vero cell culture capacity for bulk antigen production. Manufacturing gravity centers on India, China, and select European facilities with WHO prequalified status. Bovine serum albumin and specialized cell culture media constitute critical input dependencies. Single-source vulnerability runs through limited bioprocessing engineer pools constraining technology transfer velocity. Distribution runs through cold-chain networks extending from Hyderabad and Pune manufacturing clusters to provincial health centers across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA platform migration from SARS-CoV-2 infrastructure is collapsing development timelines for universal flavivirus candidates, creating a regulatory and manufacturing inflection that rewards first movers with prequalified substrate platforms.
For Market Incumbents: Pre-empt emerging mRNA entrants by accelerating Vero cell technology transfer partnerships with Southeast Asian manufacturers before WHO prequalification pathways formalize for novel modalities. Secure backward integration into bovine serum albumin supply through agricultural commodity hedging to defend margin structures against input volatility. Lock five-year procurement frameworks with Vietnam, Thailand, and Cambodia ministries before competitive bidding reopens. For New Entrants and Emerging Players: Pursue Sub-Saharan African markets lacking routine Japanese encephalitis vaccination despite ecological transmission suitability, where first-mover positioning remains uncontested by established prequalified suppliers. Target adult travel medicine channels in North American specialized clinics as the most penetrable premium segment outside tender-constrained government programs. Lead with FDA biologics licensing pathway differentiation to capture pricing architecture unavailable to CE-marked competitors. For Investors and Strategic Acquirers: WHO prequalification pathway expansion for mRNA modalities reshapes the acquisition landscape toward platform-agnostic manufacturers with demonstrated cell culture scale. Long-term viability hinges on captive Vero cell capacity integration with established cold-chain distribution networks. Monitor CDSCO technology transfer approval velocity as the critical signal for emerging-market manufacturing partnership viability.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Advancement | Unlocks Gavi Alliance procurement eligibility and UNICEF supply agreements for novel Vero cell formulations. |
| Vero Cell Technology Transfer Partnership | Accelerates substrate platform migration from mouse-brain-derived production to safety-improved cell culture. |
| Multiyear Tender Framework Negotiation | Secures demand visibility through five-year partnership structures with Vietnam, Thailand, and Cambodia ministries. |
| mRNA Platform Pipeline Diversification | Repurposes COVID-19 manufacturing infrastructure toward universal flavivirus candidate development. |
| Cold-Chain Distribution Expansion | Extends last-mile thermostability capabilities to tropical provincial health centers across endemic regions. |
Research Methodology
Cross-validation between regulatory filing databases and procurement contract disclosures anchors the qualitative findings on manufacturing capacity and tender award patterns. Primary interviews with vaccine development executives, CDSCO regulatory affairs leads, Gavi Alliance procurement officers, and hospital formulary directors combined with secondary validation through WHO prequalification listings, ClinicalTrials.gov entries, FDA biologics licensing records, and EMA medical device registrations. Bottom-up dose demand modeling and top-down market sizing triangulate volume estimates across the analysis window.
Calibration against historical tender award values and disclosed manufacturing capacity expansions grounds the projection framework. Segmentation dimensions include production platform type, administration route, target population demographic, and regional regulatory cluster. CAGRs derive from dose volume trajectories indexed to national immunization program expansion schedules and travel medicine clinic network growth. Forecast inputs incorporate Vero cell culture yield improvements and mRNA platform technology transfer timelines.
Sensitivities concentrate around WHO prequalification pathway formalization for mRNA candidates, CDSCO lot-release protocol modifications, and bovine serum albumin commodity price volatility. Forecasts reflect assumptions on pediatric schedule integration persistence and travel medicine demand recovery. Cross-checking against UNICEF vaccine procurement dashboards and Gavi Alliance disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Calcineurin Inhibitor Drugs Market
Pharmaceuticals
P2X7 Receptor Antagonists Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Asia Pacific Drug Development Market
Pharmaceuticals
Hepatic Antiviral Drugs Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Global Antiemetic Drugs Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Topical Corticosteroids Market