
 Topical Corticosteroids Market | 2026-2036
Topical Corticosteroids Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Corticosteroids Market Outlook
Specialty pharmaceutical manufacturing in India and China is rebalancing as Western buyers diversify active pharmaceutical ingredient sourcing. LEO Pharma leverages its century-long dermatology focus to sustain premium positioning in psoriasis and eczema segments. Pfizer competes through broad commercial infrastructure, while AbbVie anchors its portfolio with immunology-aligned dermatological pipelines.
Topical corticosteroids are synthetic glucocorticoid formulations designed for percutaneous absorption, with potency tiers determined by vasoconstriction assays and HPLC-measured drug concentration. These agents modulate inflammatory gene transcription to treat localized immune-mediated skin disorders. Hydrocortisone occupies the largest volume tier as the safest first-line option across all age groups, while clobetasol commands the highest per-unit margins among super-potent prescriptions. Cream and ointment delivery modes dominate hospital procurement, though gel formulations are gaining fastest in pediatric and cosmetically sensitive applications where residue and occlusion tolerance matter.
FDA potency classifications, EMA's MDR requirements for device-drug combinations, and WHO Essential Medicines List inclusion criteria collectively govern formulation standards, label claims, and reimbursement access across markets. The FDA's updated pregnancy labeling for corticosteroids has tightened teratogenic risk communication, directly influencing prescriber behavior in women's health and obstetric dermatology. Stakeholders must monitor evolving bioequivalence standards for generic topical steroids, as these will determine which manufacturers retain formulary access versus facing substitution mandates.
Market Dynamics
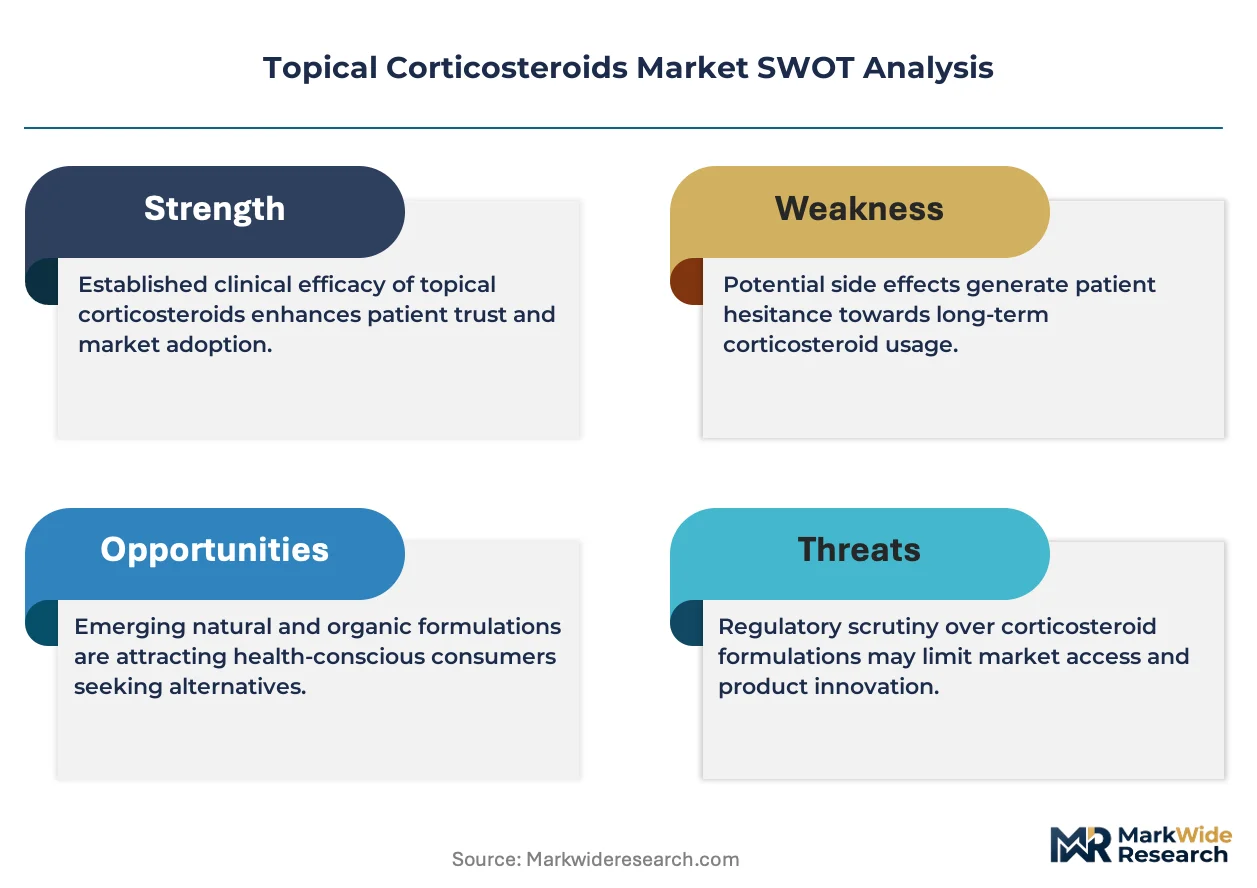
FDA potency classification updates are compressing prescription flexibility for dermatologists, forcing formulary managers to re-tier coverage based on vasoconstriction assay thresholds rather than clinical discretion alone.
Growth Catalysts
- Homecare migration:Patient-administered formulations reduce clinic dependency. Homecare settings now absorb mid-potency creams previously reserved for institutional dispensing.
- EMA MDR alignment:Device-drug combination standards in Europe are harmonizing quality benchmarks. Manufacturers achieving CE marking under MDR gain accelerated WHO prequalification pathways.
- Pediatric formulation gaps:Unmet need for cosmetically acceptable vehicles in children under 12 drives gel and foam development. Hydrocortisone 1% gels capture this segment fastest.
Market Restraints
- API sourcing concentration:Active pharmaceutical ingredient production clusters in India and China. Western buyers face single-source vulnerability for hydrocortisone and betamethasone intermediates.
- Safety labeling friction:FDA's updated pregnancy Category D warnings for clobetasol and halobetasol restrict obstetric dermatology prescribing. Liability exposure deters off-label use.
- Topical calcineurin inhibitors:Tacrolimus and pimecrolimus ointments displace low-potency steroids in facial and intertriginous eczema. Payers favor non-steroid step therapy protocols.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:WHO Essential Medicines List inclusion for hydrocortisone creates procurement anchor. National malaria and HIV programs present co-formulation partnership avenues.
- IRA Medicare price negotiation:Excluded drug status for topical dermatologics preserves pricing autonomy. Manufacturers can optimize launch sequencing around the negotiation calendar.
- Biologic-sparing protocols:Super-potent steroids combined with calcipotriene delay systemic immunology escalation. Dermatology clinics in Germany and France pilot these regimens aggressively.
Industry Challenges
- Bioequivalence validation timelines:FDA's evolving in vitro release testing standards for generic topical steroids extend ANDA review cycles. Formulation scientists face capability gaps in IVRT method development.
- Cold chain gel stability:Temperature-sensitive hydroalcoholic vehicles require validated distribution infrastructure. Last-mile pharmacy networks in tropical climates lack controlled storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Corticosteroids Market |
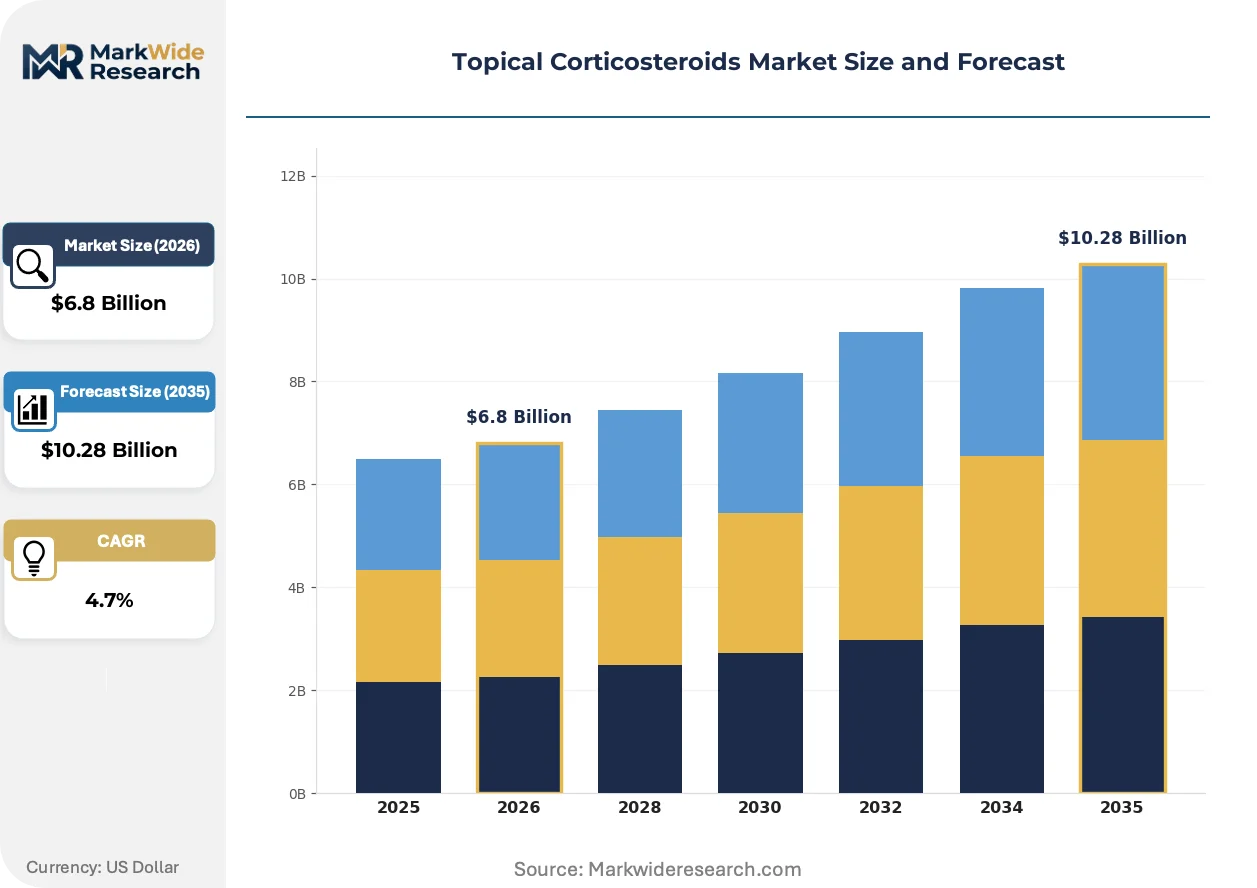
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocortisone, Betamethasone, Clobetasol, Triamcinolone Therapy Area: Dermatitis, Psoriasis, Eczema, Allergic Reactions Delivery Mode: Cream, Ointment, Lotion, Gel End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | GlaxoSmithKline, AbbVie, Pfizer, Sanofi, Novartis, Bayer, Merck and Co, AstraZeneca, LEO Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Corticosteroids Market Strategic Shifts
Formulation science and regulatory science are converging to redefine acceptable efficacy thresholds. Manufacturers now compete on dermatopharmacokinetic validation rather than marketing claims alone.
Nanosuspension technology is consolidating super-potent steroid delivery. Clobetasol propionate nanocrystals enhance follicular penetration for alopecia areata. Compounding pharmacies in the United States adopt these vehicles for off-label scalp applications. The technology is consolidating manufacturing advantage with specialized particle engineering firms.
REACH microplastic restrictions are forcing vehicle reformulation across European markets. Polyethylene glycol and microbead-containing bases face sunset dates. Reformulation costs concentrate on ointment heritage products with legacy excipient profiles. German and French regulators are accelerating compliance deadlines beyond EU baseline requirements.
Direct-to-consumer pharmacy channels are disintermediating traditional wholesale distribution. Amazon Pharmacy and Capsule capture refill volumes for chronic eczema maintenance prescriptions. Dermatology practices in California and Texas now write 90-day supplies explicitly for mail-order fulfillment. Pediatric caregivers in suburban markets show strongest channel preference for discreet home delivery.
Topical Corticosteroids Market Segmentation
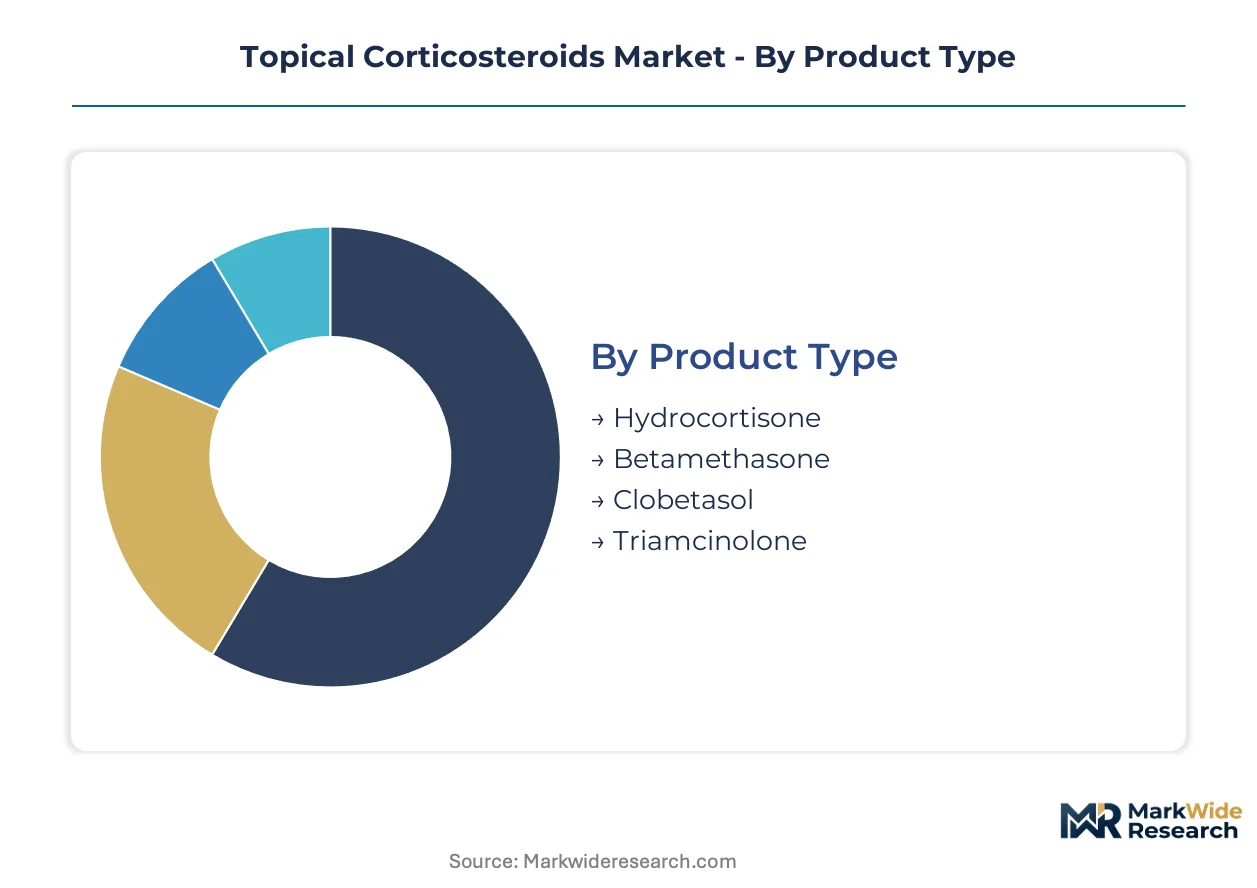
Segmentation in topical corticosteroids reveals how formulation science, clinical setting, and patient autonomy intersect to determine procurement patterns. Understanding these divides exposes where manufacturers can defend margin versus where volume commoditization accelerates.
Product Type:
Integration depth varies sharply across potency tiers, with low-potency agents functioning as standalone first-line therapy while super-potent formulations embed within combination protocols and specialist-managed regimens.
- Hydrocortisone:The mildest synthetic glucocorticoid, available in 0.5% to 2.5% concentrations, functions as the default entry therapy across pediatric and geriatric populations. Demand clusters in United States retail pharmacy chains and United Kingdom primary care networks where OTC availability and safety profile drive high prescription volume with compressed per-unit margins.
- Clobetasol:Super-potent propionate ester formulations deliver the strongest vasoconstriction response, reserved for recalcitrant plaque psoriasis and lichen planus. Germany's dermatology clinics and France's hospital outpatient departments anchor demand, though FDA pregnancy Category D labeling restricts obstetric applications and limits addressable market expansion.
- Betamethasone:Mid-to-high potency dipropionate and valerate salts serve as the workhorse for inflammatory dermatoses requiring more than hydrocortisone but less than clobetasol.
- Triamcinolone:Acetonide and diacetate variants occupy the intermediate tier, frequently deployed in intralesional injection protocols alongside topical delivery.
Hydrocortisone leads volumes today; clobetasol is gaining share fastest in specialist-managed segments.
Therapy Area:
Cost tier stratification dominates this dimension, with chronic maintenance conditions commanding premium formulation investment versus acute episodic presentations where generic substitution prevails.
- Dermatitis:Contact and seborrheic variants generate the highest prescription frequency globally, with mid-potency creams serving as the standard maintenance vehicle. United States commercial payers and United Kingdom NHS formularies drive procurement concentration, though EMA MDR compliance costs are forcing portfolio rationalization among smaller European suppliers.
- Eczema:Atopic dermatitis in children and adults requires cosmetically acceptable vehicles that balance occlusion with residue tolerance. Gel and lotion demand is climbing fastest in suburban United States markets where direct-to-consumer pharmacy channels capture refill loyalty from pediatric caregivers.
- Psoriasis:Chronic plaque disease necessitates rotational therapy with calcipotriene or biologic-sparing protocols in severe cases.
- Allergic Reactions:Acute urticaria and insect bite responses drive episodic, price-sensitive purchasing in emergency and retail settings.
Dermatitis leads volumes today; eczema is expanding most quickly as pediatric formulation gaps attract development investment.
Delivery Mode:
Application maturity separates legacy ointment bases with decades of clinical validation from next-generation vehicles engineered for specific anatomical sites and patient compliance.
- Cream:Oil-in-water emulsions dominate hospital procurement and general practitioner prescribing due to versatility across body sites and ease of spreadability. United States group purchasing organizations and Germany's hospital pharmacy consortia anchor volume concentration, though REACH microplastic restrictions are forcing excipient reformulation for European market access.
- Gel:Hydroalcoholic and aqueous vehicles address cosmetic sensitivity in facial, intertriginous, and scalp applications where residue visibility and occlusion intolerance limit ointment acceptability. Pediatric demand in France and cosmetically conscious adult segments in California are climbing the fastest, though cold chain stability requirements constrain tropical market penetration.
- Ointment:Occlusive petrolatum-based systems retain dominance for hyperkeratotic plaques and lichenified lesions.
- Lotion:Fluid vehicles serve hair-bearing areas and large surface applications where spread efficiency matters.
Cream leads volumes today; gel is gaining share fastest as vehicle science advances.
End User:
Customer type determines whether procurement flows through centralized institutional tenders or fragmented retail channels with divergent price transparency and substitution pressure.
- Homecare:Patient-administered formulations for chronic eczema and psoriasis maintenance are absorbing volumes previously captured by clinic dispensing. United States Medicare Part D and United Kingdom community pharmacy networks drive this shift, with Amazon Pharmacy and Capsule capturing refill loyalty through 90-day supply automation.
- Hospitals:Acute care settings concentrate super-potent and combination therapy procurement through formulary committees with strict potency classification adherence. Germany's university hospitals and France's public hospital networks anchor demand, with FDA bioequivalence standards determining generic substitution latitude.
- Clinics:Dermatology and allergy specialist practices balance sample-driven initiation with retail pharmacy fulfillment for maintenance.
- Pharmacies:Retail and mail-order channels intermediate between prescriber and patient, with OTC hydrocortisone capturing walk-in volume.
Hospitals lead volumes today; homecare is expanding most quickly as patient autonomy preferences reshape distribution architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as API production migrates toward jurisdictions with streamlined environmental compliance and lower cost-of-quality benchmarks. Western buyers now dual-source hydrocortisone and betamethasone intermediates to reduce single-source vulnerability.
United States
Dermatology clinic volumes and direct-to-consumer pharmacy channels anchor demand concentration. FDA potency classification updates compress prescription flexibility, forcing formulary managers to re-tier coverage based on vasoconstriction assay thresholds. The Northeast Corridor and California sustain the densest prescriber networks for chronic eczema maintenance.
Germany
Hospital outpatient departments and university hospitals drive super-potent steroid procurement for psoriasis and lichen planus protocols. EMA MDR alignment requirements harmonize quality benchmarks for device-drug combinations. Bavaria's pharmaceutical manufacturing corridor hosts specialized particle engineering firms advancing nanosuspension technology.
India
Specialty pharmaceutical manufacturing clusters in Gujarat and Maharashtra supply hydrocortisone and betamethasone intermediates to Western buyers diversifying sourcing. CDSCO oversight of active pharmaceutical ingredient facilities shapes export qualification timelines. Hyderabad's formulation science ecosystem attracts contract development work for pediatric gel vehicles.
China
NMPA regulatory pathways for generic topical steroids influence bioequivalence validation standards across Asia-Pacific supply chains. Yangtze River Delta chemical parks concentrate corticosteroid intermediate production. Shanghai-based manufacturers face REACH microplastic restriction compliance costs for European market access.
France
Public hospital networks anchor demand for mid-to-high potency creams in inflammatory dermatoses management. ANSM enforces pregnancy labeling standards that restrict clobetasol prescribing in obstetric dermatology. The Île-de-France region pilots biologic-sparing protocols combining super-potent steroids with calcipotriene.
Topical Corticosteroids Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue nanosuspension technology and pediatric formulation gaps. The vendor base stratifies across three tiers: century-long dermatology specialists commanding premium positioning, diversified pharmaceutical conglomerates leveraging commercial infrastructure, and regional generic manufacturers competing on bioequivalence validation speed. Strategic moves concentrate on M&A for particle engineering capabilities and vertical integration into API sourcing to mitigate supply concentration risk.
Within the dermatology-specialist tier, LEO Pharma exemplifies sustained premium positioning through century-long category focus. Among diversified pharmaceutical conglomerates, Pfizer and AbbVie anchor competitive presence—Pfizer through broad commercial infrastructure spanning hospital and retail channels, AbbVie through immunology-aligned dermatological pipelines that complement systemic therapy portfolios. These three entities represent distinct strategic archetypes: heritage specialization, scale-driven distribution, and immunology integration.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AbbVie |
| Pfizer |
| Sanofi |
| Novartis |
| Bayer |
| Merck and Co |
| AstraZeneca |
| LEO Pharma |
| Others |
Value Chain & Pricing Dynamics
Particle engineering specialists in Bavaria's pharmaceutical corridor command wage premiums that compress mid-tier manufacturer margins while enabling three-tier pricing separation between nanosuspension-enhanced super-potent formulations, standard cream bases, and economy hydrocortisone generics.
Pricing Analysis
Distributor margins on institutional procurement contracts absorb 12-18 points before hospital formulary committees see landed costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by vasoconstriction assay certification and FDA bioequivalence tier. Cost compression in generic betamethasone segments intensifies because ANDA backlog delays first-mover advantage. Pediatric caregivers in suburban United States markets show least price sensitivity for cosmetically acceptable gel vehicles.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for temperature-sensitive hydroalcoholic gel formulations requiring validated cold chain infrastructure. Active pharmaceutical ingredient production draws from India, China, and limited Italian fermentation capacity. Hydrocortisone, betamethasone dipropionate, and clobetasol propionate intermediates face single-source vulnerability as Western buyers dual-source only 40% of volume. Distribution runs through direct-to-consumer pharmacy channels disintermediating traditional wholesale for chronic maintenance prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Topical corticosteroids constitute a late-cycle quality story as demand shifts toward nanosuspension-enhanced super-potent formulations commanding formulation-science premiums over commodity generics.
For Market Incumbents: Anchor backward integration into hydrocortisone API production to mitigate single-source concentration in Gujarat and Maharashtra manufacturing clusters. Secure FDA bioequivalence validation capabilities ahead of evolving IVRT standards that threaten formulary access for manufacturers lacking in-house dermatopharmacokinetic expertise. Defend margin position by controlling particle engineering partnerships for nanocrystal scalp applications. For New Entrants and Emerging Players: Enter via pediatric formulation gaps in Sub-Saharan Africa where WHO Essential Medicines List inclusion creates procurement anchors for hydrocortisone 1% gel co-development with national malaria and HIV programs. Target cosmetically sensitive vehicle segments in France and California where residue intolerance limits incumbent ointment penetration. Pursue CE marking under EMA MDR to unlock accelerated WHO prequalification pathways. For Investors and Strategic Acquirers: Dermatology-specialist pharmaceutical conglomerates are the most active acquirers in this space, seeking particle engineering capabilities to consolidate nanosuspension manufacturing advantage. Five-to-ten year viability hinges on biologic-sparing protocol adoption in German and French clinics delaying systemic immunology escalation. Acquisition target archetype: specialized formulation science firms with validated IVRT method development capabilities. Signal to watch: FDA publication of final bioequivalence guidance for generic topical steroids triggering ANDA review acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Particle Engineering Acquisition | LEO Pharma and Pfizer compete for Bavarian nanocrystal specialists to secure scalp-delivery advantages. |
| EMA MDR CE Marking Pathway | Device-drug combination standards harmonize quality benchmarks for European market access. |
| API Backward Integration | Captive supply of hydrocortisone intermediates reduces India-China sourcing concentration risk. |
| Pediatric Gel Development | Hyderabad formulation ecosystems attract contract work for cosmetically acceptable vehicles in children under 12. |
| Direct-to-Consumer Channel Expansion | Amazon Pharmacy and Capsule capture 90-day refill loyalty from eczema maintenance patients. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded qualitative assessments of prescription protocol shifts and procurement concentration patterns. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation cross-checked segment-level assumptions.
Segmented outputs across potency tier, delivery mode, therapy area, and end-user setting populated the analytical framework over the projection horizon. CAGRs emerged from dermatology clinic volume trajectories, direct-to-consumer pharmacy channel penetration curves, and generic substitution elasticity parameters calibrated to FDA bioequivalence standard evolution.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-time formulary re-tiering data introduce uncertainty bands around institutional volume forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
Listeria Monocytogenes Treatment Market
Pharmaceuticals
Ginkgo Leaf Extract and Dipyridamole Injection Market
Pharmaceuticals
United States Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
High Potency API Contract Manufacturing Market
Pharmaceuticals
Zimbabwe Pharmaceutical Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Peptide and Anticoagulant Drugs Market
Pharmaceuticals
Global Erectile Dysfunction Drugs Market