
 Global Anti-Infective Agents Market | 2026-2036
Global Anti-Infective Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Infective Agents Market Foresight
RNA-targeted therapeutics and phage-based delivery platforms is tilting development pipelines away from traditional small-molecule chemistry. Pfizer Inc. leverages its mRNA manufacturing infrastructure to accelerate infectious disease vaccine-adjacent programs, while Gilead Sciences, Inc. anchors its portfolio in antiviral polymerase inhibitors with established regulatory pathways. Merck & Co., Inc. competes through backward integration into active pharmaceutical ingredient supply for its key anti-infective franchises.
Anti-infective agents comprise chemically or biologically derived substances that inhibit pathogen replication or directly destroy infectious organisms, including synthetic antibacterials with defined minimum inhibitory concentrations, nucleoside analogue antivirals, and polyene macrolide antifungals, formulated for systemic or localized administration to treat or prevent communicable diseases. Antibacterials retains the largest revenue pool due to entrenched hospital formulary placement and high-volume prophylactic use in surgical protocols, while antivirals represents the fastest-expanding segment driven by chronic hepatitis C elimination campaigns and respiratory virus preparedness initiatives. The injectable formulation category commands premium pricing in acute care settings, whereas oral formulations dominate ambulatory and long-term care facility dispensing volumes.
The FDA's Qualified Infectious Disease Product program accelerates review timelines for novel antibacterial agents addressing resistant pathogens, while the EMA's AMR regulatory science strategy reshapes European clinical endpoint expectations for anti-infective trials. India's CDSCO aligns domestic manufacturing standards with WHO prequalification requirements to expand export access for generic anti-infective producers. Stakeholders must monitor how antimicrobial stewardship mandates in major hospital systems reshape procurement criteria and reimbursement tiers for new therapeutic entrants.
Market Dynamics
Antimicrobial stewardship mandates in major hospital systems are compressing procurement cycles for broad-spectrum agents while accelerating demand for narrow-spectrum alternatives with resistance-sparing profiles. This regulatory pressure is restructuring formulary placement criteria across acute care networks in the United States, the European Union, and India.
Growth Catalysts
- FDA Qualified Infectious Disease Product designation:The accelerated review pathway for novel antibacterial agents addressing resistant pathogens is shortening time-to-market for developers targeting carbapenem-resistant Enterobacteriaceae.
- India's hospital sector procurement expansion:CDSCO-aligned manufacturing standards for WHO prequalification are unlocking export access for domestic generic producers serving Southeast Asian and African markets.
- RNA-targeted therapeutic platforms:mRNA manufacturing infrastructure repurposed from vaccine programs is enabling rapid pivot to infectious disease prophylaxis and therapeutic candidates.
Market Restraints
- API supply concentration in China and India:Backward integration gaps among Western formulators create vulnerability to export restriction shocks and quality enforcement actions.
- Antifungal polyene macrolide production complexity:Fermentation-based manufacturing requires dedicated bioreactor capacity with limited contract manufacturing availability.
- Clinical trial endpoint uncertainty under EMA AMR strategy:Shifting European expectations for non-inferiority margins and patient-reported outcomes are extending development timelines.
Strategic Opportunities
- China's specialty clinic network expansion:Tier-2 and tier-3 city outpatient centers are creating new dispensing channels for oral antiviral regimens outside traditional hospital pharmacy control.
- Phage-based delivery platform convergence with synthetic biology:Engineered bacteriophage vectors combined with CRISPR-guided payload targeting are opening precision antibacterial modalities.
- EU Green Deal sustainable manufacturing incentives:Funding streams for solvent-reduction and continuous-flow chemistry are advantaging early adopters in API synthesis.
Industry Challenges
- Antimicrobial resistance surveillance data integration:Hospital infection control departments lack standardized interoperability between local susceptibility testing and national resistance registries.
- Multidisciplinary clinical trial staffing shortages:Qualified infectious disease pharmacokineticists and medical microbiologists are concentrated in academic medical centers, limiting site activation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Infective Agents Market |
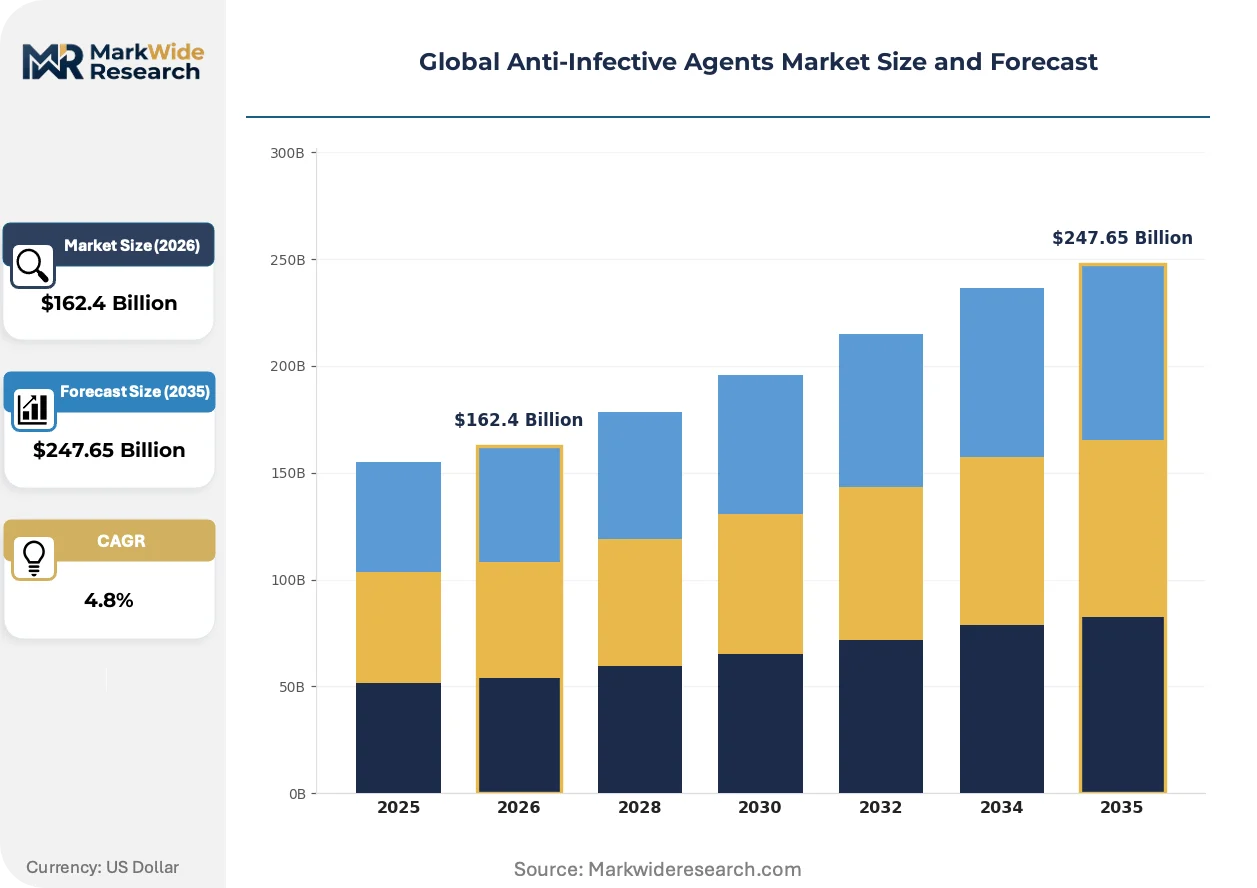
| Market Size in 2026 | $162.4 Billion |
| Market Size in 2035 | $247.65 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
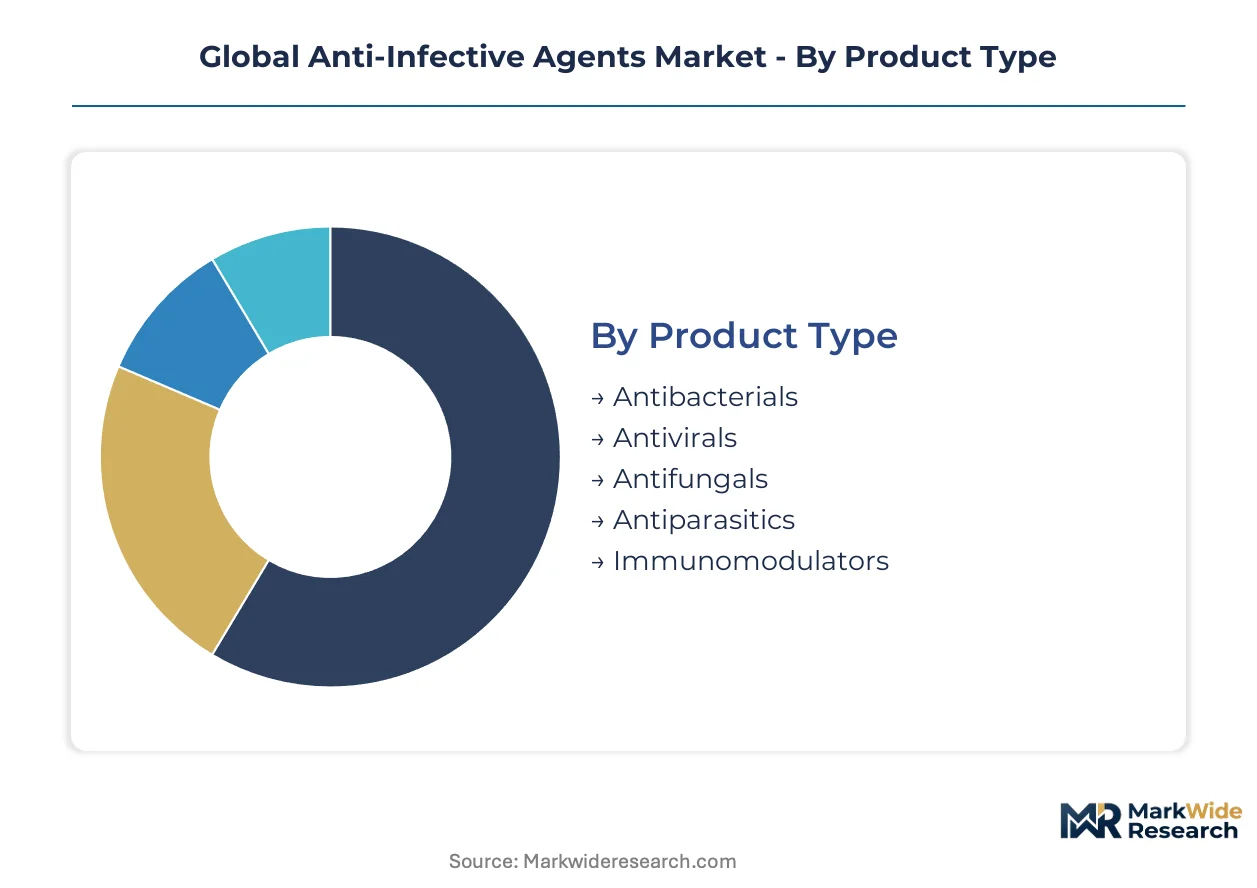
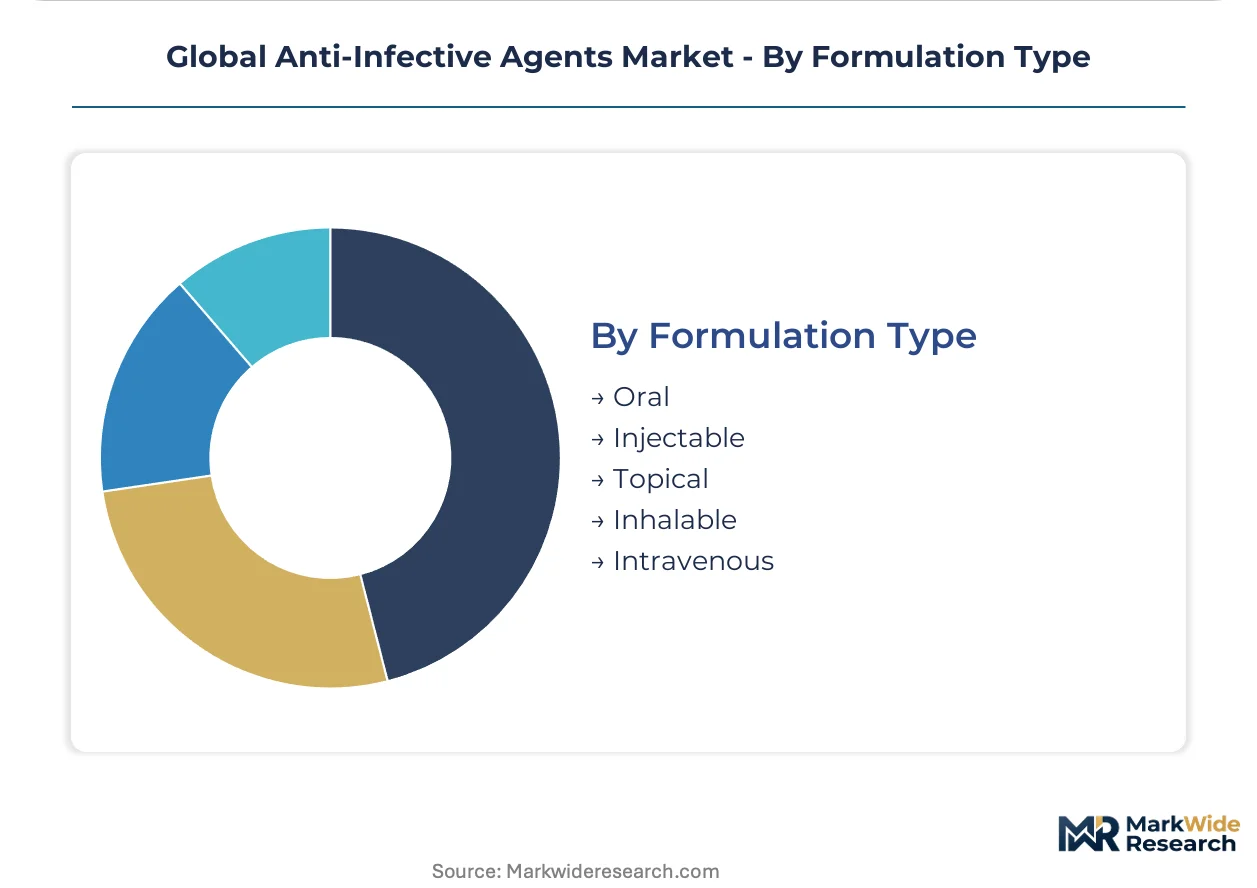
| Segmentation | Product Type: Antibacterials, Antivirals, Antifungals, Antiparasitics, Immunomodulators Therapy Area: Respiratory Infections, Urinary Tract Infections, Gastrointestinal Infections, Dermatological Infections, Central Nervous System Infections End User: Hospitals, Specialized Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Long-Term Care Facilities Formulation Type: Oral, Injectable, Topical, Inhalable, Intravenous |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Merck & Co., Inc., Novartis AG, Gilead Sciences, Inc., Sanofi, Bayer AG, F. Hoffmann-La Roche Ltd, Johnson & Johnson Services Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Infective Agents Market Shifts & Advancements
Development pipelines are pivoting from traditional small-molecule chemistry toward biologically derived modalities with programmable specificity. This shift is compressing the traditional discovery-to-clinic timeline while introducing new manufacturing and regulatory complexity.
RNA-targeted therapeutics are collapsing the distinction between prophylactic vaccines and therapeutic interventions in infectious disease management. Hospital systems in the United States are piloting combined mRNA platforms for seasonal respiratory virus preparedness. The structural consequence is a convergence of manufacturing infrastructure previously siloed between vaccine and therapeutic production networks.
The EMA's AMR regulatory science strategy is reshaping clinical endpoint expectations for anti-infective trials across European member states. Developers must now demonstrate resistance-sparing properties alongside efficacy, forcing earlier incorporation of pharmacodynamic modeling. This regulatory friction is diverting trial investment toward jurisdictions with clearer non-inferiority guidance.
Hospital procurement committees are consolidating vendor relationships through antimicrobial stewardship program mandates. United States health systems are reducing formulary breadth in favor of contracted narrow-spectrum agents with resistance surveillance reporting obligations. This concentration is most visible in integrated delivery networks with centralized pharmacy and therapeutics committees.
Global Anti-Infective Agents Market Segmentation
Segmentation in the anti-infective agents market reveals how procurement criteria, clinical settings, and route-of-administration preferences fragment demand across distinct commercial channels. Understanding these divisions exposes where pricing power concentrates and where formulary placement battles intensify.
Product Type:
Cost tier determines manufacturing investment thresholds and margin structures across chemically distinct therapeutic classes.
- Antibacterials:Synthetic and semi-synthetic compounds targeting bacterial cell wall synthesis or protein production dominate hospital procurement volumes. Stewardship program mandates in the United States and European Union are narrowing formulary placement toward resistance-sparing narrow-spectrum agents. Antibacterials holds installed capacity. Antivirals is rotating up the share rankings.
- Antivirals:Nucleoside analogues and polymerase inhibitors address chronic hepatitis C elimination campaigns and respiratory virus preparedness. China's specialty clinic networks and India's hospital sector are expanding dispensing channels for oral antiviral regimens outside traditional pharmacy control.
- Antifungals:Polyene macrolides and azole compounds require fermentation-based manufacturing with dedicated bioreactor capacity.
- Antiparasitics:Agents targeting protozoan and helminth infections serve tropical disease programs and travel medicine protocols.
- Immunomodulators:Biologic adjuncts enhancing host immune response complement direct-acting anti-infective therapy.
Antibacterials anchors procurement volumes. Antivirals is climbing the fastest.
Therapy Area:
Application-specific resistance patterns and treatment duration requirements reshape development priorities and clinical trial endpoint design.
- Respiratory Infections:Community-acquired pneumonia and ventilator-associated pneumonia drive acute care consumption of broad-spectrum agents. The FDA's Qualified Infectious Disease Product designation accelerates review timelines for novel antibacterials addressing resistant pathogens in this high-mortality indication. Respiratory Infections holds installed capacity. Urinary Tract Infections is rotating up the share rankings.
- Urinary Tract Infections:Recurrent and complicated UTIs sustain outpatient prescribing volumes for oral fluoroquinolones and cephalosporins. EMA's AMR regulatory science strategy is reshaping European clinical endpoint expectations for non-inferiority margins in uncomplicated UTI trials.
- Gastrointestinal Infections:Clostridioides difficile and Helicobacter pylori eradication protocols sustain niche demand for narrow-spectrum agents.
- Dermatological Infections:Topical and systemic agents address bacterial, fungal, and viral skin pathogens in ambulatory settings.
- Central Nervous System Infections:Meningitis and encephalitis require agents with blood-brain barrier penetration and hospital-based intravenous administration.
Respiratory Infections commands acute care premium pricing. Urinary Tract Infections is gaining share fastest.
End User:
Customer type determines reimbursement pathways, procurement committee structures, and resistance surveillance reporting obligations.
- Hospitals:Integrated delivery networks with centralized pharmacy and therapeutics committees consolidate vendor relationships through antimicrobial stewardship mandates. India's hospital sector procurement expansion under CDSCO-aligned manufacturing standards unlocks export access for domestic generic producers. Hospitals holds installed capacity. Specialized Clinics is rotating up the share rankings.
- Specialized Clinics:Tier-2 and tier-3 city outpatient centers in China create new dispensing channels for oral antiviral regimens outside traditional hospital pharmacy control.
- Diagnostic Laboratories:Reference labs and hospital-based microbiology services guide targeted therapy selection through rapid susceptibility testing.
- Ambulatory Surgical Centers:Prophylactic protocols for clean and clean-contaminated procedures sustain perioperative antibacterial consumption.
- Long-Term Care Facilities:Skilled nursing facilities and assisted living communities manage recurrent infections in elderly populations with colonization pressure.
Hospitals anchors procurement volume concentration. Specialized Clinics is expanding most quickly.
Formulation Type:
Route of administration dictates manufacturing complexity, bioequivalence requirements, and care setting economics.
- Injectable:Intravenous and intramuscular formulations command premium pricing in acute care settings with bioequivalence pathways established through FDA ANDA and EMA centralized procedures. Injectable holds installed capacity. Oral is rotating up the share rankings.
- Oral:Tablets, capsules, and suspensions dominate ambulatory and long-term care facility dispensing volumes with convenience-driven adherence advantages.
- Topical:Creams, ointments, and gels address localized dermatological and ophthalmic infections with minimal systemic exposure.
- Inhalable:Nebulized and dry powder formulations target respiratory tract infections with localized drug delivery.
- Intravenous:Hospital-compounded and ready-to-use bag formulations reduce pharmacy preparation burden in critical care settings.
Injectable captures acute care premium tiers. Oral is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and India concentrate demand through antimicrobial stewardship mandates, while China's specialty clinic networks fragment dispensing channels outside traditional pharmacy control.
United States
Integrated delivery networks consolidate vendor relationships through centralized pharmacy and therapeutics committees. The FDA's Qualified Infectious Disease Product designation accelerates review timelines for novel antibacterials targeting carbapenem-resistant Enterobacteriaceae. Boston's academic medical centers pilot combined mRNA platforms for seasonal respiratory virus preparedness.
Germany
Hospital formulary placement tightens around resistance-sparing narrow-spectrum agents with surveillance reporting obligations. The EMA's AMR regulatory science strategy reshapes clinical endpoint expectations for non-inferiority margins in anti-infective trials. Baden-Württemberg's pharmaceutical manufacturing cluster expands fermentation-based capacity for polyene macrolide antifungals.
India
Domestic hospital sector procurement expansion unlocks export access for generic producers serving Southeast Asian and African markets. The CDSCO aligns manufacturing standards with WHO prequalification requirements for active pharmaceutical ingredient producers. Hyderabad's bulk drug manufacturing belt deepens backward integration into fermentation-based intermediates.
China
Tier-2 and tier-3 city outpatient centers create new dispensing channels for oral antiviral regimens outside traditional hospital pharmacy control. The NMPA streamlines review pathways for innovative anti-infective candidates addressing resistant pathogens. Shanghai's specialty clinic networks concentrate demand for nucleoside analogue polymerase inhibitors.
United Kingdom
National Health Service antimicrobial stewardship programs compress procurement cycles for broad-spectrum agents while accelerating narrow-spectrum alternatives. The MHRA implements EMA-aligned guidance on resistance-sparing properties in clinical trial design. London's academic medical centers concentrate infectious disease pharmacokineticists and medical microbiologists for site activation capacity.
Global Anti-Infective Agents Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base spans multinational pharmaceutical conglomerates with mRNA manufacturing infrastructure, mid-cap antiviral specialists with established regulatory pathways, and generic producers with backward-integrated active pharmaceutical ingredient supply. Three archetypes dominate: scale-driven platform players, narrow-spectrum resistance-sparing specialists, and fermentation-capable antifungal manufacturers. Competitive moves concentrate on strategic partnerships for phage-based delivery platforms and geographic expansion into China's specialty clinic networks.
Within the scale-driven platform tier, Pfizer Inc. and Merck & Co., Inc. occupy positions leveraging mRNA manufacturing infrastructure and captive active pharmaceutical ingredient supply respectively. Gilead Sciences, Inc. exemplifies the antiviral specialist archetype with polymerase inhibitor portfolios. These three entities represent the dominant competitive anchors across the United States, European, and Asian procurement channels.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| Novartis AG |
| Gilead Sciences, Inc. |
| Sanofi |
| Bayer AG |
| F. Hoffmann-La Roche Ltd |
| Johnson & Johnson Services Inc. |
| Others |
Supply & Pricing Matrix
China's fermentation-based intermediate concentration and India's bulk drug manufacturing belt anchor global active pharmaceutical ingredient supply, concentrating margin capture upstream while Western formulators face cost-plus contract pressures indexed to energy and solvent benchmarks.
Pricing Analysis
Cost-plus contracts with API suppliers carry indexation clauses tied to energy and fermentation feedstock benchmarks. Price differentiation separates GMP-certified sterile injectables from non-sterile oral generics, with brand premiums attaching to FDA QIDP-designated novel agents. Pricing pressure stems from hospital procurement consolidation through antimicrobial stewardship mandates. Generic oral antibacterials face acute price sensitivity from India's hospital sector and Southeast Asian tender markets, while narrow-spectrum resistance-sparing agents command premium tolerance in US integrated delivery networks.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Indian and Chinese API producers enable working capital flexibility for downstream formulators. Manufacturing concentrates in India, China, and Germany, with fermentation-based polyene macrolide production drawing from corn-derived dextrose and soy-based nitrogen sources. Single-source vulnerability runs through China's dedicated bioreactor capacity for macrolide antifungals. Distribution runs through hospital procurement committees in the United States and European Union, with China's specialty clinic networks fragmenting oral antiviral channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti-infective agents market sits in early-cycle expansion, with RNA-targeted therapeutic platforms and phage-based delivery systems creating new modality categories beyond traditional small-molecule chemistry.
For Market Incumbents: Entrench formulary position through backward integration into fermentation-based API supply for polyene macrolides and captive mRNA manufacturing infrastructure. Counter phage-based delivery platform threats by acquiring synthetic biology capabilities or licensing CRISPR-guided payload engineering. Prioritize resistance surveillance data integration with hospital infection control departments to secure stewardship-mandated procurement contracts.
For New Entrants and Emerging Players: Build out narrow-spectrum resistance-sparing portfolios targeting carbapenem-resistant Enterobacteriaceae under FDA QIDP pathways. China's tier-2 and tier-3 specialty clinic networks offer the most penetrable dispensing channel for oral antiviral regimens outside hospital pharmacy control. Pursue go-to-market partnerships with domestic generic producers holding CDSCO-aligned WHO prequalification status.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap antiviral specialists possessing established polymerase inhibitor regulatory pathways but limited geographic reach. Long-term viability hinges on resistance-sparing clinical profiles and manufacturing scalability across the 5-10 year antimicrobial stewardship tightening horizon. Watch for inflection signals in EMA non-inferiority margin guidance revisions that redirect trial investment toward clearer regulatory jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Phage-Based Delivery Platform Development | Engineered bacteriophage vectors with CRISPR-guided payloads open precision antibacterial modalities beyond traditional chemistry. |
| Backward Integration into API Supply | Captive fermentation capacity for polyene macrolides insulates margins from China's bioreactor concentration risk. |
| Specialty Clinic Network Expansion | Tier-2 and tier-3 city outpatient centers in China fragment oral antiviral dispensing outside hospital control. |
| Resistance Surveillance Data Integration | Hospital infection control interoperability with national registries secures stewardship-mandated formulary placement. |
| mRNA Manufacturing Infrastructure Repurposing | Vaccine-adjacent production networks collapse prophylactic-therapeutic boundaries in infectious disease management. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA QIDP designations, EMA AMR regulatory science guidance, CDSCO manufacturing circulars, and WHO prequalification lists. Primary interviews engaged drug development executives at scale-driven platform players, regulatory affairs leads navigating EMA non-inferiority expectations, hospital procurement managers in US integrated delivery networks, formulary directors implementing stewardship mandates, and API supply chain managers in Hyderabad's bulk drug belt. Bottom-up patient-volume modeling triangulates against top-down pharmaceutical expenditure tracking across national health accounts.
Forecast inputs span product type segmentation across antibacterials, antivirals, and antifungals; therapy area concentration in respiratory and urinary tract infections; end-user channel splits between hospitals and specialty clinics; and formulation economics distinguishing injectable premium tiers from oral volume scales. CAGRs derive from regression-adjusted historical growth rates applied across the projection horizon, incorporating antimicrobial stewardship adoption curves and regulatory pathway acceleration effects from FDA QIDP and EMA AMR strategies.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform players repurposing mRNA infrastructure or phage-based specialists securing synthetic biology partnerships would shift outcomes. Macroeconomic deviation in healthcare procurement budgets, regulatory disruption in clinical endpoint standards, or technological breakthrough in programmable biologics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Testosterone Replacement Therapy Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Psychedelic Drugs Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Medical Nitroglycerin Spray Market
Pharmaceuticals
Acetylcholine Market
Pharmaceuticals
United Kingdom (UK) Diabetes Drugs Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Middle East and Africa Laxative Market