
 Farm Animal Drugs Market | 2026-2036
Farm Animal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Farm Animal Drugs Market Analysis
Project finance and veterinary service leasing is rewriting competitive dynamics for mid-sized livestock operations that previously lacked capital for preventive drug programs. Zoetis Inc. leverages its diagnostic-to-treatment platform to anchor long-term contracts with integrated poultry producers. Boehringer Ingelheim Animal Health sustains R&D intensity across respiratory vaccine portfolios. Ceva Santé Animale specializes in hatchery vaccination systems that reduce labor costs for large-scale broiler operations.
Farm animal drugs comprise pharmacologically active compounds formulated for therapeutic, prophylactic, or growth-promoting administration to food-producing species, typically manufactured under veterinary pharmaceutical good manufacturing practice with batch potency testing and stability validation. These products prevent disease losses, ensure food safety residue compliance, and maintain herd productivity in intensive livestock systems. Vaccines command durable margin pools due to cold-chain requirements and strain-update cycles that lock in recurring revenue. Antiparasitics face generic erosion in mature cattle markets but retain premium positioning in companion-animal crossover formulations. Injectable administration routes dominate in cattle and swine due to bioavailability requirements, while oral medicated feeds expand in poultry where mass medication protocols reduce labor.
The FDA's Veterinary Feed Directive restricts over-the-counter antimicrobial use in feed, compelling veterinarians to authorize prescriptions and reshaping distribution channel economics. EMA's guidelines on veterinary medicinal products establish maximum residue limits that determine export market access for meat and dairy producers. USDA's National Animal Health Monitoring System tracks drug use patterns that inform future restriction timelines. Stakeholders must monitor regulatory divergence between jurisdictions that accept precautionary bans and those maintaining risk-based frameworks, as this split determines which manufacturing footprints and product registrations retain strategic value.
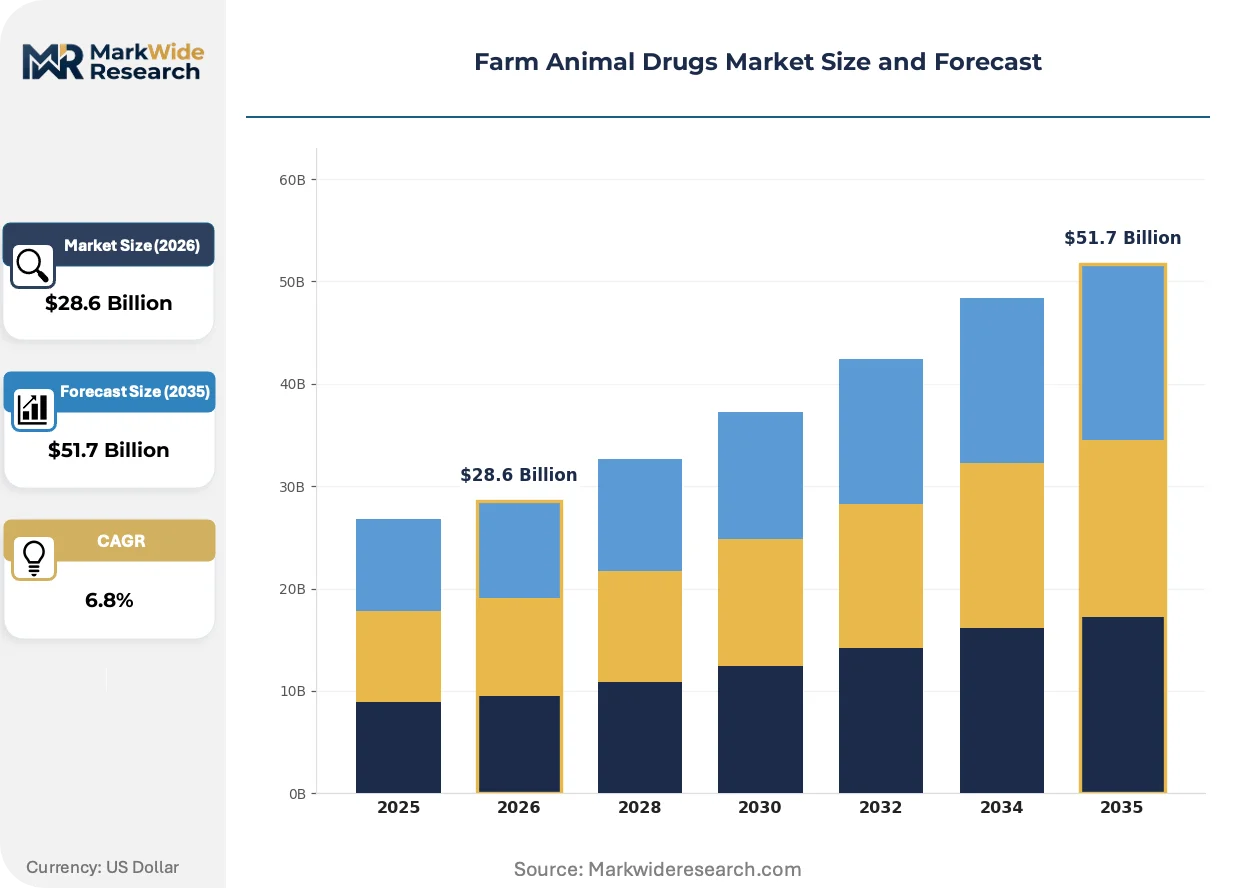
Market Dynamics
The FDA's Veterinary Feed Directive is compressing antimicrobial distribution channels while integrated livestock operators consolidate procurement power through diagnostic-linked service contracts.
Growth Catalysts
- Preventive vaccination protocols:Dairy cattle operations in the United States are expanding herd health programs to reduce culling losses and maintain milk yield consistency. Cold-chain infrastructure investments in Brazil's southeastern corridor support vaccine penetration.
- EMA residue limit harmonization:Export-oriented meat producers in the European Union are upgrading pharmaceutical compliance to access premium market segments. Maximum residue limit alignment reduces border rejection risk for integrated processors.
- Hatchery automation integration:Large-scale broiler operations are embedding vaccination systems into automated chick processing lines. Labor cost reduction drives adoption across vertically integrated poultry complexes.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for veterinary antiparasitics concentrates in Chinese chemical hubs. Geopolitical friction exposes formulators to input disruption and price volatility.
- Generic erosion in mature segments:Off-patent macrocyclic lactones face commoditization in North American cattle markets. Margin compression limits R&D reinvestment for follow-on formulations.
- Antimicrobial resistance surveillance:USDA's National Animal Health Monitoring System tracks use patterns that inform restriction timelines. Regulatory overhang discourages long-term product development commitments.
Strategic Opportunities
- Companion-animal crossover formulations:Premium antiparasitic delivery systems developed for canine markets are adapting to small ruminant applications. Margin structures in pet therapeutics attract livestock investment.
- Leased veterinary service models:Mid-sized operations lacking capital for preventive programs are accessing diagnostics-through-treatment platforms via subscription structures. Equipment and drug bundling reduces upfront barriers.
- Precision dosing via digital integration:Weight-based injectable systems are converging with herd management software to reduce withdrawal period violations. Data capture enables outcome-based contracting with protein processors.
Industry Challenges
- Veterinary prescription authorization capacity:The FDA's Veterinary Feed Directive requires veterinarian oversight for feed-administered antimicrobials. Rural practice shortages create bottlenecks for livestock operators seeking compliance.
- Batch potency validation complexity:Vaccine stability testing under cold-chain stress demands specialized quality infrastructure. Smaller manufacturers face capital barriers to maintaining cGMP compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Farm Animal Drugs Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiparasitics, Vaccines, Hormones Administration Route: Injectable, Oral, Topical, Inhalation Livestock Type: Cattle, Poultry, Swine, Aquaculture End User: Veterinarians, Farmers, Livestock Producers, Research Institutions |
| Companies Covered | Merck Animal Health, Virbac SA, Zoetis Inc., Phibro Animal Health, Vetoquinol SA, Elanco Animal Health, Ceva Santé Animale, MSD Animal Health, Boehringer Ingelheim Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Farm Animal Drugs Market Emerging Trajectories
Diagnostic-to-treatment platforms are collapsing the traditional separation between disease detection and pharmaceutical intervention, restructuring how livestock operators contract for animal health services.
mRNA vaccine platforms are migrating from human pharmaceutical development into veterinary respiratory disease applications. Swine producers in North Carolina and Iowa are piloting strain-adaptable formulations that reduce lag time between variant emergence and herd protection. This technology is compressing the traditional 18-month vaccine update cycle toward 6-month turnaround, enabling contract structures that tie pharmaceutical payments to outbreak risk reduction.
EMA's guidelines on veterinary medicinal products are tightening maximum residue limit enforcement for export-certified meat and dairy. Third-party auditors in the Netherlands and Germany are embedding residue testing into processor procurement contracts. Smallholder cooperatives in Eastern Europe are consolidating to afford compliance infrastructure, accelerating vertical integration between drug prescribers and slaughterhouses.
Integrated livestock operators are consolidating pharmaceutical procurement through direct manufacturer contracts that bypass traditional distributor markups. Poultry complexes in Brazil's Paraná state and cattle feedlots in Texas are negotiating diagnostic-inclusive pricing that shifts payment from product volume to health outcomes. This restructuring concentrates purchasing power among the largest 15 percent of livestock operations while squeezing regional veterinary clinic margins.
Farm Animal Drugs Market Segmentation
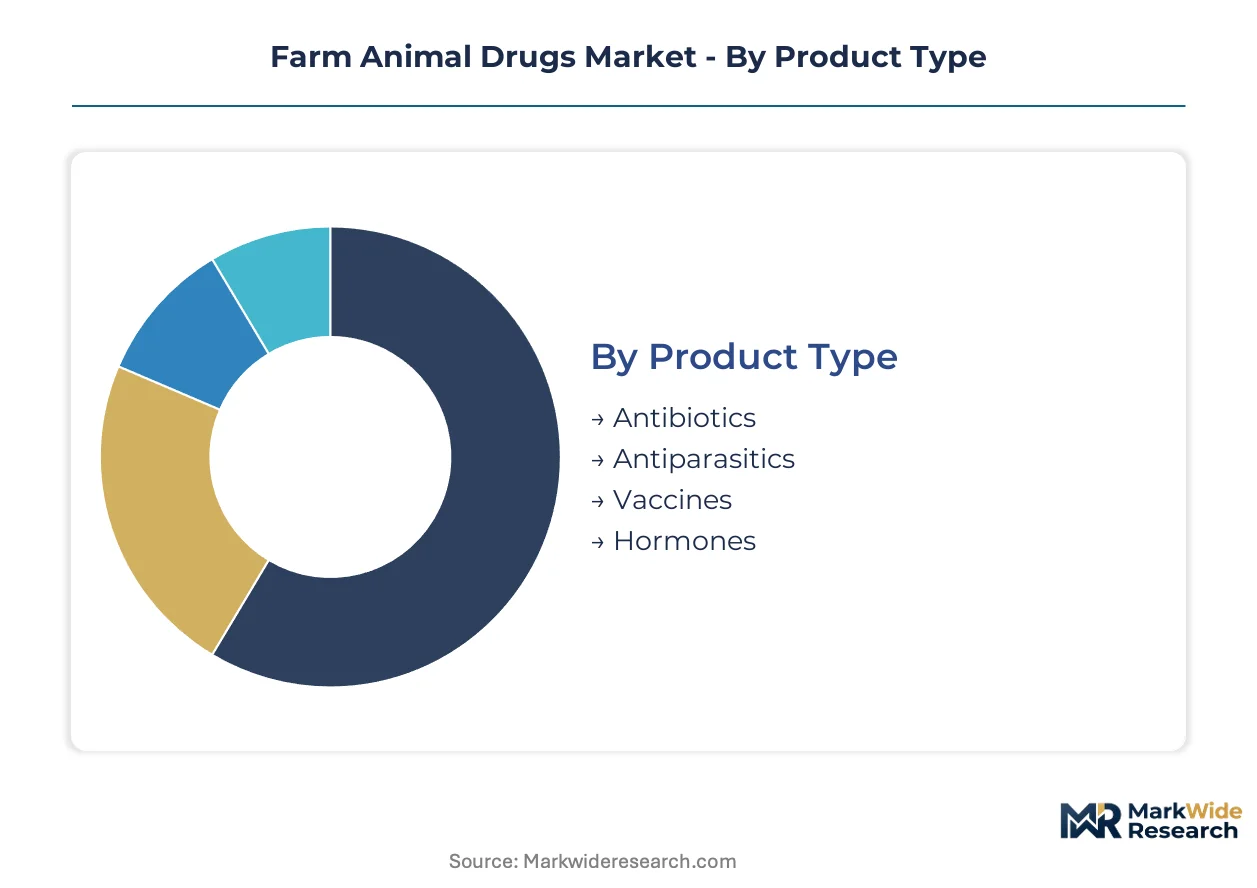
Farm animal drugs serve divergent biological systems and regulatory frameworks across species and production systems. Segmentation reveals where formulation complexity, margin structures, and compliance burdens concentrate commercial value.
Product Type:
Pharmaceutical categories span the use-case spectrum from acute disease intervention to preventive immunization and metabolic manipulation.
- Vaccines:Antigen formulations with adjuvant systems requiring cold-chain integrity from manufacture to administration. Demand clusters in Brazil's southeastern cattle corridor where integrated operators negotiate multi-year supply agreements tied to diagnostic platforms.
- Antiparasitics:Macrocyclic lactones and benzimidazoles targeting endoparasite and ectoparasite burdens. Generic erosion in North American cattle markets pressures margin pools, though premium pour-on formulations retain pricing power in companion-animal crossover applications.
- Antibiotics:Bactericidal and bacteriostatic compounds for therapeutic and metaphylactic use. FDA's Veterinary Feed Directive restricts feed-administered antimicrobial access, compressing distribution channel economics and elevating veterinarian prescription authority.
- Hormones:Growth promotants and reproductive synchrony agents regulated under maximum residue limits. Export market access depends on EMA alignment and destination country acceptance protocols.
The dominant share belongs to vaccines, while antiparasitics is closing the gap fastest through premium delivery system innovation.
Administration Route:
Delivery modality determines bioavailability, labor requirements, and withdrawal period management across production systems.
- Injectable:Parenteral formulations achieving precise plasma concentration in cattle and swine. Bioavailability requirements in large ruminants sustain premium pricing for long-acting depot formulations.
- Oral:Medicated feeds and water-soluble concentrates enabling mass medication in poultry operations. Labor cost reduction drives adoption across vertically integrated broiler complexes.
- Topical:Pour-on and spot-on applications for ectoparasite control. Ease of administration supports use in extensive grazing systems with limited handling infrastructure.
- Inhalation:Aerosol and intranasal delivery for respiratory disease prophylaxis. Hatchery automation integration expands application in day-old chick processing lines.
Injectable routes command the highest value per dose, though oral administration is gaining share fastest through poultry sector consolidation.
Livestock Type:
Species-specific physiology and production intensity shape therapeutic requirements and regulatory exposure.
- Cattle:Dairy and beef operations with distinct metabolic disease profiles and reproductive management needs. Preventive vaccination protocols in United States dairy herds reduce culling losses and maintain milk yield consistency.
- Poultry:Broiler and layer systems with compressed production cycles and high-density pathogen pressure. Hatchery vaccination automation reduces labor costs for large-scale integrated operations.
- Swine:Intensive farrow-to-finish and wean-to-finish systems with respiratory disease complexity. mRNA vaccine pilots in North Carolina and Iowa operations compress strain adaptation timelines.
- Aquaculture:Finfish and shellfish production with unique pharmacokinetics and environmental residue concerns. Regulatory frameworks for aquatic species remain less harmonized across export markets.
Cattle generates the largest absolute demand, while poultry is expanding most quickly through vertical integration and automation.
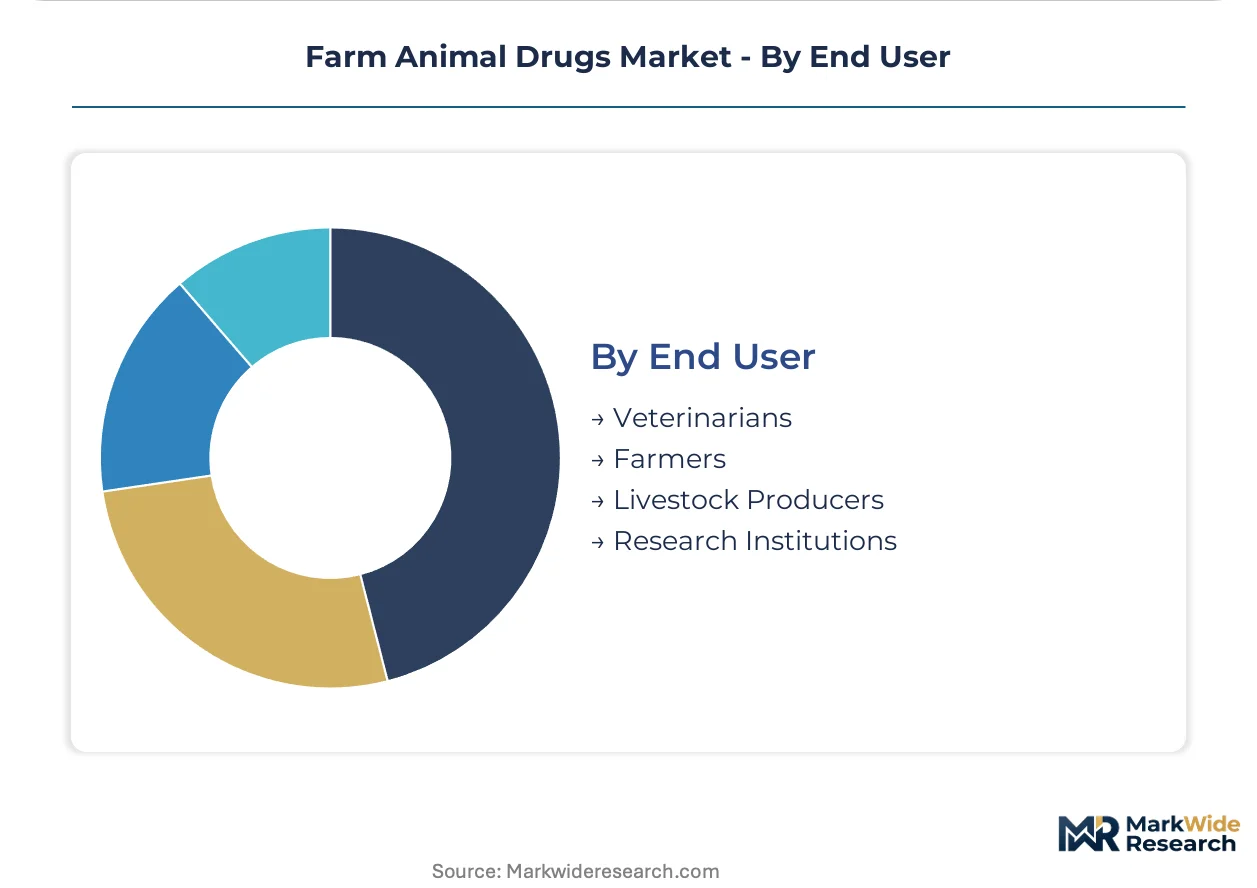
End User:
Prescription authority and procurement scale determine access patterns and contracting structures.
- Veterinarians:Licensed practitioners with feed directive authority and diagnostic service integration. Rural practice shortages create compliance bottlenecks under FDA antimicrobial oversight requirements.
- Livestock Producers:Integrated operators with direct manufacturer contracting power and outcome-based payment structures. Diagnostic-linked service agreements bypass traditional distributor markups.
- Farmers:Mid-sized and smallholder operations accessing pharmaceuticals through veterinary intermediaries. Subscription-based service models reduce capital barriers to preventive program adoption.
- Research Institutions:Universities and contract research organizations conducting efficacy and safety studies. Regulatory submission data generation supports product registration maintenance.
Livestock producers control the dominant procurement volume, while veterinarians are consolidating influence fastest through prescription authority expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds Brazilian benchmarks by roughly 40 percent due to stricter FDA compliance requirements and diagnostic-linked contracting models. German export certification commands premium spreads over Eastern European supply. Chinese API concentration depresses finished-drug margins across downstream markets.
United States
Dairy operations in Wisconsin and California drive preventive vaccination procurement to reduce culling losses. The FDA's Veterinary Feed Directive mandates veterinarian oversight for feed-administered antimicrobials, compressing distribution channels. Texas cattle feedlots negotiate direct manufacturer contracts that bypass traditional veterinary clinic markups.
Brazil
Integrated poultry and beef operations in Paraná and Mato Grosso scale veterinary drug procurement through diagnostic platforms. ANVISA enforces residue limit alignment with EU export standards. São Paulo state's southeastern cattle corridor attracts cold-chain infrastructure investment for vaccine distribution.
Germany
Export-certified pork and dairy producers in Lower Saxony upgrade pharmaceutical compliance for premium market access. EMA guidelines on maximum residue limits determine border acceptance protocols for integrated processors. Bavarian cooperatives consolidate to afford third-party audit infrastructure.
China
Swine restocking programs in Sichuan and Henan provinces generate therapeutic demand following disease outbreaks. The national pharmaceutical regulator tightens GMP enforcement for veterinary vaccine manufacturing. Shandong's chemical hubs concentrate active pharmaceutical ingredient production for global antiparasitic formulators.
India
Dairy cooperatives in Gujarat and Maharashtra expand artificial insemination and reproductive health programs. CDSCO regulates veterinary drug registration with residue limit harmonization for Middle East export markets. Haryana's integrated livestock operations pilot subscription-based veterinary service models.
Farm Animal Drugs Market Vendor Landscape
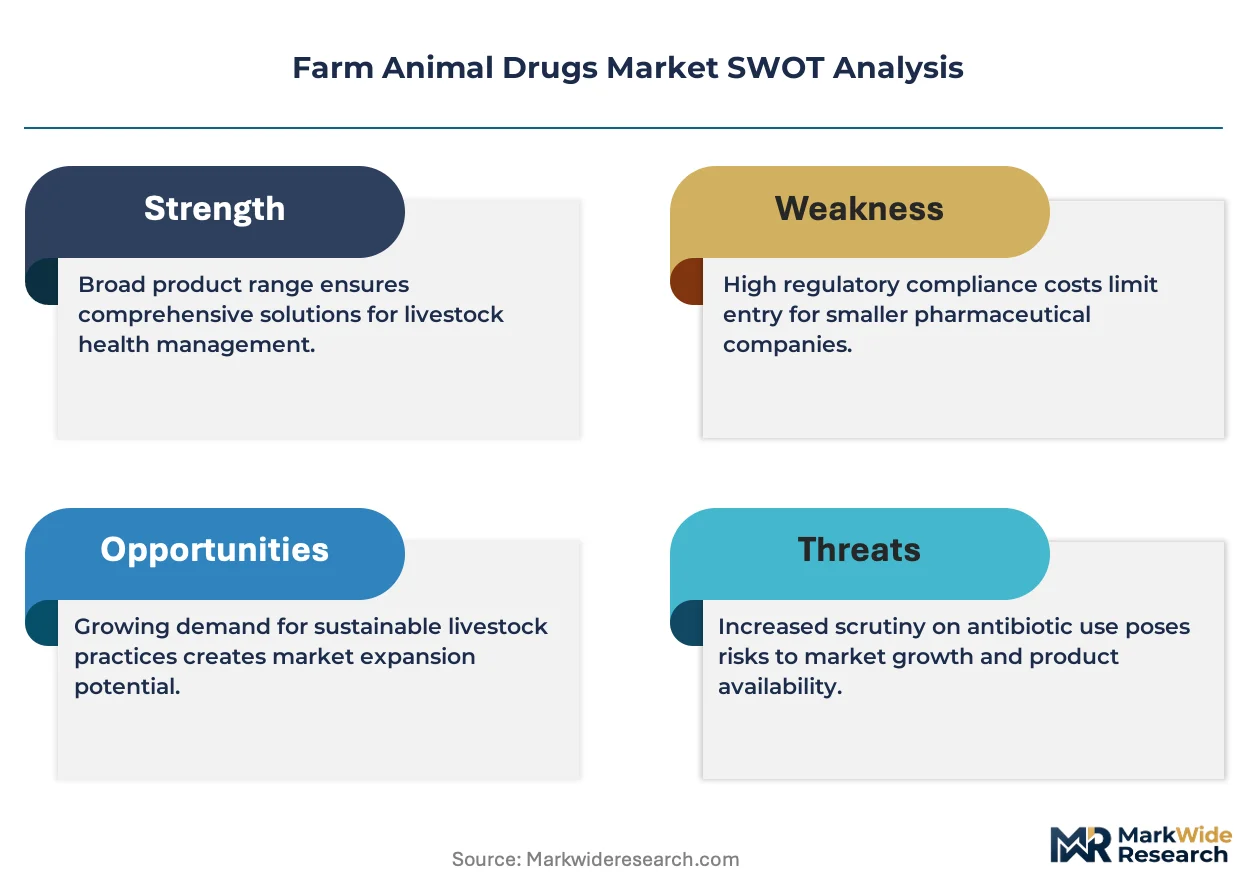
Platform integrators command the system tier; component specialists sit upstream with formulation expertise. The market consolidates around diagnostic-to-treatment bundling that locks in multi-year supply agreements. Three archetypes dominate: full-service animal health platforms, respiratory vaccine specialists, and hatchery automation integrators. Competitive moves concentrate on strategic partnerships linking diagnostics with pharmaceutical procurement and backward integration into active pharmaceutical ingredient sourcing.
Among the full-service platforms, Zoetis Inc. and Merck Animal Health exemplify the diagnostic-linked contracting model that is displacing traditional distributor relationships. Boehringer Ingelheim Animal Health occupies a position within the respiratory vaccine specialist tier. Ceva Santé Animale sits within the hatchery automation integration segment, representing the convergence of pharmaceutical delivery with capital equipment bundling.
| Leading Market Players |
|---|
| Merck Animal Health |
| Virbac SA |
| Zoetis Inc. |
| Phibro Animal Health |
| Vetoquinol SA |
| Elanco Animal Health |
| Ceva Santé Animale |
| MSD Animal Health |
| Boehringer Ingelheim Animal Health |
| Others |
Supply Flow & Price Mechanics
Shandong's chemical manufacturing clusters supply the bulk of macrocyclic lactone precursors that underpin antiparasitic formulation economics across downstream markets. Capacity utilization at these hubs directly determines margin compression or expansion for finished-drug manufacturers in Brazil and the United States. Cold-chain vaccine distribution from São Paulo's southeastern corridor adds logistics premiums that differentiate Brazilian pricing from North American benchmarks.
Pricing Analysis
Integrated livestock producers anchor contract-based long-term offtake structures that bypass traditional distributor markups. Three-tier pricing structure across premium, standard, and economy levels reflects FDA compliance tier and diagnostic platform bundling. Cost compression in generic macrocyclic lactones is intensifying because of API oversupply from Chinese chemical hubs. Smallholder cooperatives exhibit highest price sensitivity, while vertically integrated poultry complexes in Paraná negotiate least.
Supply Chain Analysis
Active pharmaceutical ingredient manufacturing draws from Shandong province in China, Basel region in Switzerland, and Hyderabad cluster in India. Fermentation-derived antiparasitic precursors, recombinant protein substrates, and adjuvant lipid systems constitute critical input dependencies. Single-source vulnerability concentrates in Chinese chemical intermediates for benzimidazole derivatives. Distribution runs through direct manufacturer contracts with integrated livestock operators, displacing veterinary clinic intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA vaccine platform maturation is disrupting traditional 18-month strain-update cycles, compressing development timelines toward 6-month turnarounds that reward diagnostic-linked pharmaceutical bundling.
For Market Incumbents: Entrench diagnostic-to-treatment platform control by embedding weight-based precision dosing systems into herd management software contracts. Backward integration into adjuvant lipid sourcing reduces exposure to Shandong chemical hub volatility. Hatchery automation partnerships with Brazilian poultry complexes lock in multi-year vaccine supply agreements that generic entrants cannot replicate.
For New Entrants and Emerging Players: Pursue leased veterinary service models targeting mid-sized dairy operations in Wisconsin and California that lack capital for preventive program infrastructure. Subscription-based diagnostics-through-treatment platforms represent the most penetrable entry vector. Partner with regional cold-chain logistics providers to bypass incumbent distribution networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors respiratory vaccine specialists with mRNA platform capabilities and hatchery automation integrators with pharmaceutical-equipment bundling expertise. Long-term viability hinges on regulatory navigation capacity across FDA Veterinary Feed Directive and EMA maximum residue limit frameworks. Watch for ANVISA-EU harmonization announcements as inflection indicators for Brazilian export-oriented producer demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Platform Integration | Zoetis and Merck Animal Health embed diagnostics to lock in multi-year pharmaceutical procurement contracts. |
| API Backward Integration | Boehringer Ingelheim reduces Shandong chemical hub dependency through captive adjuvant manufacturing. |
| Hatchery Automation Partnership | Ceva Santé Animale bundles vaccination systems with day-old chick processing lines in Paraná poultry complexes. |
| mRNA Vaccine Scale-Up | Swine producers in Iowa pilot strain-adaptable formulations that compress traditional development cycles. |
| Subscription Service Launch | Mid-sized operations in Haryana access preventive programs via equipment and drug bundling without upfront capital. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with livestock producers, veterinary practitioners, pharmaceutical regulatory affairs leads, and cold-chain logistics operators; and secondary validation through FDA Veterinary Feed Directive filings, EMA veterinary medicinal product submissions, ANVISA residue limit protocols, and USDA National Animal Health Monitoring System drug use tracking databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs considered product type segmentation by vaccines, antiparasitics, antibiotics, and hormones; administration route differentiation across injectable, oral, topical, and inhalation modalities; livestock species-specific demand patterns; and end-user procurement structures from integrated operators to smallholder cooperatives. CAGRs derived from regression analysis against veterinary pharmaceutical expenditure intensity and protein production volume elasticities, incorporating cold-chain infrastructure investment trajectories and regulatory timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by generic API manufacturers or mRNA platform specialists would shift outcomes. Cross-checking against USDA drug use survey benchmarks and EMA export certification data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antibody Therapy Market
Pharmaceuticals
Brain Tumor Drugs Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Lithuania Pharmaceutical Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Repurposed Human Immunosuppressants Market
Pharmaceuticals
Acetaminophen Market